
 Global Cancer Vaccine Market | 2026-2036
Global Cancer Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cancer Vaccine Market Analysis
Outcome-based reimbursement for maintenance immunotherapy regimens is decoupling cancer vaccine revenue from one-time product sales. Merck & Co., Inc. leverages its checkpoint inhibitor infrastructure to anchor combination therapy development across solid tumors. GSK plc competes through specialized adjuvant systems that enhance cellular immune responses in therapeutic formulations. BioNTech SE dominates mRNA manufacturing scale, positioning its individualized neoantigen platform as a template for future autologous vaccines.
A cancer vaccine is a biological preparation designed to stimulate antigen-specific T-cell responses against tumor-associated antigens, with mRNA formulations encoding patient-specific neoantigens synthesized through in vitro transcription and lipid nanoparticle encapsulation. These products serve to eliminate residual disease, prevent recurrence, or intercept malignant transformation in high-risk populations. Therapeutic vaccines command the deepest margin pools due to chronic administration protocols and companion diagnostic requirements, while RNA vaccines represent the fastest-expanding modality as manufacturing flexibility enables rapid personalization. Preventive vaccines remain concentrated in viral oncology targets such as HPV-related cervical malignancies, where established immunization programs sustain predictable demand curves.
The FDA's breakthrough therapy designation and the EMA's PRIME eligibility scheme compress development timelines for candidates addressing unmet oncology needs, while WHO prequalification standards govern access pathways in lower-income health systems. REACH and EU GMP Annex 1 requirements enforce stringent contaminant controls for plasmid DNA and viral vector substrates used in vaccine construction. Stakeholders must monitor evolving FDA guidance on real-world evidence requirements for accelerated approvals, as post-market confirmatory trials increasingly determine long-term reimbursement status across public and private payers.
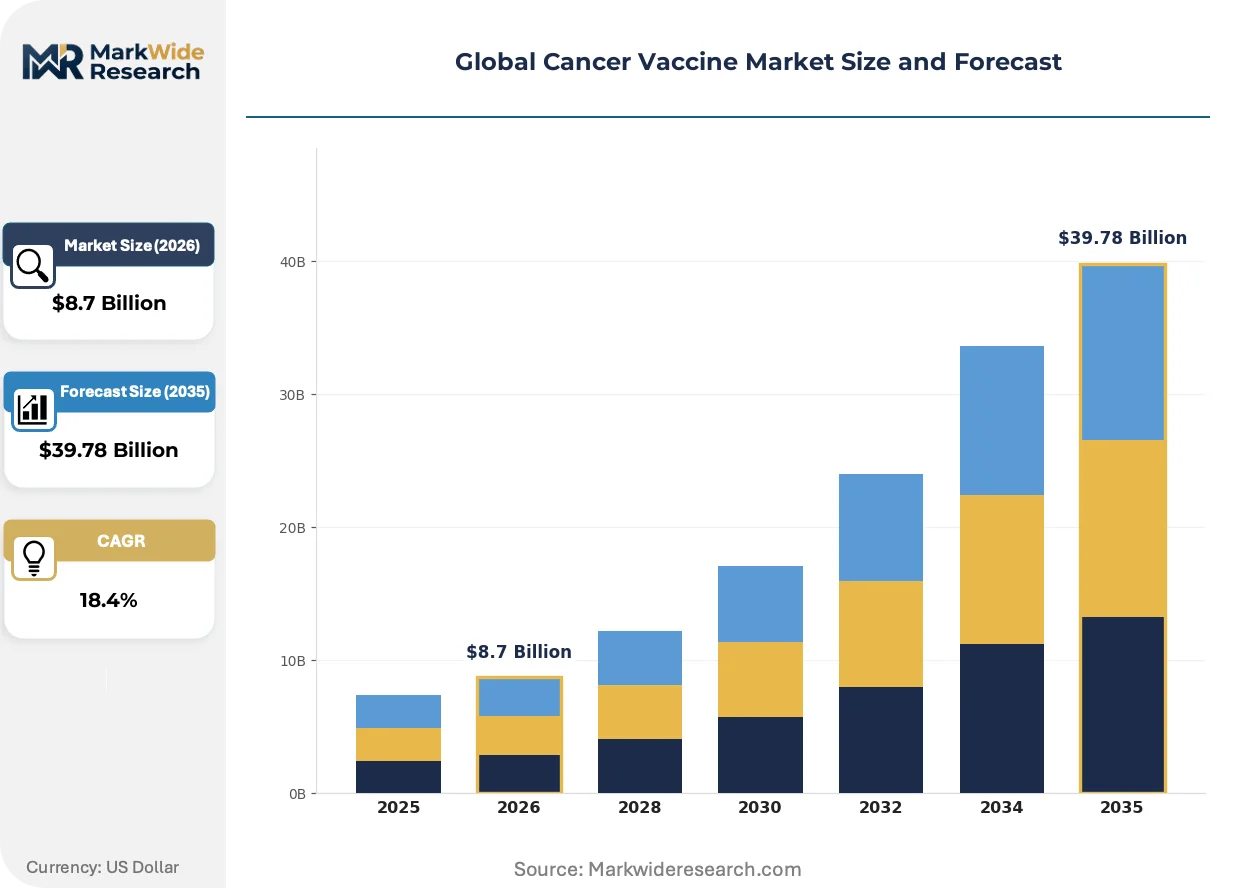
Market Dynamics
Checkpoint inhibitor combination protocols are restructuring cancer vaccine commercialization, forcing developers to demonstrate additive efficacy rather than standalone survival benefit. This clinical integration mandate compresses development timelines while expanding companion diagnostic requirements across therapeutic categories.
Growth Catalysts
- EMA PRIME eligibility:Accelerated assessment pathways compress regulatory review for candidates targeting unmet oncology needs in the European Union.
- Tumor-infiltrating lymphocyte profiling:Biomarker-guided patient selection improves response rates and supports reimbursement negotiations with public payers.
- Academic medical center networks:United States-based NCI-designated cancer centers anchor multi-site neoantigen vaccine trials through coordinated infrastructure.
Market Restraints
- Plasmid DNA supply concentration:Contract manufacturing organizations in Belgium and Germany control critical raw material inputs for mRNA vaccine construction.
- Cold chain infrastructure gaps:Ultra-low temperature storage requirements exclude community oncology practices from therapeutic vaccine administration.
- Reimbursement uncertainty:CMS national coverage determinations lag behind FDA accelerated approvals, creating payment gaps for novel immunotherapy combinations.
Strategic Opportunities
- Japan's regenerative medicine framework:PMDA's conditional early approval system enables commercial access during confirmatory trials for autologous cell therapies.
- HPV-negative oropharyngeal targets:Expanding therapeutic indications beyond viral etiologies opens addressable populations in smoking-related malignancies.
- Direct-to-patient logistics:Temperature-controlled courier networks enable decentralized administration of personalized vaccines outside hospital infusion centers.
Industry Challenges
- Bioinformatics talent scarcity:Neoantigen prediction algorithm development requires specialized computational immunologists with cross-training in oncology and machine learning.
- GMP facility qualification timelines:EU GMP Annex 1 compliance for sterile lipid nanoparticle production extends facility commissioning by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cancer Vaccine Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Vaccines, Preventive Vaccines, DNA Vaccines, RNA Vaccines Therapy Area: Breast Cancer, Melanoma, Cervical Cancer, Prostate Cancer Delivery Mode: Intramuscular, Subcutaneous, Intradermal, Oral End User: Hospitals, Research Institutions, Clinics, Biotech Companies |
| Companies Covered | Merck & Co., Inc., GSK plc, Moderna, Inc., Bristol-Myers Squibb Company, AstraZeneca, Dendreon Pharmaceuticals LLC, Dynavax Technologies, BioNTech SE, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cancer Vaccine Market Emerging Trajectories
Personalized manufacturing workflows are compressing the gap between tumor sequencing and vaccine administration, enabling true point-of-care immunotherapy production. These operational advances are reshaping competitive differentiation around speed-to-treatment rather than cost-per-dose alone.
Lipid nanoparticle encapsulation systems are overtaking viral vector delivery for therapeutic cancer vaccines. Academic medical centers in the United States and Switzerland are adopting mRNA platforms for in-house neoantigen synthesis. This shift is overtaking centralized biologics manufacturing by enabling same-facility production and administration within 4-6 weeks of tumor biopsy.
REACH authorization requirements for novel lipid excipients are tightening supply chain documentation for European manufacturers. The European Chemicals Agency now mandates full substance registration for synthetic ionizable lipids used in nanoparticle formulations. German and Dutch formulation specialists are responding by qualifying alternative excipient suppliers from domestic chemical producers.
Hospital procurement committees are consolidating immunotherapy purchasing through integrated delivery networks rather than individual oncology department contracts. United States-based health systems are negotiating enterprise-wide pricing for therapeutic vaccines across multiple tumor types. This concentration is most visible in Texas and California, where multi-hospital systems command volume-based rebates exceeding standalone academic center arrangements.
Global Cancer Vaccine Market Segmentation
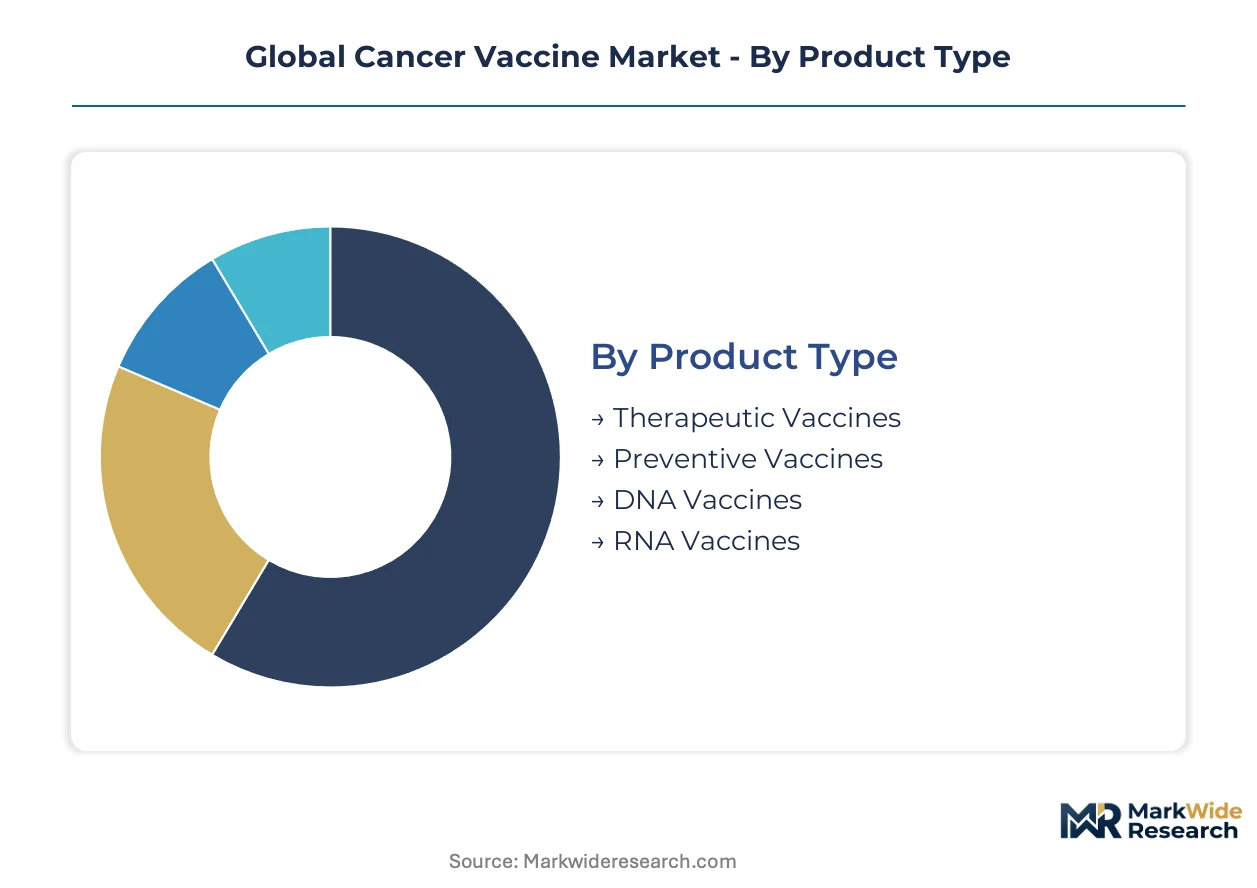
Cancer vaccine segmentation reveals competing imperatives between mass-market preventive formulations and hyper-personalized therapeutic platforms. Each dimension—product architecture, clinical indication, administration route, and procurement channel—carries distinct margin profiles and manufacturing constraints that reshape competitive positioning.
Product Type:
Customization intensity spans from standardized viral-targeting preventives to fully individualized neoantigen therapeutics requiring patient-specific synthesis workflows.
- Therapeutic Vaccines:Autologous or allogeneic formulations designed to treat existing malignancies through tumor-associated antigen presentation. Hospital oncology departments in the United States and Germany are expanding procurement of these products as maintenance regimens following surgical resection or checkpoint inhibitor induction.
- RNA Vaccines:Messenger RNA platforms encoding patient-specific neoantigens synthesized via in vitro transcription and lipid nanoparticle encapsulation. Manufacturing flexibility at BioNTech SE's German facilities and Moderna's Massachusetts operations is compressing production timelines from tumor biopsy to final dose.
- Preventive Vaccines:Prophylactic formulations targeting oncogenic viruses such as human papillomavirus. Established immunization programs sustain predictable demand curves with centralized manufacturing and cold-chain distribution.
- DNA Vaccines:Plasmid-based constructs encoding tumor antigens, amplified through electroporation delivery systems. Clinical validation lags behind RNA platforms due to immunogenicity optimization challenges.
Leading the category by volume: Preventive Vaccines. Growing fastest: RNA Vaccines.
Therapy Area:
Addressable patient populations vary dramatically by tumor mutational burden, neoantigen visibility, and existing standard-of-care competition.
- Melanoma:High tumor mutational burden generates abundant neoantigen targets for personalized vaccine design. Checkpoint inhibitor combination trials at NCI-designated cancer centers in the United States are establishing clinical validation benchmarks for the broader therapeutic vaccine field.
- Breast Cancer:HER2-targeting therapeutic vaccines and triple-negative subtypes with high PD-L1 expression are attracting development investment. Academic medical center networks in Switzerland and the Netherlands are coordinating multi-site trials for adjuvant applications.
- Prostate Cancer:Sipuleucel-T established proof-of-concept for therapeutic vaccines in castration-resistant disease, though subsequent platforms have struggled to demonstrate superior survival benefit.
- Cervical Cancer:HPV-positive tumors retain strong preventive vaccine penetration, limiting therapeutic addressability to HPV-negative or recurrent cases.
Melanoma commands premium pricing due to clinical validation density. Breast cancer applications are expanding fastest as biomarker stratification improves patient selection.
Delivery Mode:
Route selection balances immunogenicity optimization against administration convenience and cold-chain requirements.
- Intramuscular:Standard for mRNA lipid nanoparticle formulations, leveraging established infrastructure from infectious disease vaccination programs. United States hospital systems are qualifying dedicated infusion centers for combination immunotherapy protocols.
- Intradermal:Enhanced antigen-presenting cell engagement through dermal dendritic cell targeting. Swiss and German dermatology clinics are pioneering this route for peptide-based neoantigen vaccines.
- Subcutaneous:Preferred for sustained-release depot formulations and certain viral vector platforms. Community oncology practices favor this route for reduced infrastructure requirements.
- Oral:Limited clinical validation due to gastrointestinal degradation barriers, though mucosal immunity applications in HPV-related malignancies retain exploratory interest.
Intramuscular administration dominates current therapeutic protocols. Intradermal delivery is gaining fastest as dendritic cell targeting science matures.
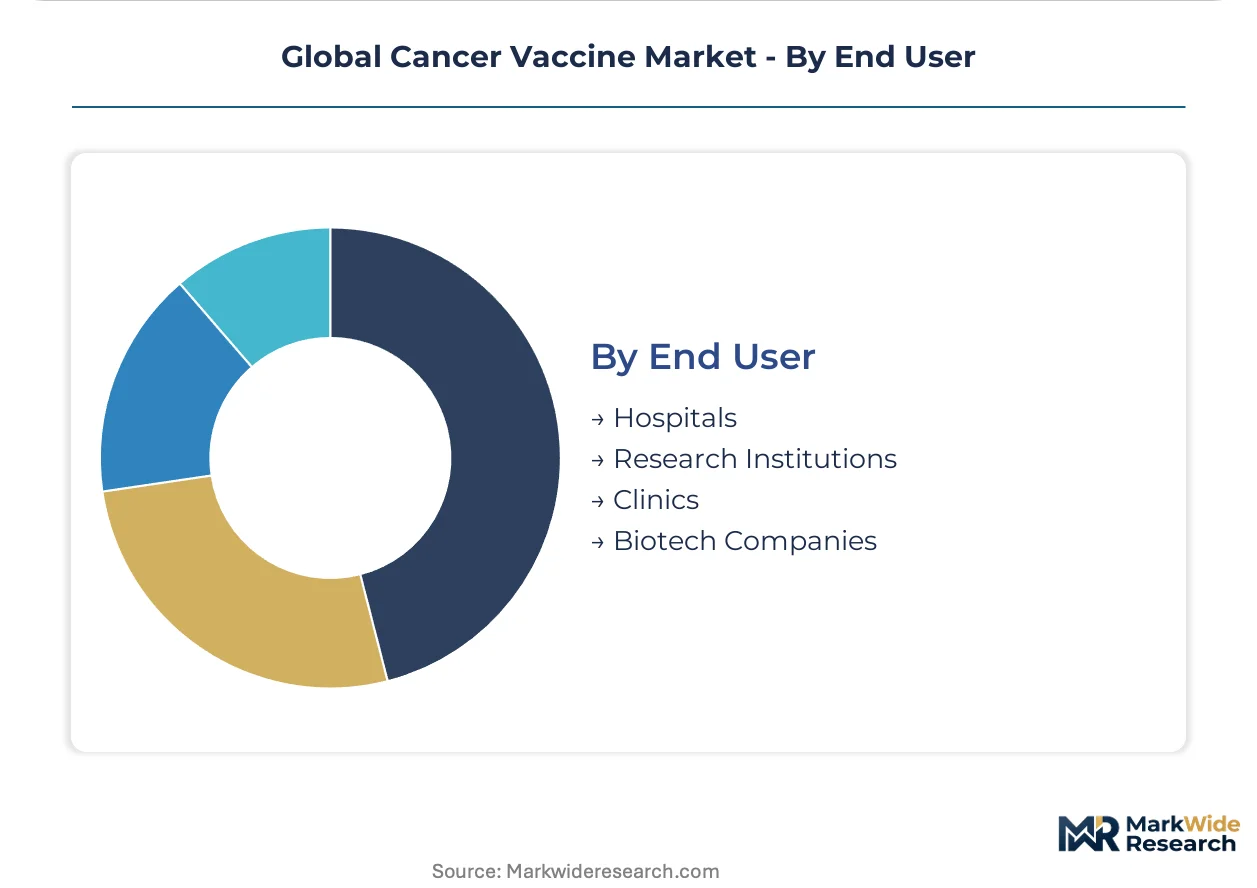
End User:
Procurement authority is consolidating from individual department purchasing toward enterprise-level immunotherapy contracting.
- Hospitals:NCI-designated cancer centers and integrated delivery networks in Texas and California are negotiating volume-based rebates across multiple tumor types. These institutions anchor combination therapy trials requiring inpatient monitoring capabilities.
- Research Institutions:Academic medical centers in Boston, Basel, and Heidelberg are conducting first-in-human neoantigen vaccine studies with dedicated GMP manufacturing suites.
- Biotech Companies:Development-stage firms outsource personalized manufacturing to contract organizations while retaining clinical trial execution in-house.
- Clinics:Community oncology practices face exclusion from therapeutic vaccine administration due to ultra-low temperature storage requirements and companion diagnostic complexity.
Hospitals capture the deepest procurement volume. Research institutions are expanding fastest as decentralized manufacturing enables same-facility production and administration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors therapeutic vaccine development through its dense concentration of NCI-designated cancer centers and academic medical institutions. The metropolitan area hosts coordinated neoantigen trial networks that compress patient enrollment timelines. Manufacturing partnerships with regional contract organizations enable same-facility production and administration workflows.
United States
The National Cancer Institute's Cancer Moonshot initiative funds extensive neoantigen vaccine trials through designated cancer centers in Texas and California. FDA breakthrough therapy designation pathways compress clinical validation timelines for novel mRNA platforms. Hospital procurement committees in integrated delivery networks negotiate enterprise-wide immunotherapy pricing across multiple tumor types.
Germany
BioNTech SE's manufacturing facilities in Mainz anchor European mRNA production scale for individualized neoantigen platforms. EMA PRIME eligibility schemes accelerate regulatory assessment for candidates targeting unmet oncology needs. REACH authorization requirements for novel lipid excipients tighten supply chain documentation through the European Chemicals Agency.
Switzerland
Academic medical centers in Basel coordinate multi-site adjuvant vaccine trials for breast cancer applications through specialized immunotherapy networks. Swissmedic maintains alignment with EMA centralized procedures while enabling rapid national authorization for priority therapeutics. The Basel-Zurich corridor concentrates formulation specialists responding to domestic chemical producer qualification requirements.
Japan
PMDA's conditional early approval system enables commercial access during confirmatory trials for autologous cell therapies in oncology. METI funding streams support regenerative medicine manufacturing infrastructure development in the Kanto region. Tokyo-based hospital networks integrate personalized vaccine protocols into standard maintenance regimens following surgical resection.
United Kingdom
London's academic medical centers conduct first-in-human neoantigen vaccine studies with dedicated GMP manufacturing suites for lipid nanoparticle formulations. MHRA operates post-Brexit recognition pathways with EMA procedures while maintaining independent accelerated assessment for breakthrough therapies. The Cambridge-London corridor attracts bioinformatics talent for neoantigen prediction algorithm development.
Global Cancer Vaccine Market Vendor Landscape
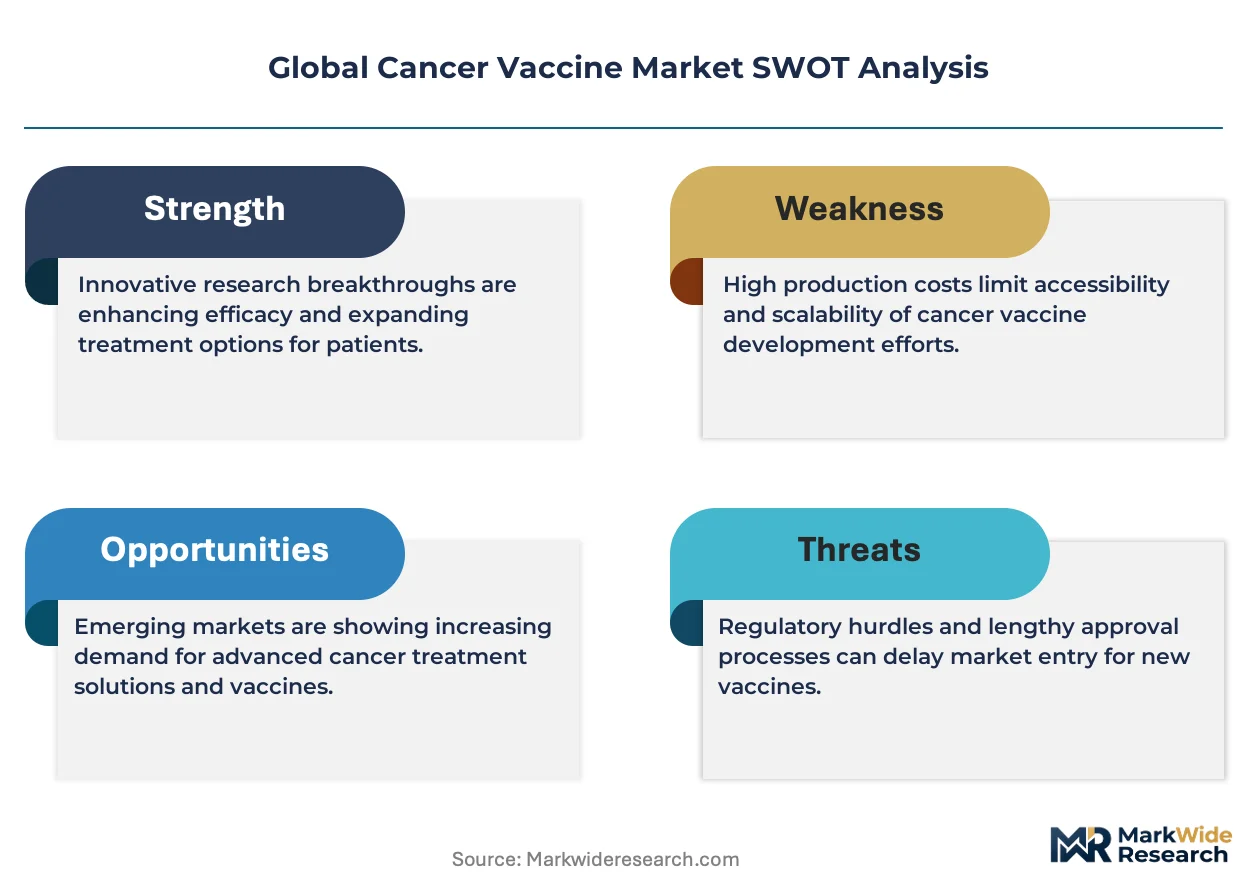
Capital-heavy producers compete with asset-light designers across the cancer vaccine landscape, with integrated pharmaceutical conglomerates maintaining GMP manufacturing infrastructure while biotechnology specialists outsource personalized production workflows. The market structure concentrates around checkpoint inhibitor combination protocols that force developers to demonstrate additive efficacy. Three archetypes dominate: mRNA platform specialists with manufacturing scale advantages, adjuvant system developers enhancing cellular immune responses, and personalized medicine operators compressing tumor-to-dose timelines. Dominant competitive moves include strategic partnerships anchoring combination therapy development and backward integration into plasmid DNA supply chains.
Among German-based mRNA platform operators, BioNTech SE exemplifies the manufacturing-scale archetype through its individualized neoantigen production infrastructure. Merck & Co., Inc. occupies a position within the checkpoint inhibitor combination tier, leveraging existing oncology infrastructure. GSK plc represents the specialized adjuvant development segment, focusing on cellular immune response enhancement rather than direct antigen delivery platforms.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GSK plc |
| Moderna, Inc. |
| Bristol-Myers Squibb Company |
| AstraZeneca |
| Dendreon Pharmaceuticals LLC |
| Dynavax Technologies |
| BioNTech SE |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
EU GMP Annex 1 sterility requirements gate qualified supply for lipid nanoparticle formulations and anchor premium-tier pricing access for compliant manufacturers. REACH authorization mandates for novel synthetic lipids further tighten documentation burdens, compressing margins for non-integrated players while rewarding backward integration into domestic chemical supply.
Pricing Analysis
Value-based reimbursement tied to progression-free survival anchors pricing for therapeutic cancer vaccines, with outcome guarantees commanding premium positioning against standard-of-care benchmarks. Price differentiation separates GMP-certified autologous platforms from research-grade formulations, while volume-scale contracts through United States integrated delivery networks exert downward pressure on per-dose economics. Hospital procurement committees demonstrate highest price sensitivity in community oncology settings, whereas NCI-designated cancer centers prioritize clinical validation density over unit cost.
Supply Chain Analysis
Domestic-content mandates in Japan's regenerative medicine framework and United States biosecurity initiatives are reshaping sourcing patterns for plasmid DNA and lipid excipients. Manufacturing concentrates in Germany, Belgium, and the United States, with critical inputs drawing from specialized chemical producers in the Netherlands and Switzerland. Single-source vulnerability pervades ionizable lipid supply, where ECHA registration requirements restrict qualified suppliers. Distribution runs through temperature-controlled courier networks enabling direct-to-patient logistics outside traditional hospital infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU GMP Annex 1 facility qualification creates an 18-24 month barrier-to-entry moat for sterile lipid nanoparticle producers.
For Market Incumbents: Lock in plasmid DNA supply through captive production or long-term offtake agreements with Belgian and German contract manufacturers. Expand GMP manufacturing footprint in United States NCI-designated cancer centers to compress tumor-to-dose timelines against emerging mRNA platform competitors.
For New Entrants and Emerging Players: Capture white-space in HPV-negative oropharyngeal malignancies where smoking-related populations lack established therapeutic vaccine protocols. Japan's PMDA conditional approval pathway offers the most penetrable regulatory geography for autologous cell therapy developers seeking commercial access during confirmatory trials.
For Investors and Strategic Acquirers: First FDA breakthrough therapy designation for a personalized neoantigen vaccine in solid tumors beyond melanoma is the leading indicator that checkpoint inhibitor combination protocols are expanding addressable populations. Target acquisition profiles center on bioinformatics platforms with validated neoantigen prediction algorithms and existing GMP manufacturing partnerships. Watch for CMS national coverage determinations closing reimbursement gaps as the inflection signal for mainstream adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | NCI Cancer Moonshot funding accelerates patient enrollment across multi-site neoantigen studies. |
| Manufacturing Scale-Up | BioNTech SE's Mainz facilities anchor European mRNA production capacity for individualized platforms. |
| Regulatory Approval Pathway | EMA PRIME eligibility compresses assessment timelines for candidates addressing unmet oncology needs. |
| Backward Integration | In-house plasmid DNA production insulates against Belgian and German CMO concentration risk. |
| Licensing Agreement | Checkpoint inhibitor partnerships with Merck & Co. validate combination therapy efficacy benchmarks. |
Methodological Framework
Multi-period observation of FDA breakthrough therapy designations, EMA PRIME eligibility awards, and CMS national coverage determinations anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, ClinicalTrials.gov records, EMA assessment reports, and hospital formulary databases. Bottom-up patient-flow modeling across tumor types triangulated against top-down manufacturer capacity disclosures.
Segment-weighting applied product-type splits across therapeutic, RNA, preventive, and DNA vaccine categories, with therapy-area disaggregation by melanoma, breast, prostate, and cervical indications. Administration route, end-user channel, and regional regulatory cluster dimensions informed volume allocation. CAGRs derived from logistic growth curve fitting to clinical trial enrollment trajectories and manufacturing capacity expansion announcements, with checkpoint inhibitor combination protocol adoption rates serving as primary demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bioinformatics talent scarcity, plasmid DNA supply disruptions, and evolving real-world evidence requirements for accelerated approvals. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Cell and Gene Therapy Manufacturing Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market