
 In Vivo CRO Market | 2026-2036
In Vivo CRO Market Size, Share, and Industry Trends Forecast 2026-2036
In Vivo CRO Market Intelligence
Biotechnology firms are rotating toward full-service in vivo CRO partnerships as complex modalities strain internal capabilities. Syneos Health leverages integrated site and laboratory networks to capture multi-year outsourcing contracts. WuXi AppTec anchors global capacity through its Shanghai and Suzhou campuses with significant rodent and non-rodent capacity. Charles River Laboratories dominates the North American toxicology segment with purpose-built facilities for GLP safety assessment.
In vivo contract research organizations execute pharmacology, toxicology, and efficacy studies using live animal models under controlled laboratory conditions, typically requiring GLP compliance, species-specific husbandry protocols, and validated bioanalytical methods to generate regulatory-submission data for drug developers. Toxicology studies generate the largest revenue pool within service type segmentation due to mandatory safety requirements across all therapeutic classes, while pharmacology applications in immuno-oncology represent the fastest-expanding demand category as checkpoint inhibitor and cell therapy pipelines mature. Imaging techniques within technology segmentation command premium pricing structures owing to capital intensity and specialized operator training requirements.
FDA GLP regulations and EMA Good Laboratory Practice standards enforce data integrity and study reconstruction requirements that determine market access for CRO deliverables. EPA and OECD Test Guidelines further shape environmental and chemical safety assessment protocols that dictate service line expansion decisions. Stakeholders must monitor evolving FDA guidance on alternative methods and 3Rs implementation as these frameworks progressively determine acceptable study designs and species selection criteria.

Market Dynamics
Biotechnology firms now outsource complex pharmacology studies to specialized CROs as internal capabilities strain against cell therapy pipeline complexity. This structural shift toward full-service partnerships concentrates contract value among vendors with integrated toxicology and bioanalytical platforms.
Growth Catalysts
- NIH funding expansion:United States federal research budgets sustain preclinical study demand through academic and biotech channels. Direct grant flows accelerate outsourcing decisions.
- FDA Animal Rule pathway:Biodefense and orphan disease indications create specialized study requirements that only GLP-certified CROs can fulfill. Regulatory mandates pull contract volume toward qualified vendors.
- Cell therapy pipelines:Immuno-oncology developers require species-specific tumor models and imaging endpoints. Complex modalities demand external expertise.
Market Restraints
- Non-human primate supply concentration:Southeast Asian breeding colonies face export restrictions and disease surveillance requirements. Supply volatility disrupts study timelines.
- GLP facility capital intensity:Purpose-built vivarium construction requires specialized HVAC, waste containment, and pathogen exclusion systems. Fixed costs barrier entry for mid-scale competitors.
- 3Rs regulatory pressure:EMA and FDA guidance on reduction, refinement, and replacement progressively limits acceptable species selection. Methodology constraints compress addressable study types.
Strategic Opportunities
- India preclinical capacity:CDSCO alignment with OECD Test Guidelines positions Indian CROs for Western sponsor contracts. Cost arbitrage meets regulatory equivalence.
- Imaging-integrated pharmacology:PET-CT and MRI endpoints converge with traditional histopathology. Technology fusion enables premium service tiers.
- Japan PMDA consultation pathways:Early engagement mechanisms reward CROs with local regulatory intelligence. Proximity to review processes attracts sponsor investment.
Industry Challenges
- Veterinary pathologist scarcity:Board-certified toxicologic pathologists command compensation premiums that compress CRO margins. Talent competition intensifies with pharmaceutical employers.
- Legacy data system integration:Electronic data capture platforms from multiple acquisition histories resist interoperability. Study reconstruction across systems risks GLP audit findings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vivo CRO Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Protocol Development, In Vitro Services, Toxicology Studies, Regulatory Services End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Manufacturers Technology: Imaging Techniques, Genomics, Pharmacology, Bioinformatics Application: Drug Discovery, Preclinical Testing, Efficacy Studies, Disease Models |
| Companies Covered | Syneos Health, WuXi AppTec, IQVIA, Crown Bioscience, Parexel International, ICON plc, Laboratory Corporation of America, Pharmaceutical Product Development, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vivo CRO Market Strategic Shifts & Innovations
Preclinical research is fragmenting across technology modalities as sponsors demand specialized capabilities that single vendors rarely consolidate. This dispersion creates partnership networks rather than consolidated procurement.
Patient-derived xenograft (PDX) models are fragmenting traditional cell-line-based oncology pharmacology. Biotech sponsors now specify PDX panels for mechanism-of-action studies. This capability requirement splits contract awards between oncology-specialist CROs and generalist providers lacking tumor bank depth.
EMA's revised guidance on non-clinical safety studies for biotechnology-derived pharmaceuticals tightens immunogenicity assessment requirements. CROs must validate anti-drug antibody assays alongside standard toxicology endpoints. European biotech sponsors now prioritize vendors with integrated immunology laboratories.
Sponsor procurement teams now unbundle large toxicology programs into discrete study awards. Biotech firms issue separate contracts for rodent and non-rodent segments, enabling parallel vendor qualification. This behavior is most pronounced among venture-backed US developers managing milestone-dependent cash flows.
In Vivo CRO Market Segmentation
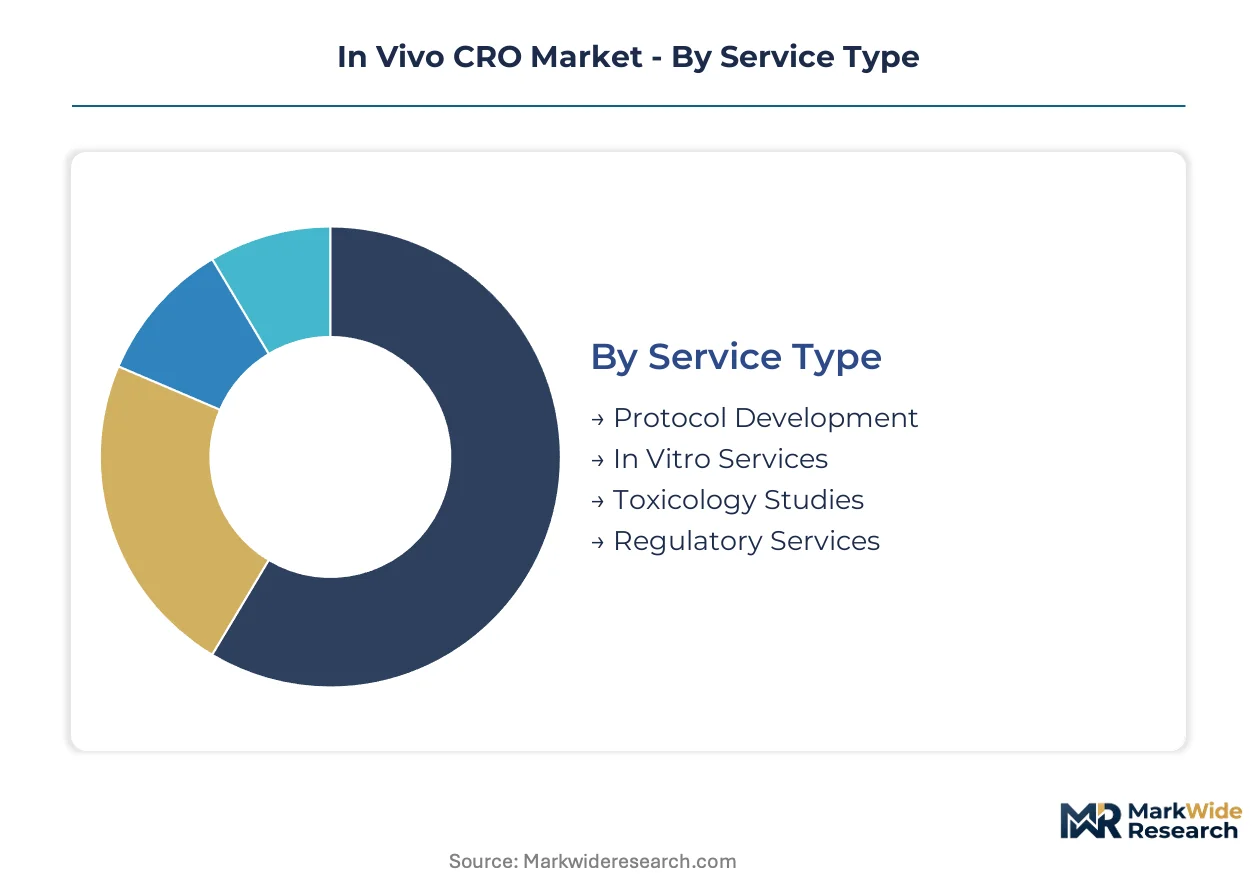
Service specialization determines vendor selection criteria across the In Vivo CRO Market. Biotechnology sponsors unbundle complex programs, forcing CROs to declare segment-specific capabilities rather than claim universal coverage.
Service Type:
Substitution pressure from alternative methods and in silico modeling concentrates most acutely on early-stage protocol development, while GLP-mandated toxicology maintains regulatory insulation against displacement.
- Toxicology Studies:GLP-compliant safety assessment protocols evaluate acute, chronic, and reproductive toxicity across rodent and non-rodent species. Demand concentrates among FDA-regulated sponsors in the United States where IND-enabling packages require standardized study designs. Mandatory regulatory submission creates pricing power for certified facilities.
- Regulatory Services:Consultation pathways navigate FDA Animal Rule applications, EMA scientific advice procedures, and PMDA pre-submission meetings. Japanese biotech sponsors prioritize CROs with Tokyo-based regulatory intelligence capabilities. Early engagement mechanisms compress approval timelines for orphan indications.
- Protocol Development:Study design optimization for species selection, dose-ranging, and endpoint validation. Sponsors increasingly retain this function in-house.
- In Vitro Services:Ex vivo tissue assays and cell-based screening support mechanistic understanding. Absorption and metabolism studies precede in vivo initiation.
Toxicology studies anchor the volume base while regulatory services gains share at the steepest rate.
End User:
Customer-type economics split sharply between cash-constrained venture-backed developers and multinational pharmaceutical procurement functions with multi-year master service agreements.
- Biotechnology Firms:Cell therapy and gene editing pipelines strain internal pharmacology capabilities. These sponsors demand integrated imaging and bioanalytical platforms from single vendors. NIH grant flows and venture formation in Boston and San Francisco accelerate outsourcing velocity.
- Pharmaceutical Companies:Large-cap developers maintain selective outsourcing for capacity overflow and specialized modalities. Toxicology programs above a threshold value typically route to preferred CRO panels with pre-negotiated rates.
- Academic Institutions:NIH-funded principal investigators outsource GLP-compliant segments while retaining exploratory pharmacology internally. Budget constraints favor cost-competitive vendors.
- Contract Manufacturers:CDMOs extend service portfolios through CRO partnerships rather than captive vivarium investment. Relationship-based procurement dominates.
Biotechnology firms anchor the volume base while academic institutions expand most quickly as federal research budgets climb.
Technology:
Capital intensity and operator training requirements stratify pricing power across modalities, with imaging commanding premiums against commoditized genomics services.
- Imaging Techniques:PET-CT, MRI, and optical imaging enable longitudinal pharmacodynamic assessment without terminal sacrifice. Immuno-oncology developers in the United States specify imaging endpoints for checkpoint inhibitor studies. Equipment amortization and radiochemistry expertise sustain margin structures.
- Pharmacology:Efficacy modeling in tumor xenografts, autoimmune disease, and infectious disease indications. Patient-derived xenograft capabilities differentiate oncology-specialist CROs.
- Genomics:Transcriptomic and epigenetic profiling of treatment response. Platform standardization compresses pricing.
- Bioinformatics:Data integration across histopathology, biomarker, and clinical observation streams. Computational biology talent scarcity constrains expansion.
Pharmacology anchors the volume base while imaging techniques climb the fastest as longitudinal endpoints displace terminal assessments.
Application:
Pipeline-stage economics concentrate contract value in preclinical testing while discovery-phase work faces displacement from artificial intelligence target identification.
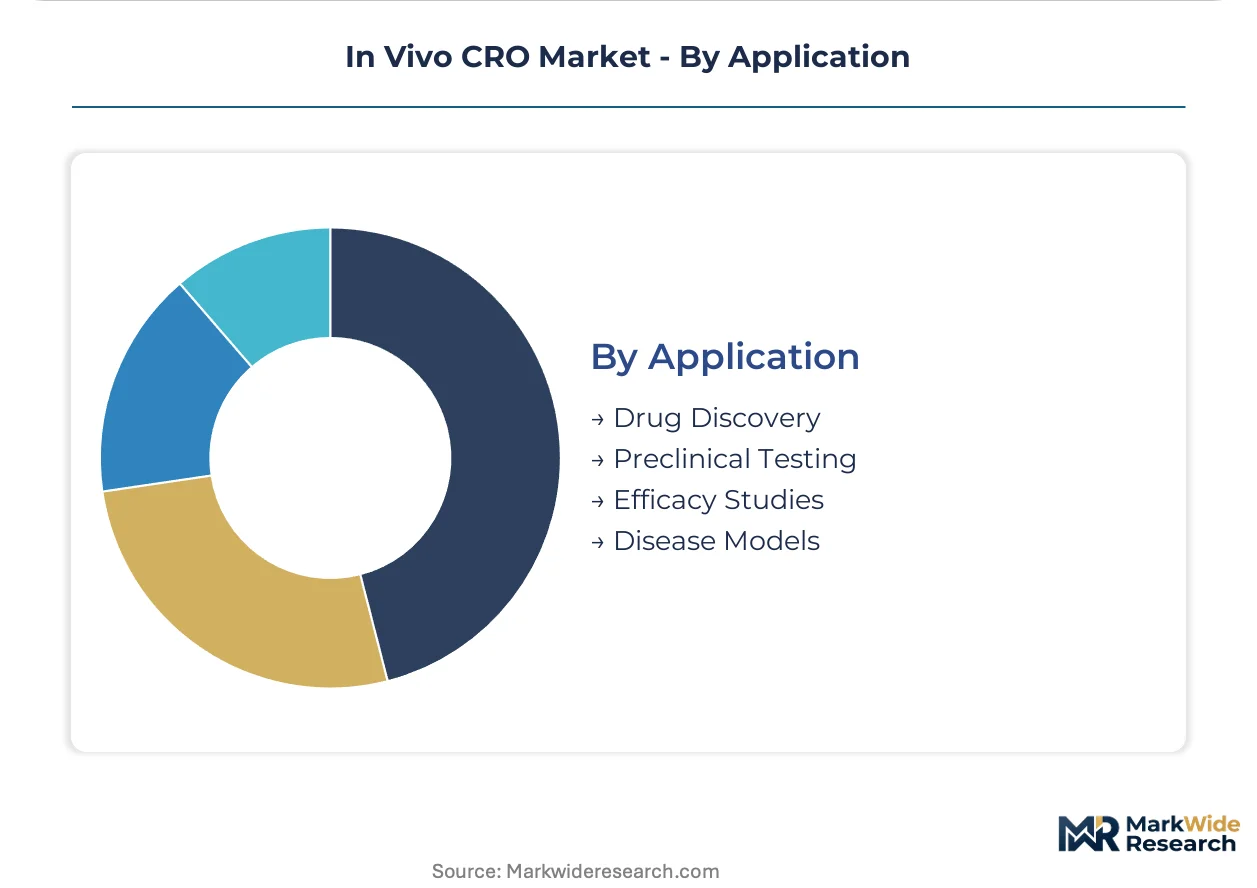
- Preclinical Testing:GLP toxicology and safety pharmacology programs generate IND-enabling data packages. FDA and EMA submission requirements sustain demand regardless of therapeutic modality. United States-based sponsors drive the largest contract values.
- Drug Discovery:Target validation and lead optimization studies precede formal development. In silico methods and organ-on-chip technologies erode addressable scope.
- Efficacy Studies:Mechanism-of-action confirmation and comparative effectiveness assessment. Cell therapy developers require species-specific tumor models.
- Disease Models:Custom model development for rare indications and biodefense applications. The FDA Animal Rule pathway creates specialized demand.
Preclinical testing anchors the volume base while disease models expand most quickly as orphan indication pipelines multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preclinical outsourcing flows from the United States toward specialized facilities in China and India, while European sponsors retain regional capacity for GLP-mandated toxicology programs. NIH grant disbursements and FDA submission requirements anchor North American demand, whereas cost arbitrage drives sponsor investment in Asian CRO infrastructure.
United States
Boston and San Francisco biotech clusters generate concentrated demand for IND-enabling toxicology packages. FDA GLP regulations and the Animal Rule pathway for biodefense indications create specialized study requirements that only certified vendors can fulfill. Charles River Laboratories anchors North American capacity through purpose-built vivarium facilities in Massachusetts and North Carolina.
China
WuXi AppTec's Shanghai and Suzhou campuses supply rodent and non-rodent capacity to Western pharmaceutical sponsors. NMPA alignment with OECD Test Guidelines enables dual submission packages for FDA and Chinese regulators. Yangtze River Delta biotech formation accelerates domestic CRO utilization alongside export-oriented contract research.
Germany
EMA scientific advice procedures and centralized marketing authorization pathways concentrate regulatory service demand in Frankfurt and Munich corridors. German pharmaceutical sponsors maintain selective outsourcing relationships for specialized pharmacology models. Heidelberg and Berlin academic-industry partnerships generate early-stage study volume.
India
CDSCO harmonization with OECD standards positions Indian CROs for Western sponsor contracts across toxicology and bioanalytical segments. Cost-competitive vivarium operations in Hyderabad and Bangalore attract mid-cap biotech procurement. Contract value concentrates in non-GLP discovery support while GLP capacity expands through facility investment.
Japan
PMDA pre-submission consultation mechanisms reward CROs with Tokyo-based regulatory intelligence capabilities. Japanese biotech sponsors prioritize vendors with local pharmacology expertise and imaging platform access. Osaka and Kansai region academic medical centers generate patient-derived model demand for mechanism-of-action studies.
In Vivo CRO Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base stratifies into three tiers: integrated full-service networks, regional capacity specialists, and modality-focused boutiques. Publicly traded CROs leverage acquisition programs to consolidate toxicology and bioanalytical capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves as sponsors demand single-vendor accountability for complex cell therapy programs.
Among North American-listed operators, Charles River Laboratories and Laboratory Corporation of America exemplify the integrated network archetype through combined site and laboratory infrastructure. Syneos Health occupies a position bridging clinical and preclinical service delivery. WuXi AppTec represents the Asia-anchored global capacity model with significant rodent and non-rodent operations.
| Leading Market Players |
|---|
| Syneos Health |
| WuXi AppTec |
| IQVIA |
| Crown Bioscience |
| Parexel International |
| ICON plc |
| Laboratory Corporation of America |
| Pharmaceutical Product Development |
| Charles River Laboratories |
| Others |
Cost & Logistics Intelligence
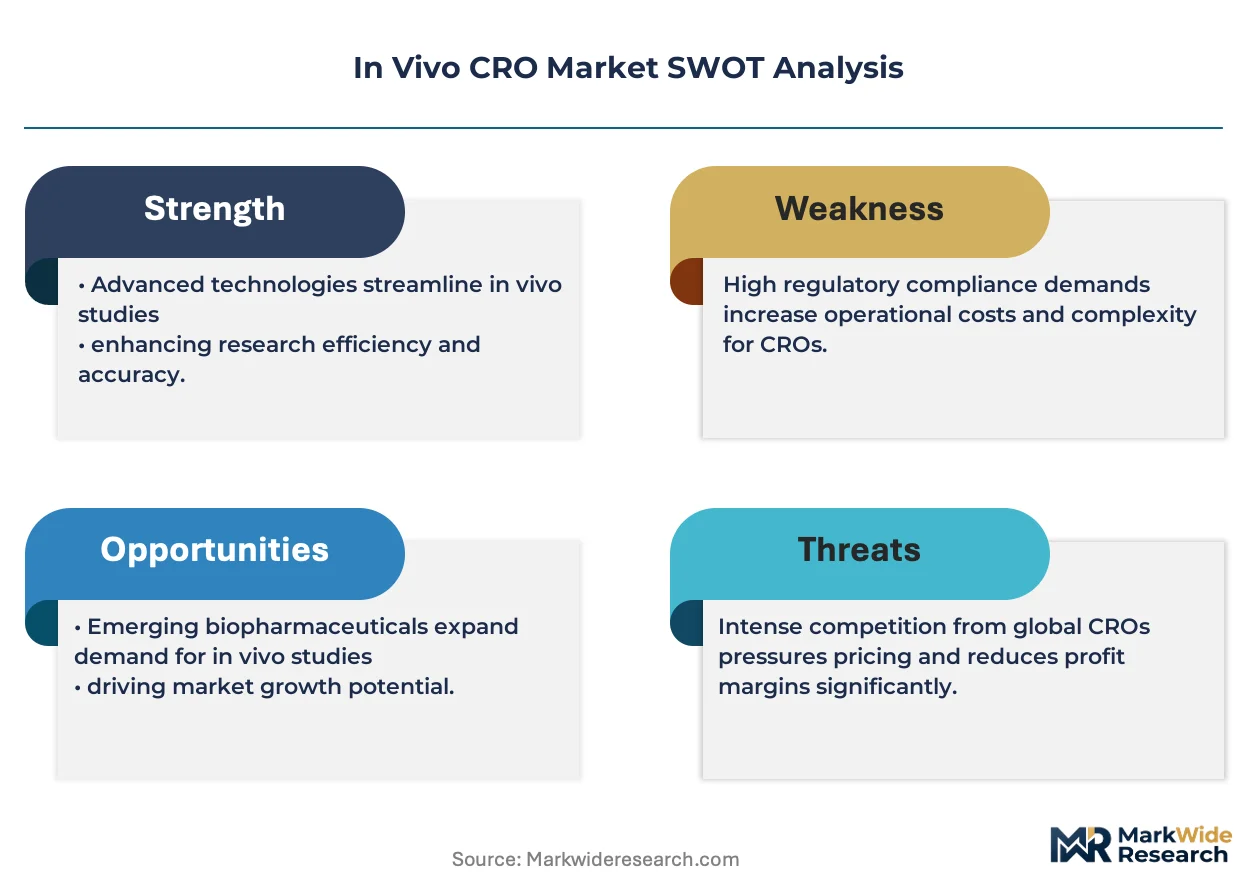
GLP facility utilization rates above 85 percent anchor price floors across North American and European markets, concentrating supply power among operators with purpose-built vivarium infrastructure while compressing margins for mid-scale competitors lacking species diversification. Scale economies in non-human primate breeding colonies and imaging platform amortization create tiered cost structures that propagate through contract pricing.
Pricing Analysis
Next-generation imaging-integrated pharmacology commands 40-60 percent premiums over standard histopathology endpoints, while legacy toxicology services face commoditization pressure from Indian and Chinese capacity expansion. Three-tier pricing structure across premium, standard, and economy levels separates FDA GLP-certified facilities from OECD-aligned regional operators and non-GLP discovery shops. Cost compression in standard toxicology segments is intensifying because sponsor procurement teams unbundle programs for parallel vendor qualification. Biotechnology firms with milestone-dependent cash flows exhibit highest price sensitivity, while multinational pharmaceutical procurement functions with multi-year master service agreements demonstrate lowest sensitivity.
Supply Chain Analysis
Strategic stockpiling of specific-pathogen-free rodent breeding pairs and cryopreserved embryo inventories dominates inventory strategy, contrasting with just-in-time reagent procurement for bioanalytical assays. Geographic supply concentration centers on the United States, China, and India for vivarium operations, with Southeast Asian breeding colonies supplying non-human primate cohorts. Raw material dependencies include specialized feed formulations, veterinary pharmaceuticals, and radiochemistry isotopes for imaging endpoints. Single-source vulnerability in non-human primate supply creates systemic risk from export restriction policies. Distribution runs through sponsor-directed logistics networks with temperature-controlled chain custody from CRO facility to study termination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In silico modeling and organ-on-chip technologies present viable substitution threats to early-stage in vivo pharmacology, forcing incumbents to defend core GLP toxicology relationships and imaging-integrated service tiers.
For Market Incumbents: Secure exclusive multi-year contracts with top-20 biotechnology sponsors by embedding bioanalytical and regulatory consulting capabilities within toxicology programs. Deepen backward integration into patient-derived xenograft model banks to differentiate oncology service offerings from generalist competitors. Priority defensive moves center on veterinary pathologist talent retention and GLP facility capacity expansion in Boston and San Francisco corridor proximity. For New Entrants and Emerging Players: Differentiate on CDSCO-aligned GLP certification combined with cost-competitive vivarium operations in Hyderabad and Bangalore corridors. White-space targets include imaging-integrated pharmacology for cell therapy developers and regulatory intelligence services for PMDA consultation pathways. Most penetrable segment: mid-cap biotechnology firms managing IND-enabling study timelines with constrained internal capabilities. For Investors and Strategic Acquirers: Imaging-platform CROs with PET-CT and MRI capabilities anchored in United States biotech clusters represent the most attractive acquisition archetype for long-term viability across the 5-10 year window. Signal to watch: FDA guidance acceleration on alternative methods and 3Rs implementation that would compress addressable toxicology volumes and redirect capital toward technology-integrated service models.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Facility Capacity Expansion | Positions operators to capture IND-enabling toxicology volume from FDA-regulated sponsors. |
| Imaging Platform Integration | Enables longitudinal pharmacodynamic endpoints that command premium pricing from immuno-oncology developers. |
| Patient-Derived Xenograft Model Bank Acquisition | Differentiates oncology pharmacology capabilities from commoditized cell-line-based competitors. |
| Regulatory Intelligence Service Launch | Captures FDA Animal Rule and PMDA consultation pathway demand from orphan indication sponsors. |
| CDSCO Alignment Certification | Unlocks Western sponsor contracts through OECD Test Guidelines equivalence for Indian CRO operations. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, CRO procurement managers, and toxicology study directors; and secondary validation through FDA GLP inspection records, EMA scientific advice procedures, NIH grant disbursement databases, and OECD Test Guidelines harmonization documentation. Bottom-up triangulation across service-type volume estimates and top-down cross-check against end-user spending patterns anchored forecast integrity.
Across the analysis window, the analytical framework modeled segmentation dimensions including service type, end-user archetype, technology modality, and regional regulatory cluster. CAGRs were derived from sponsor pipeline velocity, federal research budget trajectories, and facility capacity expansion announcements. Industry-specific forecast inputs incorporated cell therapy pipeline maturation rates and FDA guidance evolution on alternative methods.
Material uncertainties — regulatory restriction shifts in non-human primate export, 3Rs implementation acceleration, and sponsor unbundling behavior intensification — sit outside the modeled envelope. Forecasts reflect assumptions around GLP certification maintenance and OECD alignment persistence. Revision becomes warranted when FDA alternative methods guidance crosses implementation thresholds that materially displace traditional study designs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Plasmid DNA Preparation Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Asia-Pacific Biotechnology Market