
 Caustic Soda Market | 2026-2036
Caustic Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Caustic Soda Market Analysis
Water treatment utilities are rotating toward higher-purity caustic soda grades as municipal infrastructure upgrades accelerate. The Dow Chemical Company anchors North American supply through integrated chlor-alkali assets on the US Gulf Coast. Olin Corporation competes on membrane cell technology leadership, sustaining cost advantages across its Ohio River Valley production network. BASF SE differentiates via captive supply integration into European specialty chemical value chains.
Caustic soda is sodium hydroxide, an inorganic compound produced primarily through the chlor-alkali process using membrane, diaphragm, or mercury cell technologies, with membrane cells now dominating due to lower energy consumption and mercury-free output. Liquid caustic soda commands the largest volume share due to ease of handling in bulk industrial applications, while flake caustic soda captures premium pricing from soap and detergent manufacturers requiring precise dosing control. Pulp and paper applications remain structurally mature in North America and Europe, whereas water treatment represents the fastest-growing application segment as utilities confront stricter discharge limits.
EPA effluent guidelines and OSHA process safety management standards govern US production and handling, while REACH registration requirements in Europe restrict import pathways for non-compliant Asian producers. India's BIS certification mandates and China's GB standards on chlor-alkali energy consumption collectively reshape competitive access across the three largest demand centers. Stakeholders must monitor regulatory divergence between membrane-grade specifications and mercury-cell legacy capacity as compliance timelines tighten.
Market Dynamics
Membrane cell technology is consolidating production economics across the chlor-alkali value chain, compressing legacy mercury-cell margins while EPA and MEE compliance timelines accelerate asset turnover decisions.
Growth Catalysts
- EPA Effluent Guidelines:Municipal water treatment utilities face stricter discharge limits, expanding membrane-grade caustic soda procurement for pH neutralization in secondary treatment processes.
- India's BIS Certification Mandate:Standardized product specifications are displacing unstandardized imports across chemical manufacturing clusters in Gujarat and Maharashtra.
- Membrane Cell Electrification:Lower energy intensity per ton of chlorine equivalent is pulling capacity investments toward membrane technology retrofits and greenfield builds.
Market Restraints
- Electricity Cost Volatility:Chlor-alkali production remains power-intensive, with European producers exposed to natural gas-linked grid pricing that compresses operating margins during peak demand periods.
- Supply Concentration Risk:US Gulf Coast integrated producers anchor North American supply, creating geographic vulnerability to hurricane-related logistics disruptions.
- Substitution Pressure:Soda ash competes in certain pH adjustment applications, particularly in glass manufacturing and some water treatment contexts where lower alkalinity suffices.
Strategic Opportunities
- India's Chemical Manufacturing Expansion:Domestic chlor-alkali capacity is underpenetrated relative to downstream demand growth in textiles and alumina refining.
- China's Dual Carbon Goals:MEE energy intensity standards are creating compliance-driven replacement demand for inefficient legacy capacity.
- Digital Procurement Platforms:Bulk chemical marketplaces are emerging as direct channels between membrane-grade producers and mid-sized water treatment operators, compressing distributor margins.
Industry Challenges
- Membrane Cell Technician Scarcity:Specialized electrochemical engineering expertise required for zero-gap cell maintenance is concentrated among aging workforces in Germany and Japan.
- REACH Registration Timelines:European importers face extended compliance documentation requirements that delay Asian supply qualification.
- Legacy Asset Stranding:Mercury-cell phase-out deadlines are forcing accelerated depreciation schedules for remaining diaphragm and mercury capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caustic Soda Market |
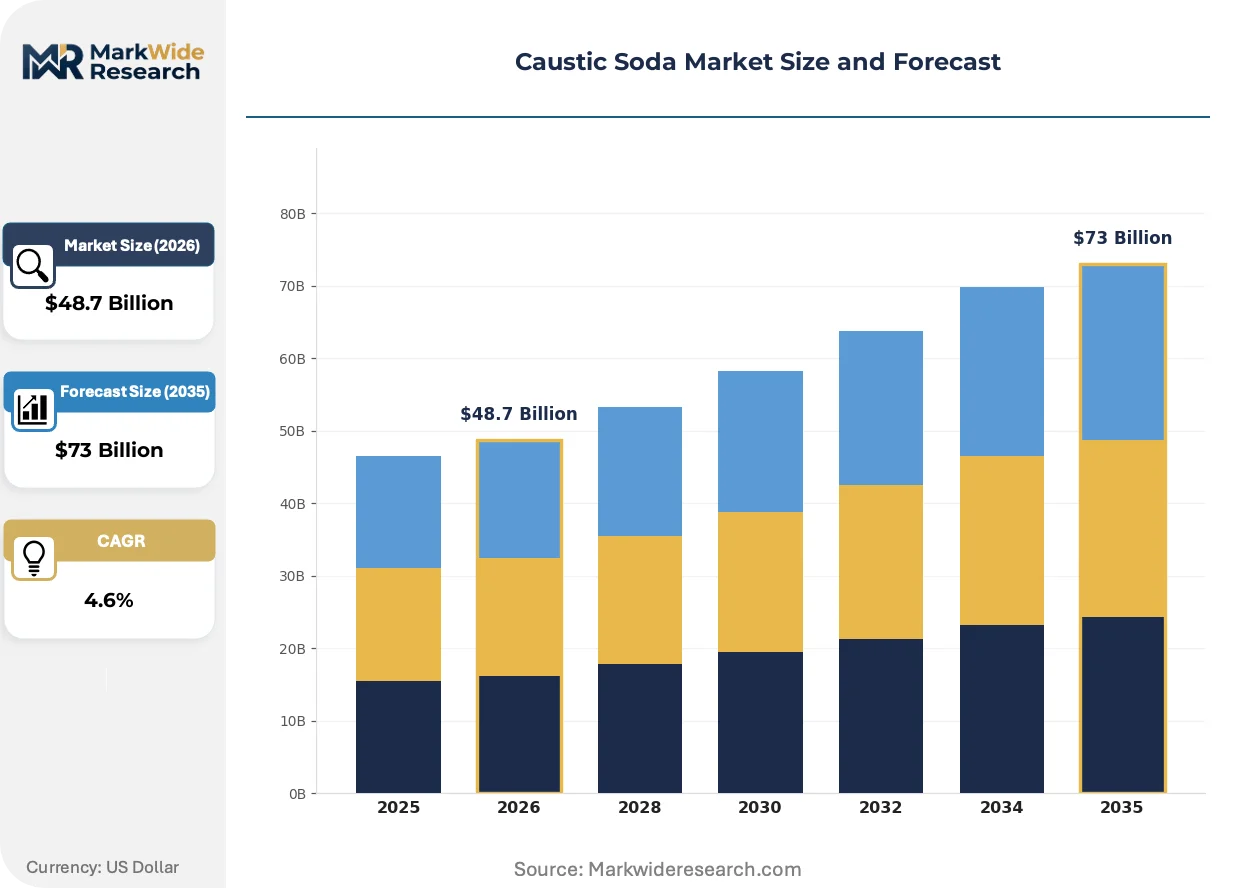
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Caustic Soda, Solid Caustic Soda, Flake Caustic Soda, Pearled Caustic Soda Application: Pulp & Paper, Textile, Cleaners, Water Treatment End User: Chemical Manufacturing, Food Processing, Soap & Detergent, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Retail, Export |
| Companies Covered | The Dow Chemical Company, Occidental Petroleum Corporation, Olin Corporation, Westlake Corporation, Formosa Plastics Corporation, BASF SE, INEOS, PPG Industries, Saudi Basic Industries Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caustic Soda Market Emerging Trajectories
Electrification of production processes and regulatory tightening on energy intensity are compressing the competitive set toward membrane-technology specialists while reshaping procurement patterns across municipal and industrial buyers.
Membrane cell technology with zero-gap electrode configurations is displacing conventional diaphragm and mercury-cell designs across new capacity installations. Water treatment utilities in the US and Germany are specifying membrane-grade purity for municipal pH regulation contracts. The technology shift is enabling producers to capture premium pricing while meeting tightening EPA and REACH substance restrictions.
China's GB standards on chlor-alkali energy consumption, enforced by MEE under dual carbon targets, are mandating efficiency retrofits or shutdowns for legacy capacity. Domestic producers face compressed timelines to transition membrane technology or exit. The policy is concentrating supply among state-owned enterprises with capital access for greenfield membrane builds.
Long-term offtake agreements are replacing spot market purchases among large water treatment utilities seeking supply security. Distributor networks in Europe are losing volume to direct producer relationships as buyers consolidate procurement functions. The pattern is most visible in Germany and the Netherlands where municipal water boards have centralized chemical purchasing.
Caustic Soda Market Segmentation
Caustic soda procurement patterns diverge sharply across physical forms, end-use chemistry, and channel economics. Buyers in water treatment and specialty chemicals prioritize purity grades and logistics reliability over unit cost, fragmenting margin capture across the value chain.
Product Type:
Margin pools concentrate in solid and specialty-grade formats where handling complexity and purity premiums sustain pricing power above commodity liquid benchmarks.
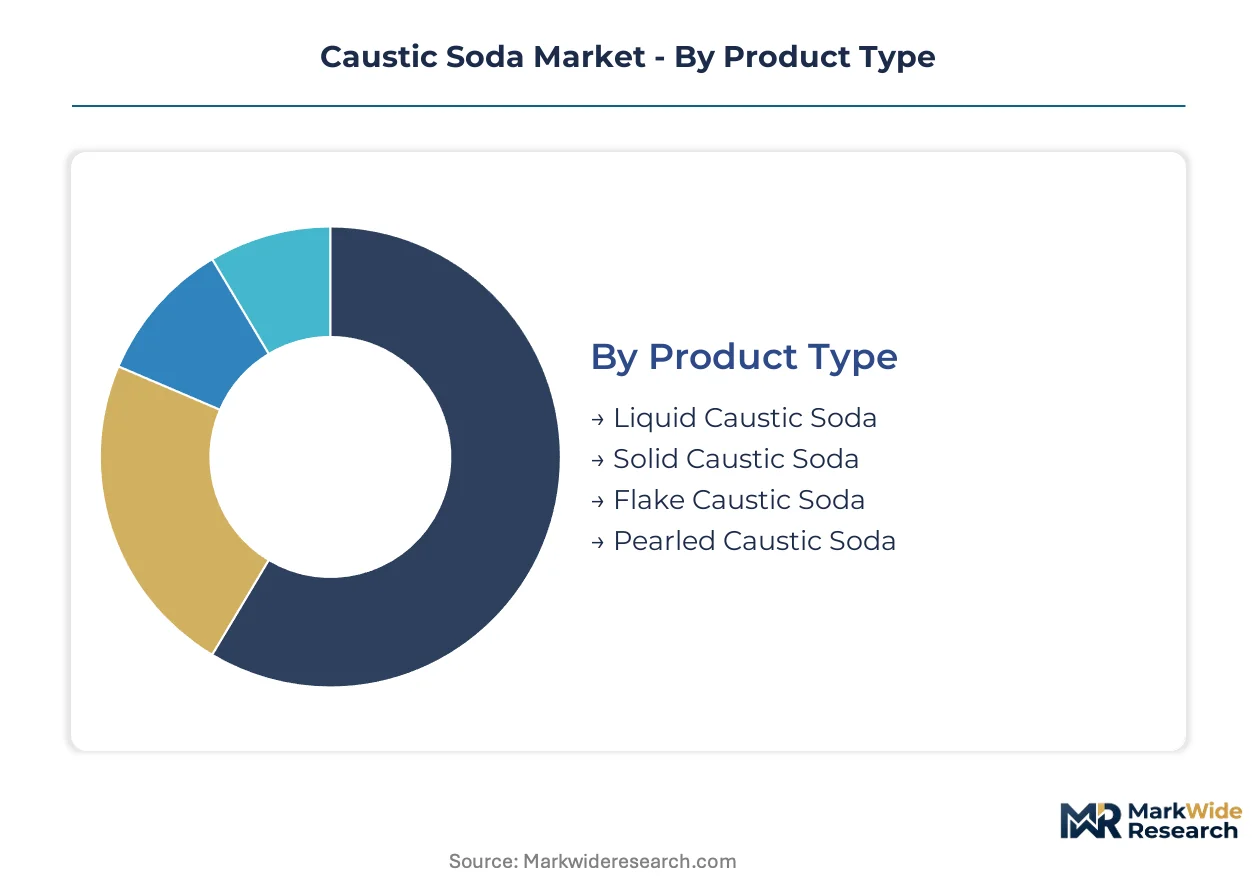
- Liquid Caustic Soda:Aqueous solution at 50% concentration dominates bulk industrial offtake due to pumpable logistics and lower unit handling costs. Demand concentrates in US Gulf Coast chemical corridors and Gujarat manufacturing clusters where pipeline and tanker infrastructure minimizes transfer losses.
- Flake Caustic Soda:Rapid-dissolving crystalline form delivers precise dosing control for soap and detergent manufacturers. European specialty chemical producers in Germany and the Netherlands pay premiums for low-carbonate flake specifications that reduce process contamination.
- Solid Caustic Soda:Cast block form serves remote mining and metallurgical sites lacking liquid storage infrastructure. Australian bauxite refineries and Chilean copper operations anchor procurement volumes.
- Pearled Caustic Soda:Spherical beads minimize dust generation during pneumatic conveying. Japanese electronics-grade chemical plants specify pearled formats for cleanroom handling protocols.
Liquid caustic soda holds installed capacity. Flake caustic soda is rotating up the share rankings.
Application:
Application-level profitability tracks regulatory stringency, with discharge-limited sectors commanding membrane-grade premiums over commodity specifications.
- Water Treatment:Municipal utilities deploy caustic soda for pH neutralization in secondary and tertiary wastewater processes. US utilities under EPA effluent guidelines are consolidating procurement through direct producer relationships, bypassing distributor markups.
- Pulp & Paper:Kraft pulping operations consume caustic soda for lignin removal and chemical recovery cycles. Scandinavian mills in Finland and Sweden lead technology upgrades toward closed-loop systems that reduce per-ton consumption intensity.
- Cleaners:Industrial and institutional cleaning formulations rely on caustic soda for grease saponification and surface preparation. Brazilian and Mexican manufacturing plants serving Latin American markets drive regional volume.
- Textile:Mercerization and dyeing processes use caustic soda to improve cotton fiber luster and dye uptake. Bangladeshi and Vietnamese textile exporters are expanding consumption as apparel manufacturing shifts from China.
Pulp & paper holds installed capacity. Water treatment is climbing the fastest.
End User:
End-user margins split between process-critical applications with captive chlor-alkali integration and merchant-market buyers exposed to spot price volatility.
- Chemical Manufacturing:Alumina refineries and petrochemical producers represent the largest integrated demand pool. Indian alumina capacity expansions in Odisha and Andhra Pradesh are pulling membrane-grade imports from Middle Eastern producers.
- Soap & Detergent:Formulators require consistent caustic soda quality for fatty acid neutralization. Indonesian and Malaysian palm-oil-based oleochemical clusters source flake and pearled grades for automated batching systems.
- Pharmaceuticals:USP-grade caustic soda serves pH adjustment in active pharmaceutical ingredient synthesis. FDA-inspected facilities in North Carolina and New Jersey enforce supplier qualification protocols that limit qualified sources.
- Food Processing:Food-grade caustic soda enables peeling and processing of fruits, vegetables, and cocoa. California tomato processors and Dutch cocoa butter refineries maintain dedicated food-grade supply chains with full lot traceability.
Chemical manufacturing holds installed capacity. Soap & detergent is rotating up the share rankings.
Distribution Channel:
Channel economics reflect buyer scale and specification complexity, with large utilities compressing distributor roles while mid-sized industrial users sustain intermediary value.
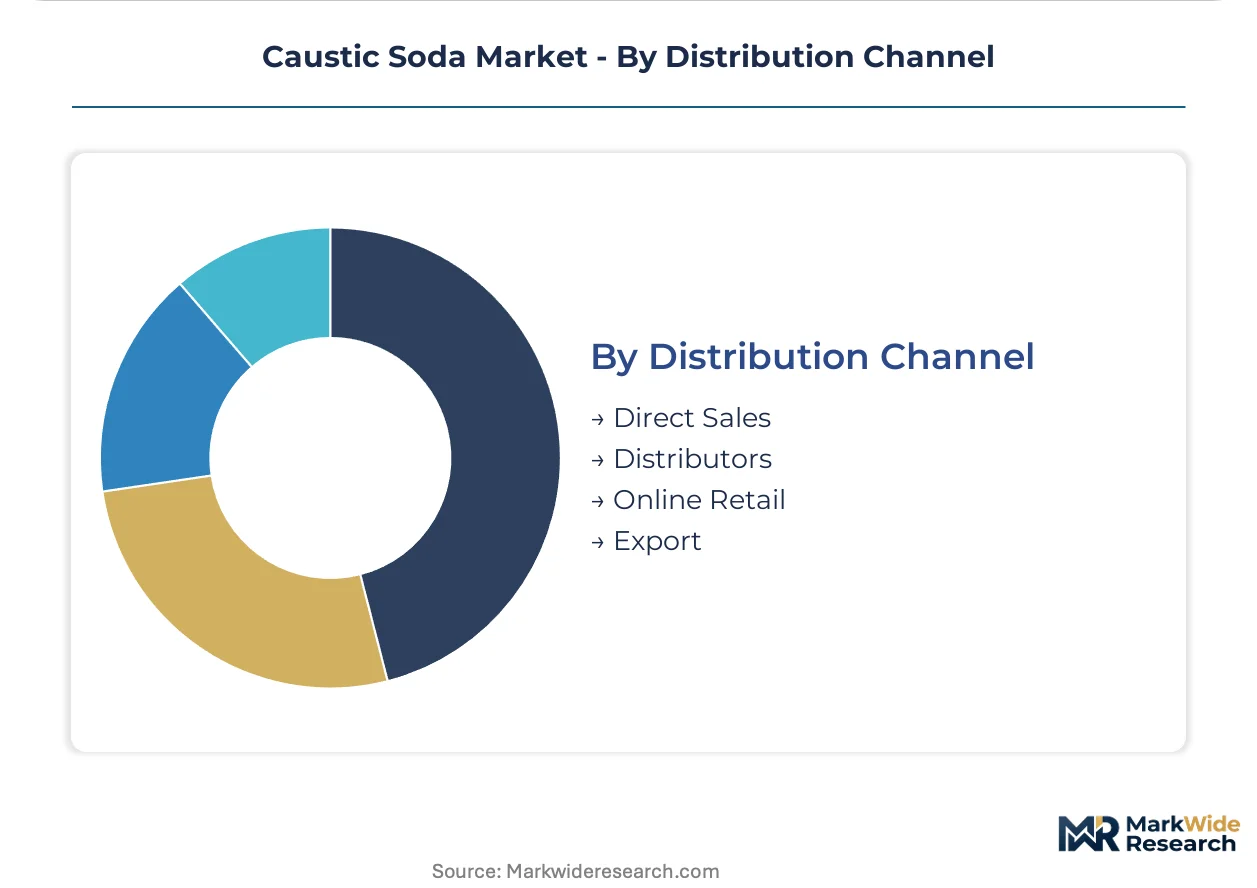
- Direct Sales:Long-term offtake agreements link membrane-grade producers to municipal water boards and integrated chemical manufacturers. German municipal water associations in North Rhine-Westphalia have centralized procurement through direct producer contracts.
- Distributors:Regional chemical distributors serve fragmented industrial accounts with mixed-product logistics and technical service. French and Italian specialty distributors maintain stocked warehouse networks for just-in-time delivery to mid-sized manufacturers.
- Export:Bulk liquid and containerized solid shipments move through port terminals to deficit markets. Middle Eastern producers with access to low-cost natural gas feedstock dominate export flows to South Asia and East Africa.
- Online Retail:Digital procurement platforms are emerging for standardized flake and solid grades in small-batch quantities. Indian B2B marketplaces are qualifying BIS-certified suppliers for direct shipment to Gujarat and Maharashtra chemical SMEs.
Direct sales holds installed capacity. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Middle Eastern producers ship bulk liquid caustic soda to deficit markets in South Asia and East Africa, while integrated chlor-alkali corridors on the US Gulf Coast supply chemical manufacturers across the Americas.
United States
Water treatment utilities under EPA effluent guidelines are consolidating procurement of membrane-grade caustic soda for pH neutralization. OSHA process safety management standards govern handling protocols across production and distribution networks. The US Gulf Coast chemical corridor anchors North American supply through integrated chlor-alkali assets with pipeline connectivity to Texas and Louisiana manufacturing clusters.
Germany
Municipal water boards in North Rhine-Westphalia have centralized chemical purchasing through direct producer contracts, bypassing traditional distributor networks. REACH registration requirements restrict import pathways for non-compliant Asian producers, compressing qualified supplier lists. The Rhine-Ruhr industrial region concentrates demand from specialty chemical producers seeking low-carbonate flake specifications for automated batching systems.
China
Domestic producers face compressed timelines to transition membrane technology or exit under MEE energy intensity standards tied to dual carbon goals. GB standards on chlor-alkali energy consumption are mandating efficiency retrofits for legacy capacity. State-owned enterprises with capital access for greenfield membrane builds are concentrating supply in the Yangtze River Delta chemical clusters.
India
Alumina capacity expansions in Odisha and Andhra Pradesh are pulling membrane-grade imports from Middle Eastern producers. BIS certification mandates are displacing unstandardized imports across chemical manufacturing clusters in Gujarat and Maharashtra. Domestic chlor-alkali capacity remains underpenetrated relative to downstream demand growth in textiles and alumina refining.
Saudi Arabia
Low-cost natural gas feedstock positions Saudi producers to dominate export flows to South Asian and East African deficit markets. The country's national industrial development programs support chlor-alkali capacity expansion for regional supply security. Jubail Industrial City anchors production with integrated petrochemical corridors serving alumina and water treatment demand across the Middle East.
Caustic Soda Market Vendor Landscape
Listed leaders compete with private specialists across integrated chlor-alkali economics, with publicly traded chemical conglomerates holding scale advantages in membrane technology deployment. The vendor base splits between Gulf Coast integrated producers with captive chlorine offtake and European specialty chemical groups with backward integration into electrochemical feedstocks. Three archetypes dominate: membrane-technology specialists, diversified petrochemical conglomerates with chlor-alkali divisions, and regional merchant-market suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term offtake agreements with municipal water utilities.
Within the integrated multinational tier, The Dow Chemical Company and Olin Corporation exemplify membrane-cell technology leadership, while BASF SE occupies a position representing captive supply integration into European specialty chemical value chains. These three entities anchor competitive positioning across their respective home markets, with Dow representing US Gulf Coast production economics, Olin exemplifying Ohio River Valley network advantages, and BASF sitting within German industrial chemical supply chains.
| Leading Market Players |
|---|
| The Dow Chemical Company |
| Occidental Petroleum Corporation |
| Olin Corporation |
| Westlake Corporation |
| Formosa Plastics Corporation |
| BASF SE |
| INEOS |
| PPG Industries |
| Saudi Basic Industries Corporation |
| Others |
Supply Flow & Price Mechanics
Membrane-grade caustic soda displacing mercury-cell legacy output is redrawing supply geography toward US Gulf Coast and Yangtze River Delta production clusters while compressing price premiums for higher-purity grades as membrane technology scales.
Pricing Analysis
Membrane-to-diaphragm-to-mercury cell pricing gaps stratify procurement economics across the chlor-alkali sector. Three-tier pricing structure across membrane-grade premium, diaphragm-standard, and mercury-cell residual tiers tracks energy intensity and regulatory compliance costs. Price differentiation rests on EPA and MEE certification thresholds plus volume scale in long-term offtake agreements. Pricing pressure stems from electricity cost volatility in European grid markets, compressing operating margins for non-integrated producers. Municipal water utilities exhibit lowest price sensitivity due to regulatory-mandated purity specifications, while mid-sized industrial cleaners face acute cost pressure from soda ash substitution in marginal applications.
Supply Chain Analysis
Strait of Hormuz transit underwrites Middle Eastern export flows to South Asian deficit markets, creating logistics chokepoint exposure for Indian alumina refiners. Supply concentrates in the United States, China, and Saudi Arabia, with integrated Gulf Coast producers anchoring Americas coverage. Raw material dependencies center on salt brine feedstock, electricity pricing, and chlorine offtake agreements for co-product absorption. Single-source vulnerability runs through hurricane-exposed Texas and Louisiana production corridors. Distribution runs through direct producer relationships with large utilities, regional chemical distributors for fragmented industrial accounts, and emerging B2B platforms for standardized solid grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Caustic soda procurement is shifting toward platform-mediated direct contracting between membrane-grade producers and municipal utilities, with interoperability standards for BIS and REACH certification data exchange enabling this ecosystem inflection.
For Market Incumbents: Fortify membrane-technology leadership through zero-gap cell retrofits in Ohio River Valley and US Gulf Coast assets to defend against Middle Eastern export competition. Deepen backward integration into captive chlorine offtake with downstream PVC and isocyanate producers to absorb co-product volume and stabilize margin volatility from merchant chlorine price swings. For New Entrants and Emerging Players: Differentiate on BIS-certified membrane-grade supply to Gujarat and Maharashtra chemical SMEs currently dependent on unstandardized imports. Target India's underpenetrated domestic chlor-alkali capacity relative to alumina and textile downstream demand. Pursue digital-first go-to-market through B2B procurement platforms qualifying direct producer relationships with mid-sized water treatment operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European specialty distributors losing volume to direct producer contracting in Germany and the Netherlands. Long-term viability favors membrane-technology specialists with regulatory-compliant capacity and locked utility offtake over legacy mercury-cell exposure facing accelerated depreciation. Watch MEE enforcement timelines for Chinese capacity exit decisions as inflection signal for regional supply tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Retrofit | Zero-gap electrode upgrades reduce energy intensity per ton while satisfying MEE dual carbon compliance deadlines. |
| Long-term Supply Agreement | Municipal water boards in North Rhine-Westphalia bypass distributor markups through direct producer contracting. |
| Backward Integration | Captive chlorine offtake into PVC production stabilizes co-product absorption and merchant market exposure. |
| BIS Certification Investment | Standardized product specifications displace unstandardized imports across Gujarat and Maharashtra manufacturing clusters. |
| Digital Procurement Platform | B2B marketplaces compress distributor margins by linking membrane-grade producers directly to mid-sized industrial buyers. |
Methodological Framework
Initial hypotheses were tested against primary input from chlor-alkali plant managers, municipal water utility procurement leads, specialty chemical R&D directors, and regional distribution channel partners and refined through secondary validation. Primary fieldwork combined structured interviews with downstream end-users and upstream producers across US Gulf Coast, German Rhine-Ruhr, and Indian Gujarat manufacturing corridors. Secondary sources included customs and trade flow databases, SEC 10-K filings from listed chemical conglomerates, ACC and Cefic industry statistics, and BIS certification registries. Bottom-up capacity and demand modeling was triangulated against top-down macroeconomic indicators to ensure cross-verification.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within grade-tier, end-use industry, and regional production hub segmentation. The analytical framework models membrane-grade, diaphragm-standard, and mercury-cell residual tiers alongside water treatment, pulp and paper, and alumina refining application splits. CAGRs were derived through regression-based trending of historical capacity utilization against regulatory compliance timelines and electricity cost trajectories. Forecast inputs incorporated MEE energy intensity enforcement schedules, EPA effluent guideline adoption curves, and Indian BIS certification rollout pace.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of mercury-cell phase-outs or abrupt electricity price regime shifts would require recalibration. Forecasts reflect documented assumptions on technology substitution rates and regional demand migration patterns. Practitioners should keep alternative scenarios live as MEE dual carbon compliance deadlines and Indian domestic capacity expansion timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Hydroxyzine Imine Market
Chemicals
Muriatic Acid Market
Chemicals
HATU Market
Chemicals
Formalin Market
Chemicals
Whitening Ingredients Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Di Nitro Toluene Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Triethylaluminum Market
Chemicals
Fluoroboric Acid Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Desalination Chemicals Market
Chemicals
Power Plant Chemicals Market
Chemicals
Global Waterproofing Chemicals Market