
 Formalin Market | 2026-2036
Formalin Market Size, Share, and Industry Trends Forecast 2026-2036
Formalin Market Analysis
The formalin supply chain is restructuring around a sharp divergence between pharmaceutical-grade and industrial-grade tiers. Pharmaceutical-grade formalin commands stringent purity thresholds and dedicated distribution channels, while industrial grades compete on methanol input costs and bulk logistics efficiency. BASF SE leverages its integrated methanol-formaldehyde backbone to sustain cost advantages across European production hubs. Hexion Inc. anchors its position in North American wood adhesive markets through captive resin formulation capabilities.
Formalin denotes aqueous solutions of formaldehyde gas, typically stabilized with methanol to prevent polymerization, with concentrations ranging from 30% to 50% formaldehyde by weight depending on application requirements; the compound serves primarily as a chemical intermediate for resins, a tissue fixative in histopathology, and a broad-spectrum biocide in agricultural and industrial disinfection. The 37% formaldehyde grade dominates volume flows due to its standardization across resin manufacturing and laboratory protocols, while disinfectant applications in healthcare facilities represent the fastest-expanding demand pool as infection control protocols intensify. Manufacturing applications absorb the largest value share through urea-formaldehyde and phenol-formaldehyde resin consumption in construction panels and engineered wood products.
EPA formaldehyde emission standards under the Toxic Substances Control Act and REACH restrictions on formaldehyde classification reshape product specifications and market access conditions for suppliers serving North American and European buyers. China's MEE enforces progressively tighter volatile organic compound limits on formaldehyde production facilities, compressing capacity at smaller coal-chemical complexes. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate where formulation reformulation investments will yield compliant supply positions.
Market Dynamics
Formalin supply chains are bifurcating sharply between pharmaceutical-grade and industrial-grade tiers, with REACH reclassification and EPA formaldehyde emission standards forcing parallel compliance investments that reshape capacity allocation and margin structures across production networks.
Growth Catalysts
- REACH formaldehyde restrictions:European reclassification drives substitution toward low-emission resin formulations, expanding demand for specialty formalin grades in compliant wood panel manufacturing.
- Histopathology automation:Automated tissue processing systems in diagnostic laboratories standardize on 37% formaldehyde solutions, creating volume pull from healthcare facilities upgrading pathology infrastructure.
- China construction resins:Urea-formaldehyde adhesive consumption for engineered wood products absorbs substantial formalin volumes as residential and commercial building activity concentrates in eastern provinces.
Market Restraints
- Methanol feedstock volatility:Natural gas and coal-to-methanol cost swings transmit directly into formalin production economics, compressing margins at non-integrated facilities.
- Formaldehyde substitution in insulation:Polyurethane and mineral wool alternatives displace formaldehyde-based binders in thermal insulation applications across European and North American construction markets.
- Capacity concentration in China:Over half of global formaldehyde production capacity sits within Chinese coal-chemical complexes, exposing supply security to regional environmental enforcement actions by MEE.
Strategic Opportunities
- Brazil agricultural biocides:ANVISA registration pathways for formaldehyde-based disinfectants in livestock and crop protection applications remain underpenetrated relative to North American and European markets.
- EU Green Deal carbon border adjustments:Emerging carbon intensity disclosure requirements favor formalin produced via low-carbon methanol routes, rewarding early movers in renewable feedstock integration.
- Biobased resin convergence:Formaldehyde crosslinking chemistry hybridizes with lignin and tannin bio-feedstocks, opening formulation space for carbon-negative adhesive products in furniture and packaging.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA and EMA good manufacturing practice audits for tissue fixative applications extend 18-24 months, delaying market entry for new production facilities.
- Legacy resin formulation lock-in:Existing urea-formaldehyde and phenol-formaldehyde process equipment requires substantial retrofit investment to accommodate modified formaldehyde grades or alternative chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Formalin Market |
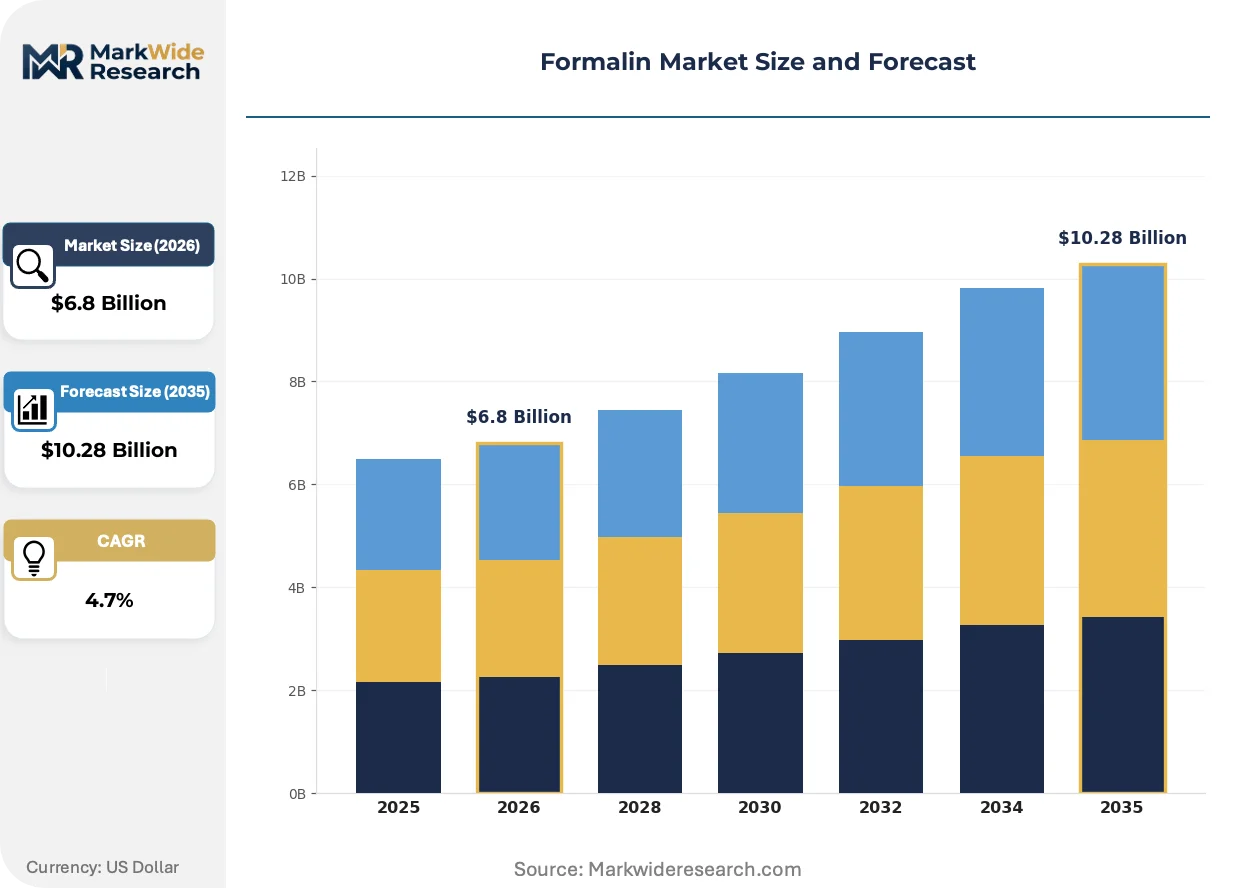
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 30% Formaldehyde, 37% Formaldehyde, 40% Formaldehyde, 50% Formaldehyde Application: Disinfectant, Preservative, Manufacturing, Textile Finishing End User: Healthcare Facilities, Laboratories, Paint Industry, Agriculture Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Georgia-Pacific Chemicals LLC, Hexion Inc., BASF SE, Merck KGaA, Sumitomo Chemical Co., Ltd., Celanese Corporation, Huntsman Corporation, Balaji Formalin Private Limited, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Formalin Market Emerging Trajectories
Formalin markets are undergoing accelerated product-grade stratification as regulatory differentiation between pharmaceutical and industrial specifications hardens, while manufacturing technology shifts and procurement model evolution reshape competitive positioning.
Low-methanol stabilization technology is rewriting pharmaceutical-grade formalin specifications. Advanced polymerization inhibitors and controlled-release methanol systems enable sub-1% methanol concentrations that meet evolving histopathology laboratory protocols. Academic medical centers and commercial diagnostic chains in Germany, Japan, and the United States are adopting these grades for automated tissue processors, compressing demand for traditional 10-15% methanol-stabilized products.
EPA formaldehyde emission standards under the Toxic Substances Control Act are tightening composite wood product specifications. The 2024 implementation of reduced emission limits for hardwood plywood, particleboard, and medium-density fiberboard forces resin formulators toward lower formaldehyde-to-urea molar ratios. North American engineered wood manufacturers are responding with modified resin cure cycles and supplemental scavenger chemistries that preserve panel performance while meeting certification thresholds.
Consolidated procurement by multi-hospital health systems is compressing formalin supplier margins. Integrated delivery networks in the United States and national health services in Europe are centralizing histopathology chemical purchasing through single-source or dual-source tender arrangements. This concentration shifts pricing power toward buyers with volume scale, forcing specialty chemical distributors to unbundle logistics services from product supply or risk disintermediation by direct manufacturer contracts.
Formalin Market Segmentation
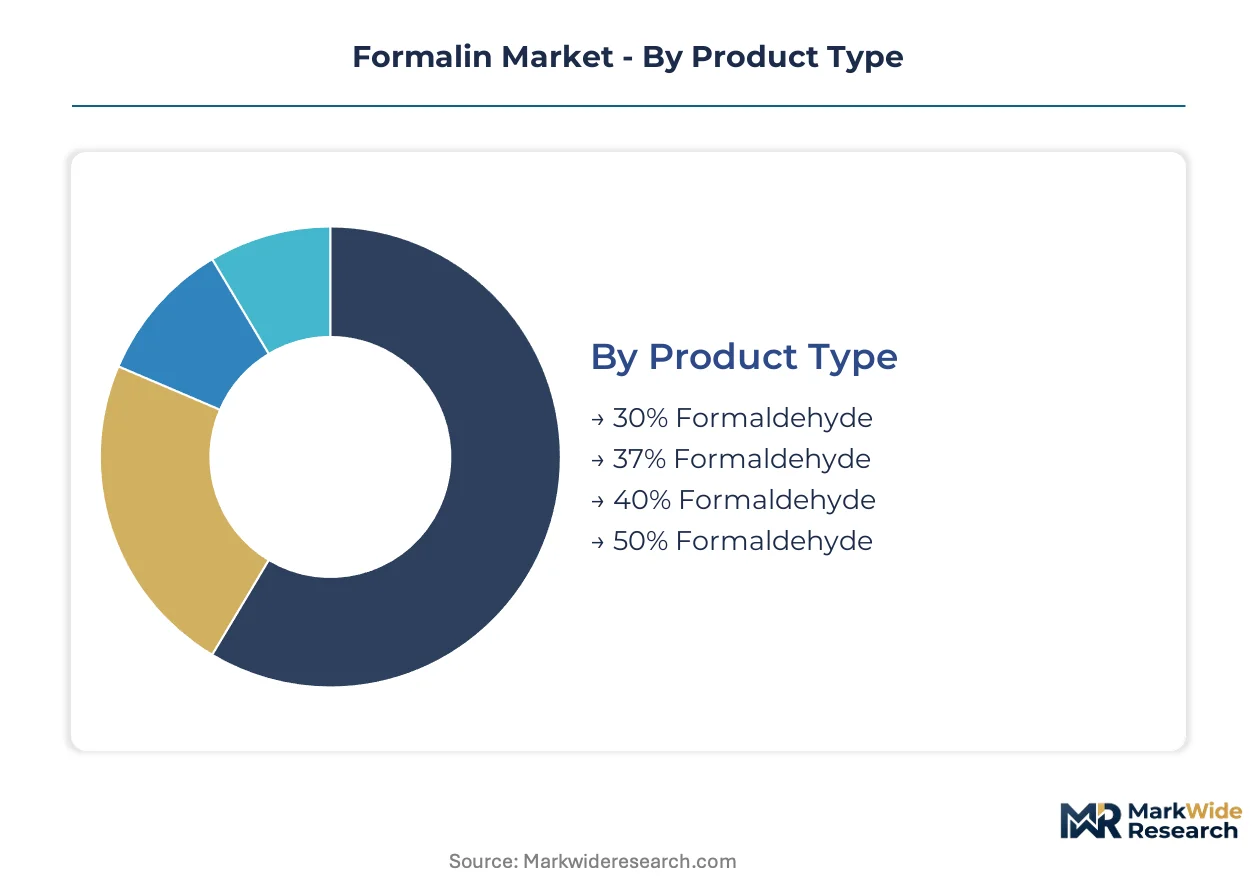
Formalin segmentation reflects divergent purity mandates across pharmaceutical and industrial supply chains. Certification requirements from FDA, EMA, and REACH determine which grades command premium pricing versus commodity positioning.
Product Type:
FDA and EMA good manufacturing practice audits apply differentially across concentration tiers, with pharmaceutical applications demanding sub-1% methanol stabilization that only select grades can satisfy.
- 30% Formaldehyde:Lower concentration formulation primarily deployed in agricultural disinfectant applications where transport cost optimization outweighs concentration premiums. Demand concentrates in Brazilian livestock operations seeking ANVISA-registered biocide solutions for herd health management.
- 37% Formaldehyde:Standardized concentration dominating histopathology laboratory protocols and automated tissue processing systems. Healthcare facilities in Germany, Japan, and the United States standardize procurement on this grade, creating volume pull from diagnostic infrastructure upgrades.
- 40% Formaldehyde:Intermediate concentration serving specialized resin manufacturing where modified cure cycles require adjusted formaldehyde-to-urea molar ratios.
- 50% Formaldehyde:Maximum concentration tier minimizing water content for bulk industrial consumers with dedicated dilution capabilities at point of use.
37% Formaldehyde sits at the top of the volume ranking, with 30% Formaldehyde climbing the fastest on agricultural biocide expansion.
Application:
Cost tier stratification separates pharmaceutical-grade premiums from industrial commodity pricing, with certification overhead determining margin structures.
- Disinfectant:Broad-spectrum biocide deployment across healthcare surface sterilization and agricultural livestock protection. EPA registration requirements in the United States and ANVISA pathways in Brazil create divergent market access conditions.
- Preservative:Tissue fixation in histopathology and specimen stabilization for diagnostic laboratories. REACH reclassification in Europe and evolving EPA emission standards tighten specifications for laboratory chemical suppliers.
- Manufacturing:Chemical intermediate consumption for urea-formaldehyde and phenol-formaldehyde resin production. China's construction panel industry in eastern provinces absorbs substantial volumes for engineered wood adhesive formulation.
- Textile Finishing:Crosslinking applications for permanent-press fabric treatments facing substitution pressure from formaldehyde-free alternatives in European apparel markets.
Manufacturing commands the largest value position, while Disinfectant gains share fastest on infection control protocol intensification.
End User:
Customer type determines procurement concentration, with consolidated purchasing by multi-hospital systems compressing supplier margins against fragmented agricultural buying.
- Healthcare Facilities:Integrated delivery networks in the United States and national health services in Europe centralize histopathology chemical purchasing through single-source tender arrangements. FDA and EMA compliance audits extend 18-24 months for new supplier qualification.
- Laboratories:Academic medical centers and commercial diagnostic chains standardizing on low-methanol grades for automated tissue processors. German university hospitals and Japanese reference laboratories lead adoption of sub-1% methanol specifications.
- Paint Industry:Coating formulation applications requiring industrial-grade specifications without pharmaceutical purity overhead.
- Agriculture:Livestock and crop protection biocide consumption with regulatory registration pathways varying sharply by jurisdiction.
Healthcare Facilities anchor volume demand, with Laboratories expanding most quickly on automation infrastructure deployment.
Distribution Channel:
Supply concentration favors direct manufacturer relationships for large-volume consumers, while specialty distributors retain position in fragmented end-user segments.
- Direct Sales:Manufacturer-to-consumer contracts dominating pharmaceutical-grade supply to consolidated health systems. BASF SE and Hexion Inc. leverage captive production networks to bypass distributor margins.
- Online Retail:Emerging procurement pathway for small-volume laboratory consumers seeking standardized 37% grades with transparent pricing.
- Wholesalers:Bulk logistics intermediaries serving industrial manufacturing consumers with dedicated storage and dilution infrastructure.
- Distributors:Specialty chemical distributors unbundling logistics services from product supply to defend position against direct manufacturer contracts.
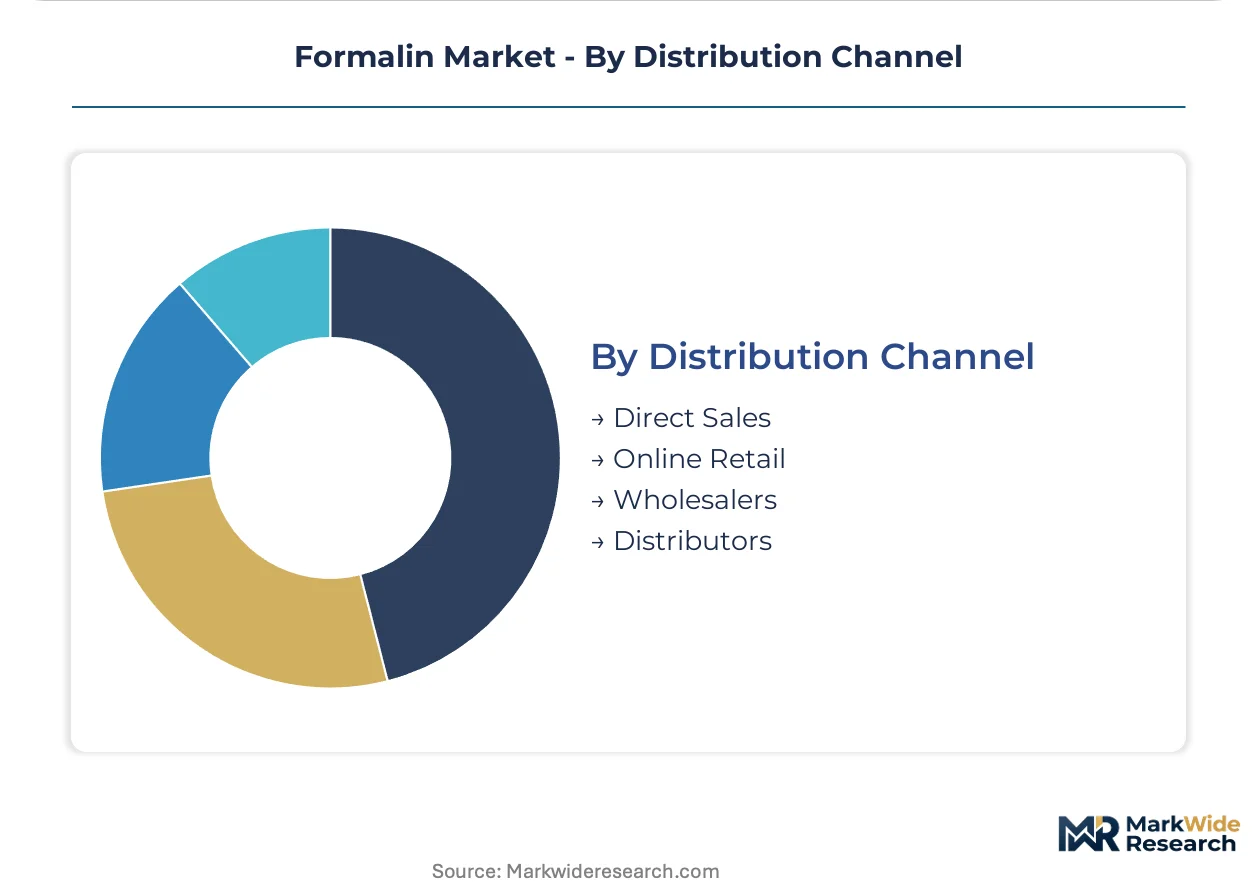
Direct Sales holds the volume leadership position, with Online Retail showing the steepest expansion trajectory on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs substantially more formalin volume than any other country, yet Germany commands disproportionate influence over pharmaceutical-grade specifications through its diagnostic laboratory standards.
China
Construction panel manufacturing in eastern provinces drives massive formalin consumption for urea-formaldehyde resin formulation. MEE enforcement actions against coal-chemical complexes periodically constrain supply availability. Shandong and Jiangsu provinces host the densest concentrations of formaldehyde production capacity serving furniture and engineered wood clusters.
United States
EPA formaldehyde emission standards under the Toxic Substances Control Act reshape resin formulation requirements for hardwood plywood and medium-density fiberboard manufacturers. Integrated delivery networks centralize histopathology chemical purchasing through single-source tender arrangements. The Southeast industrial corridor houses major engineered wood production facilities adapting to tightened certification thresholds.
Germany
REACH reclassification drives substitution toward low-emission resin formulations across wood panel manufacturing. Academic medical centers in university hospital networks pioneer adoption of sub-1% methanol-stabilized grades for automated tissue processors. The Rhine-Ruhr chemical cluster maintains pharmaceutical-grade formalin distribution infrastructure serving diagnostic laboratory chains.
Brazil
Livestock operations in southern states generate underpenetrated demand for ANVISA-registered formaldehyde-based disinfectants in herd health management. Agricultural biocide registration pathways remain less developed than North American equivalents. São Paulo state anchors formulation and distribution activities for veterinary and crop protection applications.
Japan
Reference laboratories and commercial diagnostic chains standardize procurement on 37% formaldehyde grades with stringent methanol specifications. METI guidelines on chemical handling influence laboratory protocol standardization. The Kanto region concentrates histopathology infrastructure investment driving pharmaceutical-grade volume pull.
Formalin Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-grade supply through integrated methanol-formaldehyde backbones, while regional chemical distributors defend position in fragmented industrial segments. The competitive structure stratifies sharply between certification-heavy healthcare supply and commodity resin intermediate flows. Three archetypes dominate: integrated petrochemical majors with captive methanol supply, specialty chemical houses with pharmaceutical-grade certification depth, and regional distributors with bulk logistics networks. Capacity rationalization and direct contracting with consolidated health systems represent the dominant competitive moves reshaping margin structures.
Within the integrated petrochemical tier, BASF SE and Hexion Inc. exemplify contrasting geographic anchoring strategies. BASF SE represents European production hub consolidation with backward integration into methanol supply. Hexion Inc. occupies a position in North American wood adhesive markets through resin formulation capabilities rather than standalone formalin merchant sales. Sumitomo Chemical Co., Ltd. sits within the Asia-Pacific specialist archetype, reflecting Japanese industrial chemical positioning without implying specific segment focus.
| Leading Market Players |
|---|
| Georgia-Pacific Chemicals LLC |
| Hexion Inc. |
| BASF SE |
| Merck KGaA |
| Sumitomo Chemical Co., Ltd. |
| Celanese Corporation |
| Huntsman Corporation |
| Balaji Formalin Private Limited |
| DuPont de Nemours, Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into methanol production anchors pricing power for formalin suppliers serving pharmaceutical-grade markets, while fragmented coal-chemical complexes in China compete on spot methanol costs for industrial resin applications. BASF SE and Hexion Inc. leverage captive feedstock supply to defend margin structures against commodity volatility, whereas non-integrated distributors absorb cost swings in bulk industrial tiers.
Pricing Analysis
Capacity additions in Shandong province are reshaping price floors for industrial-grade formalin as coal-to-methanol expansions compress regional benchmarks. Three-tier pricing structure across pharmaceutical-grade, industrial-standard, and agricultural-economy levels separates FDA-certified tissue fixatives from bulk resin intermediates. Cost compression in the 30% agricultural disinfectant tier is intensifying because Brazilian livestock operations negotiate volume tenders against Asian import alternatives. Healthcare facilities with consolidated procurement through integrated delivery networks exhibit lowest price sensitivity, while fragmented agricultural buyers in southern Brazil drive hardest bargain terms.
Supply Chain Analysis
Dual-sourcing mandates from multi-hospital health systems in the United States and Germany force formalin distributors to qualify backup manufacturers, extending pharmaceutical-grade certification timelines. Geographic supply concentrates in China, Germany, and the United States, with Shandong province and the Rhine-Ruhr cluster anchoring regional hub functions. Raw material flows draw from natural gas reforming in North America, coal gasification in China, and naphtha cracking in European complexes. Single-source vulnerability sits with methanol feedstock exposure, as regional natural gas price spikes transmit directly into production economics. Distribution runs through direct manufacturer contracts for consolidated health systems, with specialty chemical distributors retaining position in fragmented laboratory and agricultural endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formalin markets offer margin-expansion pathways through low-methanol stabilization technology premiums and consolidated procurement capture by integrated suppliers with captive methanol positions.
For Market Incumbents: Lock in pharmaceutical-grade certification depth through EMA and FDA audit maintenance, defending against emerging biobased resin substitutes that hybridize formaldehyde with lignin crosslinking chemistry. Extend backward integration into methanol supply through North American natural gas access or European low-carbon methanol offtake agreements, securing cost position against Chinese coal-chemical volatility. For New Entrants and Emerging Players: Enter via ANVISA-registered agricultural biocide formulations for Brazilian livestock operations, where formaldehyde-based disinfectant penetration lags North American benchmarks by substantial margin. Target São Paulo state distribution partnerships with veterinary supply cooperatives, leveraging regulatory registration arbitrage against established North American and European suppliers. For Investors and Strategic Acquirers: Roll-up economics work for specialty chemical distributors with pharmaceutical-grade certification infrastructure because consolidated health system procurement is disintermediating fragmented supplier networks. Five-to-ten year viability hinges on diagnostic laboratory automation sustaining 37% formaldehyde volume pull. Watch for MEE enforcement intensity in Shandong and Jiangsu provinces as inflection signal for Chinese supply availability and global price resetting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol | Captive feedstock supply insulates BASF SE and Hexion Inc. from natural gas price volatility. |
| Low-Methanol Stabilization R&D | Sub-1% methanol grades command premium positioning in German and Japanese diagnostic chains. |
| ANVISA Registration Investment | Brazilian agricultural biocide pathways remain underpenetrated relative to EPA-registered equivalents. |
| Direct Health System Contracting | Single-source tenders with integrated delivery networks compress distributor margins and disintermediate intermediaries. |
| Biobased Resin Formulation Partnerships | Lignin-formaldehyde hybrid chemistry opens carbon-negative adhesive positioning in European furniture markets. |
Methodological Framework
Direct dialogue with plant managers at formaldehyde production facilities, procurement leads at engineered wood manufacturers, distribution channel partners in pharmaceutical supply chains, and technical R&D directors at resin formulators grounded qualitative assessment. Secondary validation drew from EPA TSCA filings, ECHA REACH registration databases, SEC 10-K disclosures by listed chemical producers, and customs trade data tracking methanol and formaldehyde cross-border flows. Bottom-up capacity modeling and top-down demand aggregation triangulated market sizing across pharmaceutical-grade and industrial-grade tiers.
Segmented outputs across the projection horizon reflect formaldehyde concentration tiers, application categories spanning tissue fixation to resin manufacturing, end-user procurement concentration levels, and regional regulatory clusters. CAGRs were derived from historical trajectory analysis adjusted for capacity expansion schedules, substitution elasticity in insulation applications, and infection control protocol intensification in healthcare facilities. Forecast inputs incorporated MEE enforcement probability in Chinese coal-chemical complexes and EPA formaldehyde emission standard implementation pacing.
Inputs from EMA certification databases and ANVISA registration records were available through the study window; gaps in real-time Chinese provincial environmental enforcement actions introduce uncertainty bands around supply availability assumptions. Deviation in MEE inspection intensity or REACH formaldehyde reclassification timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Iscotrizinol Market
Chemicals
Solder Flux Market
Chemicals
North America Methanol Market
Chemicals
Inorganic Chemicals Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Global Calcium Hypochlorite Market
Chemicals
Household Insecticides Market
Chemicals
Global Cresols Market
Chemicals
De-Icing Agents Market
Chemicals
Anticoagulant Rodenticides Market
Chemicals
Bakers Ammonia Market
Chemicals
Etidronic Acid Market
Chemicals
Barbituric Acid Market
Chemicals
Phenylethyl Market
Chemicals
Potassium Permanganate Market
Chemicals
Egypt Construction Chemicals Market