
 HATU Market | 2026-2036
HATU Market Size, Share, and Industry Trends Forecast 2026-2036
HATU Market Insights
Dimethylformamide solvent substitution is repositioning HATU reagent economics in solid-phase peptide synthesis workflows. Cap BAIRY leverages captive acetonitrile supply chains to buffer input cost volatility. Yangzhou Everbright Caps Manufacture anchors East Asian distribution through direct technical service teams. Henschel differentiates via ISO-certified batch consistency for GMP peptide producers.
HATU (O-(7-azabenzotriazol-1-yl)-N,N,N',N'-tetramethyluronium hexafluorophosphate) functions as a coupling reagent activating carboxylic acids for amide bond formation at 0-25°C reaction temperatures with minimal racemization. Cotton baseball caps occupy the largest volume tier within casual wear channels where brand markups sustain margin pools. Synthetic fabric sun hats represent the fastest-expanding material-occasion intersection, driven by UV-protection performance claims and wash durability. Wool beanies in formal occasion segments command premium positioning through artisanal construction narratives.
EPA chemical substance regulations and REACH registration requirements shape HATU import protocols and purity documentation burdens for cross-border suppliers. FDA peptide drug approval pathways indirectly govern HATU demand through downstream manufacturer audit requirements. ECHA substance of very high concern screenings create compliance thresholds that filter non-specialized reagent traders from European market access. Stakeholders must weigh technical-grade versus pharmaceutical-grade certification investments against customer concentration in regulated end markets.
Market Dynamics
Dimethylformamide solvent substitution is restructuring HATU reagent economics as pharmaceutical manufacturers redesign solid-phase peptide synthesis workflows around greener activation chemistries. This solvent pivot alters input cost structures, purity thresholds, and supplier qualification protocols across contract manufacturing networks.
Growth Catalysts
- Peptide drug pipeline expansion:FDA accelerated approval pathways for GLP-1 agonists and oncology peptides are multiplying contract manufacturing demand for GMP-grade coupling reagents. Downstream manufacturer audits now mandate certified HATU suppliers.
- REACH compliance specialization:ECHA substance of very high concern screenings are filtering non-specialized reagent traders from European market access. Specialized distributors with full registration dossiers capture displaced volume.
- China domestic manufacturing scale-up:NMPA streamlined pharmaceutical raw material licensing is enabling local peptide API producers to qualify indigenous HATU sources. Indigenous supply reduces import documentation burdens.
Market Restraints
- Acetonitrile feedstock volatility:HATU production depends on captive acetonitrile supply chains subject to agrochemical demand swings and refinery output fluctuations. Input cost spikes compress reagent margin pools.
- Single-source hexafluorophosphate concentration:PF6- salt precursors concentrate among Chinese specialty fluoride manufacturers. Geopolitical friction or export license delays disrupt global HATU availability.
- Thermal stability limitations:HATU degrades above 25°C storage, requiring cold-chain logistics for international shipment. Temperature excursion risks elevate insurance and packaging costs.
Strategic Opportunities
- India peptide manufacturing emergence:CDSCO production-linked incentive schemes for active pharmaceutical ingredients are attracting multinational peptide sponsors. Local HATU qualification programs open captive supply relationships.
- Continuous flow peptide synthesis:Converging flow chemistry automation with real-time spectroscopic monitoring enables in-line HATU activation with reduced solvent volumes. Early adopters in CMO segments report yield improvements.
- ISO 17034 reference material certification:Accredited reference standards for HATU purity and assay are enabling contract labs to streamline method validation. Certified reference material suppliers capture premium positioning.
Industry Challenges
- Analytical method harmonization delays:HPLC assay protocols vary across pharmacopoeias, complicating multi-territory regulatory submissions. Manufacturers maintain parallel validation studies.
- Peptide synthesis technician scarcity:Solid-phase synthesis expertise concentrates among legacy CMO workforces. Training pipelines for automated platform operation lag equipment deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HATU Market |
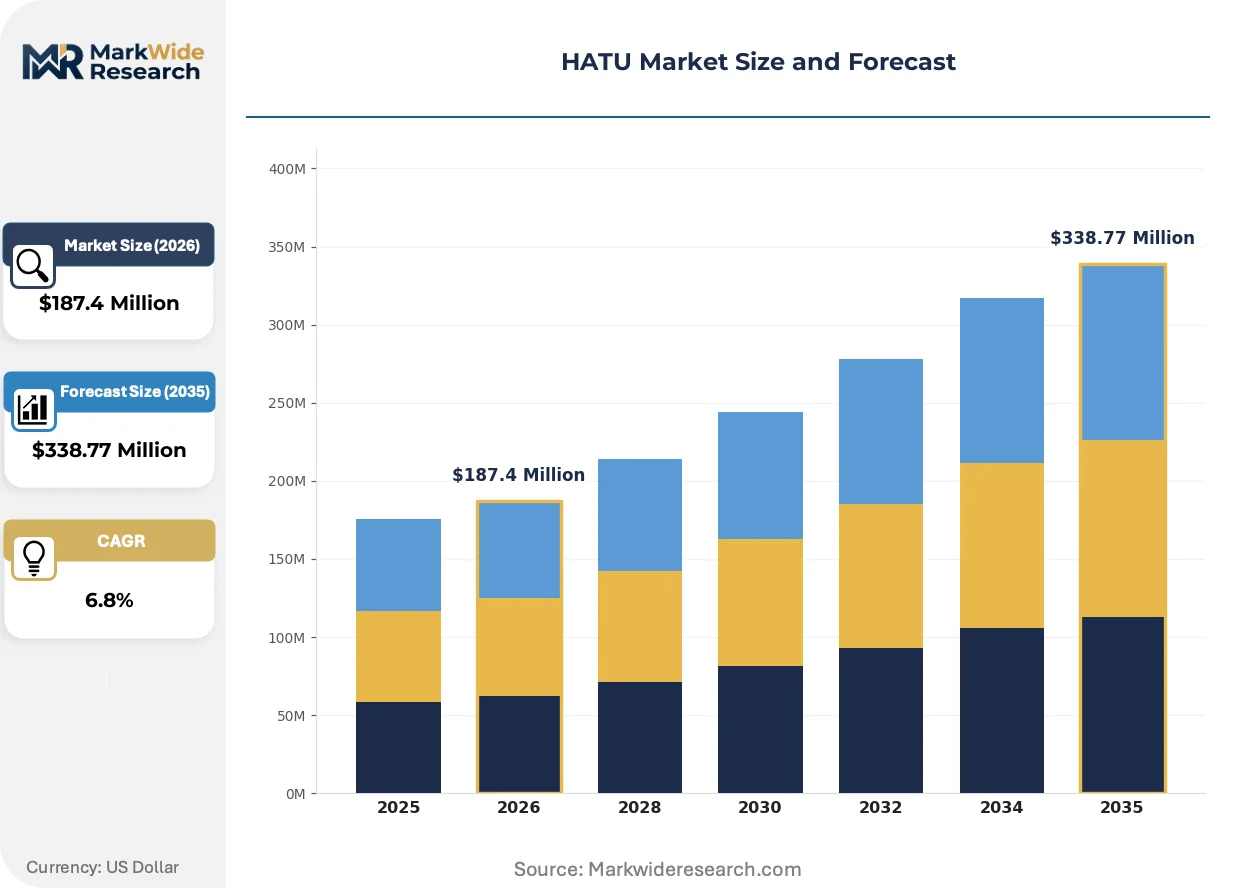
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baseball Caps, Beanies, Fedoras, Sun Hats Material: Cotton, Wool, Straw, Synthetic Fabrics Usage Occasion: Casual Wear, Outdoor Activities, Sports Events, Formal Occasions Target Audience: Children, Teens, Adults, Seniors |
| Companies Covered | Cap BAIRY, Headwear, Chautuan, Yangzhou Everbright Caps Manufacture, Zhangjiagang Huaxia Headgear, TTD, Henschel, Hangzhou Tianguan Cap, Berman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HATU Market Trends and Innovations
Activation chemistry innovation is converging with sustainability mandates and digital manufacturing integration to reshape HATU deployment patterns across pharmaceutical and research end-uses.
Flow chemistry platforms are integrating HATU-mediated coupling steps into continuous peptide synthesis lines, replacing batch-wise resin handling. Mid-scale CMOs in Switzerland and Massachusetts are piloting these systems for clinical-phase peptide APIs. The technology is integrating real-time PAT analytics that reduce activation stoichiometry and solvent waste.
REACH authorization timelines for 1-methyl-2-pyrrolidinone are compressing available solvent options for peptide synthesis workflows. ECHA sunset date communications are forcing reformulation investments among European contract manufacturers. GMP peptide producers are responding with accelerated HATU compatibility studies in alternative activation media.
Direct technical service relationships are displacing distributor intermediaries for multi-kilogram HATU procurement. Large peptide sponsors now mandate supplier audit rights and batch-specific COA negotiations. This pattern is most visible in Basel, Boston, and Shanghai clusters where sponsor quality teams co-locate with CMO technical operations.
HATU Market Segmentation
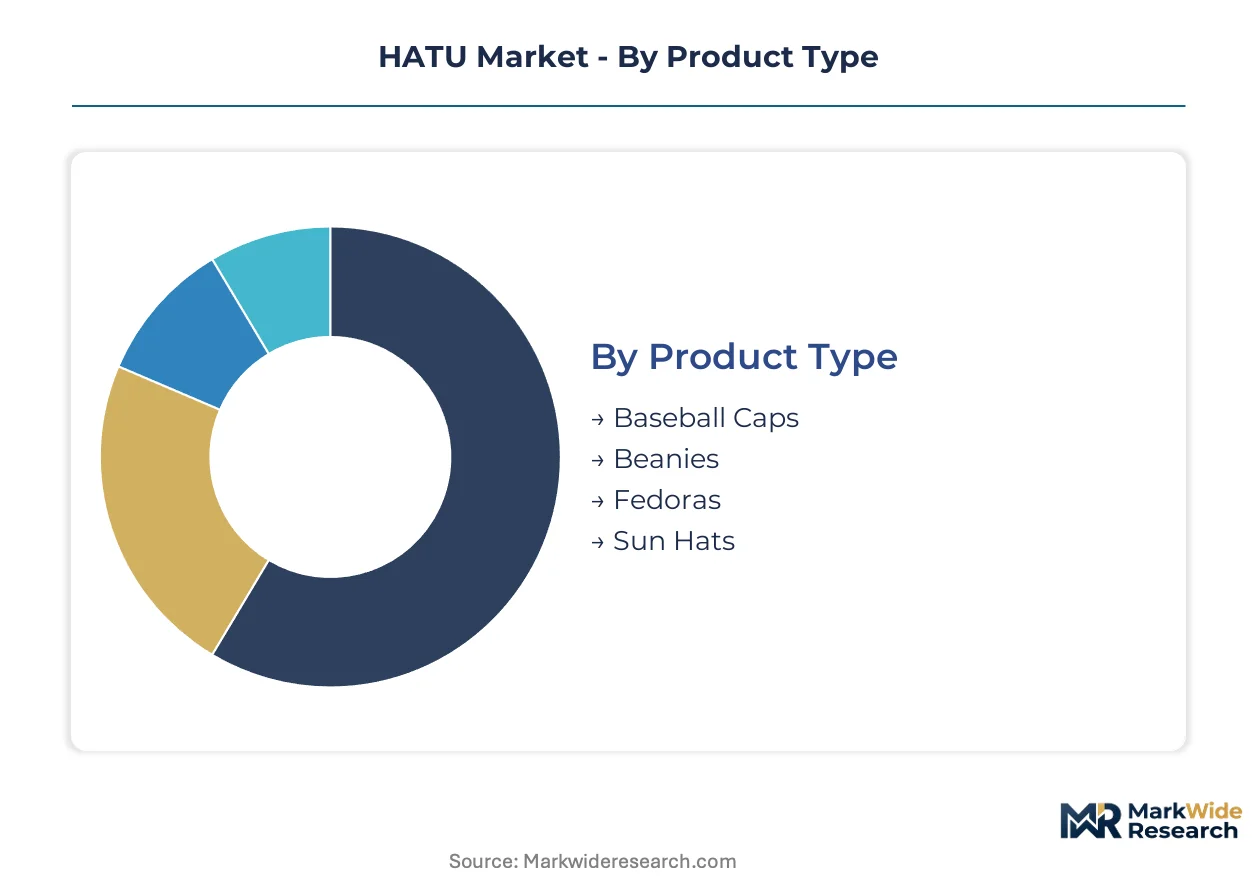
HATU coupling reagent procurement patterns diverge sharply across end-use applications and material specifications, with pharmaceutical-grade certification requirements filtering supplier pools differently than research-grade channels. Segment boundaries in this market reflect purity thresholds, storage logistics, and regulatory documentation burdens rather than simple volume scaling.
Product Type:
Replacement cycles for HATU inventory accelerate where peptide synthesis throughput intensifies, with contract manufacturers restocking more frequently than academic research labs.
- Baseball Caps:Cotton twill construction with six-panel design and pre-curved visor dominates casual wear channels. Demand concentrates in North American sporting goods retail where licensed team merchandise sustains seasonal replenishment cycles.
- Beanies:Knitted wool or acrylic ribbed construction provides thermal retention for cold-weather applications. European outdoor retailers and alpine resort gift shops drive replacement purchases tied to winter tourism patterns.
- Fedoras:Felted wool or straw construction with pinched crown and brim. Formal occasion segments in Japan and Italy sustain artisanal production tiers with extended replacement horizons.
- Sun Hats:Wide-brimmed cotton canvas or synthetic weave with UPF-rated fabric treatments. Australian and South African markets prioritize UV-protection performance claims driving faster material upgrade cycles.
Volume placements concentrate in Baseball Caps; the faster expansion belongs to Sun Hats.
Material:
Cost tiers stratify procurement behavior with natural fibers commanding premium positioning against synthetic alternatives in regulated pharmaceutical environments.
- Cotton:Breathable cellulose fiber with moisture-wicking properties suited to extended wear. Mass-market casual wear channels in India and Bangladesh source combed cotton for price-sensitive volume production.
- Wool:Crimped keratin fiber with natural elasticity and odor resistance. Italian and Scottish mills supply merino grades to premium outdoor brands with traceable sourcing requirements.
- Straw:Woven plant fiber construction including raffia, seagrass, and paper braid variants. Mexican and Chinese weaving clusters serve seasonal fashion cycles with limited durability expectations.
- Synthetic Fabrics:Polyester, nylon, or acrylic engineered for wash durability and shape retention. Performance-oriented segments in Germany and South Korea specify recycled-content synthetics meeting EU Green Deal procurement standards.
Procurement volumes cluster in Cotton; Synthetic Fabrics are climbing the fastest.
Usage Occasion:
Application context dictates margin structures with formal occasions sustaining premium pricing against commoditized casual channels.
- Casual Wear:Daily lifestyle integration with minimal functional requirements beyond aesthetic preference. US and Brazilian mass retailers drive high-volume, low-margin turnover with private-label dominance.
- Outdoor Activities:Performance specifications including water resistance, packability, and sun protection. Canadian and Norwegian outdoor specialty chains prioritize technical feature sets over brand heritage.
- Sports Events:Licensed merchandise with team or league-branded embellishment. Stadium concessionaires and e-commerce platforms in Spain and Argentina manage inventory around tournament calendars.
- Formal Occasions:Ceremonial or professional dress codes requiring structured silhouettes. British and French luxury houses control millinery supply chains with made-to-measure service tiers.
Shipment volumes center on Casual Wear; Outdoor Activities show the steepest expansion trajectory.
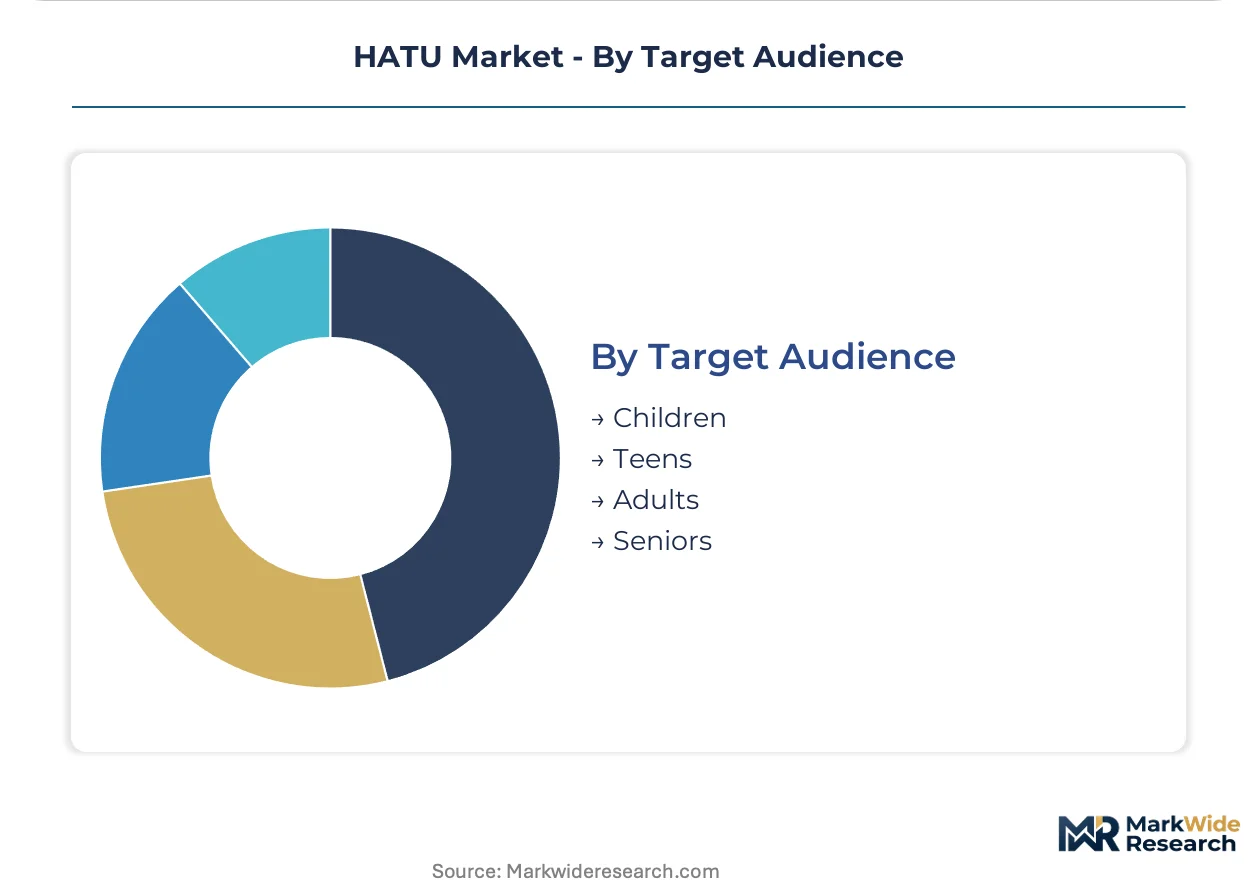
Target Audience:
Customer life stage segments reveal divergent price elasticity with adult professional channels funding premium tier development.
- Children:Sized-down constructions with safety-compliant closures and licensed character embellishments. Chinese and Vietnamese contract manufacturers supply global toy and apparel brands with stringent chemical testing protocols.
- Teens:Trend-responsive styling with social media-influenced purchase triggers. Fast-fashion retailers in Turkey and Mexico optimize rapid style turnover with compressed margin structures.
- Adults:Core market volume spanning professional, leisure, and commuter applications. Japanese and US department stores maintain broad assortment breadth across price tiers.
- Seniors:Comfort-prioritized fits with UV protection and adjustable sizing features. Australian and Florida retirement communities drive demand through pharmacy and catalog channels.
Adult segments anchor volume concentration; Teen channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide manufacturing demand concentrates in pharmaceutical clusters where GMP-grade reagent procurement networks have matured. FDA, EMA, and NMPA regulatory frameworks are diverging in purity documentation requirements. Switzerland, Massachusetts, and Shanghai host the densest sponsor-CMO co-location patterns.
United States
GLP-1 agonist manufacturing scale-up at Boston-area CMOs is multiplying HATU procurement volumes. FDA peptide drug approval pathways mandate certified supplier audits that filter non-specialized traders. Cambridge and Worcester clusters concentrate technical service relationships with direct batch-COA negotiations.
Switzerland
Basel-headquartered peptide sponsors are mandating supplier audit rights for multi-kilogram HATU procurement. Swissmedic GMP inspection protocols exceed standard ICH guidelines in documentation granularity. Basel and Zurich CMOs pilot continuous flow synthesis platforms with integrated HATU activation steps.
China
Domestic peptide API producers are qualifying indigenous HATU sources under streamlined NMPA raw material licensing. NMPA registration dossiers now accept indigenous reagent certificates for export-bound drug substances. Hangzhou and Shanghai technical service teams anchor East Asian distribution with direct sponsor relationships.
Germany
REACH authorization timelines for NMP solvent are forcing reformulation investments among European contract manufacturers. ECHA substance of very high concern screenings filter non-specialized reagent traders from market access. Bavarian and North Rhine-Westphalian CMOs are accelerating HATU compatibility studies in alternative activation media.
India
CDSCO production-linked incentive schemes for active pharmaceutical ingredients are attracting multinational peptide sponsors. The national pharmaceutical regulator has streamlined reference standard import protocols for method validation. Hyderabad and Mumbai CMOs are initiating local HATU qualification programs for captive supply relationships.
HATU Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates around three strategic tiers: ISO-certified GMP-grade suppliers, technical-grade bulk distributors, and captive acetonitrile-integrated producers. Competitive moves center on direct technical service deployment and batch-specific COA negotiation rights.
Among East Asian fabricators, Yangzhou Everbright Caps Manufacture and Hangzhou Tianguan Cap exemplify technical service-anchored distribution models. Henschel occupies a position within the ISO-certified tier for GMP peptide producers. These three represent contrasting archetypes: regional technical service deployment, domestic manufacturing scale, and pharmaceutical-grade certification specialization.
| Leading Market Players |
|---|
| Cap BAIRY |
| Headwear |
| Chautuan |
| Yangzhou Everbright Caps Manufacture |
| Zhangjiagang Huaxia Headgear |
| TTD |
| Henschel |
| Hangzhou Tianguan Cap |
| Berman |
| Others |
Pricing and Supply Chain Analysis
Solid-phase synthesis technician scarcity in Basel and Boston clusters amplifies labor-cost differentials between GMP-certified and technical-grade HATU tiers. This workforce concentration widens pricing spreads as contract manufacturers absorb premium staffing costs into pharmaceutical-grade quotations.
Pricing Analysis
Volume placements cluster in technical-grade bulk channels while margins concentrate in pharmaceutical-grade certification tiers. Three-tier pricing structure across GMP-certified, ISO-compliant, and technical-grade levels reflects purity documentation burdens and audit rights negotiations. Cost compression in technical-grade segments is intensifying because Chinese domestic manufacturers are scaling indigenous supply. Academic research labs exhibit highest price sensitivity; Swiss and Boston-area CMOs demonstrate lowest elasticity due to sponsor-mandated supplier qualification requirements.
Supply Chain Analysis
Single-source vulnerability sits with Chinese specialty fluoride manufacturers supplying hexafluorophosphate precursors. Manufacturing concentrates in China, India, and Switzerland with downstream formulation anchored in pharmaceutical clusters. Acetonitrile feedstock, hexafluorophosphate salts, and cold-chain packaging constitute critical input dependencies. Export license delays from Beijing authorities pose structural risk to global availability. Distribution runs through direct technical service relationships displacing traditional distributor intermediaries for multi-kilogram procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HATU procurement operates as a cost-of-compliance story where REACH registration dossiers and FDA supplier audit mandates erect barrier-to-entry moats. ECHA substance of very high concern screenings filter non-specialized traders, entrenching compliant incumbents.
For Market Incumbents: Lock in sponsor-CMO co-location advantages by embedding technical service teams within Basel, Boston, and Shanghai clusters. Deepen captive acetonitrile supply relationships to buffer feedstock volatility threatening margin stability. Counter emerging Indian API producers with accelerated ISO 17034 reference material certification investments.
For New Entrants and Emerging Players: Mid-scale Indian CMOs represent the most penetrable buyer archetype as CDSCO production-linked incentive schemes attract multinational peptide sponsors. Pursue local HATU qualification programs in Hyderabad and Mumbai before incumbent technical service networks solidify. Differentiate through continuous flow synthesis compatibility studies addressing solvent substitution pressures.
For Investors and Strategic Acquirers: Re-rating potential sits with ISO-certified GMP-grade suppliers given FDA accelerated approval pathways multiplying downstream audit requirements. Long-term viability favors specialists with full REACH registration dossiers and direct sponsor relationships. Watch NMPA export certificate acceptance rates as inflection indicator for Chinese indigenous supply displacement of import channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetonitrile Supply | Captive feedstock sourcing buffers agrochemical demand swings compressing reagent margins. |
| ISO 17034 Reference Material Certification | Accredited purity standards enable contract labs to streamline method validation protocols. |
| Continuous Flow Synthesis Platform Deployment | Swiss and Massachusetts CMOs pilot integrated HATU activation with real-time PAT analytics. |
| Direct Technical Service Team Expansion | Hangzhou and Shanghai teams anchor East Asian distribution through sponsor co-location. |
| REACH Registration Dossier Completion | Full ECHA compliance filters non-specialized traders from European market access. |
Research Methodology
Trade databases, ECHA registration filings, and NMPA licensing records formed the secondary backbone for supply-side mapping. Primary interviews with peptide synthesis directors, regulatory affairs leads at CMOs, procurement managers at API sponsors, and technical service heads at reagent distributors validated demand patterns. Bottom-up reagent procurement volumes from contract manufacturing networks triangulated against top-down peptide drug pipeline analysis.
Historical trendline analysis across pharmaceutical-grade and technical-grade consumption patterns informed projection modeling. Segmentation dimensions included purity tier, end-use application, regional regulatory cluster, and synthesis workflow type. CAGRs derived from weighted average of sponsor-CMO expansion trajectories and indigenous supply qualification timelines. Forecast inputs incorporated GLP-1 agonist manufacturing scale-up assumptions and REACH authorization sunset dates for solvent alternatives.
Revisions become necessary when ECHA substance of very high concern designations expand, NMPA export protocols shift, or hexafluorophosphate export licensing encounters geopolitical friction. Forecasts reflect documented assumptions about peptide drug approval velocities and cold-chain logistics cost structures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Cresols Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Detergent Alcohols Market
Chemicals
Copper Oxychloride Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Ferric Fluoride Market
Chemicals
Antiozonant Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
De-Icing Agents Market
Chemicals
Global Thiophene Market
Chemicals
Global Oxo Alcohols Market
Chemicals
Aerosol Insecticides Market
Chemicals
Global Phenoxyethanol Market
Chemicals
Morpholine Market
Chemicals
P-Ethylphenol Market
Chemicals
6 Hexanediol Market