
 Metal Finishing Chemicals Market | 2026-2036
Metal Finishing Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Finishing Chemicals Market Intelligence
The long-standing procurement model favoring small, regional metal fabricators is unwinding as large OEMs centralize their surface treatment specifications. This shift benefits large-scale chemical suppliers. Henkel AG & Co. KGaA leverages its extensive portfolio to serve these consolidated OEM accounts. Atotech Deutschland GmbH specializes in advanced electroplating solutions required for high-tech electronics and automotive applications, while Chemetall GmbH maintains a strong position in aerospace surface treatments.
Metal finishing chemicals are specialized formulations applied to metallic substrates to alter their surface properties. These treatments, which can include the deposition of metallic layers or the formation of a passivated film, provide critical corrosion resistance, wear protection, and aesthetic enhancement. Within product types, electroplating chemicals command a significant share due to their use in automotive and electronics manufacturing. Demand for conversion coatings is accelerating, particularly for providing corrosion protection on aluminum components in aerospace and construction materials.
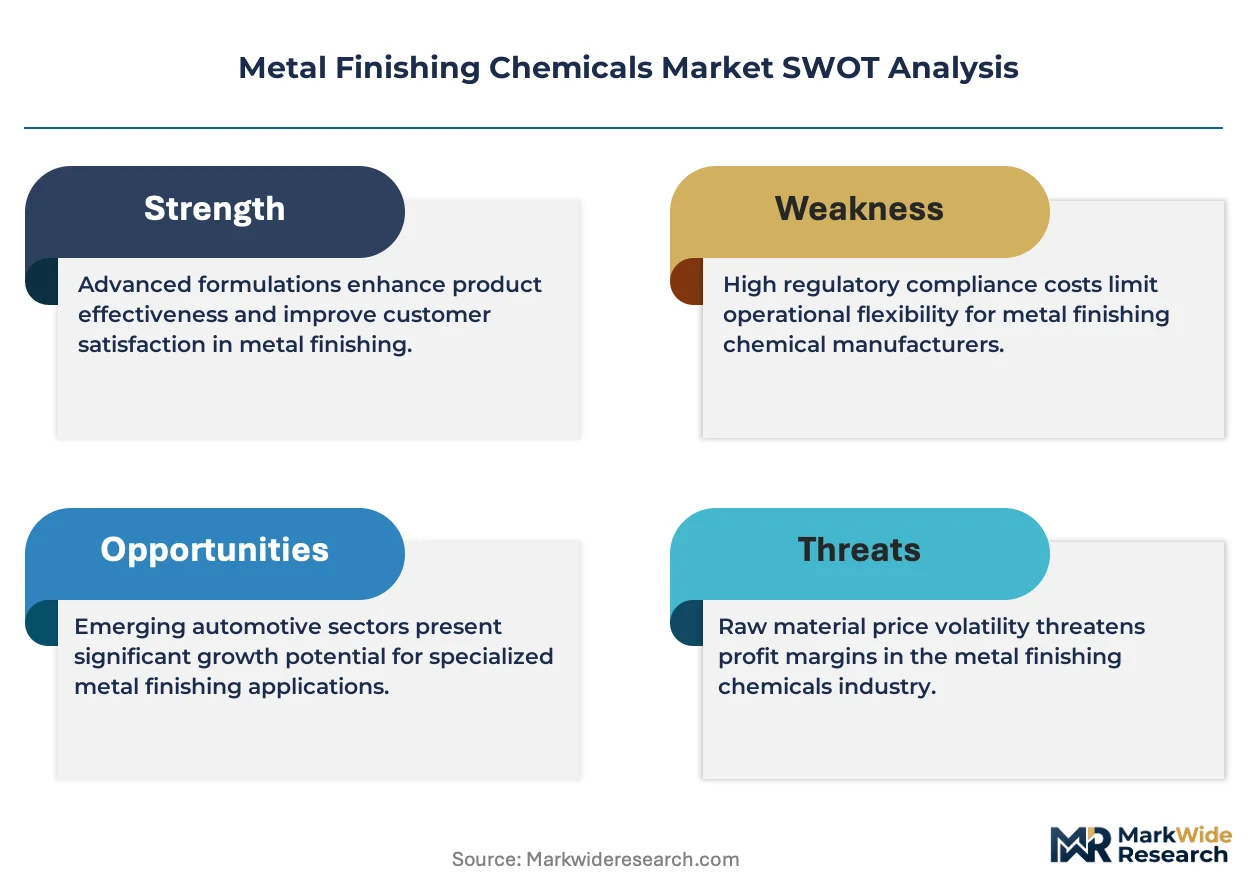
Regulatory frameworks, including the EU's REACH, US EPA guidelines, and China's GB standards, heavily influence product development. These rules mandate the phase-out of hazardous substances like hexavalent chromium, forcing a shift towards compliant alternatives. The ability to scale production of high-performance, environmentally benign chemical systems will determine future market leadership.
Market Dynamics
The imperative to replace hazardous substances, most notably hexavalent chromium, stands as the central structural force in the metal finishing chemicals market. This regulatory-driven substitution is compelling a fundamental reinvention of product portfolios and application processes across global supply chains.
Growth Catalysts
- Regulatory Mandates:The EU's REACH framework and similar regulations are forcing the phase-out of legacy chemicals, creating a direct and immediate market for compliant, high-performance alternatives like trivalent chromium and chrome-free conversion coatings.
- Aerospace Sector Demand:Expansion in aerospace manufacturing accelerates the need for advanced surface treatments, particularly corrosion-resistant coatings for lightweight aluminum and titanium alloys used in airframes and engine components.
- Manufacturing Concentration:The continued consolidation of industrial manufacturing activity in China creates a geographically focused, high-volume consumption base for a wide range of metal finishing chemicals, from electroplating to passivation.
Market Restraints
- Raw Material Volatility:The price and availability of key metals used in electroplating formulations, such as nickel, zinc, and tin, are subject to significant market fluctuations, creating input cost instability for chemical manufacturers.
- Performance Gaps:Some environmentally compliant alternatives still exhibit performance deficits in extreme corrosion or wear resistance compared to legacy systems like hexavalent chromium, limiting their adoption in certain critical applications.
- Complex Certification Pathways:Gaining approval for new chemical formulations across multiple international regulatory bodies, including the US EPA and ECHA in Europe, is a costly and time-consuming process that can delay market entry.
Strategic Opportunities
- Electric Vehicle Components:The rapid growth of the electric vehicle market creates a new, large-scale opportunity for specialized coatings providing corrosion protection and electrical insulation for battery enclosures, busbars, and motor housings.
- Functional Nanocoatings:Integrating nanomaterials into finishing formulations to create surfaces with enhanced properties, such as self-healing, anti-microbial, or super-hydrophobic characteristics, opens new value-added market segments.
- Southeast Asia Expansion:As manufacturing diversifies beyond China, countries like Vietnam, Indonesia, and Thailand represent underpenetrated markets for advanced finishing chemicals, particularly in the electronics and automotive parts sectors.
Industry Challenges
- Specialized Talent Scarcity:A shortage of chemical engineers and process technicians with expertise in both modern, environmentally benign chemistries and the automated equipment required for their application poses an operational constraint.
- Capital-Intensive Transitions:End-users face significant capital expenditure to retrofit or replace existing finishing lines to make them compatible with new chemical systems, which can slow the pace of adoption.
- Supply Chain Reconfiguration:Shifting to new product formulations requires a corresponding adjustment in the raw material supply chain, creating logistical challenges in sourcing and qualifying new suppliers while maintaining quality consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Finishing Chemicals Market |
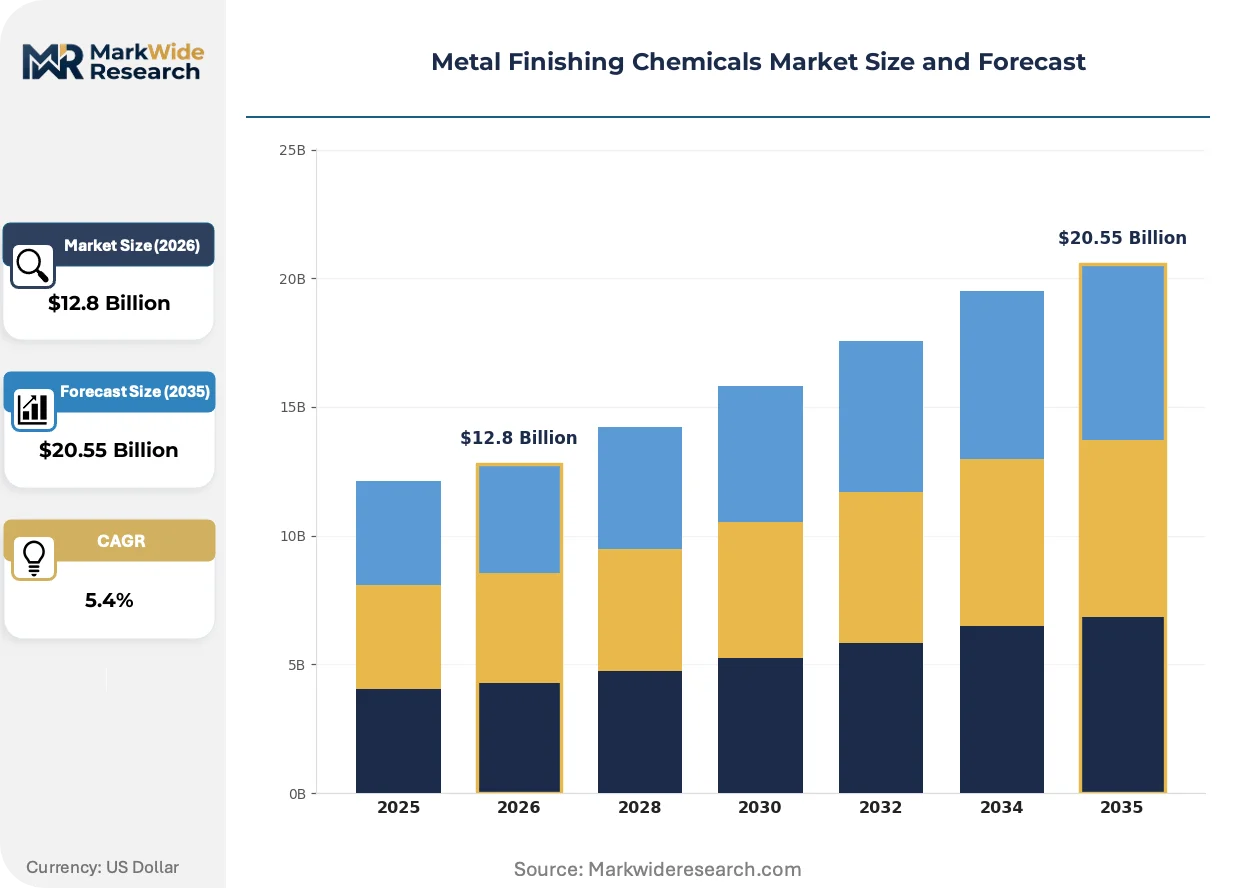
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $20.55 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroplating, Anodizing, Passivation, Conversion Coating, Cleaning Agents Technology: Cathodic Electrodeposition, Barrel Plating, Rack Plating, Immersion Plating, Spray Coating Application: Electronics Manufacturing, Aerospace Components, Construction Materials, Consumer Goods, Marine Equipment End User: OEMs, Tier-1 Suppliers, Metal Fabricators, Surface Treatment Plants, Aftermarket Providers |
| Companies Covered | DOW, Chemetall GmbH, Atotech Deutschland GmbH, Henkel AG & Co. KGaA, Elementis PLC, NOF Corporation, Houghton International Inc., McGean-Rohco Inc., Quaker Chemicals Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Finishing Chemicals Market Strategic Shifts & Innovations
The market is defined by a dual pursuit of enhanced performance and environmental compliance. This pressure is driving innovation not only in chemical formulations but also in the efficiency and precision of their application, pushing suppliers to deliver holistic system-level improvements.
Advanced Electroplating for Electronics
Specialized electroplating chemicals are formulated to deposit uniform metallic layers on printed circuit boards. The high-tech electronics sector is rapidly adopting these advanced solutions to meet stringent performance requirements. This technology trend is miniaturizing the conductive traces and vias on complex multi-layer boards, enabling the production of more powerful and compact electronic devices.
Water-Based and Compliant Chemistries
China's GB standards, aligned with its national dual carbon goals, are imposing stricter limits on volatile organic compounds and hazardous substances in industrial processes. This directly impacts chemical selection, compelling a transition away from solvent-based systems. The automotive and construction materials sectors are most affected, accelerating their shift toward water-based pretreatment chemicals and formulations compatible with powder coating applications.
Centralization of OEM Specifications
A significant behavioral shift is underway as large, global OEMs increasingly centralize surface treatment specifications for components used across their worldwide manufacturing platforms. This trend disrupts the traditional procurement model where regional fabricators selected their own chemical suppliers. This pattern is most visible within the automotive and aerospace verticals, where ensuring global product consistency and quality is a primary strategic objective.
Metal Finishing Chemicals Market Segmentation
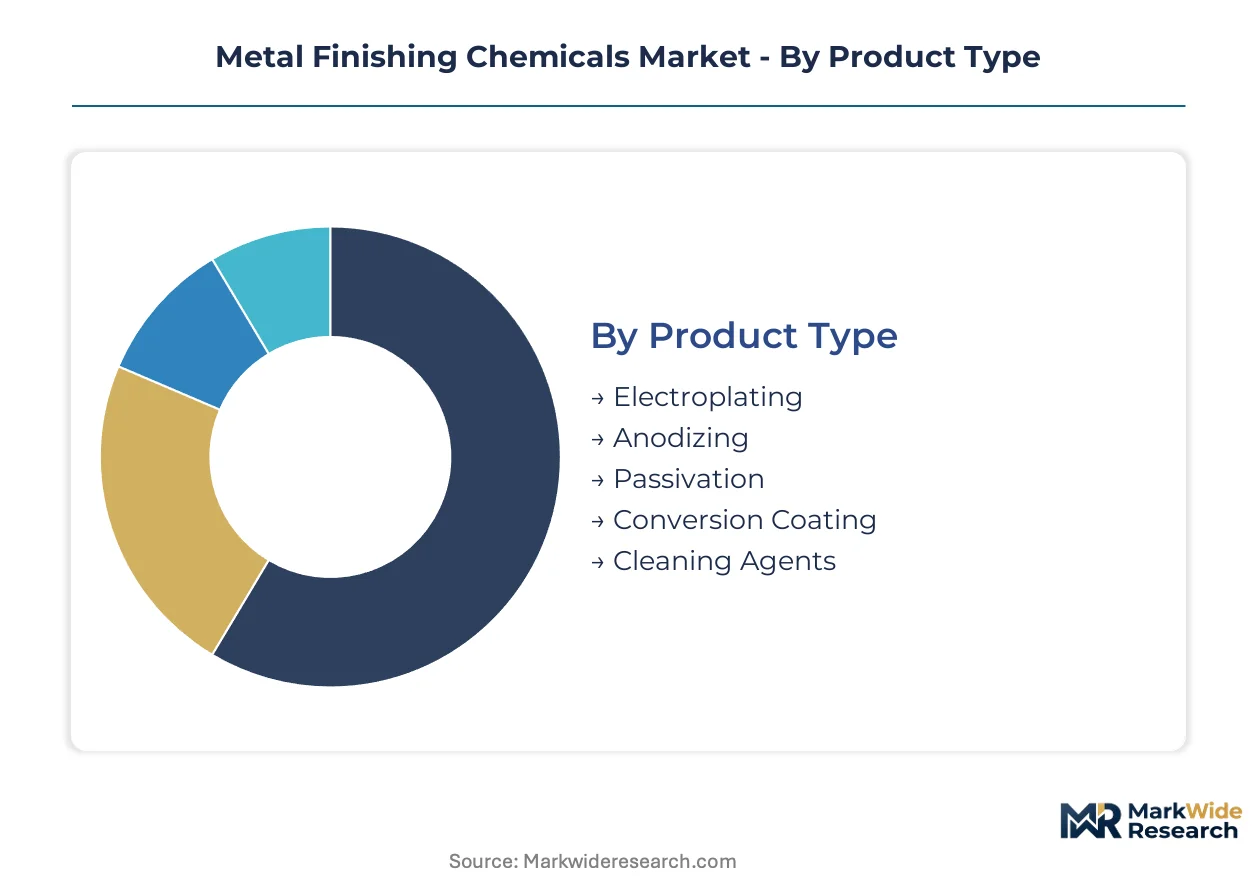
The metal finishing chemicals market is categorized by the distinct properties and applications of its chemical formulations, the technologies employed for their deposition, the end-use industries they serve, and the types of entities that consume them. Understanding these segments reveals where value creation and technological advancements are most concentrated within the industry.
Product Type:
Margin pools within product types gravitate towards specialized formulations offering superior performance or environmental compliance.
- Electroplating:Electroplating chemicals facilitate the deposition of uniform metallic layers onto substrates, enhancing conductivity and corrosion resistance. Demand concentrates in the automotive and electronics sectors, driven by the need for advanced surface properties in complex components.
- Anodizing:Anodizing chemicals create a durable, porous oxide layer on aluminum, offering enhanced corrosion and wear resistance for architectural and automotive parts.
- Passivation:Passivation chemicals remove free iron from stainless steel surfaces, forming a protective oxide layer that prevents rust and maintains material integrity.
- Conversion Coating:Conversion coatings form a protective passive film on metal surfaces, primarily for corrosion resistance and adhesion promotion for subsequent layers. This segment sees accelerating demand for aluminum components in aerospace and construction materials, particularly with chrome-free alternatives.
- Cleaning Agents:Cleaning agents prepare metal surfaces by removing oils, greases, and contaminants, ensuring optimal adhesion and performance of subsequent finishing treatments.
Electroplating holds significant installed capacity due to its long-standing use. Conversion Coating is rotating up the share rankings due to regulatory shifts.
Technology:
Technology adoption within metal finishing aligns with the complexity and scale of the parts being treated.
- Cathodic Electrodeposition:Cathodic electrodeposition applies a uniform coating using an electric current, ideal for complex geometries and achieving precise film thickness. This technology is critical for automotive components requiring excellent corrosion protection and for specialized electronics applications.
- Barrel Plating:Barrel plating processes coat large volumes of small parts by tumbling them in a rotating barrel containing the plating solution. Its efficiency makes it a cost-effective solution for fasteners, connectors, and other small components in consumer goods manufacturing.
- Rack Plating:Rack plating uses specialized racks to hold larger or more delicate parts individually, ensuring uniform coating and preventing damage during treatment.
- Immersion Plating:Immersion plating, or electroless plating, deposits metallic coatings without an external electric current, useful for intricate parts and non-conductive substrates.
- Spray Coating:Spray coating applies liquid or powder chemicals directly onto surfaces, offering flexibility for large structures and localized treatment in construction.
Cathodic Electrodeposition shows strong expansion in new application areas. Barrel Plating maintains its large volume contribution to the market.
Application:
Application segments are differentiated by the specific performance requirements and regulatory compliance needs of their end products.
- Electronics Manufacturing:Electronics manufacturing requires highly specialized finishing chemicals for printed circuit boards and semiconductor components, ensuring conductivity and reliability. Miniaturization and increasing complexity of devices drive demand for advanced electroplating solutions and precise surface treatments.
- Aerospace Components:Aerospace components demand extreme corrosion resistance, wear protection, and lightweight solutions for airframes, engines, and landing gear. Expansion in aerospace manufacturing accelerates the need for advanced surface treatments, particularly chrome-free coatings for aluminum and titanium alloys.
- Construction Materials:Construction materials utilize metal finishing chemicals for durability and aesthetic appeal on facades, roofing, and structural elements, often focusing on weather resistance.
- Consumer Goods:Consumer goods employ finishing chemicals for decorative purposes, corrosion protection, and improved tactile feel on appliances, electronics, and household items.
- Marine Equipment:Marine equipment requires robust anti-corrosion and anti-fouling coatings to withstand harsh saltwater environments, extending the lifespan of vessels and offshore structures.
Electronics Manufacturing continues to drive high-value chemical innovation. Aerospace Components are gaining share fastest due to stringent material requirements.
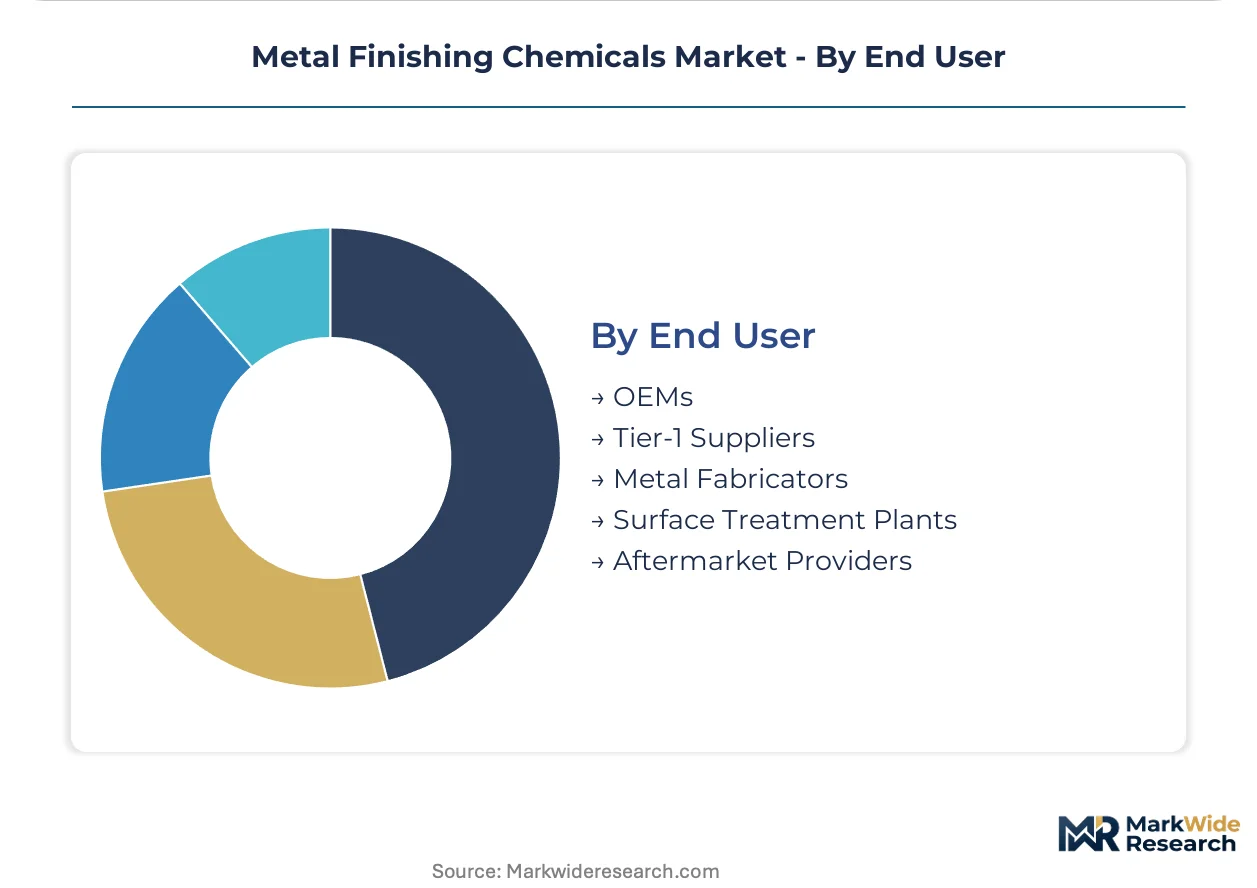
End User:
End-user segments reflect diverse procurement models, ranging from in-house processing to specialized external service providers.
- OEMs:Original Equipment Manufacturers (OEMs) increasingly centralize surface treatment specifications for components used across their global manufacturing platforms. This shift benefits large-scale chemical suppliers capable of providing consistent quality and technical support across multiple regions, especially in automotive and aerospace.
- Tier-1 Suppliers:Tier-1 suppliers integrate metal finishing into their production lines for specific components, ensuring compliance with OEM specifications and quality standards.
- Metal Fabricators:Metal fabricators often apply basic finishing treatments in-house or outsource to regional providers, focusing on cost-efficiency for their processed materials.
- Surface Treatment Plants:Surface treatment plants are specialized facilities offering a broad range of finishing services to various industries, leveraging advanced equipment and expertise. They serve as crucial intermediaries, enabling smaller fabricators and diverse clients to access high-quality finishing processes without significant capital investment.
- Aftermarket Providers:Aftermarket providers supply chemicals for repair, maintenance, and customization of existing products, catering to specific needs in automotive and industrial sectors.
OEMs are reshaping competitive positioning through centralized procurement. Surface Treatment Plants are adapting their service offerings to meet evolving regulatory demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OEMs increasingly centralize surface treatment specifications, reshaping procurement models across major industrial regions. This shift drives demand for consistent, high-performance chemical systems globally. Environmental regulations and technological advancements also influence regional market dynamics.
China
China's industrial manufacturing activity creates a significant, geographically focused consumption base for metal finishing chemicals. The country's GB standards and dual carbon goals compel a transition towards water-based and compliant chemistries. The Yangtze River Delta region, a hub for electronics and automotive production, experiences high-volume demand for advanced electroplating and conversion coatings.
Germany
Germany's robust automotive and high-tech electronics sectors drive demand for specialized metal finishing solutions. The EU's REACH framework mandates the phase-out of hazardous substances, accelerating innovation in chrome-free alternatives. Bavaria, a key automotive manufacturing region, focuses on adopting high-performance, environmentally benign chemical systems for vehicle components.
United States
The United States aerospace components sector and growing electric vehicle market fuel demand for advanced surface treatments. US EPA guidelines influence product development, pushing for safer chemical formulations. Detroit's automotive cluster and Seattle's aerospace industry require specialized coatings for corrosion resistance and wear protection.
Japan
Japan's advanced electronics manufacturing and precision automotive industries require highly specialized finishing chemicals. JIS standards ensure stringent quality and environmental compliance for industrial processes. The Kanto region, including Tokyo, remains a center for developing and adopting advanced electroplating solutions for miniaturized components.
India
India's expanding automotive and electronics manufacturing sectors contribute to a rising demand for metal finishing chemicals. The Bureau of Indian Standards (BIS) promotes quality and safety in industrial applications. Maharashtra, a significant industrial state, sees growing adoption of compliant chemistries for diverse manufacturing needs.
Metal Finishing Chemicals Market Key Industry Players
Player mix skews toward large-scale chemical suppliers capable of serving centralized OEM accounts. The market exhibits a tiered structure, with global players offering extensive portfolios alongside specialized providers focusing on niche applications. Key strategic archetypes include diversified chemical giants, advanced electroplating specialists, and aerospace surface treatment experts. Companies primarily engage in portfolio diversification and technology innovation to meet evolving regulatory and performance demands.
Within the diversified chemical giants' tier, Henkel AG & Co. KGaA leverages its extensive portfolio to serve consolidated OEM accounts across various industries. Atotech Deutschland GmbH occupies a position among specialists, providing advanced electroplating solutions for high-tech electronics and automotive applications. Chemetall GmbH anchors its competitive positioning in aerospace surface treatments, focusing on corrosion protection for critical components.
| Leading Market Players |
|---|
| DOW |
| Chemetall GmbH |
| Atotech Deutschland GmbH |
| Henkel AG & Co. KGaA |
| Elementis PLC |
| NOF Corporation |
| Houghton International Inc. |
| McGean-Rohco Inc. |
| Quaker Chemicals Corp |
| Others |
Cost & Logistics Intelligence
EU's REACH framework and China's GB standards gate the qualification of new chemical suppliers, directly influencing both market access and the premium achievable for environmentally compliant formulations. This regulatory pressure drives price differentiation for advanced, chrome-free alternatives.
Pricing Analysis
The pricing gap between legacy hexavalent chromium systems and next-generation chrome-free alternatives is significant, reflecting R&D investment and regulatory compliance costs. Pricing predominantly follows a contract-based long-term offtake model, particularly for large OEM accounts. Price differentiation stems from the stringent certification level required for aerospace or electronics applications and the enhanced performance tier of specialized formulations. Raw material volatility for metals like nickel and zinc creates pricing pressure for chemical manufacturers. Metal fabricators often exhibit the highest price sensitivity, while major OEMs prioritize performance and compliance over cost.
Supply Chain Analysis
Inventory management for metal finishing chemicals often balances just-in-time delivery for high-volume users with strategic stockpiles of critical raw materials. Supply concentration for base chemicals and specialized additives centers in China, Germany, and the United States. The industry relies heavily on key metals such as nickel, zinc, and tin, exposing the supply chain to significant commodity price volatility. Distribution runs through direct supply channels to large OEMs and Tier-1 suppliers, complemented by specialized chemical distributors serving regional metal fabricators and surface treatment plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metal finishing chemicals market presents a defensive moat story, primarily due to the deep regulatory entrenchment of compliant formulations and the high switching costs associated with changing established chemical systems. This creates sustained demand for approved solutions.
For Market Incumbents:Fortify market leadership by accelerating R&D investment into next-generation chrome-free alternatives that close existing performance gaps, especially for extreme corrosion resistance. Expand global technical support and application engineering capabilities to serve centralized OEM specifications. Invest heavily in certification processes for new environmentally benign chemistries to maintain regulatory compliance. Consolidate market share through strategic acquisitions of smaller, innovative formulators specializing in functional nanocoatings.
For New Entrants and Emerging Players:Differentiate on specialized performance for emerging applications, targeting the electric vehicle components market with novel corrosion protection and electrical insulation solutions. Pursue opportunities in functional nanocoatings, creating surfaces with enhanced properties like self-healing or anti-microbial characteristics. The Southeast Asia automotive parts sector represents a penetrable segment for advanced finishing chemicals. Go-to-market strategies should emphasize integrated system solutions, bundling chemicals with application expertise and equipment compatibility.
For Investors and Strategic Acquirers:The EU's REACH framework reshapes the acquisition landscape, favoring companies with proven portfolios of compliant, high-performance chemistries. This market offers sustained demand for compliant solutions over a 5-10 year window, driven by continuous regulatory evolution. Acquisition targets should include advanced electroplating specialists like Atotech Deutschland GmbH and aerospace surface treatment experts such as Chemetall GmbH. The speed of hexavalent chromium phase-out in critical applications will serve as a key signal for investment prioritization.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Chrome-Free Production | Ensures readiness to meet accelerating demand for compliant alternatives driven by EU's REACH. |
| R&D Investment in Functional Nanocoatings | Captures new value-added market segments in electronics and automotive applications. |
| Global Technical Support Network Enhancement | Serves centralized OEM accounts like Henkel AG & Co. KGaA with consistent quality. |
| Joint Venture for EV Battery Component Coatings | Penetrates the rapidly growing electric vehicle market with specialized corrosion protection. |
| Certification Pathway Acceleration for New Chemistries | Speeds market entry for environmentally benign systems, gaining regulatory advantage. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted during the primary research phase, complementing extensive secondary data validation. Interviews included R&D directors, procurement leads at major OEMs, chemical plant managers, and distribution channel partners. Secondary sources encompassed customs and trade data, industry reports from chemical associations like ACC, and company SEC 10-K filings. This approach utilized both bottom-up market sizing from individual segments and top-down validation against macroeconomic indicators.
The forecast framework established a comprehensive analytical window, modeling market dynamics from the base year through the projection horizon. Segmentation dimensions included product type, technology, application, end-user, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical trends, projected technological advancements, and anticipated market shifts. Key industry-specific inputs included regulatory compliance timelines for hazardous substances and electric vehicle production forecasts.
Decision-makers should treat outputs as directional under current raw material stability and regulatory enforcement assumptions; material deviation would warrant model refresh. Forecasts reflect a specific set of macroeconomic and technological assumptions. Raw material price volatility or accelerated regulatory shifts represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Fluorene Market
Chemicals
Global Methylene Chloride Market
Chemicals
Solder Flux Market
Chemicals
Global Electronic Grade Phosphoric Acid Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Ammonia Market
Chemicals
Caustic Soda Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Tributyl Phosphate Market
Chemicals
Pinoxaden Market
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Linear Mercaptans Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
India Metal Treatment Chemical Market