
 Polyphosphoric Acid (PPA) Market | 2026-2036
Polyphosphoric Acid (PPA) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphosphoric Acid (PPA) Market Analytics
The divergence between pharmaceutical-grade and industrial-grade PPA is hardening around purity thresholds and certification overhead. ICL Group Ltd leverages captive phosphate rock supply to sustain cost advantages across both tiers. PJSC PhosAgro anchors its position through vertical integration into phosphorus raw materials, while Solvay SA differentiates via specialized polymer-grade formulations for European chemical manufacturers.
Polyphosphoric Acid (PPA) is a condensed phosphoric acid polymer with a P2O5 content typically ranging from 76% to 85% by weight, produced through thermal dehydration of orthophosphoric acid under controlled temperature profiles; it functions primarily as a dehydration agent, catalyst, and phosphate source in industrial synthesis. The technical grade segment dominates volume flows into fertilizer and water treatment applications, whereas pharmaceutical grade commands concentrated margin pools due to stringent USP and EP compliance requirements. Chemical synthesis applications represent the fastest-expanding demand channel as PPA replaces conventional sulfuric acid in selective esterification reactions for specialty surfactants and lubricant additives.
The EPA regulates PPA under TSCA reporting requirements for phosphorus compound manufacturing, while REACH mandates registration and hazard communication for industrial-grade imports into the European Union; China's MEE enforces wastewater discharge limits that push producers toward closed-loop thermal process designs. Forward-looking stakeholders must weigh regulatory compliance costs against the margin premium available in pharmaceutical and food-grade certifications.
Market Dynamics
Polyphosphoric Acid production is consolidating around thermal dehydration process efficiency as energy costs force reactor upgrades and captive phosphate rock access becomes the decisive cost variable separating margin leaders from commodity processors.
Growth Catalysts
- REACH Phase-in Substances Registration:ECHA's updated dossier requirements for phosphorus compounds are accelerating pharmaceutical-grade PPA qualification timelines among European fine chemical manufacturers seeking compliant catalyst sources.
- Specialty Surfactant Esterification:Lubricant additive producers in Germany and the United States are substituting sulfuric acid with PPA-derived phosphate esters to achieve cleaner reaction profiles and reduced wastewater treatment burden.
- China's Captive Phosphate Integration:Domestic phosphoric acid capacity expansion in Guizhou and Yunnan provinces is enabling backward integration into PPA for flame retardant and fertilizer additive manufacturing.
Market Restraints
- Phosphate Rock Price Volatility:Concentrated Moroccan and Chinese phosphate ore supply exposes PPA producers to input cost spikes that compress margins on fixed-price industrial-grade contracts.
- Technical Purity Ceiling:Conventional thermal dehydration processes face inherent limits in achieving USP-grade P2O5 consistency without prohibitively expensive fractional crystallization add-ons.
- Sulfuric Acid Substitution Resilience:Established mineral acid supply chains in commodity esterification retain cost advantages that slow PPA penetration in price-sensitive industrial surfactant segments.
Strategic Opportunities
- India's Agrochemical Formulation Expansion:CDSCO's streamlined active ingredient registration is attracting PPA-based phosphate ester investments for crop protection chemical synthesis.
- Battery Electrolyte Additive Convergence:Lithium-ion cell manufacturers are testing polyphosphate-derived flame retardant synergists that combine thermal stability with ionic conductivity enhancement.
- Food-Grade Certification Premium:FSSAI's tightening food additive purity specifications in India is creating margin pools for processors capable of meeting combined EP/FCC/GB standards.
Industry Challenges
- Thermal Process Engineering Talent Scarcity:Specialized reactor design and temperature-profile optimization expertise for high-viscosity PPA production concentrates among a shrinking cohort of legacy phosphorus chemists.
- Multi-Jurisdiction Certification Timelines:Simultaneous USP, EP, and GB standard qualification for pharmaceutical-grade material extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphosphoric Acid (PPA) Market |
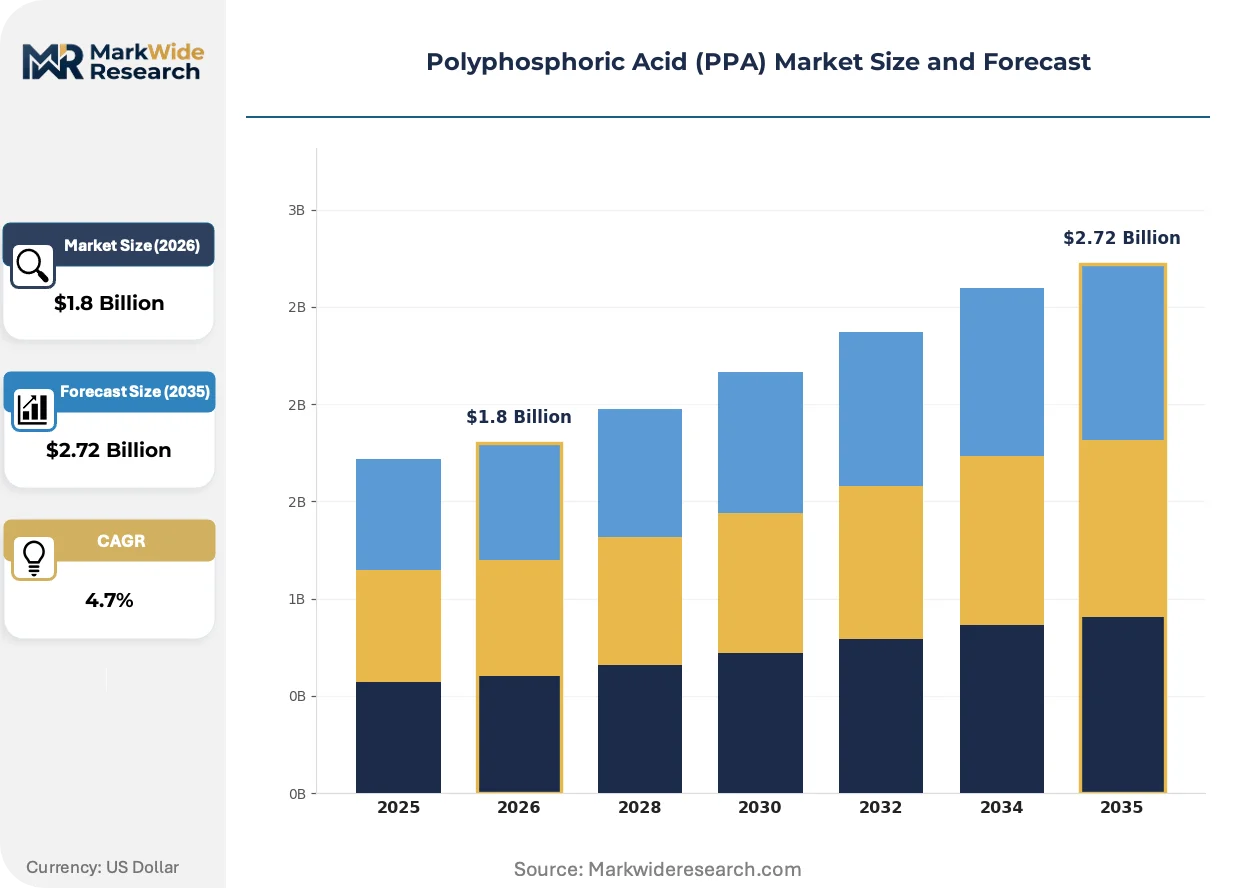
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Food Grade, Pharmaceutical Grade, Industrial Grade Application: Fertilizers, Water Treatment, Chemical Synthesis, Flame Retardants End User: Agriculture, Water Utilities, Chemical Manufacturing, Plastics Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | ICL Group Ltd, EuroChem Group, OCP Group, IFFCO, Solvay SA, The Mosaic Company, Nutrien Ltd, Ma’aden, PJSC PhosAgro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphosphoric Acid (PPA) Market Evolving Landscape
Process intensification and regulatory harmonization are compressing the technology gap between industrial and pharmaceutical-grade production, while end-use diversification into energy storage materials is opening non-traditional demand channels.
Membrane-assisted thermal dehydration is unifying water removal efficiency with impurity rejection in next-generation PPA reactors. Specialty chemical manufacturers in the Netherlands and Japan are piloting ceramic membrane modules that reduce energy intensity by 15-20% versus conventional atmospheric dehydration. This technology convergence is compressing capital payback periods for mid-scale producers seeking pharmaceutical-grade certification without greenfield reactor investments.
REACH's 2023 updated guidance on persistent, bioaccumulative, and toxic substance assessment is redirecting phosphorus compound classification efforts across EU chemical manufacturers. The industrial consequence is accelerated substitution of linear phosphate esters with branched-chain alternatives synthesized via high-purity PPA intermediates. Water treatment chemical formulators in Belgium and France are most affected, with several producers advancing dossier updates to maintain downstream authorization.
Specification-driven supplier consolidation is concentrating procurement among dual-certified PPA sources capable of spanning pharmaceutical and food-grade applications. Distributor networks in North America are losing share to direct mill relationships as large agrochemical and personal care manufacturers consolidate qualified vendor lists. This pattern is most visible in the United States, where three major surfactant producers have reduced active PPA suppliers from seven to three since 2022.
Polyphosphoric Acid (PPA) Market Segmentation
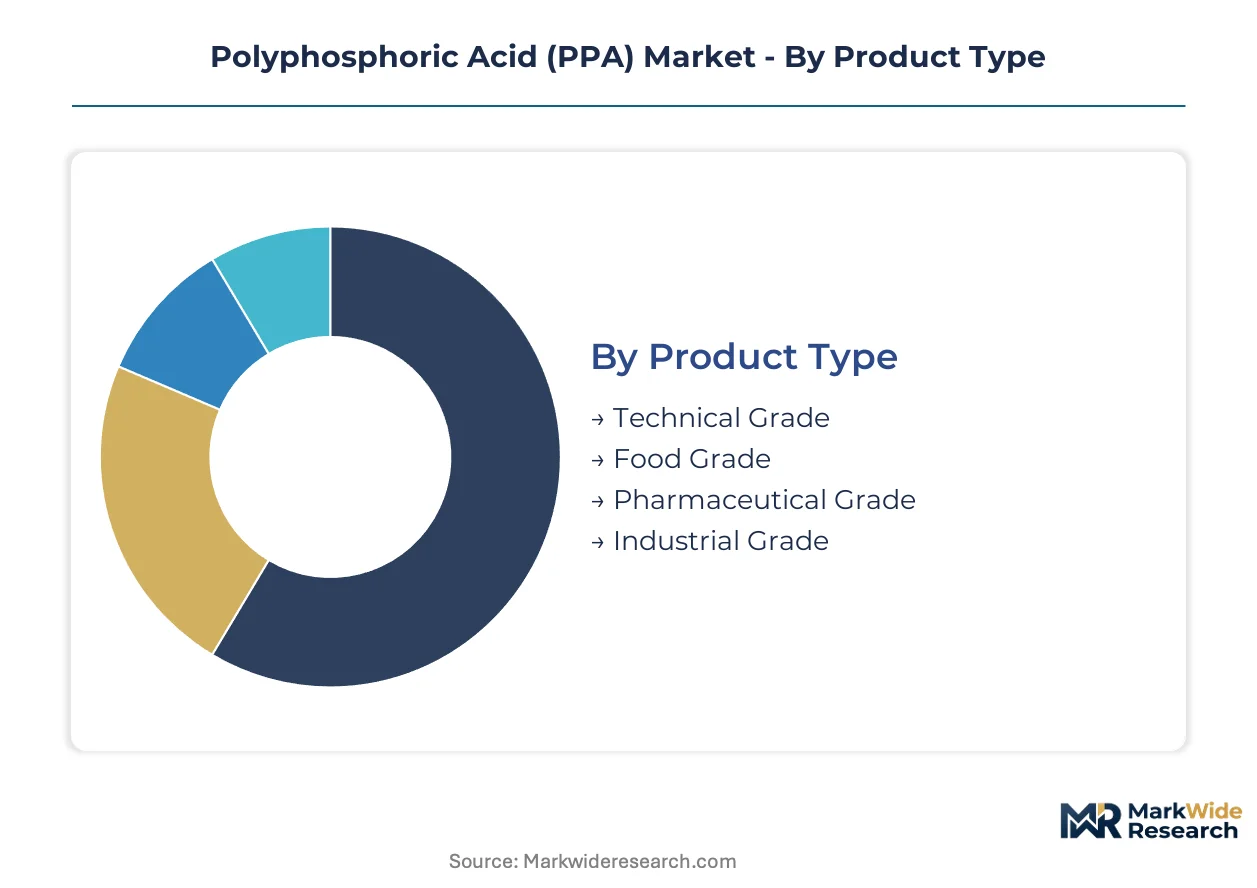
Polyphosphoric Acid market segmentation reflects a supply-side split between commodity volume flows and certified premium tiers. Grade differentiation determines pricing architecture, while application channels expose divergent regulatory exposure across end-use verticals.
Product Type:
Supply concentration in phosphate rock access hardens cost advantages around grade-specific purification thresholds.
- Technical Grade:P2O5 content ranges from 76% to 85% with controlled viscosity profiles for industrial dehydration applications. Fertilizer additive manufacturing in China and water treatment chemical formulators in Germany absorb the largest volume flows, driven by phosphate rock integration economics in Guizhou province.
- Pharmaceutical Grade:USP and EP compliance mandates fractional crystallization add-ons that lift purity benchmarks above 99.5% P2O5 consistency. European fine chemical manufacturers in the Netherlands and Belgium concentrate demand here, constrained by ECHA registration timelines and multi-jurisdiction certification overhead.
- Food Grade:FCC and GB standard alignment enables phosphate ester applications in food processing additives.
- Industrial Grade:Broad-spectrum material serving commodity esterification with lower purity tolerances.
Today's leader: Technical Grade. Tomorrow's challenger: Pharmaceutical Grade.
Application:
Cost tier stratification separates high-volume commodity processors from margin-accretive specialty chemical manufacturers.
- Chemical Synthesis:PPA replaces sulfuric acid in selective esterification for specialty surfactants and lubricant additives. German lubricant additive producers and U.S. surfactant manufacturers lead substitution adoption, attracted by cleaner reaction profiles and reduced wastewater treatment burden.
- Flame Retardants:Branched-chain phosphate esters synthesized via high-purity PPA intermediates serve polymer compounding. REACH's PBT assessment redirects formulators in Belgium and France toward compliant alternatives, expanding fastest among application channels.
- Fertilizers:Technical grade PPA functions as a phosphate source and dehydration agent in compound fertilizer manufacturing.
- Water Treatment:Scale inhibition and corrosion control applications in municipal and industrial systems.
Chemical synthesis commands premium positioning. Flame retardants gain share fastest.
End User:
Customer type concentration drives direct mill relationships over distributor networks among large-volume consumers.
- Chemical Manufacturing:Specialty surfactant and agrochemical synthesis operations demand dual-certified PPA sources spanning pharmaceutical and food-grade specifications. U.S. surfactant producers have consolidated qualified vendor lists from seven to three suppliers since 2022.
- Agriculture:Compound fertilizer and crop protection chemical formulators absorb technical grade volumes. India's CDSCO streamlined registration is attracting PPA-based phosphate ester investments for active ingredient synthesis.
- Water Utilities:Municipal treatment systems and industrial cooling water operations.
- Plastics:Polymer compounding for flame retardant synergists in construction and electronics applications.
Chemical manufacturing anchors procurement consolidation. Agriculture offers expansion headroom.
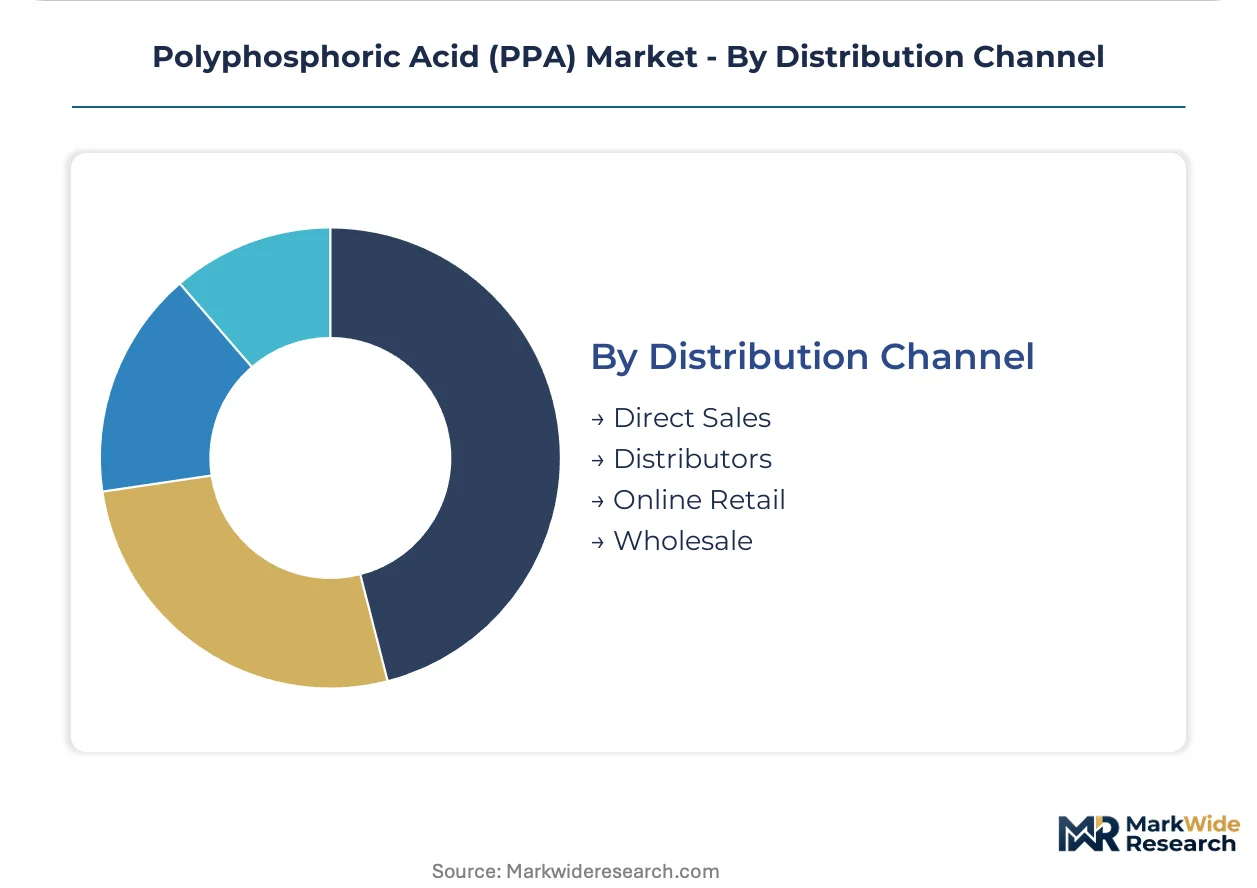
Distribution Channel:
Volume concentration among large end-users is displacing traditional distributor intermediation with direct supply relationships.
- Direct Sales:Large agrochemical and personal care manufacturers in North America bypass distributor networks for qualified mill relationships. Specification-driven supplier consolidation favors this channel for dual-certified material.
- Distributors:Mid-scale chemical manufacturers and regional formulators rely on stocked inventory and technical support.
- Wholesale:Commodity industrial grade flows through bulk handlers serving price-sensitive segments.
- Online Retail:Small-lot specialty chemical procurement for research and pilot-scale operations.
Direct sales dominate premium tiers. Distributors retain commodity intermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphorus chemists and thermal process engineers concentrate in industrial clusters tied to phosphate rock access and downstream chemical manufacturing infrastructure.
China
Domestic phosphoric acid capacity expansion in Guizhou and Yunnan provinces enables backward integration into PPA for flame retardant and fertilizer additive manufacturing. The Ministry of Ecology and Environment enforces wastewater discharge limits that push producers toward closed-loop thermal process designs. Manufacturing concentrates in Guiyang and Kunming, where captive phosphate rock supply supports integrated PPA-to-derivative production chains.
United States
Lubricant additive producers in Texas and Louisiana substitute sulfuric acid with PPA-derived phosphate esters to achieve cleaner reaction profiles and reduced wastewater treatment burden. The EPA regulates PPA under TSCA reporting requirements for phosphorus compound manufacturing. Houston and Baton Rouge host the largest concentration of specialty surfactant and agrochemical synthesis operations demanding dual-certified PPA sources.
Germany
Fine chemical manufacturers in the Rhineland and Bavaria seek pharmaceutical-grade PPA qualification amid ECHA's updated dossier requirements for phosphorus compounds. REACH compliance mandates registration and hazard communication for industrial-grade imports into the European Union. Leverkusen and Ludwigshafen represent the primary demand centers, with lubricant additive producers leading substitution adoption for specialty esterification applications.
India
Agrochemical formulators in Gujarat and Maharashtra attract PPA-based phosphate ester investments following CDSCO's streamlined active ingredient registration process. The Food Safety and Standards Authority of India's tightening food additive purity specifications creates margin pools for processors capable of meeting combined EP/FCC/GB standards. Vadodara and Mumbai anchor procurement consolidation among crop protection chemical synthesis operations.
Saudi Arabia
Compound fertilizer manufacturers in the Eastern Province absorb technical grade PPA volumes as phosphate rock processing infrastructure expands. The Saudi Food and Drug Authority and Saudi Standards, Metrology and Quality Organization enforce import specifications that favor qualified mill relationships over distributor intermediation. Jubail Industrial City hosts the largest concentration of downstream phosphate derivative manufacturing capacity in the Gulf region.
Polyphosphoric Acid (PPA) Market Competitive Landscape
Capital-heavy producers compete with asset-light formulators across distinct value chain positions in the Polyphosphoric Acid market. Integrated phosphate miners with captive rock supply command structural cost advantages in technical grade production, while specialized chemical houses concentrate margin capture in pharmaceutical and food-grade certification tiers. Three archetypes dominate: upstream-integrated miners, midstream dehydration specialists, and downstream formulation houses. Competitive moves center on reactor capacity expansion and multi-jurisdiction certification acquisition.
Among upstream-integrated miners, ICL Group Ltd, OCP Group, and Ma'aden exemplify the archetype of phosphate rock access translating into downstream PPA cost leadership. These Israel-, Morocco-, and Saudi Arabia-based entities occupy positions where captive raw material supply anchors volume competitiveness in industrial-grade segments. Solvay SA and PJSC PhosAgro represent the specialized chemical house tier, with Belgium- and Russia-based structures emphasizing certification depth over scale.
| Leading Market Players |
|---|
| ICL Group Ltd |
| EuroChem Group |
| OCP Group |
| IFFCO |
| Solvay SA |
| The Mosaic Company |
| Nutrien Ltd |
| Ma'aden |
| PJSC PhosAgro |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between pharmaceutical and technical tiers manifests in both pricing premiums and supply chain complexity. REACH dossier requirements and USP compliance timelines force European and North American buyers toward qualified mill relationships with captive phosphate rock access, while commodity industrial-grade flows concentrate through bulk handlers serving price-sensitive fertilizer additive manufacturers in China.
Pricing Analysis
Certification-bundled versus unbundled service splits dominate PPA procurement structures. Pharmaceutical-grade material commands three-tier pricing stratification across USP/EP dual-certified, single-certified, and industrial-grade tiers, with purity consistency and ECHA registration status as primary price differentiation drivers. Cost compression in technical-grade segments is intensifying because Chinese domestic phosphoric acid capacity expansion feeds oversupply into fertilizer additive channels. Agrochemical formulators exhibit highest price sensitivity, while fine chemical manufacturers in the Netherlands and Belgium absorb certification premiums for compliant catalyst sourcing.
Supply Chain Analysis
Freight cost exposure from phosphate rock mining centers in Morocco and China shapes downstream PPA economics. Production concentrates in China, Morocco, and Saudi Arabia, where captive phosphate ore supply anchors thermal dehydration operations. Supply chains draw from concentrated phosphate rock deposits, sulfuric acid inputs, and ceramic membrane reactor components. Single-source vulnerability runs through Moroccan ore supply controlled by OCP Group. Distribution runs through direct mill relationships for premium grades and bulk commodity handlers for technical-grade fertilizer applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's updated REACH dossier requirements for phosphorus compounds accelerate pharmaceutical-grade qualification demand among European fine chemical manufacturers.
For Market Incumbents: Lock in phosphate rock supply agreements in Morocco and China before capacity constraints tighten. Expand ceramic membrane reactor deployments in Guizhou province to capture 15-20% energy cost reductions that defend margin position against commodity processors. Prioritize simultaneous USP and EP certification acquisition to maintain qualified vendor status as North American surfactant producers consolidate supplier lists from seven to three sources. For New Entrants and Emerging Players: CDSCO's streamlined active ingredient registration in India opens a window for PPA-based phosphate ester investments targeting agrochemical formulation expansion in Gujarat and Maharashtra. Food-grade certification under FSSAI's tightening purity specifications represents the most penetrable white-space opportunity, with combined EP/FCC/GB standard compliance as the go-to-market angle for processors serving multinational food additive distributors. For Investors and Strategic Acquirers: Consolidation pressure builds where thermal process engineering talent scarcity concentrates among legacy phosphorus chemists approaching retirement. Mid-scale dehydration specialists with partial certification coverage present acquisition targets capable of margin expansion through pharmaceutical-grade qualification completion. Watch battery electrolyte additive convergence as the inflection signal, where lithium-ion cell manufacturers testing polyphosphate-derived flame retardant synergists would validate non-traditional demand channel viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive ore supply in Morocco and China insulates margin from input cost volatility. |
| Ceramic Membrane Reactor Deployment | Dutch and Japanese pilot programs demonstrate 15-20% energy intensity reduction for pharmaceutical-grade production. |
| Multi-Jurisdiction Certification Acquisition | Dual USP/EP qualification extends product launch cycles but secures qualified vendor status with consolidated buyers. |
| Flame Retardant Synergist Development | REACH's PBT assessment redirects Belgian and French formulators toward branched-chain phosphate ester alternatives. |
| Direct Mill Relationship Expansion | North American agrochemical and personal care manufacturers bypass distributor networks for specification-driven supply security. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at thermal dehydration facilities, procurement leads at lubricant additive manufacturers, distribution channel partners serving European water treatment formulators, and technical R&D directors at specialty surfactant producers. Secondary validation drew from customs and trade data, Cefic sector reports, SEC 10-K filings from listed phosphate compound manufacturers, and ECHA registration dossiers. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates.
Historical reference periods anchored the forecast window to established thermal process efficiency trends and regulatory implementation timelines. The analytical framework segmented across grade tier, end-use industry, regional production hub, and certification status dimensions throughout the projection horizon. CAGRs derived from segment-level growth rate convergence analysis incorporating phosphate rock price elasticity, energy cost trajectories, and substitution adoption curves for sulfuric acid replacement in esterification reactions.
Revisions become necessary when phosphate rock supply disruptions, REACH substance authorization withdrawals, or battery electrolyte additive test failures materialize. Forecasts reflect documented assumptions about regulatory timeline adherence and process technology diffusion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
United States Construction Chemicals Market
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Sodium Cyanide Market
Chemicals
Formalin Market
Chemicals
Europe Biguanide Market
Chemicals
Africa Sodium Cyanide Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Methanol to Gasoline Market
Chemicals
Wood Preservation Chemicals Market
Chemicals
South America Surface Treatment Chemicals Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Catechol Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Thiourea Market
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Global Chiral Chemicals Market