
 Global Oxo Alcohols Market | 2026-2036
Global Oxo Alcohols Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oxo Alcohols Market Analysis
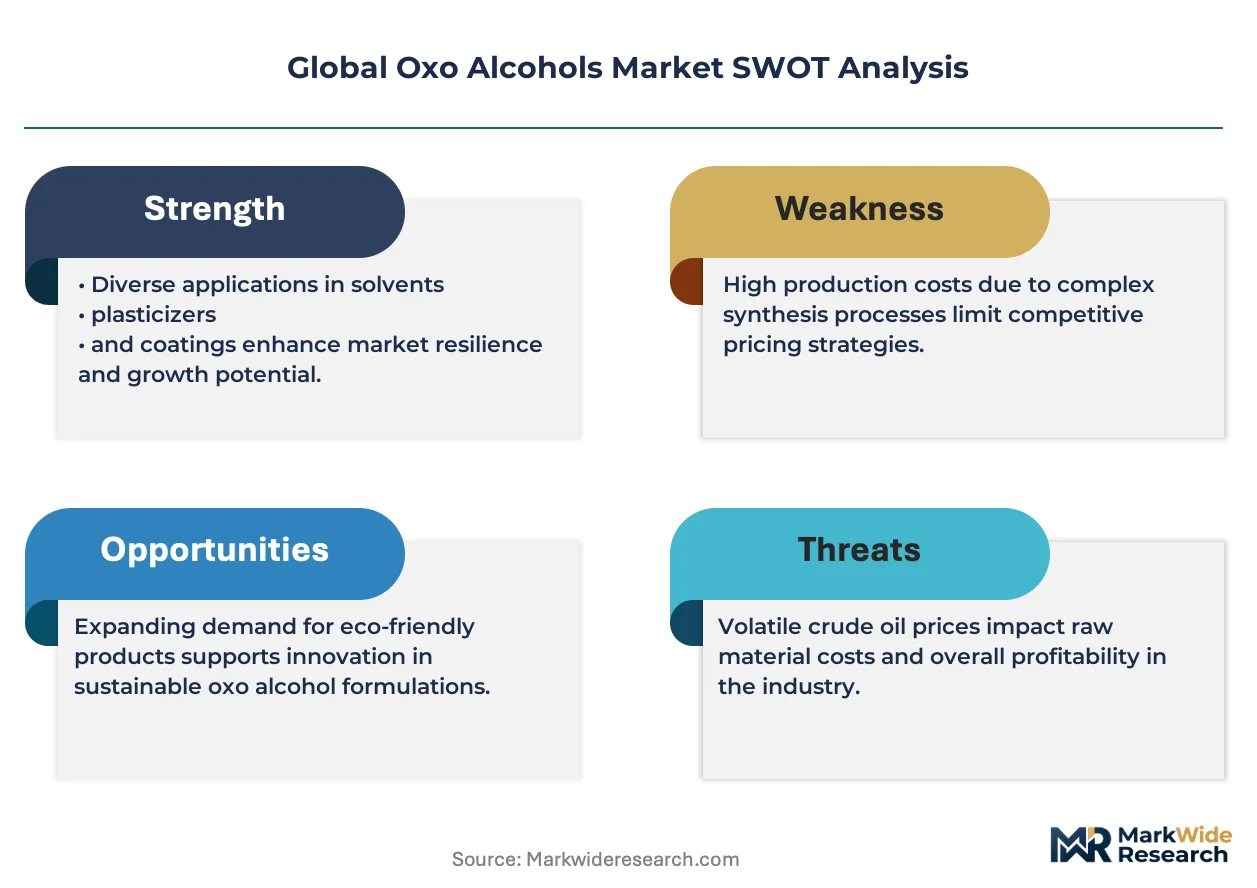
The oxo alcohols industry is restructuring around a widening gap between premium-grade specialty products and commodity butanol streams. BASF SE leverages integrated propylene-to-oxo complexes across Ludwigshafen and Antwerp to sustain margin capture in high-purity 2-ethylhexanol. Dow Chemical Company anchors North American supply through Gulf Coast hydroformylation assets, while INEOS competes on scale economics via its Seal Sands facility on Teesside.
Oxo alcohols comprise C4-C8 aldehyde-derived alcohols produced via hydroformylation of olefins with syngas, typically containing 99% purity specifications for downstream plasticizer and solvent applications. These chemicals serve primarily as intermediates for phthalate and non-phthalate plasticizers, coating solvents, and surfactant feedstocks. Plasticizers represent the dominant application segment, though surfactant-grade propanol shows faster structural growth as home care formulators shift toward biodegradable alternatives. Coatings demand tracks automotive refinish and architectural volumes, with solvent applications facing substitution pressure from waterborne technologies.
REACH in Europe and EPA regulations in the United States tighten volatile organic compound limits and restrict certain phthalate plasticizers, redirecting formulation demand toward approved oxo alcohol derivatives. China's MEE enforces stricter emissions standards at oxo plants along the Yangtze River basin, constraining regional supply elasticity. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating product portfolios toward compliant plasticizer and solvent grades.
Market Dynamics
Plasticizer-grade oxo alcohols face bifurcation pressure as REACH phthalate restrictions and China's MEE emissions standards simultaneously tighten, forcing producers to reconfigure product slates toward non-phthalate plasticizer feedstocks or specialty solvent grades.
Growth Catalysts
- Construction intensity in India:Infrastructure build-out and urban housing expansion drive plasticizer consumption for PVC piping and flooring applications. Derivative demand concentrates in Maharashtra and Gujarat chemical processing corridors.
- REACH compliance migration:European formulators replace restricted phthalate plasticizers with DINCH and DOTP alternatives manufactured from 2-ethylhexanol. ECHA substance evaluation accelerates approved feedstock qualification timelines.
- Biodegradable surfactant chemistry:Home care manufacturers substitute petroleum-based ethoxylates with oxo-derived alcohol ethoxylates. Procter & Gamble and Unilever procurement specifications now prioritize renewable carbon index thresholds.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker margins fluctuate with crude oil benchmarks, compressing oxo alcohol producer spreads. Gulf Coast propylene supply disruptions transmit rapidly to derivative pricing.
- Supply concentration in China:Yangtze River basin producers control approximately sixty percent of Asian 2-ethylhexanol capacity. MEE environmental inspections trigger unplanned outages with limited geographic diversification.
- Waterborne coating substitution:Architectural and automotive OEM formulators reduce solvent demand through high-solids and waterborne technologies. Solvent-grade butanol faces structural displacement in decorative coatings.
Strategic Opportunities
- Indonesia downstream build-out:Chandra Asri and Lotte Chemical expand olefin-to-plasticizer integration on Java. Local oxo alcohol demand will outpace domestic supply, creating import substitution openings.
- Non-phthalate mandate acceleration:EU Toy Safety Directive and US Consumer Product Safety Improvement Act tighten phthalate limits in children's products. DINP and DIDP replacement chemistry requires alternative oxo alcohol feedstocks.
- Hydroformylation catalyst advancement:Rhodium-phosphine ligand systems enable lower-pressure operation with higher n-aldehyde selectivity. Process licensors offer retrofits reducing syngas consumption and carbon intensity metrics.
Industry Challenges
- Process control engineering scarcity:Hydroformylation unit operation requires specialized expertise in syngas handling and rhodium catalyst recovery. European and North American technical workforce attrition constrains debottlenecking execution.
- Product qualification timelines:Automotive interior specifications demand eighteen-to-twenty-four-month validation cycles for new plasticizer grades. OEM approval bottlenecks delay volume ramp despite technical readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oxo Alcohols Market |
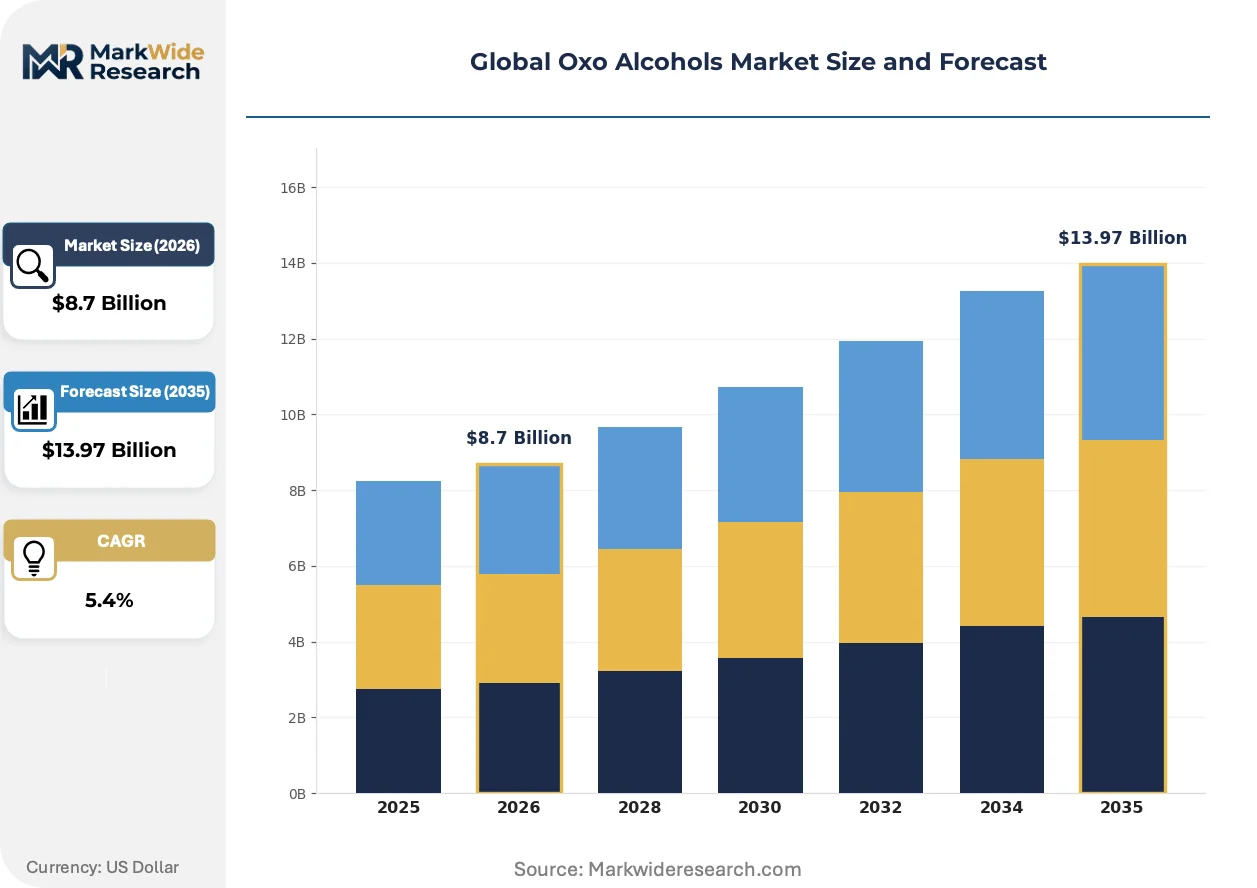
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2-Ethylhexanol, Butanol, Propanol, Isobutanol Application: Solvents, Plasticizers, Surfactants, Coatings End User: Automotive, Construction, Chemical Manufacturing, Pharmaceuticals Distribution Channel: Direct Sales, Online Sales, Wholesalers, Distributors |
| Companies Covered | Evonik Industries, ExxonMobil Chemical Company, BASF SE, Eastman Chemical Company, LG Chem, Arkema, Dow Chemical Company, INEOS, Oxea GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oxo Alcohols Market Emerging Trajectories
Process intensification and regulatory chemistry mandates are restructuring how oxo alcohols are produced, certified, and consumed across plasticizer and surfactant value chains.
Membrane-based syngas purification is modularizing hydroformylation plant configurations. BASF and Johnson Matthey collaborate on compact membrane modules that replace conventional pressure-swing adsorption units. Mid-scale producers in Poland and Thailand adopt these skidded systems to avoid large-scale cryogenic investment, compressing project timelines from thirty-six to eighteen months.
REACH authorization requirements for di-iso-nonyl phthalate and di-iso-decyl phthalate are redirecting European plasticizer demand. Compounders in Germany and Belgium reformulate with terephthalate and trimellitate esters requiring 2-ethylhexanol rather than isononanol feedstocks. This chemistry pivot elevates demand for high-purity 2-ethylhexanol while constraining isononanol offtake from C9-rich oxo streams.
Automotive OEMs now mandate full material disclosure across interior component supply chains. Tier-1 suppliers to Stellantis and BMW submit oxo alcohol-derived plasticizer certificates through IMDS and CDX platforms. This transparency requirement favors integrated producers with certified mass-balance documentation over merchant market spot suppliers.
Global Oxo Alcohols Market Segmentation
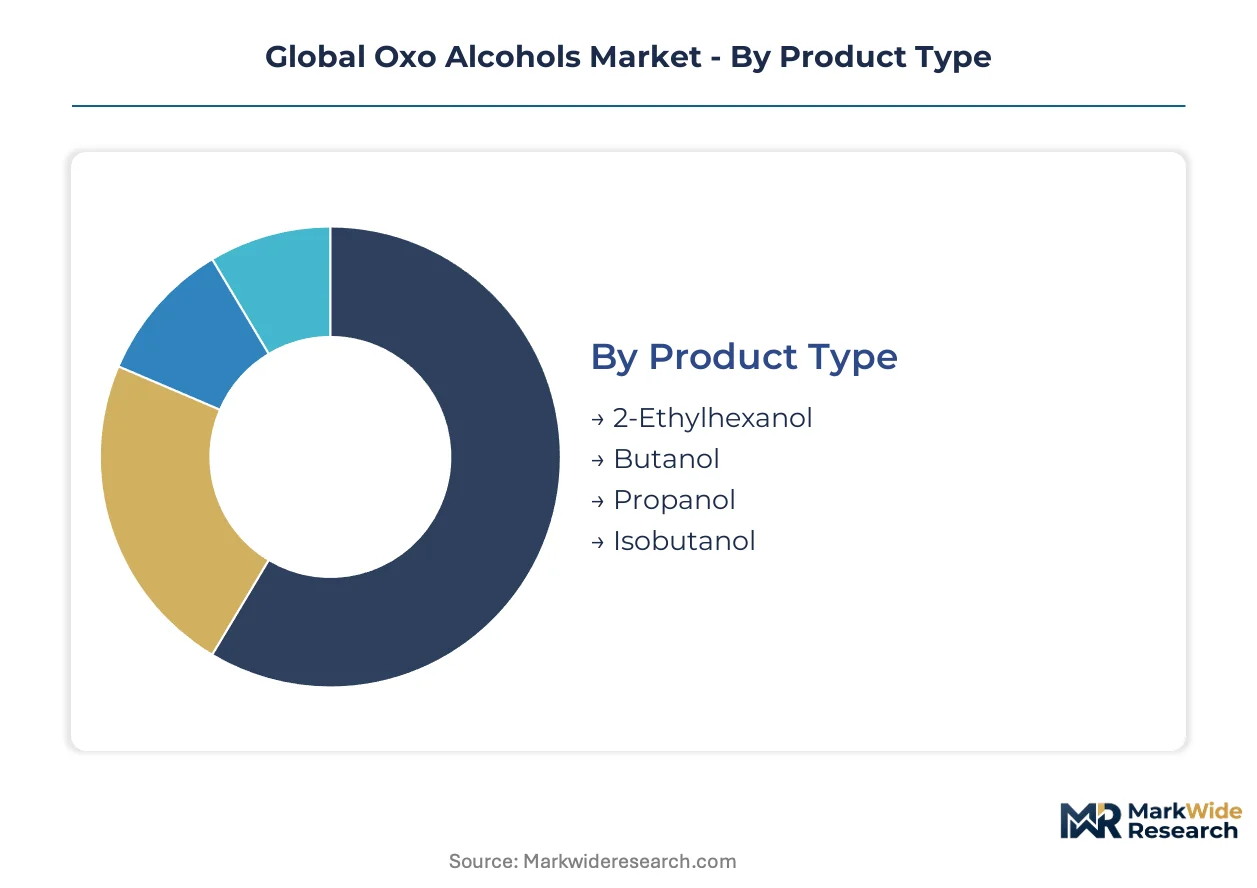
Oxo alcohol producers configure product slates around feedstock economics and regulatory chemistry mandates. Segment boundaries blur as hydroformylation units pivot between plasticizer-grade and solvent-grade output based on margin signals.
Product Type:
Purity specifications and carbon chain length determine pricing tiers and downstream qualification requirements.
- 2-Ethylhexanol:C8 branched alcohol produced from propylene hydroformylation and subsequent aldol condensation. Demand concentrates in Germany and Belgium as DINP and DOTP plasticizer compounders reformulate away from restricted phthalates under ECHA authorization timelines.
- Butanol:Straight-chain C4 alcohol serving solvent and butyl acrylate feedstock markets. Construction-grade PVC flooring manufacturers in Maharashtra and Gujarat absorb volume for adhesive and sealant formulations.
- Propanol:C3 alcohol split between n-propanol and isopropanol isomers. Home care formulators specify oxo-derived grades for biodegradable surfactant ethoxylation.
- Isobutanol:Branched C4 alcohol with lower volatility than n-butanol. Coatings solvent applications in automotive refinish track OEM waterborne transition curves.
2-Ethylhexanol leads on scale; propanol leads on momentum.
Application:
End-use chemistry requirements dictate hydroformylation product slate optimization and catalyst selection.
- Plasticizers:Phthalate and non-phthalate ester intermediates commanding highest purity specifications. REACH authorization restrictions on DINP and DIDP redirect formulation demand toward 2-ethylhexanol-based terephthalates in European compounding.
- Solvents:Butanol and isobutanol grades for coatings, inks, and extraction applications. Architectural formulators in China reduce solvent loadings through high-solids technology adoption.
- Surfactants:Alcohol ethoxylate feedstocks for home and personal care. Procter & Gamble procurement specifications now require renewable carbon index documentation.
- Coatings:Automotive OEM and refinish solvent demand. Waterborne technology penetration constrains volume growth in decorative segments.
Plasticizers dominate absolute consumption; surfactants climb the fastest.
End User:
Industry-specific material disclosure and certification requirements filter supplier selection.
- Automotive:Interior component plasticizers subject to IMDS and CDX platform documentation. Tier-1 suppliers to Stellantis and BMW mandate mass-balance certificates.
- Construction:PVC piping, flooring, and membrane applications. Infrastructure build-out in India concentrates derivative demand in western chemical processing corridors.
- Chemical Manufacturing:Butyl acrylate and other ester intermediates. Merchant market spot purchases compete with backward-integrated propylene-to-derivatives complexes.
- Pharmaceuticals:High-purity solvent grades for API synthesis and extraction. cGMP compliance requirements limit qualified supplier pools.
Construction anchors volume; automotive imposes the steepest certification barriers.
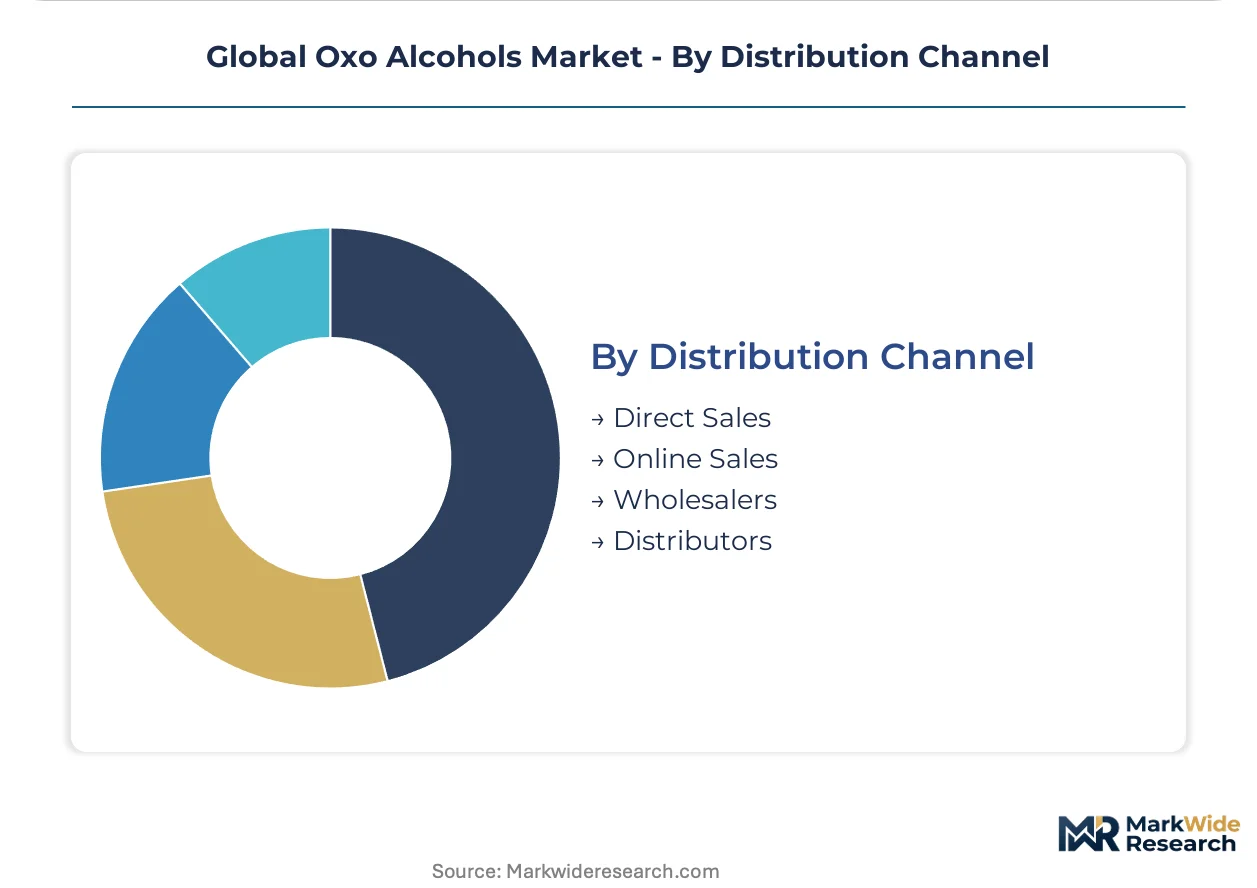
Distribution Channel:
Volume scale and geographic concentration determine channel economics and working capital intensity.
- Direct Sales:Long-term offtake agreements with integrated plasticizer and acrylate producers. BASF and Dow anchor Gulf Coast and Antwerp supply through dedicated pipeline and tankage arrangements.
- Wholesalers:Regional inventory positioning for solvent and coating grade volumes. European distributors manage REACH documentation transfer to downstream formulators.
- Distributors:Technical service and blending capabilities for specialty surfactant grades. Southeast Asian networks cover Indonesia and Vietnam import substitution demand.
- Online Sales:Spot market price discovery and small-lot procurement. Limited penetration due to bulk handling requirements and hazardous material shipping restrictions.
Direct sales capture margin; distributors extend geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands sixty percent of Asian 2-ethylhexanol capacity while Germany and Belgium concentrate European reformulation demand for REACH-compliant plasticizers, creating divergent regional supply dynamics.
China
Yangtze River basin producers face MEE emissions inspections that trigger unplanned outages with limited geographic diversification. The Ministry of Ecology and Environment enforces stricter wastewater and VOC standards at oxo plants in Jiangsu and Zhejiang provinces. Chemical processing clusters along the lower Yangtze supply domestic plasticizer compounders serving construction and automotive sectors.
Germany
Ludwigshafen and Marl host integrated propylene-to-oxo complexes serving DINCH and DOTP plasticizer reformulation. ECHA substance evaluation accelerates approved feedstock qualification timelines under REACH authorization requirements. BASF SE leverages captive hydroformylation assets to supply terephthalate ester compounders replacing restricted phthalates.
United States
Gulf Coast propylene supply disruptions transmit rapidly to derivative pricing, compressing producer spreads during naphtha-cracker margin volatility. EPA volatile organic compound limits tighten solvent-grade specifications for coatings applications. Houston and Corpus Christi anchor North American hydroformylation capacity through pipeline-connected tankage arrangements.
India
Infrastructure build-out and urban housing expansion in Maharashtra and Gujarat drive plasticizer consumption for PVC piping and flooring. BIS standards for chemical intermediates impose quality specifications on imported oxo alcohol grades. Dahej and Mundra chemical processing corridors absorb volume for adhesive and sealant formulations.
Belgium
Antwerp hosts integrated oxo alcohol production serving European non-phthalate plasticizer compounders. REACH authorization restrictions on DINP and DIDP redirect formulation demand toward 2-ethylhexanol-based alternatives. The Port of Antwerp-Bruges logistics hub enables efficient distribution to German and French downstream processors.
Global Oxo Alcohols Market Vendor Landscape
Top-tier vendors anchor integrated petrochemical complexes, while mid-scale operators compete on specialty grades and regional logistics. The market structures around three tiers: global diversified chemicals with captive olefin feedstocks, regional oxo specialists with hydroformylation licensing, and merchant distributors with blending capabilities. Strategic archetypes include backward-integrated propylene-to-derivatives producers, technology licensors with catalyst supply arrangements, and formulation-focused compounders with specification expertise. Competitive moves center on capacity debottlenecking in high-margin specialty grades and geographic expansion into Southeast Asian import substitution markets.
Within the integrated chemicals tier, BASF SE, Dow Chemical Company, and INEOS exemplify archetypes of scale-driven hydroformylation operators. BASF SE represents European complex integration with Ludwigshafen and Antwerp assets. Dow Chemical Company occupies a position in North American Gulf Coast supply chains. INEOS anchors UK-based production through Teesside manufacturing. These entities sit within a competitive set where process control expertise and catalyst recovery capabilities determine operating economics.
| Leading Market Players |
|---|
| Evonik Industries |
| ExxonMobil Chemical Company |
| BASF SE |
| Eastman Chemical Company |
| LG Chem |
| Arkema |
| Dow Chemical Company |
| INEOS |
| Oxea GmbH |
| Others |
Supply Flow & Price Mechanics
Integrated plasticizer compounders in Germany and Belgium command contract-based long-term offtake arrangements that anchor pricing power for high-purity 2-ethylhexanol grades. This buyer concentration enables producers to sustain premium realizations against volatile propylene feedstock swings while merchant spot purchasers absorb sharper price transmission.
Pricing Analysis
Contract-based long-term offtake dominates high-volume procurement, while spot market transactions serve smaller solvent-grade buyers with less predictable demand patterns. Price differentiation hinges on purity certification tiers and volume scale commitments, with REACH-compliant specialty grades commanding sustained premiums over commodity butanol streams. Pricing pressure stems from naphtha-cracker margin volatility compressing producer spreads during Gulf Coast propylene supply disruptions. Merchant spot purchasers in architectural coatings exhibit highest price sensitivity, whereas automotive Tier-1 suppliers under IMDS documentation mandates show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River basin producers controlling approximately sixty percent of Asian 2-ethylhexanol capacity. Geographic supply concentration clusters in China, Germany, and the United States, with hydroformylation feedstocks drawing from propylene, syngas, and rhodium catalyst supply chains. Supply chain risk centers on MEE environmental inspections triggering unplanned outages with limited geographic diversification. Distribution runs through pipeline-connected tankage arrangements at integrated complexes, supplemented by regional wholesalers managing REACH documentation transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Oxo Alcohols Market functions as a stable compounder underpinned by non-phthalate plasticizer reformulation mandates that sustain structural demand for compliant feedstocks.
For Market Incumbents: Hedge propylene feedstock exposure through backward integration into Gulf Coast or Antwerp olefin assets while accelerating catalyst recovery technology investments. Waterborne coating substitution threatens solvent-grade butanol offtake, demanding portfolio pivot toward surfactant-grade propanol and high-purity 2-ethylhexanol streams. For New Entrants and Emerging Players: Launch via distributor partnerships targeting Indonesia's olefin-to-plasticizer integration gap on Java, where local demand outpaces domestic supply. Specialty surfactant-grade propanol for home care formulators represents the most penetrable segment, given Procter & Gamble and Unilever procurement specifications prioritizing renewable carbon index thresholds. For Investors and Strategic Acquirers: Chemical conglomerates seeking downstream integration are the most active acquirer in this space, pursuing hydroformylation licensing specialists with catalyst supply arrangements. Mid-scale European operators with membrane-based syngas purification capabilities offer compelling five-to-ten-year viability given modular deployment advantages. Watch for MEE inspection intensity in Jiangsu province as a supply disruption signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Gulf Coast and Antwerp producers secure margin capture against naphtha-cracker volatility. |
| Membrane-Based Syngas Purification Deployment | Polish and Thai mid-scale operators compress project timelines through modular skidded systems. |
| Non-Phthalate Plasticizer Feedstock Qualification | German compounders accelerate ECHA-approved 2-ethylhexanol offtake under REACH authorization timelines. |
| Indonesia Distribution Network Expansion | Southeast Asian distributors capture import substitution demand from Chandra Asri and Lotte Chemical build-outs. |
| Rhodium-Phosphine Catalyst System Retrofit | Process licensors enable lower-pressure hydroformylation with higher n-aldehyde selectivity and reduced carbon intensity. |
Methodological Framework
Bottom-up plasticizer and surfactant demand modeling reconciled against top-down hydroformylation capacity tracking forms the analytical core. Primary interviews with plant managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors informed operational assumptions. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA substance evaluation databases. Top-down and bottom-up estimates triangulated through cross-referencing producer disclosures with derivative consumption patterns.
Input-output matrices mapped propylene feedstock availability against hydroformylation output across product grades and end-use applications over the projection horizon. Segmentation dimensions modeled include carbon chain length, purity tier, end-use industry, and regional production hub. CAGRs derived from elasticity-adjusted demand curves incorporating construction intensity indices and automotive production forecasts. Industry-specific inputs encompassed REACH authorization timelines and MEE emissions inspection frequencies.
Several conditions sit outside the modeled scope, including force majeure disruptions at Yangtze River basin facilities and abrupt shifts in crude oil benchmarks affecting naphtha-cracker economics. Forecasts reflect documented assumptions about regulatory enforcement consistency and catalyst technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Di Nitro Toluene Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Cumene Market
Chemicals
Valeryl Chloride Market
Chemicals
Aluminium Chloride Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Fluorene Market
Chemicals
Guaiacol Market
Chemicals
Thioacetic Acid Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Sodium Tripolyphosphate (STPP) Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Global P-Phenylenediamine Market