
 Desalination Chemicals Market | 2026-2036
Desalination Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Desalination Chemicals Market Outlook
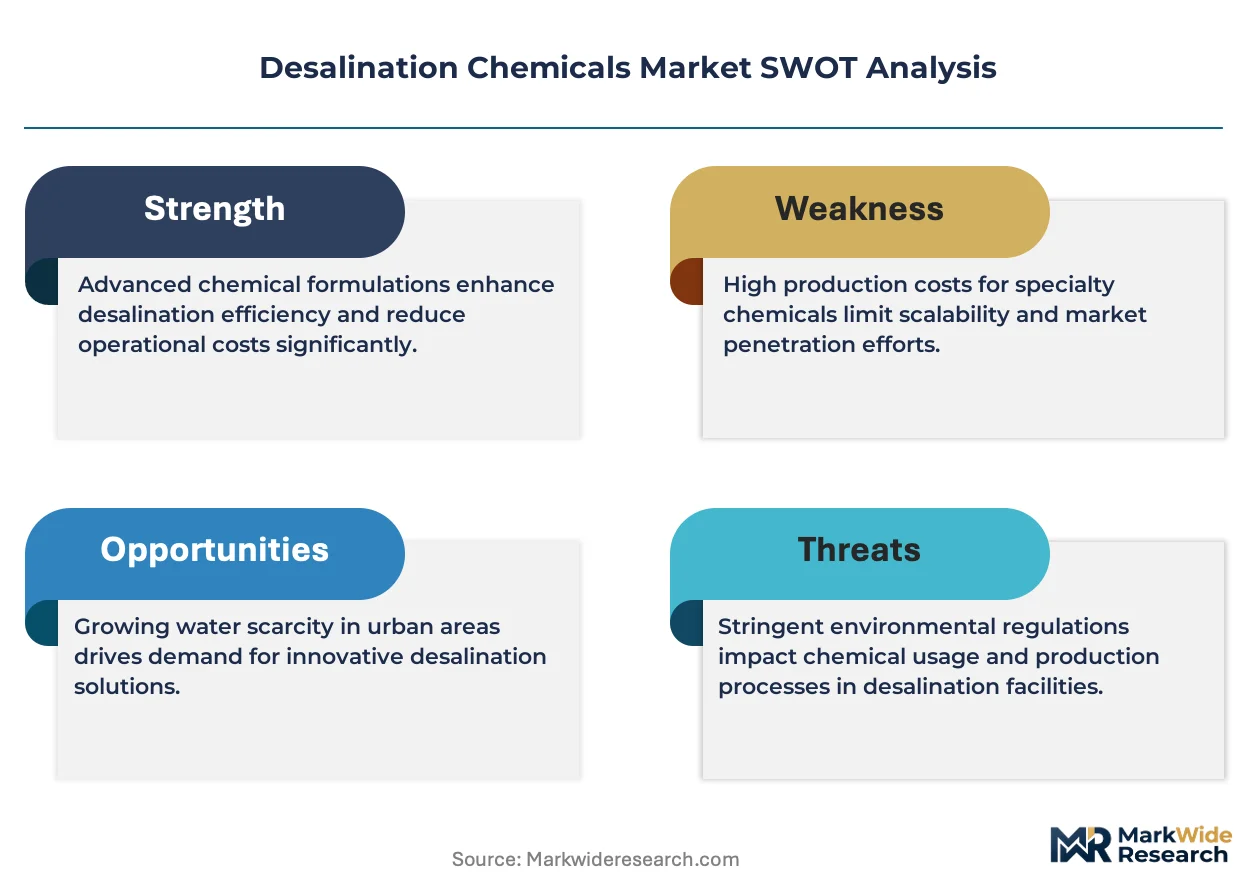
The desalination chemicals supply base is restructuring around a sharp split between premium membrane-compatible formulations and commodity pretreatment chemicals. Kemira leverages its polymer chemistry depth to dominate high-performance antiscalant tiers. Ecolab sustains integrated service models that bundle chemical dosing with remote monitoring systems. SNF Group anchors global volume through acrylamide-based coagulant scale.
Desalination chemicals comprise specialty formulations—antiscalants, biocides, coagulants, and pH adjusters—engineered to inhibit mineral scaling, control biofouling, and optimize membrane performance in reverse osmosis and thermal distillation systems. These chemicals operate within narrow pH windows and temperature thresholds to protect polyamide thin-film composite membranes from irreversible fouling. Antiscalants command disproportionate margin pools due to polymer complexity and site-specific dosing optimization. Seawater desalination applications absorb the largest chemical volumes, while brackish water treatment segments expand fastest as inland utilities confront aquifer depletion. Power generation end users represent the most technically demanding customer class, requiring halogen-tolerant formulations compatible with combined-cycle cooling circuits.
EPA regulates desalination concentrate discharge under the Clean Water Act National Pollutant Discharge Elimination System, while NSF/ANSI 60 certification governs chemical contact safety for municipal drinking water outputs. Saudi Arabia's Saline Water Conversion Corporation enforces proprietary membrane warranty standards that effectively gate market access for non-compliant chemical suppliers. Stakeholders must monitor evolving boron and bromide discharge limits as coastal jurisdictions tighten marine environmental protections.
Market Dynamics
Membrane chemistry advances are compressing dosing windows for antiscalants and biocides, forcing suppliers to reformulate around narrower pH tolerances and temperature bands that protect polyamide thin-film composites from irreversible fouling.
Growth Catalysts
- Saudi Arabia's Red Sea megaproject pipeline:Saline Water Conversion Corporation capacity expansions are absorbing record volumes of membrane-compatible antiscalants and halogen-tolerant biocides.
- EPA Clean Water Act NPDES discharge standards:Tightening concentrate disposal rules are compelling utilities to adopt higher-efficiency pretreatment chemistries that reduce brine volumes.
- Reverse osmosis modularization:Containerized SWRO units are proliferating in coastal municipalities, creating distributed demand nodes for site-optimized chemical dosing protocols.
Market Restraints
- Acrylamide monomer supply concentration:SNF Group and Kemira control upstream polymer feedstock, exposing downstream formulators to input cost volatility and allocation risk.
- NSF/ANSI 60 certification timelines:Municipal drinking water approvals stretch 18-24 months, gating market entry for novel antiscalant polymers.
- Thermal distillation substitution threat:Multi-effect distillation plants in the Gulf Cooperation Council are ceding share to membrane systems, eroding legacy biocide and antifoam demand pools.
Strategic Opportunities
- Brackish water inland utilities:Aquifer depletion in Arizona and Texas is driving RO adoption for agricultural and municipal groundwater treatment, opening new chemical service territories.
- EU Green Deal industrial water reuse mandates:REACH-aligned formulations for zero-liquid-discharge circuits are creating premium product tiers in European process industries.
- Remote dosing system integration:IoT-enabled chemical monitoring is converging with predictive analytics, enabling subscription-based service models that displace transactional chemical sales.
Industry Challenges
- Membrane warranty compliance:Saline Water Conversion Corporation and IDE Technologies enforce proprietary chemical compatibility standards that fragment formulation requirements across customer sites.
- Specialized polymer synthesis talent:Phosphonate and polycarboxylate antiscalant development requires rare expertise in scale inhibition kinetics, constraining R&D throughput at mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desalination Chemicals Market |
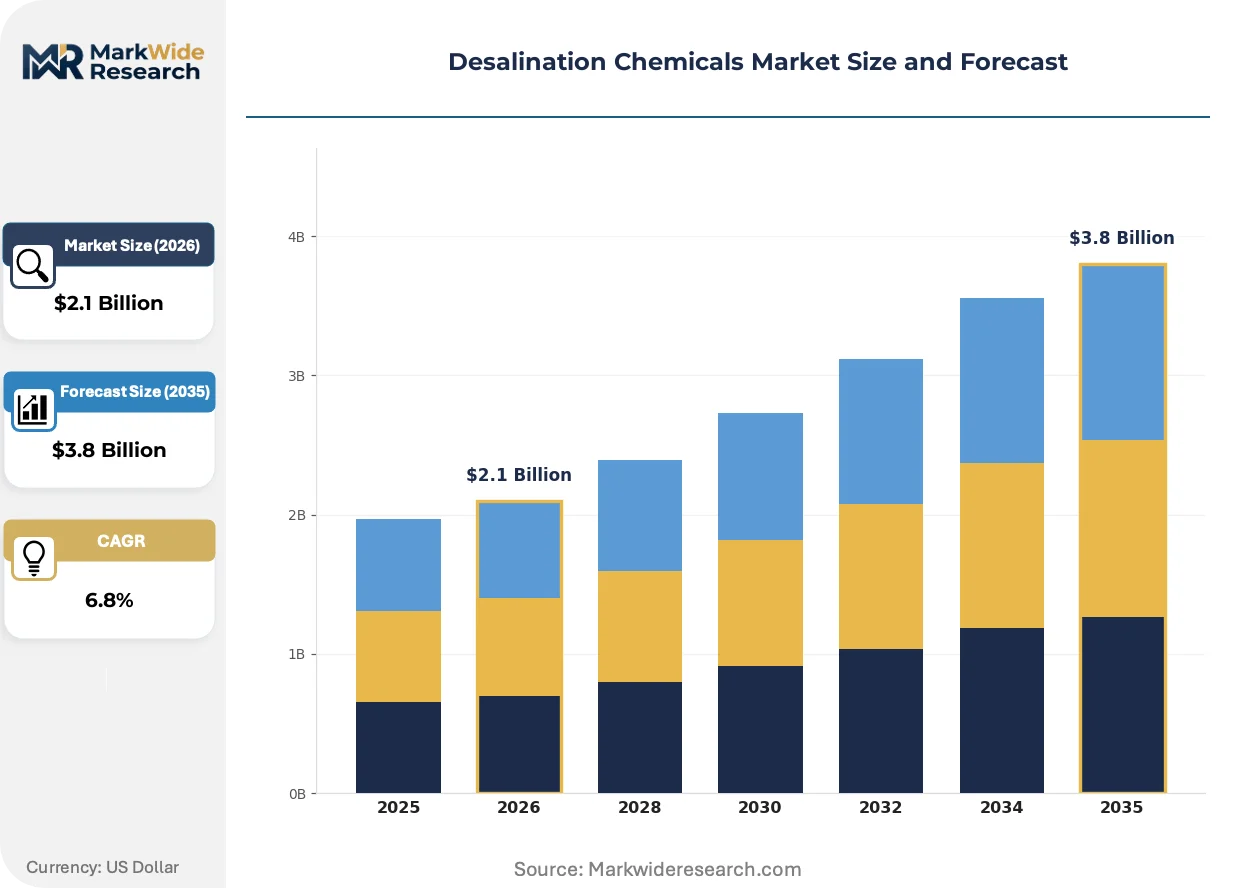
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulants, Antiscalants, pH Adjusters, Biocides Application: Seawater Desalination, Brackish Water Treatment, Industrial Water Supply, Municipal Water Supply End User: Power Generation, Agricultural, Oil & Gas, Municipalities Distribution Channel: Direct Sales, Distributors, Online Sales, Retailers |
| Companies Covered | Italmatch Water Solutions, Kemira, Ecolab, BASF, SNF Group, Veolia Water Technologies & Solutions, Solenis, American Water Chemicals, Kurita Water Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desalination Chemicals Market Strategic Shifts
Formulation science is pivoting from commodity pretreatment chemicals toward precision-engineered membrane protectants, while digital dosing infrastructure and regulatory chemistry are rewriting procurement and compliance architectures.
Phosphonate-polymer hybrid antiscalants are modularizing around site-specific water chemistries, combining threshold inhibition with crystal dispersion in single-dose formulations. Power generation utilities with combined-cycle cooling circuits are adopting these blends fastest, compressing supplier margins on standalone phosphonate products while expanding service attach rates for integrated dosing optimization.
REACH restrictions on boron and bromide discharge are forcing Mediterranean coastal plants to abandon legacy halogenated biocides for non-oxidizing alternatives. ECHA's evolving substance evaluation roadmap is accelerating substitution in Spanish and Italian desalination facilities, with membrane manufacturers tightening warranty terms for plants using non-compliant chemistries.
Buyers are consolidating chemical procurement under integrated service contracts that bundle formulation supply with membrane performance guarantees. Saudi Arabia's independent water and power projects are leading this shift, displacing transactional chemical vendors with operators that accept fouling risk in exchange for long-term dosing agreements.
Desalination Chemicals Market Segmentation
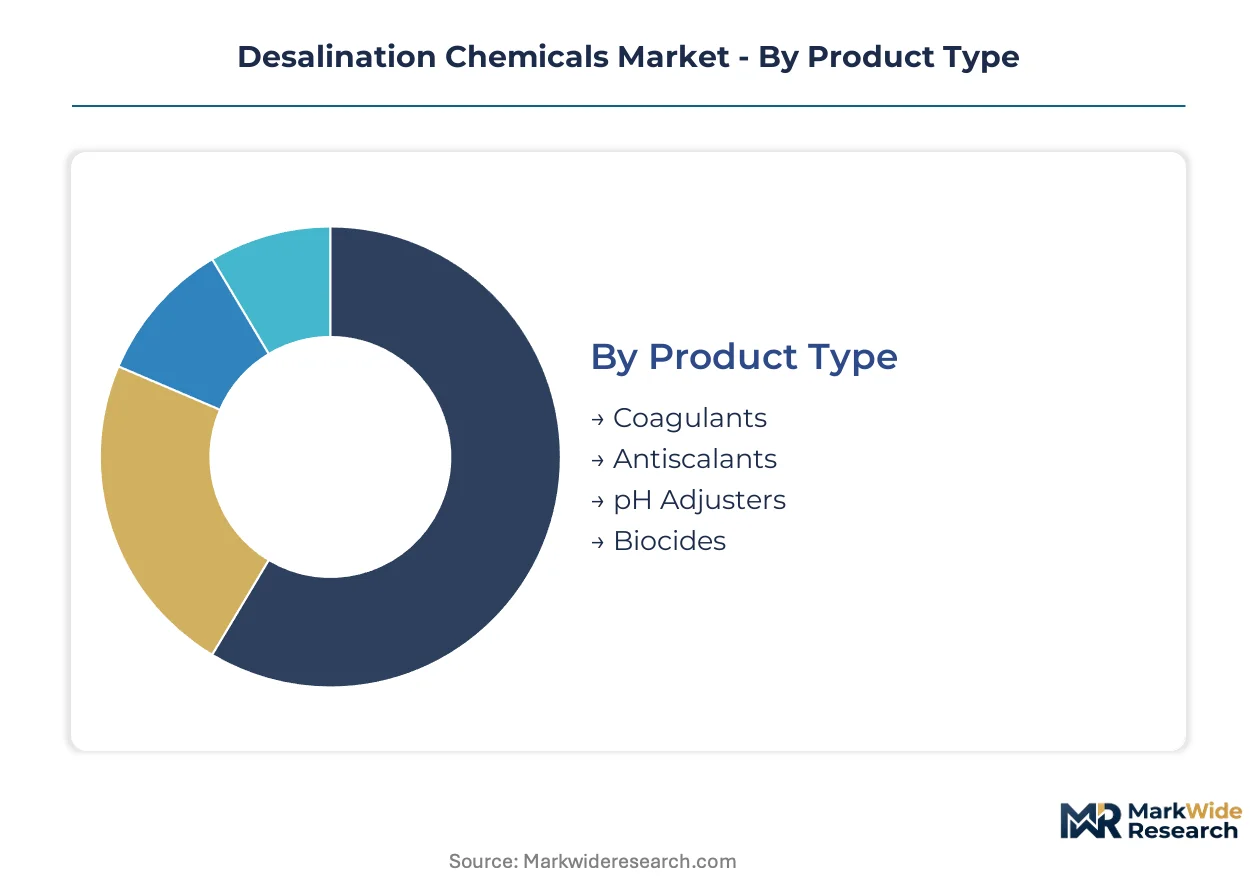
Desalination chemicals fragment across four intersecting dimensions that govern procurement economics. Product chemistry determines membrane compatibility thresholds. Application salinity dictates dosing intensity and formulation sophistication. End-user technical requirements shape service attachment rates. Distribution channel selection reflects geographic density of installed capacity.
Product Type:
Customization intensity varies sharply across this category, with polymer complexity driving tiered service models alongside commodity pretreatment chemicals.
- Antiscalants:Phosphonate and polycarboxylate polymers inhibit mineral precipitation on polyamide membranes through threshold inhibition and crystal dispersion. Power generation utilities in Saudi Arabia absorb the most technically demanding formulations, where Saline Water Conversion Corporation warranty standards enforce proprietary compatibility testing.
- Coagulants:Acrylamide-based flocculants remove suspended solids and organic matter ahead of membrane arrays. Municipalities across Arizona and Texas deploy these most heavily as brackish groundwater RO adoption accelerates.
- pH Adjusters:Sulfuric acid and caustic soda solutions maintain narrow pH windows that protect thin-film composite integrity. Coastal plants in Spain and Italy face REACH-driven reformulation pressure as boron discharge limits tighten.
- Biocides:Halogenated and non-oxidizing formulations control biofouling in intake structures and membrane channels. Mediterranean facilities are substituting legacy chemistries fastest under ECHA substance evaluation protocols.
Most installed capacity flows through antiscalant dosing systems. Expansion is steepest in biocide substitution for REACH-compliant alternatives.
Application:
Volume concentration tracks water stress severity, with coastal salinity gradients determining chemical intensity per cubic meter treated.
- Seawater Desalination:Reverse osmosis and thermal distillation plants on the Red Sea coast consume the largest absolute chemical volumes. Saudi Arabia's independent water and power projects bundle antiscalant supply under long-term performance contracts.
- Brackish Water Treatment:Inland RO systems for depleted aquifers require less intensive pretreatment but faster-growing chemical service territories. Agricultural irrigation districts in Texas and Arizona are expanding capacity fastest.
- Industrial Water Supply:Process industry zero-liquid-discharge circuits demand REACH-aligned formulations under EU Green Deal mandates.
- Municipal Water Supply:Coastal utilities face EPA NPDES discharge standards that concentrate pretreatment chemical procurement under integrated service models.
Seawater applications dominate current chemical throughput. Brackish water segments are climbing the fastest as inland aquifer depletion spreads.
End User:
Technical sophistication tiers separate warranty-critical membrane operators from price-sensitive agricultural buyers.
- Power Generation:Combined-cycle cooling circuits require halogen-tolerant formulations compatible with thermal stress cycling. Independent water and power producers in Saudi Arabia impose the most stringent chemical compatibility standards.
- Municipalities:NSF/ANSI 60 certification requirements stretch 18-24 months, gating novel polymer entry and consolidating supply relationships.
- Oil & Gas:Produced water treatment for enhanced oil recovery applies desalination chemistries in high-salinity extraction environments.
- Agricultural:Irrigation districts prioritize cost efficiency over performance guarantees, favoring commodity coagulant procurement.
Power generation commands the highest service attach rates. Municipal procurement is gaining share fastest as coastal utilities consolidate under performance-based contracts.
Distribution Channel:
Channel selection reflects customer density and technical service requirements across fragmented geographic markets.
- Direct Sales:Integrated chemical service contracts bundle formulation supply with remote monitoring and membrane performance guarantees. Saudi Arabia's megaproject pipeline anchors this channel.
- Distributors:Regional chemical distributors serve mid-scale municipal and agricultural accounts with standardized pretreatment chemistries.
- Online Sales:Containerized SWRO units create distributed demand nodes suitable for catalog-based procurement of pH adjusters and commodity biocides.
- Retailers:Limited to small-scale agricultural and residential RO maintenance applications.
Direct sales capture the largest contract value. Distributor channels are expanding most quickly as brackish water adoption spreads to inland territories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia absorbs larger chemical volumes than any other single market, while the United States builds membrane capacity faster across its drought-stricken Southwest. Geographic demand splits between Gulf megaprojects and inland brackish water utilities confronting aquifer depletion.
Saudi Arabia
Saline Water Conversion Corporation expansions along the Red Sea coast drive record antiscalant consumption. SFDA enforces proprietary membrane warranty standards that gate market access for non-compliant chemical suppliers. The Jubail industrial cluster hosts independent water and power projects bundling long-term chemical service contracts.
United States
Municipalities across Arizona and Texas deploy brackish water RO systems as Colorado River allocations contract. EPA NPDES discharge standards under the Clean Water Act tighten concentrate disposal rules for coastal plants. California's Central Valley agricultural districts represent the fastest-growing inland chemical service territory.
Spain
Mediterranean coastal desalination plants face accelerated biocide substitution under REACH restrictions on boron and bromide discharge. ECHA substance evaluation protocols pressure facilities toward non-oxidizing alternatives. The Murcia and Almería regions concentrate capacity serving intensive agricultural irrigation districts.
China
Coastal industrial zones in Shandong and Zhejiang provinces expand membrane capacity for process water supply. MEE discharge standards tighten marine environmental protections for concentrate disposal. The Yangtze River Delta hosts zero-liquid-discharge circuit installations driving REACH-aligned formulation demand.
Australia
Perth and Adelaide utilities sustain large-scale seawater desalination operations as reservoir levels fluctuate. The country's national environmental regulator enforces marine discharge limits that concentrate pretreatment chemical procurement. Queensland's Gold Coast desalination plant anchors membrane-compatible formulation demand on the eastern seaboard.
Desalination Chemicals Market Competitive Environment
Top-tier vendors anchor integrated service contracts, while mid-tier formulators compete on commodity pretreatment chemicals. The supply base structures around polymer chemistry depth versus geographic scale. Three archetypes dominate: polymer specialists with antiscalant expertise, diversified water treatment platforms, and regional distributors serving inland brackish water utilities. Competitive moves concentrate on backward integration into acrylamide feedstock and IoT-enabled dosing system deployment.
Within the polymer specialist tier, Kemira and SNF Group exemplify divergent scale strategies. Kemira leverages Nordic polymer chemistry depth to dominate high-performance antiscalant tiers requiring site-specific dosing optimization. SNF Group anchors global volume through acrylamide-based coagulant scale, exposing downstream formulators to input cost concentration risk. Ecolab represents the diversified platform archetype, sustaining bundled chemical dosing with remote monitoring systems across municipal and industrial accounts.
| Leading Market Players |
|---|
| Italmatch Water Solutions |
| Kemira |
| Ecolab |
| BASF |
| SNF Group |
| Veolia Water Technologies & Solutions |
| Solenis |
| American Water Chemicals |
| Kurita Water Industries |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap polymer specialists in France and Germany anchor premium antiscalant supply, their multi-generational ownership structures enabling patient capital allocation toward proprietary phosphonate synthesis while resisting quarterly pricing pressure from commodity coagulant traders.
Pricing Analysis
Bundled chemical service contracts with membrane performance guarantees command 40-60% price premiums over unbundled transactional sales of standalone biocides and pH adjusters. Price differentiation rests on NSF/ANSI 60 certification tier and Saline Water Conversion Corporation warranty compliance, with Saudi independent water and power projects absorbing the least price-sensitive demand. Cost compression in commodity coagulant tiers is intensifying because SNF Group and Kemira control upstream acrylamide feedstock. Agricultural irrigation districts in Texas and Arizona represent the most price-sensitive buyer class, prioritizing per-unit chemical cost over dosing optimization services.
Supply Chain Analysis
Reverse logistics for spent membrane cartridges and expired chemical totes remain underdeveloped across the desalination chemicals value chain, with most coastal plants landfilling polyamide elements rather than recovering rare earth catalysts embedded in antiscalant polymers. Manufacturing concentrates in France, Germany, and the United States for phosphonate and polycarboxylate polymer synthesis. Raw material flows draw from Saudi petrochemical feedstock, Louisiana chlorine derivatives, and Chinese sulfuric acid. Single-source vulnerability concentrates in acrylamide monomer supply. Distribution runs through direct technical service teams for megaproject accounts and regional chemical distributors for inland brackish water utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA NPDES discharge standard tightening and REACH biocide substitution mandates mechanically expand addressable demand for compliant formulation suppliers.
For Market Incumbents: To counter thermal distillation substitution eroding legacy biocide demand pools in Gulf Cooperation Council markets, Kemira and Ecolab should deepen backward integration into phosphonate intermediate production and deploy IoT-enabled dosing systems that lock in long-term service contracts with membrane performance guarantees. Certification investment in Saline Water Conversion Corporation warranty compliance represents the critical defensive moat against Asian polymer challengers. For New Entrants and Emerging Players: REACH restrictions on boron and bromide discharge in Spain and Italy open a window for non-oxidizing biocide specialists to capture Mediterranean coastal plant substitution demand. Target Arizona and Texas brackish water agricultural districts with commodity coagulant offerings priced below SNF Group's delivered cost. A site-optimized dosing protocol service model, bundled with containerized SWRO unit chemical supply, offers the most penetrable go-to-market angle against entrenched integrated service incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier polymer formulators lacking proprietary antiscalant synthesis capability but holding established distributor relationships across inland U.S. brackish water territories. Long-term viability favors suppliers with demonstrated NSF/ANSI 60 certification throughput and Saline Water Conversion Corporation warranty acceptance. Monitor ECHA substance evaluation protocol expansion timelines as the inflection signal for accelerated biocide substitution demand in European coastal markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphonate Intermediates | Kemira's captive supply of phosphonate monomers insulates margin compression from Chinese feedstock volatility. |
| IoT-Enabled Dosing System Deployment | Ecolab's remote monitoring convergence with predictive analytics locks Saudi independent water and power projects into subscription revenue. |
| REACH-Aligned Biocide Reformulation | Non-oxidizing biocide certification under ECHA protocols opens Spanish and Italian coastal plant procurement to compliant suppliers. |
| Brackish Water Geographic Expansion | Texas and Arizona agricultural district penetration creates chemical service territories beyond Saudi megaproject concentration. |
| Long-Term Performance Contract Structuring | Saline Water Conversion Corporation warranty bundling displaces transactional vendors with fouling-risk transfer models. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with desalination plant operators, chemical procurement managers at municipal utilities, polymer R&D directors, and membrane OEM technical service leads with secondary validation through EPA NPDES permit databases, ECHA substance evaluation registries, SEC 10-K filings from listed water treatment suppliers, and customs trade data on acrylamide monomer flows. Bottom-up chemical volume estimates by plant capacity and dosing intensity triangulated against top-down market value reconstructions.
Historical reference periods anchored the forecast window to documented membrane installation cycles and regulatory implementation timelines across the projection horizon. The analytical framework modeled segmentation dimensions spanning product chemistry tier, application salinity gradient, end-user technical sophistication, and regional regulatory cluster. CAGRs derived from installed capacity buildout trajectories and intensity-per-cubic-meter dosing trends. Industry-specific forecast inputs included Saline Water Conversion Corporation megaproject pipeline announcements and EPA NPDES discharge standard revision schedules.
Revisions become necessary when boron discharge limit tightening accelerates beyond current ECHA timelines or when acrylamide feedstock supply disruptions exceed historical allocation volatility patterns. Forecasts reflect assumptions about membrane chemistry stability and polymer synthesis talent availability. Practitioners should monitor Saline Water Conversion Corporation warranty standard evolution and REACH substance evaluation protocol expansion for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Potassium Permanganate Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Trifluoroacetic Acid (TFA) Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Egypt Construction Chemicals Market
Chemicals
Fluorene Market
Chemicals
Acetic Ether Market
Chemicals
Cetostearyl Alcohol Market
Chemicals
Metal Finishing Chemicals Market
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
Resorcinol Market
Chemicals
Nonanoic Acid Market
Chemicals
Heptaldehyde Market
Chemicals
Xanthates Market
Chemicals
Stimulation Materials Market