
 Global Aluminum Chloro Hydrate (ACH) Market | 2026-2036
Global Aluminum Chloro Hydrate (ACH) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Chloro Hydrate (ACH) Market Foresight
Iron-based coagulants is realigning competitive economics in the aluminum chloro hydrate sector as utilities reassess total cost of treatment. Kemira leverages its integrated alumina supply chain to maintain feedstock stability across Nordic and North American plants. USALCO anchors its position through deep relationships with municipal procurement offices in the Great Lakes region. Holland Company specializes in high-purity cosmetic grades that command premium positioning among personal care formulators.
Aluminum chloro hydrate is a polymeric aluminum compound with the general formula AlnCl(3n-m)(OH)m, typically supplied as a solution with basicity between 40-83% and aluminum content of 23-24% by weight, functioning primarily as a coagulating agent that neutralizes suspended particle charges in water and as an antiperspirant active that forms occlusive gel plugs within eccrine ducts. The solution product type dominates volume flows into municipal water treatment due to ease of bulk handling and dosing automation, while powder and flake formats retain stronger margins in pharmaceutical and cosmetic applications where transport cost sensitivity is lower and cGMP documentation requirements are stricter. Water treatment as an application category absorbs the majority of ACH tonnage globally, though cosmetics and pharmaceuticals represent the densest margin pools per kilogram sold.
EPA drinking water standards under the Safe Drinking Water Act and REACH registration requirements under ECHA jurisdiction both impose escalating purity and documentation burdens on ACH suppliers seeking access to regulated end markets. FDA oversight of over-the-counter antiperspirant monographs further constrains the cosmetic-grade segment through specific active concentration limits and efficacy testing protocols. Stakeholders must monitor how tightening effluent standards in industrial wastewater sectors redirect demand toward higher-basicity ACH variants that generate less chloride residual in treated discharge streams.
Market Dynamics
REACH compliance in Europe is tightening purity thresholds for cosmetic-grade ACH, forcing suppliers to redirect formulation R&D toward low-iron variants and recalibrate production economics across multiple grades simultaneously.
Growth Catalysts
- Urban water infrastructure mandates:Municipal procurement offices across Southeast Asian cities are expanding coagulant volumes as urbanization intensifies and centralized treatment expands.
- EPA Safe Drinking Water Act enforcement:Escalating documentation burdens for suppliers accessing regulated US municipal markets are consolidating demand toward certified producers with established compliance infrastructure.
- Textile processing cluster concentration:Dye-fixing applications in Zhejiang Province are absorbing rising ACH volumes as regional fabric finishing capacity scales.
Market Restraints
- Alumina feedstock volatility:Bauxite refining economics and energy costs at smelter complexes create margin compression for non-integrated ACH producers.
- Iron-based coagulant substitution:Ferric chloride and ferric sulfate are capturing select municipal tenders where total treatment cost calculations favor iron chemistry.
- Chloride residual regulations:Tightening effluent standards in industrial wastewater sectors limit deployment of standard-basicity ACH variants in certain discharge-sensitive applications.
Strategic Opportunities
- Pharmaceutical-grade expansion:cGMP-compliant powder and flake formats command premium positioning where transport cost sensitivity is lower and documentation requirements are stricter.
- High-basicity variant development:Formulations generating reduced chloride residual in treated streams align with tightening industrial discharge standards in Germany and the Netherlands.
- Cosmetic active concentration optimization:FDA OTC antiperspirant monograph compliance creates formulation services revenue for suppliers with validated efficacy testing protocols.
Industry Challenges
- Multi-jurisdiction registration complexity:Simultaneous ECHA REACH, EPA drinking water, and FDA cosmetic compliance requires dedicated regulatory affairs capacity that strains mid-tier producers.
- Basicity customization at scale:Producing 40-83% basicity ranges with consistent aluminum content demands precise process control that complicates batch scheduling and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Chloro Hydrate (ACH) Market |
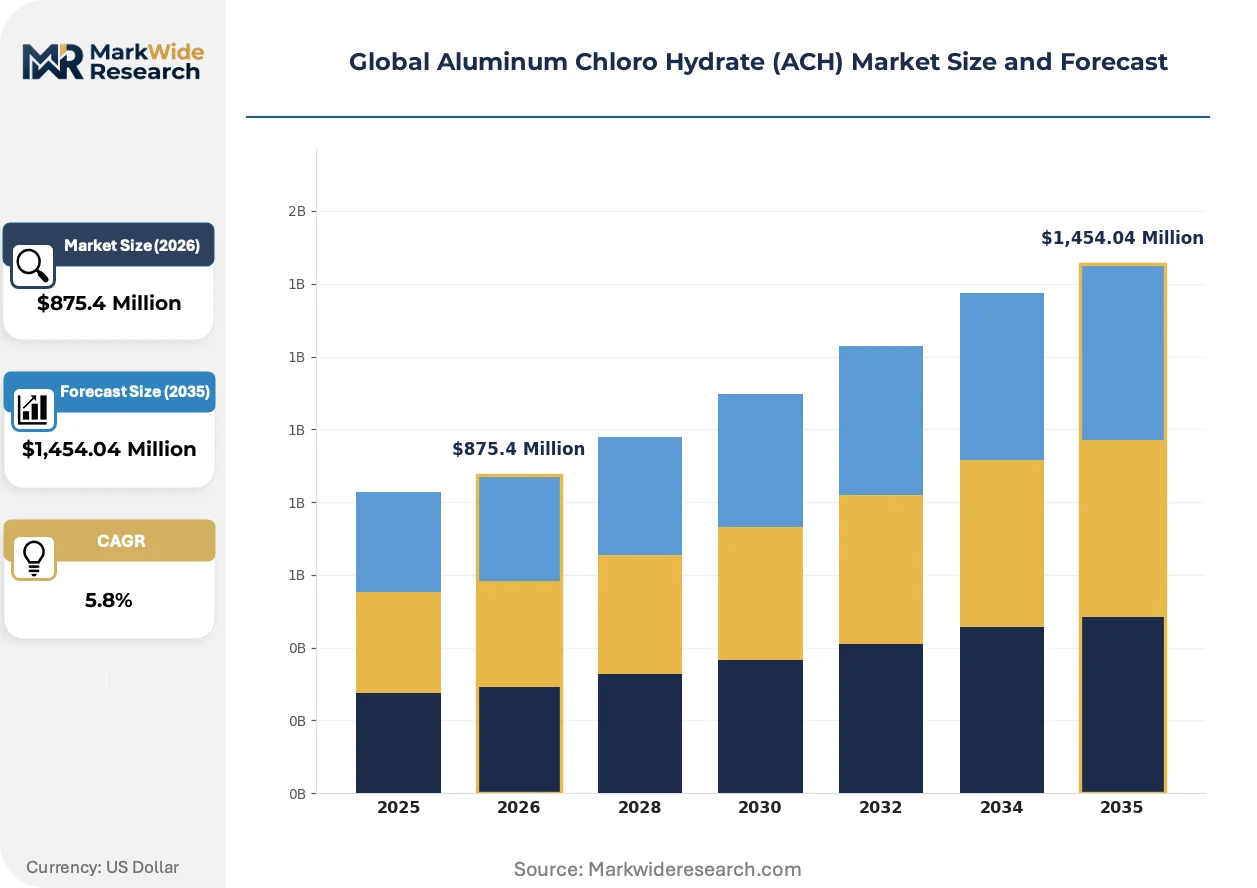
| Market Size in 2026 | $875.4 Million |
| Market Size in 2035 | $1,454.04 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Flakes, Granules, Solution Application: Water Treatment, Cosmetics, Pharmaceuticals, Textile Processing End User Industry: Municipal Facilities, Personal Care Brands, Drug Manufacturers, Fabric Mills Packaging Type: Drums, Bags, Bulk Containers, Bottles |
| Companies Covered | Kemira, USALCO, Chemtrade Logistics Inc., Holland Company, Summit Chemical, GEO, BASF, Omega Chemicals, Gulbrandsen Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Chloro Hydrate (ACH) Market Shifts & Advancements
Formulation science and regulatory convergence are compressing product lifecycles across the ACH value chain, with purity specifications and basicity customization now serving as primary differentiation vectors rather than commodity volume metrics.
Continuous coagulant dosing systems with automated basicity adjustment are unifying municipal water treatment operations previously segmented between manual batch preparation and fixed-concentration supply contracts. Utilities in the Great Lakes region are adopting these integrated platforms to reduce operator intervention and stabilize effluent quality. This convergence is compressing the supplier base toward vendors capable of delivering calibrated solution concentrations with real-time telemetry.
ECHA REACH registration requirements are tightening substance documentation and purity verification protocols for ACH entering European cosmetic and pharmaceutical channels. Formulators must now maintain detailed supply chain records and batch-specific analytical certificates that exceed prior self-certification norms. Cosmetic-grade producers are responding by segregating production lines and implementing dedicated quality management systems for regulated markets.
Buyer concentration among municipal procurement offices is consolidating annual contract structures away from spot purchasing toward multi-year framework agreements with performance guarantees. This shift compresses supplier margins while extending payment cycles and technical service obligations. The pattern is most visible in Nordic markets where Kemira's integrated alumina supply chain anchors long-term relationships with regional water authorities.
Global Aluminum Chloro Hydrate (ACH) Market Segmentation
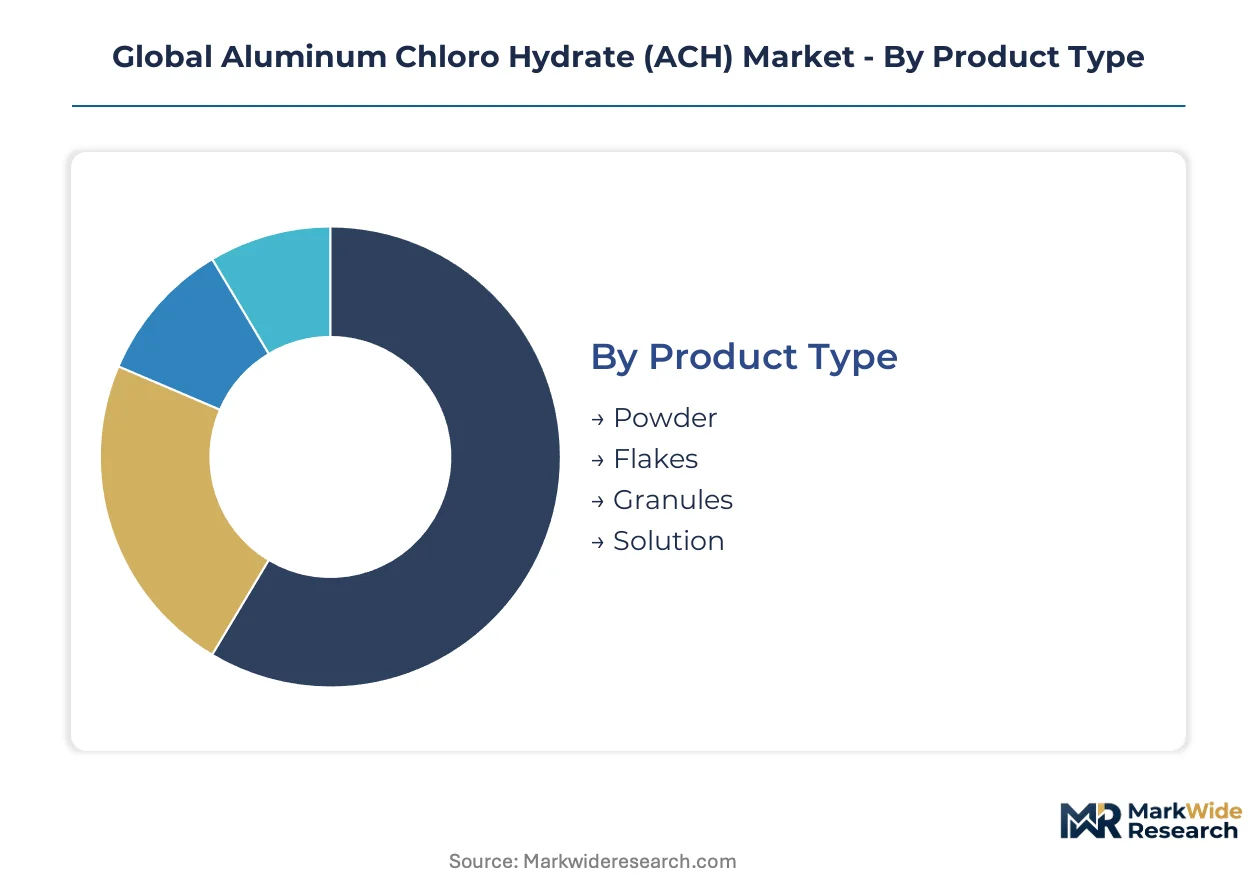
ACH segmentation reflects divergent purity requirements and handling economics across regulated end markets. Water treatment utilities prioritize bulk solution logistics, while pharmaceutical and cosmetic channels demand documented cGMP compliance with specialized packaging formats.
Product Type:
Upgrade cycles in municipal infrastructure favor solution formats with automated dosing compatibility, while batch pharmaceutical manufacturing sustains demand for solid-phase variants with extended stability profiles.
- Solution:Liquid formulations with 23-24% aluminum content and 40-83% basicity range dominate municipal procurement due to compatibility with continuous dosing systems and reduced operator handling. Southeast Asian urban water authorities in Thailand, Vietnam, and Indonesia are expanding solution contracts as centralized treatment infrastructure scales.
- Powder:Fine particulate grades with controlled particle size distribution serve pharmaceutical tablet manufacturing and cosmetic active formulation where precise mass dosing and extended shelf stability are critical. FDA OTC antiperspirant monograph compliance drives specification tightening among US personal care formulators.
- Flakes:Intermediate solid format balances dissolution kinetics with transport density for regional textile processing clusters.
- Granules:Coarse particulate grades optimize dust-free handling in automated bulk transfer systems at industrial water treatment facilities.
Volume placements concentrate in Solution; the faster expansion belongs to Powder as pharmaceutical-grade documentation requirements intensify.
Application:
Cost tier differentiation separates commodity water treatment volumes from premium cosmetic and pharmaceutical channels where certification expenses constitute a larger share of delivered cost.
- Water Treatment:Coagulation and flocculation of suspended solids in municipal and industrial effluent streams constitutes the dominant tonnage channel. EPA Safe Drinking Water Act enforcement in the United States and parallel national standards in Germany and Japan are consolidating procurement toward certified suppliers with established compliance infrastructure.
- Cosmetics:Antiperspirant active ingredient functioning through eccrine duct occlusion commands the densest margin pool per kilogram. ECHA REACH registration requirements are tightening purity verification protocols and forcing segregation of production lines for regulated European markets.
- Pharmaceuticals:cGMP-compliant grades for topical and oral formulations require batch-specific analytical certificates exceeding prior self-certification norms.
- Textile Processing:Dye-fixing applications in Zhejiang Province and comparable regional clusters absorb rising volumes as fabric finishing capacity scales.
Water Treatment absorbs the largest absolute tonnage; Cosmetics exhibits the steepest margin expansion trajectory.
End User Industry:
Customer type fragmentation creates divergent service requirements, with municipal procurement offices demanding multi-year framework agreements and pharmaceutical buyers requiring technical documentation packages.
- Municipal Facilities:City and regional water authorities in the Great Lakes region, Nordic countries, and Southeast Asian metropolitan areas procure through annual or multi-year contracts with performance guarantees. Buyer concentration is compressing margins while extending payment cycles and technical service obligations.
- Personal Care Brands:Formulators of antiperspirant and deodorant products require validated efficacy testing protocols and supply chain documentation for FDA OTC monograph compliance.
- Drug Manufacturers:cGMP-compliant production with dedicated quality management systems supports oral and topical pharmaceutical applications.
- Fabric Mills:Regional textile processing clusters in China and comparable manufacturing centers consume ACH for dye fixation and wastewater pretreatment.
Procurement is shifting toward Municipal Facilities; Personal Care Brands are gaining share fastest as formulation complexity increases.
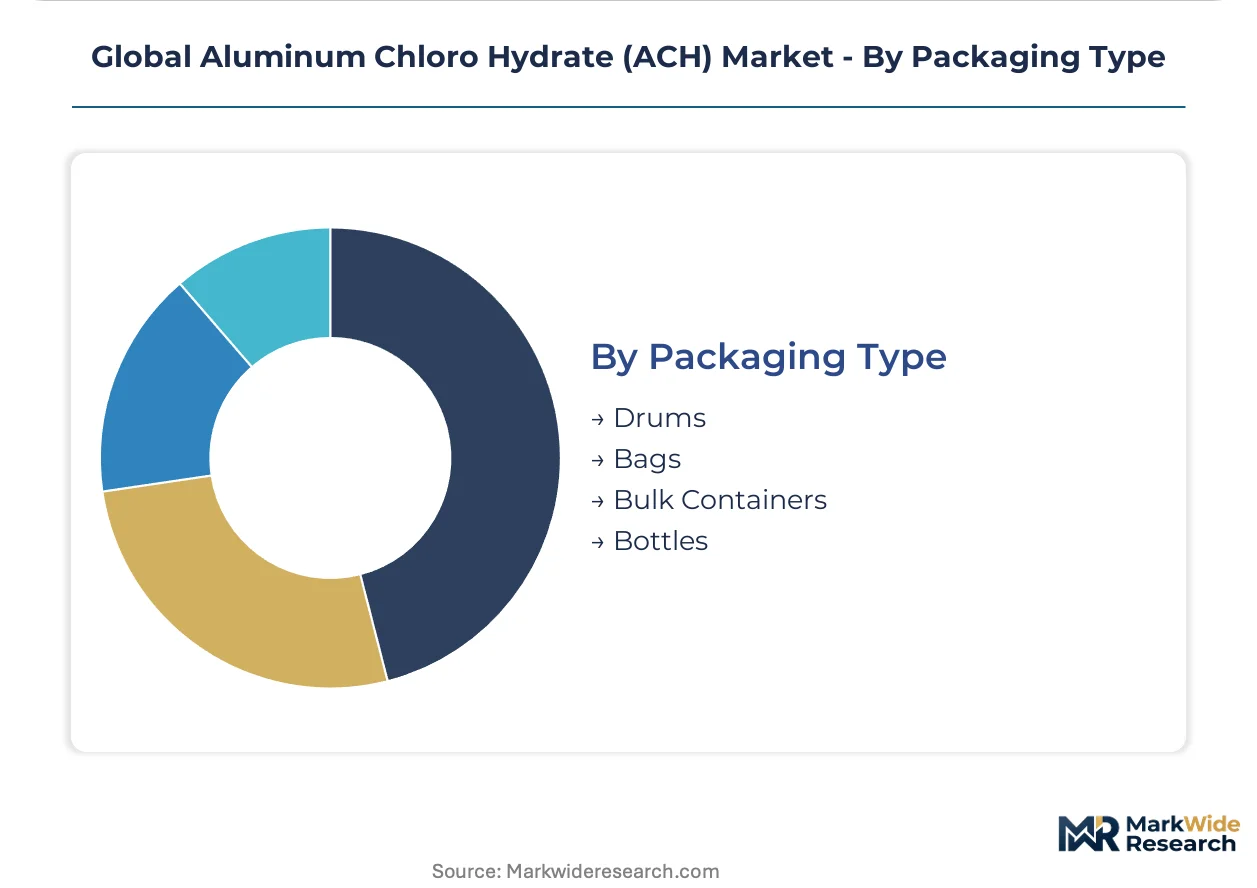
Packaging Type:
Supply concentration in bulk formats mirrors the infrastructure-heavy nature of water treatment demand, while specialized pharmaceutical packaging commands premium positioning through documentation and contamination control.
- Bulk Containers:Intermediate bulk containers and tanker deliveries optimize logistics for high-volume municipal water treatment contracts with dedicated storage and dosing infrastructure.
- Drums:Standard 200-liter steel or plastic drums serve mid-scale industrial water treatment and textile processing applications with moderate volume requirements.
- Bags:Multi-layer laminated bags with moisture barriers protect powder and flake grades for pharmaceutical and cosmetic manufacturing environments.
- Bottles:Small-format containers with tamper-evident closures and lot-specific labeling support laboratory-scale pharmaceutical formulation and quality control sampling.
Shipment volumes cluster in Bulk Containers; Bottles are climbing the fastest as pharmaceutical-grade SKU proliferation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang Province's textile processing clusters concentrate dye-fixing demand within China's coastal special economic zones, anchoring volume procurement for industrial-grade ACH formulations.
United States
Great Lakes municipal water authorities expand coagulant procurement under EPA Safe Drinking Water Act enforcement. The EPA mandates escalating documentation burdens for certified suppliers. Chicago and Detroit metropolitan utilities adopt automated dosing systems with real-time telemetry integration.
Germany
Industrial wastewater discharge standards tighten chloride residual limits in the Rhine-Ruhr manufacturing corridor. ECHA REACH registration requirements impose substance documentation protocols on cosmetic-grade imports. BASF's Ludwigshafen complex maintains integrated alumina feedstock for regional ACH production.
China
Zhejiang Province fabric finishing mills absorb rising ACH volumes for dye fixation applications. The Ministry of Ecology and Environment enforces dual carbon goals that redirect chemical procurement toward lower-emission variants. Hangzhou and Shaoxing processing clusters scale centralized wastewater pretreatment infrastructure.
Thailand
Bangkok metropolitan waterworks expand solution-format contracts as urbanization intensifies centralized treatment capacity. The country's national environmental regulator tightens effluent quality standards for municipal discharge. Eastern Economic Corridor industrial estates deploy high-basicity ACH variants for electronics manufacturing wastewater.
Netherlands
Rotterdam port logistics anchor bulk ACH import flows for European water treatment redistribution. ECHA REACH compliance tightens purity verification for pharmaceutical-grade formulations entering Dutch formulation channels. Amsterdam and Utrecht cosmetic laboratories demand segregated production lines with dedicated quality management systems.
Global Aluminum Chloro Hydrate (ACH) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated alumina producers commanding municipal water treatment contracts while formulation houses capture cosmetic-grade premiums. The vendor base concentrates around three strategic archetypes: integrated chemical majors with captive bauxite refining, regional solution blenders serving single-country procurement offices, and high-purity specialists with cGMP-compliant production lines. Capacity expansion and backward integration into alumina feedstock represent the dominant competitive moves as energy costs compress non-integrated margins.
Among Nordic and North American integrated producers, Kemira and USALCO exemplify the supply-chain-anchored archetype, while Holland Company occupies a position within the high-purity specialist tier. These three entities represent contrasting strategic postures: integrated feedstock security versus premium-grade certification infrastructure versus regional procurement relationship depth.
| Leading Market Players |
|---|
| Kemira |
| USALCO |
| Chemtrade Logistics Inc. |
| Holland Company |
| Summit Chemical |
| GEO |
| BASF |
| Omega Chemicals |
| Gulbrandsen Technologies |
| Others |
Supply & Pricing Matrix
Dual carbon goals enforced by China's Ministry of Ecology and Environment gate qualified supply for lower-emission ACH variants while simultaneously restricting premium-tier pricing access to producers with verified carbon accounting systems. This environmental mandate compresses margins for non-compliant producers while elevating certified suppliers into contracted procurement channels with extended payment terms.
Pricing Analysis
Short lead-time premiums dominate municipal procurement economics, with Great Lakes water authorities paying elevated rates for guaranteed delivery windows under multi-year framework agreements. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels separates cGMP-certified powder formats from bulk solution contracts. Cost compression in standard-basicity industrial grades is intensifying because iron-based coagulants capture selective tenders on total treatment cost calculations. Municipal procurement offices exhibit the highest price sensitivity due to budget cycle constraints, while pharmaceutical formulators absorb premium positioning for documented batch-specific analytical certificates.
Supply Chain Analysis
Alumina feedstock supply rests on bauxite refining complexes concentrated in China, Australia, and Brazil, with energy costs at smelter operations constituting the dominant variable in ACH production economics. Captive supply of metallurgical-grade alumina from integrated producers such as BASF's Ludwigshafen complex and Kemira's Nordic operations insulates against commodity volatility. Single-source vulnerability in high-purity cosmetic-grade production lines creates supply risk as ECHA REACH registration requirements force segregation of equipment for regulated European markets. Distribution runs through Rotterdam port logistics for European redistribution and bulk tanker networks for North American municipal contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Safe Drinking Water Act enforcement constructs a formidable barrier-to-entry moat, consolidating procurement toward certified producers with established compliance infrastructure and documented analytical capabilities.
For Market Incumbents: Hedge alumina feedstock exposure through backward integration into bauxite refining or long-term offtake agreements with Australian and Brazilian suppliers. Iron-based coagulant substitution threatens municipal market share in chloride-sensitive applications, necessitating accelerated development of high-basicity variants that generate reduced residual discharge. Capacity addition in Southeast Asian solution-blending facilities captures urban water infrastructure expansion in Thailand and Vietnam while reducing logistics exposure to Rotterdam port congestion. For New Entrants and Emerging Players: Regional textile processing clusters in Zhejiang Province represent an underserved buyer archetype with rising ACH volumes for dye-fixing applications and less stringent certification requirements than pharmaceutical or cosmetic channels. Fabric mills operating centralized wastewater pretreatment infrastructure offer the most penetrable segment for industrial-grade solution formats without cGMP compliance burdens. A technical service-led go-to-market angle emphasizing basicity customization and on-site dosing optimization differentiates against commodity suppliers. For Investors and Strategic Acquirers: Consolidation of annual municipal contracts toward multi-year framework agreements with performance guarantees is the leading indicator that procurement relationship depth and compliance infrastructure are becoming the primary valuation drivers over production scale. Long-term viability across the analysis window favors targets with integrated alumina supply chains and established FDA OTC antiperspirant monograph testing protocols. Watch for REACH registration deadline extensions as a signal of regulatory complexity favoring incumbent specialists over new entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Feedstock | Captive bauxite supply insulates Kemira and BASF against energy cost volatility at smelter complexes. |
| High-Basicity Variant Development | Reduced chloride residual formulations align with tightening industrial discharge standards in Germany and the Netherlands. |
| cGMP-Compliant Production Line Segregation | Dedicated quality management systems enable premium positioning in ECHA REACH-regulated cosmetic and pharmaceutical channels. |
| Automated Dosing System Partnerships | Real-time telemetry integration with Great Lakes utilities compresses supplier base toward certified vendors. |
| Southeast Asian Solution Blending Capacity | Regional production footprints capture Bangkok and Jakarta municipal procurement expansion with reduced logistics costs. |
Research Methodology
Multi-period observation of municipal contract award patterns, REACH registration timelines, and textile processing capacity utilization anchored the trend analysis, supplemented by interviews with plant managers at Nordic and North American ACH production facilities, procurement leads at Great Lakes water authorities, technical R&D directors at personal care formulators, and distribution channel partners in European bulk chemical logistics. Secondary validation drew from customs and trade data, ECHA substance registration databases, EPA Safe Drinking Water Act enforcement records, and SEC 10-K filings from integrated chemical majors. Bottom-up volume modeling across product type and application segments triangulated against top-down macroeconomic drivers.
Input-output matrices structured the analytical framework across the projection horizon, modeling ACH demand through grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from segmented volume trajectories calibrated to infrastructure investment cycles and regulatory implementation schedules. Forecast inputs incorporated alumina price elasticity, energy cost pass-through coefficients, and municipal procurement contract renewal rates.
Revisions become necessary when bauxite refining economics shift dramatically, REACH registration requirements extend to additional substance categories, or iron-based coagulant substitution accelerates beyond baseline assumptions. A small set of triggers—including EPA enforcement intensity, dual carbon goal stringency in China, and ECHA purity threshold adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Gold Plating Chemicals Market
Chemicals
Chlorosilane Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Ethanolamine Market
Chemicals
Calcium Borate Market
Chemicals
Hydrazine Market
Chemicals
Hydrazine Hydrate Market
Chemicals
Global Inorganic Fluorides Market
Chemicals
Global Acetic Anhydride Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Allyl Chloride Market
Chemicals
Methylamines Market
Chemicals
Diphenylamine (DPA) Market
Chemicals
Ferric Oxide Market