
 Muriatic Acid Market | 2026-2036
Muriatic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Muriatic Acid Market Analytics
Aftermarket service revenue for acid recovery and regeneration systems is rewriting profit distribution across the value chain. BASF SE leverages captive chlorine integration to sustain feedstock cost advantages in European operations. Olin Corporation anchors North American supply through its Gulf Coast chlor-alkali network. INOVYN competes on membrane-cell technology leadership and coastal logistics access.
Muriatic acid is an aqueous solution of hydrogen chloride typically containing 31 to 38 percent HCl by weight, produced primarily as a coproduct of chlor-alkali electrolysis or through the synthesis burning of chlorine with hydrogen; it functions as a strong mineral acid for pH adjustment, metal surface preparation, and chemical synthesis across industrial processes. Industrial grade formulations dominate volume flows into steel pickling and water treatment applications where purity thresholds remain moderate. Chemical manufacturing represents the fastest-expanding application segment as pharmaceutical intermediates and specialty chloride production expand. Technical grade supply occupies the thickest margin pool due to certification requirements and batch-traceability demands from semiconductor etching clients.
EPA effluent limitation guidelines constrain discharge concentrations from metal finishing facilities, directly shaping acid consumption intensity and recovery system investments. REACH registration and CLP classification in Europe mandate granular hazard communication and downstream user notification protocols that elevate compliance costs for importers. OSHA permissible exposure limits and process safety management rules govern storage and handling infrastructure specifications across US manufacturing sites. Stakeholders must monitor regulatory divergence between jurisdictions as carbon-border adjustment mechanisms and chemical footprint disclosures begin to alter competitive access conditions.
Market Dynamics
Membrane-cell chlor-alkali technology diffusion is concentrating production capacity among coastal integrated operators, while EPA effluent guidelines and REACH registration protocols simultaneously reshape specification requirements and handling infrastructure investments across downstream metal finishing and chemical synthesis facilities.
Growth Catalysts
- Steel pickling intensity:Automotive lightweighting programs drive expanded hot-rolled coil consumption for structural components, directly lifting acid demand from metal surface preparation operations.
- REACH registration completion:Full CLP classification harmonization across EU member states enables streamlined cross-border distribution and reduces downstream user notification friction for importers.
- Membrane-cell technology:Ion-exchange membrane electrolysis expansion in coastal China lowers coproduct acid production costs and improves chlorine integration economics for integrated chlor-alkali operators.
Market Restraints
- Chlorine feedstock volatility:Electricity cost fluctuations and chlorine demand cyclicality from PVC and isocyanate sectors transmit price instability into acid coproduct economics.
- Coastal production concentration:Over 70% of merchant supply originates from Gulf Coast and Yangtze River Delta chlor-alkali clusters, exposing buyers to hurricane and logistics disruption risks.
- Sulfuric acid substitution:Phosphate fertilizer producers and some metal pickling operations switch to sulfuric acid where surface finish requirements permit, compressing muriatic acid share in pH adjustment applications.
Strategic Opportunities
- Semiconductor etching expansion:Technical-grade demand from wafer fabrication facilities in Taiwan and South Korea creates premium-margin pull for ultra-pure HCl with full batch traceability.
- Acid regeneration services:Spent acid recovery and reconcentration systems generate recurring aftermarket revenue streams independent of virgin acid commodity cycles.
- EU Green Deal chemical footprint disclosure:Carbon-border adjustment mechanisms reward low-carbon electrolysis routes, creating competitive differentiation for membrane-cell producers with renewable electricity sourcing.
Industry Challenges
- Corrosion engineering specialization:Storage and handling infrastructure design requires scarce materials science expertise for fluoropolymer-lined vessels and hydrogen chloride vapor containment systems.
- Multi-jurisdiction compliance synchronization:Divergent OSHA permissible exposure limits, EPA risk management plan thresholds, and REACH downstream user obligations create documentation complexity for multinational distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Muriatic Acid Market |
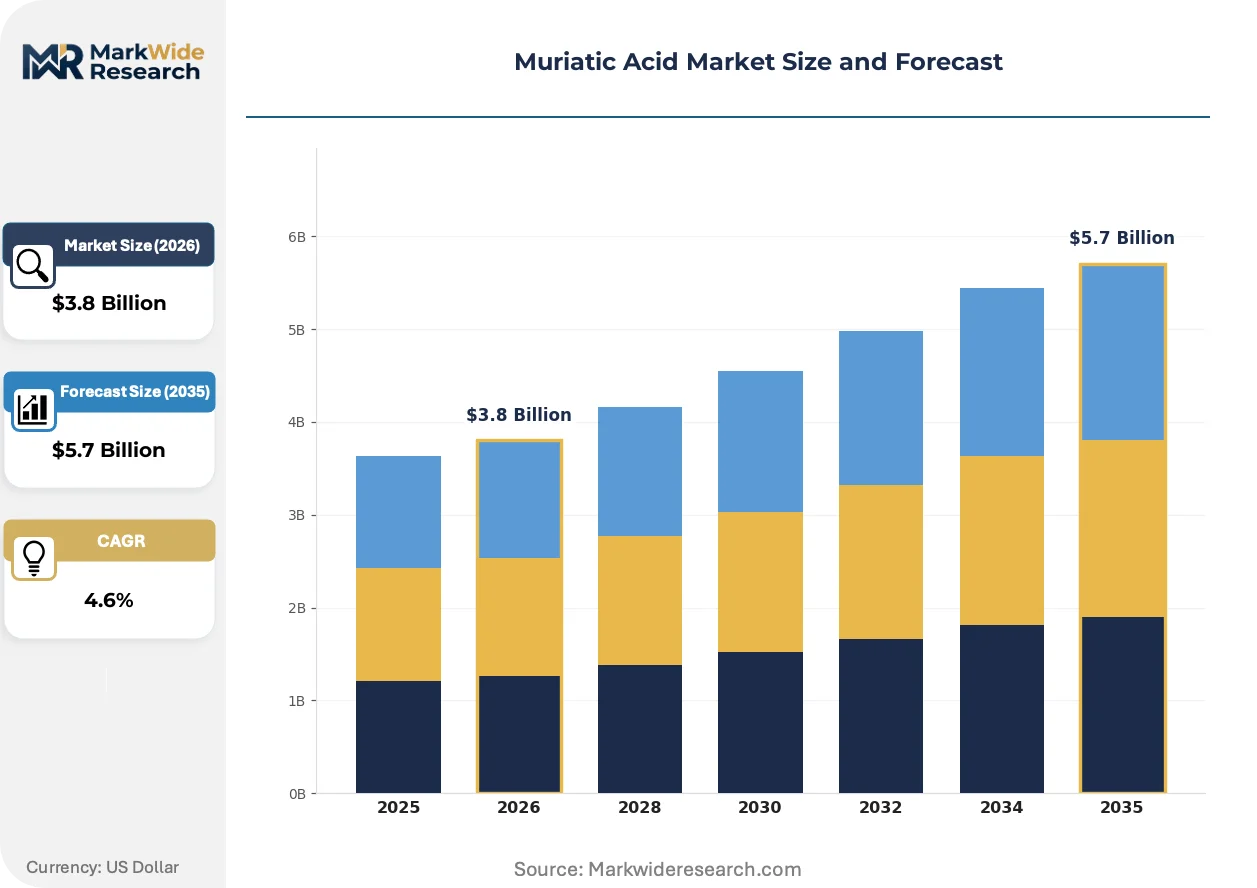
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Food Grade, Industrial Grade, Laboratory Grade Application: Water Treatment, Cleaning, Pool Maintenance, Chemical Manufacturing End User: Construction, Agriculture, Healthcare, Automotive Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | BASF SE, Occidental Petroleum Corporation, Olin Corporation, Westlake Chemical Corporation, The Dow Chemical Company, INOVYN, OxyChem, ERCO Worldwide, Detrex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Muriatic Acid Market Evolving Landscape
Process intensification and circular economy mandates are compressing traditional acid consumption models while elevating recovery system investments and purity-grade stratification across industrial and technical specifications.
Diffusion dialysis membrane technology is collapsing the economics of spent acid regeneration by enabling direct acid recovery without neutralization or thermal reconcentration. Steel mills in Germany and Japan adopt these systems to reduce fresh acid procurement volumes by 40-60% while eliminating hazardous waste disposal liabilities. The technology is collapsing virgin acid demand intensity in mature pickling operations and shifting supplier revenue toward equipment and service contracts.
EPA effluent limitation guidelines for metal finishing facilities mandate real-time monitoring and zero-discharge thresholds for chloride-containing wastewater. US electroplating shops and coil coating operations invest in closed-loop rinse systems and acid recovery evaporators to comply with NPDES permit conditions. Small and mid-sized job shops face disproportionate compliance burdens, accelerating consolidation toward integrated coil processors with captive regeneration capabilities.
Specification-driven procurement now separates technical-grade semiconductor clients from industrial-grade bulk buyers through distinct certification and audit requirements. Japanese and Taiwanese electronics manufacturers impose JIS K 8180 and SEMI standard compliance with full supply chain documentation, while North American water treatment utilities prioritize cost-per-ton metrics. Semiconductor fabrication clusters in Hsinchu and Pyeongtaek drive fastest specification escalation, with batch-specific COA requirements and dedicated logistics protocols displacing commodity spot purchasing.
Muriatic Acid Market Segmentation
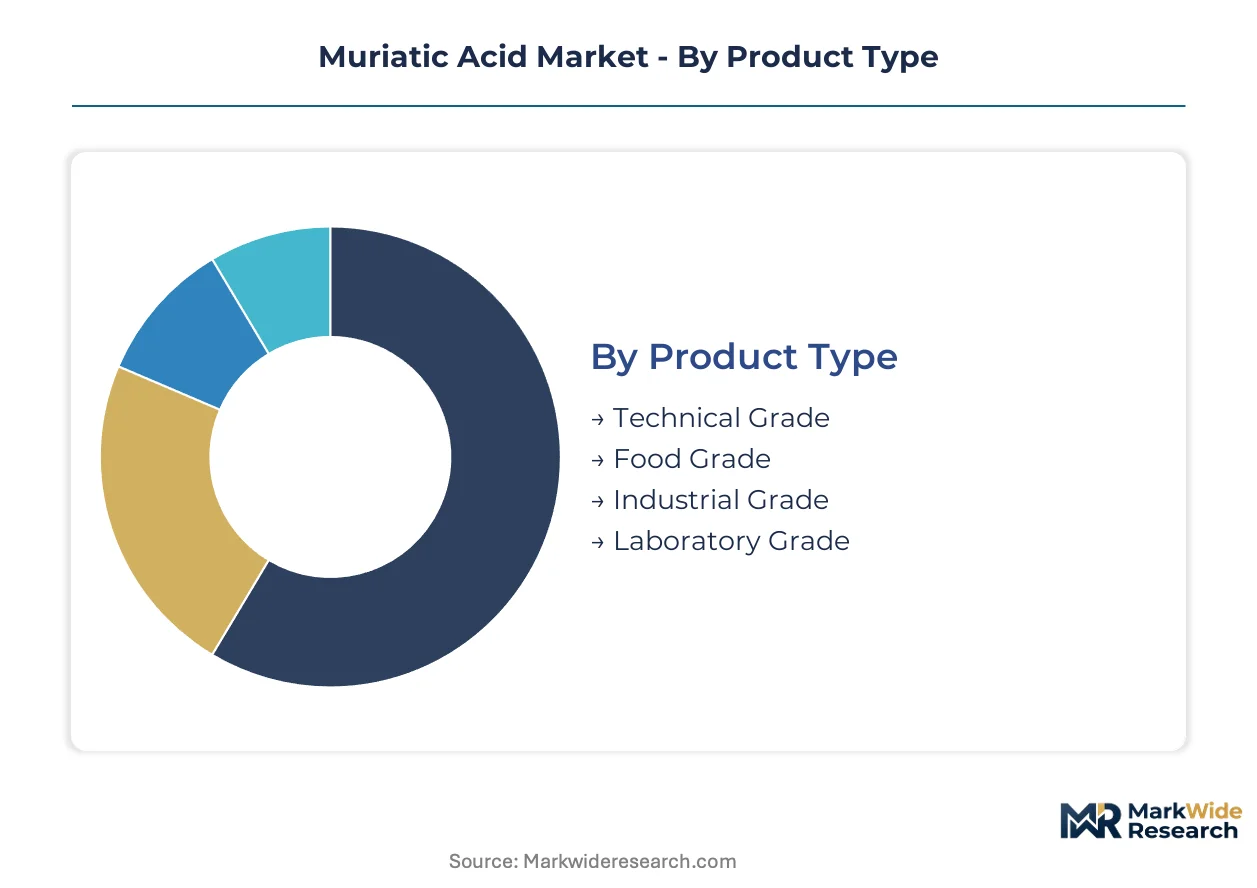
Muriatic acid segmentation reflects divergent purity requirements and service intensity across industrial, technical, and consumer channels. Aftermarket regeneration services and certification protocols create distinct margin architectures within each category.
Product Type:
After-sales-service intensity varies dramatically across purity grades, with technical and laboratory segments demanding batch-traceability support and on-site handling consultation while industrial buyers prioritize volume logistics.
- Technical Grade:Ultra-pure formulations meeting SEMI and JIS K 8180 specifications for semiconductor etching and electronics manufacturing. Demand concentrates in Taiwan's Hsinchu Science Park and South Korea's Pyeongtaek cluster, where wafer fabrication facilities require dedicated logistics protocols and certificate-of-analysis documentation for every batch.
- Industrial Grade:Moderate-purity solutions containing 31-38% HCl by weight, optimized for steel pickling and water treatment operations. Steel mills in Germany and Japan deploy diffusion dialysis regeneration systems to reduce fresh acid procurement by 40-60%, shifting supplier revenue toward equipment service contracts.
- Food Grade:Purified formulations meeting food additive specifications for starch hydrolysis and pH adjustment in food processing.
- Laboratory Grade:High-purity reagents for analytical chemistry and research applications requiring precise concentration tolerances.
Industrial grade holds the largest share; momentum sits with technical grade.
Application:
Cost tier stratification separates commodity bulk applications from premium-process segments where specification compliance commands price premiums.
- Chemical Manufacturing:Feedstock for pharmaceutical intermediates, specialty chlorides, and agrochemical synthesis. Chlor-alkali integrated producers in China's Yangtze River Delta leverage membrane-cell technology to lower coproduct acid costs and improve chlorine integration economics.
- Water Treatment:pH adjustment and alkalinity control in municipal and industrial water systems. US utilities prioritize cost-per-ton metrics over certification complexity, exposing the segment to sulfuric acid substitution where surface finish requirements permit.
- Cleaning:Masonry etching, concrete preparation, and industrial equipment descaling in construction maintenance.
- Pool Maintenance:Residential and commercial swimming pool pH balancing, distributed through retail and wholesale channels.
Water treatment holds the largest share; chemical manufacturing is expanding most quickly.
End User:
Customer type determines procurement sophistication, with automotive and healthcare buyers imposing stringent audit requirements while construction and agriculture prioritize volume pricing.
- Automotive:Steel pickling for hot-rolled coil surface preparation in structural component manufacturing. EPA effluent guidelines constrain discharge concentrations from metal finishing facilities, driving acid recovery system investments among coil processors.
- Healthcare:Pharmaceutical synthesis and medical device sterilization applications requiring full supply chain documentation.
- Construction:Masonry cleaning, concrete etching, and cement residue removal in building maintenance and renovation.
- Agriculture:Soil pH adjustment and irrigation system maintenance in large-scale farming operations.
Automotive holds the largest share; healthcare is gaining share fastest.
Distribution Channel:
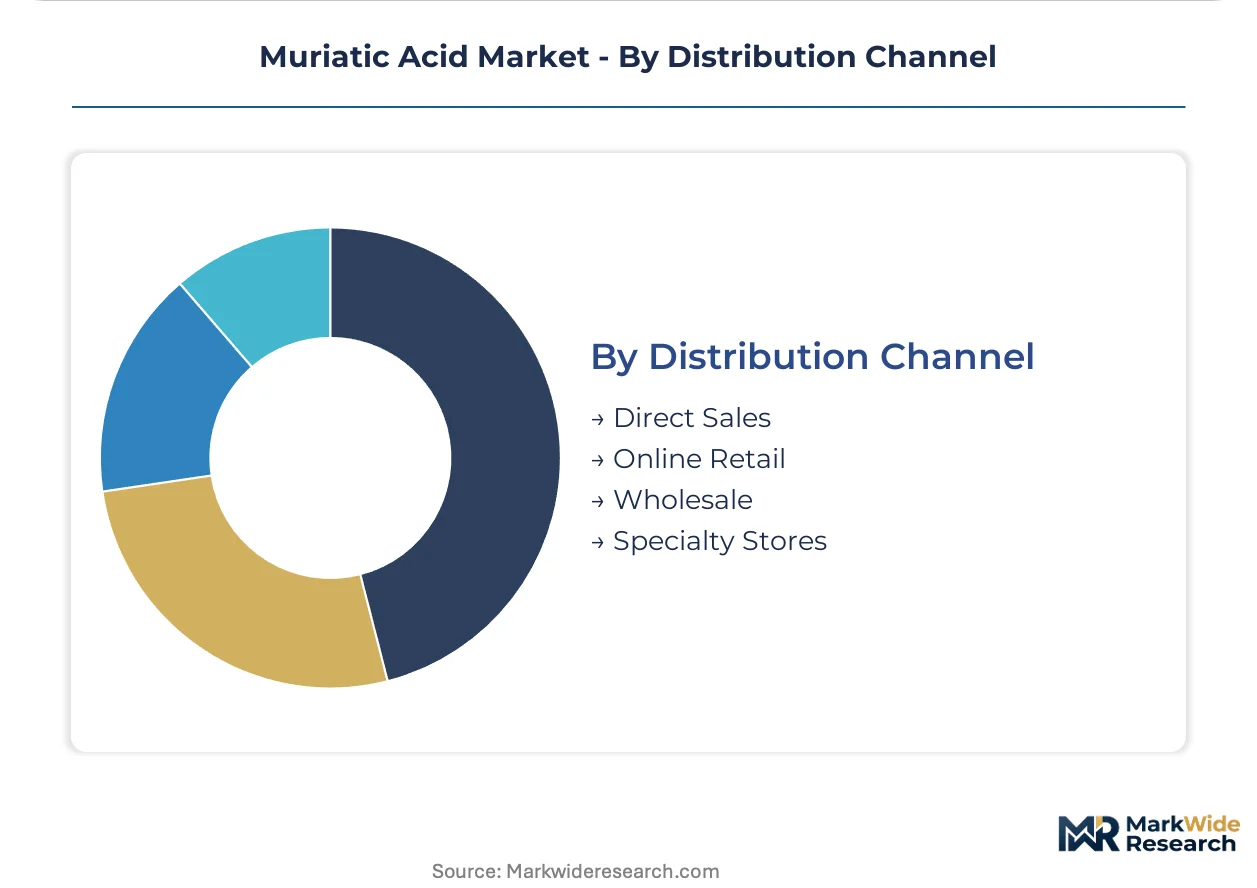
Supply concentration shapes channel economics, with coastal chlor-alkali clusters favoring direct sales to large consumers while fragmented end-users rely on wholesale and specialty intermediaries.
- Direct Sales:Long-term contracts between chlor-alkali producers and large industrial consumers. Olin Corporation's Gulf Coast network and INOVYN's coastal logistics access anchor North American and European direct supply.
- Wholesale:Regional distributors serving mid-sized metal finishers, water treatment utilities, and agricultural operations.
- Specialty Stores:Local suppliers catering to construction contractors and pool maintenance professionals with technical support services.
- Online Retail:E-commerce platforms for small-volume consumers in residential pool maintenance and DIY cleaning applications.
Direct sales holds the largest share; specialty stores show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water treatment utilities in India and Brazil exhibit acute price elasticity, while semiconductor fabricators in Taiwan and South Korea absorb premium technical-grade pricing without volume reduction. This demand-elasticity contrast shapes regional supplier strategies and margin architectures.
United States
Automotive lightweighting programs drive hot-rolled coil consumption for structural components, directly lifting acid demand from steel pickling operations. EPA effluent limitation guidelines constrain discharge concentrations from metal finishing facilities, forcing acid recovery system investments. Gulf Coast chlor-alkali clusters anchor merchant supply, with Olin Corporation's integrated network serving coil processors across the Southeast and Midwest.
China
Massive chlor-alkali output and downstream chemical processing base concentrate global demand volume. MEE enforcement of dual carbon goals pressures membrane-cell technology diffusion across coastal provinces. Yangtze River Delta integrated producers leverage captive chlorine integration to sustain feedstock cost advantages in pharmaceutical intermediate synthesis.
Germany
Diffusion dialysis membrane technology adoption collapses virgin acid demand intensity in mature steel pickling operations. REACH registration and CLP classification harmonization enable streamlined cross-border distribution to downstream metal finishers. Ruhr industrial region steel mills deploy closed-loop regeneration systems, shifting supplier revenue toward equipment service contracts.
Japan
Technical-grade specification escalation accelerates fastest among Hsinchu and Pyeongtaek electronics clusters, with Japanese suppliers serving as quality-certification intermediaries. METI industrial decarbonization roadmaps reward low-carbon electrolysis routes for membrane-cell producers. Kanto region chemical processors maintain JIS K 8180 compliance for semiconductor etching supply chains.
South Korea
Wafer fabrication facilities in Pyeongtaek drive premium-margin pull for ultra-pure HCl with full batch traceability. MFDS pharmaceutical manufacturing standards elevate supply chain documentation requirements for imported acid feedstocks. Seoul Capital Area specialty chemical producers anchor technical-grade consumption for electronics manufacturing.
Muriatic Acid Market Competitive Landscape
Integrated chlor-alkali operators and merchant chemical distributors split the market between captive supply economics and logistics-intensive distribution. The vendor base concentrates among coastal membrane-cell producers with chlorine integration advantages, while regional wholesalers serve fragmented water treatment and construction end-users. Two archetypes dominate: scale-driven integrated producers with captive feedstock control, and specialty-grade refiners serving semiconductor certification requirements. Capacity expansion along Gulf Coast and Yangtze River Delta clusters, plus acid regeneration service contract proliferation, constitute the dominant competitive moves reshaping profit distribution.
Within the integrated producer tier, BASF SE and Olin Corporation exemplify archetypal positioning through European captive chlorine networks and North American Gulf Coast infrastructure respectively. INOVYN occupies a position representing membrane-cell technology leadership with coastal logistics access. These three entities anchor the competitive structure without exhausting the participant set, as Detrex Corporation and ERCO Worldwide sit within specialized regeneration service and regional distribution segments respectively.
| Leading Market Players |
|---|
| BASF SE |
| Occidental Petroleum Corporation |
| Olin Corporation |
| Westlake Chemical Corporation |
| The Dow Chemical Company |
| INOVYN |
| OxyChem |
| ERCO Worldwide |
| Detrex Corporation |
| Others |
Value Network & Pricing Analysis
Overcapacity signals from China's Yangtze River Delta chlor-alkali clusters are compressing spot pricing for industrial-grade material while simultaneously accelerating supplier migration toward long-term service contracts. This utilization-driven bifurcation rewards membrane-cell operators with renewable electricity sourcing while stranding legacy diaphragm-cell assets in margin erosion.
Pricing Analysis
Aftermarket service revenue from acid regeneration and reconcentration systems now drives lifetime value for integrated producers. Three-tier pricing structure across technical, industrial, and laboratory grades separates semiconductor clients with SEMI certification requirements from bulk water treatment buyers prioritizing cost-per-ton metrics. Pricing pressure stems from sulfuric acid substitution in phosphate fertilizer and metal pickling applications where surface finish tolerances permit. Water treatment utilities exhibit acute price sensitivity, while Taiwanese wafer fabricators absorb premium technical-grade pricing without volume reduction.
Supply Chain Analysis
Contract manufacturing concentration resides with coastal membrane-cell operators in China's Jiangsu and Shandong provinces, Olin Corporation's Gulf Coast network, and INOVYN's European coastal logistics hubs. Merchant supply draws from chlorine coproduction at chlor-alkali facilities tethered to PVC and isocyanate demand cycles. Single-source vulnerability concentrates risk in hurricane-exposed Gulf Coast clusters and Yangtze River Delta logistics chokepoints. Distribution runs through direct sales contracts for large steel mills and chemical processors, with regional wholesalers serving fragmented construction and pool maintenance end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as automotive lightweighting programs drive hot-rolled coil consumption and acid demand from steel pickling operations.
For Market Incumbents: Entrench membrane-cell technology leadership through coastal capacity expansion and captive chlorine integration. Defend against sulfuric acid substitution by embedding diffusion dialysis regeneration services into long-term steel mill contracts. Prioritize certification investment for SEMI and JIS K 8180 compliance to capture technical-grade margin pools. For New Entrants and Emerging Players: India's underpenetrated water treatment sector offers white-space expansion as municipal utilities modernize pH adjustment infrastructure. Target acid regeneration service contracts at mid-sized German and Japanese steel mills seeking to reduce fresh acid procurement volumes. Pursue a go-to-market angle centered on closed-loop rinse system integration for EPA-compliant metal finishers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across technical-grade refining infrastructure as semiconductor fabrication clusters demand batch-traceability capabilities. Long-term viability favors acquisition targets with membrane-cell technology and renewable electricity sourcing. Watch for EPA effluent guideline enforcement intensity as an inflection indicator for acid recovery system investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Cell Capacity Expansion | Coastal chlor-alkali operators in China's Jiangsu province leverage renewable electricity to lower coproduct acid production costs. |
| Backward Integration into Chlorine Supply | BASF SE's European captive chlorine networks insulate feedstock economics from merchant chlorine volatility. |
| Acid Regeneration Service Contracts | German Ruhr region steel mills adopt diffusion dialysis systems to reduce fresh acid procurement by 40-60 percent. |
| Technical-Grade Certification Investment | Taiwan's Hsinchu Science Park wafer fabricators impose SEMI standard compliance with full supply chain documentation. |
| Long-Term Supply Agreements | Olin Corporation's Gulf Coast network anchors direct sales contracts with Southeast and Midwest coil processors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with chlor-alkali plant managers, steel mill procurement leads, semiconductor chemical buyers, and water treatment utility engineers; and secondary validation against SEC 10-K filings, customs and trade data, EPA effluent limitation guidelines, and ACC industry reports. Bottom-up volume modeling triangulated with top-down value estimation across grade tier, end-use industry, and regional production hub dimensions.
Forecast inputs incorporated membrane-cell technology diffusion rates, automotive lightweighting program timelines, and semiconductor fabrication capacity expansion across the analysis window. Segmentation modeling captured purity grade stratification, application intensity differentials, and distribution channel economics. CAGRs derived from production capacity utilization trajectories, chlorine demand cyclicality from PVC and isocyanate sectors, and regulatory enforcement patterns for acid recovery system mandates.
Practitioners should monitor chlorine feedstock volatility, EPA effluent guideline enforcement intensity, and sulfuric acid substitution rates for early signals of forecast revision. Quarterly review of membrane-cell capacity additions, semiconductor fabrication cluster expansion, and carbon-border adjustment mechanism implementation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Hydrogen Chloride Market
Chemicals
Triethanolamine Market
Chemicals
India Methanol Market
Chemicals
Scouring Agents Market
Chemicals
Immunochemicals Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Paint Stripper Market
Chemicals
3-Iodoaniline Market
Chemicals
3,5-Dinitroaniline Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Germany Methanol Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Global Thiophene Market
Chemicals
Mercury (I) Sulphate Market