
 Di Nitro Toluene Market | 2026-2036
Di Nitro Toluene Market Size, Share, and Industry Trends Forecast 2026-2036
Di Nitro Toluene Market Outlook
Pharmaceutical-grade purity specifications is reorganizing procurement standards across the Di Nitro Toluene value chain. BASF SE leverages its integrated aromatics complex in Ludwigshafen to sustain consistent high-purity output for regulated end uses. Lanxess Corporation anchors European supply through specialized dinitrotoluene derivatives capacity at its Krefeld-Uerdingen site. Covestro AG competes on technology leadership in controlled nitration processes that reduce byproduct formation.
Di nitro toluene denotes a class of nitroaromatic compounds produced through controlled nitration of toluene, typically yielding ortho-, meta-, and para-isomers with varying melting points between fifty and seventy degrees Celsius depending on isomeric composition; these compounds serve primarily as precursors for toluene diisocyanate synthesis and as energetic materials in commercial explosives formulations. Orthodinitrotoluene dominates volume throughput due to its established role as the principal feedstock for TDI production chains, while P-Dinitrotoluene captures specialized margin pools in defense-oriented explosives applications where crystalline stability under thermal stress commands premium pricing. The Chemical Intermediates application segment retains structural importance despite slower growth, as automotive and construction end users maintain steady offtake for polyurethane foam precursors.
EPA oversight in the United States and REACH registration requirements in Europe enforce stringent handling protocols and emissions thresholds that elevate compliance costs for producers without captive nitration infrastructure. China's MEE implements wastewater discharge standards that directly affect operating permits for dinitrotoluene manufacturers in the Yangtze River Delta cluster. India's CEA monitors storage and transport safety for explosives-grade material moving through the country's defense supply chain. Stakeholders must weigh capital allocation between purity upgrades for pharmaceutical qualification and scale investments in standard-grade chemical intermediate output.
Market Dynamics
Defense procurement of explosives-grade di nitro toluene is accelerating as munitions modernization programs in India and Germany expand offtake volumes, while REACH compliance and China's dual carbon goals simultaneously tighten purity specifications for chemical intermediate applications.
Growth Catalysts
- Defense modernization programs:India's CEA-monitored munitions supply chain and Germany's Bundeswehr procurement are expanding explosives-grade material orders. These programs require crystalline stability specifications that favor high-purity orthodinitrotoluene output.
- REACH registration tiering:ECHA's differentiated registration requirements for chemical intermediates versus energetic materials create compliance pathways that reward producers with captive nitration infrastructure and continuous purification systems.
- TDI precursor demand:Automotive and construction end-users in South Korea and the United States maintain steady polyurethane foam precursor offtake, anchoring volume throughput for standard-grade chemical intermediate applications.
Market Restraints
- Toluene feedstock volatility:Crude oil-linked aromatics pricing creates margin compression for producers without backward integration into refinery operations or long-term supply contracts with integrated petrochemical complexes.
- Yangtze River Delta concentration:China's MEE wastewater discharge standards affect operating permits for dinitrotoluene manufacturers clustered in this region, creating geographic supply risk during environmental enforcement cycles.
- Pharmaceutical-grade substitution:Alternative nitration pathways and non-toluene-based isocyanate precursors threaten standard-grade demand in regulated end uses where purity specifications are tightening.
Strategic Opportunities
- Pharmaceutical qualification pathways:Producers investing in purification upgrades can access premium margin pools in regulated end uses where FDA and EMA standards exceed standard chemical intermediate specifications.
- Dual carbon alignment in China:MEE emissions trading schemes and provincial green manufacturing incentives reward nitration process improvements that reduce nitrous oxide byproduct formation and energy intensity.
- Defense supply chain localization:India's PLI scheme for critical chemicals and explosives precursors offers tariff and procurement advantages for domestic production capacity serving CEA-monitored defense offtake.
Industry Challenges
- Controlled nitration expertise scarcity:Specialized process engineers capable of managing exothermic reaction safety and isomer ratio control are concentrated among legacy producers, constraining new capacity deployment.
- Multi-jurisdiction certification timelines:Simultaneous REACH, EPA, and MEE compliance requires 18-36 month qualification periods that delay revenue recognition for purity upgrades and new facility commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Di Nitro Toluene Market |
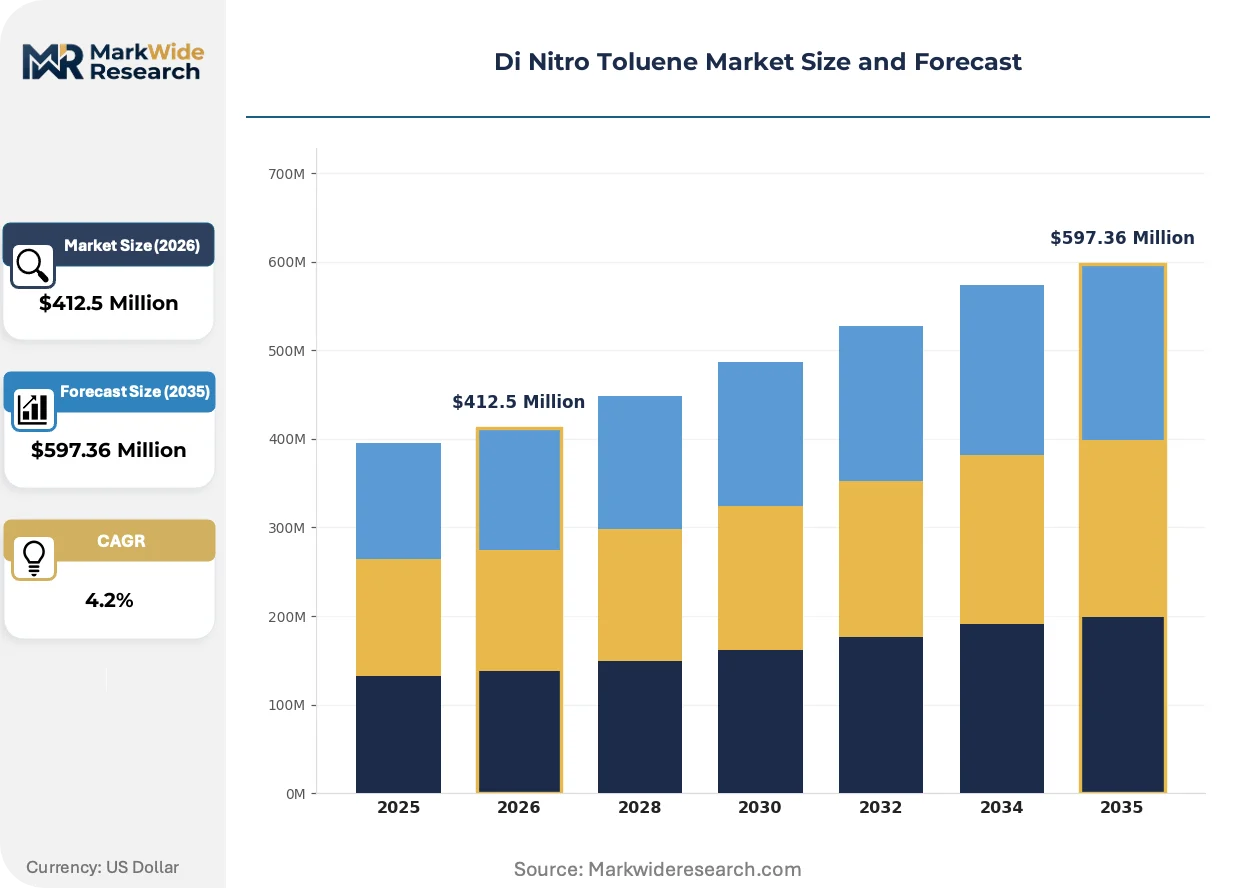
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $597.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthodinitrotoluene, Metadinitrotoluene, P-Dinitrotoluene, Others Application: Explosives Manufacturing, Chemical Intermediates, Paints & Coatings, Solvents End User: Defense, Construction, Automotive, Pharmaceutical Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Dow Inc., Spectrum Chemical Manufacturing Corp., BASF SE, Panoli Intermediates, Sigma-Aldrich Corporation, Lanxess Corporation, Huntsman Corporation, Toray Fine Chemicals, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Di Nitro Toluene Market Strategic Shifts
Continuous flow nitration technology and real-time process analytical control are reshaping production economics, while regulatory tiering between defense and chemical intermediate applications fragments compliance strategies.
Continuous flow reactor systems are replacing batch nitration in new capacity installations. South Korean and German TDI producers are adopting these systems fastest, driven by labor cost and safety imperatives. The technology is decomposing the traditional scale advantages of large-batch aromatics complexes by enabling distributed, smaller-footprint production with equivalent purity output.
REACH authorization requirements for substances of very high concern are expanding to cover certain dinitrotoluene isomer mixtures. ECHA's 2023-2025 substance evaluation roadmap triggers downstream user notification obligations that elevate documentation costs. Chemical intermediate applications in European polyurethane supply chains face the steepest compliance burden, pushing some formulation users toward non-EU sourcing.
Defense procurement offices are consolidating supplier qualification lists around dual-use purity capabilities. India's CEA and the United States' defense logistics agencies now require explosives-grade producers to demonstrate pharmaceutical-grade contamination controls. This behavioral shift compresses the historical separation between defense and chemical intermediate supply chains, forcing multi-segment certification investments that smaller pure-play producers struggle to fund.
Di Nitro Toluene Market Segmentation
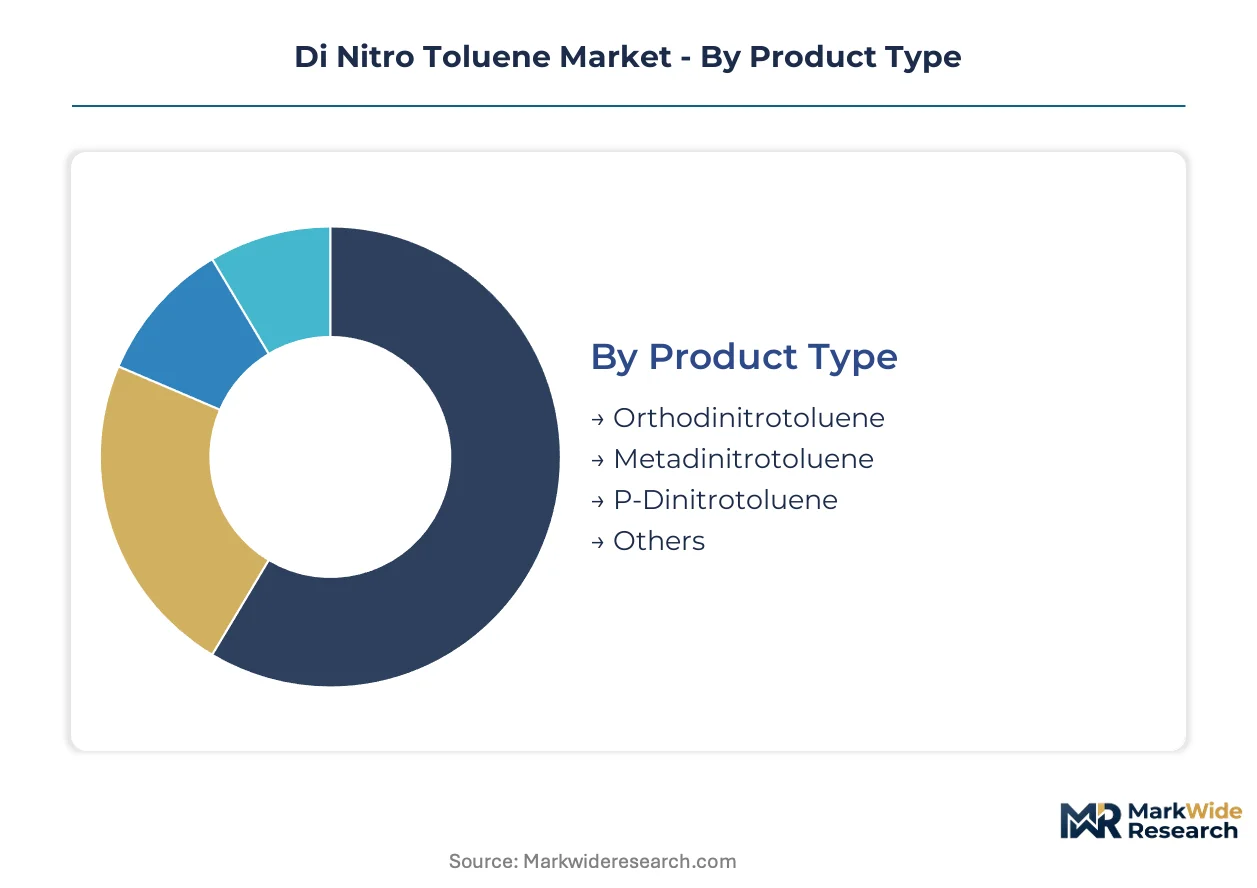
Di nitro toluene segmentation reflects divergent purity requirements across defense procurement and chemical intermediate channels. Regulatory tiering between explosives-grade and pharmaceutical-grade specifications creates distinct margin architectures within each category.
Product Type:
REACH registration tiering and defense procurement specifications differentiate isomer value pools across European and Indian supply chains.
- Orthodinitrotoluene:This isomer dominates commercial throughput as the principal feedstock for toluene diisocyanate synthesis. South Korean and United States polyurethane producers anchor steady offtake volumes despite slower growth in automotive foam applications.
- P-Dinitrotoluene:Crystalline stability under thermal stress commands premium pricing in defense-oriented explosives formulations. India's CEA-monitored munitions supply chain and Germany's Bundeswehr procurement favor this isomer for modernization programs requiring precise detonation characteristics.
- Metadinitrotoluene:Specialized applications in dye intermediates and photographic chemicals sustain niche demand through Japanese and European specialty chemical distributors.
- Others:Mixed isomer streams and technical-grade compositions serve cost-sensitive industrial applications where purity specifications remain less stringent.
Orthodinitrotoluene handles the majority of throughput; P-Dinitrotoluene is the fastest mover on share.
Application:
Customer procurement patterns split between long-term defense contracts and spot-market chemical intermediate purchasing.
- Explosives Manufacturing:Defense procurement offices in India and Germany consolidate supplier qualification lists around dual-use purity capabilities. CEA and Bundeswehr requirements now mandate pharmaceutical-grade contamination controls for explosives-grade material.
- Chemical Intermediates:TDI precursor demand from automotive and construction end-users in South Korea and the United States maintains volume throughput. REACH compliance costs push some European formulation users toward non-EU sourcing for standard-grade material.
- Paints & Coatings:Solvent and pigment intermediate applications face substitution pressure from non-toluene-based chemistries in regulated European markets.
- Solvents:Industrial cleaning and extraction applications concentrate in Chinese manufacturing clusters subject to MEE wastewater discharge enforcement cycles.
Explosives Manufacturing captures the steepest expansion trajectory as defense modernization accelerates; Chemical Intermediates retains structural volume leadership.
End User:
Margin stratification follows certification intensity from pharmaceutical qualification through standard industrial grade.
- Defense:India's PLI scheme for critical chemicals and explosives precursors offers tariff advantages for domestic capacity serving CEA-monitored offtake. Procurement localization trends favor producers with multi-jurisdiction certification.
- Construction:Polyurethane foam precursor demand correlates with residential and commercial building cycles in South Korea and the United States.
- Automotive:Seating and interior foam specifications drive TDI-derived di nitro toluene consumption through tiered supplier contracts.
- Pharmaceutical:FDA and EMA standards for nitroaromatic intermediates create premium margin pools accessible only through continuous purification system investments.
Defense commands pricing leadership; Pharmaceutical is expanding most quickly on regulatory tightening.
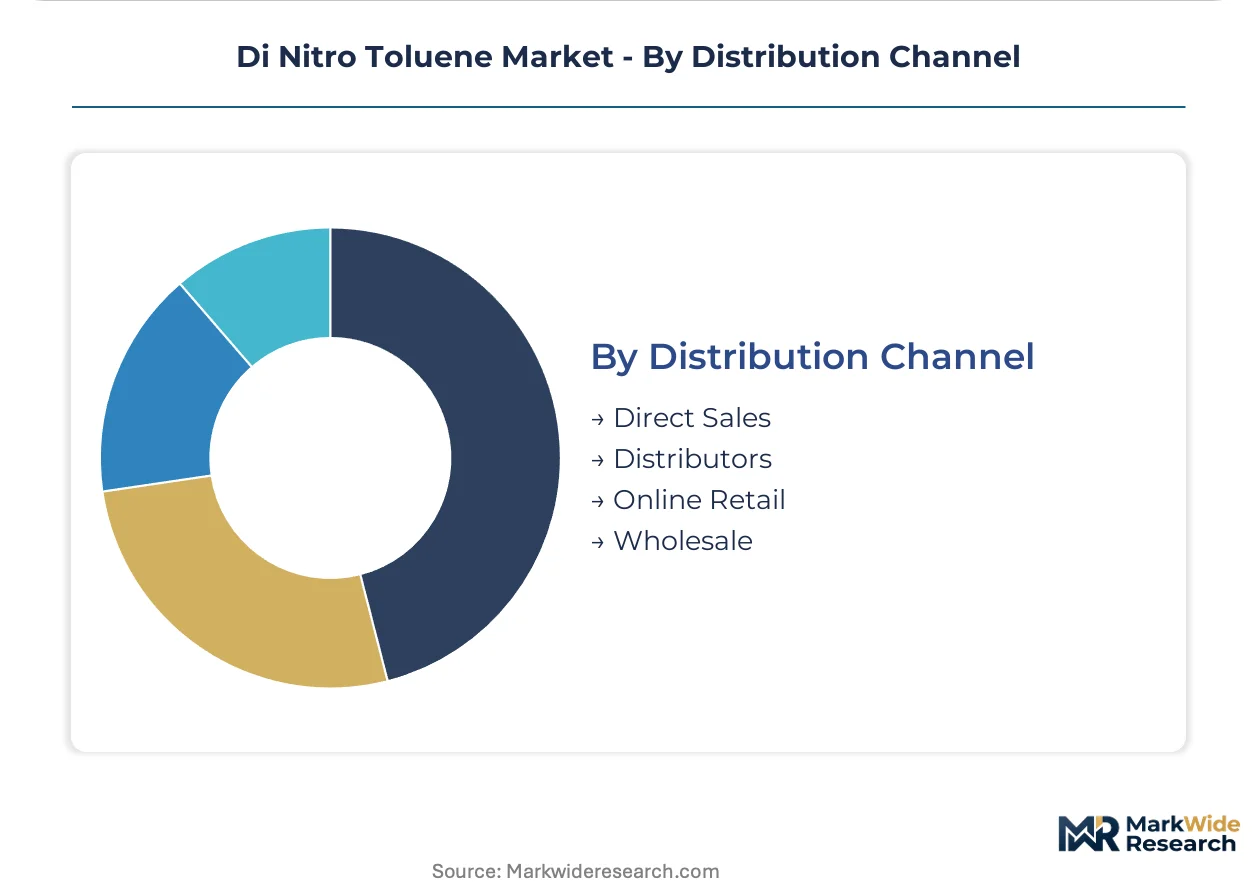
Distribution Channel:
Supply chain configuration reflects handling protocol complexity and customer scale concentration.
- Direct Sales:Integrated aromatics complexes in Ludwigshafen and Krefeld-Uerdingen serve large TDI producers through pipeline and dedicated tanker arrangements. Long-term contracts minimize feedstock volatility exposure.
- Distributors:Specialty chemical distributors manage multi-product logistics for mid-scale explosives manufacturers and pharmaceutical compounders across European and Indian markets.
- Online Retail:Limited to small-volume laboratory and research chemical procurement with stringent documentation requirements.
- Wholesale:Bulk handling of standard-grade material serves industrial solvent and coating intermediate users in Chinese Yangtze River Delta clusters.
Direct Sales moves the largest volumes; Distributors are gaining share fastest on customer fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for explosives-grade material shapes procurement strategies across major consuming regions, while export-oriented aromatics complexes in Germany and China balance regional supply equations through specialized derivative output.
United States
Defense logistics agencies consolidate supplier qualification lists around dual-use purity capabilities for munitions applications. EPA oversight enforces stringent handling protocols and emissions thresholds that elevate compliance costs for producers without captive nitration infrastructure. The Gulf Coast petrochemical corridor anchors standard-grade chemical intermediate production serving domestic TDI precursor demand.
Germany
Bundeswehr procurement expansion drives explosives-grade material orders requiring crystalline stability specifications. ECHA's REACH registration tiering creates compliance pathways that reward producers with continuous purification systems at integrated aromatics complexes. The Ludwigshafen-Krefeld industrial cluster sustains high-purity output for regulated pharmaceutical and defense end uses.
China
Dual carbon goals and MEE wastewater discharge standards tighten operating permits for manufacturers in the Yangtze River Delta cluster. Provincial green manufacturing incentives reward nitration process improvements that reduce nitrous oxide byproduct formation. Domestic defense supply chain localization reduces import dependence for explosives-grade material.
India
CEA-monitored munitions modernization programs expand offtake volumes for high-purity orthodinitrotoluene. The PLI scheme for critical chemicals and explosives precursors offers tariff advantages for domestic production capacity. Gujarat and Maharashtra industrial corridors concentrate new capacity investments serving defense procurement localization.
South Korea
Automotive and construction end-users maintain steady polyurethane foam precursor offtake through tiered supplier contracts. Continuous flow nitration technology adoption accelerates among TDI producers driven by labor cost and safety imperatives. The Ulsan petrochemical complex anchors volume throughput for standard-grade chemical intermediate applications.
Di Nitro Toluene Market Competitive Environment
Listed leaders compete with private specialists across purification capability and regulatory certification dimensions. The vendor base stratifies into three tiers: integrated aromatics majors with captive nitration infrastructure, mid-scale derivative specialists with regional regulatory qualifications, and research chemical distributors serving laboratory and small-batch procurement. Consolidation pressure concentrates among standard-grade producers facing feedstock volatility and multi-jurisdiction compliance timelines. Dominant competitive moves include backward integration into refinery aromatics supply and pharmaceutical-grade qualification investments.
Within the integrated majors tier, BASF SE and Lanxess Corporation exemplify European producers leveraging specialized dinitrotoluene derivatives capacity for regulated end uses. Covestro AG occupies a technology leadership position in controlled nitration processes. Among research chemical distributors, Spectrum Chemical Manufacturing Corp. and Sigma-Aldrich Corporation anchor North American supply for laboratory-grade material with stringent documentation requirements.
| Leading Market Players |
|---|
| Dow Inc. |
| Spectrum Chemical Manufacturing Corp. |
| BASF SE |
| Panoli Intermediates |
| Sigma-Aldrich Corporation |
| Lanxess Corporation |
| Huntsman Corporation |
| Toray Fine Chemicals |
| Covestro AG |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for explosives-grade material signal supply-chain rigidity that amplifies pricing power for producers with captive nitration infrastructure in Germany and India. REACH registration tiering and defense procurement specifications fragment buyer leverage across chemical intermediate and energetic materials channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate standard-grade chemical intermediate transactions. Price differentiation rests on certification grade—pharmaceutical-grade contamination controls command substantial premia over standard TDI precursor material—and volume scale, with tiered pricing separating defense procurement lots from spot-market chemical intermediate purchases. Cost compression in standard-grade output is intensifying because toluene feedstock volatility erodes margins for non-integrated producers. Construction and automotive end-users in South Korea exhibit highest price sensitivity, while India's CEA-monitored defense procurement offices demonstrate lowest sensitivity due to localization mandates.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European TDI producers sourcing mixed isomer streams from Chinese Yangtze River Delta manufacturers. Geographic supply concentration centers on Germany's Ludwigshafen-Krefeld corridor, China's Yangtze River Delta cluster, and India's Gujarat-Maharashtra industrial belt. Raw material dependencies draw from refinery-grade toluene, concentrated sulfuric and nitric acids, and specialized catalyst systems. Single-source vulnerability pervades the explosives-grade channel where India's defense localization requirements restrict qualified supplier pools. Distribution runs through pipeline and dedicated tanker arrangements for integrated majors, with specialty chemical distributors managing multi-product logistics for mid-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized process engineers capable of managing exothermic nitration safety represent the critical capability gap constraining capacity expansion, creating durable competitive moats for incumbents with legacy expertise.
For Market Incumbents: Secure controlled nitration expertise through targeted retention programs and captive training pipelines to defend against talent poaching from emerging Indian capacity. Deepen upstream control over refinery aromatics supply through long-term offtake agreements with integrated petrochemical complexes, mitigating toluene price volatility that compresses standard-grade margins. For New Entrants and Emerging Players: Lead with continuous flow reactor technology adoption to bypass the scale advantages of legacy batch nitration infrastructure and capture labor-cost-sensitive TDI producers in South Korea. Target pharmaceutical-grade qualification pathways as the most penetrable white-space segment, leveraging 18-36 month multi-jurisdiction certification timelines as a competitive barrier against smaller pure-play producers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because REACH tiering, EPA oversight, and China's MEE wastewater standards progressively elevate compliance costs that favor consolidated producers with captive infrastructure. Acquisition focus should center on mid-scale European derivative specialists with existing ECHA registrations and continuous purification systems. Monitor India's PLI scheme disbursement velocity as the signal indicating defense supply chain localization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refinery Aromatics | Long-term toluene supply contracts with Ludwigshafen complexes reduce feedstock volatility exposure. |
| Pharmaceutical-Grade Qualification Investment | FDA and EMA certification unlocks premium margin pools in regulated nitroaromatic intermediate applications. |
| Continuous Flow Nitration Technology Deployment | South Korean TDI producers adopt these systems fastest, driven by labor cost and safety imperatives. |
| Defense Supply Chain Localization | India's PLI scheme offers tariff advantages for domestic capacity serving CEA-monitored munitions offtake. |
| Green Manufacturing Transition | China's MEE emissions trading rewards nitration process improvements reducing nitrous oxide byproduct formation. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with plant managers at integrated aromatics complexes, procurement leads at South Korean TDI producers, distribution channel partners in European specialty chemicals, and technical R&D directors at explosives manufacturers providing operational validation. Secondary sources encompassed customs and trade data from India and Germany, Cefic chemical industry reports, SEC 10-K filings from listed aromatics majors, and ECHA registration databases. Bottom-up capacity and utilization estimates were triangulated against top-down demand projections from automotive and construction end-use sectors.
Across the analysis window, volume and value outputs reflect segmentation modeling across grade tier, end-use industry, regional production hub, and isomer composition dimensions. CAGRs were derived from trend extrapolation of defense procurement modernization cycles and TDI precursor demand patterns, with cross-validation against historical aromatics complex utilization rates and regulatory enforcement intensity indices.
Forecasts assume regulatory continuity in REACH, EPA, and MEE regimes; material policy shifts would require re-modeling. Specific risk factors include abrupt toluene price spikes from crude oil volatility, accelerated pharmaceutical-grade substitution pathways, and unforeseen environmental enforcement suspensions in China's Yangtze River Delta. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
P-Ethylphenol Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Glyoxal Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
Paint Remover Market
Chemicals
Cupric Chloride Market
Chemicals
Acid Anhydrides Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Ammonia Market
Chemicals
Caustic Soda Market
Chemicals
Europe Methanol Market
Chemicals
Brazil Methanol Market
Chemicals
Detergent Alcohols Market
Chemicals
Fluorine Derivatives Market
Chemicals
Global Glycine Market