
 Fluoroboric Acid Market | 2026-2036
Fluoroboric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Fluoroboric Acid Market Analysis
Reagent-grade fluoroboric acid is redrawing competitive positioning as semiconductor fabs and pharmaceutical laboratories tighten purity specifications. Solvay leverages its European fluorochemical infrastructure to sustain supply security for high-purity grades. Honeywell International Inc anchors North American demand through integrated fluorspar-to-acid production. DuPont de Nemours, Inc. specializes in application-specific formulations for advanced electronics etching.
Fluoroboric acid (HBF4) is an inorganic compound produced by reacting boric acid with hydrofluoric acid, typically supplied as a colorless aqueous solution with concentrations ranging from 40% to 50% by weight; it serves primarily as a metal surface treatment agent, electroplating bath additive, and catalyst in organic synthesis. Electroplating applications dominate volume consumption across automotive and electronics supply chains, while laboratory-grade and reagent-grade segments capture disproportionate margin pools from pharmaceutical quality control and semiconductor wafer processing. Packaging configurations gravitate toward IBC totes for industrial electroplating operations and borosilicate bottles for reagent-grade distribution to analytical laboratories.
EPA hazardous waste regulations and OSHA permissible exposure limits constrain domestic manufacturing practices and transportation logistics for concentrated fluoroboric acid in the United States. REACH registration requirements and CLP hazard classification rules in Europe impose compliance costs that favor producers with established dossier capabilities. ECHA substance evaluation cycles will determine whether downstream users must seek authorization for specific applications. Stakeholders should monitor regulatory divergence between jurisdictions when allocating capital toward capacity expansion or product registration investments.
Market Dynamics
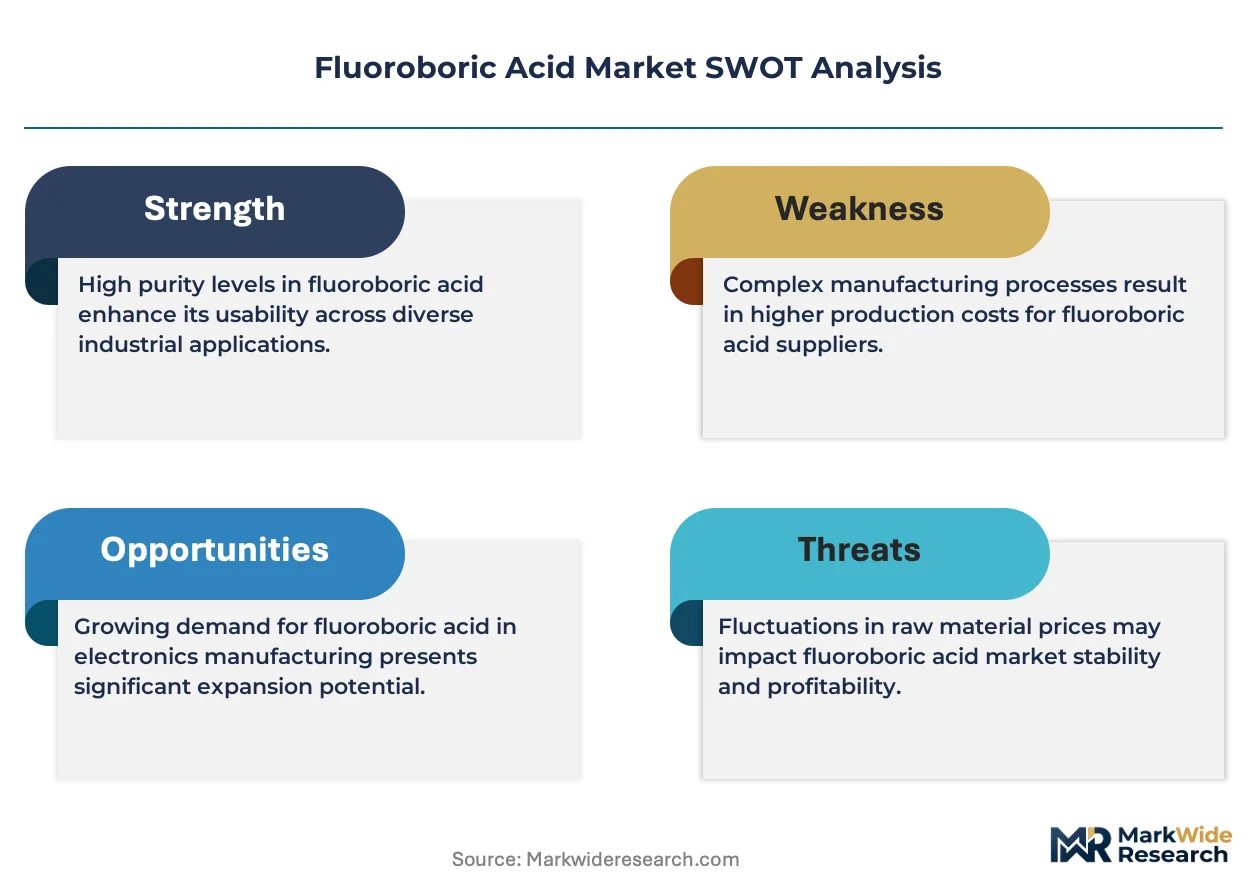
Electronics-grade purity specifications are compressing margins for commodity producers while concentrating volume with integrated fluorspar-to-acid operators capable of sub-ppm impurity control.
Growth Catalysts
- REACH chemical safety mandates:European electroplating operations are upgrading bath chemistries to fluoroboric acid formulations with documented environmental profiles, accelerating substitution of chromic acid alternatives.
- China's electroplating hub expansion:Domestic automotive and semiconductor supply chains in Jiangsu and Guangdong provinces are absorbing industrial-grade volumes for surface treatment applications.
- Sub-10nm etching requirements:Advanced logic node production is mandating ultra-high-purity fluoroboric acid for wafer cleaning protocols, pulling reagent-grade specifications upward.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar mining concentrates in Mexico, China, and Mongolia, exposing processors to export quota volatility and geopolitical disruption.
- OSHA permissible exposure limits:United States manufacturing facilities face stringent worker safety thresholds that elevate ventilation and PPE compliance costs above Asian competitor baselines.
- Hydrofluoric acid substitution in etching:Buffered oxide etch formulations and dry plasma processes are capturing share in legacy semiconductor cleaning applications.
Strategic Opportunities
- Indian pharmaceutical API manufacturing:Quality control laboratories serving generic drug exporters present underpenetrated demand for ACS-grade fluoroboric acid in heavy metal testing protocols.
- EU Green Deal industrial decarbonization incentives:Electroplating operations modernizing for energy efficiency qualify for transition financing that favors closed-loop bath chemistries including fluoroboric acid systems.
- Direct-to-laboratory e-procurement platforms:Reagent-grade distributors are bypassing traditional chemical supply houses to serve pharmaceutical QC labs with borosilicate bottle configurations and lot-specific certificates.
Industry Challenges
- Analytical chemist scarcity:Semiconductor fabs and pharmaceutical laboratories face recruitment gaps for specialists capable of validating sub-ppb impurity specifications in incoming acid lots.
- ECHA authorization timelines:Downstream electroplating users confront extended substance evaluation cycles that delay process validation and customer qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluoroboric Acid Market |
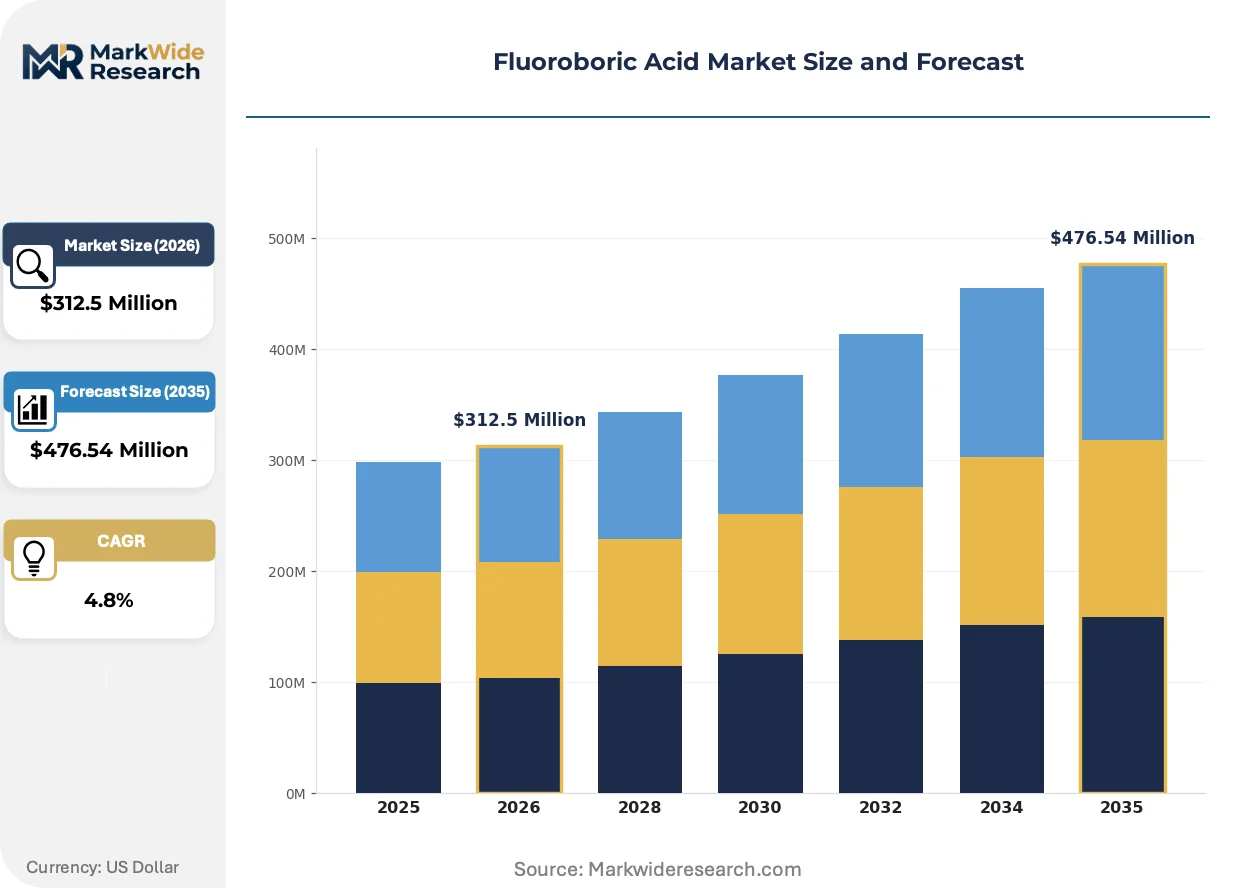
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Electroplating, Textile, Ceramics, Glass Manufacturing End User: Aerospace, Automotive, Electronics, Pharmaceutical Purity: Industrial Grade, Laboratory Grade, Reagent Grade, Technical Grade Packaging Type: Drums, Bottles, Bags, IBC Totes |
| Companies Covered | DuPont de Nemours, Inc., Merck KGaA, Solvay, General Chemical Corp., Atotech USA, Inc., BASF SE, 3M Company, Derivados del Flúor, Honeywell International Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluoroboric Acid Market Emerging Trajectories
Continuous purification technologies and closed-loop manufacturing systems are redefining competitive capability boundaries between commodity electroplating suppliers and electronics-grade specialists.
Membrane electrodialysis is supplanting traditional distillation for fluoride impurity removal in high-purity fluoroboric acid production. Taiwan-based semiconductor foundries and Korean memory manufacturers have adopted electrodialysis-treated acid for 5nm and below node processing. This purification shift is compressing the supplier base to operators with capital-intensive membrane infrastructure.
EPA hazardous waste generator regulations are tightening manifest requirements for spent fluoroboric acid bath solutions in the United States. Electroplating job shops face elevated disposal costs and liability exposure, prompting consolidation toward integrated captive treatment facilities. Automotive coating operations in Michigan and Ohio are most affected, with several facilities transitioning to centralized waste recovery contracts.
Certificate-of-analysis-driven procurement is displacing spot-market purchasing for reagent-grade fluoroboric acid. Pharmaceutical quality control departments now require lot-specific ICP-MS trace metal data prior to release, extending vendor qualification cycles. This behavioral shift is most visible among generic API manufacturers in India and contract research organizations in Western Europe.
Fluoroboric Acid Market Segmentation
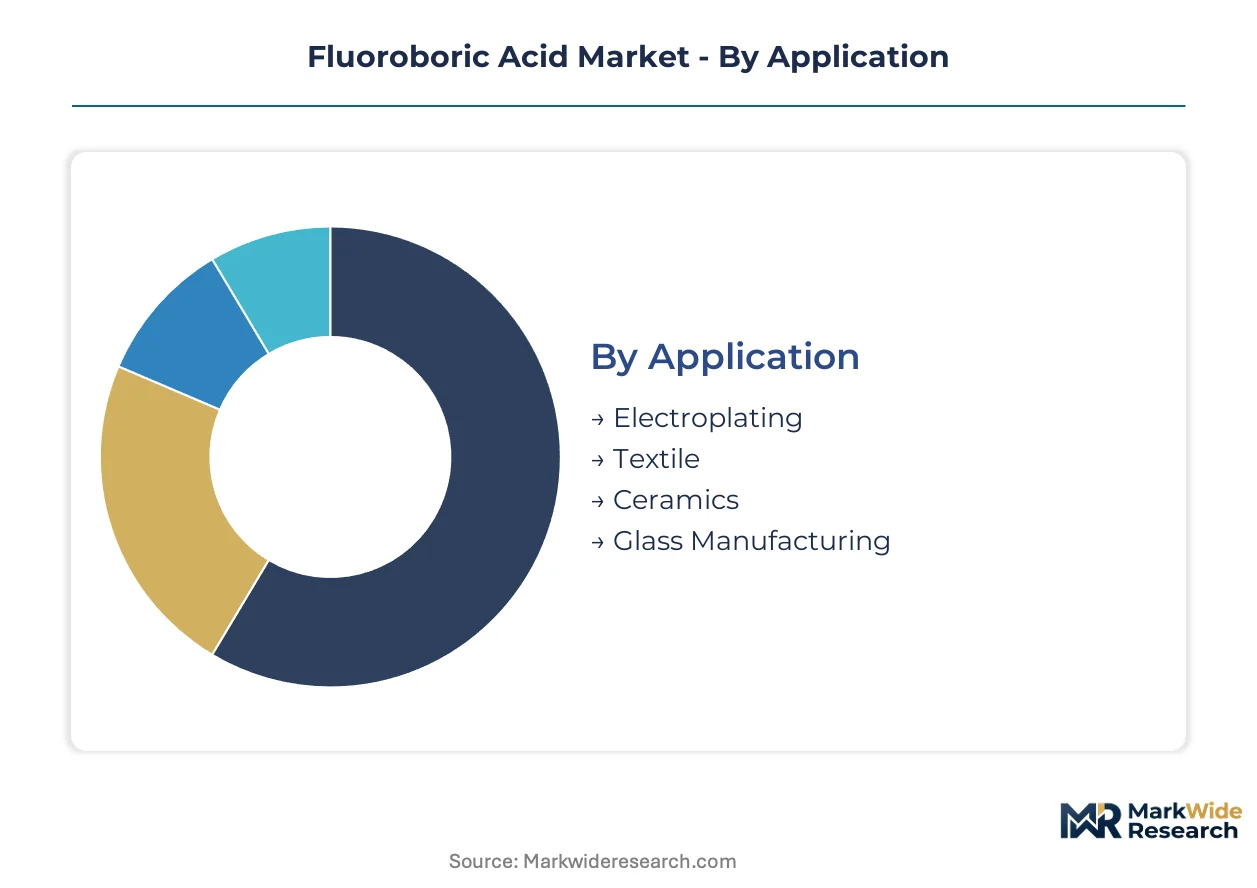
Fluoroboric acid demand fragments across purity tiers and packaging configurations that reflect divergent regulatory exposure and customer technical requirements. Substitution threats from alternative chemistries and process technologies vary sharply by segment, reshaping investment priorities for producers.
Application:
Electroplating formulations face the most acute substitution pressure as chromic acid alternatives and dry plasma processes erode volume in legacy surface treatment markets.
- Electroplating:Bath additive for metal surface finishing in automotive and electronics supply chains, absorbing industrial-grade volumes through captive treatment facilities in Michigan and Ohio. EPA hazardous waste generator regulations are elevating disposal costs and consolidating demand toward integrated operators with closed-loop recovery systems.
- Textile:Catalyst for resin finishing and flame-retardant treatments, serving synthetic fiber producers with technical-grade specifications. Jiangsu province manufacturers are absorbing volumes amid China's electroplating hub expansion for domestic automotive supply chains.
- Ceramics:Fluxing agent in specialty ceramic production, requiring controlled fluoride content for thermal property modification.
- Glass Manufacturing:Surface treatment for optical glass and specialty flat glass, demanding precise etching control.
Electroplating anchors the volume base while textile applications gain share at the steepest rate amid resin finishing demand expansion.
End User:
Customer cost tiers stratify sharply between commodity industrial purchasers and premium-certified laboratory buyers with divergent procurement protocols.
- Electronics:Semiconductor fabs and printed circuit board manufacturers mandate sub-ppm impurity specifications for wafer cleaning and etching protocols. Taiwan-based foundries and Korean memory manufacturers have adopted electrodialysis-treated acid for advanced node processing, compressing the supplier base to operators with membrane infrastructure.
- Pharmaceutical:Quality control laboratories require ACS-grade fluoroboric acid with lot-specific ICP-MS trace metal data for heavy metal testing in generic API manufacturing. Certificate-of-analysis-driven procurement is displacing spot-market purchasing, extending vendor qualification cycles for Indian pharmaceutical exporters.
- Automotive:Coating operations and electroplating job shops for decorative and functional finishes on components.
- Aerospace:Precision surface treatment for high-performance alloys and specialized component finishing.
Electronics commands the premium pricing tier while pharmaceutical QC laboratories are expanding most quickly under tightening regulatory validation requirements.
Purity:
Supply concentration favors integrated fluorspar-to-acid operators capable of sub-ppm impurity control for the highest specification tiers.
- Reagent Grade:Ultra-high-purity specification for semiconductor wafer processing and pharmaceutical analytical applications, requiring membrane electrodialysis purification and borosilicate bottle packaging. Solvay leverages European fluorochemical infrastructure to sustain supply security for this tier.
- Industrial Grade:Standard concentration aqueous solution for electroplating bath formulations and metal surface treatment, typically supplied in IBC totes for high-volume operations. Honeywell International Inc anchors North American demand through integrated fluorspar-to-acid production.
- Laboratory Grade:Intermediate purity for educational and routine analytical applications with documented specifications.
- Technical Grade:Basic purity level for industrial processes where precise impurity control is less critical.
Industrial grade sustains the volume foundation while reagent grade climbs the fastest on semiconductor node advancement and pharmaceutical QC expansion.
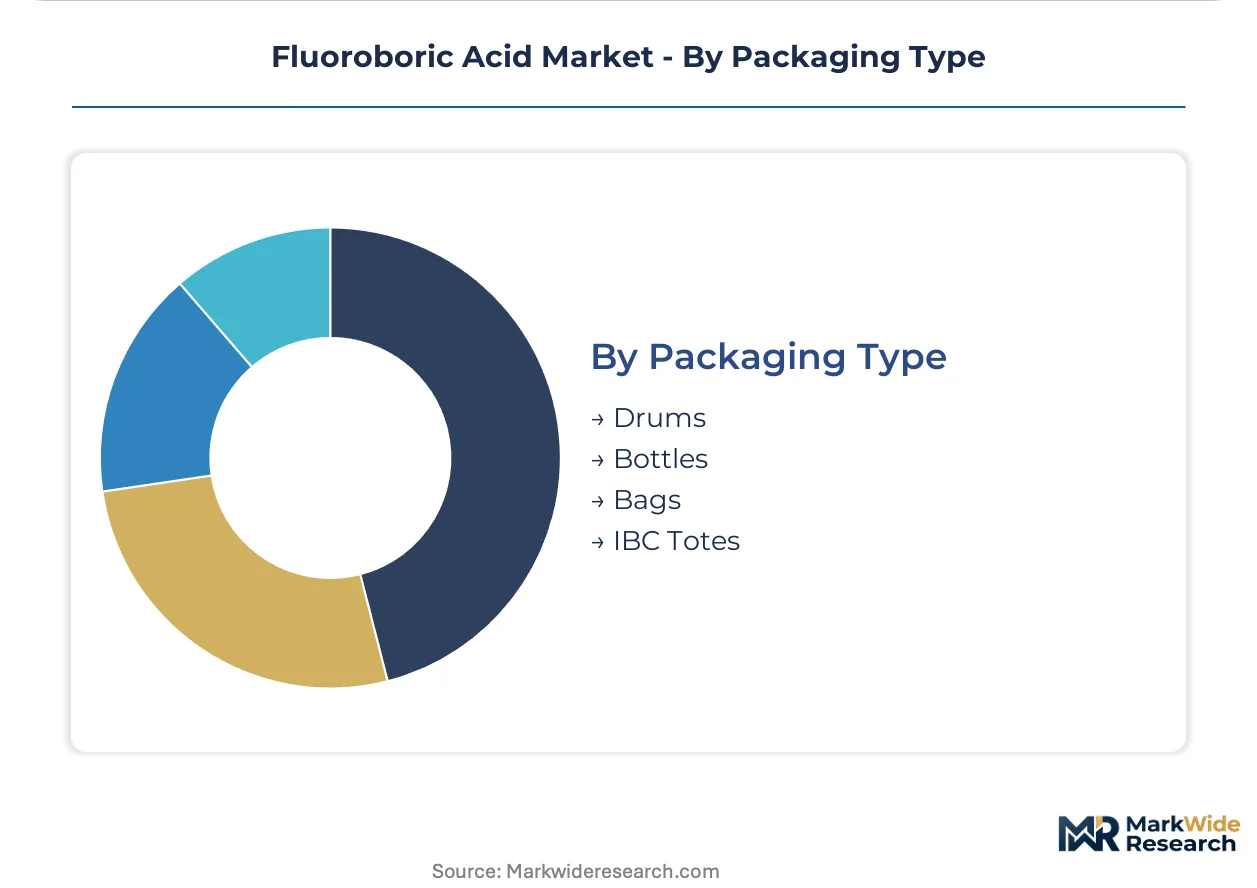
Packaging Type:
Container selection reflects the tension between bulk logistics efficiency and contamination risk management across customer segments.
- IBC Totes:Intermediate bulk containers for industrial electroplating operations consuming high volumes with centralized bath management and waste recovery contracts.
- Bottles:Borosilicate glass configurations for reagent-grade distribution to analytical laboratories, with lot-specific certificates required for pharmaceutical QC release protocols.
- Drums:Standard industrial packaging for medium-volume electroplating job shops and metal finishing operations.
- Bags:Flexible containment for specific powder or concentrated formulations in select industrial applications.
IBC totes dominate industrial volume while borosilicate bottles are gaining share fastest through direct-to-laboratory e-procurement platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows concentrate fluoroboric acid supply in integrated fluorspar-to-acid corridors, with China absorbing the largest import share for electroplating expansion while the United States and Germany sustain trade surpluses in high-purity grades.
China
Jiangsu and Guangdong provinces drive electroplating hub expansion for domestic automotive and semiconductor supply chains. MEE environmental compliance rules tighten wastewater discharge standards for metal finishing operations. Suzhou and Shenzhen industrial clusters absorb industrial-grade volumes through centralized captive treatment facilities serving tier-one automotive suppliers.
United States
EPA hazardous waste generator regulations elevate disposal costs for spent bath solutions in Michigan and Ohio automotive coating corridors. OSHA permissible exposure limits constrain manufacturing practices and transportation logistics for concentrated acid. Detroit-area electroplating operations consolidate toward integrated waste recovery contracts under stricter manifest requirements.
Germany
REACH registration requirements and CLP hazard classification rules impose compliance costs favoring producers with established dossier capabilities. ECHA substance evaluation cycles determine downstream authorization timelines for electroplating applications. North Rhine-Westphalia's industrial chemical corridor anchors European supply security for high-purity grades serving pharmaceutical QC laboratories.
India
Quality control laboratories serving generic drug exporters present expanding demand for ACS-grade fluoroboric acid in heavy metal testing protocols. BIS certification requirements tighten specifications for analytical reagents used in pharmaceutical exports. Maharashtra and Gujarat pharmaceutical clusters extend vendor qualification cycles under certificate-of-analysis-driven procurement protocols.
South Korea
Semiconductor foundries mandate ultra-high-purity specifications for sub-10nm wafer cleaning protocols. MFDS pharmaceutical regulations align with international standards for analytical reagent import certification. Gyeonggi-do and Chungcheongnam-do semiconductor manufacturing complexes pull electrodialysis-treated acid volumes from qualified membrane infrastructure operators.
Fluoroboric Acid Market Vendor Landscape
Concentration sits with integrated fluorspar-to-acid operators capable of sub-ppm impurity control, compressing margins for commodity electroplating suppliers. The supplier base stratifies across three archetypes: European fluorochemical infrastructure holders, North American integrated fluorspar processors, and application-specific formulation specialists. Dominant competitive moves include membrane electrodialysis capacity expansion for electronics-grade purification and closed-loop manufacturing system deployment under tightening EPA waste regulations.
Among diversified chemical conglomerates, Solvay and BASF SE represent the European infrastructure archetype with established fluorochemical production networks. Honeywell International Inc anchors the North American integrated processing tier through captive fluorspar supply chains. DuPont de Nemours, Inc. occupies the application-specific formulation position, with Merck KGaA exemplifying the laboratory-grade distribution archetype serving pharmaceutical QC protocols.
| Leading Market Players |
|---|
| DuPont de Nemours, Inc. |
| Merck KGaA |
| Solvay |
| General Chemical Corp. |
| Atotech USA, Inc. |
| BASF SE |
| 3M Company |
| Derivados del Flúor |
| Honeywell International Inc |
| Others |
Supply Flow & Price Mechanics
REACH registration dossiers and CLP hazard classifications gate both supplier qualification and price differentiation simultaneously, compressing margins for commodity electroplating grades while elevating premiums for membrane-electrodialysis-purified electronics specifications. This regulatory architecture concentrates pricing power with integrated fluorspar-to-acid operators capable of sub-ppm impurity documentation.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in fluoroboric acid procurement. Reagent-grade specifications with lot-specific ICP-MS certificates command substantial premiums over industrial-grade IBC tote volumes, with price differentiation driven by certification grade and volume scale. Cost compression in standard-grade electroplating formulations is intensifying because of membrane electrodialysis adoption by Taiwanese foundries. Pharmaceutical QC laboratories exhibit the lowest price sensitivity due to regulatory validation requirements, while automotive coating job shops face acute margin pressure from EPA waste disposal cost escalation.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for acid-grade fluorspar shipments originating from Mexican and Mongolian mining concentrations. Fluoroboric acid production draws from concentrated fluorspar supply in Mexico, China, and Mongolia, with hydrofluoric acid and boric acid as critical chemical inputs. Single-source vulnerability in acid-grade fluorspar exposes processors to export quota volatility from Chinese state-owned mining enterprises. Distribution runs through integrated captive treatment facilities for industrial electroplating volumes and direct-to-laboratory e-procurement platforms for reagent-grade shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated semiconductor foundries and pharmaceutical QC laboratory networks, fragmenting price-setting authority among smaller electroplating job shops. This concentration justifies targeted capability investments by supply-side stakeholders.
For Market Incumbents: Fortify membrane electrodialysis capacity in Taiwan and South Korea to defend against dry plasma etching substitution threats in sub-10nm semiconductor processing. Pursue backward integration into acid-grade fluorspar through long-term offtake agreements with Mexican mining operators, securing raw material cost stability against Chinese export quota volatility. For New Entrants and Emerging Players: Lead with ACS-grade fluoroboric acid certification for Indian pharmaceutical API quality control laboratories, where certificate-of-analysis-driven procurement has extended vendor qualification cycles and created white-space for specialized entrants. Target Maharashtra and Gujarat generic drug manufacturing clusters with borosilicate bottle configurations and lot-specific ICP-MS trace metal documentation. For Investors and Strategic Acquirers: ECHA substance evaluation timelines reshaping the acquisition landscape favor targets with established REACH dossier capabilities and closed-loop manufacturing systems. Long-term viability centers on operators with integrated fluorspar-to-acid infrastructure capable of serving both electronics-grade purity specifications and EPA-compliant waste recovery contracts. The signal to monitor is ECHA authorization decisions for electroplating applications, which will determine downstream user switching costs and incumbent pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrodialysis Capacity Expansion | Taiwanese foundries require sub-ppm purity for 5nm node processing, compressing qualified supplier bases. |
| Backward Integration into Fluorspar Mining | Mexican acid-grade fluorspar offtake agreements reduce exposure to Chinese export quota volatility. |
| Closed-Loop Manufacturing System Deployment | EPA hazardous waste generator regulations in Michigan and Ohio elevate disposal liability for job shops. |
| Direct-to-Laboratory E-Procurement Platform Launch | Indian pharmaceutical QC laboratories now require lot-specific certificates prior to reagent release. |
| REACH Dossier Capability Investment | ECHA substance evaluation cycles determine authorization timelines for European electroplating users. |
Methodological Framework
Operator-level perspectives from fluoroboric acid plant managers, electroplating procurement leads at automotive OEMs, semiconductor fab chemical supply directors, and pharmaceutical QC laboratory managers anchored the qualitative base. Primary interview insights combined with secondary validation from customs trade data, American Chemistry Council reports, SEC 10-K filings, and ECHA substance evaluation databases. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verified demand estimates.
Sensitivity analysis across fluorspar price volatility scenarios, regulatory authorization timelines, and semiconductor node advancement rates informed the projection framework. Segmentation dimensions modeled include purity grade tier, end-use industry application, packaging configuration format, and regional production hub concentration. CAGRs derived from volume trajectory analysis incorporating electroplating bath chemistry substitution rates and pharmaceutical QC laboratory expansion patterns.
Underlying assumptions cover REACH registration continuity, acid-grade fluorspar export quota stability, and membrane electrodialysis technology diffusion curves, with deviation risk concentrated in ECHA authorization delays and hydrofluoric acid substitution acceleration in semiconductor etching. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Inorganic Chemicals Market
Chemicals
Egypt Construction Chemicals Market
Chemicals
South America Isoamyl Acetate Market
Chemicals
Scouring Agents Market
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Valeryl Chloride Market
Chemicals
Asia-Pacific Non-Phthalate Plasticizers Market
Chemicals
Laboratory Chemicals Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Pyromellitic Dianhydride Market
Chemicals
Medical Grade Zinc Sulfate Market
Chemicals
Barbituric Acid Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Sodium Methoxide Market
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
Allyl Alcohol Market