
 Triethylaluminum Market | 2026-2036
Triethylaluminum Market Size, Share, and Industry Trends Forecast 2026-2036
Triethylaluminum Market Analytics
Direct supply contracts between triethylaluminum manufacturers and polymer producers is reconfiguring traditional distributor relationships in the organometallic chemicals channel. Albemarle leverages its integrated bromine-to-alkylaluminum chain to sustain captive raw material advantages across Texas and Louisiana production sites. Sasol OandS anchors southern African supply through its Secunda petrochemical complex while competing on Fischer-Tropsch-derived feedstock integration.
Triethylaluminum, an organometallic compound with formula Al(C₂H₅)₃, exists as a colorless pyrophoric liquid that ignites spontaneously in air and requires handling under inert atmosphere with nitrogen or argon blanket systems. Industrial grade material dominates volume consumption as the co-catalyst backbone for Ziegler-Natta polymerization systems producing high-density polyethylene and isotactic polypropylene. Chemical synthesis applications represent the fastest-expanding segment as pharmaceutical manufacturers adopt alkylaluminum reagents for stereoselective carbon-carbon bond formation in active pharmaceutical ingredient routes. Semiconductor manufacturing grade commands premium positioning due to parts-per-billion purity requirements and dedicated packaging protocols.
OSHA process safety management standards govern pyrophoric chemical handling thresholds at US manufacturing and user facilities while REACH registration mandates full toxicological dossiers for European volume-based market access. China's GB standards through SAMR alignment impose parallel hazardous chemical classification and storage regulations on domestic and imported material. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that could redirect fluoropolymer catalyst demand toward alternative polymer systems requiring different co-catalyst specifications.
Market Dynamics
Polymer producers are consolidating Ziegler-Natta catalyst procurement through direct triethylaluminum supply agreements, bypassing traditional chemical distributors and compressing channel margins across the organometallic value chain.
Growth Catalysts
- High-density polyethylene capacity expansion:Petrochemical complexes in China and the United States are commissioning new gas-phase reactors requiring continuous triethylaluminum co-catalyst feed.
- REACH registration completion:Full toxicological dossier acceptance by ECHA enables volume-based European market access for registered suppliers.
- Semiconductor-grade purification advances:Parts-per-billion purity protocols now support advanced node chip manufacturing in Taiwan and South Korea.
Market Restraints
- Ethylene feedstock volatility:Crude oil and natural gas liquid price swings directly compress triethylaluminum producer margins.
- Supply concentration risk:Over half of merchant capacity concentrates along the US Gulf Coast hurricane corridor.
- Metallocene catalyst substitution:Single-site catalyst systems for specialty polyethylene grades reduce Ziegler-Natta co-catalyst intensity.
Strategic Opportunities
- India petrochemical buildout:Reliance Industries and Indian Oil Corporation are expanding integrated polyethylene complexes requiring captive alkylaluminum supply.
- Pharmaceutical stereoselective synthesis:Carbon-carbon bond formation in active pharmaceutical ingredient routes opens high-margin chemical synthesis demand.
- China dual carbon policy alignment:Energy-efficient polymerization catalyst systems receive preferential project approval under MIIT green manufacturing guidelines.
Industry Challenges
- Pyrophoric handling certification:OSHA process safety management compliance requires specialized technician training programs exceeding twelve-month qualification timelines.
- Inert atmosphere infrastructure:Nitrogen blanket systems and argon-purged transfer equipment demand capital deployment at user facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triethylaluminum Market |
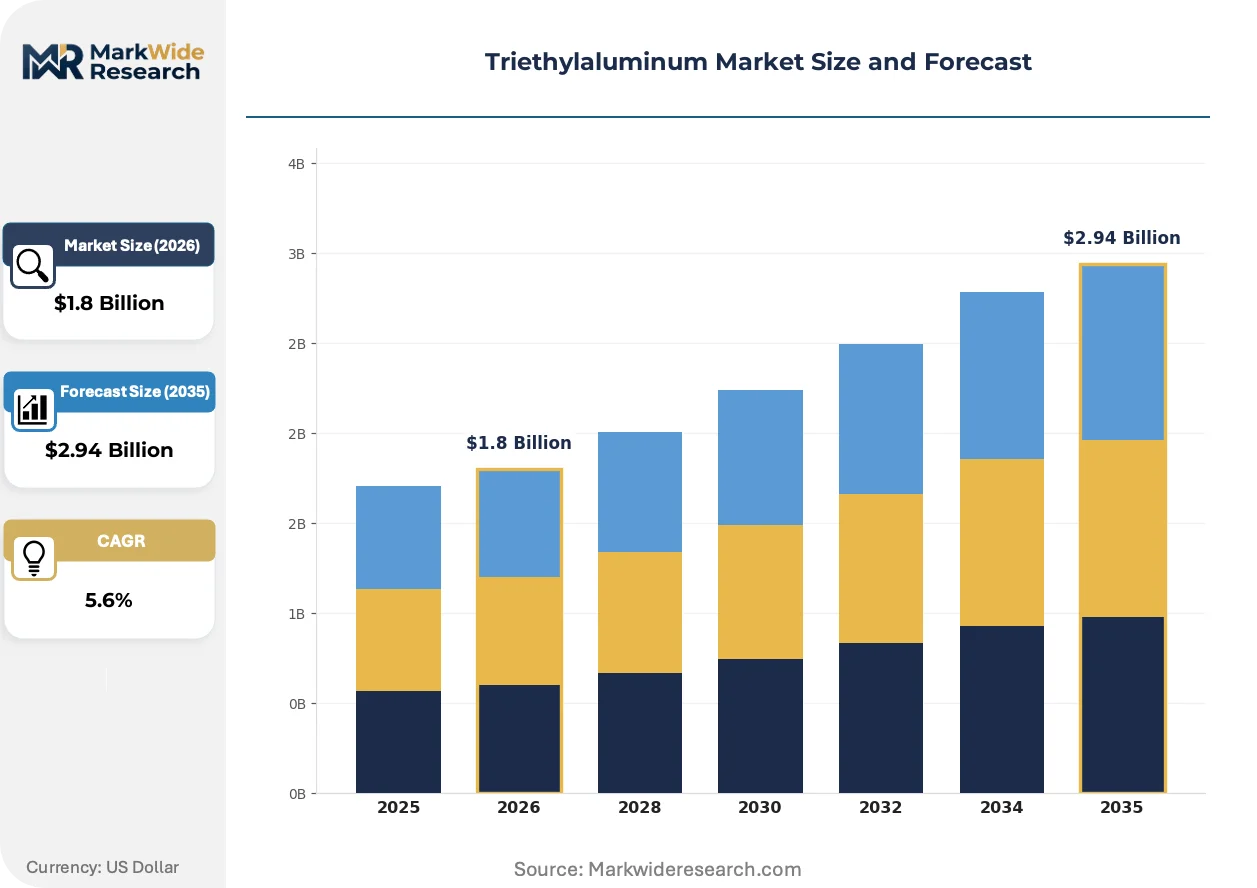
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Pharmaceutical Grade, Specialty Grade Application: Polymer Production, Chemical Synthesis, Catalyst, Semiconductor Manufacturing End User: Chemical Industry, Electronics, Pharmaceuticals, Research Institutions Packaging Type: Bulk Containers, Drums, Cylinders, Jerricans |
| Companies Covered | Albemarle, Gulbrandsen, Sasol OandS, SOCC, Nouryon, AkzoNobel, Nippon Aluminum Alkyls, Tianjin Lianli Chemical, Lanxess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triethylaluminum Market Evolving Landscape
Digital process control systems and advanced purification technologies are reconfiguring how triethylaluminum is manufactured, distributed, and consumed across polymer and electronics supply chains.
Continuous flow reactor technology is virtualizing traditional batch organometallic synthesis. Albemarle and Sasol OandS are retrofitting Texas and Secunda facilities with real-time spectroscopic monitoring and automated temperature-pressure control loops. This virtualization compresses batch-to-batch variability, reduces in-process inventory, and enables just-in-time delivery contracts with polyethylene producers.
REACH authorization requirements for Substances of Very High Concern are tightening handling documentation across European polymer facilities. ECHA mandates updated safety data sheets and exposure scenario communication down the supply chain. German chemical parks in Ludwigshafen and Marl are investing in dedicated pyrophoric chemical handling infrastructure to maintain market access.
Direct manufacturer-to-producer contracting is displacing regional distributor networks. Polymer producers in China, Germany, and the United States now negotiate multi-year supply agreements with volume commitments and price collars. This channel compression eliminates distributor markups but requires producers to maintain in-house logistics capabilities for hazardous material transport under ADR and DOT regulations.
Triethylaluminum Market Segmentation
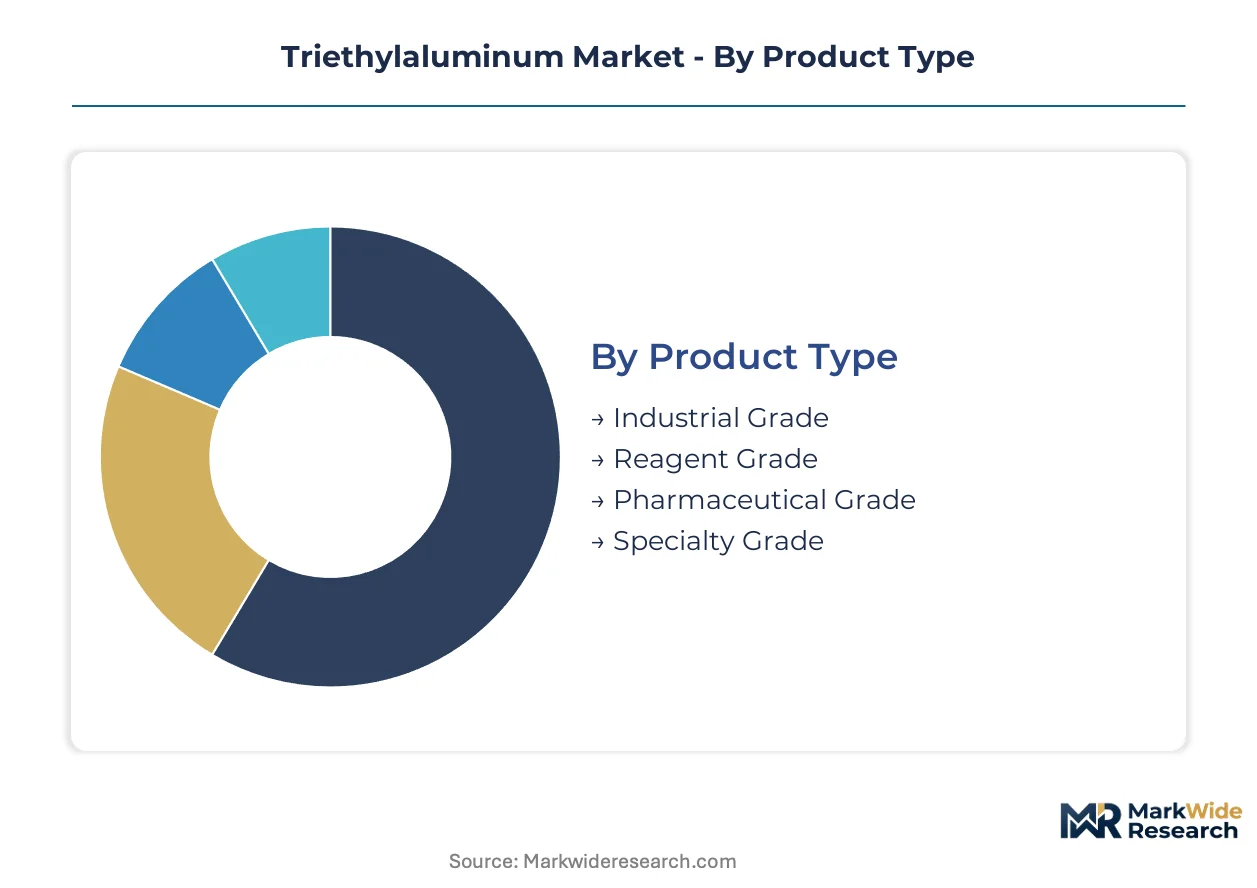
Triethylaluminum segmentation reflects divergent purity specifications and handling protocols across polymer catalyst, pharmaceutical synthesis, and semiconductor manufacturing value chains. Each grade commands distinct pricing tiers based on impurity thresholds measured in parts-per-million versus parts-per-billion scales.
Product Type:
Mature industrial formulations anchor volume consumption while emerging high-purity grades capture expanding semiconductor and pharmaceutical applications.
- Industrial Grade:Formulations with 95-98% purity serve as the workhorse co-catalyst for Ziegler-Natta polyethylene and polypropylene systems. Demand concentrates at integrated petrochemical complexes in China, Germany, and the United States where continuous reactor feeds require bulk volume rather than extreme purity.
- Reagent Grade:99% minimum purity specifications support laboratory-scale organic synthesis and pilot plant operations. Research institutions and contract manufacturing organizations in Japan and South Korea drive procurement for method development in carbon-carbon bond formation protocols.
- Pharmaceutical Grade:Ultra-low halide and trace metal specifications meet GMP requirements for active pharmaceutical ingredient manufacturing.
- Specialty Grade:Custom-formulated variants with modified viscosity or thermal stability profiles address niche polymerization conditions.
Industrial Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity catalyst consumption from premium electronics-grade positioning.
- Polymer Production:Ziegler-Natta co-catalyst applications dominate tonnage consumption across high-density polyethylene and isotactic polypropylene manufacturing. Gas-phase reactor expansions in China and the United States sustain continuous feed requirements for this mature application segment.
- Chemical Synthesis:Stereoselective carbon-carbon bond formation in pharmaceutical intermediate routes represents the most rapidly expanding application category. Contract research organizations in India and Switzerland are scaling alkylaluminum-mediated reactions from gram to kilogram quantities.
- Catalyst:Specialty catalyst formulations beyond standard Ziegler-Natta systems include metallocene activators and oligomerization initiators.
- Semiconductor Manufacturing:Parts-per-billion purity requirements support atomic layer deposition and chemical vapor deposition processes for advanced node chip fabrication.
Polymer Production retains volume leadership; Chemical Synthesis holds the steepest expansion curve.
End User:
Customer type segmentation distinguishes between process-scale commodity buyers and precision-scale specialty purchasers.
- Chemical Industry:Integrated petrochemical producers and specialty chemical manufacturers constitute the largest end-user category. Major polyethylene producers in Texas, Louisiana, and the German chemical park cluster negotiate direct supply agreements with alkylaluminum manufacturers.
- Electronics:Semiconductor foundries and display panel manufacturers require dedicated packaging and logistics protocols for pyrophoric high-purity material. Taiwan and South Korean fabrication facilities source through qualified suppliers with established cleanroom transfer capabilities.
- Pharmaceuticals:Multinational drug manufacturers and contract development organizations utilize alkylaluminum reagents for chiral synthesis steps.
- Research Institutions:University chemistry departments and national laboratories represent fragmented, small-volume demand with high specification variability.
Chemical Industry retains volume leadership; Electronics holds the steepest expansion curve.
Packaging Type:
Supply concentration in bulk formats contrasts with specialized containment for pyrophoric hazard mitigation.
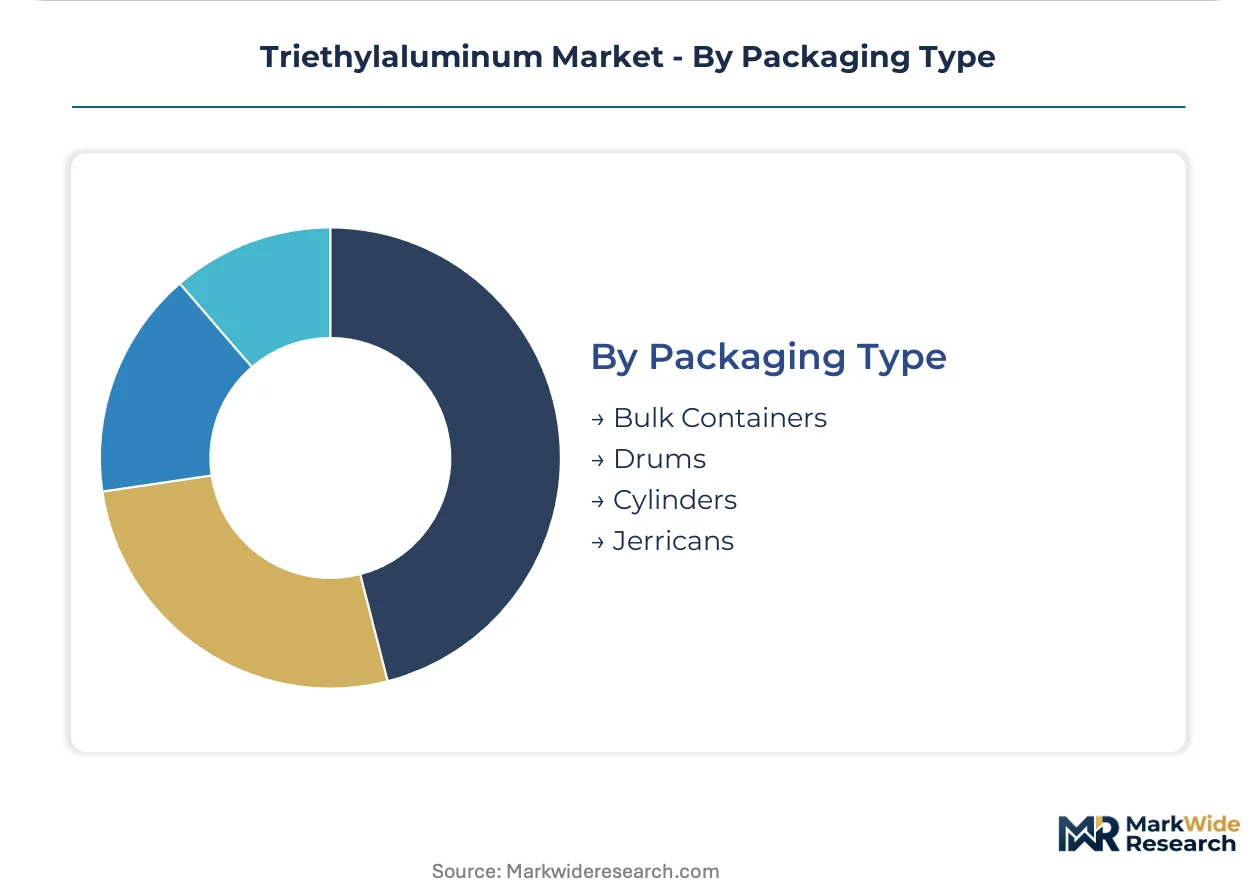
- Bulk Containers:Stainless steel ISO tanks and dedicated tanker trucks serve high-volume polymer producers with integrated unloading infrastructure. US Gulf Coast and Rotterdam-Antwerp corridor facilities handle the majority of bulk transfers under nitrogen blanket systems.
- Drums:Steel drums with internal coatings and sealed head assemblies accommodate mid-scale chemical synthesis operations. German chemical parks in Ludwigshafen and Marl maintain drum-handling infrastructure for pyrophoric organometallics.
- Cylinders:High-pressure steel cylinders with specialized valve configurations support semiconductor manufacturing precision delivery.
- Jerricans:Small-format containers serve laboratory and pilot-scale requirements with limited shelf-life demands.
Bulk Containers retain volume leadership; Cylinders hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel and Rotterdam-Antwerp pipeline corridor anchor transatlantic triethylaluminum logistics, while China's Ningbo-Zhoushan port complex handles the majority of Asian alkylaluminum imports under nitrogen-blanket protocols.
United States
Texas and Louisiana host integrated polyethylene complexes requiring continuous Ziegler-Natta co-catalyst feeds. OSHA process safety management standards govern pyrophoric handling thresholds at manufacturing and user facilities along the Gulf Coast. The Houston-Baytown-Port Arthur corridor concentrates merchant alkylaluminum capacity within hurricane exposure zones.
Germany
Ludwigshafen and Marl chemical parks maintain dedicated pyrophoric handling infrastructure for REACH-registered material. ECHA mandates updated safety data sheets and exposure scenario communication down the polymer supply chain. BASF-operated sites in the Rhine-Neckar metropolitan region negotiate direct triethylaluminum supply agreements bypassing distributor networks.
China
Ningbo-Zhoushan and Shanghai Yangshan ports handle bulk organometallic imports under SAMR-aligned GB standards for hazardous chemical classification. MIIT green manufacturing guidelines grant preferential project approval to energy-efficient polymerization catalyst systems. Sinopec and PetroChina complexes in Zhenhai and Daqing commission new gas-phase reactors requiring captive alkylaluminum supply.
South Korea
Yeosu and Ulsan petrochemical complexes drive Ziegler-Natta co-catalyst consumption for export-oriented polyethylene production. MFDS-aligned industrial chemical regulations parallel REACH documentation requirements for imported organometallics. Samsung SDI and SK Hynix fabrication facilities in Giheung and Icheon source semiconductor-grade material through qualified suppliers with cleanroom transfer capabilities.
Saudi Arabia
Jubail Industrial City and Yanbu petrochemical complexes on the Red Sea coast anchor Middle Eastern alkylaluminum demand. The national chemicals regulator mandates hazardous material storage protocols for pyrophoric organometallics at SABIC-operated facilities. Sadara and Petro Rabigh integrated sites require continuous co-catalyst feeds for metallocene and Ziegler-Natta polyethylene lines.
Triethylaluminum Market Competitive Landscape
On the supply side, the industry is consolidating around integrated bromine-to-alkylaluminum chains and Fischer-Tropsch feedstock advantages. Three archetypes dominate: petrochemical-integrated majors with captive ethylene access, specialty organometallic houses with purification expertise, and regional distributors losing share to direct contracting. Capacity expansion and backward integration into aluminum alkyl precursors represent the primary competitive vectors.
Among US-based integrated producers, Albemarle exemplifies the petrochemical-integrated archetype through its Gulf Coast manufacturing footprint. Sasol OandS anchors southern African supply from its Secunda complex, representing the Fischer-Tropsch feedstock-integrated model. Nippon Aluminum Alkyls occupies a position within the Asia-Pacific specialty tier, while Tianjin Lianli Chemical sits within China's domestic supply base.
| Leading Market Players |
|---|
| Albemarle |
| Gulbrandsen |
| Sasol OandS |
| SOCC |
| Nouryon |
| AkzoNobel |
| Nippon Aluminum Alkyls |
| Tianjin Lianli Chemical |
| Lanxess |
| Others |
Value Network & Pricing Analysis
Hurricane corridor exposure along the US Gulf Coast compresses pricing power for industrial-grade material while simultaneously forcing three-tier pricing stratification across semiconductor, pharmaceutical, and polymer catalyst grades. This geographic risk concentration rewards suppliers with diversified production footprints and penalizes single-source dependent buyers with wider price bands during supply disruptions.
Pricing Analysis
Volume-discount tiering structures separate semiconductor-grade parts-per-billion purity material from industrial-grade Ziegler-Natta co-catalysts, with pharmaceutical-grade occupying a mid-position based on GMP certification requirements. Price differentiation hinges on halide specification thresholds and dedicated packaging protocols for pyrophoric handling. Pricing pressure intensifies in industrial grades as direct manufacturer-to-producer contracting eliminates distributor markups and compresses margins. Polymer producers exhibit highest price sensitivity due to commodity polyethylene margin pressures, while semiconductor foundries accept premium positioning for supply security.
Supply Chain Analysis
Contract-manufacturing concentration for high-purity grades sits with Albemarle's Texas and Louisiana sites, Sasol OandS's Secunda complex, and Nippon Aluminum Alkyls' Japanese facilities. Geographic supply concentration clusters in the United States, Germany, and China where integrated petrochemical complexes anchor demand. Raw material dependencies center on ethylene feedstocks, aluminum metal, and hydrogen gas for alkylaluminum synthesis. Single-source vulnerability persists for semiconductor-grade material given limited qualified suppliers with cleanroom transfer capabilities. Distribution runs through nitrogen-blanketed ISO tanks and dedicated tanker trucks under DOT and ADR hazardous material regulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethylene feedstock cyclicality positions this market for recovery as petrochemical complex restocking accelerates alongside polyethylene capacity commissioning in China and India.
For Market Incumbents: Entrench Gulf Coast positions through captive ethylene integration and redundant production assets that mitigate hurricane corridor concentration risk. Expand pharmaceutical-grade purification capabilities to capture high-margin chemical synthesis demand from contract research organizations. Prioritize OSHA process safety management certification investments that extend competitive moats against unqualified entrants. For New Entrants and Emerging Players: India's petrochemical buildout offers the most penetrable geographic frontier as Reliance Industries and Indian Oil Corporation commission integrated polyethylene complexes requiring captive alkylaluminum supply. Target pharmaceutical-grade reagent positioning for stereoselective carbon-carbon bond formation in active pharmaceutical ingredient routes. Pursue qualification partnerships with Taiwan and South Korean semiconductor foundries seeking secondary qualified suppliers for supply security. For Investors and Strategic Acquirers: The market sits at a mid-cycle consolidation phase that favors Fischer-Tropsch-integrated producers with captive feedstock advantages and REACH-registered European market access. Long-term viability over the coming decade hinges on energy-efficient catalyst system alignment with China's MIIT green manufacturing guidelines and semiconductor-grade purification scalability. Monitor ethylene-naphtha spread compression as the primary inflection indicator for industrial-grade margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstocks | Captive supply from crackers at Baytown and Port Arthur insulates margin from commodity volatility. |
| Semiconductor-Grade Purification Scale-Up | Parts-per-billion protocols for Samsung SDI and SK Hynix fabrication facilities command premium positioning. |
| Long-Term Supply Agreement | Direct contracting with Sinopec and PetroChina complexes locks volume through the China dual carbon policy cycle. |
| Joint Venture for Indian Market Entry | Partnerships with Reliance Industries anchor participation in the subcontinent's polyethylene buildout. |
| Green Manufacturing Certification | MIIT-aligned energy-efficient catalyst systems receive preferential project approval in Chinese chemical parks. |
Research Methodology
Operator-level perspectives from plant managers at Gulf Coast alkylaluminum facilities, procurement leads at polyethylene producers, distribution channel partners handling pyrophoric organometallics, and technical R&D directors at catalyst manufacturers anchored the qualitative base. Secondary validation drew from SEC 10-K filings, customs and trade data, ACC and Cefic industry reports, and OSHA process safety management enforcement records. Bottom-up volume estimates from individual production sites triangulated against top-down demand projections from polymer capacity databases.
Scenario-bracketing framed projections across the analysis window, modeling grade tier segmentation, end-use industry splits, packaging format preferences, and regional production hub dynamics. CAGRs derived from historical ethylene demand elasticity, polyethylene capacity commissioning schedules, and semiconductor wafer start forecasts. Forecast inputs incorporated REACH authorization timelines, China GB standard implementation phases, and metallocene catalyst substitution rates.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by specialty chemical houses or sudden ethylene feedstock cost spikes would shift outcomes. Quarterly review of ethylene-naphtha spreads, ECHA authorization decisions, and Indian petrochemical project commissioning timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Perchloric Acid Market
Chemicals
Non-Halogenated Flame Retardant Chemicals Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Electroplating Chemicals Market
Chemicals
4-Methyl-2-Pentanone Market
Chemicals
Coagulant Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Ammonia Market
Chemicals
Valeronitrile Market
Chemicals
Desalination Chemicals Market
Chemicals
Italy Laboratory Chemicals Market
Chemicals
Malonic Acid Market
Chemicals
Cumene Market
Chemicals
Caustic Soda Market
Chemicals
Global P-Phenylenediamine Market
Chemicals
Global Glycol Ether Market