
 Sodium, Potassium, and Calcium Salts Market | 2026-2036
Sodium, Potassium, and Calcium Salts Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium, Potassium, and Calcium Salts Market Insights
Buyer concentration in the processed food and pharmaceutical sectors is consolidating, with large multinationals squeezing mid-tier suppliers on specification compliance and volume commitments. Cargill leverages its integrated salt-harvesting and distribution infrastructure to secure long-term supply contracts with North American food processors. Dow Chemical Company anchors its position through captive caustic-chlorine output that feeds downstream sodium salt derivatives. AkzoNobel competes on specialty grades for European industrial customers requiring low-magnesium chloride content.
Sodium, potassium, and calcium salts comprise ionic compounds derived from alkali and alkaline earth metals, typically produced through brine evaporation, mining, or chemical synthesis with purity thresholds ranging from technical grade to United States Pharmacopeia standards; these materials function as essential inputs for pH regulation, electrolyte balance, and chemical reactivity across manufacturing chains. Sodium chloride and sodium bicarbonate dominate volume flows, with the former supplying chlor-alkali feedstock and the latter serving effervescent pharmaceutical and bakery leavening applications where food-grade certification commands margin premiums. Calcium phosphate and potassium sulfate occupy faster-growing niches, driven by fortified food formulations and specialty fertilizer blends that reward producers with agricultural-grade registration and pharmaceutical-grade cGMP compliance.
EPA effluent guidelines and FDA food additive regulations in the United States, coupled with REACH substance registration and EFSA purity standards in Europe, compel producers to maintain dual-certification laboratories and audit-ready documentation for cross-border shipments. China's SAMR and GB standards for food-grade salt impose additional testing protocols that filter out smaller exporters lacking in-house analytical capability. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP monographs, as divergence in heavy-metal limits and microbial specifications will determine which producers retain multi-regional qualification without redundant purification investments.
Market Dynamics
REACH substance registration and FDA food additive mandates are compressing the qualified supplier base, forcing producers to absorb redundant testing costs or exit cross-border trade entirely. This regulatory convergence favors integrated manufacturers with captive laboratories over merchant traders.
Growth Catalysts
- Pharmaceutical-grade sodium bicarbonate:Effervescent tablet formulators in Germany and Switzerland are expanding offtake of USP-certified material for antacid and electrolyte applications.
- Chlor-alkali integration:Captive caustic-chlorine output from integrated chemical complexes secures downstream sodium salt derivative supply chains against merchant market volatility.
- FSSAI fortification mandates:India's food safety regulator requires iodized and fortified salt in processed foods, expanding addressable volume for compliant producers.
Market Restraints
- Brine evaporation energy costs:Thermal concentration of solar salt deposits faces margin compression from natural gas price volatility in European production clusters.
- Heavy-metal specification divergence:Misalignment between USP, EP, and JP monographs on lead and arsenic limits forces redundant purification for multi-regional qualification.
- Magnesium chloride substitution:De-icing and dust-control applications in North American infrastructure are displacing calcium chloride with lower-cost magnesium alternatives.
Strategic Opportunities
- Cell-culture media salts:Biopharmaceutical manufacturers in South Korea and Singapore are sourcing potassium phosphate and sodium bicarbonate with cGMP documentation for vaccine production.
- SAMR food-grade registration:China's State Administration for Market Regulation offers expedited pathways for producers with existing FDA or EFSA certifications.
- Direct-to-formulator e-commerce:Specialty salt distributors are bypassing traditional chemical merchant networks to supply pharmaceutical compounders with lot-traceable material.
Industry Challenges
- Analytical chemist scarcity:Multi-regional certification requires in-house ICP-MS and microbial testing capability that competes for talent with broader pharmaceutical quality assurance functions.
- Audit documentation latency:REACH registration dossiers and FDA food facility registrations demand six-to-twelve-month preparation cycles that delay market entry for new grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium, Potassium, and Calcium Salts Market |
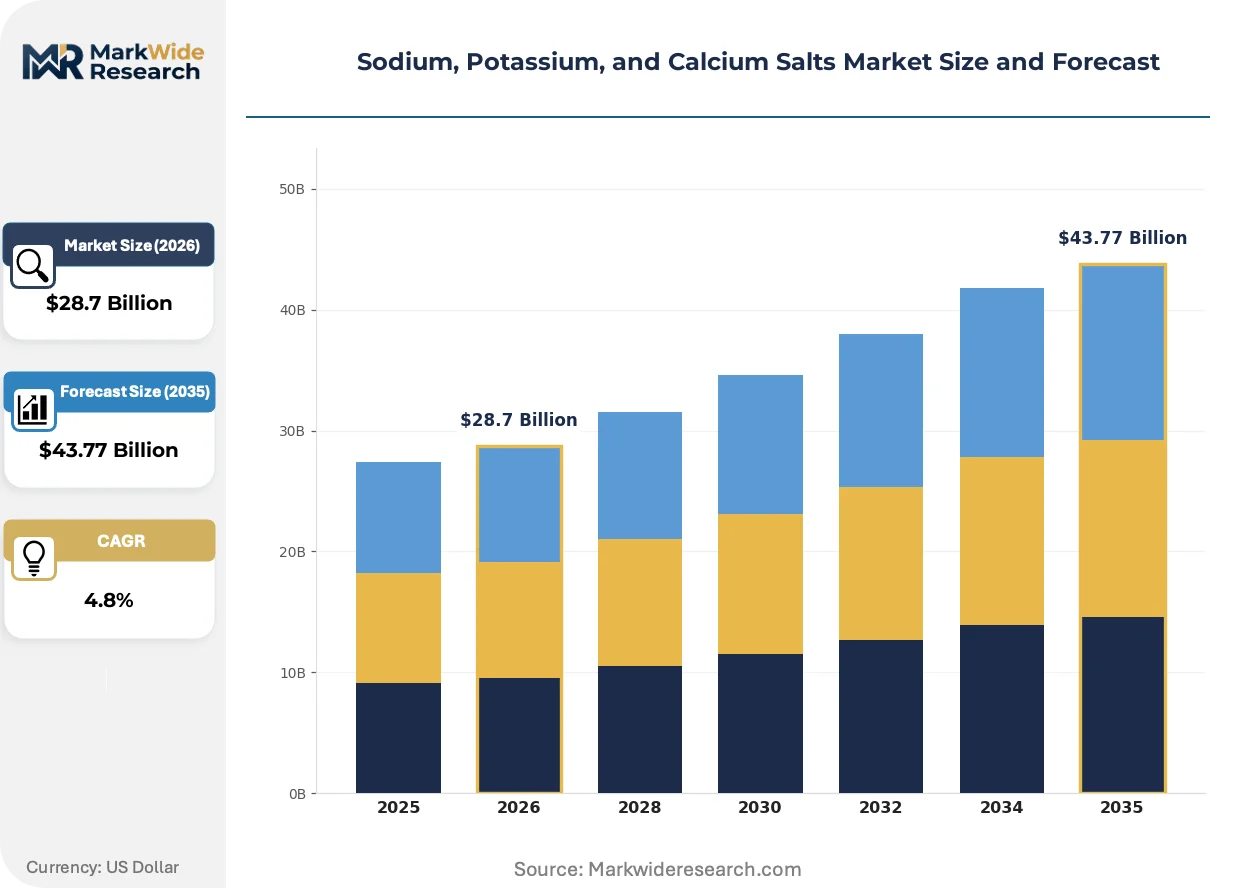
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Chloride, Potassium Carbonate, Calcium Citrate, Sodium Bicarbonate, Potassium Sulfate, Calcium Phosphate Grade: Pharmaceutical, Food Grade, Industrial, Agricultural, Laboratory, Technical Application: Water Treatment, Cement Manufacturing, Chemical Processing, Food Preservation, Animal Nutrition, Detergents End Use Industry: Chemicals, Construction, Agriculture, Pharmaceuticals, Personal Care, Paper & Pulp |
| Companies Covered | Cargill, Dow Chemical Company, AkzoNobel, Compass Minerals, Morton Salt, Wilmar International, KLK Oleo, VVF, Emery Oleochemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium, Potassium, and Calcium Salts Market Trends and Innovations
Electrolyte salt production is fragmenting into modular, decentralized units that co-locate with downstream formulation facilities, compressing logistics exposure and enabling just-in-time inventory models for pharmaceutical and food manufacturers.
Membrane electrodialysis is modularizing brine processing by enabling food-grade and pharmaceutical-grade salt production at smaller scale than traditional solar evaporation ponds. Specialty chemical manufacturers in the Netherlands and Japan are deploying containerized units adjacent to pharmaceutical formulation sites. This distributed architecture is compressing working capital requirements and reducing cross-border shipment volumes for high-purity grades.
REACH registration deadlines for sodium and potassium salt substances are forcing producers to submit full toxicological dossiers to ECHA or withdraw from European industrial markets. Chemical manufacturers with legacy registrations are leveraging data-sharing agreements to monetize existing studies. The regulatory burden is filtering out traders lacking in-house regulatory affairs capability.
Pharmaceutical formulators are consolidating suppliers to single-source relationships with integrated producers offering dual USP-EP certification. Large multinationals in Switzerland and Germany now require dedicated inventory buffers and audit rights over subcontracted testing laboratories. This concentration is visible in the effervescent and parenteral electrolyte segments where lot traceability has become non-negotiable.
Sodium, Potassium, and Calcium Salts Market Segmentation
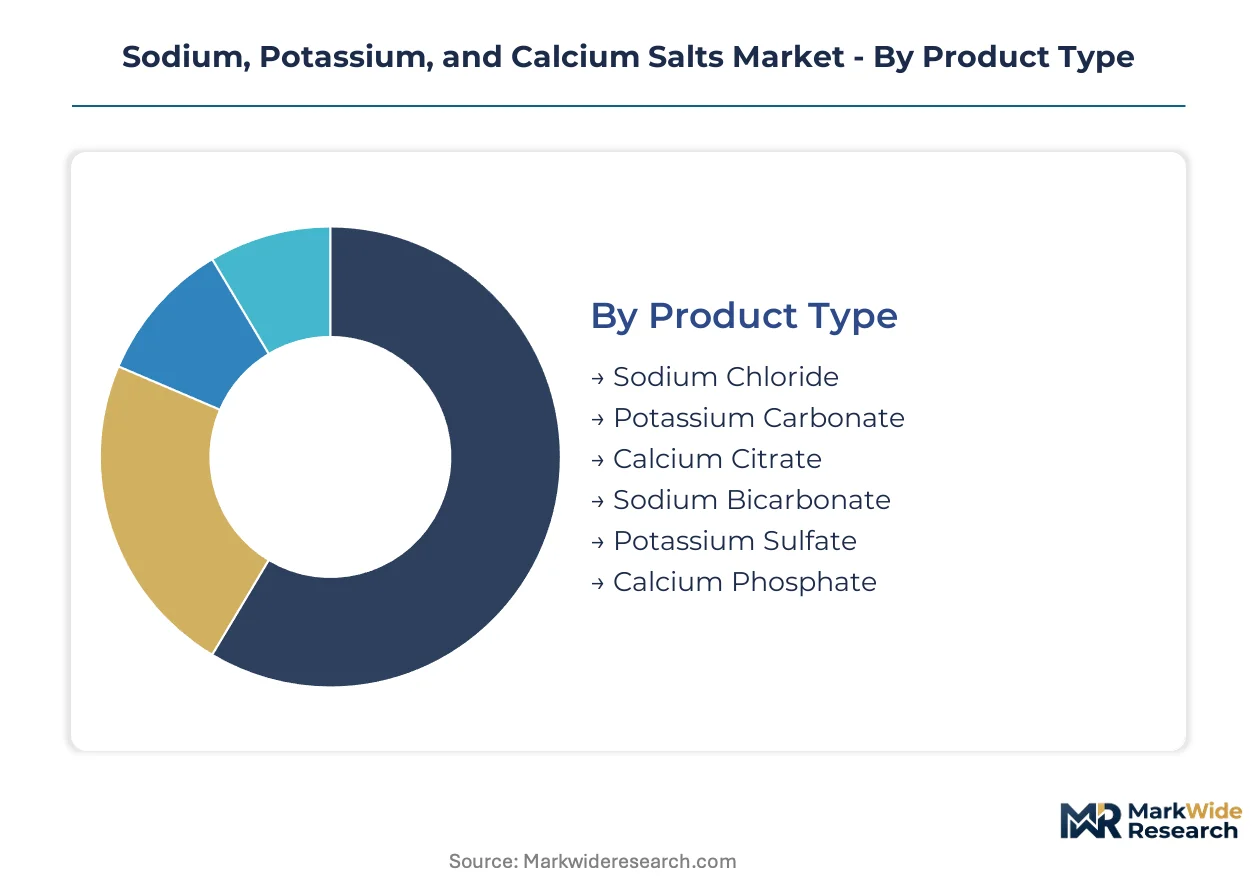
Sodium, potassium, and calcium salts serve fundamentally different roles depending on purity thresholds and end-use requirements. Segmentation reveals how pharmaceutical-grade certification commands margin premiums while industrial volumes anchor producer cash flows.
Product Type:
Standalone commodity salts dominate volume flows, while specialty derivatives embed into downstream chemical synthesis and formulation systems.
- Sodium Chloride:Halite-derived or solar-evolved crystals with purity ranging from technical to USP-grade. Chlor-alkali producers in Germany and the US Gulf Coast consume massive tonnage as captive feedstock for caustic soda and chlorine gas generation.
- Sodium Bicarbonate:Synthetic bicarbonate manufactured via Solvay process or refined from natural trona deposits. Effervescent tablet formulators in Switzerland and antacid manufacturers in India drive demand for dense, low-moisture USP grades with tight particle size distribution.
- Potassium Carbonate:Electrolytically produced or refined from potash ore for glass manufacturing and specialty fertilizers.
- Potassium Sulfate:Sulfate of potash extracted from brine deposits or synthesized for chloride-sensitive crops and tobacco cultivation.
- Calcium Phosphate:Precipitated or milled phosphate salts serving leavening agents, nutritional fortification, and dental applications.
- Calcium Citrate:Citric acid neutralization product for highly bioavailable calcium supplementation in nutraceutical tablets.
Sodium chloride leads volumes today; sodium bicarbonate is gaining share fastest.
Grade:
Cost tiers separate certification-intensive premium grades from specification-tolerant bulk material.
- Pharmaceutical:USP, EP, and JP monograph-compliant salts with validated heavy-metal limits, microbial enumeration, and endotoxin testing. Swiss and German parenteral electrolyte manufacturers require dual-certification with dedicated inventory buffers.
- Food Grade:FDA food additive and EFSA purity standard-compliant material with lot traceability for processed food and beverage applications. China's SAMR registration imposes additional testing protocols that filter out smaller exporters.
- Industrial:Technical-grade salts for chlor-alkali feedstock, de-icing, and dust control with minimal analytical documentation.
- Agricultural:Fertilizer-grade potassium and calcium salts with agricultural registration but relaxed purity versus food applications.
- Laboratory:ACS or reagent-grade material for analytical chemistry and research applications with certificate of analysis per lot.
- Technical:Unspecified purity salts for oilfield drilling fluids, metal finishing, and general chemical processing.
Industrial grade anchors volume; pharmaceutical grade commands the steepest margin expansion trajectory.
Application:
Customer type determines whether salts enter standalone sale or integrated process consumption.
- Chemical Processing:Chlor-alkali operations, organic synthesis, and catalyst support requiring consistent feedstock quality. Integrated producers with captive brine evaporation secure cost advantages against merchant market exposure.
- Food Preservation:Curing, pickling, and moisture control applications where FDA food facility registration and HACCP documentation are mandatory.
- Water Treatment:Softening, pH adjustment, and disinfection byproduct control in municipal and industrial systems.
- Cement Manufacturing:Accelerators and set-time modifiers in concrete admixtures with less stringent purity requirements.
- Animal Nutrition:Feed-grade minerals for livestock and aquaculture with regional registration varying by veterinary oversight.
- Detergents:Builders and pH stabilizers in powder and liquid formulations facing phosphate substitution pressures in ecologically sensitive watersheds.
Chemical processing consumes the largest tonnage; food preservation shows the fastest climb in specification value capture.
End Use Industry:
Maturity curves diverge sharply between cyclical industrial demand and defensive pharmaceutical offtake.
- Pharmaceuticals:Parenteral solutions, oral solid dosage, and effervescent formulations where cGMP compliance and audit rights over subcontracted laboratories are non-negotiable. Large multinationals in Switzerland and Germany consolidate to single-source relationships with integrated producers.
- Chemicals:Chlor-alkali chains, organic synthesis, and specialty derivatives where captive integration versus merchant supply determines margin resilience.
- Agriculture:Fertilizer blends and animal feed premixes with regional regulatory registration driving supplier qualification.
- Construction:Concrete admixtures and de-icing applications exposed to infrastructure spending cycles and magnesium chloride substitution.
- Personal Care:Oral care, bath products, and cosmetics where natural positioning and mineral origin claims influence ingredient selection.
- Paper & Pulp:Pulping chemicals and coating formulations facing digital substitution pressures in printing grades.
Chemicals dominates volume absorption; pharmaceuticals expands most quickly in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest absolute volume for sodium and potassium salt derivatives, yet Germany captures disproportionate value through pharmaceutical-grade specialization and chlor-alkali integration.
China
Solar evaporation complexes in Shandong and Jiangsu provinces supply chlor-alkali feedstock for domestic chemical processing clusters. SAMR food-grade registration protocols filter out smaller exporters lacking in-house analytical capability. Tianjin's chemical processing corridor is scaling membrane electrodialysis capacity for pharmaceutical-grade sodium bicarbonate production.
Germany
BASF and Bayer formulation sites in Ludwigshafen and Leverkusen drive demand for USP-EP dual-certified sodium bicarbonate and potassium phosphate. REACH substance registration mandates compel producers to maintain ECHA-compliant toxicological dossiers. The North Rhine-Westphalia chemical triangle anchors captive caustic-chlorine output that secures downstream sodium salt derivative supply chains.
United States
Great Plains brine deposits feed both food-grade salt evaporation and oilfield chemical applications across Kansas and Oklahoma. EPA effluent guidelines and FDA food facility registration requirements enforce dual-certification laboratory investments. Louisiana's chlor-alkali corridor along the Gulf Coast processes massive sodium chloride tonnage into caustic soda for specialty chemical manufacturing.
India
FSSAI fortification mandates for iodized salt in processed foods expand addressable volume for compliant domestic producers. Gujarat's Kutch district hosts solar salt operations supplying both chlor-alkali feedstock and agricultural-grade material. The Mumbai-Pune pharmaceutical belt sources USP-certified sodium bicarbonate for effervescent tablet and antacid manufacturing.
Switzerland
Novartis and Roche parenteral formulation facilities demand cGMP-documented potassium phosphate and sodium bicarbonate with dedicated inventory buffers. Swissmedic pharmaceutical regulations align closely with EMA standards while maintaining distinct microbial specification thresholds. Basel's biopharmaceutical cluster is consolidating suppliers to single-source relationships with integrated producers offering audit rights over subcontracted testing laboratories.
Sodium, Potassium, and Calcium Salts Market Competitive Landscape
North American producers anchor one tier through integrated salt-harvesting and chlor-alkali infrastructure; European specialists hold premium positioning through pharmaceutical-grade certification and REACH compliance capabilities. The supplier base compresses into three tiers: multinational integrated chemical conglomerates with captive brine assets, mid-scale regional processors serving food-grade and industrial segments, and niche pharmaceutical-grade refiners with dual USP-EP certification. Strategic moves concentrate on backward integration into brine evaporation assets and geographic expansion through SAMR registration in China.
Within the integrated multinational tier, Cargill and Dow Chemical Company exemplify scale-driven positioning through captive supply chains. AkzoNobel occupies a specialist position focused on European industrial customers requiring low-magnesium chloride content. These three entities represent the dominant competitive archetypes: agricultural-originated diversified processors, petrochemical-anchored chlor-alkali integrators, and specialty chemical refiners with regional purity expertise.
| Leading Market Players |
|---|
| Cargill |
| Dow Chemical Company |
| AkzoNobel |
| Compass Minerals |
| Morton Salt |
| Wilmar International |
| KLK Oleo |
| VVF |
| Emery Oleochemicals |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap salt processors in Gujarat and Shandong provinces anchor supply discipline through multi-generational brine asset control, enabling patient pricing strategies that resist spot-market volatility while reinvesting margins into captive laboratory infrastructure. This ownership pattern concentrates pricing power among producers with multi-regional certification capability, compressing margins for merchant traders lacking in-house analytical depth.
Pricing Analysis
Capacity additions in China's membrane electrodialysis segment are reshaping price floors for pharmaceutical-grade sodium bicarbonate, forcing legacy solar-evaporation producers to defend position through certification bundling. Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels separates USP-EP dual-certified material from single-standard grades and technical bulk. Cost compression in industrial-grade chlor-alkali feedstock is intensifying because European natural gas volatility elevates thermal evaporation expenses. Chemical processors exhibit highest price sensitivity, while Swiss parenteral formulators absorb premium tiers without volume elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston maintain hub-and-spoke patterns that buffer pharmaceutical formulators against cross-border documentation delays. Supply concentrates in China, Germany, and India as solar evaporation and membrane processing clusters scale capacity. Raw material flows draw from subterranean brine deposits, potash ore bodies, and synthetic chemical synthesis streams. Single-source vulnerability runs through REACH-registered producers with legacy ECHA dossiers that newer entrants cannot replicate. Distribution runs through integrated chemical conglomerates with captive logistics networks and specialty distributors offering lot-traceable direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium, potassium, and calcium salts function as a stable compounder anchored by non-discretionary demand from pharmaceutical electrolyte formulations and chlor-alkali processing chains that resist cyclical contraction.
For Market Incumbents: Extend backward integration into brine evaporation assets in Shandong and Gujarat to secure captive feedstock against merchant price volatility. Deepen laboratory infrastructure for simultaneous USP-EP-JP certification to defend position against membrane electrodialysis entrants with modular scale advantage. For New Entrants and Emerging Players: Begin with cell-culture media salts for South Korean and Singaporean biopharmaceutical manufacturers, where cGMP documentation requirements filter out established commodity producers. White-space concentration sits in pharmaceutical-grade potassium phosphate with dedicated inventory buffers, accessible through direct-to-formulator e-commerce channels that bypass traditional chemical merchant networks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional processors with existing FDA or EFSA registrations that can leverage expedited SAMR pathways in China. Five-to-ten-year viability rests on regulatory compliance moats rather than volume scale. Watch for REACH registration deadline extensions as inflection signal for trader exit acceleration and integrated producer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Cargill and Dow Chemical secure captive supply chains against merchant volatility in North American chlor-alkali corridors. |
| Dual USP-EP Certification Investment | Swiss parenteral formulators demand audit rights over subcontracted testing laboratories from single-source suppliers. |
| Membrane Electrodialysis Deployment | Dutch and Japanese specialty manufacturers co-locate containerized units adjacent to pharmaceutical formulation sites. |
| SAMR Registration Acceleration | China's State Administration for Market Regulation offers expedited pathways for producers with existing FDA certifications. |
| Direct-to-Formulator E-Commerce | Specialty distributors bypass traditional chemical merchant networks to supply lot-traceable material for pharmaceutical compounders. |
Research Methodology
Direct dialogue with plant managers at chlor-alkali complexes, procurement leads at downstream pharmaceutical formulators, distribution channel partners in European chemical trading hubs, and technical R&D directors at specialty salt refiners grounded qualitative findings. Secondary validation drew from customs and trade data, Cefic and ACC industry reports, SEC 10-K filings, and ECHA registration dossiers. Bottom-up volume modeling triangulated against top-down demand aggregation across grade tiers and end-use industries.
Segmented outputs across pharmaceutical, food-grade, industrial, and agricultural certification tiers combined with regional production hub clustering and application-specific consumption patterns throughout the forecast period. CAGRs derived from regression analysis against chlor-alkali capacity expansion timelines and pharmaceutical formulation growth trajectories. Key inputs included FSSAI fortification mandate compliance rates and REACH registration completion schedules.
Several conditions sit outside the modeled scope, including sudden heavy-metal specification harmonization failures between USP and EP monographs, sovereign export restrictions on potash derivatives, and disruptive substitution of calcium chloride with magnesium alternatives in de-icing applications. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
Sulfur Palletized Plant and Granulator Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Global Acrylic Esters Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Barium Sulphate Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Copper Sulfate Market