
 M, P-Cresol Market | 2026-2036
M, P-Cresol Market Size, Share, and Industry Trends Forecast 2026-2036
M, P-Cresol Market Insights
The cresol market is rebalancing as pharmaceutical-grade specifications diverge sharply from industrial-grade commodity pricing. Sasol Limited leverages its integrated coal-to-chemicals platform to sustain cost leadership in bulk industrial volumes. Mitsui Chemicals anchors its position through high-purity cresol streams tailored to Asian pharmaceutical and agrochemical formulators. Lanxess AG competes by controlling specialized hydrogenation and distillation assets that meet tightening European purity mandates.
M, P-Cresol denotes the mixed isomeric forms of cresol—methylphenol compounds with boiling points between 202°C and 202.8°C—produced primarily via sulfonation of toluene followed by alkali fusion, or through cumene oxidation byproduct recovery. These aromatic phenolics serve as essential chemical intermediates for synthetic vitamin E, antioxidants, disinfectants, and phenolic resin curing agents. Pharmaceutical grade commands the densest margin pool due to stringent impurity ceilings on sulfur and nitrogen content, while industrial grade occupies the highest volume tier as a feedstock for lubricant additives and chemical intermediates. Laboratory grade sustains premium pricing through batch-certified traceability required by analytical reagent distributors.
REACH registration requirements and the EU Green Deal carbon-border adjustments are reshaping import competitiveness for non-European cresol producers. The EPA and EMA both enforce residual solvent limits that directly determine which cresol grades qualify for pharmaceutical and food-contact applications. Stakeholders must monitor evolving purity standards and carbon-intensity disclosures to preserve market access across regulated end-use segments.
Market Dynamics
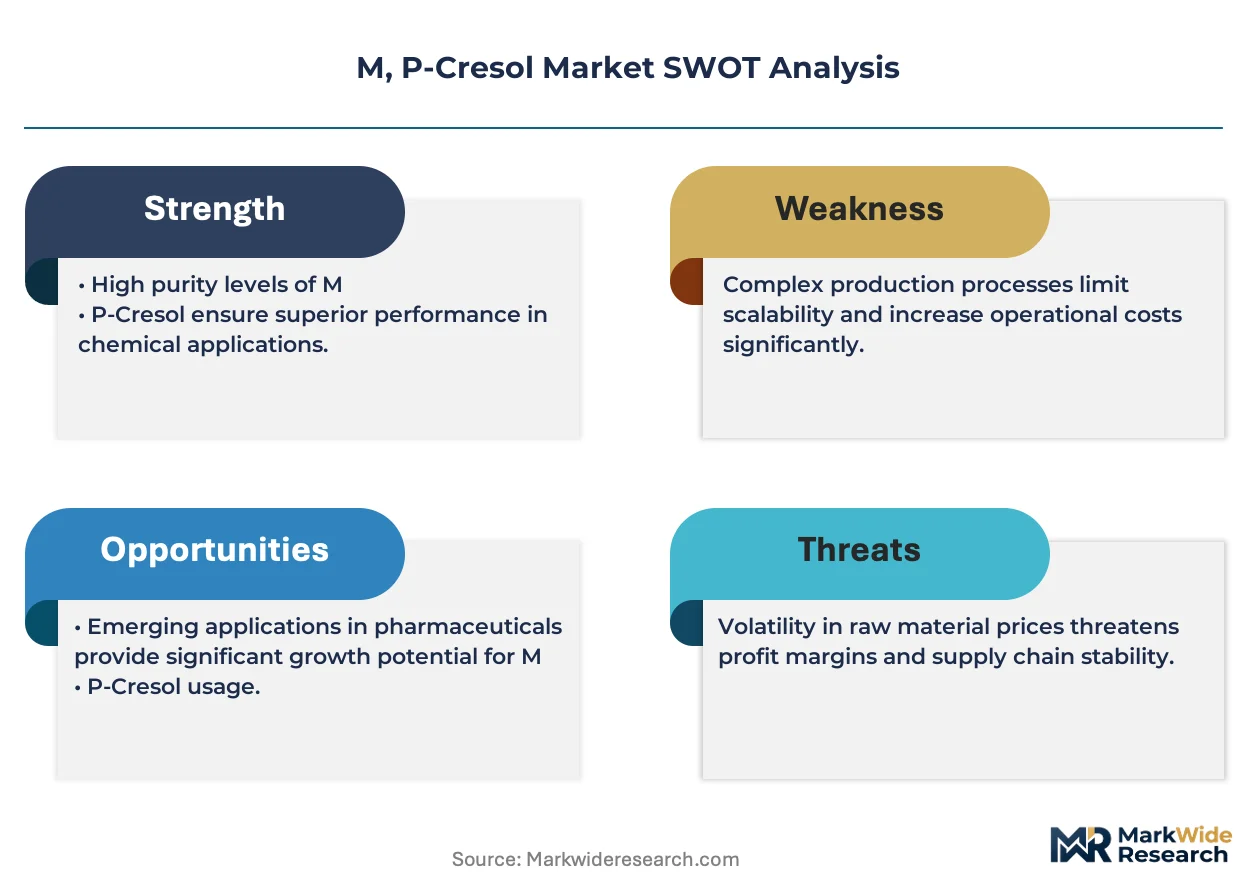
Pharmaceutical-grade purity mandates are fragmenting the M, P-Cresol market into tiered supply tiers, with sulfur and nitrogen impurity ceilings now determining which producers qualify for synthetic vitamin E and antioxidant manufacturing.
Growth Catalysts
- Synthetic vitamin E production:Pharmaceutical manufacturers in Germany and Switzerland are expanding cresol offtake for tocopherol synthesis, tightening specifications on residual solvents.
- REACH registration compliance:The EU Green Deal's carbon-border adjustments are redirecting import flows toward European producers with verified low-carbon process credentials.
- Cumene oxidation byproduct recovery:Integrated petrochemical complexes in South Korea and Japan are capturing cresol streams that previously went to fuel blending, adding merchant supply.
Market Restraints
- Toluene feedstock volatility:Aromatic naphtha pricing swings directly compress margins for sulfonation-based producers without backward integration into refinery streams.
- Specialized hydrogenation asset scarcity:Ultra-high-purity grades require dedicated catalytic hydrogenation units; fewer than twelve facilities worldwide meet current pharmaceutical specifications.
- Phenol derivative substitution:Bisphenol-A derived antioxidants are displacing cresol-based alternatives in select lubricant applications where thermal stability requirements have relaxed.
Strategic Opportunities
- Indian pharmaceutical formulators:CDSCO's alignment with ICH Q3C residual solvent guidelines is opening import pathways for certified European and Japanese cresol grades.
- Agrochemical intermediate demand:Herbicide and pesticide manufacturers in Brazil and Argentina are qualifying cresol-based precursors for glyphosate synthesis alternatives.
- Carbon-intensity disclosure mandates:The EU Green Deal's CBAM phase-in creates first-mover advantage for producers with lifecycle-assessed low-carbon process documentation.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography-mass spectrometry operators capable of certifying parts-per-billion impurity levels command premium wages, constraining batch release capacity.
- EMA certification timelines:Active pharmaceutical ingredient starting material approvals now require eighteen to twenty-four month validation cycles, freezing supplier switches.
- Legacy sulfonation infrastructure retrofit costs:Converting 1970s-era alkali fusion plants to meet current EPA effluent standards demands capital outlays that marginal producers cannot finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | M, P-Cresol Market |
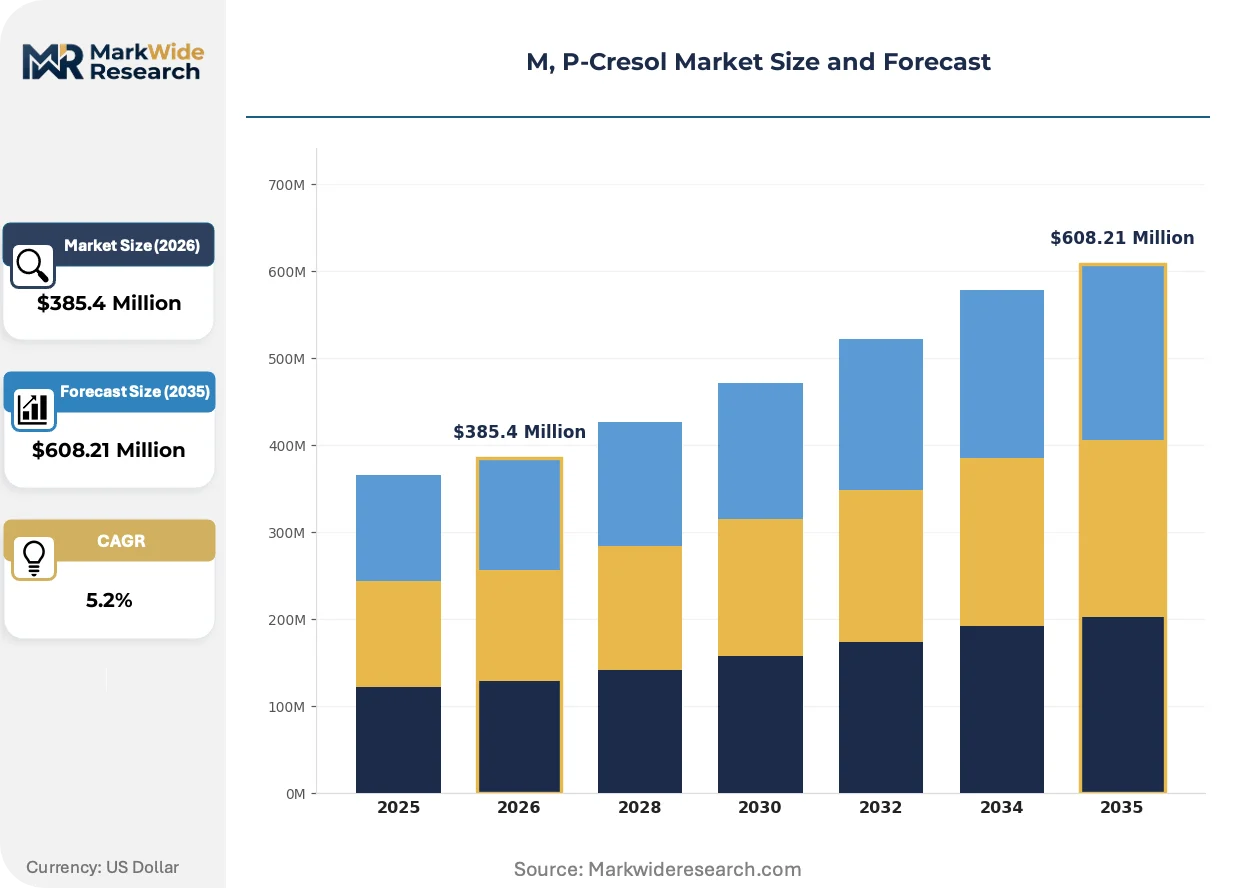
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Laboratory Grade, Food Grade Application: Solvent, Chemical Intermediate, Additive, Fungal Inhibitor End User: Chemicals, Pharmaceuticals, Agriculture, Plastics Distribution Channel: Direct Sales, Online Retail, Distributors, Markets |
| Companies Covered | Sasol Limited, Lanxess AG, Mitsui Chemicals, Inc., Atul Ltd., SABIC, RüTGERS Group, Deepak Novochem Technologies Limited, Tokyo Chemical Industry Co., Ltd., Konan Chemical Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
M, P-Cresol Market Trends and Innovations
Process intensification and digital quality assurance are compressing batch-to-batch variation in cresol production, enabling pharmaceutical manufacturers to reduce safety stock holdings and tighten supply chain specifications.
Continuous flow sulfonation reactors are automating temperature and residence time control previously managed through manual sampling adjustments. Japanese pharmaceutical formulators have adopted these systems for high-purity cresol streams since 2022. The technology is automating real-time impurity detection that previously required offline laboratory analysis, compressing release timelines from days to hours.
REACH's 2023 update to restriction entries on methylphenol isomers is mandating sub-10 ppm sulfur content for all cosmetic and pharmaceutical applications. German specialty chemical clusters are retrofitting distillation trains to meet this ceiling. The regulation is forcing non-European exporters to commission third-party purity certification or forfeit market access.
Consolidated procurement by multinational vitamin E manufacturers is replacing fragmented spot purchasing with multi-year framework agreements tied to carbon-intensity metrics. BASF and DSM-Firmenich have implemented supplier scorecards weighting lifecycle emissions at 30% of contract allocation. This pattern concentrates volume with integrated producers capable of documented process transparency.
M, P-Cresol Market Segmentation
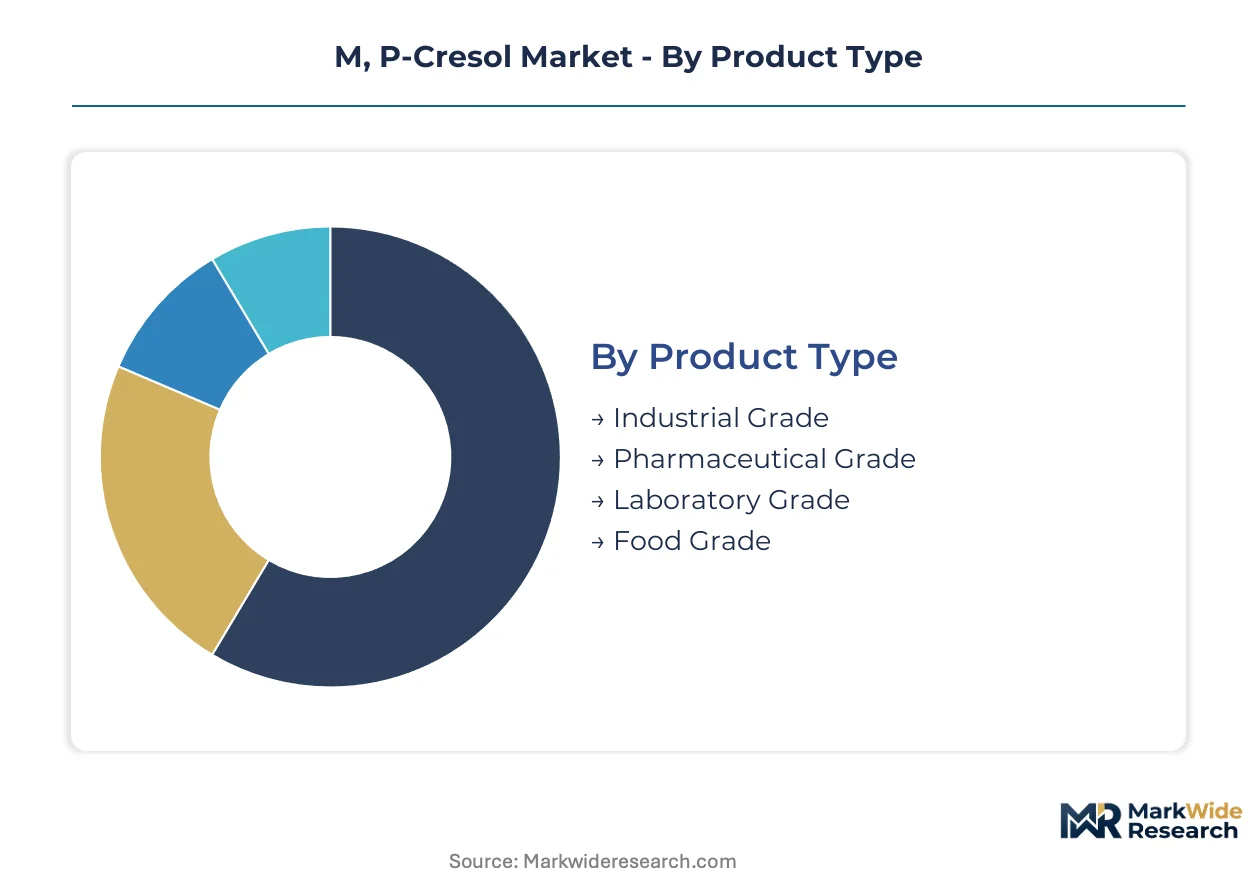
M, P-Cresol specifications diverge sharply across end-use requirements, with pharmaceutical manufacturers demanding sub-10 ppm sulfur ceilings while industrial buyers prioritize volume scale over trace impurity control. Grade-based segmentation determines pricing tiers, regulatory compliance pathways, and the capital intensity required for market entry.
Product Type:
Buyers in this category separate by purity tolerance and the certification burden they can absorb, with pharmaceutical formulators paying steep premiums for batch-traceable documentation that industrial lubricant blenders disregard.
- Industrial Grade:Contains mixed meta- and para-cresol isomers at 95-98% purity, suitable for phenolic resin curing and lubricant additive synthesis. Chemical manufacturers in Germany's Ruhr cluster consume the largest volumes for antioxidant production, though toluene feedstock volatility compresses margins for non-integrated producers.
- Pharmaceutical Grade:Delivers ≥99.5% purity with stringent limits on sulfur, nitrogen, and heavy metal residues mandated by EMA and FDA for synthetic vitamin E and tocopherol manufacturing. Swiss and German pharmaceutical formulators dominate offtake, with EMA certification timelines stretching eighteen to twenty-four months for new supplier qualification.
- Laboratory Grade:Batch-certified material with full traceability documentation for analytical reagent distributors and research institutions.
- Food Grade:Meets residual solvent limits for food-contact antioxidant applications under EFSA and FDA food additive regulations.
Industrial Grade sits at the top of the volume ranking, with Pharmaceutical Grade climbing the fastest as vitamin E manufacturers consolidate procurement around certified low-carbon supply chains.
Application:
Functional role determines specification stringency, with chemical intermediates facing the tightest impurity ceilings while solvent applications tolerate broader compositional variation.
- Chemical Intermediate:Serves as the dominant consumption pathway, feeding synthetic vitamin E, agrochemical precursors, and phenolic resin synthesis. German specialty chemical clusters anchor European demand, with REACH registration requirements forcing non-European producers to commission third-party purity certification or forfeit market access.
- Solvent:Functions as a reaction medium and extraction solvent in pharmaceutical manufacturing and industrial cleaning formulations. Japanese pharmaceutical formulators have adopted continuous flow sulfonation systems since 2022, automating real-time impurity detection that compresses release timelines from days to hours.
- Additive:Incorporated into lubricant formulations and rubber processing chemicals where thermal stability requirements govern selection criteria.
- Fungal Inhibitor:Deployed in wood preservation and agricultural applications with regulatory thresholds varying by jurisdiction.
Chemical Intermediate commands the largest revenue pool, with Solvent applications gaining share fastest through process intensification investments in Japanese and South Korean manufacturing complexes.
End User:
Industry verticals separate by regulatory exposure, with pharmaceutical and food-contact applications facing mandatory carbon-intensity disclosures under EU Green Deal frameworks that chemical and plastics processors currently escape.
- Pharmaceuticals:Synthetic vitamin E manufacturers in Germany and Switzerland drive the highest-margin demand segment. BASF and DSM-Firmenich have implemented supplier scorecards weighting lifecycle emissions at 30% of contract allocation, concentrating volume with integrated producers capable of documented process transparency.
- Chemicals:Phenolic resin and antioxidant manufacturers represent the volume foundation, with demand clustering in Germany's specialty chemical corridors.
- Agriculture:Herbicide and pesticide formulators in Brazil and Argentina are qualifying cresol-based precursors for glyphosate synthesis alternatives.
- Plastics:Polymer stabilizer and plasticizer compounders utilize industrial grades where thermal performance rather than trace purity governs purchasing decisions.
Chemicals generates the highest absolute tonnage, with Pharmaceuticals expanding most quickly as carbon-border adjustments redirect import flows toward European producers with verified low-carbon credentials.
Distribution Channel:
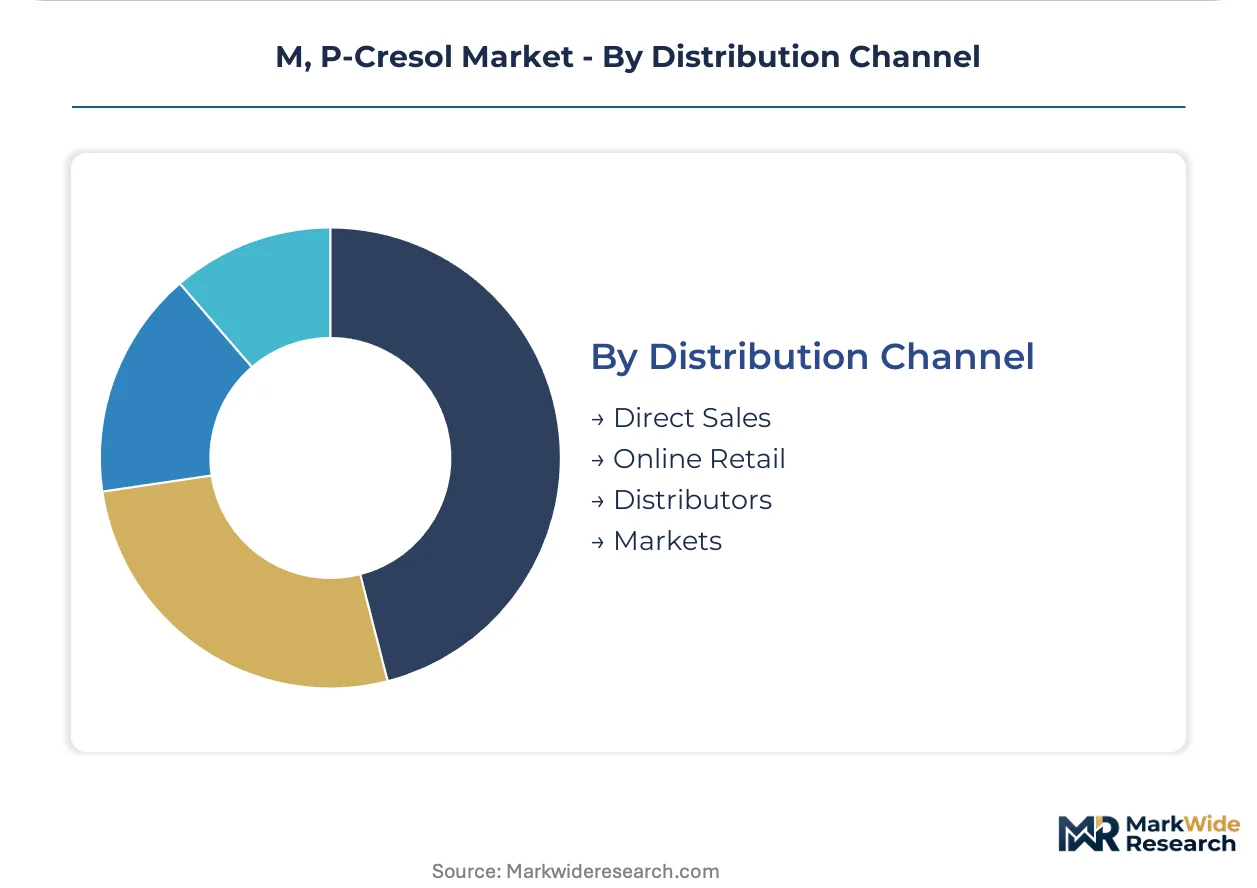
Channel selection tracks buyer scale and certification requirements, with large pharmaceutical formulators bypassing intermediaries while smaller agricultural compounders rely on distributor networks for technical support.
- Direct Sales:Dominates pharmaceutical-grade transactions where multi-year framework agreements replace spot purchasing and supplier scorecards incorporate carbon-intensity metrics. Consolidated procurement by multinational vitamin E manufacturers favors direct relationships with producers maintaining dedicated hydrogenation and distillation assets.
- Distributors:Serves mid-scale chemical and plastics processors requiring technical guidance on grade selection and regulatory compliance documentation.
- Online Retail:Handles laboratory-grade and small-volume industrial orders where batch certification and rapid turnaround outweigh price sensitivity.
- Markets:Facilitates spot transactions for commodity industrial grades in regions with fragmented buyer bases.
Direct Sales captures the largest contract value, with Online Retail advancing fastest as digital quality assurance systems enable remote batch certification for analytical reagent distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the densest margin pool for pharmaceutical-grade cresol, while China anchors industrial-grade volume through integrated coal-chemicals infrastructure. Regulatory divergence between REACH-mandated purity ceilings and emerging economy cost optimization is fragmenting trade flows.
Germany
Specialty chemical clusters in the Ruhr and along the Rhine drive pharmaceutical-grade offtake for synthetic vitamin E synthesis. REACH registration requirements and EU Green Deal carbon-border adjustments favor domestic producers with verified low-carbon process documentation. BASF and DSM-Firmenich procurement offices in Ludwigshafen and Kaiseraugst consolidate multi-year framework agreements tied to lifecycle emissions metrics.
China
Coal-to-chemicals platforms in Shanxi and Inner Mongolia sustain cost leadership in bulk industrial cresol volumes. The Ministry of Ecology and Environment enforces dual carbon goals that pressure sulfonation-based producers toward cleaner synthesis routes. Yangtze River Delta formulators in Jiangsu province increasingly specify imported pharmaceutical grades for high-margin vitamin E export contracts.
United States
Gulf Coast petrochemical complexes capture cresol streams from cumene oxidation byproduct recovery, supplying lubricant additive manufacturers. EPA residual solvent limits under 21 CFR determine qualification for food-contact antioxidant applications. Houston-area distributors serve fragmented industrial buyers across Texas and Louisiana refinery corridors.
Japan
Pharmaceutical formulators in Osaka and Tokyo prefectures adopted continuous flow sulfonation systems since 2022, compressing batch release timelines through real-time impurity detection. METI industrial standards govern phenolic resin applications for electronics packaging. Chubu region hydrogenation assets meet sub-10 ppm sulfur specifications for tocopherol synthesis.
India
CDSCO alignment with ICH Q3C residual solvent guidelines is opening import pathways for certified European and Japanese cresol grades. Maharashtra and Gujarat pharmaceutical clusters qualify starting materials for synthetic vitamin E exports. Mumbai-based formulators face eighteen to twenty-four month EMA validation cycles that freeze supplier switches.
M, P-Cresol Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade purity certification, while mid-scale sulfonation operators compete on industrial-grade volume scale. The vendor base separates into three strategic archetypes: integrated petrochemicals players with cumene oxidation byproduct recovery, coal-to-chemicals specialists with backward integration into aromatics, and dedicated hydrogenation asset operators serving regulated pharmaceutical demand. Competitive moves concentrate on multi-year procurement framework negotiations and carbon-intensity disclosure documentation for EU Green Deal compliance.
Among South African and German integrated chemicals groups, Sasol Limited and Lanxess AG exemplify divergent strategic positioning—Sasol representing coal-chemicals cost leadership in bulk volumes, Lanxess occupying specialized hydrogenation and distillation capabilities for European purity mandates. Mitsui Chemicals, Inc. anchors Japanese pharmaceutical-grade supply through high-purity cresol streams. These three entities collectively span the tiered market structure from commodity industrial feedstocks to certified starting materials for regulated end-uses.
| Leading Market Players |
|---|
| Sasol Limited |
| Lanxess AG |
| Mitsui Chemicals, Inc. |
| Atul Ltd. |
| SABIC |
| RüTGERS Group |
| Deepak Novochem Technologies Limited |
| Tokyo Chemical Industry Co., Ltd. |
| Konan Chemical Manufacturing Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Gas chromatography-mass spectrometry operators in Germany's Ruhr cluster command premium wages, compressing batch release capacity and widening spreads between pharmaceutical-grade and industrial-grade cresol pricing tiers. Labor-cost differentials between certified analytical chemists in Switzerland and commodity sulfonation operators in China's coal-chemicals belt directly amplify the three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
Certification-bundled versus unbundled service splits separate contract structures, with EMA-validated pharmaceutical grades commanding framework agreements that wrap batch traceability, carbon-intensity documentation, and multi-year offtake guarantees into unit pricing. Price differentiation rests on sulfur-content ceilings and REACH registration status, with sub-10 ppm specifications carrying steep premiums over 95-98% industrial purity. Cost compression in commodity sulfonation tiers is intensifying because toluene feedstock volatility squeezes non-integrated producers without refinery stream access. Industrial lubricant blenders exhibit highest price sensitivity, while Swiss and German vitamin E manufacturers absorb premium pricing for certified low-carbon supply chains.
Supply Chain Analysis
EMA and FDA qualification gating restricts pharmaceutical-grade supply to fewer than twelve hydrogenation facilities worldwide, concentrating certified production in Germany, Japan, and Switzerland. Raw material dependencies draw from toluene sulfonation feedstocks, cumene oxidation byproduct streams, and specialized catalytic hydrogenation catalysts. Single-source vulnerability runs through the scarcity of analytical chemists capable of certifying parts-per-billion impurity levels, constraining batch release velocity. Distribution runs through direct sales channels for pharmaceutical formulators and distributor networks serving mid-scale chemical processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The M, P-Cresol market has entered a late-cycle quality phase where synthetic vitamin E manufacturers consolidate procurement around certified low-carbon supply chains, displacing spot purchasing with carbon-intensity-weighted framework agreements.
For Market Incumbents: Cement pharmaceutical-grade purity certification as a defensive moat by retrofitting distillation trains to sub-10 ppm sulfur ceilings before REACH's cosmetic and pharmaceutical restrictions tighten further. Acquire dedicated hydrogenation assets in the Chubu region or Germany's Rhine corridor to lock in EMA certification capacity, defending against cumene oxidation byproduct recovery streams from South Korean integrated petrochemical complexes that threaten merchant supply pricing. For New Entrants and Emerging Players: Launch via distributor partnerships into India's Maharashtra and Gujarat pharmaceutical clusters, where CDSCO alignment with ICH Q3C guidelines has opened import pathways but EMA validation cycles freeze incumbent supplier relationships for eighteen to twenty-four months. Target agrochemical intermediate demand in Brazil and Argentina, where herbicide formulators are qualifying cresol-based glyphosate synthesis alternatives with lower certification burdens than pharmaceutical grades. For Investors and Strategic Acquirers: Specialty chemical conglomerates with existing hydrogenation infrastructure are the most active acquirer in this space, seeking bolt-on cresol distillation assets to fill pharmaceutical-grade capacity gaps. Over a five-to-ten year horizon, producers with lifecycle-assessed low-carbon process documentation will outcompete high-carbon sulfonation operators as EU Green Deal CBAM phase-in accelerates. Watch for carbon-border adjustment implementation milestones as the inflection signal triggering accelerated consolidation among non-European exporters lacking third-party purity certification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Feedstocks | Refinery stream access insulates sulfonation producers from aromatic naphtha volatility. |
| Continuous Flow Sulfonation Reactor Deployment | Japanese pharmaceutical formulators adopted these systems to compress batch release timelines. |
| Multi-Year Framework Agreement Negotiation | BASF and DSM-Firmenich procurement offices weight lifecycle emissions at 30% of contract allocation. |
| Third-Party Purity Certification Commissioning | Non-European exporters must secure documentation to preserve REACH market access. |
| Analytical Chemist Workforce Expansion | Ruhr cluster operators face wage premiums for gas chromatography-mass spectrometry specialists. |
Research Methodology
Multiple input streams — regulatory filing databases, customs trade records, and primary stakeholder interviews — were reconciled to construct supply-demand balances. Conversations with plant managers at sulfonation facilities, procurement leads at vitamin E manufacturers, distribution channel partners in specialty chemical corridors, and technical R&D directors at hydrogenation asset operators informed operational cost structures. Secondary validation drew from ECHA REACH registration data, SEC 10-K filings, customs/trade statistics, and Cefic industry reports. Bottom-up capacity assessments and top-down consumption estimates were triangulated against producer-reported utilization rates.
Data-stream reconciliation across the projection horizon applied a segmented analytical framework modeling grade tier, end-use industry, regional production hub, and carbon-intensity certification status. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for regulatory phase-in schedules and procurement consolidation trajectories. Forecast inputs incorporated EMA certification timeline constraints, CDSCO guideline alignment progress, and EU Green Deal CBAM implementation milestones.
Several conditions sit outside the modeled scope, including force majeure disruptions at single-source hydrogenation facilities, abrupt toluene feedstock price spikes exceeding historical volatility bands, and unannounced REACH restriction updates. Forecasts reflect assumptions about regulatory implementation pacing and procurement contract renewal rates. A model refresh is warranted upon material change in EU carbon-border adjustment enforcement timelines or EMA starting material approval pathway modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Isobutyraldehyde Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Global Nitrite Market
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Benzyl Chloride Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
Phosphates Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Glacial Methacrylic Acid Market