
 Global Sodium Lactate Market | 2026-2036
Global Sodium Lactate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sodium Lactate Market Foresight
REACH is rebalancing the cost-of-entry calculus for sodium lactate suppliers targeting European food and pharmaceutical channels. Jungbunzlauer Suisse AG leverages its integrated fermentation platform to sustain supply security across multiple grades. Corbion N.V. anchors its position through backward integration into lactic acid production. Galactic S.A. competes on specialty pharmaceutical-grade volumes with dedicated GMP lines.
Sodium lactate is the sodium salt of lactic acid, typically produced via fermentation of carbohydrate substrates followed by neutralization, yielding a clear, colorless liquid with pH buffering capacity and humectant properties; it functions primarily as a preservative, pH regulator, and moisture retention agent across food, pharmaceutical, and cosmetic systems. Food Grade sodium lactate occupies the largest volume share given its penetration in processed meat and bakery applications, while Pharmaceutical Grade commands premium positioning due to USP and EP compliance burdens. Cosmetic Grade is gaining traction as formulators replace paraben-based preservation systems, though volumes remain comparatively modest.
FDA food additive regulations, EU REACH requirements, and USP monograph standards collectively determine product specifications, testing protocols, and market access pathways for sodium lactate manufacturers. EMA and national European pharmacopeias enforce additional purity thresholds for injectable and dialysis-grade applications. Stakeholders must monitor regulatory divergence between pharmaceutical and food-grade specifications as jurisdictions tighten contaminant limits and documentation requirements.
Market Dynamics
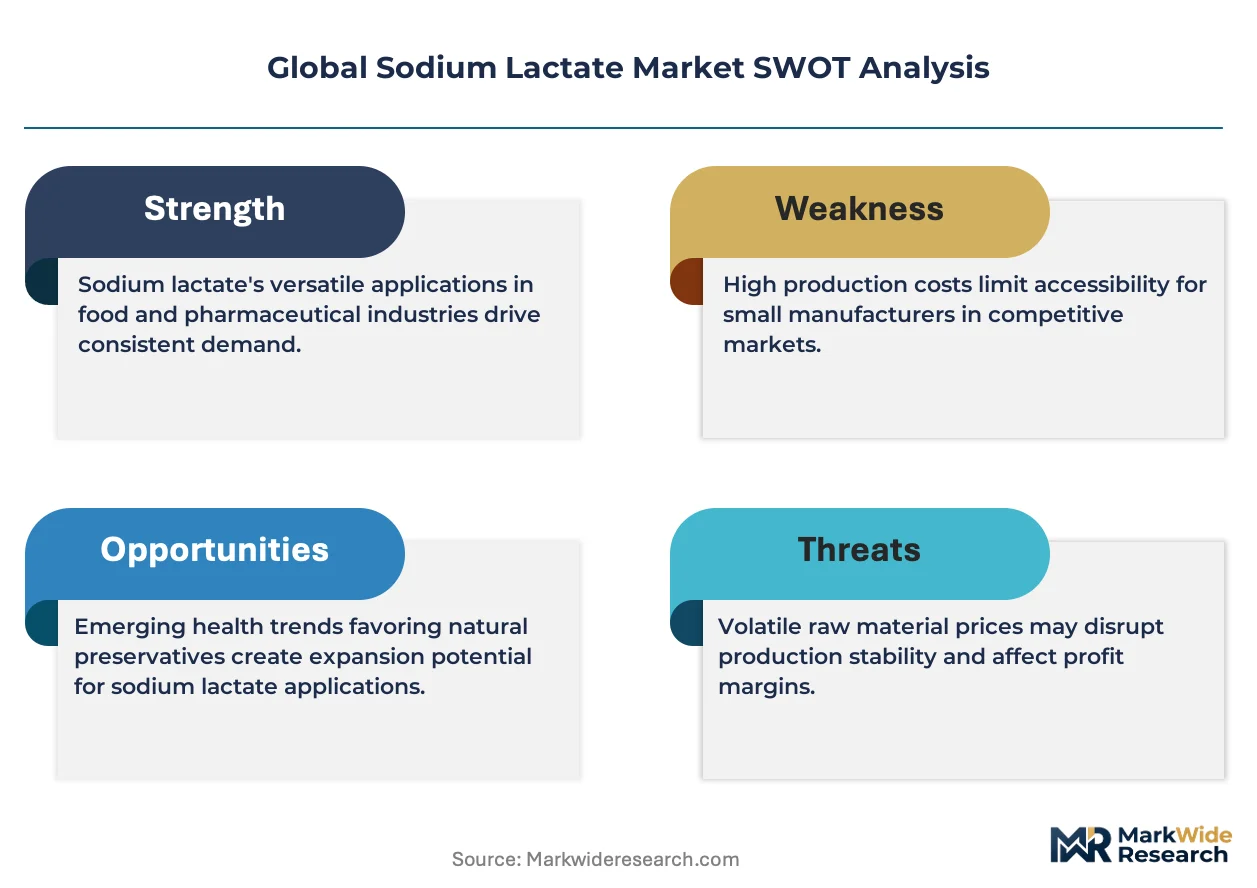
REACH compliance thresholds are restructuring supplier qualification requirements across European pharmaceutical and food channels, forcing fermentation-based producers to upgrade purification infrastructure or exit premium segments entirely.
Growth Catalysts
- Clean-label preservation demand:Processed meat and ready-to-eat manufacturers are substituting synthetic preservatives with sodium lactate to meet retailer clean-label mandates, particularly in Germany and France where EFSA scrutiny on conventional additives has intensified.
- EMA injectable-grade standards:Tightening purity requirements for dialysis and parenteral applications are consolidating demand around GMP-certified suppliers capable of endotoxin-controlled production.
- Fermentation capacity expansion:China's domestic lactic acid fermentation infrastructure is enabling integrated sodium lactate production for regional food and pharmaceutical formulators, reducing import dependency.
Market Restraints
- Corn and molasses price volatility:Carbohydrate substrate costs constitute the dominant variable in fermentation economics, with drought cycles in the US Corn Belt transmitting directly to margin compression.
- European supply concentration:REACH-registered pharmaceutical-grade capacity clusters among three integrated fermentation platforms, creating single-source vulnerability for dialysis fluid manufacturers.
- Potassium lactate substitution:Low-sodium formulation trends in processed meat are enabling partial displacement by potassium salts where sodium reduction claims drive retail positioning.
Strategic Opportunities
- Paraben replacement in cosmetics:Formulators seeking preservative alternatives beyond parabens and formaldehyde donors are qualifying sodium lactate for leave-on skin care, particularly in South Korea where MFDS has tightened preservative safety reviews.
- Bioplastic feedstock pivot:Polylactic acid manufacturers are exploring sodium lactate as a purified intermediate stream, creating potential demand overlap with existing fermentation infrastructure.
- Extended-shelf-life bakery:Industrial bakeries in Mexico and Brazil are adopting sodium lactate for mold inhibition in packaged bread, replacing calcium propionate where clean-label positioning commands retail shelf access.
Industry Challenges
- USP-EP dual certification timelines:Achieving concurrent United States Pharmacopeia and European Pharmacopoeia compliance requires 18-24 month validation cycles that strain working capital for mid-scale fermentation operators.
- Analytical capability gaps:Endotoxin testing and chiral purity verification for pharmaceutical grades demand capital-intensive QC infrastructure that smaller regional suppliers struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sodium Lactate Market |
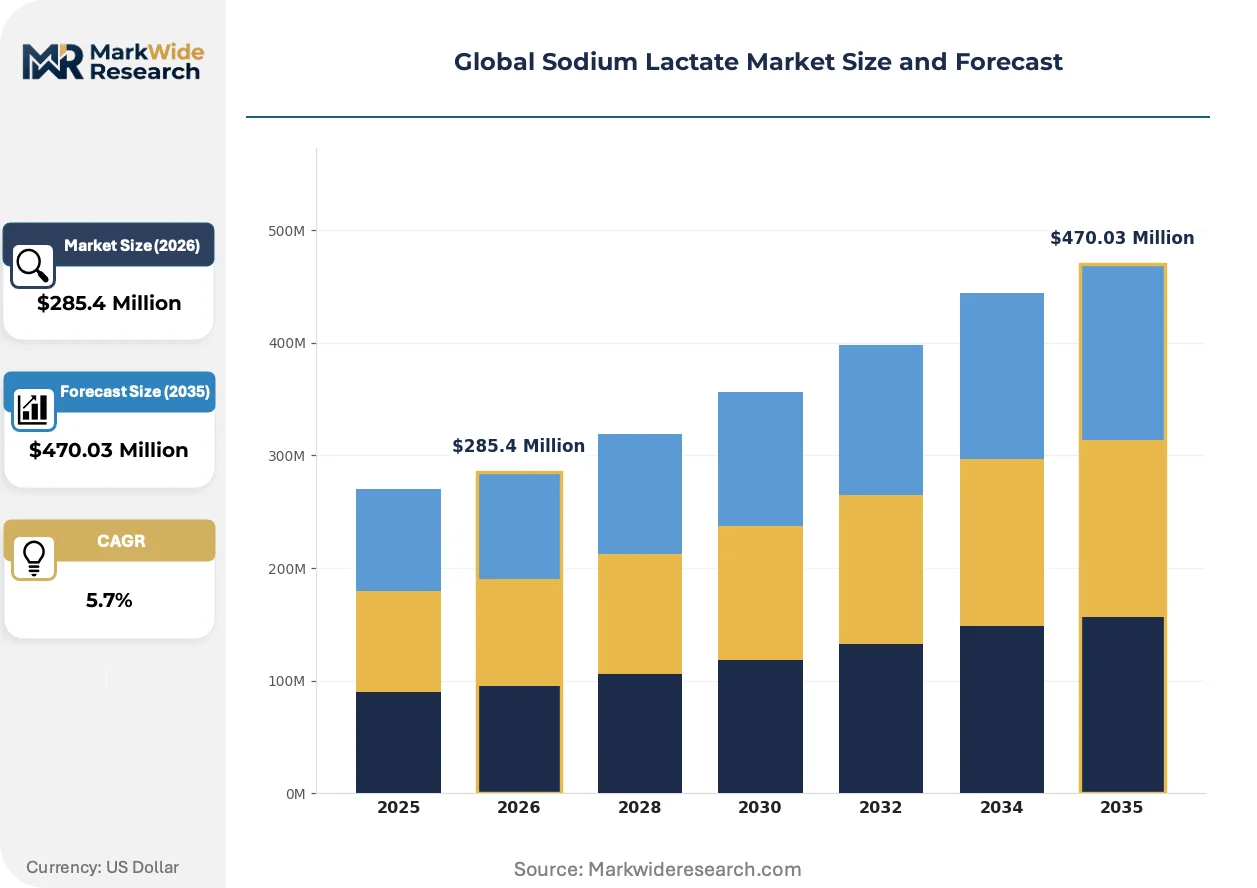
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $470.03 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Cosmetic Grade, Industrial Grade Application: Food Preservation, Biochemical Research, Cosmetic Formulations, Medical Applications End User: Food Industry, Healthcare Providers, Cosmetic Manufacturers, Research Institutions Distribution Channel: Online Retailers, Distributors, Wholesalers, Direct Sales |
| Companies Covered | Jungbunzlauer Suisse AG, Corbion N.V., Galactic S.A., Merck KGaA, Henan Jindan Lactic Acid Technology Co., Ltd., Dr. Paul Lohmann GmbH KG, Prathista Industries Limited, Cargill Incorporated, Biosynth Carbosynth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sodium Lactate Market Shifts & Advancements
Continuous fermentation and membrane filtration advances are compressing unit economics for high-purity grades, while regulatory divergence between food and pharmaceutical specifications is forcing parallel production line investments.
Cell-recycle fermentation technology is converging with nanofiltration purification to enable sustained high-cell-density operation with reduced substrate consumption. Pharmaceutical-grade producers in Switzerland and the Netherlands are retrofitting existing lactic acid plants with integrated electrodialysis systems. This convergence is compressing capital intensity per kilogram of USP-grade output, enabling mid-scale entrants to challenge established suppliers on specialty volumes.
EU REACH authorization requirements for substances of very high concern are expanding documentation burdens for sodium lactate importers, even where the substance itself is not restricted. The European Chemicals Agency is requiring enhanced supply chain transparency for fermentation-derived chemicals, including carbohydrate source verification. Food-grade importers are responding by securing dual-registered suppliers capable of providing batch-level substrate traceability.
Formulator procurement patterns are consolidating around suppliers offering integrated preservative systems rather than commodity sodium lactate alone. Meat processors are shifting from spot purchasing to annual framework agreements with fermentation houses capable of delivering pH-buffered blends with acetate or diacetate. This preference consolidation is most visible in the US, where Tyson Foods and JBS have reduced their qualified supplier bases by half since 2022.
Global Sodium Lactate Market Segmentation
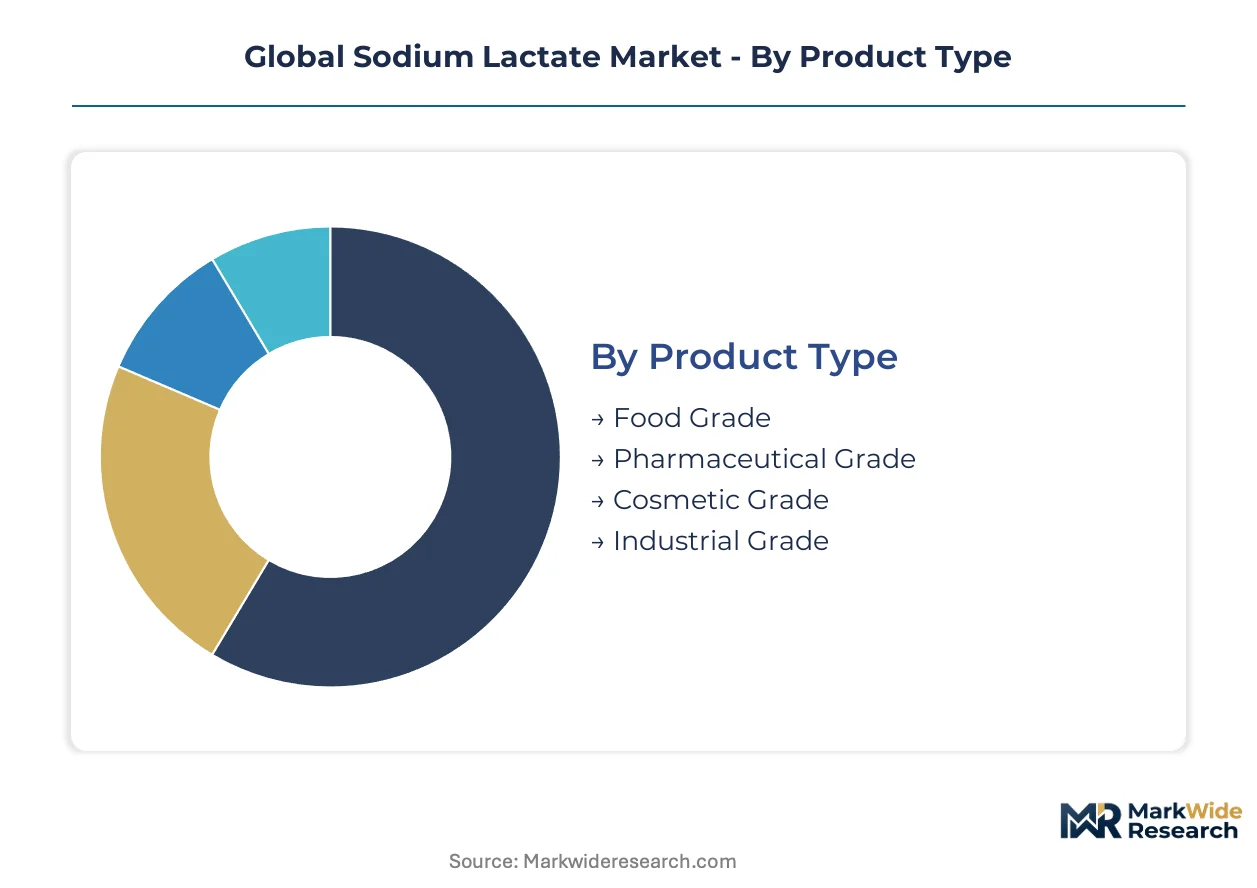
Sodium lactate market segmentation reveals distinct purity thresholds and compliance burdens that reshape supplier economics across food, pharmaceutical, and industrial channels. Grade-specific certification requirements create divergent margin structures and capital intensity profiles for fermentation-based producers.
Product Type:
Upgrade cycles in downstream applications are forcing grade-specific purification investments, with pharmaceutical and food channels demanding incompatible specification sets from shared fermentation infrastructure.
- Food Grade:Standard sodium lactate meeting FCC and JECFA specifications for pH buffering and moisture retention in processed proteins and baked goods. Demand concentrates in Germany and France where EFSA scrutiny on synthetic preservatives has accelerated clean-label substitution in processed meat applications.
- Pharmaceutical Grade:USP and EP-compliant material with endotoxin-controlled production for dialysis fluids and parenteral solutions. Demand concentrates in Switzerland and the Netherlands where GMP-certified fermentation platforms supply dialysis fluid manufacturers facing tightening EMA purity thresholds.
- Cosmetic Grade:Preservative alternative for paraben-free formulations in South Korean skin care.
- Industrial Grade:Technical-grade material for metal finishing and chemical synthesis applications.
Volume placements concentrate in Food Grade; the faster expansion belongs to Pharmaceutical Grade.
Application:
Cost tier differentiation separates commodity preservation from premium therapeutic applications, with certification overhead determining viable supplier pools.
- Food Preservation:Primary use in processed meat, poultry, and ready-to-eat meals for microbial inhibition and shelf-life extension. Tyson Foods and JBS have consolidated procurement around fermentation houses capable of delivering pH-buffered acetate blends through annual framework agreements rather than spot purchasing.
- Medical Applications:Dialysis fluid buffering, intravenous electrolyte replacement, and parenteral nutrition formulations. Endotoxin testing and chiral purity verification requirements strain working capital for mid-scale operators seeking USP-EP dual certification.
- Cosmetic Formulations:Humectant and preservative booster in leave-on skin care products.
- Biochemical Research:Cell culture media component and laboratory reagent.
Procurement concentration favors Food Preservation; Medical Applications command the steepest expansion trajectory.
End User:
Customer type determines contract structure, with industrial processors favoring annual volume commitments and research institutions requiring flexible batch sizing.
- Food Industry:Processed meat manufacturers, industrial bakeries, and ready-to-meal producers. Industrial bakeries in Mexico and Brazil are adopting sodium lactate for mold inhibition in packaged bread, replacing calcium propionate where clean-label positioning commands retail shelf access.
- Healthcare Providers:Hospital systems, dialysis clinics, and pharmaceutical compounders. EMA injectable-grade standards are consolidating demand around GMP-certified suppliers capable of endotoxin-controlled production for parenteral applications.
- Cosmetic Manufacturers:Skin care and personal care formulators seeking preservative alternatives.
- Research Institutions:Academic and commercial laboratories requiring analytical-grade material.
Contract volumes concentrate in Food Industry; Healthcare Providers show the fastest share gain.
Distribution Channel:
Supply concentration among integrated fermentation platforms shapes channel economics, with direct relationships dominating pharmaceutical-grade transactions.
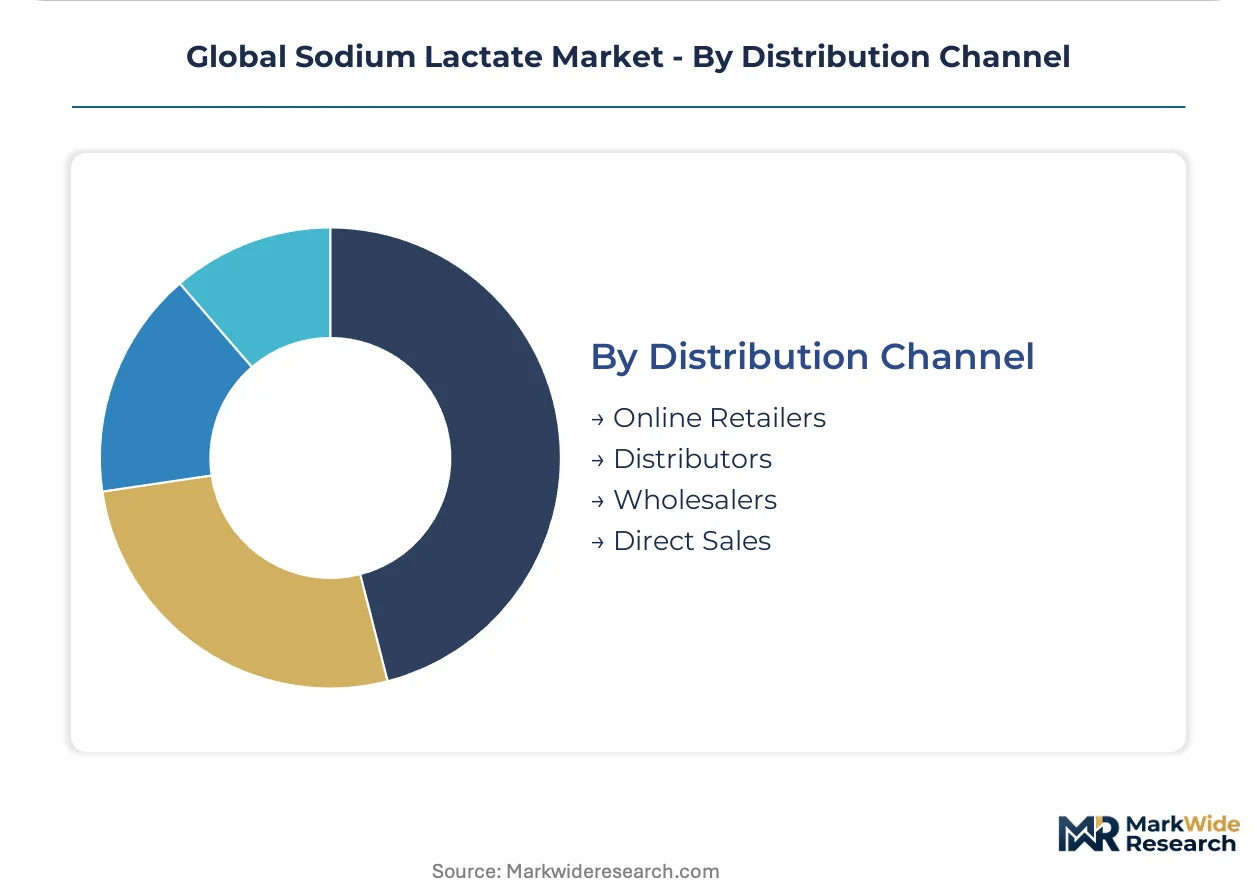
- Distributors:Regional chemical distributors serving food and industrial accounts with inventory-managed supply. REACH-registered pharmaceutical-grade capacity clusters among three integrated fermentation platforms, creating single-source vulnerability that distributors attempt to mitigate through dual-registration requirements.
- Direct Sales:Long-term supply agreements between fermentation houses and large-scale processors or pharmaceutical manufacturers. Corbion N.V. and Jungbunzlauer Suisse AG anchor positions through backward integration into lactic acid production, enabling supply security commitments.
- Online Retailers:E-commerce platforms for small-volume cosmetic and research-grade purchases.
- Wholesalers:Bulk intermediaries for commodity food-grade volumes.
Transaction value concentrates in Direct Sales; Online Retailers expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation capacity now absorbs the dominant share of regional sodium lactate consumption, while European pharmaceutical demand tightens purity specifications for dialysis fluid suppliers. Regulatory divergence between FDA food additive standards and EMA injectable-grade thresholds is fragmenting supplier qualification pathways across major consumption centers.
China
Henan and Shandong provinces host integrated lactic acid fermentation clusters supplying downstream sodium lactate for regional meat processors and pharmaceutical formulators. SAMR food additive standards and GB quality specifications govern domestic purity thresholds, with provincial governments incentivizing capacity expansion through carbon-reduction credits. Zhengzhou-based fermentation platforms are capturing share from imported European material in clean-label bakery and processed meat applications.
United States
Tyson Foods and JBS procurement consolidation has halved qualified supplier bases since 2022, favoring fermentation houses delivering pH-buffered preservative blends. FDA food additive regulations and USDA meat inspection standards determine compliance burdens for sodium lactate integration into processed poultry and ready-to-eat categories. Nebraska and Iowa processing corridors anchor demand concentration, with direct supply agreements replacing spot purchasing for shelf-life extension formulations.
Germany
EFSA scrutiny on synthetic preservatives has accelerated sodium lactate substitution in processed meat applications across Bavaria and North Rhine-Westphalia production belts. REACH registration requirements and ECHA supply chain transparency mandates impose documentation burdens on fermentation-derived chemical imports. Cologne and Hamburg distribution hubs are consolidating procurement around dual-registered suppliers capable of batch-level carbohydrate substrate traceability.
Switzerland
Swissmedic pharmaceutical standards and EMA injectable-grade specifications support premium positioning for GMP-certified sodium lactate in dialysis fluid production. Basel and Zurich pharmaceutical manufacturing clusters demand endotoxin-controlled material for parenteral applications, with validation cycles extending 18-24 months for new supplier qualification. Jungbunzlauer Suisse AG anchors regional supply security through captive lactic acid fermentation infrastructure.
South Korea
MFDS tightening of preservative safety reviews is driving sodium lactate qualification for paraben-free cosmetic formulations in Seoul and Gyeonggi-do skin care manufacturing. Domestic fermentation capacity remains limited, creating import dependency for pharmaceutical-grade material meeting KFDA pharmaceutical standards. Incheon and Busan port logistics are optimizing for just-in-time delivery to cosmetic compounders seeking clean-label preservative alternatives.
Global Sodium Lactate Market Competitive Landscape
European producers anchor the pharmaceutical-grade tier; Chinese fermentation specialists hold volume leverage in food-grade channels. Supplier concentration clusters around three integrated platforms capable of USP-EP dual certification, while mid-scale regional operators struggle to justify capital-intensive QC infrastructure for endotoxin-controlled production. Competitive positioning stratifies across backward-integrated fermentation houses, specialty pharmaceutical-grade pure-play suppliers, and diversified carbohydrate processors. Capacity expansion and strategic partnerships represent the dominant competitive moves, with bioplastic feedstock pivots creating demand overlap for existing lactic acid infrastructure.
Among European fermentation platforms, Jungbunzlauer Suisse AG and Corbion N.V. exemplify the integrated archetype through captive lactic acid production, while Galactic S.A. occupies a position within the specialty pharmaceutical-grade tier. These three names anchor the REACH-registered supplier base that dialysis fluid manufacturers depend upon for endotoxin-controlled material. Henan Jindan Lactic Acid Technology Co., Ltd. represents the Chinese volume-driven model leveraging domestic carbohydrate substrate access for regional food and pharmaceutical integration.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse AG |
| Corbion N.V. |
| Galactic S.A. |
| Merck KGaA |
| Henan Jindan Lactic Acid Technology Co., Ltd. |
| Dr. Paul Lohmann GmbH KG |
| Prathista Industries Limited |
| Cargill Incorporated |
| Biosynth Carbosynth |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade certification overhead against food-grade commodity positioning splits sodium lactate economics into divergent margin structures that reshape supplier investment priorities and buyer procurement patterns across fermentation-based production networks.
Pricing Analysis
Volume placements concentrate in food-grade contract structures while pharmaceutical-grade volumes command margin premiums through USP-EP dual certification burdens. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects endotoxin testing overhead and chiral purity verification requirements. Cost compression in food-grade channels is intensifying because carbohydrate substrate volatility transmits directly to spot pricing. Processed meat manufacturers exhibit highest price sensitivity through consolidated annual framework agreements, whereas dialysis fluid manufacturers accept premium positioning for GMP-certified supply security.
Supply Chain Analysis
REACH registration and EMA injectable-grade standards gate European pharmaceutical supply, concentrating qualified capacity among Switzerland, the Netherlands, and Germany. Raw material flows draw from US Corn Belt carbohydrate substrates, Brazilian molasses, and Chinese domestic corn starch. Single-source vulnerability clusters around three integrated fermentation platforms serving dialysis manufacturers. Distribution runs through direct long-term agreements for pharmaceutical grades and regional chemical distributors for food and industrial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade endotoxin-controlled production capacity functions as the binding constraint propping pricing power for qualified suppliers across the analysis window.
For Market Incumbents: Anticipate potassium lactate substitution pressure in processed meat by deepening captive lactic acid fermentation infrastructure and securing dual-registered status for ECHA supply chain transparency mandates. Prioritize membrane filtration retrofit investments to compress unit economics against mid-scale challengers. For New Entrants and Emerging Players: Launch via cosmetic-grade qualification pathways in South Korea where MFDS preservative safety reviews drive paraben replacement demand. Target industrial bakery channels in Mexico and Brazil with clean-label mold inhibition positioning. Pursue toll manufacturing arrangements with existing lactic acid platforms to bypass capital-intensive QC infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale fermentation operators possessing USP-EP dual certification capability given EMA injectable-grade standard tightening. Long-term viability hinges on backward integration into carbohydrate substrate sourcing. Monitor bioplastic feedstock pivot announcements as demand overlap signal for existing lactic acid infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive lactic acid fermentation secures supply continuity against carbohydrate price volatility. |
| GMP Line Certification | EMA injectable-grade compliance opens dialysis fluid and parenteral nutrition supply contracts. |
| Membrane Filtration Retrofit | Nanofiltration and electrodialysis compression reduces capital intensity per kilogram of USP-grade output. |
| Cosmetic-Grade Qualification | MFDS-aligned paraben-free preservative positioning captures South Korean skin care formulation demand. |
| Long-term Supply Agreement | Annual framework contracts with Tyson Foods and JBS procurement consolidate food-grade volume placements. |
Research Methodology
Document review covered FDA food additive regulations, EMA injectable-grade specifications, REACH registration databases, and SEC filings from listed fermentation houses, complemented by interviews with plant managers at integrated lactic acid platforms, procurement leads at processed meat manufacturers, dialysis fluid supply chain directors, and cosmetic formulators in South Korea. Secondary validation drew from customs and trade data, EFSA additive safety assessments, and USP monograph updates. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and application channels.
Cross-referencing historical price series against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled included grade tier, end-use industry, and regional regulatory cluster. CAGRs derived from trend extrapolation adjusted for capacity expansion announcements and substrate cost assumptions. Forecast inputs incorporated fermentation yield improvements and regulatory divergence scenarios between FDA and EMA specifications.
Carbohydrate substrate price shocks, REACH authorization timeline extensions, and bioplastic feedstock demand overlap are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding GMP certification retention and clean-label substitution velocity. A model refresh is warranted upon material change in EMA injectable-grade purity thresholds or SAMR food additive standard harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Bulk Ferroalloys Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Global Linear Alkyl Benzene Market
Bulk Chemicals
Global Tetrahydrofuran Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
Stilbene Market
Bulk Chemicals
White Charcoal Powder Market