
 United States Starch Derivatives Market | 2026-2036
United States Starch Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
United States Starch Derivatives Market Analytics
The premium-modified starch tier is consolidating around high-performance clean-label solutions while commodity native starch faces margin compression from overcapacity. Archer Daniels Midland Company leverages its Decatur, Illinois, wet milling complex to sustain captive supply chains for food-grade maltodextrins. Cargill Incorporated competes through backward integration into corn processing, controlling origination through its Iowa and Nebraska elevator networks. Ingredion Incorporated differentiates via specialty texture systems for plant-based meat analogs, occupying a defensible niche in the higher-margin modified starch segment.
Starch derivatives encompass chemically, physically, or enzymatically altered corn, potato, tapioca, or wheat starch molecules engineered to deliver specific viscosity, stability, or film-forming properties for industrial and consumer applications. These compounds function as thickeners, binders, encapsulants, and fat replacers across formulated product categories. Modified starch commands the dominant value share due to its tailored functionality in processed foods and pharmaceutical tableting, while native starch retains volume leadership in lower-specification applications. Dextrins are gaining traction in adhesives and soluble fiber fortification, though margin pools remain thinner than in modified starch specialties.
FDA GRAS notifications and USDA BioPreferred program requirements shape product development pathways and federal procurement eligibility for domestic starch derivative suppliers. EPA biofuel blending mandates indirectly influence corn starch feedstock availability and pricing dynamics through competing demand from ethanol processors. State-level food safety regulations in California and New York add compliance layers for cross-border distribution. Stakeholders must monitor evolving FDA guidance on novel starch modification processes and assess whether bio-based certification investments align with tightening federal sustainability procurement standards.
Market Dynamics
Clean-label formulation mandates from major food retailers are compressing demand for chemically modified starches while enzymatic and physical modification processes gain formulation share across Midwest processing corridors.
Growth Catalysts
- USDA BioPreferred procurement mandates:Federal agencies must prioritize domestically sourced bio-based starch derivatives for food service contracts, redirecting supplier qualification efforts toward Iowa and Illinois wet milling clusters.
- Plant-based meat analogs:Food technologists require specialty texture systems that replicate animal protein mouthfeel, creating specification pull for high-performance modified starches in extruded and formed applications.
- FDA GRAS pathway streamlining:Updated determinations for novel enzymatic modification processes accelerate time-to-market for clean-label alternatives to traditional chemically modified starches.
Market Restraints
- Corn feedstock concentration:Over 70% of domestic starch derivative supply chains originate within 200 miles of Decatur, Illinois, creating systemic weather and logistics vulnerability.
- Enzymatic modification cost premiums:Clean-label physical and enzymatic processes require 15-40% higher capital intensity than conventional chemical modification, compressing mid-tier processor margins.
- Cellulose and gum substitution:Hydrocolloid suppliers are displacing modified starches in select sauce and dressing applications where freeze-thaw stability requirements have relaxed.
Strategic Opportunities
- Southeast processing corridor expansion:Underutilized grain handling infrastructure in Georgia and Alabama offers greenfield sites for derivative production serving Atlantic Coast food manufacturers.
- Pharmaceutical excipient certification:USP-NF compliance for pregelatinized starches opens high-margin tablet binding and controlled-release applications with pricing multiples above food-grade equivalents.
- Bioplastics feedstock pivot:Polylactic acid and thermoplastic starch compounders are contracting directly with wet millers for specification-controlled dextrin supply, bypassing traditional distribution.
Industry Challenges
- Clean-label reformulation timelines:Food manufacturers face 18-24 month product redevelopment cycles to substitute enzymatically modified starches without altering established sensory profiles.
- Specialized process engineering scarcity:Wet milling facilities require retrofit investment for enzymatic modification capability, and qualified engineering firms with starch-specific expertise remain concentrated in Corn Belt metropolitan areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Starch Derivatives Market |
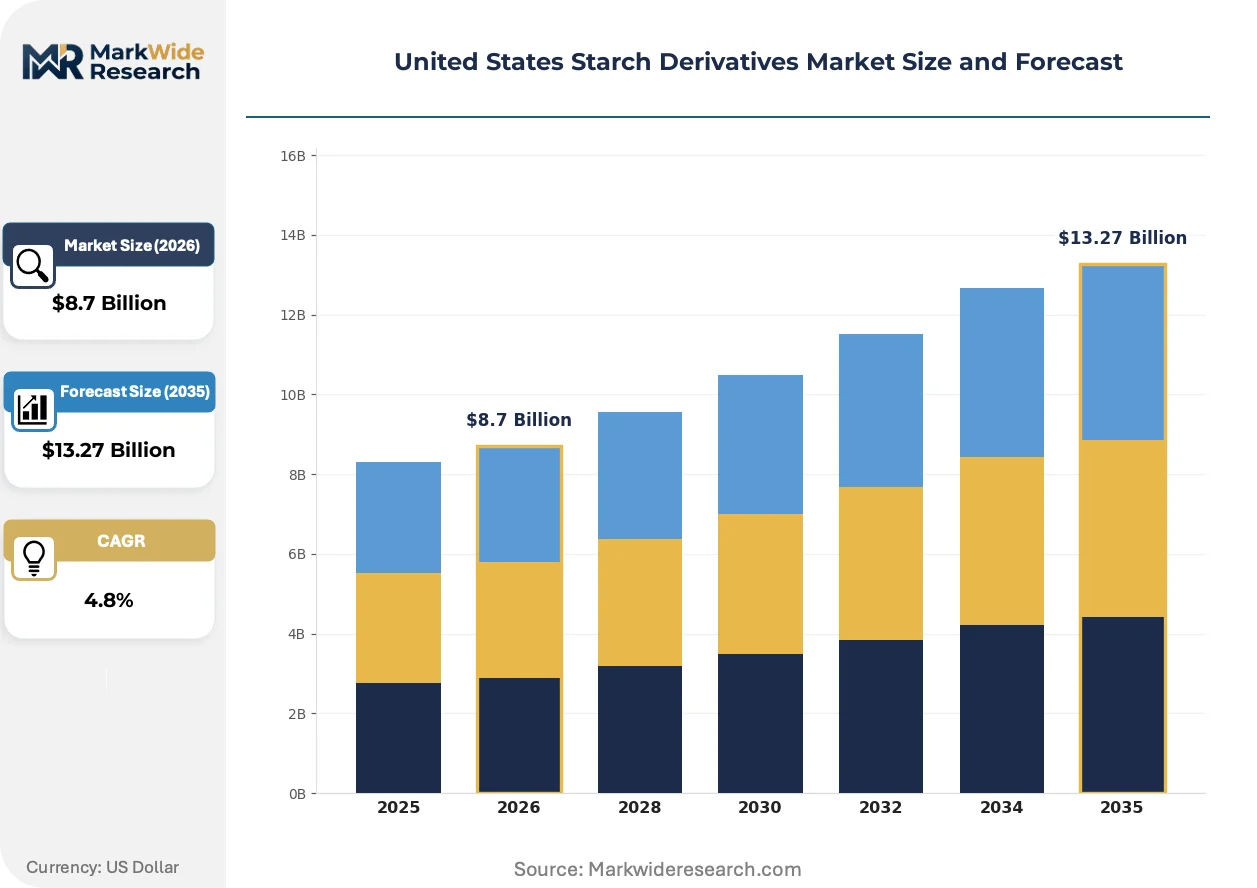
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Native Starch, Dextrins, Starch Esters Application: Food & Beverage, Pharmaceuticals, Cosmetics, Textiles End User: Food Manufacturers, Healthcare Providers, Cosmetic Brands, Chemical Companies Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Ingredion Incorporated, Tate & Lyle PLC, Tereos S.A, Roquette, AGRANA Beteiligungs-AG, Primient, Grain Processing Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Starch Derivatives Market Evolving Landscape
Enzymatic debranching technologies are displacing conventional chemical cross-linking as the dominant modification pathway for premium food applications, with equipment suppliers reporting order backlogs for continuous enzyme reactor systems.
Enzymatic modification using pullulanase and branching enzymes enables precise molecular weight control for clean-label viscosity building. Major sauce and dressing manufacturers are adopting these systems at pilot scale ahead of 2025 reformulation deadlines. This capability is converging with extrusion-cooked snack applications where expansion and texture must be maintained without E-number chemical modifiers.
The FDA's updated GRAS notification framework for novel starch modification processes reduces regulatory uncertainty for enzymatic and physical treatment methods. Ingredient suppliers are filing expanded use petitions for pregelatinized and cold-water-swelling starches in refrigerated and frozen applications. Clean-label frozen dessert and ready-meal segments are responding with accelerated specification changes that exclude chemically modified alternatives.
Food manufacturers are consolidating supplier relationships around vertically integrated wet millers capable of certifying farm-to-formulation traceability. Direct contracting is displacing traditional ingredient distribution for mid-to-large scale processors seeking lot-level origin documentation. This pattern is most visible in California and Pacific Northwest markets where retailer clean-label mandates have advanced furthest.
United States Starch Derivatives Market Segmentation
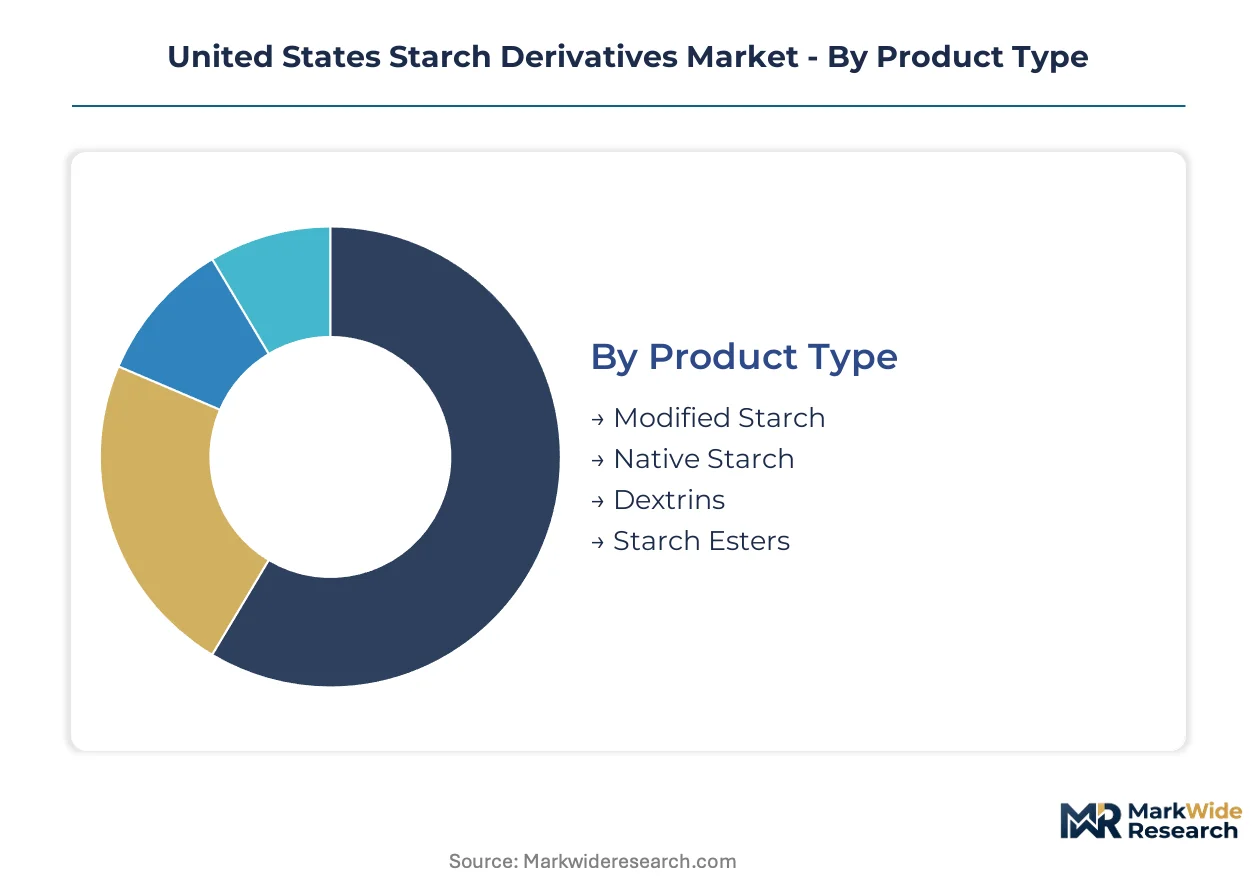
Starch derivative purchasing patterns diverge sharply between commodity bulk buyers and specialty formulators seeking certified traceability. The segmentation reveals how enzymatic modification capabilities are redrawing competitive boundaries across Midwest wet milling clusters.
Product Type:
Modified starch commands premium pricing while native starch retains volume dominance across Iowa and Illinois processing corridors.
- Modified Starch:Chemically, physically, or enzymatically altered molecules engineered for specific viscosity, stability, or film-forming properties. Food technologists in plant-based meat analog applications specify high-performance variants for extruded texture systems, with enzymatic debranching processes gaining formulation share ahead of retailer clean-label deadlines.
- Native Starch:Unmodified corn, potato, tapioca, or wheat starch retaining original granular structure. Paperboard adhesive manufacturers in the Southeast and lower-specification food processors absorb volume, though margin compression from overcapacity limits processor investment in capacity expansion.
- Dextrins:Partially hydrolyzed starch products with reduced molecular weight and increased solubility. Adhesive compounders and soluble fiber fortification applications in Georgia and Alabama processing corridors are contracting directly with wet millers.
- Starch Esters:Esterified derivatives providing emulsification and encapsulation functionality. Pharmaceutical tableting and controlled-release applications in New Jersey and North Carolina clusters require USP-NF compliance certification.
Today's leader: Modified Starch. Tomorrow's challenger: Dextrins.
Application:
Food and beverage formulation absorbs the dominant procurement volume, though pharmaceutical excipient certification opens the steepest expansion trajectory for margin-focused suppliers.
- Food & Beverage:Thickeners, binders, fat replacers, and texture modifiers across sauces, dressings, snacks, and frozen desserts. Clean-label reformulation mandates from California and Pacific Northwest retailers are compressing demand for chemically modified options.
- Pharmaceuticals:Tablet binders, disintegrants, and controlled-release matrices requiring USP-NF monograph compliance. Pregelatinized starch specifications for immediate-release and sustained-release formulations command pricing multiples above food-grade equivalents.
- Cosmetics:Film-forming agents and viscosity builders in skincare and haircare formulations. Mid-Atlantic and California formulators are consolidating supplier relationships around domestically sourced, bio-preferred certified derivatives.
- Textiles:Warp sizing agents and fabric finishing compounds. Carolina textile corridors maintain steady demand for acid-thinned and oxidized starch variants despite sectoral consolidation.
Food & Beverage anchors current procurement. Pharmaceuticals represent the fastest-climbing margin tier.
End User:
Food manufacturers drive specification complexity while healthcare procurement offices impose federal bio-preferred compliance requirements.
- Food Manufacturers:CPG formulators across Midwest and Southeast processing corridors requiring lot-level origin documentation for retailer clean-label mandates. Direct contracting with vertically integrated wet millers is displacing traditional ingredient distribution.
- Healthcare Providers:Hospital systems and long-term care facilities subject to USDA BioPreferred procurement mandates for food service contracts. Federal agency sourcing prioritizes domestically certified bio-based derivatives from Iowa and Illinois supply chains.
- Cosmetic Brands:Clean beauty formulators in California and New York seeking farm-to-formulation traceability for marketing claims. EWG verification and retailer sustainability scorecards are tightening feedstock documentation requirements.
- Chemical Companies:Industrial adhesive, paper, and bioplastics compounders. Polylactic acid and thermoplastic starch processors are bypassing distribution to contract directly with specification-controlled dextrin suppliers.
Food Manufacturers dominate volume. Chemical Companies are gaining specification influence fastest.
Distribution Channel:
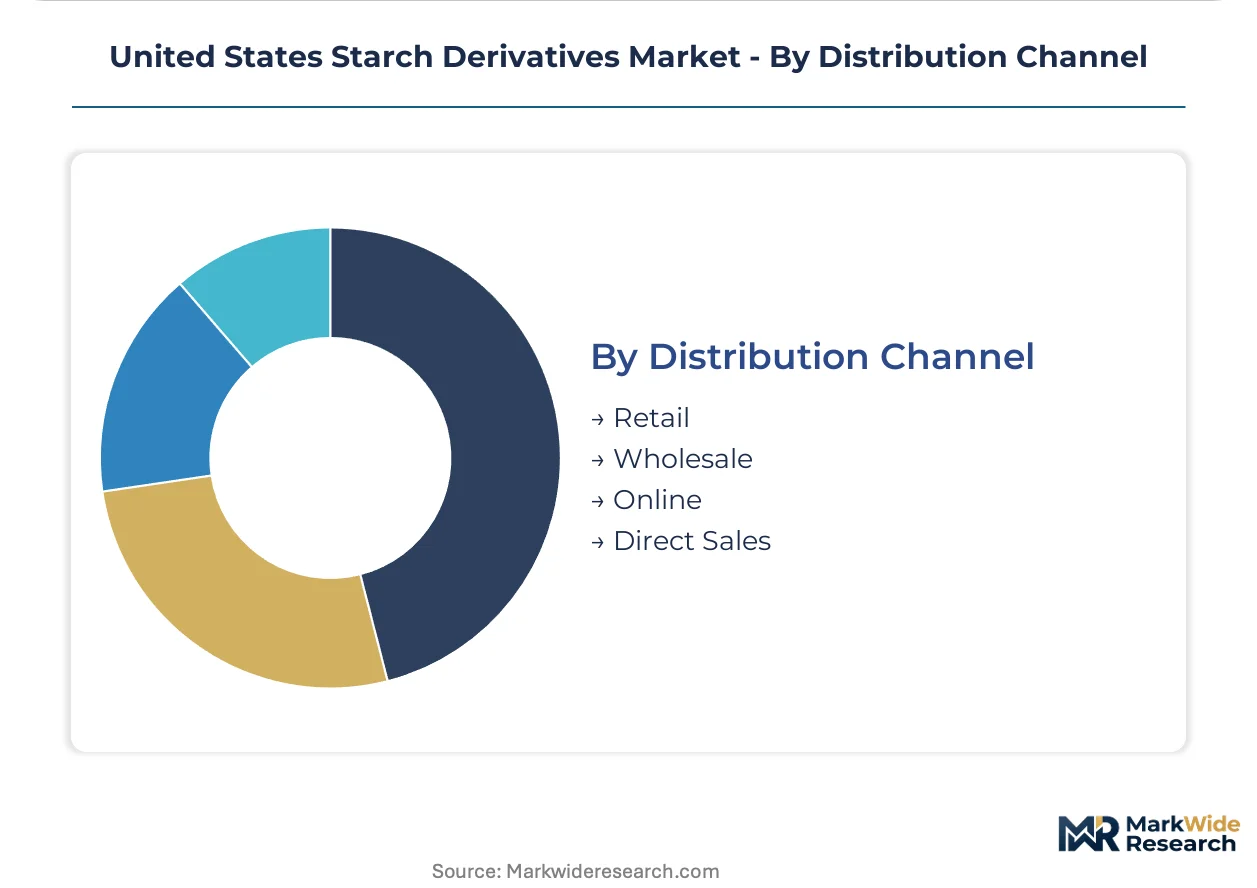
Channel selection correlates with customer scale and certification complexity, with direct relationships consolidating among mid-to-large processors.
- Retail:Small-scale food processors and artisanal manufacturers purchasing bagged native starch through agricultural supply cooperatives. Limited penetration in modified starch specialties due to technical support requirements.
- Wholesale:Regional distributors serving independent food manufacturers and textile processors across secondary markets. Inventory concentration in Decatur, Illinois, and Cedar Rapids, Iowa, logistics hubs.
- Online:Emerging procurement channel for sample quantities and specialty grades, particularly among cosmetic startups and pharmaceutical R&D laboratories. Limited to non-bulk volumes due to freight economics.
- Direct Sales:Vertically integrated wet millers contracting directly with national food manufacturers and federal procurement offices. Traceability certification and long-term supply agreements characterize these relationships.
Direct Sales commands premium relationships. Wholesale retains intermediary dominance in fragmented customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's starch derivative demand tracks roughly one-tenth of United States volumes, though both markets face parallel clean-label reformulation pressures from major retailers. The two countries share integrated corn supply chains through Great Lakes shipping corridors, yet regulatory divergence on bio-preferred procurement creates distinct supplier qualification pathways.
Midwest Corn Belt
Iowa, Illinois, and Nebraska concentrate over seventy percent of domestic wet milling capacity for food-grade maltodextrins and modified starches. The USDA BioPreferred program mandates federal agencies prioritize domestically sourced bio-based derivatives, redirecting supplier audits toward Decatur, Illinois, and Cedar Rapids, Iowa, processing clusters. Archer Daniels Midland leverages its Decatur complex to sustain captive supply chains serving Atlantic Coast food manufacturers.
Southeast Processing Corridor
Georgia and Alabama offer underutilized grain handling infrastructure for greenfield derivative production serving clean-label reformulation demand. State-level food safety regulations in adjacent Florida add compliance layers for cross-border distribution of enzymatically modified starches. Direct contracting between wet millers and national food manufacturers is displacing traditional ingredient distribution across Atlanta and Birmingham logistics hubs.
California and Pacific Northwest
Retailer clean-label mandates have advanced furthest in California, compressing demand for chemically modified starches while accelerating enzymatic process adoption. The state's food safety regulations require lot-level origin documentation that favors vertically integrated suppliers with farm-to-formulation traceability. Cosmetic formulators in Los Angeles and San Francisco consolidate supplier relationships around domestically sourced, bio-preferred certified derivatives for EWG verification compliance.
Mid-Atlantic Pharmaceutical Cluster
New Jersey and North Carolina host concentrated pharmaceutical tableting operations requiring USP-NF compliant pregelatinized starches for immediate-release and sustained-release formulations. FDA GRAS notifications for novel enzymatic modification processes reduce regulatory uncertainty for suppliers seeking excipient certification. These specifications command pricing multiples above food-grade equivalents, attracting backward integration investments from wet millers.
United States Starch Derivatives Market Competitive Landscape
Top-tier vendors anchor premium modified starch capabilities, while mid-tier processors struggle with enzymatic modification cost premiums. The vendor base stratifies across three tiers: integrated agricultural conglomerates controlling origination through elevator networks, specialty texture system developers occupying defensible niches in plant-based applications, and commodity native starch suppliers facing margin compression from overcapacity. Dominant competitive moves include backward integration into corn processing and direct contracting relationships that bypass traditional distribution channels.
Within the integrated agricultural tier, Archer Daniels Midland Company, Cargill Incorporated, and Ingredion Incorporated exemplify divergent strategic positioning. Decatur-based Archer Daniels Midland leverages its Illinois wet milling complex to sustain captive supply chains for food-grade derivatives. Cargill Incorporated controls origination through Iowa and Nebraska elevator networks, competing through upstream feedstock command. Ingredion Incorporated occupies a defensible niche in specialty texture systems for plant-based meat analogs, representing the higher-margin modified starch segment where enzymatic debranching capabilities differentiate supplier offerings.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Tereos S.A |
| Roquette |
| AGRANA Beteiligungs-AG |
| Primient |
| Grain Processing Corporation |
| Others |
Value Network & Pricing Analysis
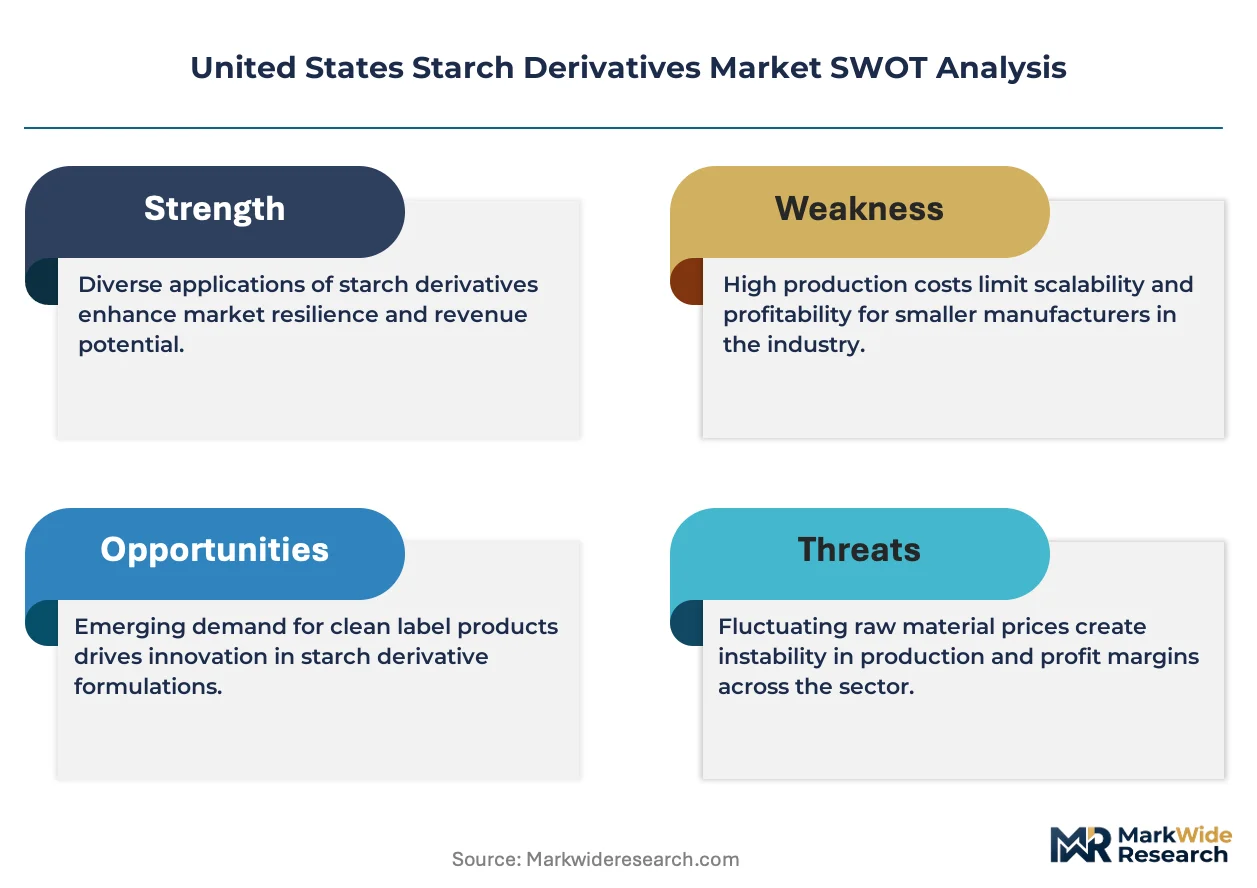
Enzymatic modification capability gaps between premium and commodity starch derivative tiers widen pricing spreads while concentrating supply relationships around Iowa and Illinois wet milling clusters with certified clean-label production. FDA GRAS pathway streamlining for novel enzymatic processes allows compliant suppliers to command sustained premiums, whereas chemically modified native starch faces margin erosion from overcapacity and substitution by hydrocolloids.
Pricing Analysis
Capacity additions in Georgia and Alabama are reshaping price floors for Southeast food manufacturers seeking alternatives to Midwest supply concentration. Three-tier pricing structure across premium enzymatic, standard chemically modified, and economy native starch levels reflects certification grade and volume scale differentiation. Price erosion runs through commodity native starch as paperboard adhesive manufacturers absorb surplus volume. Food manufacturers specifying clean-label enzymatic derivatives demonstrate lowest price sensitivity; small-scale textile processors exhibit highest.
Supply Chain Analysis
Regional distribution centers in Decatur, Illinois, and Cedar Rapids, Iowa, anchor hub-and-spoke patterns serving Atlantic Coast food manufacturers. Geographic supply concentration centers on the United States Corn Belt, with secondary nodes in Canada through Great Lakes shipping corridors. Raw material dependencies draw from corn feedstock, enzyme inputs for modification processes, and natural gas for drying operations. Single-source vulnerability stems from over seventy percent of wet milling capacity originating within two hundred miles of Decatur. Distribution runs through direct contracting relationships that bypass traditional wholesale channels for mid-to-large processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States starch derivatives market represents a late-cycle quality story as retailer clean-label mandates compress demand for chemically modified grades and concentrate procurement around enzymatic capability holders.
For Market Incumbents: Acquire enzymatic modification engineering expertise and USP-NF pharmaceutical certification assets to defend against cellulose and gum substitution in sauce applications. Backward integration into Nebraska and Iowa elevator networks secures origination control amid corn feedstock concentration risks. Prioritize retrofit investments for continuous enzyme reactor systems ahead of retailer reformulation deadlines. For New Entrants and Emerging Players: Specialty enzymatic debranching technology for plant-based meat analog texture systems offers the most penetrable wedge against integrated agricultural conglomerates. Target Southeast processing corridor greenfield sites in Georgia and Alabama serving Atlantic Coast clean-label demand. Pursue direct contracting with mid-scale food manufacturers seeking lot-level traceability documentation. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty texture system developers possessing enzymatic capabilities and pharmaceutical excipient certifications. Long-term viability hinges on differentiation beyond commodity native starch production. Monitor FDA guidance timeline on novel starch modification processes as inflection indicator for clean-label premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Capability Acquisition | Secures FDA GRAS-compliant production pathways for clean-label formulation demand from California retailers. |
| Pharmaceutical Excipient Certification | Opens USP-NF tablet binding applications with pricing multiples above food-grade maltodextrin equivalents. |
| Southeast Corridor Capacity Expansion | Reduces logistics vulnerability from Midwest concentration while serving Atlantic Coast food manufacturer procurement. |
| Direct Contracting Relationships | Bypasses wholesale distribution to capture traceability premiums from federal BioPreferred procurement mandates. |
| Bioplastics Feedstock Pivot | Supplies specification-controlled dextrins to polylactic acid compounders seeking alternative revenue streams. |
Research Methodology
Bottom-up food and beverage formulation modeling reconciled against top-down wet milling capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Midwest processing facilities, procurement leads at downstream CPG manufacturers, distribution channel partners, and technical R&D directors in enzymatic modification engineering combined with secondary validation from USDA BioPreferred program databases, FDA GRAS notification filings, SEC 10-K disclosures, and corn wet milling trade association reports. Triangulation across these sources reconciles volume estimates with facility-level production data.
Input-output matrices map enzymatic modification capacity, clean-label certification status, and end-use application requirements across the projection horizon. Segmentation dimensions modeled include product modification type, application sector, end-user procurement scale, and regional processing cluster. CAGRs derive from capacity utilization trends, substitution elasticity estimates, and federal procurement mandate implementation pacing. Corn feedstock availability and enzyme reactor installation backlogs inform supply-side constraints.
The model holds under sustained retailer clean-label mandate enforcement; deviation in FDA guidance timelines or hydrocolloid substitution acceleration would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
North America Vinyl Chloride Monomer Market
Bulk Chemicals
Global Vinyl Chloride Monomer Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Mangiferin Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Phthalic Anhydride Market
Bulk Chemicals
Cesium Salts Market
Bulk Chemicals
Tertiary Butylhydroquinone Market