
 Global Linear Alkyl Benzene Market | 2026-2036
Global Linear Alkyl Benzene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Linear Alkyl Benzene Market Outlook
Long-term supply contracts with embedded maintenance and technical service clauses is rebalancing how producers capture value beyond base chemical sales. Sasol leverages its Fischer-Tropsch integration to secure feedstock autonomy across Southern African operations. Chevron Phillips Chemical anchors North American supply through Gulf Coast paraffin infrastructure. Reliance Industries dominates Indian domestic volume with captive refinery linkages at Jamnagar.
Linear alkyl benzene consists of phenyl groups attached to linear alkyl chains ranging from C10 to C14, produced via UOP Pacol-Olex hydrogenation and dehydrogenation of kerosene-derived normal paraffins, primarily serving as the precursor for linear alkylbenzene sulfonate surfactants in detergent formulations. Regular linear alkyl benzene sustains the largest volume share as workhorse feedstock for commodity laundry powders and liquids across emerging economies. Sulfonated linear alkyl benzene occupies higher-margin positions where downstream integration into finished surfactant blends reduces logistics complexity for detergent compounders.
EPA regulations under the Safer Choice program and REACH restrictions on non-biodegradable surfactants compel reformulation toward linear structures with higher bioaccumulation safety profiles. India's BIS certification and China's GB standards for detergent active content create divergent compliance thresholds that fragment technical specifications across export destinations. Stakeholders must monitor regulatory tightening on aquatic toxicity thresholds as the primary signal for next-generation product development priorities.
Market Dynamics
Feedstock volatility and regulatory tightening on aquatic toxicity are compressing margins while forcing rapid reformulation toward biodegradable linear alkylbenzene sulfonate precursors.
Growth Catalysts
- EPA Safer Choice mandates:Detergent compounders in the United States face binding surfactant biodegradability thresholds that favor linear alkyl benzene over branched alternatives.
- Household care industrialization:India's rural detergent penetration accelerates as packaged goods distribution reaches tier-3 cities and small towns.
- Kerosene-to-paraffin hydrogenation:Advances in UOP Pacol-Olex process efficiency reduce specific energy consumption per ton of linear alkyl benzene output.
Market Restraints
- Normal paraffin supply concentration:Gulf Coast cracking economics and Fischer-Tropsch output in Southern Africa limit feedstock diversification options.
- REACH aquatic toxicity thresholds:ECHA's tightening bioaccumulation limits extend compliance timelines and raise testing burdens for European exports.
- Natural fatty alcohol substitution:Oleochemical surfactants from palm and coconut feedstocks capture premium detergent segments in Western Europe.
Strategic Opportunities
- Indonesia's unpenetrated outer islands:Logistics infrastructure expansion opens detergent manufacturing zones beyond Java-centric production.
- Convergence of sulfonation and compounding:Integrated surfactant-detergent facilities reduce working capital cycles and freight costs for regional brands.
- China's dual carbon goals:MEE emissions intensity targets create preferential access for producers with carbon-accounted linear alkyl benzene supply chains.
Industry Challenges
- Specialized catalyst regeneration expertise:UOP Pacol-Olex unit maintenance requires scarce technical talent familiar with platinum-based dehydrogenation systems.
- BIS certification timelines:India's active content testing protocols delay product launches by four to six months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Linear Alkyl Benzene Market |
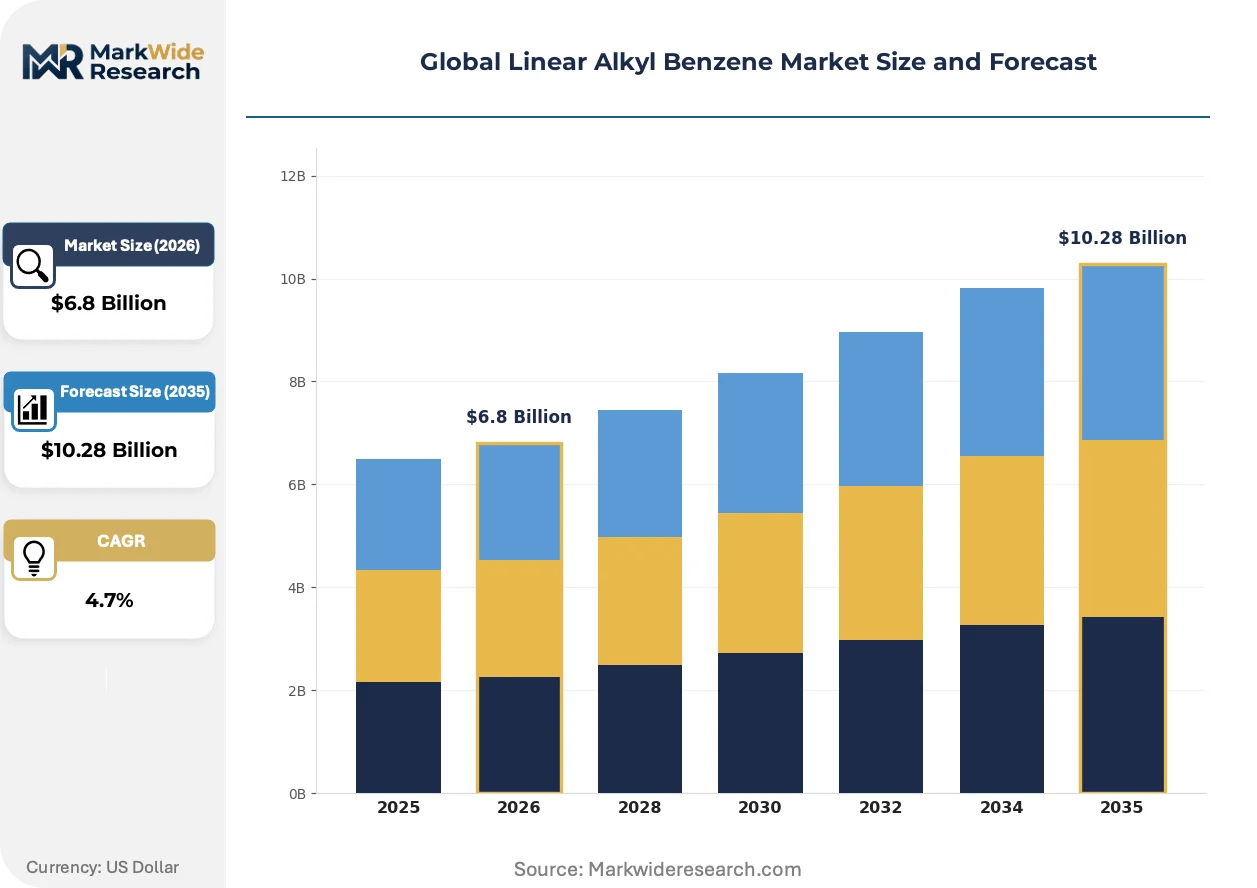
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Linear Alkyl Benzene, Branched Linear Alkyl Benzene, Modified Linear Alkyl Benzene, High-Purity Linear Alkyl Benzene, Sulfonated Linear Alkyl Benzene Application: Detergents, Textile Auxiliaries, Leather Processing, Emulsifiers, Plasticizers, Others End User Industry: Household Care, Personal Care Manufacturing, Paper & Pulp Industry, Agrochemicals, Construction Chemicals Packaging Type: Drums, ISO Tanks, Bulk Tankers, Fiber Drums, Intermediate Bulk Containers |
| Companies Covered | Sasol, Chevron Phillips Chemical, ExxonMobil, Shell, CEPSA, ISU Chemical, Reliance Industries, Fushun Petrochemicals, Indorama Ventures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Linear Alkyl Benzene Market Strategic Shifts
Process intensification and regulatory chemistry are redrawing where value accumulates across the linear alkyl benzene value chain, with downstream integration and carbon accounting emerging as decisive differentiators.
Modular sulfonation units is decentralizing surfactant production geography. Regional detergent brands in Southeast Asia now install containerized sulfonation capacity at distribution hubs rather than importing finished linear alkylbenzene sulfonate. This compression of the supply chain is reducing working capital requirements and enabling faster formulation iteration for local water hardness conditions.
REACH restrictions on non-biodegradable surfactants are forcing molecular redesign across European supply chains. ECHA's 2024 guidance on persistent organic pollutants extends testing protocols to trace impurities in linear alkyl benzene feedstocks. German and French detergent manufacturers now require certified low-bioaccumulation grades, fragmenting technical specifications and creating dual-tier procurement practices.
Long-term offtake contracting with embedded technical service clauses is displacing spot market purchasing among large detergent compounders. Buyers in India and China now negotiate five-year supply agreements that include catalyst performance monitoring and formulation optimization support. This shift locks in volume commitments while transferring process expertise upstream to specialized linear alkyl benzene producers.
Global Linear Alkyl Benzene Market Segmentation
Linear alkyl benzene producers face divergent technical specifications across detergent compounders, textile formulators, and industrial emulsifier buyers. Segmentation reveals where margin capture shifts from commodity volume to specialized grades.
Product Type:
Reformulation cycles in surfactant chemistry are driving selective upgrades from standard grades toward performance-optimized variants.
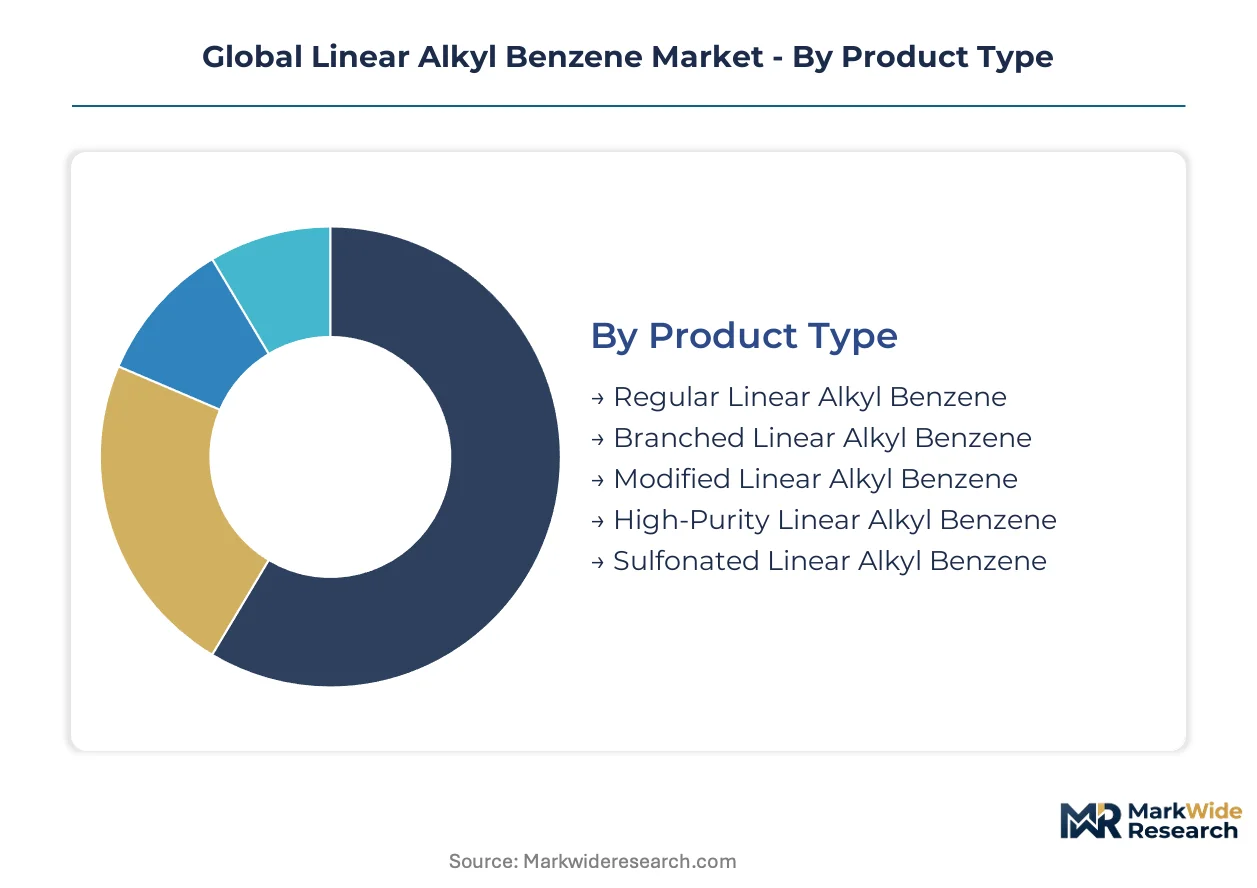
- Regular Linear Alkyl Benzene:Workhorse feedstock for commodity laundry powders and liquids, commanding the largest volume placement across India, China, and Indonesia as household care sectors industrialize. Kerosene-derived normal paraffin feedstock and UOP Pacol-Olex processing deliver cost-competitive sulfonation precursors for emerging economy detergent manufacturers.
- Sulfonated Linear Alkyl Benzene:Higher-margin position where downstream integration into finished surfactant blends reduces logistics complexity for regional detergent compounders. Modular sulfonation units at Southeast Asian distribution hubs accelerate adoption among brands seeking formulation control.
- Branched Linear Alkyl Benzene:Niche specialty for industrial emulsifier applications where cold-flow properties outweigh biodegradability requirements.
- Modified Linear Alkyl Benzene:Custom alkyl chain distributions tailored to specific hardness conditions in regional detergent formulations.
- High-Purity Linear Alkyl Benzene:Ultra-low impurity grades demanded by European REACH-compliant surfactant producers.
Volume placements concentrate in Regular Linear Alkyl Benzene; the faster expansion belongs to Sulfonated Linear Alkyl Benzene.
Application:
Cost tier differentiation separates mass-market detergent formulations from specialized industrial processing chemicals.
- Detergents:Dominant consumption channel spanning laundry powders, dish liquids, and hard surface cleaners across Asia-Pacific industrialization zones. EPA Safer Choice mandates and REACH biodegradability thresholds lock in linear structures over branched alternatives.
- Textile Auxiliaries:Scouring and wetting agent applications in Bangladesh and Vietnam garment processing clusters drive specialized emulsifier demand. Auxiliary formulators require consistent sulfonation reactivity for batch-to-batch stability.
- Leather Processing:Degreasing and fatliquoring applications in Indian and Pakistani tannery belts.
- Emulsifiers:Agrochemical and construction chemical dispersion applications.
- Plasticizers:Minor volume in flexible PVC processing.
- Others:Lubricant additives and specialty solvent applications.
Procurement volumes cluster in Detergents; margin expansion is steepest in Textile Auxiliaries.
End User Industry:
Customer type segmentation maps captive refinery linkages against merchant market purchasing patterns.
- Household Care:Packaged goods manufacturers across India's tier-2 and tier-3 city distribution networks. Unilever, Procter & Gamble, and regional champions drive formulation standardization toward concentrated liquids.
- Personal Care Manufacturing:Shampoo and body wash compounders in Southeast Asian free trade zones.
- Paper & Pulp Industry:De-inking and pitch control applications in Indonesian and Brazilian pulp mills.
- Agrochemicals:Emulsifiable concentrate formulations for pesticide dispersion.
- Construction Chemicals:Concrete admixture and asphalt emulsion applications.
Supply concentration sits with Household Care; Personal Care Manufacturing is climbing the fastest.
Packaging Type:
Logistics infrastructure maturity determines containerization economics across archipelagic and continental geographies.
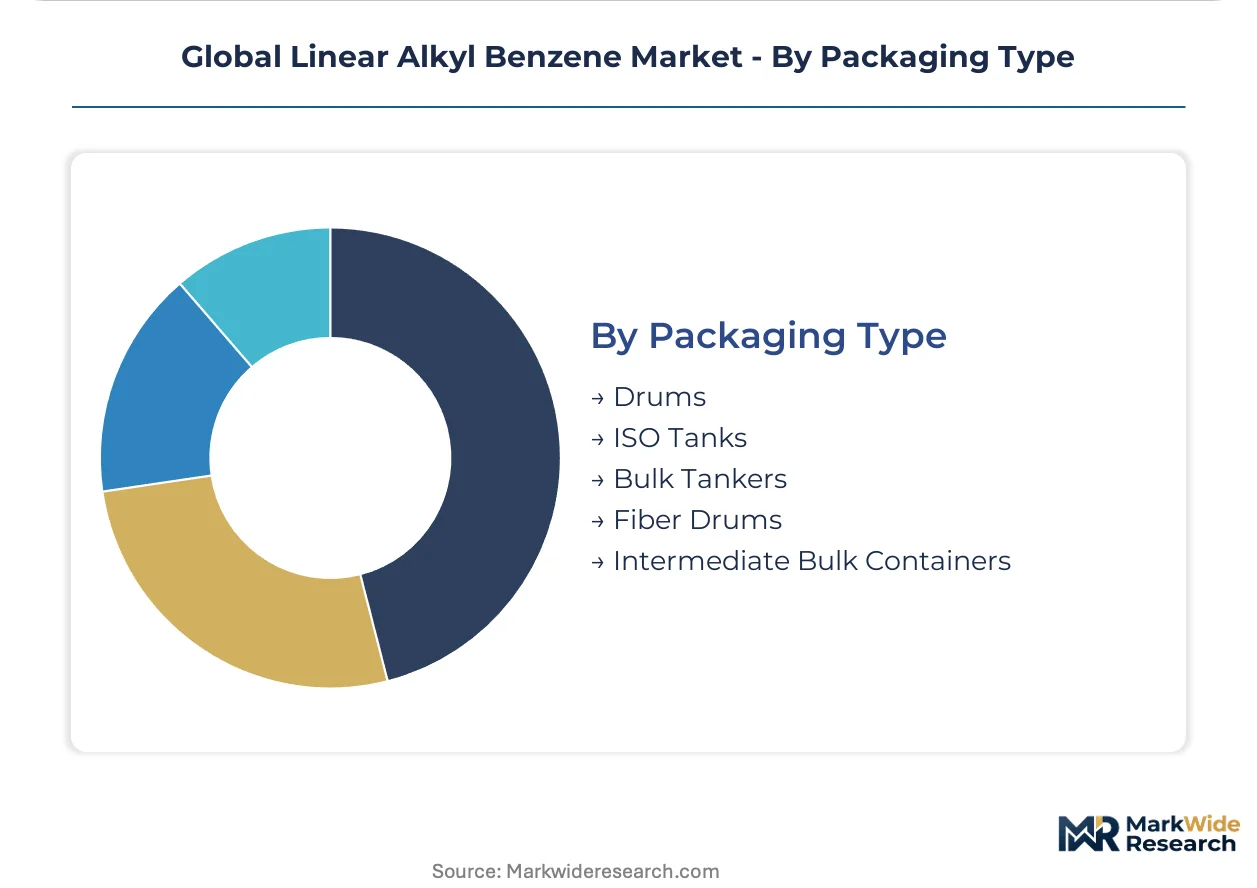
- Bulk Tankers:Refinery-integrated producers at Jamnagar, Lake Charles, and Secunda move product via dedicated chemical tanker fleets to large detergent compounding facilities. Volume scale justifies dedicated handling equipment and reduces per-unit freight burden.
- ISO Tanks:Intermodal flexibility serves mid-scale compounders in Indonesia's outer islands and India's northeast states. Containerized sulfonation units at distribution hubs pair with ISO tank deliveries for just-in-time surfactant production.
- Drums:Small-batch specialty chemical distributors and toll sulfonation operators.
- Fiber Drums:Powder handling for remote construction chemical applications.
- Intermediate Bulk Containers:Medium-volume textile auxiliary and leather processing formulators.
Freight economics favor Bulk Tankers; ISO Tanks are gaining share fastest in archipelagic Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in refinery-integrated complexes across the United States, South Africa, and India, while consumption growth concentrates in detergent manufacturing belts throughout Asia. This geographic split shapes trade flows and margin capture across the value chain.
United States
Gulf Coast petrochemical infrastructure anchors North American supply through kerosene-derived normal paraffin processing. EPA Safer Choice mandates enforce surfactant biodegradability thresholds that lock in linear structures over branched alternatives. Lake Charles and Houston host integrated detergent precursor manufacturing serving domestic compounders.
China
Household care industrialization across tier-2 and tier-3 cities drives expanding offtake for commodity laundry formulations. MEE emissions intensity targets under dual carbon goals create preferential access for producers with carbon-accounted supply chains. The Yangtze River Delta concentrates surfactant-detergent integration facilities serving domestic brands.
India
Rural detergent penetration accelerates as packaged goods distribution reaches tier-3 cities and small towns. BIS certification protocols for active content testing extend product launch timelines for new market entrants. The Jamnagar refinery complex maintains captive linear alkyl benzene output through integrated paraffin processing.
Indonesia
Logistics infrastructure expansion opens detergent manufacturing zones beyond Java-centric production networks. GB standards compliance for export-oriented surfactant producers fragments technical specifications across destinations. Outer island distribution hubs now host containerized sulfonation capacity for regional brands.
Germany
REACH aquatic toxicity thresholds and ECHA bioaccumulation limits extend compliance timelines for European surfactant exports. German detergent manufacturers require certified low-bioaccumulation grades, fragmenting procurement into dual-tier practices. The Rhine-Ruhr industrial belt concentrates specialized emulsifier and textile auxiliary formulators.
Global Linear Alkyl Benzene Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent margin capture models. The market structure consolidates around refinery-integrated majors, merchant chemical specialists, and regional detergent-integrated compounders. Three archetypes dominate: Fischer-Tropsch-integrated African operators, Gulf Coast paraffin-anchored North American producers, and Asian refinery-captive suppliers. Competitive moves center on backward integration into normal paraffin supply and forward integration into modular sulfonation services.
Among integrated energy-chemical conglomerates, Sasol and Chevron Phillips Chemical exemplify divergent feedstock strategies. Sasol occupies a position anchored to Fischer-Tropsch synthesis economics, while Chevron Phillips Chemical sits within Gulf Coast cracking infrastructure. Reliance Industries represents the refinery-captive archetype with domestic Indian volume dominance through integrated operations.
| Leading Market Players |
|---|
| Sasol |
| Chevron Phillips Chemical |
| ExxonMobil |
| Shell |
| CEPSA |
| ISU Chemical |
| Reliance Industries |
| Fushun Petrochemicals |
| Indorama Ventures |
| Others |
Value Chain & Pricing Dynamics
Refinery-integrated production economics anchor supply positions and pricing power across the linear alkyl benzene value chain, with captive kerosene-to-paraffin processing at Jamnagar, Lake Charles, and Secunda creating tiered cost structures that cascade into buyer negotiations. Long-term offtake contracting with embedded technical service clauses is displacing spot market purchasing, transferring value capture upstream to producers with catalyst performance monitoring capabilities.
Pricing Analysis
Margin tightening in commodity grades reflects normal paraffin supply concentration at Gulf Coast cracking complexes and Fischer-Tropsch facilities in Southern Africa. Three-tier pricing structure across REACH-certified premium, BIS-compliant standard, and economy grades fragments procurement practices, with European detergent compounders least price-sensitive due to regulatory compliance premiums while Indian regional brands drive aggressive cost-down negotiations. Cost compression accelerates as modular sulfonation units at Southeast Asian distribution hubs compress logistics premiums and enable just-in-time surfactant production.
Supply Chain Analysis
Reverse-logistics flows for spent platinum-based catalyst regeneration concentrate technical service expertise at UOP-licensed maintenance facilities in the United States, Germany, and Singapore. Supply draws from refinery-integrated complexes in India, the United States, and South Africa, with kerosene-derived normal paraffins, hydrogen feedstock, and specialized dehydrogenation catalysts as critical inputs. Single-source vulnerability sits with UOP Pacol-Olex technology licensing, constraining capacity expansion outside existing licensee networks. Distribution runs through dedicated chemical tanker fleets for integrated majors, ISO tank intermodal for mid-scale compounders, and drum shipments for toll sulfonation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over normal paraffin supply and forward integration into modular sulfonation services determine margin capture. Players are pursuing captive kerosene processing and containerized surfactant production as decisive levers.
For Market Incumbents: Extend catalyst performance monitoring services into five-year technical service clauses that lock in volume commitments from Indian and Chinese detergent compounders. Deepen captive paraffin supply through refinery integration or long-term offtake agreements with Fischer-Tropsch operators, defending against natural fatty alcohol substitution in European premium segments. Prioritize carbon-accounted supply chain certification to secure preferential access under China's MEE emissions intensity targets. For New Entrants and Emerging Players: Launch via ISO tank distribution partnerships targeting Indonesia's outer island detergent manufacturing zones beyond Java-centric production networks. Exploit BIS certification bottlenecks by building technical regulatory affairs capabilities that compress four-to-six month active content testing timelines for new market entrants. Target textile auxiliary formulators in Bangladesh and Vietnam garment processing clusters where sulfonation reactivity consistency commands formulation premiums. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated surfactant-detergent facilities with modular sulfonation capacity and regional brand relationships. Long-term viability across the projection horizon hinges on feedstock autonomy and downstream formulation control rather than commodity volume scale. Monitor EPA Safer Choice mandate expansion and ECHA bioaccumulation threshold tightening as inflection signals for next-generation biodegradable grade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Normal Paraffin Supply | Captive kerosene processing at Jamnagar and Secunda eliminates feedstock price volatility exposure. |
| Modular Sulfonation Unit Deployment | Containerized capacity at Indonesian distribution hubs reduces working capital cycles for regional brands. |
| REACH-Compliant Grade Certification | Ultra-low bioaccumulation grades unlock dual-tier procurement premiums from German compounders. |
| Long-Term Technical Service Contracting | Five-year agreements with catalyst monitoring transfer process expertise upstream to specialized producers. |
| Carbon-Accounted Supply Chain Development | Emissions intensity documentation secures preferential access under China's MEE dual carbon enforcement. |
Study Parameters
Multi-period observation of kerosene-to-paraffin cracking spreads, detergent active content pricing, and regulatory compliance timeline extensions anchored the trend analysis, supplemented by interviews with plant managers at integrated refinery-chemical complexes, procurement leads at downstream detergent compounders, UOP-licensed catalyst regeneration specialists, and distribution channel partners across Southeast Asian archipelagic logistics networks. Secondary validation drew from customs and trade flow databases, ACC and Cefic surfactant industry reports, SEC 10-K filings of integrated energy-chemical conglomerates, and EPA Safer Choice program documentation. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic drivers across the analysis window.
Segment-weighting approaches applied product type differentiation between regular and sulfonated grades, application concentration in detergents versus textile auxiliaries, end-user industry clustering around household care and personal care manufacturing, and packaging type logistics economics across bulk tanker, ISO tank, and drum distribution. CAGRs were derived from normalized baseline consumption and capacity expansion trajectories, incorporating UOP Pacol-Olex process efficiency improvements and regulatory-driven reformulation cycles as industry-specific forecast inputs throughout the projection horizon.
Feedstock price volatility, regulatory threshold tightening on aquatic toxicity, and natural oleochemical substitution acceleration are the dominant revision risks that could compress volume projections or accelerate grade migration timelines. Forecasts reflect documented assumptions on catalyst regeneration cycle frequencies and regional logistics infrastructure buildout rates. Practitioners should monitor EPA Safer Choice mandate scope expansion and ECHA persistent organic pollutant guidance updates for early signals of next-generation specification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Middle-East and Africa Carbon Black Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Global Sodium Sulfate Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Global Phosphoric Acid Market
Bulk Chemicals
Sorbic Acid Market
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Zinc Acetate Market