
 Global Concentrated Nitric Acid Market | 2026-2036
Global Concentrated Nitric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concentrated Nitric Acid Market Intelligence
The increasing reliance on large-scale project financing for new production facilities is rewriting the competitive landscape for concentrated nitric acid. BASF SE leverages its extensive capital access and integrated Verbund sites to maintain cost leadership in high-purity grades. Yara International ASA sustains its market position through its focus on agricultural applications and extensive distribution networks. Meanwhile, CF Industries Holdings, Inc. competes on production scale and logistical efficiency, particularly in the Americas.
Concentrated nitric acid is a fuming liquid, typically defined as having a concentration of over 70% HNO3 in an aqueous solution. Its primary industrial function is as a powerful nitrating and oxidizing agent used in the synthesis of explosives, fertilizers, and polymers. Within end-use industries, agriculture remains a foundational demand source, while the aerospace segment requires the highest purity grades for propellant applications. Demand for pure nitric acid is distinct from diluted solutions, with the former commanding premium pricing for specialized chemical synthesis.
Producers must navigate stringent environmental regulations concerning NOx emissions, enforced by bodies like the US Environmental Protection Agency (EPA). The European Chemicals Agency (ECHA) under REACH and China's Ministry of Ecology and Environment (MEE) impose strict controls on handling, transport, and precursor chemical sales. Success will depend on a producer's ability to secure stable ammonia feedstock supply while complying with evolving dual-use chemical export controls.
Market Dynamics
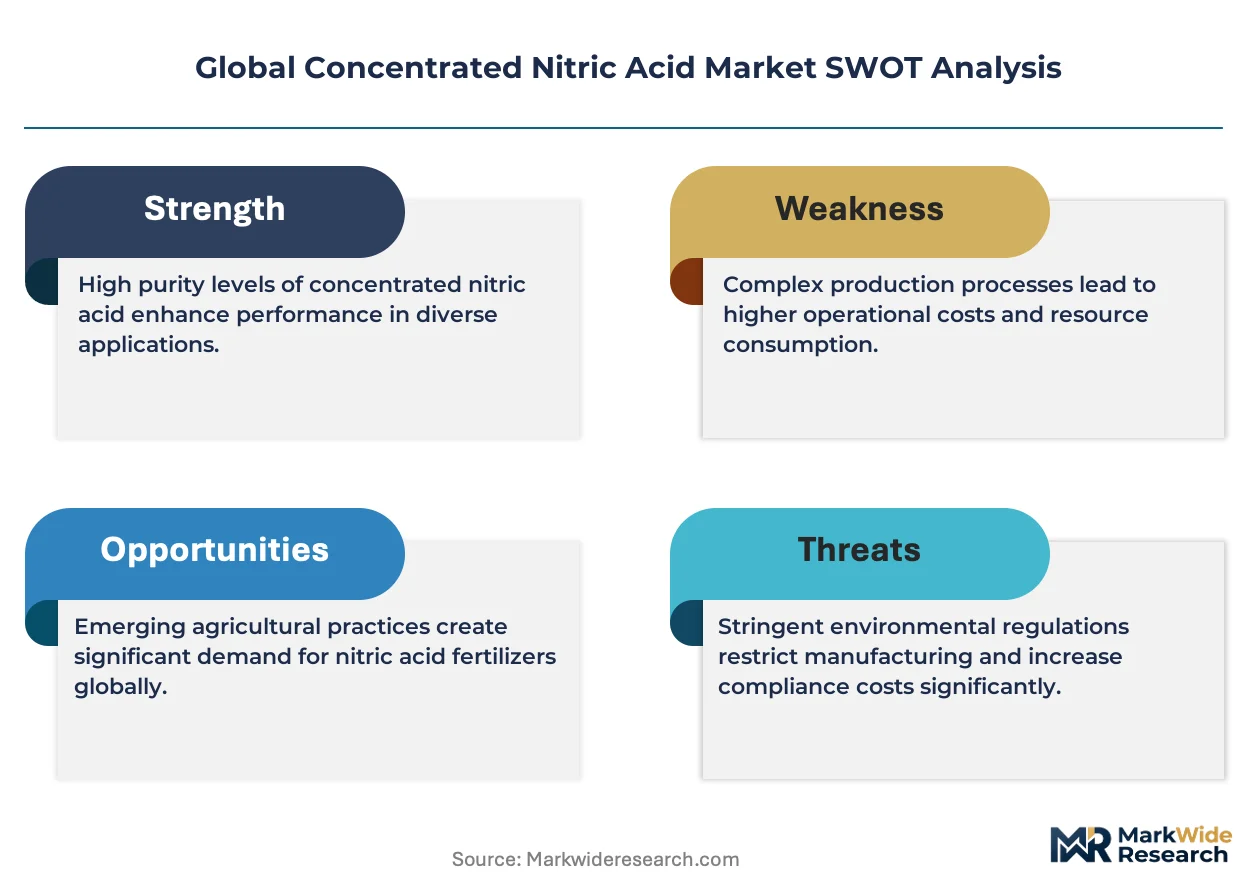
The market's central tension stems from balancing the high capital costs of NOx abatement technology, mandated by regulators like the EPA and ECHA, against escalating demand for high-purity grades from the aerospace and electronics sectors.
Growth Catalysts
- Aerospace Propellant Demand:The use of concentrated nitric acid as a storable oxidizer in rocket propulsion systems for commercial and government space programs is a significant demand driver.
- Polymer Synthesis in China:Strong consumption for the production of adipic acid, a precursor to nylon, anchors demand within China's vast industrial chemical sector.
- Specialty Chemical Nitration:Advanced nitration processes require high-concentration grades for synthesizing fine chemicals, dyes, and certain pharmaceutical intermediates, creating a high-value segment.
Market Restraints
- Ammonia Price Volatility:As the primary feedstock, fluctuations in the price and availability of ammonia, driven by energy costs and geopolitics, directly impact production cost structures.
- Stringent Emissions Controls:Regulations from the EPA and ECHA mandating costly NOx abatement technologies increase the capital and operational expenses for producers.
- Logistical Complexity:The highly corrosive and hazardous nature of the acid necessitates specialized, expensive materials for storage and transport, limiting supply chain flexibility.
Strategic Opportunities
- Semiconductor Etching:The adoption of nitric acid in wet etching and cleaning processes for silicon wafers presents a high-margin opportunity in the electronics manufacturing supply chain.
- Green Fertilizer Technologies:Development of innovative fertilizer production methods that use concentrated nitric acid more efficiently could open new avenues in sustainable agriculture.
- Geographic Expansion in ASEAN:Growing industrialization in Southeast Asian nations provides an underpenetrated market for establishing new supply chains for industrial and agricultural applications.
Industry Challenges
- High Capital Intensity:The construction of new, environmentally compliant production plants requires substantial long-term capital investment, creating high barriers to entry for new players.
- Dual-Use Export Licensing:Navigating the complex and evolving web of dual-use chemical export controls, particularly for sales to sensitive regions, poses a significant compliance burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concentrated Nitric Acid Market |
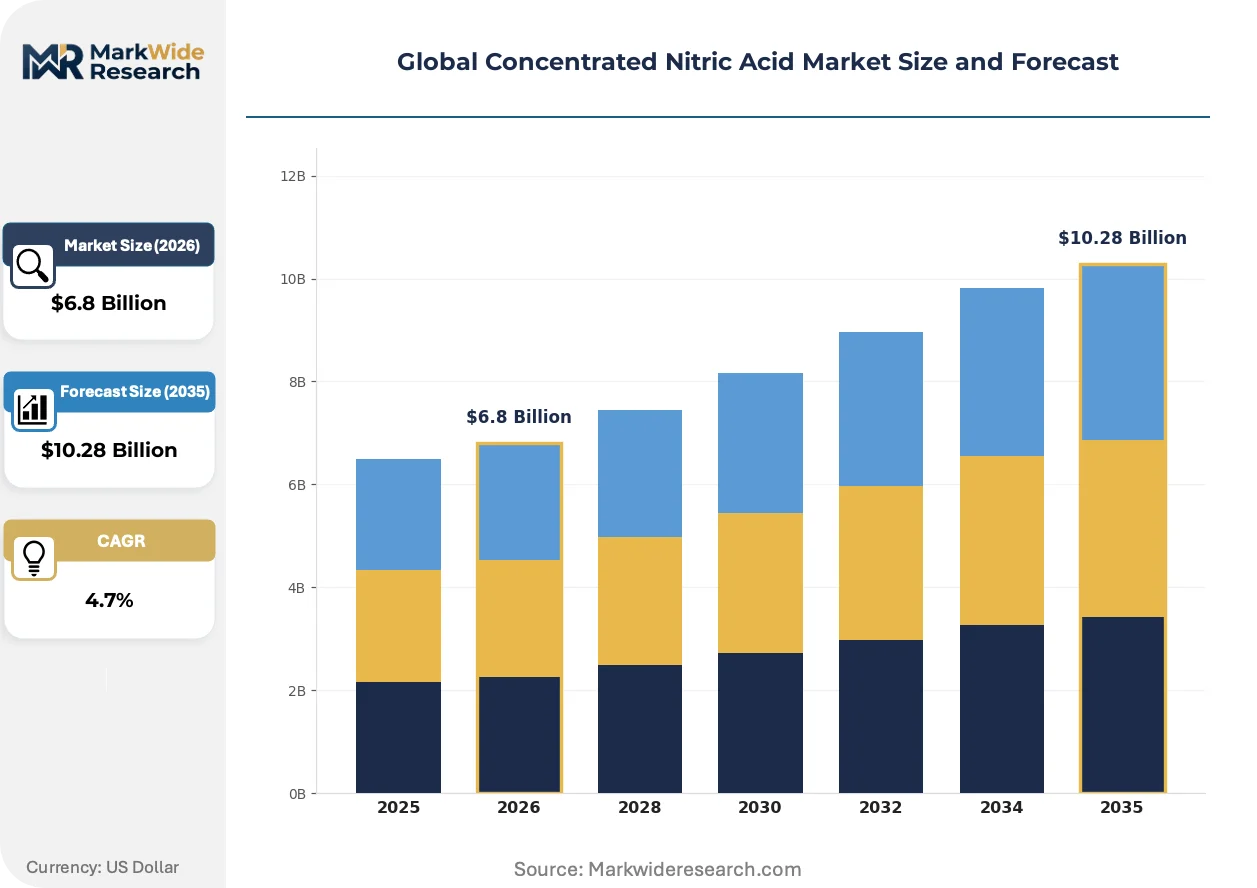
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Nitric Acid, Diluted Solutions, Aqueous Nitric Acid, Nitric Acid Anhydride End Use Industry: Aerospace, Agriculture, Pharmaceuticals, Metal Treatment Packaging Type: Drums, IBC Totes, Bulk Containers, Bottles Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Deepak Fertilizers and Petrochemicals Corporation Ltd. (DFPCL), INEOS Capital Limited, Yara International ASA, LSB Industries, The Dow Chemical Company, BASF SE, The Chemours Company, Grupa Azoty S.A., CF Industries Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concentrated Nitric Acid Market Strategic Shifts & Innovations
Process technology and plant design are evolving to internalize environmental compliance. This shift transforms emissions control from a peripheral cost center into a core element of competitive manufacturing, directly influencing plant economics and scalability.
Advanced catalytic NOx abatement systems are being integrated directly into nitric acid production towers. Chemical manufacturers are rapidly adopting these systems to meet strict emissions targets set by bodies like China's MEE. This development is hybridizing traditional process engineering with environmental control, making emissions management an inseparable component of the core production cycle.
The European Union's REACH regulation continues to tighten its grip on the chemical supply chain. It mandates comprehensive safety data and supply chain transparency, forcing producers to invest heavily in compliance to maintain market access. The agrochemical and specialty polymer sectors are most impacted, prioritizing suppliers who can guarantee full ECHA documentation.
A clear preference for long-term supply agreements that specify purity grades, volume commitments, and delivery schedules is emerging. This model is displacing the volatile, transactional purchasing common on the spot market, particularly for large consumers in the explosives and aerospace sectors. The trend is most visible in North America and Europe, where supply chain predictability is a key procurement driver.
Global Concentrated Nitric Acid Market Segmentation
The Global Concentrated Nitric Acid Market exhibits distinct segmentation across various dimensions, reflecting diverse product specifications, end-use applications, and supply chain logistics. Understanding these segments is crucial for producers to align their manufacturing capabilities with specific market demands and regulatory frameworks. Each segment presents unique challenges and opportunities for market participants.
Product Type:
Product types for concentrated nitric acid vary significantly in their production cycle and market responsiveness. High-purity grades often involve longer processing times and more stringent quality control, while standard grades can be produced with higher throughput.
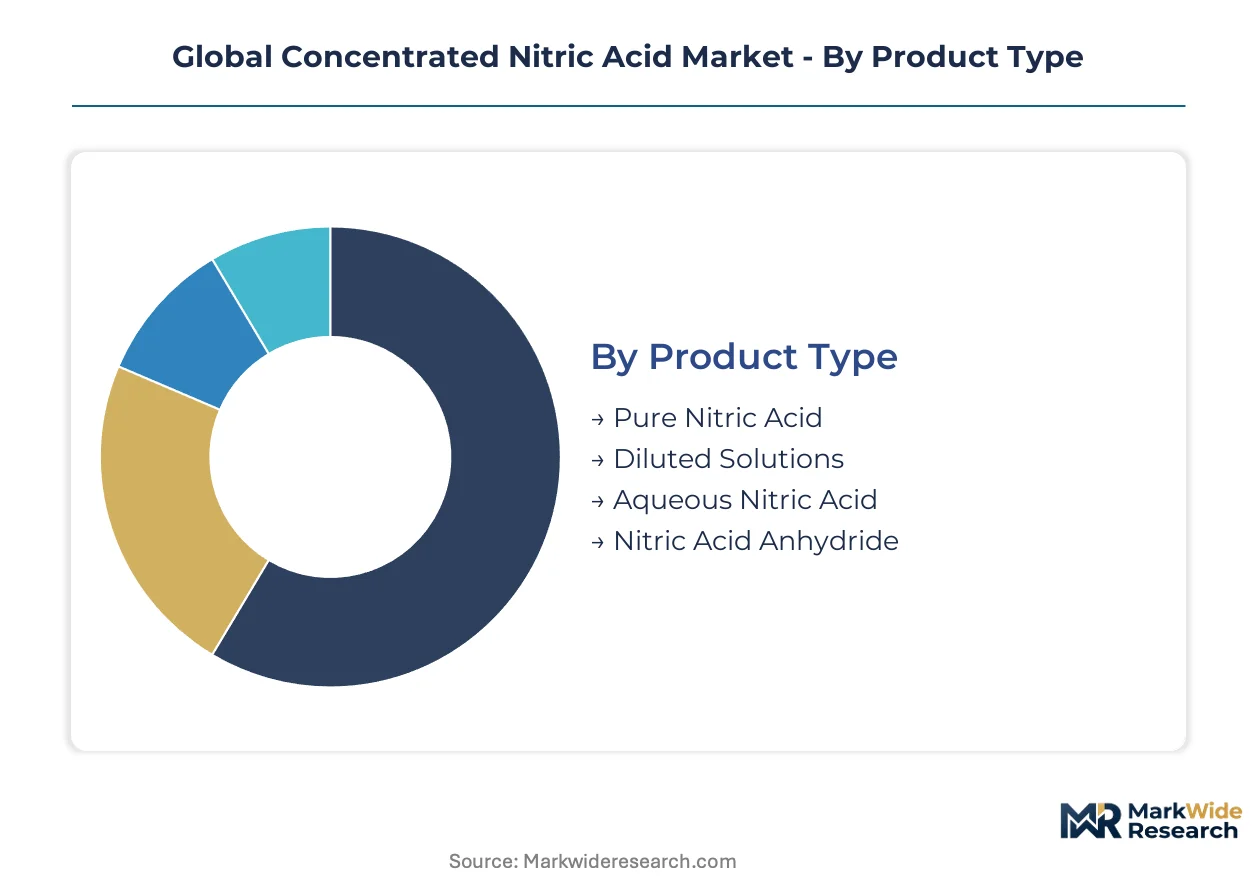
- Pure Nitric Acid:This grade typically exceeds 98% HNO3 concentration, often featuring ultra-low metal impurities. Demand for pure nitric acid concentrates within the aerospace sector for rocket propellants and in electronics manufacturing for semiconductor etching, where stringent quality specifications drive premium pricing.
- Diluted Solutions:Concentrated nitric acid serves as a precursor for various diluted solutions, typically below 70% HNO3, used across industrial applications. Demand for these solutions is foundational in agriculture for fertilizer production and in general chemical synthesis, driven by cost-effectiveness for high-volume uses.
- Aqueous Nitric Acid:This refers to nitric acid dissolved in water at various concentrations, generally less pure than "pure nitric acid." It finds application in diverse industrial processes where extreme purity is not the primary concern.
- Nitric Acid Anhydride:A highly reactive and less common form, primarily used in specialized chemical reactions requiring anhydrous conditions.
Diluted Solutions dominate the installed base for nitric acid production. Pure Nitric Acid is where expansion concentrates due to high-value applications.
End Use Industry:
End-use industries dictate the volume, purity requirements, and procurement patterns for concentrated nitric acid. Each sector presents distinct demand drivers and regulatory compliance needs.
- Aerospace:This sector requires the highest purity grades of concentrated nitric acid for use as an oxidizer in rocket propulsion systems. The demand is driven by government and commercial space programs, necessitating highly reliable and consistent product quality.
- Agriculture:Concentrated nitric acid is a critical raw material for producing nitrogen-based fertilizers, including ammonium nitrate. This segment represents a foundational demand source, with consumption patterns influenced by global food security needs and agricultural cycles.
- Pharmaceuticals:Nitric acid is employed in the synthesis of various pharmaceutical intermediates and fine chemicals. This segment demands high-quality, consistent supply for complex organic reactions.
- Metal Treatment:Used for pickling, etching, and passivation processes in metallurgy, nitric acid cleans and prepares metal surfaces.
The aerospace sector exhibits specialized demand for ultra-high purity products. Agriculture sustains consistent, high-volume consumption across global markets.
Packaging Type:
Packaging solutions for concentrated nitric acid are determined by volume, transport distance, and safety regulations, reflecting a balance between cost and hazard mitigation.
- Bulk Containers:These include ISO tanks and rail tank cars, designed for large-volume industrial shipments over long distances. Bulk containers facilitate cost-effective transport for major industrial consumers.
- Drums:Typically 200-liter or 55-gallon containers, drums offer a flexible packaging option for medium-volume users and specialized applications. They balance transport efficiency with manageable handling for diverse industrial clients.
- IBC Totes:Intermediate Bulk Containers (IBCs) provide a reusable and efficient option for volumes between drums and bulk tanks.
- Bottles:Smaller volumes are packaged in bottles, primarily for laboratory use, research, and very specialized small-scale industrial applications.
The choice of packaging reflects both logistical efficiency and hazard mitigation requirements. Bulk containers streamline large-scale industrial supply chains.
Distribution Channel:
Distribution channels for concentrated nitric acid are shaped by customer scale, geographic reach, and the need for specialized handling and technical support.
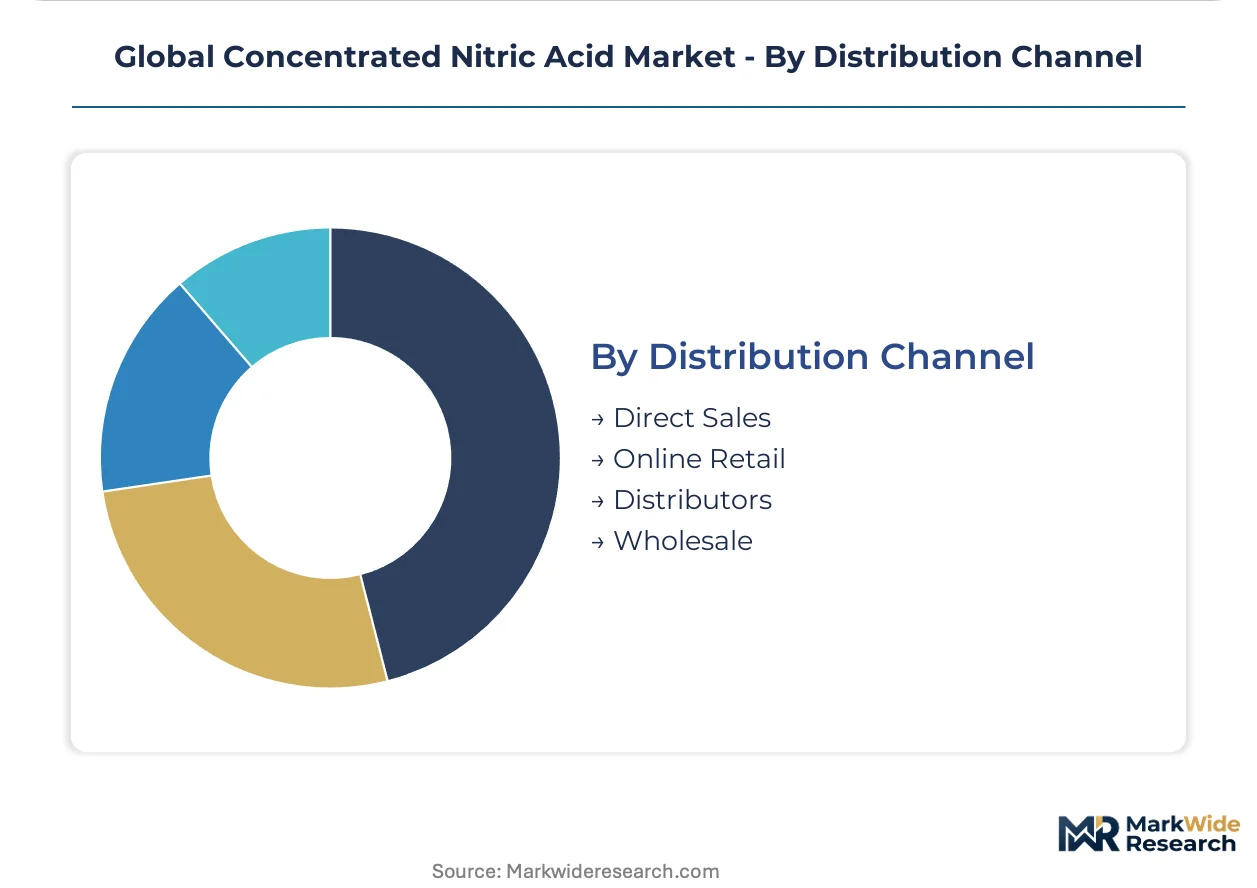
- Direct Sales:Large industrial customers, particularly in the aerospace and major chemical synthesis sectors, often procure concentrated nitric acid directly from producers. This channel allows for customized supply agreements, technical support, and stringent quality assurance.
- Distributors:Independent distributors play a crucial role in reaching smaller and medium-sized enterprises across diverse geographies. They manage inventory, provide local delivery, and often offer value-added services, expanding market access for producers.
- Online Retail:This channel is emerging for smaller quantities and specialized grades, catering to research institutions and niche industrial buyers.
- Wholesale:Wholesalers aggregate demand from multiple smaller buyers, facilitating bulk purchases from producers and onward distribution.
Direct sales channels prioritize long-term contracts and technical collaboration with major clients. Distributors extend market penetration to fragmented customer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global concentrated nitric acid market navigates a complex interplay of regional demand and supply dynamics. Major producing nations often serve as key exporters, while industrializing economies drive import demand for various end-use applications. This global trade network underpins the market's overall growth trajectory.
China
China's industrial chemical sector drives substantial demand for concentrated nitric acid. Strong consumption for adipic acid production, a key nylon precursor, anchors this segment. The Ministry of Ecology and Environment (MEE) imposes strict controls on NOx emissions from chemical plants. Production clusters in the Yangtze River Delta continue to expand, focusing on both domestic and export markets.
United States
The United States aerospace sector represents a critical, high-purity demand segment for concentrated nitric acid. Rocket propellant applications require ultra-high purity grades for consistent performance. The US Environmental Protection Agency (EPA) mandates stringent NOx abatement technologies for chemical manufacturers. Major chemical production facilities along the Gulf Coast continue to invest in compliant capacity.
Germany
Germany's advanced chemical industry relies on concentrated nitric acid for specialty chemical nitration. This includes fine chemicals and pharmaceutical intermediates, demanding consistent quality. The European Chemicals Agency (ECHA) under REACH sets comprehensive safety and handling requirements. The Rhine-Ruhr region remains a core hub for chemical manufacturing and innovation.
India
India's agricultural sector sustains foundational demand for concentrated nitric acid in fertilizer production. This segment is crucial for national food security and agricultural productivity. National environmental policies are evolving to address industrial emissions and chemical safety. Industrial zones in Gujarat and Maharashtra are expanding their chemical manufacturing base.
Global Concentrated Nitric Acid Market Key Industry Players
On the supply side, the industry is concentrating around a few large, vertically integrated chemical majors. These entities leverage economies of scale and established infrastructure to maintain market presence. Strategic archetypes include global chemical giants, specialized agricultural chemical producers, and regional industrial suppliers. Capacity expansion and technology integration for emissions control represent dominant competitive moves across the sector.
Within the integrated chemical sector, BASF SE exemplifies a global major, leveraging its extensive capital access for cost leadership in high-purity grades. Yara International ASA occupies a position as a leading agricultural chemical producer, sustaining its market share through extensive distribution networks. CF Industries Holdings, Inc. anchors the scale-driven end, competing on production volume and logistical efficiency, particularly within the Americas.
| Leading Market Players |
|---|
| Deepak Fertilizers and Petrochemicals Corporation Ltd. (DFPCL) |
| INEOS Capital Limited |
| Yara International ASA |
| LSB Industries |
| The Dow Chemical Company |
| BASF SE |
| The Chemours Company |
| Grupa Azoty S.A. |
| CF Industries Holdings, Inc. |
Cost & Logistics Intelligence
Ammonia feedstock price volatility directly influences production costs, impacting downstream pricing for concentrated nitric acid. This volatility shapes margin pools across various end-use segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for concentrated nitric acid. Pricing stratifies across high-purity grades for aerospace and standard grades for agriculture, driven by stringent quality specifications and volume scale. Pricing softness stems from ammonia price volatility and the high capital expenditure for NOx abatement technologies. Agricultural consumers exhibit high price sensitivity, while the aerospace sector prioritizes consistent quality over cost.
Supply Chain Analysis
Ammonia price volatility dominates the concentrated nitric acid supply chain risk profile. Production centers in China, the United States, and Germany draw heavily from global ammonia markets. Logistical complexity for hazardous materials necessitates specialized transport infrastructure, adding to supply chain rigidity. Distribution runs through direct sales for large aerospace and chemical synthesis clients, complemented by distributors for broader industrial reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The concentrated nitric acid market is undergoing a platform-economics inflection, driven by the integration of advanced NOx abatement technologies into core production processes. This shift creates a new ecosystem where environmental performance dictates market access and premium pricing.
For Market Incumbents: Harden existing production facilities with advanced catalytic NOx abatement systems to meet evolving EPA and ECHA standards. Secure long-term, stable ammonia feedstock contracts to mitigate price volatility, a key margin pressure point. Invest in R&D for process optimization, ensuring cost-effective compliance against emerging greener technologies. Expand compliant capacity in strategic regions like the US Gulf Coast or China's Yangtze River Delta.
For New Entrants and Emerging Players: Geographic underpenetration in Southeast Asian nations presents a significant white-space opportunity for concentrated nitric acid. Target industrial and agricultural applications in growing economies within ASEAN, leveraging demand for specialty chemical nitration. A go-to-market strategy should involve partnering with established local distributors to navigate complex regional logistics and offer localized technical support. Focus on developing high-purity grades for the semiconductor etching segment.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated producers possessing advanced NOx abatement technologies and secure ammonia feedstock supply. The market's long-term viability is anchored in essential aerospace, agricultural, and specialty chemical applications. Target acquisition profiles include companies with strong environmental compliance records and established distribution networks in high-growth regions. Increased M&A activity for compliant production assets serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding compliant production capacity addresses the growing demand from the aerospace and electronics sectors. |
| Backward Integration | Securing ammonia feedstock supply through backward integration mitigates price volatility for producers. |
| Green Manufacturing Transition | Adopting advanced NOx abatement systems ensures compliance with ECHA and EPA regulations. |
| Long-term Supply Agreement | Establishing long-term supply agreements provides predictability for major consumers in explosives and aerospace. |
| Joint Venture | Forming joint ventures in ASEAN markets facilitates market entry and local supply chain development. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings for this study. Primary insights gathered from plant managers, procurement leads at downstream OEMs, and technical R&D directors were crucial. Secondary validation involved customs/trade data, ACC/Cefic reports, and China's MEE publications. Bottom-up and top-down triangulation ensured robust market size estimation and forecast accuracy.
Quantitative models were calibrated using historical market trends and projected demand across the analysis window. Segmentation dimensions modeled included grade tier, end-use industry, packaging format, and regional production hub. Compound annual growth rates were derived from the interplay of demand drivers and supply-side capacity additions. Key forecast inputs included ammonia feedstock prices and global aerospace launch schedules.
Practitioners should monitor geopolitical events impacting ammonia supply and accelerated regulatory changes from the EPA and ECHA for early signals of market revision. Forecasts reflect assumptions about technology adoption and economic stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Saudi Arabia Sodium Thiosulphate Market
Bulk Chemicals
Diketene Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
Global Sodium Chloride Market
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
Methyl Methacrylate (MMA) Market
Bulk Chemicals
Magnesium Phosphate Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Manganese Sulfate Market