
 Lithium Benzoate Market | 2026-2036
Lithium Benzoate Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Benzoate Market Analytics
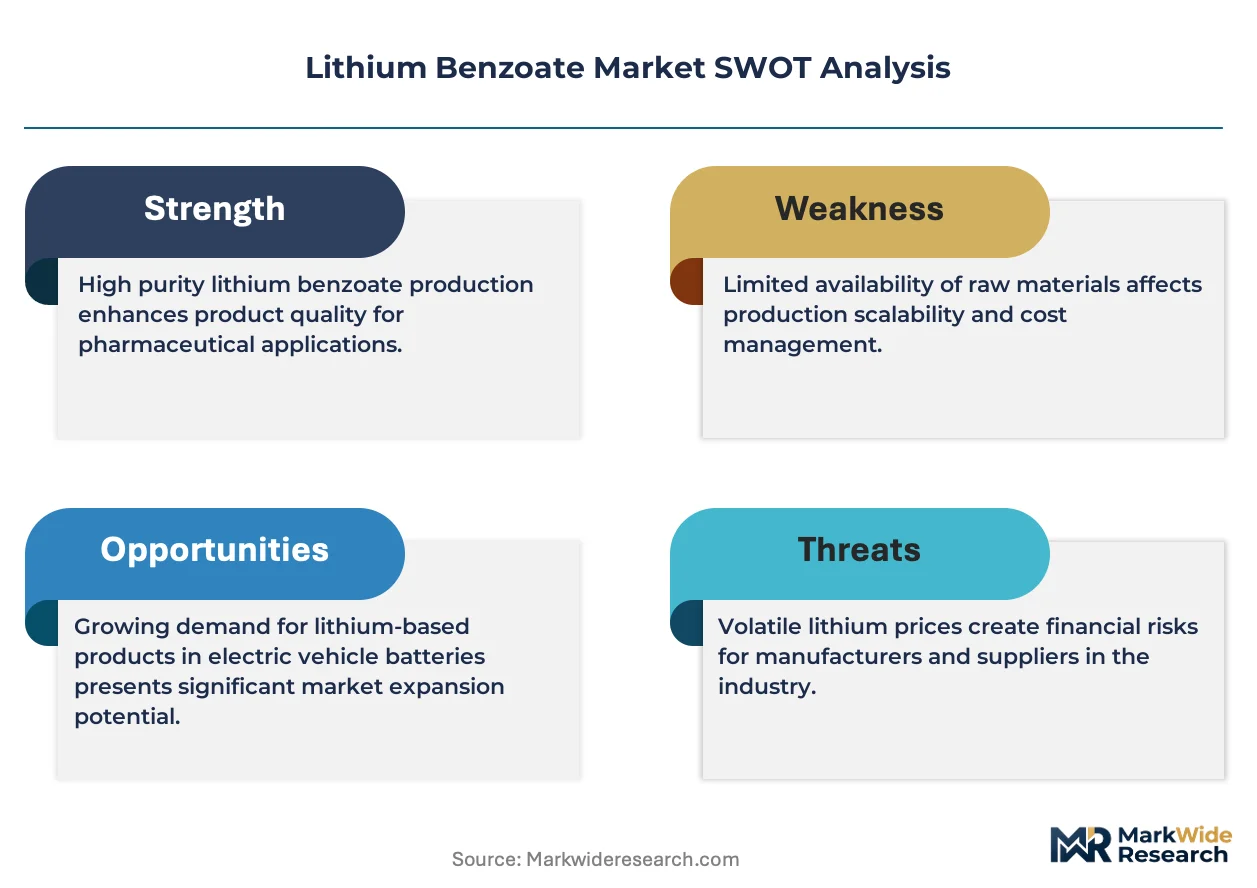
Technical-grade certification and batch-assay documentation is rebalancing what buyers contract for, shifting transactions from commodity spot purchases to specification-bound supply agreements. Albemarle Corporation leverages its bromine-lithium co-production infrastructure to sustain cost-advantaged benzoate precursor flows. Ganfeng Lithium anchors downstream chemical conversion capacity in Jiangxi province. Tianqi Lithium competes through integrated spodumene-to-salt refining that controls intermediate purity thresholds.
Lithium benzoate is the lithium salt of benzoic acid, typically synthesized through neutralization of benzoic acid with lithium hydroxide or carbonate, yielding a white crystalline powder with specified assay thresholds above 99% for pharmaceutical applications. The compound serves primarily as a pharmaceutical intermediate and preservative adjunct where lithium ion bioavailability and benzoate carrier stability matter. Pharmaceutical Grade commands premium positioning due to USP and EP monograph compliance burdens that filter out commodity producers. Food Preservative applications occupy mature volume channels with entrenched regional supplier relationships. Chemical Manufacturing segments lead absolute tonnage offtake as specialty lithium salts feed polymerization catalyst and organic synthesis demand.
FDA oversight of lithium compounds in drug applications and EPA reporting requirements for benzoate derivatives shape formulation and handling standards in the United States. REACH registration and ECHA classification protocols govern import and use across European downstream chemical operations. China's NMPA and evolving GB standards for pharmaceutical excipients are tightening domestic manufacturing audits. Stakeholders must monitor how regulatory divergence between FDA and NMPA purity specifications fragments supplier qualification requirements and influences capital allocation across grade-dedicated production lines.
Market Dynamics
Pharmaceutical-grade purity specifications are compressing supplier margins while concentrating contract volumes among REACH-registered and USP-certified producers. This bifurcation between specification-bound supply agreements and commodity spot markets is restructuring procurement relationships across lithium benzoate applications.
Growth Catalysts
- Mood stabilization therapy expansion:Healthcare providers in Germany and the United States are expanding lithium-based pharmaceutical protocols for bipolar disorder management, tightening demand for EP and USP monograph-compliant salts.
- REACH registration deadlines:ECHA's phased compliance requirements for benzoate derivatives are filtering out uncertified European suppliers, consolidating qualified production capacity among registered entities.
- Polymerization catalyst demand:Specialty chemical manufacturers in Japan are increasing lithium benzoate offtake for precision polymer synthesis, driving technical-grade volume growth.
Market Restraints
- Lithium hydroxide cost volatility:Spodumene concentrate pricing fluctuations and energy-intensive conversion costs are compressing benzoate precursor margins, particularly for non-integrated producers.
- Jiangxi supply concentration:Downstream chemical conversion capacity clusters in a single Chinese province, creating geographic risk exposure for international buyers dependent on Ganfeng-affiliated supply chains.
- Benzoic acid substitution pressure:Sodium and potassium benzoate variants compete in food preservative applications where lithium ion bioavailability provides no functional advantage.
Strategic Opportunities
- India pharmaceutical excipient growth:CDSCO's alignment with ICH quality guidelines is opening qualification pathways for imported lithium benzoate in domestic generic API manufacturing.
- Dual carbon policy tailwinds:China's MEE carbon intensity benchmarks favor low-emission benzoate production lines, rewarding producers with renewable-powered lithium conversion infrastructure.
- Direct-to-formulator distribution:API manufacturers are bypassing traditional chemical distributors to contract directly with pharmaceutical compounders, capturing margin and specification control.
Industry Challenges
- Analytical chemist scarcity:Batch-assay documentation requirements for pharmaceutical-grade certification demand specialized personnel that contract manufacturers struggle to recruit and retain.
- Multi-jurisdiction compliance timelines:Simultaneous FDA, EMA, and NMPA filing requirements for new drug applications extend qualification cycles and tie up regulatory capital.
- Legacy ERP integration friction:Specification-bound supply agreements require real-time certificate-of-analysis transmission that older enterprise systems cannot automate without costly middleware deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Benzoate Market |
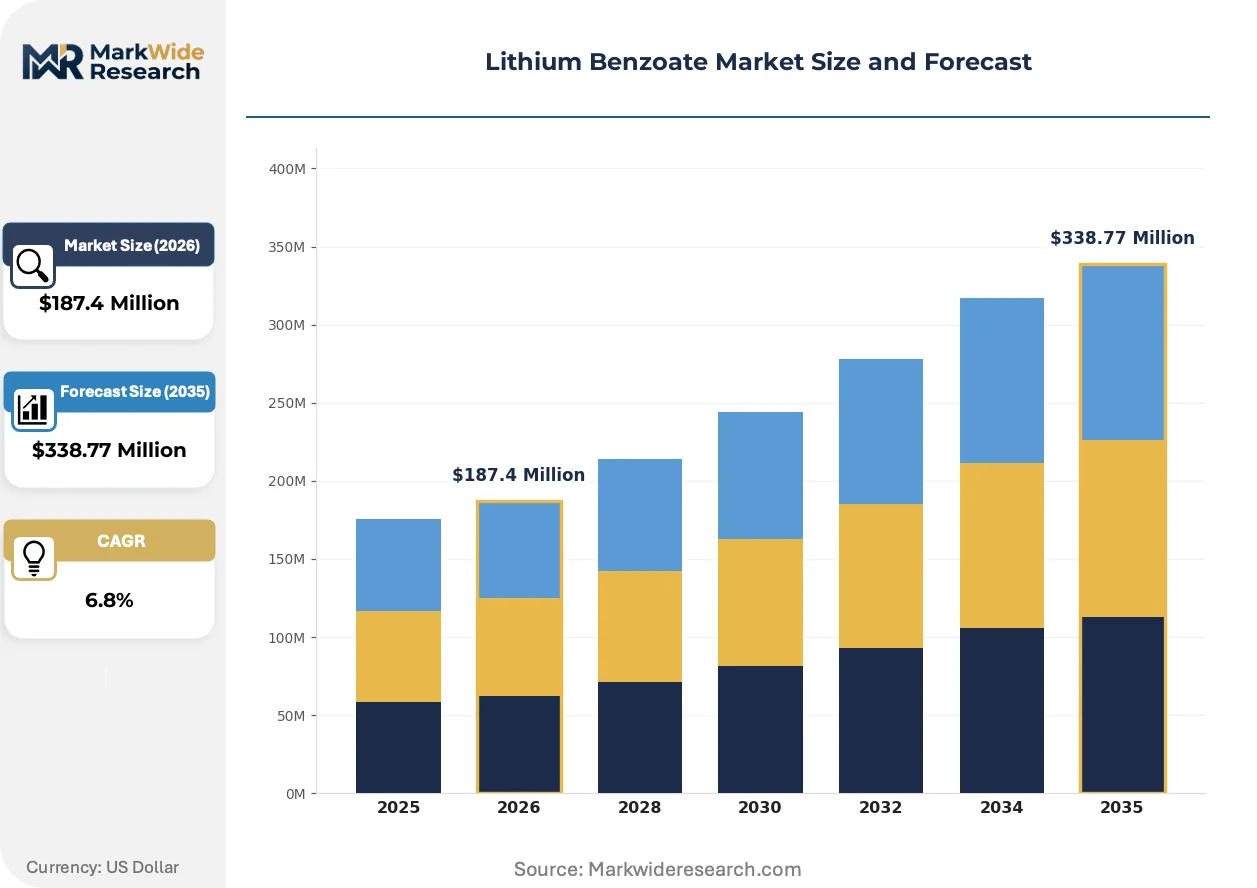
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Research Grade Application: Pharmaceuticals, Food Preservative, Personal Care Products, Chemical Manufacturing End User: Healthcare Providers, Food Industry, Cosmetic Manufacturers, Research Institutions Delivery Mode: Oral Administration, Topical Application, Injectable, Dietary Supplement |
| Companies Covered | Tianqi Lithium, Rio Tinto, Albemarle Corporation, Livent, Allkem, Sociedad Química y Minera de Chile, Pilbara Minerals, Arcadium Lithium, Ganfeng Lithium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Benzoate Market Evolving Landscape
Continuous flow neutralization reactors and blockchain-anchored batch documentation are compressing production cycles while hardening supply chain traceability. These shifts are redrawing competitive boundaries between integrated lithium producers and standalone benzoate specialists.
Modular flow chemistry systems are replacing batch neutralization vessels for lithium benzoate synthesis, enabling real-time pH monitoring and reduced solvent waste. Pharmaceutical contract manufacturers in Switzerland and Massachusetts are piloting these units for GMP-compliant production. This technology is decentralizing production authority away from centralized commodity plants toward distributed, specification-dedicated facilities.
ECHA's 2024 updates to REACH dossier requirements for lithium salts are mandating extended toxicity data for benzoate derivatives used in consumer applications. Specialty chemical importers are absorbing third-party testing costs or exiting lower-margin formulations. Food preservative applications face the steepest compliance burden, pushing some European buyers toward potassium benzoate alternatives.
Specification-driven purchasing is compressing supplier qualification cycles as pharmaceutical formulators demand locked-in assay thresholds rather than nominal grade ranges. Chemical distributors in the Netherlands and Singapore are losing volume to direct manufacturer relationships. This pattern is most visible in mood-stabilizing drug production, where compounders prioritize batch-to-batch consistency over unit cost minimization.
Lithium Benzoate Market Segmentation
Specification thresholds and regulatory compliance burdens fragment lithium benzoate procurement across divergent purity tiers and end-use protocols. Buyers segment supply relationships by certification burden rather than commodity pricing alone.
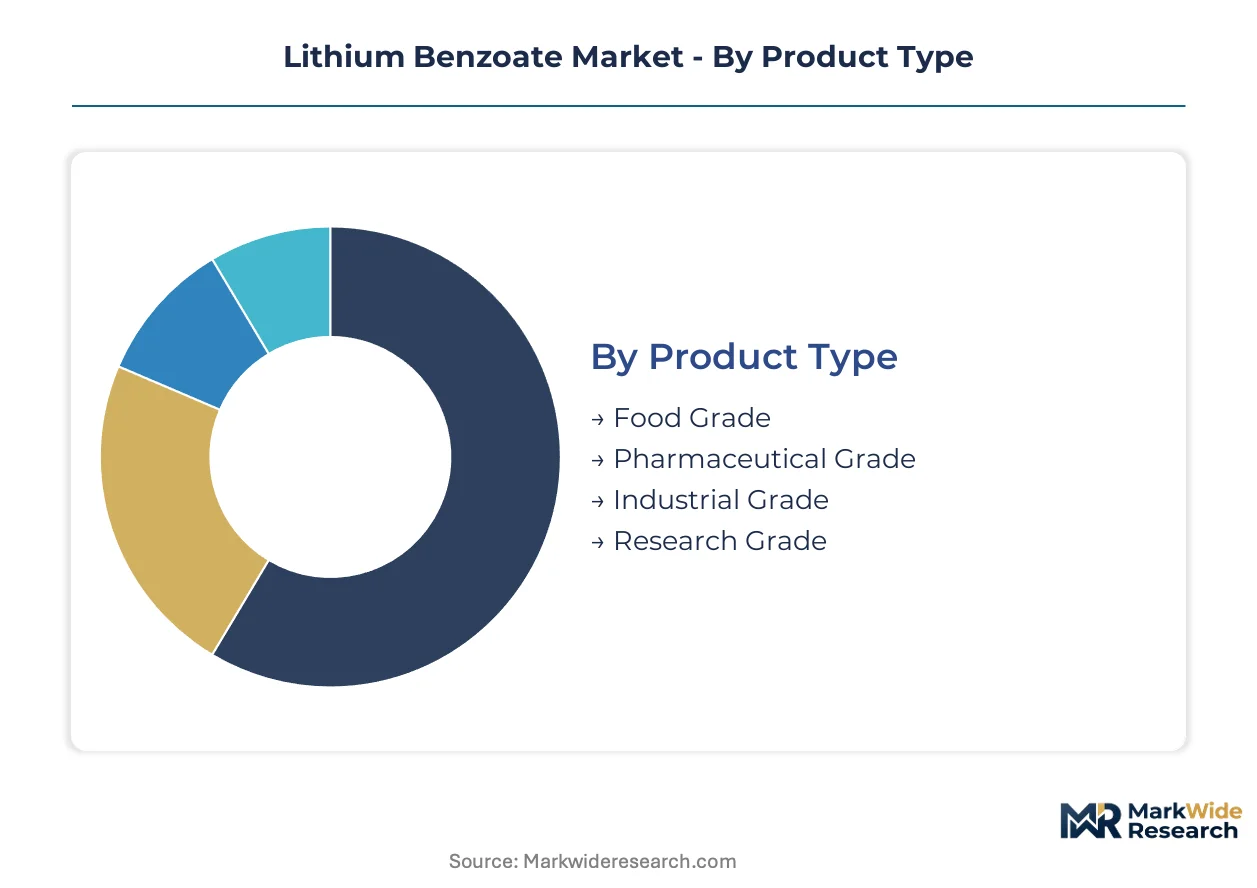
Product Type:
Purity specifications and assay documentation requirements stratify production capacity across four certification tiers.
- Pharmaceutical Grade:USP and EP monograph compliance mandates assay thresholds above 99% with full batch documentation. Healthcare providers in Germany and the United States contract exclusively through REACH-registered and FDA-inspected producers for mood stabilization therapies.
- Food Grade:FSSAI and FDA food additive specifications govern preservative applications where lithium ion bioavailability provides no functional advantage over sodium or potassium variants. Regional supplier relationships dominate procurement in mature volume channels.
- Industrial Grade:Technical certification for polymerization catalyst feedstock serves Japanese specialty chemical manufacturers with lower documentation burdens than pharmaceutical protocols.
- Research Grade:Small-batch production for analytical standards and method development supports institutional procurement with intermittent volume patterns.
Mature deployment sits with Food Grade. Newer deployment is concentrated in Pharmaceutical Grade.
Application:
Functional requirements and regulatory exposure determine margin structures across downstream use cases.
- Pharmaceuticals:Lithium ion bioavailability drives demand for bipolar disorder management protocols. CDSCO alignment with ICH guidelines in India is opening qualification pathways for imported excipients in generic API manufacturing.
- Chemical Manufacturing:Specialty lithium salts feed precision polymer synthesis and organic catalysis. Japanese manufacturers lead technical-grade offtake for continuous flow reactor integration.
- Food Preservative:Sodium and potassium benzoate substitution pressure compresses lithium variant market share where carrier ion functionality is irrelevant.
- Personal Care Products:Cosmetic formulators in South Korea and France utilize lithium benzoate for antimicrobial stability in premium skincare lines.
Established volume concentration rests with Chemical Manufacturing. Steepest expansion trajectory belongs to Pharmaceuticals.
End User:
Procurement sophistication and compliance capital availability separate institutional buyers from commodity purchasers.
- Healthcare Providers:Hospital systems and psychiatric clinics in the United States and Germany demand locked-in assay thresholds with direct manufacturer relationships bypassing chemical distributors.
- Research Institutions:University and government laboratories purchase intermittent small volumes for analytical method development and reference standard preparation.
- Food Industry:Preservative compounders prioritize unit cost minimization over specification consistency, sustaining entrenched regional supplier relationships.
- Cosmetic Manufacturers:Premium skincare formulators in France and South Korea source lithium benzoate for antimicrobial stability in high-margin product lines.
Longstanding procurement patterns characterize Food Industry. Emerging specification intensity defines Healthcare Providers.
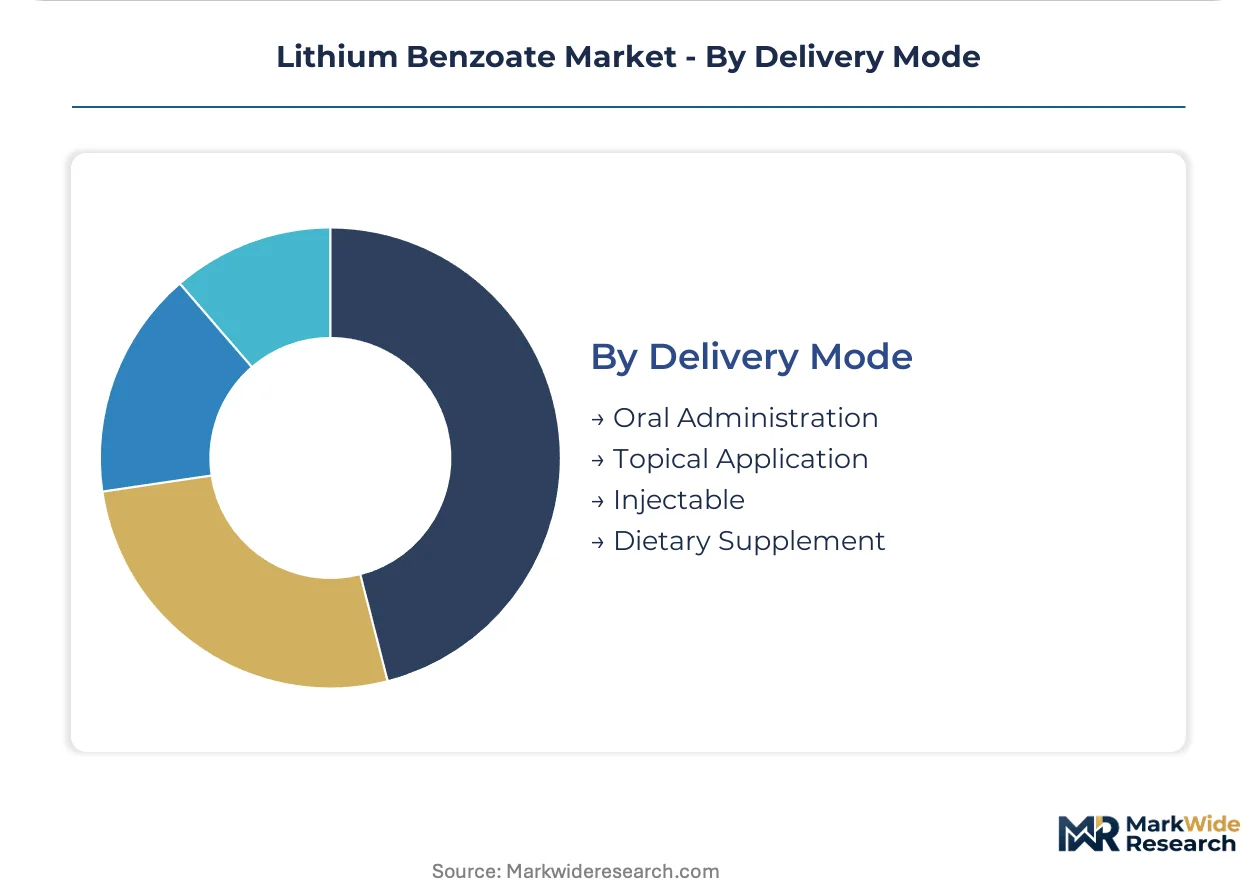
Delivery Mode:
Route of administration dictates formulation complexity and regulatory filing requirements.
- Oral Administration:Tablet and capsule formulations for mood stabilization therapies dominate pharmaceutical demand with established bioequivalence documentation.
- Dietary Supplement:Nutraceutical applications in the United States face less stringent FDA oversight than drug applications, attracting lower-purity supply tiers.
- Topical Application:Transdermal and dermatological formulations require specialized solubility profiles for cosmetic and limited pharmaceutical use.
- Injectable:Parenteral specifications impose the strictest sterility and particulate burden, restricting qualified production capacity to GMP-certified facilities.
Volume concentration remains with Oral Administration. Regulatory complexity peaks with Injectable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's Jiangxi province while consumption fragments across pharmaceutical hubs in Germany, the United States, and Japan. This geographic divide creates supply chain exposure for healthcare providers dependent on specification-grade imports.
China
Downstream chemical conversion capacity clusters in Jiangxi province where Ganfeng Lithium anchors benzoate derivative output. NMPA tightening of GB standards for pharmaceutical excipients is accelerating domestic manufacturing audits. Ganzhou and Xinyu industrial zones host integrated spodumene-to-salt refining operations that control intermediate purity thresholds for export markets.
Germany
Healthcare providers in Bavaria and North Rhine-Westphalia are expanding lithium-based mood stabilization protocols for bipolar disorder management. ECHA's phased REACH compliance deadlines for benzoate derivatives are filtering out uncertified European suppliers. Frankfurt and Ludwigshafen chemical corridors concentrate qualified production capacity among REACH-registered entities serving pharmaceutical formulators.
United States
Psychiatric clinics and hospital systems in Massachusetts and California demand locked-in assay thresholds with direct manufacturer relationships. FDA oversight of lithium compounds in drug applications shapes formulation standards while EPA reporting requirements govern benzoate derivative handling. Greater Boston hosts pharmaceutical contract manufacturers piloting continuous flow neutralization reactors for GMP-compliant production.
Japan
Specialty chemical manufacturers in Osaka and Nagoya are increasing technical-grade lithium benzoate offtake for precision polymer synthesis. METI industrial standards guide specialty lithium salt specifications for continuous flow reactor integration. Kansai region chemical complexes lead technical-grade volume growth as domestic pharmaceutical demand stabilizes.
India
CDSCO alignment with ICH quality guidelines is opening qualification pathways for imported lithium benzoate in domestic generic API manufacturing. Maharashtra and Gujarat pharmaceutical clusters are scaling excipient procurement as contract research organizations expand formulation services. Mumbai-Pune industrial corridor attracts direct-to-formulator distribution models bypassing traditional chemical distributors.
Lithium Benzoate Market Competitive Landscape
Top-tier vendors anchor integrated lithium production, while standalone benzoate specialists occupy specification-dedicated niches. The market structure bifurcates between commodity-scale precursor producers and pharmaceutical-grade certification holders. Three archetypes dominate: integrated mining-to-salt refiners, pharmaceutical-grade contract manufacturers, and regional chemical distributors losing volume to direct relationships. Capacity expansion and backward integration into spodumene concentrate sourcing represent the dominant competitive vectors.
Among integrated lithium producers, Tianqi Lithium, Albemarle Corporation, and Ganfeng Lithium exemplify the scale-driven archetype. Tianqi Lithium represents upstream control over spodumene-to-salt refining. Albemarle Corporation anchors bromine-lithium co-production infrastructure sustaining cost-advantaged precursor flows. Ganfeng Lithium occupies downstream chemical conversion capacity in Jiangxi province. These three entities sit within the tier commanding specification-bound supply agreements rather than commodity spot markets.
| Leading Market Players |
|---|
| Tianqi Lithium |
| Rio Tinto |
| Albemarle Corporation |
| Livent |
| Allkem |
| Sociedad Química y Minera de Chile |
| Pilbara Minerals |
| Arcadium Lithium |
| Ganfeng Lithium |
| Others |
Value Network & Pricing Analysis
Certification-grade bifurcation between pharmaceutical and technical specifications splits lithium benzoate procurement into contract-bound premium tiers and spot-market commodity channels. This divergence concentrates pricing power among REACH-registered producers serving German and United States healthcare providers while compressing margins for uncertified suppliers dependent on Jiangxi province output.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects spodumene concentrate cost pass-through and energy-intensive lithium hydroxide conversion. Three-tier pricing structure across pharmaceutical, food, and industrial grades separates USP-certified batches from FSSAI-aligned preservatives and technical catalyst feedstock. Cost-down pressure on food-grade variants accelerates because sodium and potassium benzoate substitution erodes lithium ion carrier premiums. Chemical Manufacturing buyers exhibit highest price sensitivity; Healthcare Providers prioritize assay consistency over unit cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from European and North American pharmaceutical formulators mandate simultaneous REACH-registered and FDA-inspected supplier qualification. Production gravity centers on China's Jiangxi province, with secondary capacity in Germany's Ludwigshafen corridor and Japan's Kansai chemical complexes. Raw material dependencies span spodumene concentrate from Australia, benzoic acid from petroleum-derived toluene oxidation, and lithium hydroxide from hard-rock or brine conversion. Single-source vulnerability concentrates in Ganfeng-affiliated downstream chemical conversion. Distribution runs through direct manufacturer relationships bypassing Netherlands and Singapore chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified production capacity for pharmaceutical-grade lithium benzoate operates below demand growth from mood stabilization therapy expansion, propping specification premiums. This supply constraint rewards incumbents with locked-in offtake agreements while filtering speculative entrants lacking certification capital.
For Market Incumbents: Deepen backward integration into spodumene concentrate sourcing to insulate margin from lithium hydroxide volatility. Anchor capacity expansion in Jiangxi province's Ganzhou industrial zone to exploit dual carbon policy tailwinds. Defend against potassium benzoate substitution in food preservative channels by emphasizing lithium ion bioavailability in pharmaceutical positioning. For New Entrants and Emerging Players: Direct-to-formulator distribution routes bypass entrenched chemical distributor relationships in India's Maharashtra pharmaceutical corridor. Target CDSCO-aligned excipient qualification for generic API manufacturing as the most penetrable entry point. Pursue continuous flow reactor technology licensing from Swiss and Massachusetts contract manufacturers to compress GMP compliance timelines. For Investors and Strategic Acquirers: Re-rating potential sits with integrated spodumene-to-salt refiners given ECHA's phased REACH compliance deadlines filtering uncertified European suppliers. Five-to-ten year viability favors producers with captive lithium hydroxide supply and pharmaceutical-grade certification infrastructure. Watch NMPA audit intensity in Jiangxi province as inflection indicator for geographic supply risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spodumene Sourcing | Captive concentrate supply insulates margin from Australian hard-rock pricing volatility. |
| Continuous Flow Reactor Deployment | Massachusetts and Swiss GMP pilots compress batch-assay documentation cycles for pharmaceutical contract manufacturers. |
| REACH Registration Completion | ECHA's 2024 dossier updates filter uncertified competitors from European mood stabilization supply chains. |
| Direct-to-Formulator Distribution | Mumbai-Pune corridor bypasses traditional chemical distributors capturing margin and specification control. |
| Dual Carbon Policy Alignment | MEE benchmarks favor renewable-powered lithium conversion in Jiangxi province's Ganzhou zone. |
Research Methodology
Independent corroboration across regulatory filing databases, customs trade records, and pharmaceutical procurement platforms underwrites the qualitative findings. Primary interviews with plant managers at Jiangxi chemical conversion facilities, procurement leads at German healthcare systems, regulatory affairs directors navigating FDA and EMA submissions, and technical R&D heads at Japanese specialty chemical manufacturers combined with secondary validation from NMPA audit disclosures, ECHA REACH dossiers, SEC 10-K filings, and CDSCO guideline updates. Bottom-up capacity estimates and top-down demand modeling triangulate volume figures.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, regional production hub, and certification status. CAGRs derive from fitted trend analysis calibrated to historical lithium salt pricing elasticity and pharmaceutical excipient demand patterns. Forecast inputs incorporate spodumene concentrate contract pricing, energy cost trajectories for lithium hydroxide conversion, and regulatory filing velocity for new drug applications.
Inputs from ECHA registration databases and NMPA manufacturing audit reports were available through the study window; gaps in real-time pharmaceutical procurement transaction data introduce uncertainty bands around price realization assumptions. Deviation in Jiangxi province power supply reliability or EMA inspection backlog duration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Ferric Sulfate Market
Bulk Chemicals
Europe Lithium Chloride Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Global Acrylic Esters Market
Bulk Chemicals
2-Methylfuran Market
Bulk Chemicals
Tin Fluoborate Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Oxalic Acid Market
Bulk Chemicals
United States Lime Market