
 Catheter-Related Bloodstream Infections (Crbsis) Market | 2026-2036
Catheter-Related Bloodstream Infections (Crbsis) Market Size, Share, and Industry Trends Forecast 2026-2036
Catheter-Related Bloodstream Infections (Crbsis) Market Intelligence
United States manufacturing expansion in antimicrobial catheter coatings is reshaping supply availability for North American hospitals. Becton Dickinson and Company leverages integrated production of vascular access devices with antiseptic barriers. Fresenius Medical Care anchors its position through dialysis catheter specialization and renal care channel control. Pfizer competes via pharmaceutical adjunct therapies that pair with device-based CRBSI prevention protocols.
Catheter-Related Bloodstream Infections constitute microbiological colonization of intravascular devices leading to systemic infection, typically involving Staphylococcus aureus or coagulase-negative staphylococci biofilm formation on polymer surfaces, with prevention requiring aseptic insertion protocols and antimicrobial surface engineering. Antimicrobial Coatings command premium positioning due to sustained clinical efficacy requirements and regulatory validation burdens. Hospitals dominate end-user procurement through centralized infection control committees that standardize catheter selection across departments. Ultrasound-guided insertion technology leads growth trajectories as vascular access teams reduce mechanical complication rates that predispose patients to infectious events.
The FDA enforces premarket clearance under 510(k) pathways for anti-infective devices, while the Centers for Medicare & Medicaid Services ties reimbursement to documented central line-associated bloodstream infection reductions. Joint Commission accreditation standards mandate compliance with evidence-based insertion bundles that specify antiseptic skin preparation and maximal sterile barrier precautions. Stakeholders must monitor evolving EPA registrations for novel antimicrobial agents applied to indwelling catheter surfaces.
Market Dynamics
Antimicrobial surface engineering and ultrasound-guided insertion protocols are compressing mechanical complication rates that previously predisposed patients to infectious colonization, forcing catheter manufacturers to integrate real-time imaging compatibility into device design cycles.
Growth Catalysts
- CMS Reimbursement Ties:The Centers for Medicare & Medicaid Services links hospital payments to documented central line-associated bloodstream infection reductions, compelling acute care facilities to upgrade catheter specifications.
- Intensive Care Demand:Tertiary hospital ICUs generate concentrated procurement volume for antimicrobial-coated catheters as sepsis prevention protocols harden into mandatory clinical bundles.
- Biofilm Science Advances:Research into Staphylococcus aureus surface colonization mechanisms enables next-generation antiseptic barrier engineering with extended efficacy windows.
Market Restraints
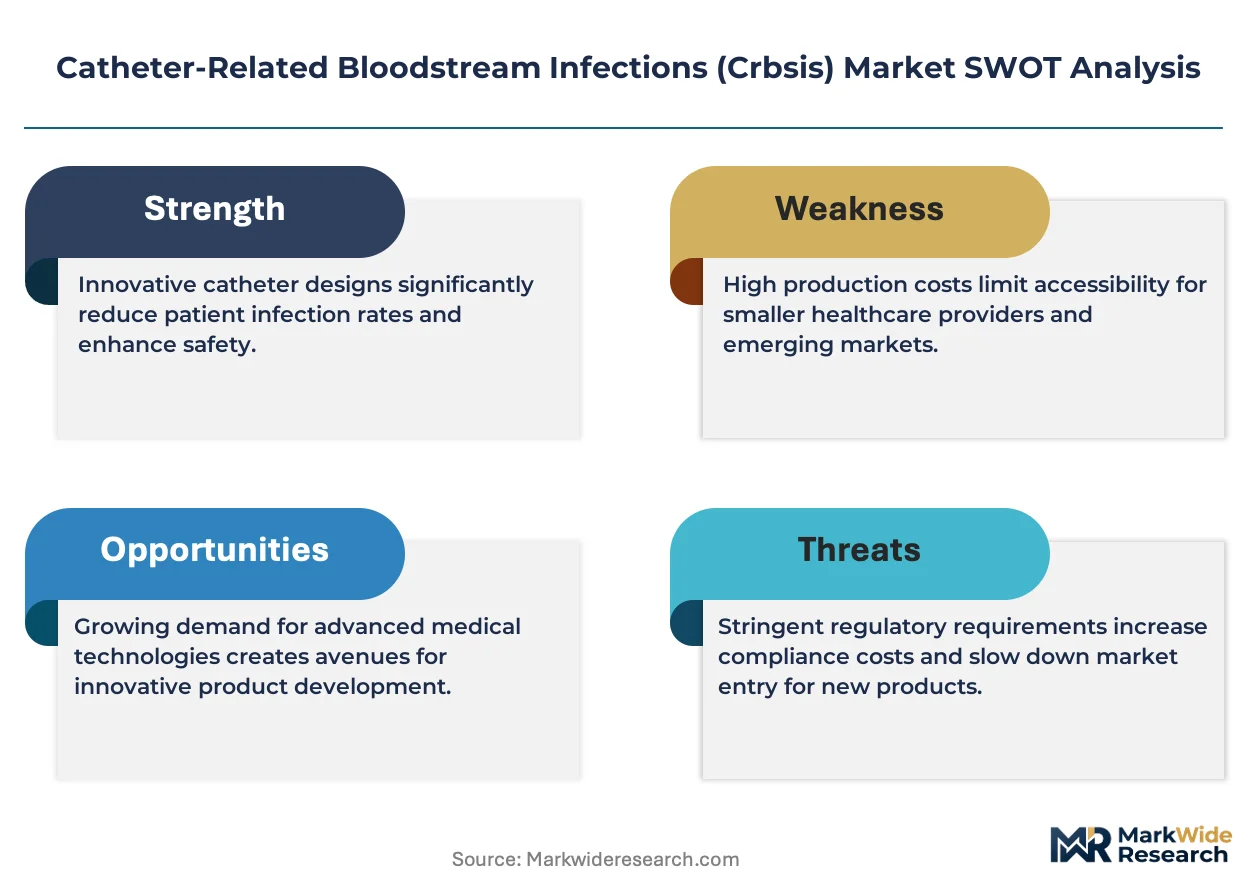
- Silver Price Volatility:Antimicrobial coatings rely on silver ion release chemistry, exposing manufacturers to commodity input swings that compress margin predictability.
- FDA 510(k) Burden:The FDA's updated premarket notification requirements for vascular access devices extend validation timelines and elevate clinical evidence thresholds for novel coatings.
- Catheter Dwell Time Limits:Clinical protocols mandate scheduled replacement intervals that cap per-patient device consumption regardless of coating durability improvements.
Strategic Opportunities
- Outpatient Dialysis Expansion:Fresenius Medical Care's channel control in renal care creates entry points for specialized dialysis catheter lines in ambulatory settings.
- EPA Registration Pathways:Novel antimicrobial agents applied to indwelling surfaces require Environmental Protection Agency pesticide registrations, creating first-mover advantages for compliant coating technologies.
- Ultrasound-Native Design:Vascular access teams are standardizing real-time needle visualization, rewarding catheter systems engineered for probe compatibility and reduced insertion attempts.
Industry Challenges
- Interventional Radiology Skill Gaps:Ultrasound-guided central line placement demands specialized training that outpaces supply of certified vascular access specialists, creating insertion bottleneck risks.
- Coating Validation Timelines:Antimicrobial efficacy claims require longitudinal clinical studies that delay product launches by 18-36 months against fast-follower competition.
- Infection Control Committee Fragmentation:Hospital procurement standardization across departments faces resistance from specialty silos with entrenched supplier relationships and protocol preferences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catheter-Related Bloodstream Infections (Crbsis) Market |
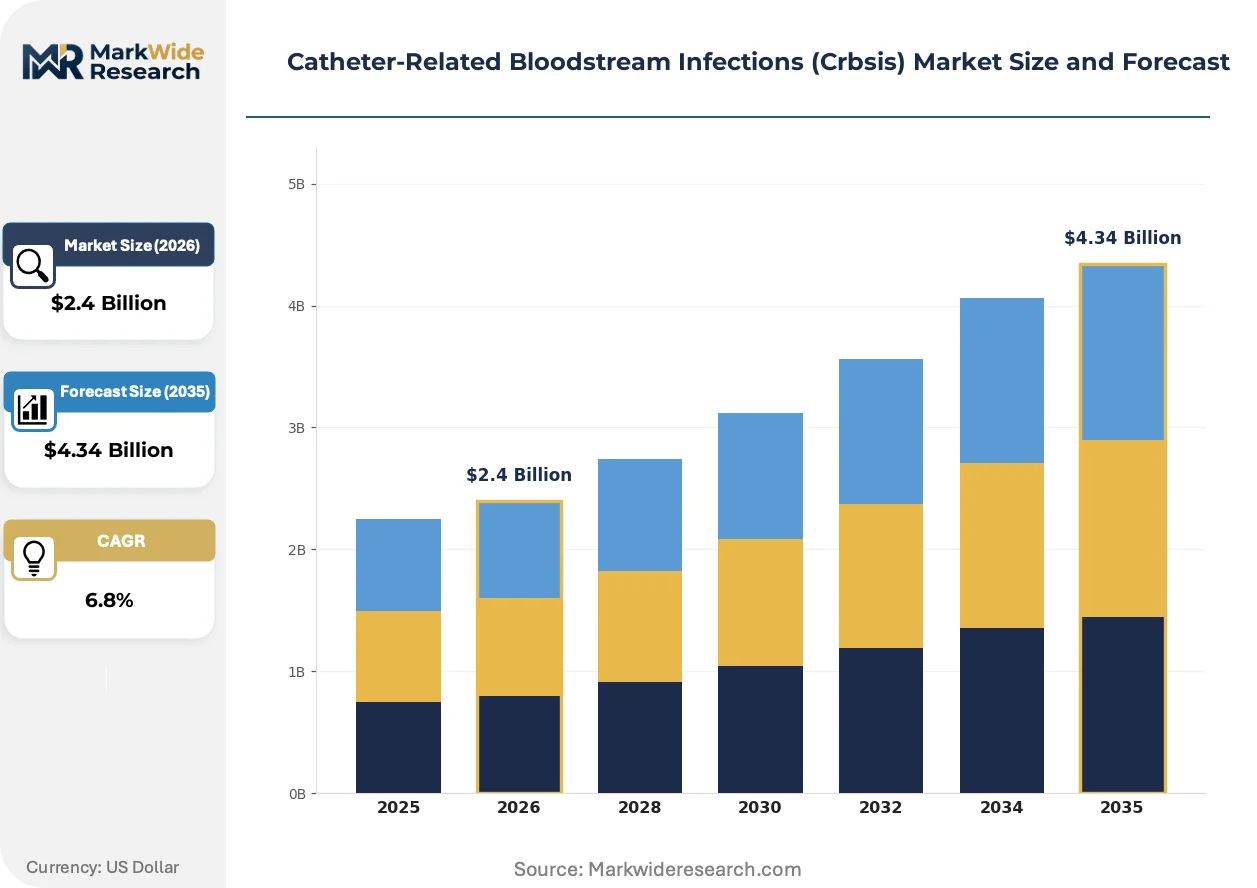
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Antimicrobial Coatings, Insertion Kits, Management Solutions End User: Hospitals, Outpatient Clinics, Diagnostic Laboratories, Home Healthcare Application: Critical Care, Elective Procedures, Long-term Therapy, Emergency Interventions Technology: Conventional, Antiseptic Techniques, Ultrasound-guided, Innovative Catheters |
| Companies Covered | Becton Dickinson and Company, Fresenius Medical Care, Pfizer, CorMedix, 3M Company, Citius Pharmaceuticals, Smiths Medical, AstraZeneca, Glenmark Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catheter-Related Bloodstream Infections (Crbsis) Market Strategic Shifts & Innovations
Device-based infection prevention is converging with pharmaceutical adjunct protocols, compressing the historical separation between medical device and drug therapy revenue models in vascular access care.
Chlorhexidine-impregnated sponge dressings paired with antimicrobial catheter hubs are collapsing the incidence of extraluminal colonization pathways that previously drove post-insertion infections. Surgical ICUs and oncology wards are adopting these integrated barrier systems as standard-of-care within 12-18 month replacement cycles. The technology is collapsing traditional distinctions between passive and active infection prevention, forcing bundled pricing negotiations that merge device and consumable procurement.
REACH authorization requirements for biocidal products in the European Union are reshaping antimicrobial coating formulations and supplier qualification processes. Manufacturers must demonstrate human and environmental safety profiles for silver, chlorhexidine, and benzalkonium chloride applications that exceed historical medical device standards. Dialysis catheter producers serving European markets are reformulating surface chemistries to maintain CE marking compliance under evolving ECHA substance evaluations.
Centralized infection control committees are consolidating catheter selection authority away from individual department heads, compressing vendor diversification and standardizing specifications across cardiology, oncology, and surgical units. Group purchasing organizations are capturing this consolidation through multi-hospital contracts that specify antiseptic barrier performance tiers. The United States acute care sector exhibits the most pronounced concentration, with tertiary systems deploying identical central line bundles across 10-40 facility networks.
Catheter-Related Bloodstream Infections (Crbsis) Market Segmentation
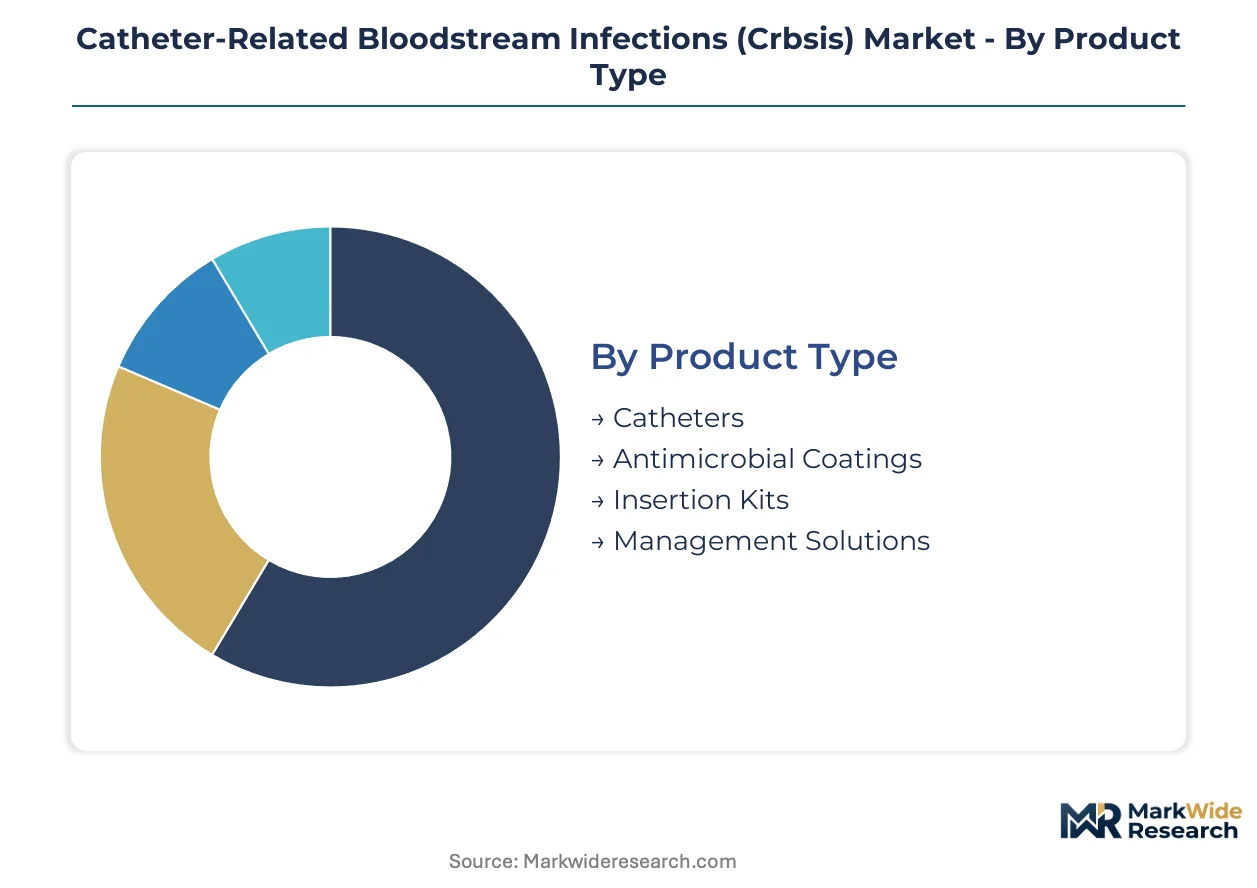
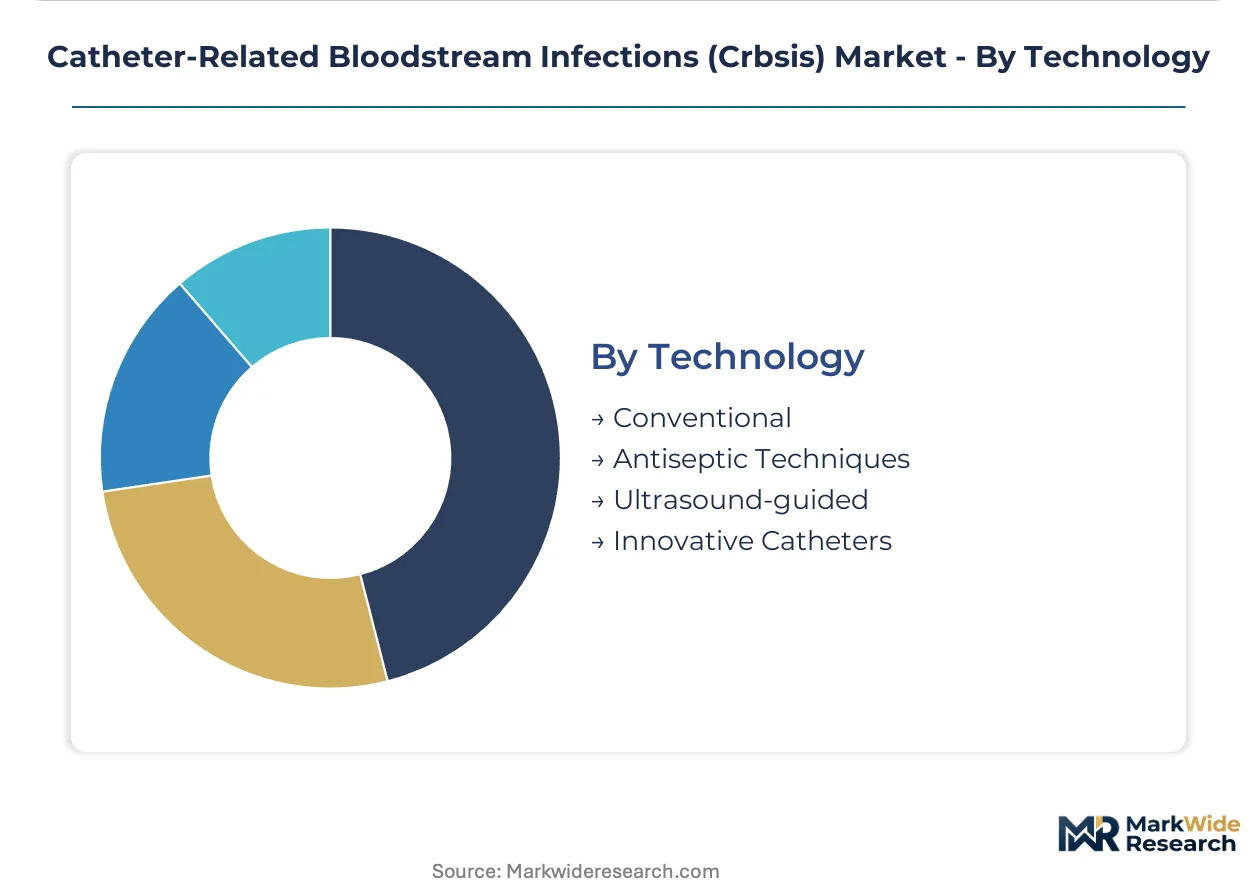
Segmentation in the CRBSI market reveals how infection prevention strategies fragment across clinical settings and technological maturity levels. Procurement committees weigh coating chemistry against insertion protocol investments when standardizing vascular access portfolios.
Product Type:
Mature hardware segments coexist with emerging coating technologies that command premium positioning through regulatory validation burdens.
- Catheters:Polyurethane and silicone-based vascular access devices form the procedural foundation across ICU and dialysis settings. Tertiary hospital networks in the United States concentrate procurement volume as central line bundles mandate standardized specifications.
- Antimicrobial Coatings:Silver ion release and chlorhexidine-impregnated surfaces extend dwell time safety windows through biofilm inhibition chemistry. FDA 510(k) clearance timelines for novel coating formulations delay commercial launches despite clinical efficacy data.
- Insertion Kits:Bundled sterile barrier systems integrate maximal precaution components for aseptic protocol compliance.
- Management Solutions:Software platforms and surveillance systems track device utilization and infection event reporting for quality metrics.
Catheters retain volume leadership; Antimicrobial Coatings holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive acute care infrastructure from distributed ambulatory delivery models.
- Hospitals:Centralized infection control committees drive standardized catheter selection across cardiology, oncology, and surgical departments through value-based procurement contracts. CMS reimbursement penalties for preventable bloodstream infections compel specification upgrades in United States acute care networks.
- Outpatient Clinics:Ambulatory surgical centers and infusion suites prioritize rapid turnover compatible with short-dwell catheter protocols.
- Diagnostic Laboratories:Phlebotomy and vascular access for imaging procedures generate periodic device demand outside continuous care pathways.
- Home Healthcare:Patient or caregiver-administered infusion therapy expands addressable volume beyond facility walls into residential settings.
Hospitals dominate revenue concentration; Home Healthcare is climbing the fastest as parenteral therapy shifts outside institutional walls.
Application:
Clinical urgency and patient acuity determine coating specification intensity and monitoring protocol rigor.
- Critical Care:ICU patients with prolonged central venous access face highest sepsis risk profiles, driving antimicrobial-coated catheter deployment. Mechanical ventilation and vasopressor dependencies in United States tertiary hospitals correlate with extended dwell times that amplify colonization probability.
- Elective Procedures:Scheduled surgeries with predictable recovery trajectories utilize standard vascular access without sustained antimicrobial protection.
- Long-term Therapy:Chemotherapy, parenteral nutrition, and antimicrobial regimens require tunneled or implanted devices with extended functionality.
- Emergency Interventions:Trauma and resuscitation scenarios prioritize rapid vascular access over coating sophistication.
Critical Care captures premium pricing; Long-term Therapy is expanding most quickly as oncology and immunology outpatient protocols proliferate.
Technology:
Customer type differentiation separates institutional purchasers investing in imaging infrastructure from cost-constrained settings relying on traditional techniques.
- Conventional:Landmark-based anatomical insertion without real-time visualization persists in resource-limited environments and emergency scenarios. Rural United States hospitals and international markets with constrained capital budgets maintain reliance on traditional Seldinger technique training.
- Antiseptic Techniques:Chlorhexidine skin preparation and hub disinfection protocols reduce extraluminal colonization independent of device engineering.
- Ultrasound-guided:Real-time needle visualization compresses mechanical complication rates and insertion attempt counts. Vascular access team specialization in United States academic medical centers accelerates probe-compatible catheter design requirements.
- Innovative Catheters:Bioelectric impedance sensing and integrated antimicrobial elution systems represent next-generation platform development.
Conventional methods retain procedural volume; Ultrasound-guided is gaining share fastest as vascular access specialist certification expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antimicrobial catheter manufacturing clusters in the United States, Germany, and Japan supply tertiary hospitals across North America, Europe, and Asia-Pacific. FDA 510(k) pathways in the United States and CE marking under the EU MDR in Europe shape product development timelines differently across jurisdictions.
United States
CMS reimbursement penalties for preventable bloodstream infections compel acute care networks to upgrade catheter specifications. The FDA enforces premarket clearance under 510(k) pathways for anti-infective vascular access devices. Boston and Minneapolis medical device clusters anchor integrated production of antimicrobial-coated catheters with antiseptic barrier systems.
Germany
REACH authorization requirements for biocidal products reshape antimicrobial coating formulations serving European hospital networks. The EU MDR elevates clinical evidence thresholds for novel coating technologies beyond historical medical device standards. The Baden-Württemberg industrial corridor concentrates precision polymer engineering for dialysis catheter surface chemistries.
Japan
PMDA regulatory frameworks govern antimicrobial device approvals for vascular access applications in aging patient populations. METI industrial policy supports domestic catheter manufacturing capacity for hospital procurement security. The Kanto region around Tokyo hosts specialized coating technology development for extended-dwell intravenous devices.
United Kingdom
NHS England infection prevention mandates standardize central line bundle compliance across acute trust networks. The MHRA post-Brexit regulatory framework maintains alignment with EU MDR device classification while establishing independent conformity assessment routes. London and the Southeast concentrate vascular access specialist training programs that drive ultrasound-guided insertion protocol adoption.
China
NMPA medical device registration requirements for imported antimicrobial catheters extend market entry timelines for foreign manufacturers. National health system reforms prioritize domestic production of high-value vascular access devices to reduce import dependency. The Yangtze River Delta manufacturing belt scales polyurethane catheter extrusion capacity for hospital procurement consolidation.
Catheter-Related Bloodstream Infections (Crbsis) Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in coating chemistry and polymer substrate supply. The vendor base separates into diversified medical device conglomerates with vascular access portfolios, renal care specialists with dialysis catheter channel control, and pharmaceutical adjunct therapy providers. Three archetypes dominate: integrated device-antiseptic bundle suppliers, coating technology licensors, and dialysis-focused channel captives. Competitive moves center on strategic partnerships between coating innovators and catheter manufacturers, plus geographic expansion through hospital group purchasing organization contracts.
Among diversified medical technology conglomerates, Becton Dickinson and Company occupies a position exemplifying integrated vascular access device production with antiseptic barrier capabilities. Fresenius Medical Care anchors the renal care specialist archetype through dialysis catheter channel dominance. Pfizer sits within the pharmaceutical adjunct therapy tier, pairing device-based prevention protocols with systemic antimicrobial agents. These three represent distinct competitive vectors rather than direct product substitution.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Fresenius Medical Care |
| Pfizer |
| CorMedix |
| 3M Company |
| Citius Pharmaceuticals |
| Smiths Medical |
| AstraZeneca |
| Glenmark Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Silver price volatility determines both the premium spread for antimicrobial-coated catheters and the geographic clustering of coating chemistry production. Manufacturers hedge commodity exposure through long-term offtake agreements with mining consortiums, compressing margin flexibility for standard-grade polyurethane devices while amplifying pricing power at the antimicrobial tier.
Pricing Analysis
FDA 510(k) clearance timelines dictate the pricing tier structure across the CRBSI prevention landscape. Three-tier pricing separates premium antimicrobial-eluting catheters with validated biofilm resistance from standard chlorhexidine-impregnated devices and economy polyurethane lines without surface modification. Price differentiation hinges on certification grade and volume scale, with tertiary hospital networks capturing 15-20 point discounts through GPO consolidation. Pricing pressure stems from CMS reimbursement penalties that force acute care facilities toward specification upgrades regardless of capital budget constraints. Outpatient dialysis clinics exhibit highest price sensitivity due to thin per-treatment margins, while academic medical centers prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced polymer extrusion equipment limit technology transfer to emerging manufacturing hubs, concentrating precision catheter production in the United States, Germany, and Japan. Silver nitrate and chlorhexidine gluconate feedstock draws from Indian and Chinese chemical processors, creating tariff exposure at the antimicrobial coating stage. Single-source vulnerability sits with specialized polyurethane resin suppliers serving FDA-registered device manufacturers. Distribution runs through hospital group purchasing organizations and renal care channel captives rather than open medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in ambulatory infusion and home healthcare segments where institutional procurement standardization has not yet penetrated. Dialysis catheter specialization and ultrasound-compatible device engineering create defendable niches against consolidated acute care vendors.
For Market Incumbents: Entrench position through backward integration into antimicrobial coating chemistry and captive supply of silver-ion substrates. Acquire vascular access specialist training programs to lock in ultrasound-guided insertion protocol standardization. Defend against coating technology licensors by accelerating EPA registration pathways for novel biocidal surface formulations.
For New Entrants and Emerging Players: Build out home healthcare infusion therapy portfolios where catheter selection remains decentralized and patient-directed. Target oncology outpatient clinics with tunneled device lines optimized for extended dwell chemotherapy protocols. Pursue white-label manufacturing partnerships with established polymer extruders to bypass 18-36 month FDA validation timelines.
For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by elevating clinical evidence burdens for novel coating technologies. Five-to-ten year viability favors coating chemistry licensors with validated biofilm science IP over commodity catheter manufacturers. Monitor EPA registration decisions for novel antimicrobial agents as the critical inflection signal for coating technology valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Partnership | Accelerates FDA 510(k) pathways by leveraging validated biofilm resistance data from specialty chemistry houses. |
| Ultrasound-Native Device Engineering | Captures vascular access team procurement specifications as real-time needle visualization becomes standard protocol. |
| Hospital System Partnership | Locks in multi-facility central line bundle standardization across 10-40 facility tertiary networks. |
| EPA Registration Pathway | Creates first-mover advantage for novel biocidal surface agents before competitive coating formulations reach market. |
| Reimbursement Strategy | Aligns catheter specifications with CMS penalty avoidance metrics to compel acute care facility upgrades. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with vascular access specialists, hospital infection control committee chairs, biomedical engineering directors, and GPO contracts managers; and secondary validation against FDA 510(k) filings, EPA pesticide registrations, CMS Medicare cost reports, and hospital procurement databases. Bottom-up triangulation of catheter shipment volumes by coating chemistry and top-down reconciliation with acute care capital expenditure surveys anchored market sizing.
Forecast inputs incorporated ICU admission trends, dialysis patient prevalence, and antimicrobial coating adoption curves across the projection horizon. Segmentation modeling captured product type, end user tier, application acuity, and insertion technology dimensions. CAGRs derived from logarithmic trend fitting of historical volume trajectories adjusted for regulatory milestone impacts including EU MDR implementation and updated FDA premarket notification requirements.
Sensitivities concentrate around silver commodity price shocks, EPA registration delays for novel biocidal agents, and vascular access specialist training bottlenecks that compress ultrasound-guided insertion adoption. Cross-checking against CDC NHSN bloodstream infection surveillance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Denture Disinfectants Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Infection Prevention Market
Infection Control
Hospital Acquired Infections Therapeutic Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
Australia Hand Sanitizer Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Sterilization Equipment and Disinfectant Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Virus Filtration Market
Infection Control
Global High Level Disinfection Services Market
Infection Control
Hand Hygiene Market