
 Global Sepsis Therapeutics Market | 2026-2036
Global Sepsis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sepsis Therapeutics Market Foresight
Combination therapy revenue is rewriting how pharmaceutical firms allocate R&D budgets across sepsis drug portfolios. Pfizer Inc leverages its manufacturing scale to dominate intravenous antibiotic supply chains in North American hospitals. Eli Lilly and Company differentiates through immunomodulator pipelines targeting cytokine storm modulation. GSK plc anchors its position via long-standing relationships with infectious disease clinics across Western Europe.
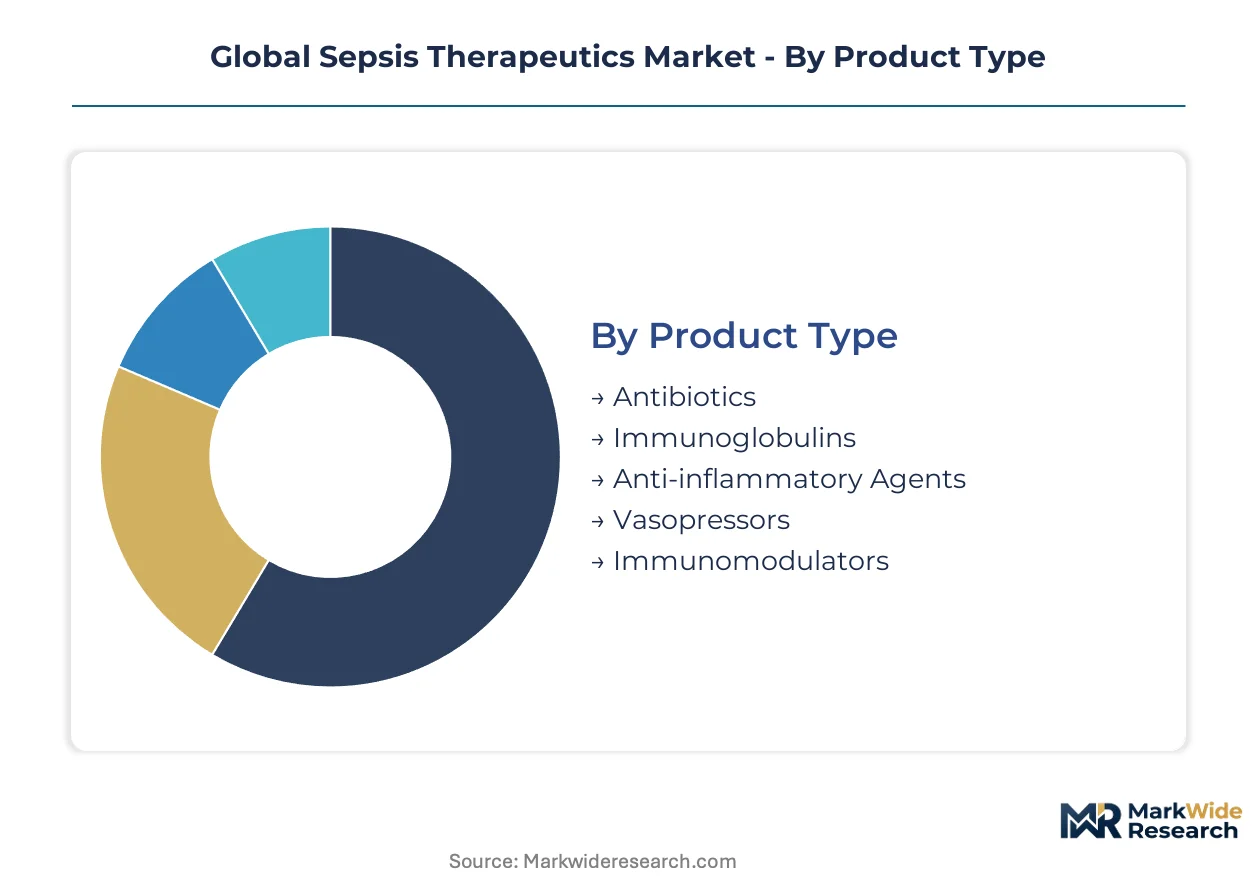
Sepsis therapeutics comprise pharmacological interventions designed to control infection source, modulate dysregulated immune response, and maintain organ perfusion in patients with life-threatening organ dysfunction caused by a dysregulated host response to infection; these treatments typically require intravenous administration within the first hour of recognition to achieve optimal survival outcomes. The therapy area dimension reveals septic shock commands the deepest clinical investment due to mortality escalation, while neonatal sepsis attracts emerging biologic development despite formulation complexity. Antibiotics occupy the largest product type share though immunomodulators represent the fastest margin expansion opportunity as precision medicine approaches mature.
FDA Breakthrough Therapy designations and EMA's PRIME eligibility framework are compressing development timelines for novel sepsis therapeutics while tightening manufacturing quality standards. WHO sepsis resolution targets and national antibiotic stewardship programs in Germany and Japan are reshaping hospital procurement criteria toward outcome-validated protocols. Stakeholders must monitor regulatory divergence between accelerated approval pathways and post-market evidence requirements to align portfolio investments with evolving payer expectations.
Market Dynamics
The FDA's Breakthrough Therapy designation pathway is compressing clinical trial timelines for novel immunomodulators while simultaneously tightening manufacturing quality standards across intravenous antibiotic supply chains. This regulatory acceleration is forcing pharmaceutical firms to reallocate R&D budgets toward precision medicine approaches.
Growth Catalysts
- Hospital-Acquired Infection Surveillance Mandates:Tightening mandates in the United States, Germany, and Japan are accelerating adoption of rapid sepsis diagnostics in intensive care units.
- Combination Antibiotic Protocols:Expanding ICU adoption of combination therapy is rewriting how pharmaceutical firms allocate R&D budgets across sepsis drug portfolios.
- Neonatal Sepsis Biologic Development:Emerging biologic development for neonatal sepsis is attracting clinical investment despite formulation complexity.
Market Restraints
- Antibiotic Stewardship Program Constraints:National antibiotic stewardship programs in Germany and Japan are reshaping hospital procurement criteria toward outcome-validated protocols, limiting volume expansion.
- Post-Market Evidence Requirements:Divergence between accelerated approval pathways and post-market evidence requirements is creating regulatory friction for portfolio investments.
- Immunomodulator Manufacturing Complexity:Precision medicine approaches for cytokine storm modulation require specialized manufacturing capabilities that concentrate supply risk.
Strategic Opportunities
- Underpenetrated Western Europe Markets:Long-standing relationships with infectious disease clinics create expansion pathways for immunomodulator portfolios across France, Italy, and Spain.
- EMA PRIME Eligibility Framework:The PRIME eligibility pathway offers regulatory tailwind for novel sepsis therapeutics seeking compressed development timelines in European markets.
- AI-Enabled Diagnostic Convergence:Integration of machine learning with rapid sepsis diagnostics is enabling earlier recognition protocols and therapy initiation.
Industry Challenges
- Immunomodulator Talent Scarcity:Cytokine storm modulation expertise remains concentrated among limited specialist research teams, constraining pipeline expansion.
- Legacy System Integration Complexity:New rapid diagnostic platforms face friction integrating with established hospital electronic health record systems.
- Multicenter Trial Coordination Burden:Sepsis trials require coordination across dispersed ICU networks, extending enrollment timelines and protocol compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sepsis Therapeutics Market |
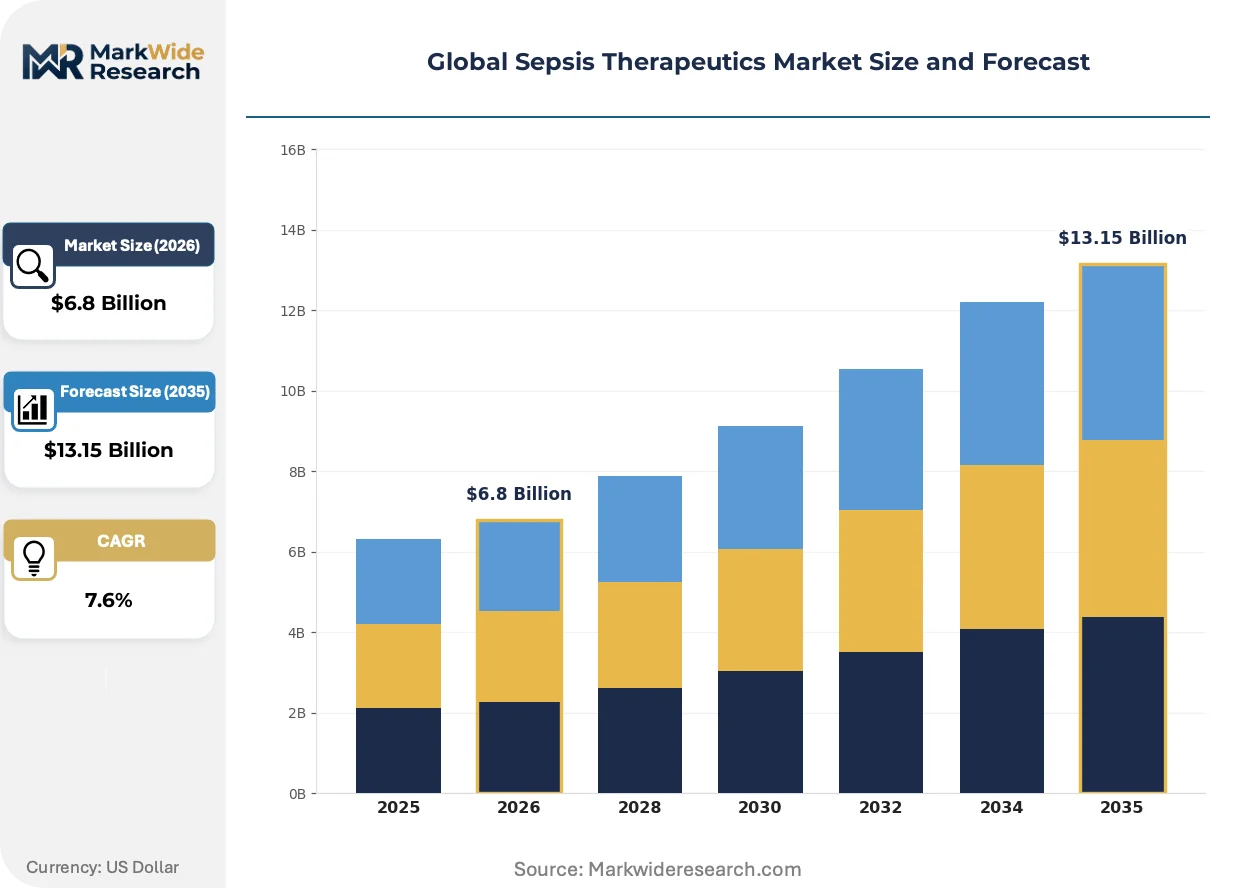
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Immunoglobulins, Anti-inflammatory Agents, Vasopressors, Immunomodulators Therapy Area: Neonatal Sepsis, Septic Shock, Bloodstream Infection, Pneumonia, Urinary Tract Infection End User: Intensive Care Units, Emergency Departments, Infectious Disease Clinics, Surgical Wards, Long-term Care Facilities Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular, Inhalation |
| Companies Covered | AbbVie Inc, Viatris Inc, Pfizer Inc, Astellas Pharma Inc, Eli Lilly and Company, GSK plc, F. Hoffmann-La Roche Ltd, Partner Therapeutics Inc, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sepsis Therapeutics Market Shifts & Advancements
Rapid diagnostic platforms are reshaping competitive positioning by collapsing the recognition-to-treatment window. This technological shift is forcing pharmaceutical firms to align drug development with point-of-care capabilities.
Machine learning algorithms embedded in sepsis risk stratification tools are migrating from retrospective analysis to real-time bedside decision support. Intensive care units in tertiary hospitals are adopting these platforms within six-month procurement cycles. This capability compression is enabling earlier antibiotic administration and immunomodulator timing.
EMA's PRIME eligibility framework is accelerating development timelines for novel sepsis therapeutics while tightening manufacturing quality standards. The industrial consequence is a bifurcation between firms capable of accelerated pathway navigation and those constrained by legacy compliance infrastructure. Immunomodulator pipelines targeting cytokine storm modulation are most affected, with sponsors restructuring clinical operations around European regulatory expectations.
Hospital procurement committees are consolidating vendor relationships around outcome-validated therapy protocols. Group purchasing organizations are displacing individual hospital formulary decisions with standardized sepsis bundles across health systems. This concentration is most visible in the United States, where integrated delivery networks are enforcing antibiotic stewardship compliance through centralized contracting.
Global Sepsis Therapeutics Market Segmentation
Sepsis therapeutics demand fragments across pharmacological mechanisms, clinical settings, and administration routes. Understanding these segment boundaries reveals where R&D investments concentrate and where procurement committees exercise vendor consolidation power.
Product Type:
After-sales service intensity varies sharply across product categories, with biologics requiring cold chain monitoring and batch-specific pharmacovigilance that antibiotics rarely demand.
- Antibiotics:Broad-spectrum and combination intravenous formulations dominate hospital formularies. Demand concentrates in United States tertiary hospitals where FDA antibiotic stewardship mandates tighten procurement criteria toward outcome-validated protocols.
- Immunomodulators:Biologic agents targeting cytokine storm modulation command specialized manufacturing and infusion center coordination. Investment momentum sits with German and Japanese academic medical centers pursuing precision medicine approaches.
- Immunoglobulins:Polyclonal antibody preparations require plasma-derived supply chains with extended donor traceability.
- Anti-inflammatory Agents:Corticosteroid and NSAID protocols face generic commoditization pressures across European markets.
- Vasopressors:Catecholamine and vasopressin analogs integrate into standardized sepsis bundles with limited differentiation.
Antibiotics hold the largest share; momentum sits with immunomodulators.
Therapy Area:
Cost tier stratification separates high-mortality acute presentations from resource-intensive neonatal populations with distinct reimbursement pathways.
- Septic Shock:Refractory hypotension requiring vasopressor support drives the deepest clinical investment due to mortality escalation and ICU length-of-stay costs. United States integrated delivery networks centralize procurement around outcome-guaranteed protocols.
- Neonatal Sepsis:Early-onset and late-onset presentations in premature infants attract emerging biologic development despite formulation complexity and limited trial enrollment. Japanese perinatal centers pioneer immunoglobulin protocols.
- Bloodstream Infection:Catheter-associated and primary bacteremia presentations trigger rapid diagnostic platform adoption.
- Pneumonia:Ventilator-associated and community-acquired variants align with existing respiratory therapy infrastructure.
- Urinary Tract Infection:Complicated pyelonephritis and urosepsis cases present lower acuity with ambulatory transition potential.
Septic shock commands premium pricing; neonatal sepsis is climbing the fastest.
End User:
Application urgency dictates staffing ratios, equipment investment, and therapy initiation windows across clinical environments.
- Intensive Care Units:Tertiary medical-surgical and cardiovascular ICUs deploy rapid sepsis diagnostics and combination antibiotic protocols within one-hour recognition mandates. German hospital-acquired infection surveillance requirements accelerate technology refresh cycles.
- Emergency Departments:High-volume triage environments in United States urban centers integrate machine learning risk stratification to compress door-to-antibiotic intervals.
- Infectious Disease Clinics:Outpatient parenteral antibiotic therapy programs manage step-down care with home infusion coordination.
- Surgical Wards:Post-operative sepsis surveillance relies on modified early warning score triggers.
- Long-term Care Facilities:Skilled nursing environments face diagnostic capability constraints and delayed recognition patterns.
Intensive care units absorb the highest per-patient investment; emergency departments are gaining share fastest.
Delivery Mode:
Volume concentration follows intravenous administration requirements, with oral and alternative routes serving narrow transition niches.
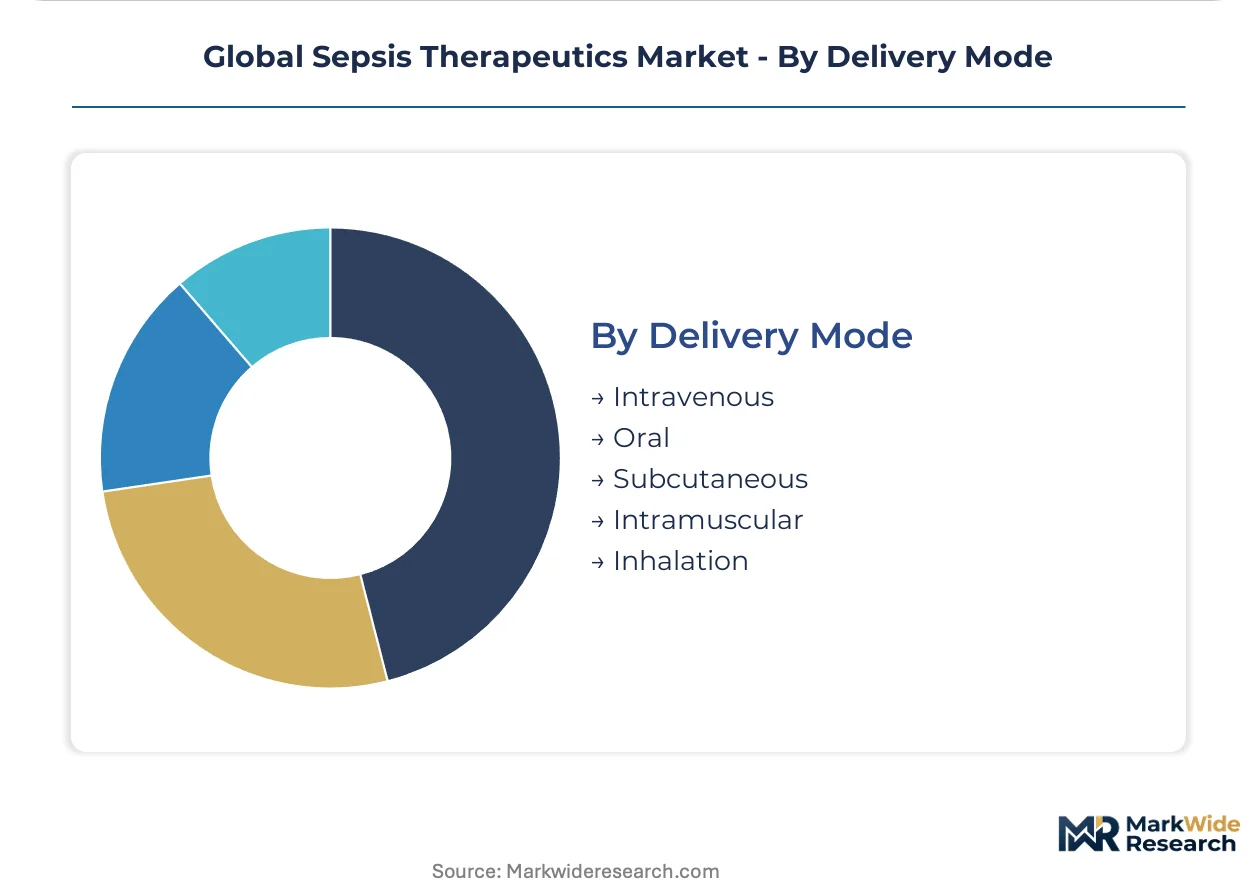
- Intravenous:Continuous and intermittent infusion protocols dominate acute sepsis management, requiring pharmacy compounding infrastructure and smart pump integration. United States group purchasing organizations consolidate vendor relationships around standardized infusion workflows.
- Oral:Bioavailability-limited agents serve step-down and outpatient parenteral antibiotic therapy completion with adherence monitoring challenges.
- Subcutaneous:Interferon and biologic preparations enable home administration for chronic immunomodulation.
- Intramuscular:Depot antibiotic formulations support resource-limited settings with refrigeration constraints.
- Inhalation:Nebulized antimicrobial delivery targets ventilator-associated pneumonia with limited sepsis systemic application.
Intravenous administration holds dominant volume; subcutaneous delivery shows steepest expansion trajectory for transition care models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sepsis therapeutic consumption diverges sharply across geographies: United States hospitals prioritize rapid diagnostic integration, while Japanese and German markets emphasize antibiotic stewardship compliance, and emerging economies concentrate on intravenous antibiotic access.
United States
Integrated delivery networks in tertiary hospitals drive demand for combination antibiotic protocols and AI-enabled sepsis recognition tools. FDA Breakthrough Therapy designations compress immunomodulator development timelines while tightening post-market evidence requirements. The Boston-Cambridge corridor anchors biologic development clusters targeting cytokine storm modulation.
Germany
Academic medical centers in Baden-Württemberg and Bavaria pioneer precision medicine approaches for septic shock management. National antibiotic stewardship programs reshape hospital procurement criteria toward outcome-validated protocols. EMA PRIME eligibility frameworks accelerate novel therapeutic approvals across Frankfurt-Rhine-Main pharmaceutical hubs.
Japan
Perinatal centers in Tokyo and Osaka advance immunoglobulin protocols for neonatal sepsis despite formulation complexity constraints. METI coordinates hospital-acquired infection surveillance mandates that accelerate rapid diagnostic adoption. The Kansai region concentrates biologic manufacturing infrastructure for plasma-derived therapeutics.
United Kingdom
NHS England's sepsis recognition mandates compress door-to-antibiotic intervals in emergency departments across London and Birmingham. MHRA alignment with EMA accelerated pathways enables earlier immunomodulator access. The Cambridge-London corridor hosts emerging biotech clusters focused on AI-diagnostic convergence.
India
Private hospital chains in Maharashtra and Karnataka expand ICU capacity with standardized sepsis bundles and intravenous antibiotic protocols. CDSCO regulatory frameworks balance accelerated access with manufacturing quality standards. The Delhi-NCR corridor concentrates domestic pharmaceutical production of broad-spectrum antibiotics.
Global Sepsis Therapeutics Market Competitive Landscape
Capability concentration sits with immunomodulator specialists; scale advantage sits with intravenous antibiotic manufacturers. The market structures around three tiers: multinational pharmaceutical conglomerates with integrated hospital supply chains, mid-cap biotech firms with precision medicine pipelines, and regional generic manufacturers serving cost-sensitive acute care markets. Dominant competitive moves include portfolio diversification into rapid diagnostic partnerships and backward integration into active pharmaceutical ingredient production.
Within the multinational tier, Pfizer Inc and Eli Lilly and Company exemplify divergent strategic archetypes: the former anchors manufacturing scale across North American hospital networks, while the latter occupies a position in cytokine storm modulation pipelines. GSK plc represents the European incumbent model, leveraging long-standing infectious disease clinic relationships across Western Europe. These three entities collectively illustrate how regulatory pathway expertise and manufacturing infrastructure determine competitive positioning in sepsis therapeutics.
| Leading Market Players |
|---|
| AbbVie Inc |
| Viatris Inc |
| Pfizer Inc |
| Astellas Pharma Inc |
| Eli Lilly and Company |
| GSK plc |
| F. Hoffmann-La Roche Ltd |
| Partner Therapeutics Inc |
| AstraZeneca plc |
| Others |
Supply & Pricing Matrix
The Boston-Cambridge biopharmaceutical corridor anchors immunomodulator manufacturing capacity, concentrating supply risk for cytokine storm modulation therapies and amplifying pricing power for sponsors capable of accelerated FDA Breakthrough Therapy navigation. This geographic concentration of precision medicine infrastructure creates asymmetric leverage between firms with captive biologics production and those dependent on contract manufacturing organizations.
Pricing Analysis
Long-term offtake agreements dominate procurement between integrated delivery networks and intravenous antibiotic manufacturers, while spot purchasing persists for generic broad-spectrum agents in cost-sensitive acute care markets. Three-tier pricing structure across premium biologics, standard branded antibiotics, and economy generics reflects FDA certification tier and cold chain service bundling. Pricing pressure stems from national antibiotic stewardship programs in Germany and Japan tightening outcome-validated procurement criteria. Emergency departments exhibit highest price sensitivity due to volume throughput mandates, while intensive care units prioritize clinical efficacy over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard between plasma-derived immunoglobulin suppliers and Japanese perinatal centers managing neonatal sepsis protocols. Active pharmaceutical ingredient production concentrates in India and China, with fill-finish operations anchored in the United States and Germany. Biologics manufacturing draws from recombinant protein production, plasma fractionation, and specialized aseptic filling inputs. Single-source vulnerability persists for cytokine storm modulation cell lines. Distribution runs through group purchasing organizations consolidating hospital formulary decisions across United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sepsis therapeutics represent a service-attach opportunity where pharmacovigilance monitoring and infusion center coordination generate recurring revenue expanding faster than drug product sales. Cold chain logistics and batch-specific adverse event tracking now command premium pricing separate from molecule procurement.
For Market Incumbents: Insulate manufacturing scale advantages through backward integration into active pharmaceutical ingredient production, particularly for combination antibiotic protocols facing generic erosion. Lock in group purchasing organization contracts with outcome-guaranteed sepsis bundles before emerging biotech firms secure FDA Breakthrough Therapy designations for competing immunomodulators. For New Entrants and Emerging Players: Build out AI-enabled diagnostic partnerships as the fastest path to hospital formulary inclusion, leveraging machine learning risk stratification to compress door-to-antibiotic intervals in United States emergency departments. Target underpenetrated infectious disease clinics in France, Italy, and Spain with subcutaneous immunomodulator formulations enabling home administration and reduced ICU length-of-stay. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision medicine specialists with cytokine storm modulation pipelines and EMA PRIME eligibility track records over legacy intravenous antibiotic manufacturers facing stewardship program constraints. The inflection signal to monitor is FDA approval velocity for novel immunomodulators relative to antibiotic stewardship mandate expansion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA Breakthrough Therapy designation compresses immunomodulator development timelines for cytokine storm modulation candidates. |
| Regulatory Approval Pathway | EMA PRIME eligibility framework accelerates novel sepsis therapeutic access across German and Japanese academic medical centers. |
| Manufacturing Scale-Up | Cold chain biologics infrastructure expansion secures supply security for plasma-derived immunoglobulin protocols in perinatal settings. |
| Pipeline Diversification | AI-diagnostic convergence partnerships enable earlier sepsis recognition and therapy initiation in United States tertiary hospitals. |
| Reimbursement Strategy | Outcome-validated protocol contracting aligns with NHS England sepsis recognition mandates and integrated delivery network centralization. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Scenario-bracketing around regulatory approval velocity and antibiotic stewardship mandate intensity shaped projections across the analysis window. Segmentation dimensions included therapy area, product type, end-user setting, and regional regulatory cluster. CAGRs were derived from epidemiological trend extrapolation and pricing elasticity modeling specific to sepsis recognition protocol adoption.
Practitioners should monitor FDA Breakthrough Therapy designation grants and EMA PRIME eligibility decisions for early signals of competitive inflection. Forecasts reflect assumptions about immunomodulator manufacturing scale-up feasibility and rapid diagnostic platform integration timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Surgical Site Infections Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Dental Infection Treatment Market
Infection Control
Infection Prevention Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Peptide-Based Infection Therapeutics Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Intra Abdominal Infection Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Antimicrobial Suture Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Point of Care Infection Control Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market