
 Sterilization Equipment and Disinfectant Market | 2026-2036
Sterilization Equipment and Disinfectant Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Equipment and Disinfectant Market Outlook
Multi-source procurement for sterilization equipment is broadening as hospital systems diversify vendor relationships beyond legacy single-source contracts. STERIS plc leverages its installed base of steam sterilizers to sustain recurring consumable revenue streams across North American health networks. Getinge AB anchors European market presence through automated washer-disinfector lines, while Shinva Medical Instrument Co., Ltd. dominates domestic Chinese hospital procurement with localized service infrastructure.
Sterilization equipment and disinfectant encompasses thermal, chemical, and radiation-based systems engineered to achieve microbial lethality validated by SAL 10^-6 parameters for medical and industrial applications. Steam sterilizers operate at saturated steam temperatures of 121°C to 134°C with corresponding pressure thresholds, while hydrogen peroxide vapor systems enable low-temperature processing of heat-sensitive endoscopes and electronics. Chemical sterilants command premium positioning due to material compatibility requirements in minimally invasive surgical suites, whereas plasma technology segments attract specialized demand from ophthalmic and semiconductor cleanroom operations. Healthcare facilities represent the dominant application channel, with pharmaceutical manufacturing driving fastest growth in continuous sterilization tunnel adoption for parenteral drug packaging.
FDA 510(k) clearance pathways and EPA disinfectant registration requirements shape product development timelines and market access barriers for entrants targeting US healthcare systems. EMA Medical Device Regulation and ISO 17665 steam sterilization validation standards compel European manufacturers to maintain documented bioburden control protocols across distributed production networks. Stakeholders must monitor evolving sustainability mandates from the EU Green Deal affecting chemical sterilant formulation chemistry and equipment energy consumption benchmarking.
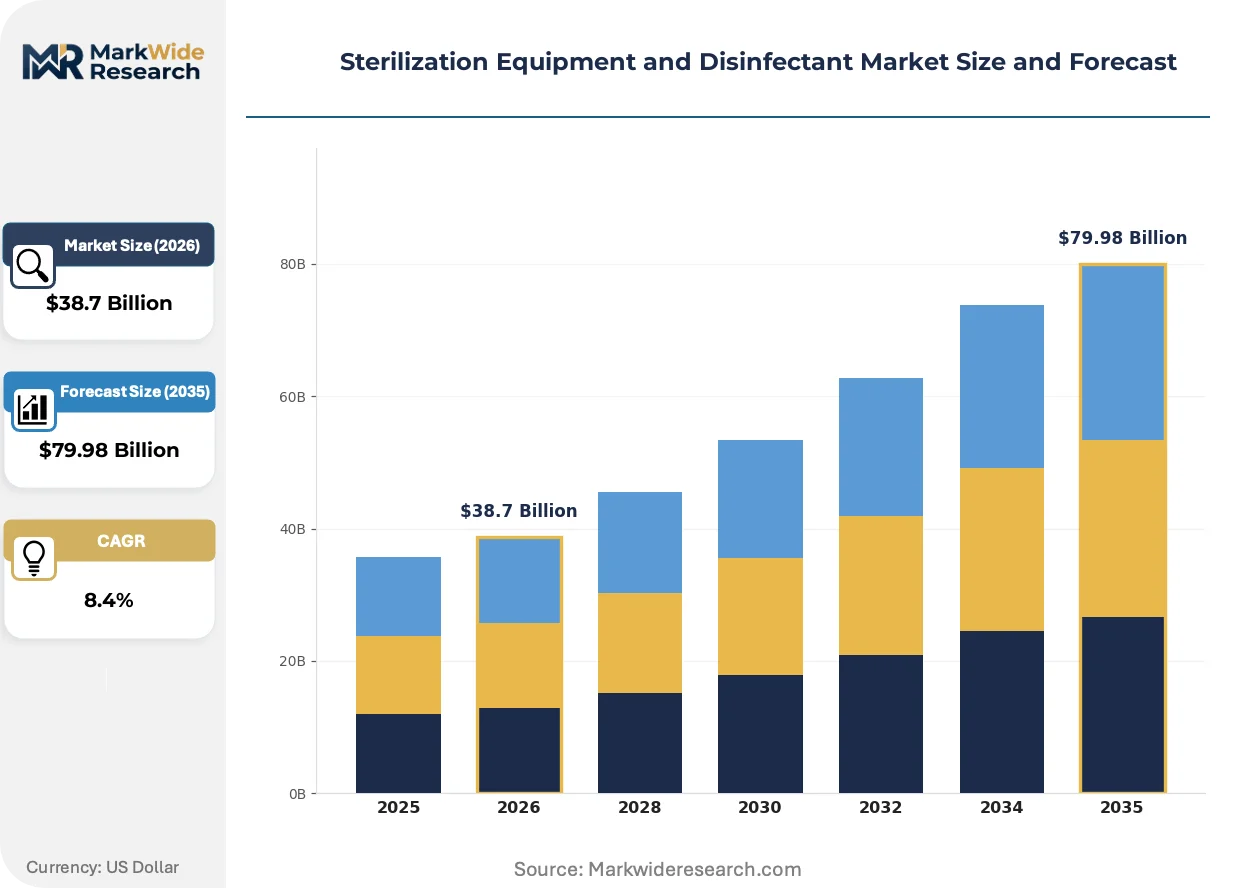
Market Dynamics
Hospital systems are consolidating sterilization operations into centralized sterile supply departments, forcing equipment vendors to reconfigure service architectures around fleet management rather than unit sales. This operational concentration is compressing procurement cycles and elevating technical service capabilities as the primary competitive differentiator.
Growth Catalysts
- FDA 510(k) pathway modernization:Streamlined clearance timelines for hydrogen peroxide vapor systems are accelerating hospital adoption of low-temperature alternatives to steam sterilization for heat-sensitive instrumentation.
- Surgical volume recovery:Ambulatory surgical centers in the United States are expanding sterilization capacity to accommodate migrated procedures from inpatient settings, creating equipment demand concentration.
- EU MDR traceability mandates:Medical device reprocessing documentation requirements are compelling European hospitals to replace legacy sterilizers with connected systems enabling automated cycle logging.
Market Restraints
- Stainless steel input volatility:Chamber fabrication costs for steam sterilizers fluctuate with nickel pricing, compressing margins for equipment manufacturers without long-term supply agreements.
- Peracetic acid supply concentration:Chemical sterilant production clusters in German and Belgian chemical corridors, creating single-source vulnerability for North American healthcare facilities.
- Heat sensitivity ceiling:Thermal sterilization remains incompatible with advanced polymer surgical instruments, limiting addressable market expansion in minimally invasive suites.
Strategic Opportunities
- Indian hospital infrastructure buildout:Central government health scheme expansion is funding sterile supply department construction in tier-2 and tier-3 cities with limited installed base.
- Pharmaceutical continuous processing:Sterilization tunnel integration with blow-fill-seal lines for parenteral packaging presents white space beyond traditional healthcare applications.
- EU Green Deal chemistry restrictions:Formulation bans on legacy aldehyde sterilants are creating regulatory tailwinds for hydrogen peroxide and peracetic acid platform expansion.
Industry Challenges
- Biomedical equipment technician scarcity:Specialized training requirements for automated washer-disinfector maintenance exceed supply of certified personnel in rural health networks.
- ISO 17665 validation timelines:Steam sterilization performance qualification protocols extend equipment commissioning by 8-12 weeks, delaying revenue recognition for vendors.
- Legacy system integration friction:Hospital information system connectivity with new-generation sterilizers requires custom middleware development, complicating deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Equipment and Disinfectant Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Sterilizers, Ethylene Oxide Sterilizers, Hydrogen Peroxide Sterilizers, Chemical Sterilants Application: Healthcare Facilities, Laboratories, Pharmaceuticals, Food Processing Technology: Dry Heat, Chemical, Radiation, Plasma End User: Hospitals, Clinics, Research Institutions, Industrial Manufacturers |
| Companies Covered | STERIS plc, Getinge AB, Fortive Corp., Solventum Corporation, 3M, Belimed AG, Steelco S.p.A., Shinva Medical Instrument Co., Ltd., MMM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Equipment and Disinfectant Market Strategic Shifts
Connected sterilization platforms are displacing standalone equipment, embedding sensors and cloud analytics that transform capital goods into recurring revenue instruments. This shift is compressing traditional sales cycles and elevating software competency among hardware manufacturers.
Peracetic acid vapor systems are rewriting material compatibility assumptions in ophthalmic device reprocessing. Surgical suites handling premium intraocular lenses are adopting these platforms at twice the rate of general surgery departments. The technology is enabling same-day turnaround for single-use device reprocessing programs, compressing inventory carrying costs.
EMA Medical Device Regulation Annex I technical documentation requirements are forcing sterilization equipment manufacturers to maintain bioburden control records across distributed component sourcing. European notified bodies are rejecting submissions lacking validated supply chain contamination controls. German and French hospital procurement departments are now requiring MDR compliance certificates as gate criteria for tender participation.
After-sales service unbundling is fragmenting traditional equipment procurement in United States health networks. Hospital systems are separating capital acquisition from maintenance contracts, awarding multi-vendor service agreements to specialized third-party technicians. This behavior is most visible in California and Texas IDN consolidations, where sterile supply directors prioritize uptime guarantees over manufacturer loyalty.
Sterilization Equipment and Disinfectant Market Segmentation
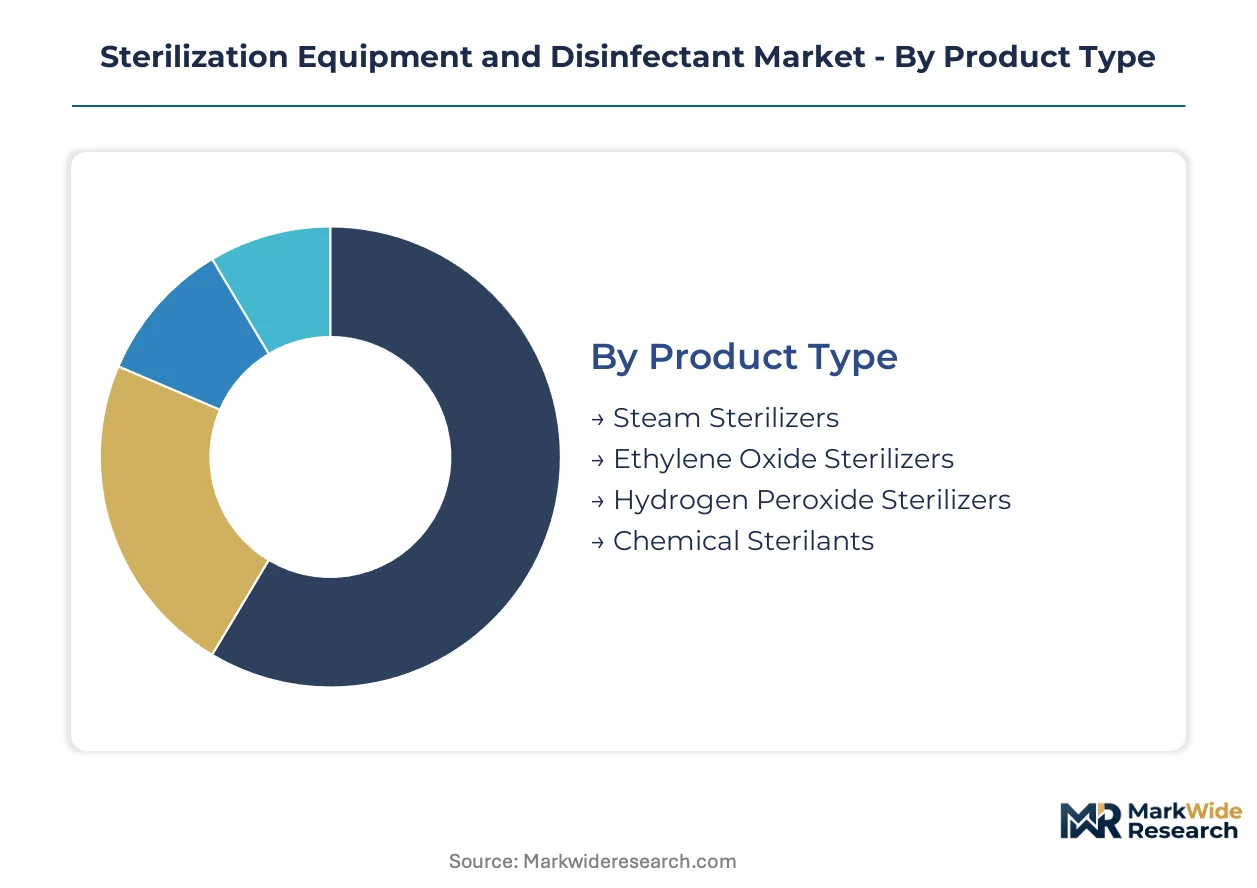
Sterilization equipment purchasing decisions split across capital intensity thresholds and regulatory validation requirements. Each segmentation dimension reveals distinct procurement patterns between healthcare systems and industrial operators.
Product Type:
Steam sterilizers demand the heaviest upfront capital deployment, with chamber fabrication and pressure vessel certification driving equipment costs. Hydrogen peroxide platforms require lower infrastructure investment but impose recurring consumable commitments.
- Steam Sterilizers:Saturated steam systems operating at 121°C to 134°C with validated SAL 10^-6 lethality parameters dominate hospital central sterile supply departments. United States health networks are replacing legacy units to meet FDA 510(k) documentation requirements for connected cycle logging.
- Hydrogen Peroxide Sterilizers:Low-temperature vapor platforms process heat-sensitive endoscopes and polymer surgical instruments incompatible with thermal methods. Ambulatory surgical centers in Germany are adopting these systems to accommodate migrated minimally invasive procedures.
- Ethylene Oxide Sterilizers:Gas-based systems serve industrial-scale medical device manufacturers with chamber volumes exceeding healthcare installations.
- Chemical Sterilants:Peracetic acid and glutaraldehyde formulations enable manual reprocessing where automated equipment deployment is uneconomical.
Most installed capacity flows through steam sterilizers. Expansion is steepest in hydrogen peroxide platforms.
Application:
Volume concentration varies sharply by sterilization cycle frequency and batch size requirements. Healthcare facilities process thousands of instrument sets daily, while pharmaceutical operations prioritize continuous tunnel throughput.
- Healthcare Facilities:Hospital sterile supply departments and ambulatory surgery centers execute validated reprocessing protocols for reusable medical devices. Centralized operations in China are expanding automated washer-disinfector integration to manage surgical volume recovery.
- Pharmaceuticals:Blow-fill-seal packaging lines for parenteral drugs require sterilization tunnel integration with continuous processing workflows. European manufacturers are retrofitting legacy batch systems to meet EMA traceability mandates.
- Laboratories:Research facilities demand smaller-capacity units with flexible cycle programming for diverse material compatibility.
- Food Processing:Aseptic packaging operations deploy hydrogen peroxide vapor for carton sterilization in high-speed filling lines.
Healthcare facilities command the largest equipment installed base. Pharmaceutical applications are climbing the fastest.
Technology:
Energy consumption profiles and material compatibility constraints determine technology selection across end-use segments. Thermal methods retain cost advantages where instrument construction permits.
- Chemical:Liquid and vapor-phase sterilants enable processing of temperature-sensitive materials including flexible endoscopes and electronic components. FDA streamlined clearance pathways for hydrogen peroxide systems are accelerating hospital adoption.
- Plasma:Low-temperature hydrogen peroxide plasma systems serve ophthalmic device reprocessing with stringent material compatibility requirements. French and German surgical suites handling premium intraocular lenses are deploying these platforms at elevated rates.
- Dry Heat:Convection and conduction systems process moisture-sensitive powders and oils in pharmaceutical manufacturing.
- Radiation:Gamma and electron beam sterilization dominates single-use medical device terminal sterilization at contract service providers.
Chemical technology carries the broadest installed footprint. Plasma systems are gaining share fastest in specialized surgical applications.
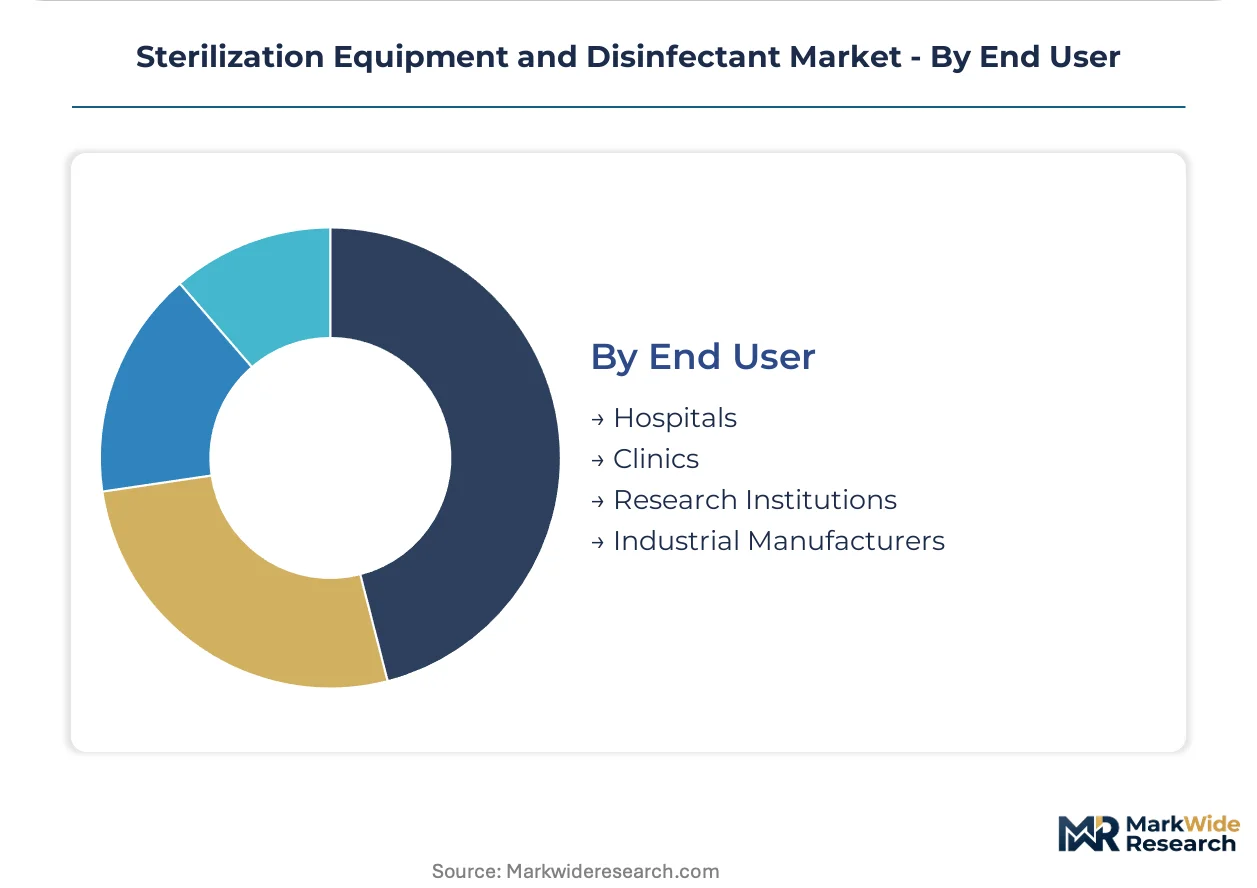
End User:
Procurement sophistication diverges between integrated delivery networks with dedicated sterile supply infrastructure and fragmented operators relying on third-party reprocessing.
- Hospitals:Central sterile supply departments in United States IDNs are consolidating vendor relationships and unbundling service contracts from capital acquisition. California and Texas health systems prioritize uptime guarantees over manufacturer loyalty.
- Industrial Manufacturers:Medical device producers maintain captive sterilization capacity or contract with specialized service providers. ISO 17665 validation protocols extend equipment commissioning timelines, compressing vendor revenue recognition cycles.
- Clinics:Smaller surgical facilities deploy tabletop sterilizers or outsource to centralized reprocessing hubs.
- Research Institutions:Academic medical centers balance diverse protocol requirements against limited capital budgets.
Hospitals absorb the majority of capital equipment shipments. Industrial manufacturers are scaling capacity most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical corridors anchor peracetic acid production for North American healthcare facilities, while Chinese hospital procurement concentrates sterilization equipment demand in tier-2 city expansions.
United States
FDA 510(k) pathway modernization accelerates hydrogen peroxide vapor system clearances for heat-sensitive endoscope processing. Ambulatory surgical centers in Texas and California expand sterilization capacity to accommodate migrated inpatient procedures. IDN consolidations in these states unbundle service contracts from capital acquisition, prioritizing uptime guarantees.
Germany
EMA Medical Device Regulation traceability mandates compel hospital replacement of legacy sterilizers with connected cycle-logging systems. Automated washer-disinfector lines anchor Getinge AB's European market presence. The Rhine-Ruhr chemical corridor maintains concentrated peracetic acid production, creating supply vulnerability for export-dependent healthcare systems.
China
Central government health scheme expansion funds sterile supply department construction in tier-2 and tier-3 cities with limited installed base. NMPA medical device regulations shape domestic procurement standards. Shinva Medical Instrument Co., Ltd. dominates hospital procurement through localized service infrastructure in provincial medical device clusters.
India
CDSCO medical device regulations tighten import requirements for sterilization equipment, favoring domestic assembly partnerships. Central sterile supply department buildout accelerates in Maharashtra and Karnataka hospital networks. Mumbai and Bangalore medical device distributors expand technical service capabilities to support automated fleet deployment.
Japan
PMDA regulatory harmonization with ISO 17665 standards extends equipment commissioning validation timelines. METI sustainability mandates drive energy consumption benchmarking for steam sterilizer replacements. Tokyo and Osaka surgical centers adopt hydrogen peroxide plasma systems for ophthalmic device reprocessing with stringent material compatibility requirements.
Sterilization Equipment and Disinfectant Market Competitive Environment
Global majors compete with regional champions across service architecture and regulatory compliance capabilities. The vendor base stratifies between integrated sterilization platform providers and specialized consumable formulators. Three archetypes dominate: North American health network service integrators, European regulatory compliance specialists, and Chinese domestic procurement champions. Competitive moves concentrate on fleet management contract unbundling and third-party technical service partnerships.
Among publicly traded healthcare equipment conglomerates, STERIS plc and Getinge AB exemplify divergent regional anchoring strategies, with the former sustaining recurring consumable revenue across North American networks and the latter dominating European automated washer-disinfector deployment. Fortive Corp. occupies a position spanning industrial and medical sterilization applications through portfolio diversification. These three entities represent the scale-driven tier where installed base leverage determines recurring revenue capture.
| Leading Market Players |
|---|
| STERIS plc |
| Getinge AB |
| Fortive Corp. |
| Solventum Corporation |
| 3M |
| Belimed AG |
| Steelco S.p.A. |
| Shinva Medical Instrument Co., Ltd. |
| MMM Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA 510(k)-cleared connected sterilizers and legacy thermal units manifests in both capital pricing spreads and supply chain sourcing complexity. Premium-tier equipment commands elevated procurement thresholds through validated bioburden documentation, while commodity steam sterilizers compete on nickel-input cost positioning and regional fabrication proximity.
Pricing Analysis
Stainless steel nickel-content pass-through dominates steam sterilizer cost structures, with chamber fabrication margins compressing when spot metal markets spike. Three-tier pricing structure across premium connected systems, standard automated units, and economy thermal platforms reflects after-sales bundling intensity and ISO 17665 validation documentation depth. Pricing pressure stems from hospital IDN consolidations unbundling service contracts from capital acquisition. Ambulatory surgical centers exhibit acute price sensitivity; integrated delivery networks with captive biomedical engineering teams prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Transoceanic freight cost volatility for pressure vessel chambers shapes total landed cost differentials between German fabricators and Chinese assembly partners. Peracetic acid production concentrates in Belgium and Germany, while steam sterilizer chamber manufacturing draws from Italian and Chinese metalworking clusters. Single-source vulnerability runs through the Rhine-Ruhr chemical corridor for North American healthcare sterilant supply. Distribution runs through hospital GPO contracts and direct OEM service architectures, with third-party technical service partnerships fragmenting traditional manufacturer-captive models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in consumable attach rates and software-enabled fleet management contracts, as hardware commoditization pressures force vendors toward recurring revenue architectures. Premium-tier positioning through MDR-compliant connected systems offers the clearest path to pricing power recovery.
For Market Incumbents: To counter third-party technical service unbundling, STERIS plc and Getinge AB should deepen captive service infrastructure in California and Texas IDN consolidations where uptime guarantees determine contract awards. Backward integration into peracetic acid formulation chemistry mitigates supply concentration risk from Belgian and German production clusters. Certification investment in FDA 510(k) pathway modernization for hydrogen peroxide platforms sustains low-temperature sterilization pricing premiums against steam commoditization. For New Entrants and Emerging Players: Launch via third-party service partnerships targeting Indian tier-2 and tier-3 city hospital buildouts, where central government health scheme funding outruns domestic technical service capacity. Pharmaceutical continuous sterilization tunnel integration presents the most penetrable white space beyond saturated healthcare installed bases. White-label connected platform development for regional European champions bypasses EMA MDR traceability mandate compliance timelines that disadvantage de novo entrants. For Investors and Strategic Acquirers: Consolidation pressure builds where biomedical equipment technician scarcity exceeds automated fleet deployment velocity in rural health networks. Mid-cap sterilization equipment manufacturers with validated ISO 17665 documentation protocols and established European notified body relationships represent prime acquisition targets. Watch hydrogen peroxide vapor system FDA clearance velocity as inflection indicator for low-temperature platform market share capture against thermal sterilization incumbency.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Platform Development | Cloud-enabled cycle logging satisfies EMA MDR traceability mandates for European hospital procurement. |
| Peracetic Acid Supply Security | Captive formulation chemistry insulates margins from Rhine-Ruhr production concentration vulnerability. |
| Third-Party Service Partnership | Unbundled maintenance contracts capture IDN consolidation demand in Texas and California health systems. |
| Pharmaceutical Tunnel Integration | Blow-fill-seal line compatibility opens parenteral packaging white space beyond healthcare saturation. |
| Indian Infrastructure Localization | Tier-2 city service hubs align with central government health scheme sterile supply department funding. |
Study Parameters
Bottom-up hospital procurement modeling reconciled against top-down equipment shipment tracking forms the analytical core. Primary interviews with sterile supply directors, biomedical equipment technicians, GPO contracts managers, and pharmaceutical manufacturing engineers combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and customs trade records. Top-down triangulation against installed base estimates and replacement cycle assumptions grounds volume projections.
Input-output matrix framing links stainless steel nickel pricing, peracetic acid chemical feedstock costs, and biomedical technician labor availability to equipment demand elasticity across the projection horizon. Segmentation dimensions span sterilization technology type, application channel, end-user scale tier, and regional regulatory cluster. CAGRs derive from surgical volume recovery trajectories, MDR-mandated replacement cycle compression, and pharmaceutical continuous processing adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel price volatility extremes or EMA notified body backlog extensions. Forecasts reflect assumptions about surgical migration patterns, IDN consolidation velocity, and chemical sterilant formulation chemistry regulatory shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Surgical Site Infection Control Market
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Antimicrobial Wipes Market
Infection Control
Disinfection Equipment Market
Infection Control
Botulism Market
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
Sterilization Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Sterilization Technologies Market
Infection Control
Sterilization Monitoring Market
Infection Control
Sterilization Tunnel Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market