
 Global High Level Disinfection Services Market | 2026-2036
Global High Level Disinfection Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Level Disinfection Services Market Intelligence
Peracetic acid formulations are displacing glutaraldehyde in automated endoscope reprocessors, which is recalibrating operating economics for sterilization service contracts. STERIS leverages captive peracetic acid supply to anchor its North American hospital accounts. Getinge AB sustains European market presence through integrated washer-disinfector and chemistry bundling. Ecolab competes on chemical service density, embedding dosing equipment and compliance reporting into multi-year agreements.
High level disinfection services encompass the complete decontamination cycle for semi-critical medical devices, employing liquid chemical germicides achieving tuberculocidal, virucidal, fungicidal, and sporicidal kill within standardized contact times. Automated disinfection systems using hydrogen peroxide vapor or peracetic acid dominate capital-intensive hospital installations, while manual chemical cleaning persists in smaller clinics where equipment utilization cannot justify robotics. End user segmentation tilts toward hospitals as surgical volume rebounds and joint commission inspection frequency intensifies, with laboratories representing a faster-growing but smaller revenue pool as biosafety level containment requirements expand.
FDA 510(k) clearance requirements for automated endoscope reprocessors shape device compatibility and service validation protocols, while EPA registration of disinfectant chemistries determines which formulations service providers may legally deploy in US healthcare facilities. The EU Medical Device Regulation imposes post-market surveillance obligations on disinfection equipment manufacturers selling into European member states. Stakeholders must monitor evolving sporicidal efficacy testing standards and chemistry compatibility matrices as device complexity advances.
Market Dynamics
The EPA's tightened sporicidal efficacy standards are compressing service provider certification timelines while simultaneously elevating capital requirements for chemistry validation infrastructure. This regulatory pressure is reshaping competitive economics across the decontamination services value chain.
Growth Catalysts
- Joint Commission Inspection Intensification:US hospitals are expanding outsourced disinfection procurement to preempt accreditation penalties, particularly in ambulatory surgical centers where internal sterilization capacity remains limited.
- Peracetic Acid Chemistry Transition:Automated endoscope reprocessor manufacturers are accelerating formulation shifts away from glutaraldehyde, creating service contract renewal cycles tied to chemistry compatibility validation.
- Biosafety Level Containment Expansion:Academic and commercial laboratories in Germany, Japan, and Singapore are scaling high-containment research facilities, generating demand for specialized vapor-phase hydrogen peroxide decontamination services.
Market Restraints
- Capital Equipment Intensity:Automated washer-disinfector systems require substantial upfront investment, constraining service provider expansion into mid-sized clinic segments where equipment utilization rates cannot amortize deployment costs.
- Chemistry Supply Concentration:Peracetic acid precursor manufacturing clusters in the US Gulf Coast and Northwestern Europe expose service providers to feedstock disruption risks from regional weather events or energy price volatility.
- FDA 510(k) Validation Friction:Automated endoscope reprocessor clearance timelines create device-to-chemistry matching delays that extend service contract negotiation cycles and compress provider margin structures.
Strategic Opportunities
- India ASC Market Penetration:The country's expanding network of ambulatory surgical centers under Ayushman Bharat infrastructure programs offers first-mover positioning for outsourced sterilization services as domestic infection control standards professionalize.
- EU MDR Post-Market Surveillance Services:Disinfection equipment manufacturers selling into European member states now require ongoing clinical performance documentation, creating annuity revenue streams for validation and compliance monitoring specialists.
- Hydrogen Peroxide Vapor Robotics Convergence:Integration of autonomous mobile robots with room decontamination systems enables overnight terminal cleaning protocols in US and UK hospital systems seeking labor cost containment.
Industry Challenges
- Sterilization Engineering Talent Scarcity:Service providers face recruitment bottlenecks for professionals credentialed in both automated systems maintenance and EPA chemistry compliance, particularly in secondary US metropolitan markets.
- Legacy Device Integration Complexity:Hospitals with mixed fleets of FDA-cleared and pre-amendment endoscope reprocessors encounter chemistry compatibility conflicts that fragment service standardization and elevate training costs.
- Sporicidal Efficacy Testing Standardization Delays:Divergent EPA AOAC methods and emerging ISO alternatives create validation protocol uncertainty that extends service provider quality system implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Level Disinfection Services Market |
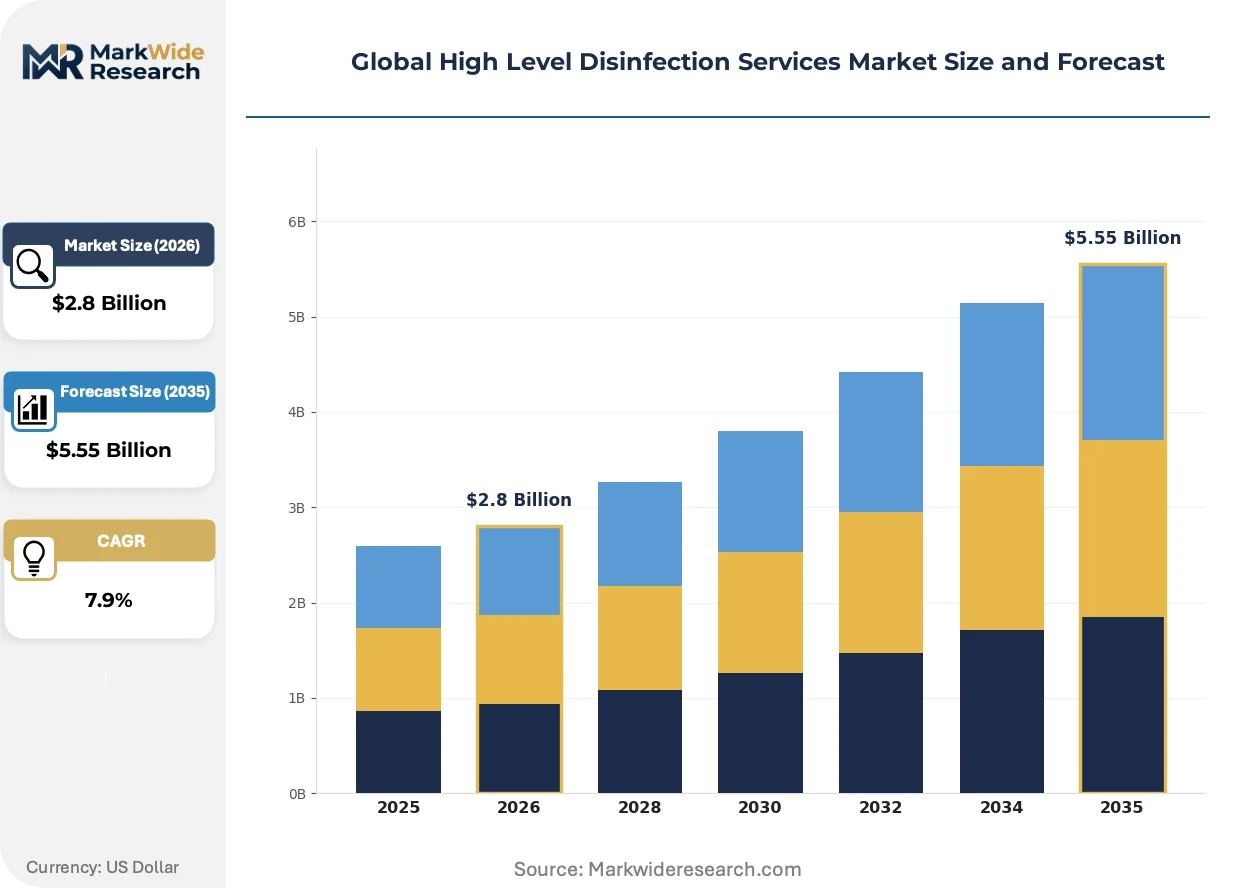
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Manual Disinfection, Automated Disinfection, Chemical Cleaning, Thermal Cleaning End User: Hospitals, Clinics, Laboratories, Dental Offices Technology: Ultraviolet, Ozone, Hydrogen Peroxide, Steam Application: Medical Equipment, Surgical Instruments, Environmental Surfaces, Patient Areas |
| Companies Covered | STERIS, Fortive, Getinge AB, Steelco S.p.A., Ecolab, GE Healthcare, Altapure, Olympus Corporation, Ruhof Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Level Disinfection Services Market Strategic Shifts & Innovations
Decontamination service delivery is pivoting from chemical-centric contracts toward integrated equipment-chemistry-compliance bundles that lock in multi-year hospital relationships. This structural shift is compressing standalone chemical supplier margins while elevating capital deployment requirements.
Peracetic acid-based formulations are converging with automated endoscope reprocessor platforms to deliver sub-ten-minute high-level disinfection cycles. US hospital systems with high endoscopy throughput are adopting these integrated systems most aggressively, replacing legacy glutaraldehyde protocols that require extended aeration periods. The chemistry-platform convergence is enabling same-day device turnaround economics that manual processing cannot match.
The EU Medical Device Regulation's post-market surveillance obligations are forcing disinfection equipment manufacturers to maintain continuous clinical performance documentation across European member states. German and French notified bodies are interpreting MDR technical file requirements most stringently, creating compliance cost divergence between premium and economy equipment tiers. Service providers with embedded regulatory affairs capabilities are capturing documentation outsourcing contracts from manufacturers lacking in-house surveillance infrastructure.
US ambulatory surgical centers are consolidating vendor relationships from multi-supplier chemical purchasing toward single-source service agreements bundling equipment, chemistry, and compliance reporting. This buyer concentration is displacing traditional distribution relationships where independent dealers previously supplied fragmented product categories. The ASC segment in Texas, Florida, and Arizona outpatient markets exhibits the most pronounced consolidation, driven by private equity-backed center rollups seeking procurement standardization.
Global High Level Disinfection Services Market Segmentation
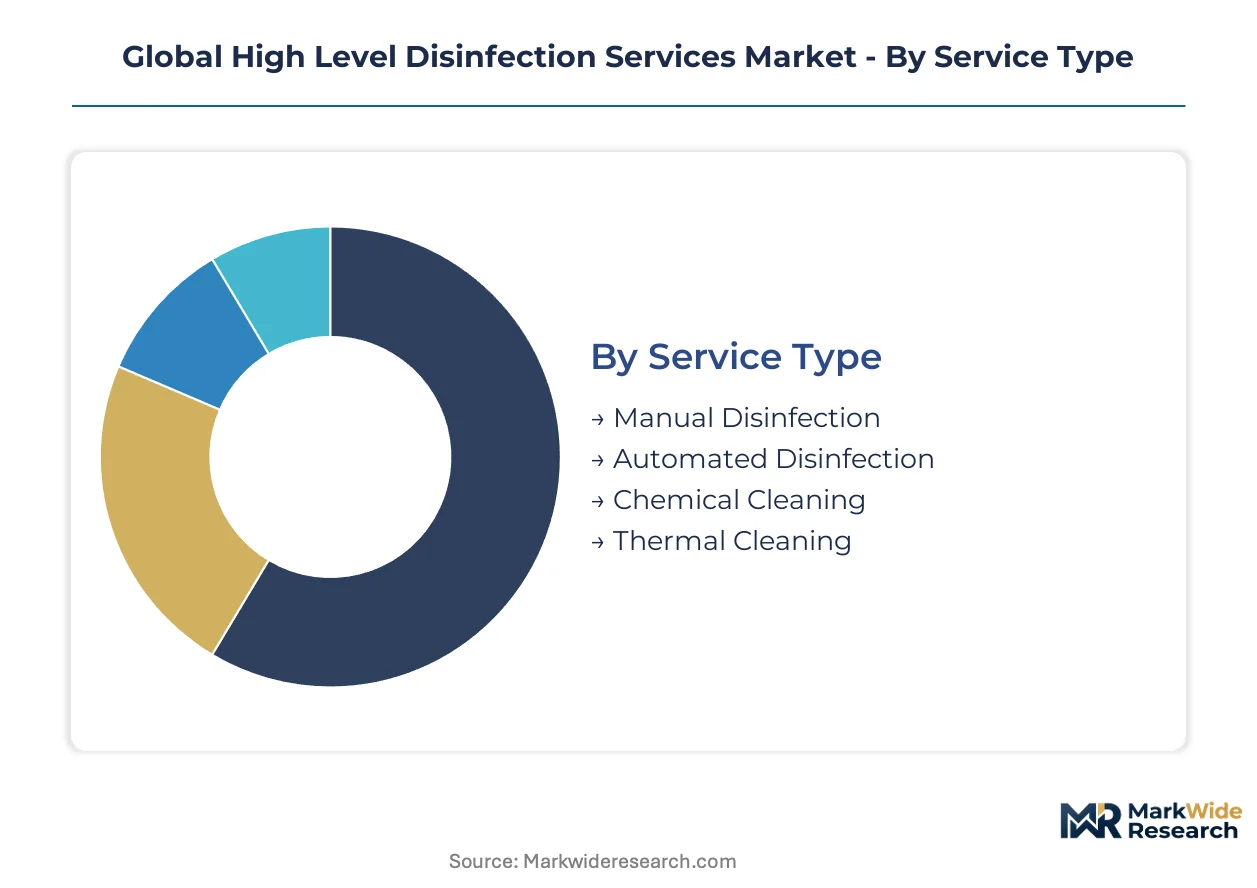
High level disinfection services fragment across four structural dimensions that determine procurement economics and vendor positioning. Service type and end-use concentration drive contract value, while technology choice and application scope dictate capital intensity and regulatory compliance burden.
Service Type:
Standalone disinfection services operate independently of hospital sterilization infrastructure, while embedded services integrate with automated washer-disinfector networks and chemistry supply systems.
- Automated Disinfection:Robotic endoscope reprocessors and vapor-phase hydrogen peroxide systems deliver sub-ten-minute cycle times with validated sporicidal kill logs. US hospital systems with high endoscopy throughput deploy these platforms most aggressively, replacing manual protocols that extend device turnaround.
- Manual Disinfection:Technician-performed chemical immersion remains prevalent in smaller clinics where surgical volume cannot justify capital equipment. Labor costs and EPA chemistry compliance training requirements constrain margin expansion for standalone service providers.
- Chemical Cleaning:Peracetic acid and glutaraldehyde formulations applied through immersion or wipe protocols dominate mid-sized ambulatory surgical center contracts.
- Thermal Cleaning:Steam and dry heat methods restricted to heat-tolerant instruments serve niche applications in dental and veterinary settings.
Automated Disinfection leads volumes today; Manual Disinfection is gaining share fastest among outsourced clinic procurement.
End User:
Customer scale determines contract structure, with large integrated delivery networks demanding bundled equipment-chemistry-compliance packages while independent facilities purchase discrete services.
- Hospitals:Academic medical centers and health systems with Joint Commission accreditation pressure drive the highest contract values. These buyers prioritize FDA 510(k) validated reprocessor compatibility and real-time compliance reporting dashboards.
- Laboratories:Biosafety level containment facilities in Germany, Japan, and Singapore generate specialized demand for vapor-phase hydrogen peroxide room decontamination. Research volume expansion and dual-use pathogen handling protocols are accelerating procurement.
- Clinics:Outpatient surgical centers in Texas, Florida, and Arizona exhibit pronounced vendor consolidation from multi-supplier chemical purchasing toward single-source agreements.
- Dental Offices:Smaller instrument volumes and lower regulatory scrutiny sustain price-competitive manual chemical service tiers.
Hospitals anchor revenue concentration; Laboratories are expanding most quickly as high-containment research scales.
Technology:
Technology selection tracks capital availability and cycle time requirements, with chemistry-based methods dominating device reprocessing and energy-intensive approaches reserved for terminal room decontamination.
- Hydrogen Peroxide:Vapor-phase and plasma systems achieve sporicidal efficacy in unoccupied spaces without residue concerns. UK and US hospital systems deploy these for overnight terminal cleaning protocols integrated with autonomous mobile robots.
- Peracetic Acid:Liquid formulations in automated endoscope reprocessors displace glutaraldehyde through faster cycle times and reduced aeration requirements. Chemistry-platform convergence is recalibrating service contract renewal economics.
- Ultraviolet:UV-C tower and upper-room systems supplement manual cleaning in patient areas with moderate pathogen load.
- Ozone:Gaseous decontamination for water-sensitive equipment remains limited by material compatibility constraints and extended aeration protocols.
Hydrogen Peroxide dominates capital-intensive installations; Peracetic Acid formulations are climbing the fastest as chemistry transitions accelerate.
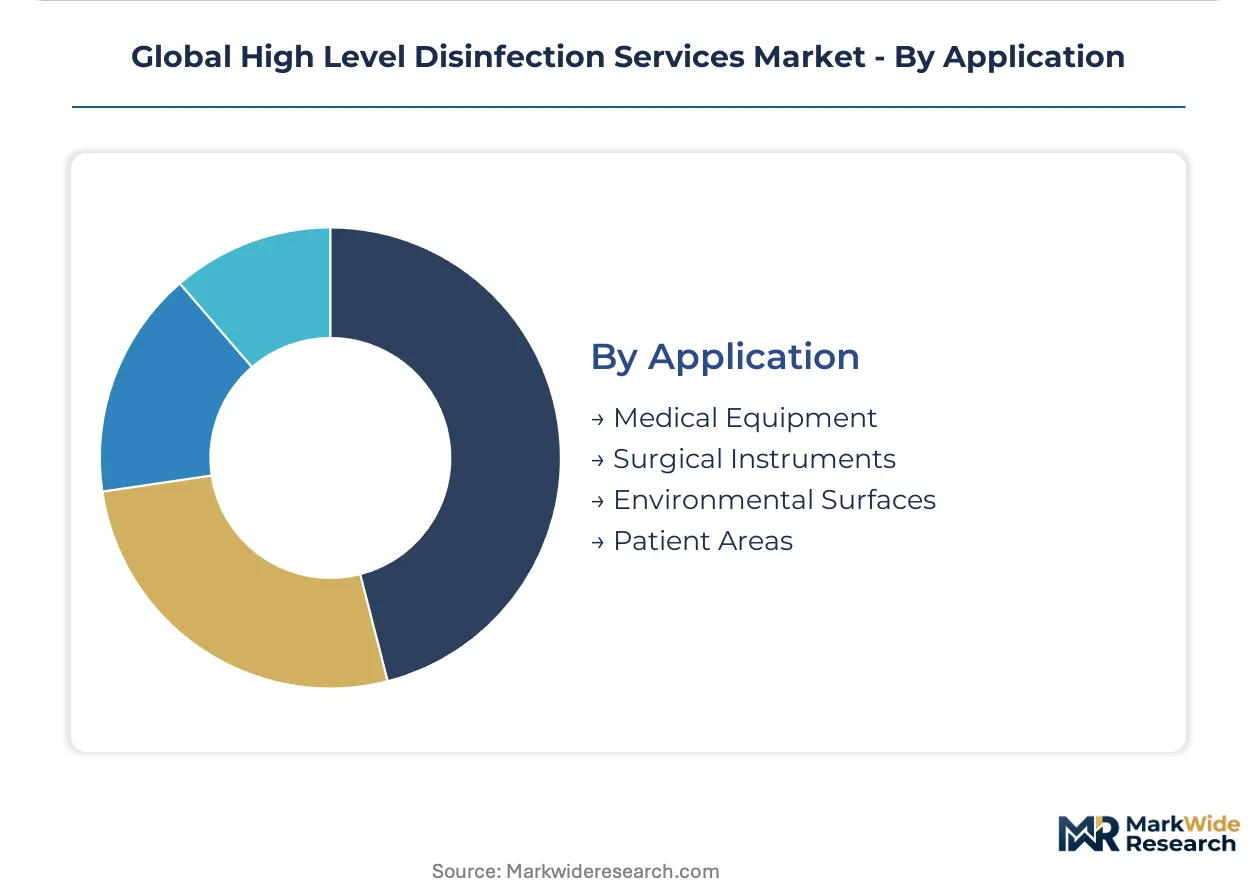
Application:
Application scope determines regulatory stringency, with invasive device reprocessing subject to FDA device-level clearance while environmental surface protocols follow EPA registration requirements.
- Surgical Instruments:Semi-critical devices requiring high-level disinfection between patients drive the most stringent validation protocols. Automated washer-disinfector chemistry compatibility matrices and FDA 510(k) reprocessor clearances shape service provider capabilities.
- Medical Equipment:Endoscopes, ultrasound probes, and tonometer tips present complex luminal geometries demanding automated reprocessor platforms with validated flow dynamics.
- Environmental Surfaces:Terminal cleaning of operating rooms and isolation wards employs hydrogen peroxide vapor or UV-C systems with occupancy sensing controls.
- Patient Areas:High-touch surface disinfection in general medical wards sustains manual chemical wipe service tiers with lower capital barriers.
Surgical Instruments commands the largest contract values; Environmental Surfaces shows the steepest expansion trajectory as terminal cleaning protocols professionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida ambulatory surgical centers anchor North American demand concentration for outsourced sterilization services. German biosafety laboratories and Singapore research facilities drive specialized vapor-phase decontamination procurement. Japanese hospital systems and Indian Ayushman Bharat infrastructure programs reshape Asia-Pacific service delivery models.
United States
Joint Commission inspection intensification drives hospital procurement of bundled equipment-chemistry-compliance contracts. EPA sporicidal efficacy standards compress service provider certification timelines and elevate capital requirements. Texas, Florida, and Arizona outpatient markets exhibit pronounced vendor consolidation as private equity-backed center rollups seek procurement standardization.
Germany
Biosafety level containment expansion in academic and commercial laboratories generates specialized demand for hydrogen peroxide vapor decontamination. EU Medical Device Regulation post-market surveillance obligations force equipment manufacturers to maintain continuous clinical performance documentation. Notified bodies in Berlin and Munich interpret MDR technical file requirements most stringently, creating compliance cost divergence between equipment tiers.
Singapore
High-containment research facility scaling accelerates procurement of vapor-phase hydrogen peroxide room decontamination services. The country's national biomedical regulator enforces strict dual-use pathogen handling protocols. One-North and Tuas biomedical clusters concentrate specialized service provider capabilities for BSL-3 and BSL-4 containment environments.
Japan
Surgical volume rebound and hospital accreditation pressure drive automated endoscope reprocessor deployment. METI guidelines shape domestic equipment validation protocols and chemistry registration requirements. Tokyo and Osaka metropolitan hospital systems prioritize same-day device turnaround economics that peracetic acid platforms enable.
India
Ayushman Bharat infrastructure programs expand the ambulatory surgical center network, creating first-mover positioning for outsourced sterilization services. CDSCO medical device regulations professionalize domestic infection control standards. Mumbai, Delhi-NCR, and Bangalore clusters concentrate private hospital chain procurement as accreditation requirements tighten.
Global High Level Disinfection Services Market Key Industry Players
Global majors compete with regional champions across chemistry supply and equipment validation capabilities. The market structure tilts toward integrated bundling, with standalone chemical suppliers facing margin compression as hospitals consolidate vendor relationships. Three archetypes dominate: captive chemistry manufacturers with equipment platforms, pure-play service contractors with compliance specialization, and diversified hygiene conglomerates with chemical density advantages. M&A activity targets regional service contractors with EPA validation infrastructure, while strategic partnerships between equipment makers and chemistry suppliers lock in multi-year hospital accounts.
Among North American-anchored providers, STERIS and Ecolab occupy positions reflecting distinct strategic vectors. STERIS exemplifies the captive chemistry archetype through in-house peracetic acid supply integration. Ecolab represents chemical service density specialization, embedding dosing infrastructure and compliance reporting into long-term agreements. Getinge AB anchors European market presence through integrated washer-disinfector and chemistry bundling, reflecting the equipment-platform convergence strategy that automated endoscope reprocessor manufacturers pursue.
| Leading Market Players |
|---|
| STERIS |
| Fortive |
| Getinge AB |
| Steelco S.p.A. |
| Ecolab |
| GE Healthcare |
| Altapure |
| Olympus Corporation |
| Ruhof Corporation |
| Others |
Cost & Logistics Intelligence
Peracetic acid precursor feedstock indices on the US Gulf Coast cascade through contract renegotiation cycles into three-tier pricing structures across premium, standard, and economy service tiers. Hospital procurement committees in Texas and Florida exploit this concentration to extract volume discounts from providers lacking captive chemistry supply.
Pricing Analysis
Input-cost pass-through from acetic acid and hydrogen peroxide feedstocks governs contract escalation clauses in multi-year service agreements. Pricing stratifies across premium, standard, and economy tiers based on EPA sporicidal certification grade and real-time compliance reporting dashboard inclusion. Cost compression in the manual disinfection tier is intensifying because mid-sized clinics consolidate vendor relationships. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with Joint Commission pressure accept premium tier pricing for validated automation platforms.
Supply Chain Analysis
Peracetic acid precursor manufacturing rests on specialty chemical producers clustered in the US Gulf Coast and Northwestern Europe, with secondary capacity in Japan. Key inputs include acetic acid, hydrogen peroxide, and stabilized surfactant formulations. Single-source vulnerability concentrates around Gulf Coast petrochemical complexes exposed to hurricane disruption. Distribution runs through integrated equipment-chemistry bundling direct to hospital systems, bypassing traditional independent dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
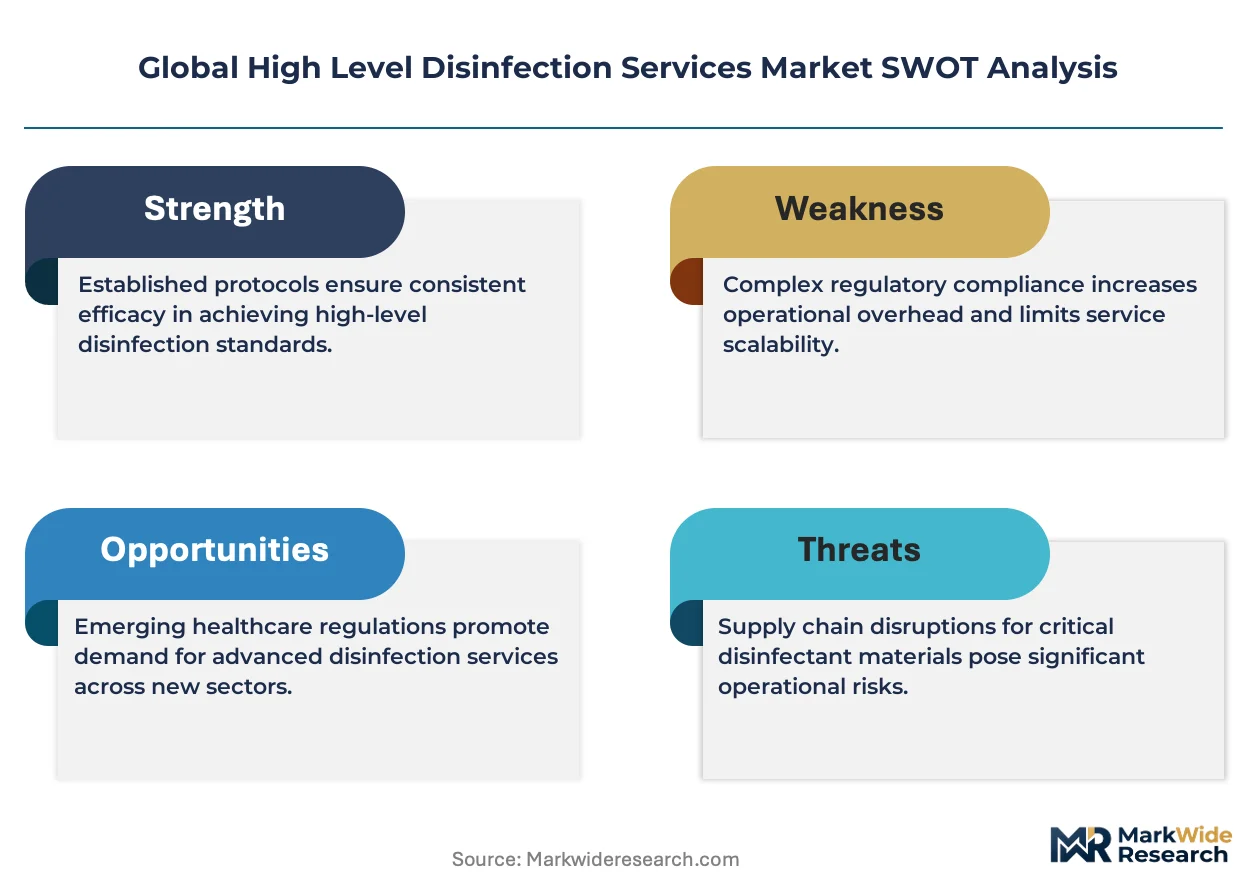
The Global High Level Disinfection Services Market operates as a stable compounder anchored by irreversible regulatory ratchets on sporicidal efficacy standards that perpetually reset compliance baselines upward.
For Market Incumbents: Deploy captive peracetic acid supply as a lock-in mechanism against standalone chemical suppliers. Deepen backward integration into precursor manufacturing to insulate margin structures from Gulf Coast feedstock volatility. Fortify EPA validation infrastructure as a competitive moat against emerging regional contractors lacking chemistry-platform convergence capabilities. For New Entrants and Emerging Players: Launch via outsourced sterilization service contracts targeting India's Ayushman Bharat ambulatory surgical center expansion. Penetrate the laboratory vapor-phase decontamination segment in Singapore and Germany where biosafety level containment scaling outpaces incumbent service density. Lead with autonomous mobile robot integration for overnight terminal cleaning protocols in UK and US hospital systems seeking labor cost containment. For Investors and Strategic Acquirers: Asymmetric upside sits with regional service contractors possessing EPA chemistry validation infrastructure and established hospital system relationships. The five-to-ten-year viability window favors platforms with integrated equipment-chemistry-compliance bundling capabilities. Watch for FDA 510(k) clearance timeline compression as the inflection signal indicating accelerated contract renewal velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chemistry-Platform Convergence | Peracetic acid integration with automated reprocessors compresses cycle times below ten minutes for same-day device turnaround. |
| Regulatory Affairs Capability Buildout | EU MDR post-market surveillance documentation services capture annuity revenue streams from equipment manufacturers lacking in-house infrastructure. |
| Autonomous Mobile Robot Integration | Overnight terminal cleaning protocols in US and UK hospital systems reduce labor costs while maintaining Joint Commission compliance. |
| India ASC Market Entry | Ayushman Bharat infrastructure expansion creates first-mover positioning as domestic infection control standards professionalize under CDSCO oversight. |
| Captive Precursor Manufacturing | In-house peracetic acid production insulates margin structures from Gulf Coast feedstock disruption and energy price volatility. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital sterilization directors, biomedical engineers, EPA compliance officers, GPO contracts managers, and automated reprocessor manufacturer product managers with secondary validation against FDA 510(k) filings, EPA disinfectant registration databases, hospital procurement contract repositories, and EU MDR technical file submissions. Bottom-up service provider revenue aggregation and top-down end-use spending allocation were triangulated against chemistry consumption estimates.
The forecast window anchored historical reference periods to surgical volume rebound trajectories and Joint Commission inspection frequency intensification across the projection horizon. Segmentation dimensions modeled include service type, end user scale tier, technology platform, and application scope with chemistry-platform convergence velocity as an industry-specific dimension. CAGRs were derived from equipment installation base expansion rates and contract renewal pricing dynamics, incorporating automated endoscope reprocessor deployment curves and biosafety level facility construction pipelines as forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen EPA chemistry registration revocations, catastrophic Gulf Coast petrochemical disruption, and rapid glutaraldehyde resurgence through novel formulation advances. Forecasts reflect documented assumptions on regulatory timeline stability and surgical volume continuity. A small set of named triggers warrants ongoing watch: FDA 510(k) clearance acceleration, EU MDR notified body capacity constraints, and autonomous robot decontamination efficacy validation completion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Medical Disinfectant Wipes Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Alcohol Wipes Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
Antiseptic Bathing Market
Infection Control
Sterilization Technologies Market
Infection Control
Europe Hospital-Acquired Infection Diagnostics Market
Infection Control
Point of Care Infection Control Market