
 Middle East and Africa Hand Sanitizer Market | 2026-2036
Middle East and Africa Hand Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hand Sanitizer Market Foresight
Pharmacy distribution networks across the Middle East and Africa are reshaping how hand sanitizer reaches end users, with institutional buyers now bypassing traditional wholesale layers. Reckitt Benckiser Group PLC leverages its pan-African logistics infrastructure to sustain shelf presence in fragmented retail environments. The Procter & Gamble Company competes through concentrated brand equity in Gulf Cooperation Council markets. Clicks Group anchors supply continuity across Southern Africa's pharmacy chains.
Hand sanitizer comprises alcohol-based or non-alcohol topical antiseptic formulations, typically containing ethanol or isopropanol at concentrations between 60% and 95%, manufactured through compounding, filtration, and sterile filling processes designed to reduce microbial load on skin surfaces. Gel formulations dominate volume throughput across hospital procurement channels due to controlled dispensing and reduced spillage. Foam variants capture premium positioning in hospitality settings where user experience drives selection criteria. Spray formats occupy niche demand within education and residential segments where rapid coverage of large surface areas matters.
South Africa's Health Products Regulatory Authority and Saudi Arabia's Food and Drug Authority enforce divergent efficacy labeling requirements, compelling manufacturers to maintain multiple formulation dossiers. Nigeria's National Agency for Food and Drug Administration and Control imposes import registration protocols that extend market access timelines for new entrants. Stakeholders must monitor regulatory harmonization initiatives between Gulf and sub-Saharan jurisdictions to optimize portfolio deployment.
Market Dynamics
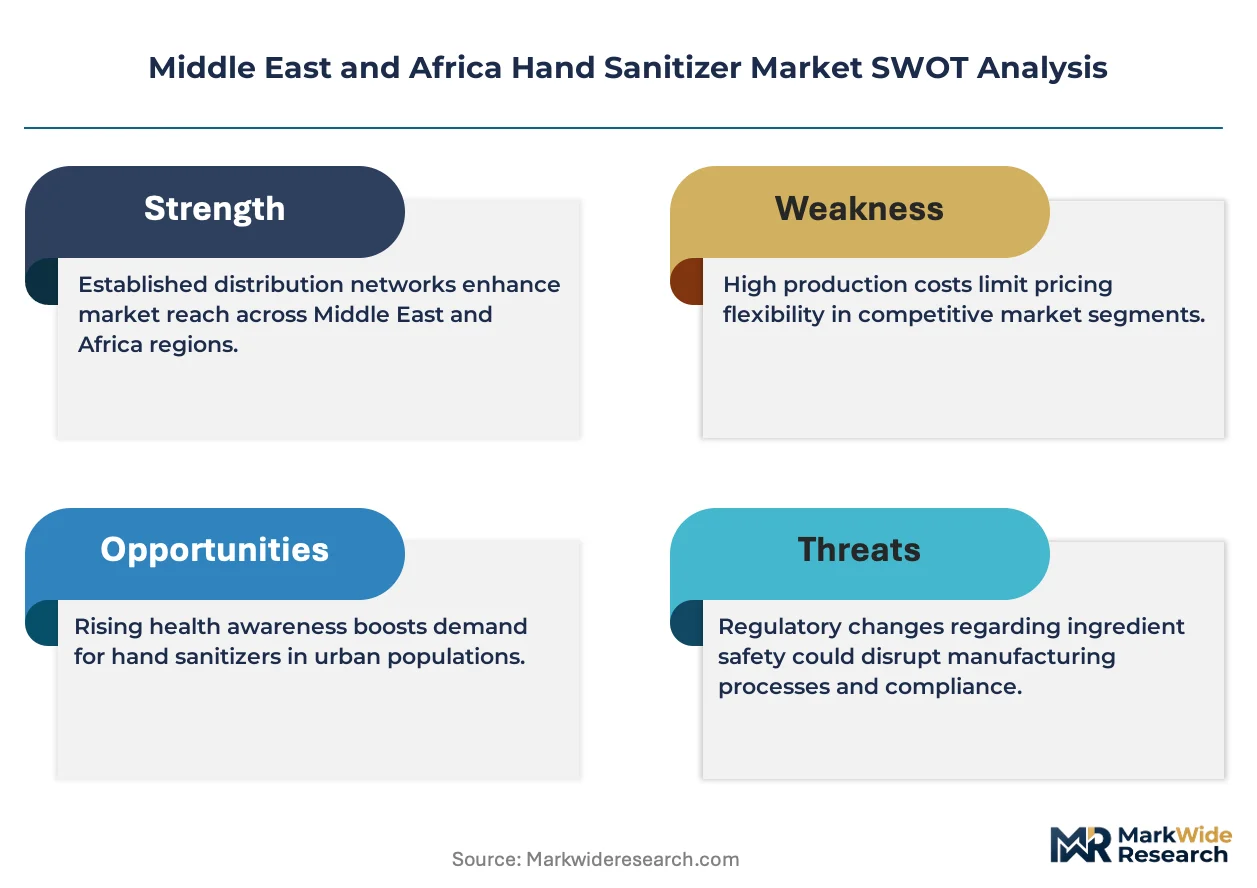
Hospital procurement consolidation across the Gulf Cooperation Council is compressing supplier margins while elevating compliance requirements for alcohol concentration verification and sterile manufacturing documentation.
Growth Catalysts
- SFDA efficacy mandates:Saudi Arabia's Food and Drug Authority now requires real-time stability testing for alcohol-based formulations, accelerating facility upgrades among domestic compounders.
- Urban hospital networks:Nigeria's Lagos and Abuja clinic chains are standardizing hand hygiene protocols across 200-plus facilities, creating predictable demand for bulk gel formats.
- Ethanol feedstock localization:South Africa's sugarcane-to-ethanol conversion infrastructure is reducing import dependency for active pharmaceutical ingredients.
Market Restraints
- Isopropanol price volatility:Feedstock costs for non-alcohol alternatives fluctuate with crude oil derivatives, squeezing margin predictability for foam formulation specialists.
- Import registration timelines:Nigeria's National Agency for Food and Drug Administration and Control extends market access by 14-18 months for new entrants lacking local manufacturing partnerships.
- Water-scarce sterile filling:Desert climate regions face 40% higher utility costs for USP-grade water generation in compounding facilities.
Strategic Opportunities
- East African clinic expansion:Kenya and Ethiopia's primary care networks remain underpenetrated by branded sanitizer suppliers, offering first-mover positioning for WHO-prequalified manufacturers.
- MOHAP green procurement:Dubai's Ministry of Health and Prevention is piloting biodegradable packaging mandates for institutional tenders, rewarding early formulation adapters.
- Direct-to-hospital e-procurement:Digital tender platforms are bypassing wholesale layers in South Africa's public health sector, enabling margin recovery for compliant suppliers.
Industry Challenges
- Sterile validation expertise:Gulf-based manufacturers face acute shortages of personnel trained in EU GMP Annex 1 environmental monitoring protocols.
- Multi-jurisdiction dossier maintenance:Divergent labeling requirements between South Africa's Health Products Regulatory Authority and Saudi Arabia's Food and Drug Authority force parallel documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hand Sanitizer Market |
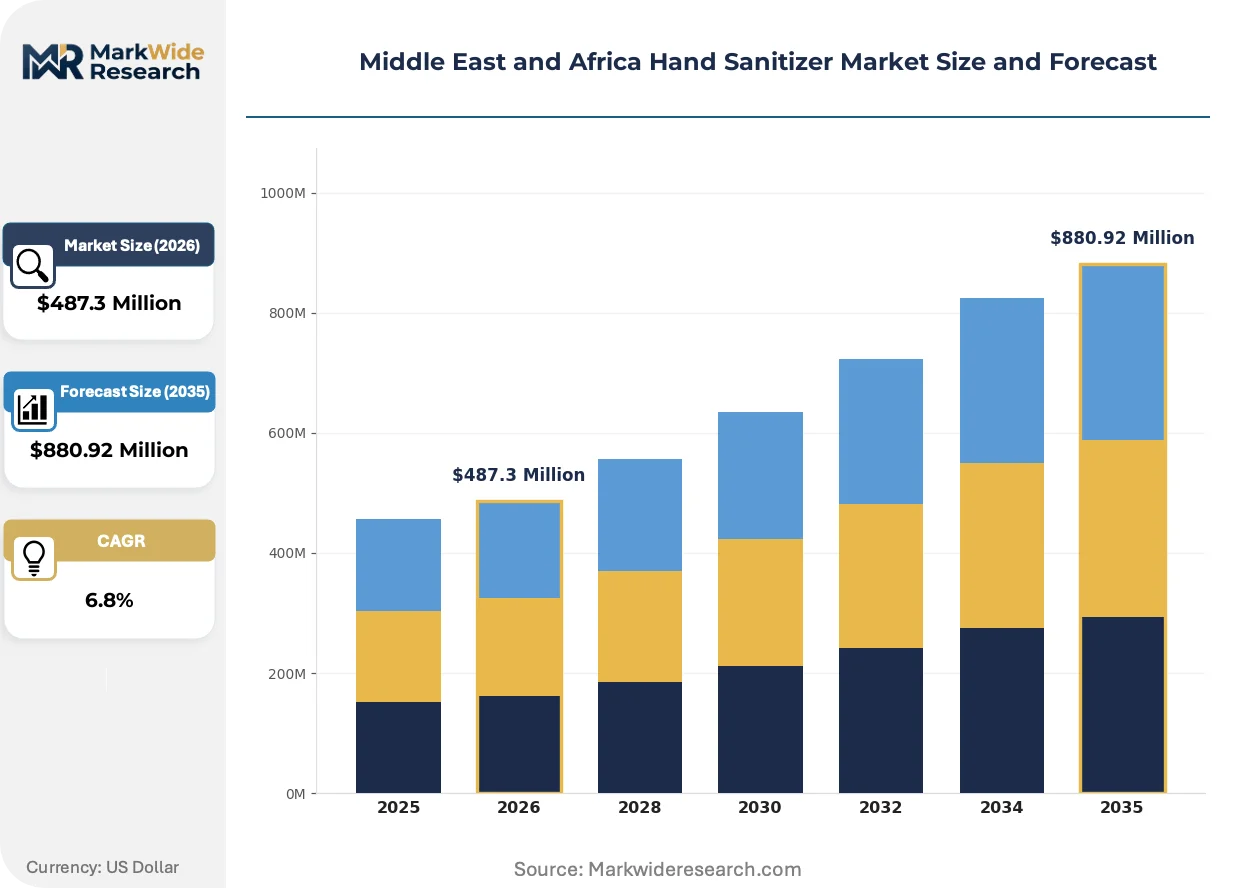
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Spray, Wipes Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores End User: Healthcare, Hospitality, Education, Residential Packaging Type: Refillable, Travel Size, Bulk, Pump Bottle |
| Companies Covered | Reckitt Benckiser Group PLC, Unilever PLC, S. C. Johnson & Son, The Procter & Gamble Company, 3M Company, Clicks Group, The Cape Town Toiletry Co., GOJO Industries, Himalaya Drug Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hand Sanitizer Market Shifts & Advancements
Formulation chemistry and distribution architecture are undergoing parallel transformation as institutional buyers demand verified efficacy alongside supply chain transparency.
Quaternary ammonium compound blends with residual activity claims are rendering obsolete single-application alcohol gels in food processing and hospitality settings. UAE-based hotel chains are adopting these formulations for back-of-house protocols. The shift is compressing reorder frequency and altering inventory management assumptions for procurement officers.
REACH-aligned substance restrictions are propagating through Gulf supply chains as Saudi Arabia and UAE regulators harmonize with EU chemical safety frameworks. Manufacturers must now submit extended safety data sheets for fragrance additives and dye components. Premium positioning now requires explicit non-allergen certification from third-party laboratories.
Consolidated tendering by hospital group purchasing organizations is fragmenting the wholesale intermediary layer across Southern Africa. Clicks Group and independent pharmacy chains are building captive logistics networks to serve clinic clusters directly. Kenya's public sector procurement reforms are mirroring this disintermediation pattern in East Africa.
Middle East and Africa Hand Sanitizer Market Segmentation
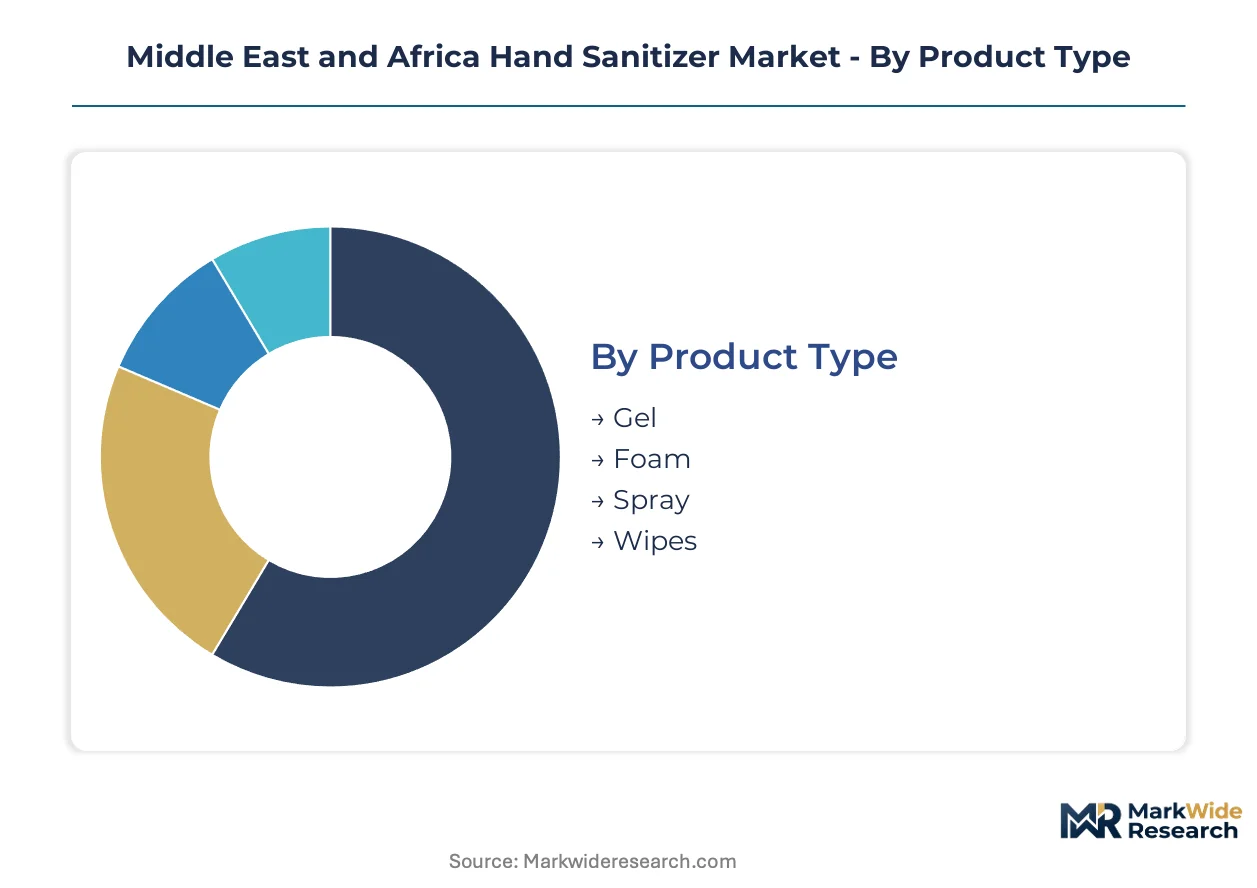
Hand sanitizer procurement patterns across the Middle East and Africa diverge sharply by setting and scale. Hospital buyers prioritize bulk formats with sterile documentation while hospitality and education sectors optimize for user experience and rapid deployment.
Product Type:
Use-case spectrum spans controlled clinical environments through mobile consumer applications.
- Gel:Viscous ethanol or isopropanol formulations between 60% and 95% concentration enable measured dispensing and reduced drip loss. Hospital procurement across South Africa's public health networks and Nigeria's urban clinic chains concentrates here due to compliance with WHO hand hygiene protocols and compatibility with wall-mounted dispensers.
- Foam:Aerated formulations using quaternary ammonium compounds or alcohol blends deliver expanded coverage per unit volume. Premium hospitality settings in Dubai and Riyadh favor foam for back-of-house protocols where rapid application frequency and skin tolerance drive selection.
- Spray:Aerosol or pump-dispersed fine mist formats suit rapid coverage of large surface areas and shared equipment.
- Wipes:Pre-saturated towelettes in sachet or canister formats target education and travel segments where water access is limited.
Established volume favors gel; emerging adoption favors foam.
Distribution Channel:
Cost tier separation distinguishes institutional procurement from fragmented retail access.
- Pharmacies:Regulated channel with mandatory SAHPRA or NAFDAC registration documentation. Clicks Group and independent chains across Southern Africa anchor supply continuity for clinical-grade formulations requiring cold chain or stability verification.
- Online Retail:Direct-to-consumer and B2B platforms are compressing wholesale layers in South Africa's public sector. E-procurement portals enable compliant suppliers to recover margins previously captured by intermediaries.
- Supermarkets:Mass retail presence for household and small commercial buyers.
- Convenience Stores:Impulse and emergency purchase locations in high-traffic urban zones.
Pharmacy networks dominate institutional volume; online channels are gaining share fastest in public sector reform environments.
End User:
Application severity dictates formulation specification and compliance documentation requirements.
- Healthcare:Surgical and clinical hand antisepsis requiring alcohol concentrations above 70% with real-time stability testing per SFDA mandates. Procurement consolidation across Gulf Cooperation Council hospital networks is elevating sterile manufacturing documentation requirements.
- Hospitality:Food service and guest contact protocols favor residual-activity quaternary ammonium blends over single-application alcohol gels in UAE hotel chains.
- Education:School and university procurement emphasizes rapid-coverage formats for shared equipment and high-touch surfaces.
- Residential:Household consumption concentrated in pump bottle and travel-size formats.
Healthcare commands specification intensity; hospitality is displacing alcohol gels fastest with residual-activity alternatives.
Packaging Type:
Volume scale and mobility requirements segment container engineering priorities.
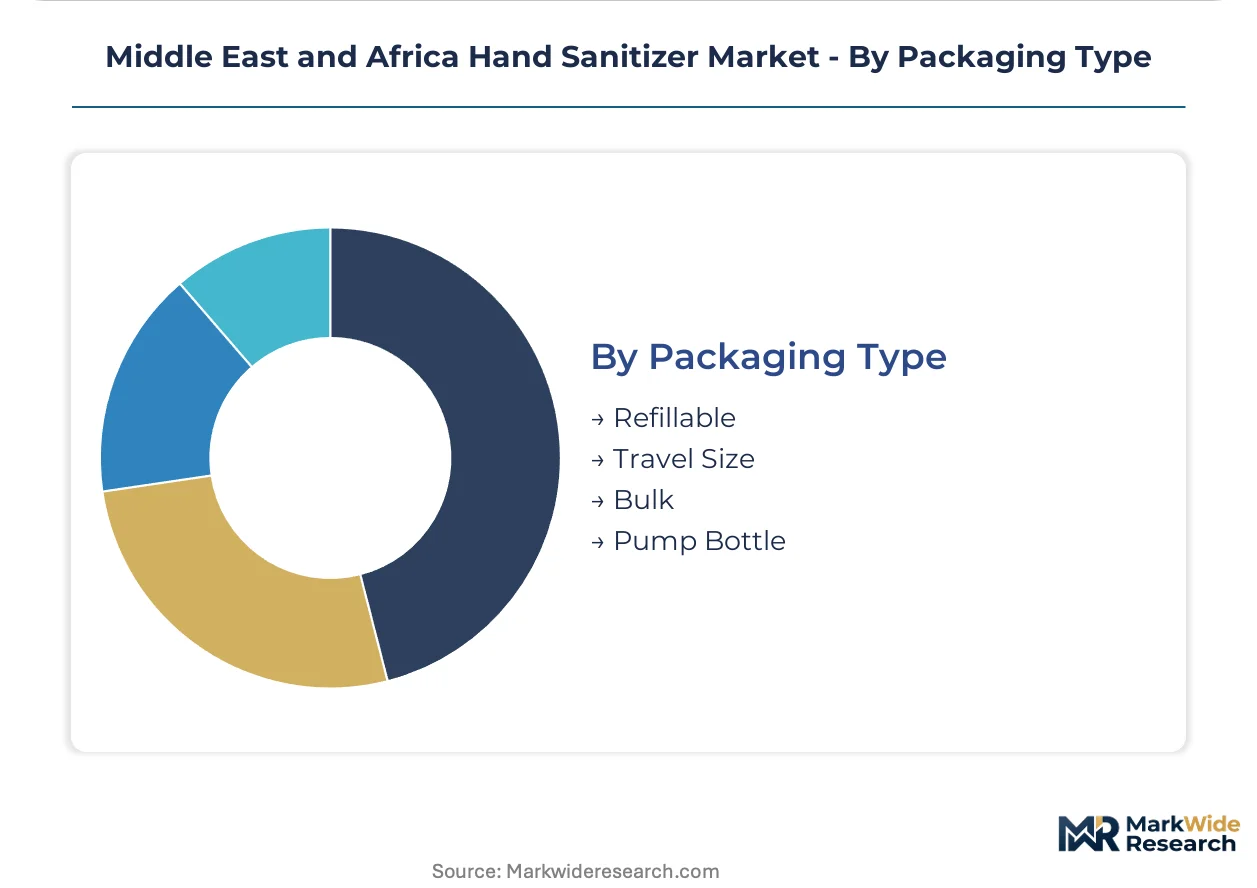
- Bulk:Five-liter and larger containers for hospital and food processing central fill stations. Procurement officers in Lagos and Abuja clinic chains standardize on bulk gel for 200-plus facility networks.
- Pump Bottle:Countertop and wall-mounted dispensers for clinical stations and hospitality checkpoints.
- Refillable:Cartridge systems reducing plastic waste per MOHAP green procurement pilots in Dubai institutional tenders.
- Travel Size:Sub-100ml containers for aviation-compliant personal carriage and field medical kits.
Bulk formats anchor hospital procurement; refillable systems align with emerging sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Port in Dubai anchors distribution capacity for hand sanitizer feedstocks entering Gulf markets. South Africa's Durban-Gauteng logistics corridor channels ethanol from KwaZulu-Natal sugarcane belt to compounding facilities. Nigeria's Apapa port complex handles bulk isopropanol imports for Lagos manufacturing clusters.
Saudi Arabia
SFDA mandates real-time stability testing for alcohol-based formulations, accelerating facility upgrades among domestic compounders. Riyadh's King Salman Medical City and Jeddah hospital networks are consolidating procurement through centralized tender platforms. Eastern Province manufacturing zones near Jubail Industrial City are attracting ethanol-to-sanitizer conversion investments.
United Arab Emirates
MOHAP green procurement pilots in Dubai are mandating biodegradable packaging for institutional tenders. Abu Dhabi's SEHA hospital group is standardizing quaternary ammonium foam protocols across 40-plus facilities. Sharjah's Hamriyah Free Zone is emerging as a sterile filling hub serving GCC export markets.
South Africa
SAHPRA enforces stringent efficacy standards for topical antiseptics that elevate documentation burdens for importers. Clicks Group and independent pharmacy chains are building captive logistics networks to serve clinic clusters directly. KwaZulu-Natal's sugarcane-to-ethanol infrastructure is reducing import dependency for active pharmaceutical ingredients.
Nigeria
NAFDAC import registration protocols extend market access timelines by 14-18 months for new entrants lacking local partnerships. Lagos and Abuja clinic chains are standardizing hand hygiene protocols across 200-plus facilities. Apapa port throughput constraints are forcing procurement officers to pre-position bulk inventory six months ahead of demand.
Kenya
Public sector procurement reforms are disintermediating wholesale layers through digital tender platforms. Nairobi's hospital networks remain underpenetrated by branded sanitizer suppliers. Mombasa port modernization is shortening customs clearance cycles for ethanol imports from regional trade partners.
Middle East and Africa Hand Sanitizer Market Competitive Landscape
On the supply side, the industry is bifurcated between multinational consumer goods conglomerates and regional pharmacy distributors. Gulf Cooperation Council procurement consolidation is compressing supplier margins while elevating compliance requirements. Three archetypes dominate: pan-African logistics operators, Gulf-based sterile compounders, and Southern African retail pharmacy chains. Competitive moves center on direct-to-hospital e-procurement bypasses and captive ethanol feedstock integration.
Within the multinational tier, Reckitt Benckiser Group PLC and The Procter & Gamble Company exemplify divergent geographic positioning. Reckitt Benckiser leverages pan-African logistics infrastructure to sustain shelf presence in fragmented retail environments. Procter & Gamble competes through concentrated brand equity in Gulf Cooperation Council markets. Clicks Group anchors supply continuity across Southern Africa's pharmacy chains, representing the regional distributor archetype.
| Leading Market Players |
|---|
| Reckitt Benckiser Group PLC |
| Unilever PLC |
| S. C. Johnson & Son |
| The Procter & Gamble Company |
| 3M Company |
| Clicks Group |
| The Cape Town Toiletry Co. |
| GOJO Industries |
| Himalaya Drug Company |
| Others |
Supply & Pricing Matrix
NAFDAC's 14-18 month import registration timeline compresses pricing power for non-local manufacturers while elevating procurement premiums for domestic compounders. This regulatory chokepoint forces tiered margin structures across Gulf and sub-Saharan supply corridors, with hospital buyers absorbing compliance premiums and retail channels facing spot-price volatility.
Pricing Analysis
Volume-discount tiering separates WHO-prequalified institutional supply from fragmented retail access, with bulk gel contracts commanding 40-60% unit cost advantages over pharmacy shelf formats. Price differentiation hinges on SFDA real-time stability certification and captive ethanol integration in South Africa's KwaZulu-Natal belt. Pricing pressure intensifies as Gulf hospital procurement consolidation squeezes supplier margins through centralized tender platforms. Healthcare procurement officers exhibit lowest price sensitivity due to compliance mandates, while convenience store channels face acute margin compression.
Supply Chain Analysis
Upstream ethanol feedstock draws from South Africa's sugarcane belt, Saudi Arabia's Jubail petrochemical corridors, and Nigerian isopropanol imports through Apapa port. Raw material dependencies center on USP-grade water generation, quaternary ammonium compound imports, and sterile filling equipment. Single-source vulnerability concentrates in Gulf-based sterile validation expertise for EU GMP Annex 1 protocols. Distribution runs through Jebel Ali Port's hub-and-spoke architecture serving GCC markets, with Durban-Gauteng corridors anchoring Southern African logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic-era inventory destocking cyclicality, with institutional procurement normalization driving demand predictability across hospital networks. The cyclical driver is Gulf Cooperation Council healthcare infrastructure expansion accelerating tender pipeline visibility.
For Market Incumbents: Insulate margin positions through captive ethanol integration in KwaZulu-Natal and Sharjah free zone sterile filling capacity. Defend against disintermediation by embedding directly into South Africa's e-procurement portals and SEHA's centralized tender platforms. Prioritize MOHAP biodegradable packaging certification to capture Dubai institutional premium tiers. For New Entrants and Emerging Players: Build out presence in Kenya's underpenetrated primary care networks and Ethiopia's clinic expansion corridors before branded suppliers establish procurement relationships. Target East African digital tender platforms as the most penetrable channel given public sector procurement reforms. Anchor go-to-market strategy through WHO prequalification status enabling hospital system access. For Investors and Strategic Acquirers: SFDA's real-time stability testing mandate reshapes the acquisition landscape toward domestic Gulf compounders with upgraded facilities. Long-term viability centers on regulatory compliance infrastructure rather than brand equity alone. Acquisition target archetype: mid-scale sterile manufacturers with existing SAHPRA or NAFDAC dossiers and captive logistics networks. Signal to watch: harmonization initiatives between Gulf and sub-Saharan regulatory frameworks accelerating cross-border portfolio deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ethanol Integration | KwaZulu-Natal sugarcane-to-ethanol conversion reduces import dependency for South African compounders. |
| SFDA Stability Certification Investment | Real-time testing capability unlocks Riyadh and Jeddah hospital network procurement consolidation. |
| Direct-to-Hospital E-Procurement | Digital tender platforms bypass wholesale layers in South Africa's public health sector reform. |
| WHO Prequalification Pathway | Hospital system access across Kenya and Ethiopia requires verified efficacy documentation. |
| Biodegradable Packaging Transition | MOHAP green procurement pilots in Dubai reward early formulation adapters with tender preference. |
Research Methodology
Desk research of customs trade databases, pharmaceutical regulatory filings, and hospital procurement records preceded structured interviews with pharmacy chain procurement directors, sterile manufacturing facility managers, and Gulf hospital GPO contract specialists. Secondary validation drew from SAHPRA registration databases, NAFDAC import protocols, and SFDA facility inspection reports. Bottom-up volume estimates triangulated against top-down healthcare expenditure allocations across the analysis window.
Assumptions held regulatory framework stability and feedstock price corridors within observed bands, while demand elasticity and competitive entry timing were varied across scenarios. Segmentation modeling spanned product formulation, packaging format, distribution channel, and end-use setting dimensions. CAGRs were derived from regression-weighted historical procurement trajectories and facility capacity expansion pipelines, with ethanol localization rates and hospital network standardization timelines as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Jubail-based petrochemical entrants or accelerated NAFDAC local manufacturing partnerships would shift outcomes. Cross-checking against Gulf hospital GPO contract award databases and South African public tender disclosure records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Healthcare Protective Masks Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Global Infection Prevention Devices Market
Infection Control
Global Disinfection Robots Market
Infection Control
Sterilization Technologies Market
Infection Control
Surgical Site Infection Control Market
Infection Control
Ear Infection Treatment Market
Infection Control
Intra Abdominal Infection Market
Infection Control
Yeast Infection Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Perianal Infection Treatment Market
Infection Control
Europe Hospital-Acquired Infection Diagnostics Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Community Acquired Pneumonia (CAP) Market