
 Denture Disinfectants Market | 2026-2036
Denture Disinfectants Market Size, Share, and Industry Trends Forecast 2026-2036
Denture Disinfectants Market Analysis
European chemical manufacturers are rebalancing supply chains toward chlorhexidine and hydrogen peroxide precursors after raw material constraints disrupted tablet production. GlaxoSmithKline plc leverages its pharmaceutical heritage to sustain premium positioning in alcohol-based formulations. Colgate-Palmolive Company anchors mass-market penetration through retail pharmacy networks across North America. Dentsply Sirona Inc. specializes in professional-grade disinfectants distributed through dental supply channels.
Denture disinfectants are antimicrobial formulations designed to eliminate biofilm, fungi, and bacteria from removable dental prostheses, typically containing active ingredients at concentrations between 0.12% and 3.6% depending on the target pathogen spectrum. Their primary purpose is preventing stomatitis and cross-contamination in both clinical and home settings. Tablet formulations dominate unit volume due to convenience and dosing precision, while liquid solutions command higher margins in dental clinic procurement. Hydrogen peroxide-based formulations represent the fastest-expanding segment as clinicians shift away from alcohol-based products that degrade acrylic denture bases.
The FDA regulates denture disinfectants as antimicrobial devices under 21 CFR 872.6730, requiring substantiated efficacy claims against Candida albicans and Staphylococcus aureus. The EPA additionally oversees environmental release profiles for active ingredients like chlorhexidine gluconate. ISO 23317 standards for dental materials further constrain formulation chemistry and biocompatibility testing protocols. Stakeholders must monitor evolving EPA antimicrobial tolerance reassessments that could restrict legacy active ingredients.
Market Dynamics
Clinicians across the United States, Germany, and Japan are accelerating migration from alcohol-based formulations to hydrogen peroxide and chlorhexidine alternatives, compressing legacy product lines while reshaping supplier R&D priorities toward acrylic-compatible chemistries.
Growth Catalysts
- FDA 21 CFR 872.6730 efficacy mandates:Antimicrobial device classification requirements substantiate professional-grade claims against Candida albicans, elevating clinical procurement standards and filtering subtherapeutic formulations from dental supply channels.
- Long-term care facility adoption:Institutional volume concentrates in facilities managing stomatitis prevention protocols, where standardized dosing and compliance documentation favor tablet formulations with precise active ingredient concentrations.
- Acrylic preservation technology:Hydrogen peroxide chemistries at 0.12% to 3.6% concentration ranges eliminate biofilm without degrading polymethyl methacrylate denture bases, resolving a structural limitation that constrained alcohol-based product lifecycles.
Market Restraints
- Chlorhexidine precursor supply concentration:European chemical manufacturers face raw material constraints disrupting tablet production, forcing reformulation cycles and inventory volatility for hydrogen peroxide alternatives.
- EPA antimicrobial tolerance reassessments:Environmental release scrutiny of chlorhexidine gluconate creates regulatory friction, threatening legacy active ingredient approvals and compliance cost structures for established product lines.
- Home-use substitution by sodium hypochlorite:Unsupervised consumers employ diluted bleach solutions despite acrylic degradation risks, compressing addressable market for branded disinfectants in retail pharmacy segments.
Strategic Opportunities
- Underpenetrated Japanese home-care segment:Aging demographics and denture prevalence exceed professional product penetration rates, creating white space for pharmacy-distributed tablet formats with Japanese-language compliance labeling.
- EMA MDR biocompatibility alignment:Convergence with ISO 23317 dental material standards enables single-registration pathways across European Economic Area markets, reducing certification redundancy for multi-market suppliers.
- Tele-dentistry channel integration:Remote consultation platforms in Germany are expanding into product fulfillment, creating direct-to-patient distribution for prescription-strength disinfectants previously confined to dental supply chains.
Industry Challenges
- ISO 23317 testing protocol complexity:Biocompatibility validation timelines extend product development cycles, requiring specialized toxicology partnerships that concentrate capability among established pharmaceutical heritage manufacturers.
- Dual EPA-FDA jurisdiction navigation:Environmental release profiles and antimicrobial device claims demand parallel submission strategies, straining regulatory affairs functions and delaying market entry for novel active ingredient combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denture Disinfectants Market |
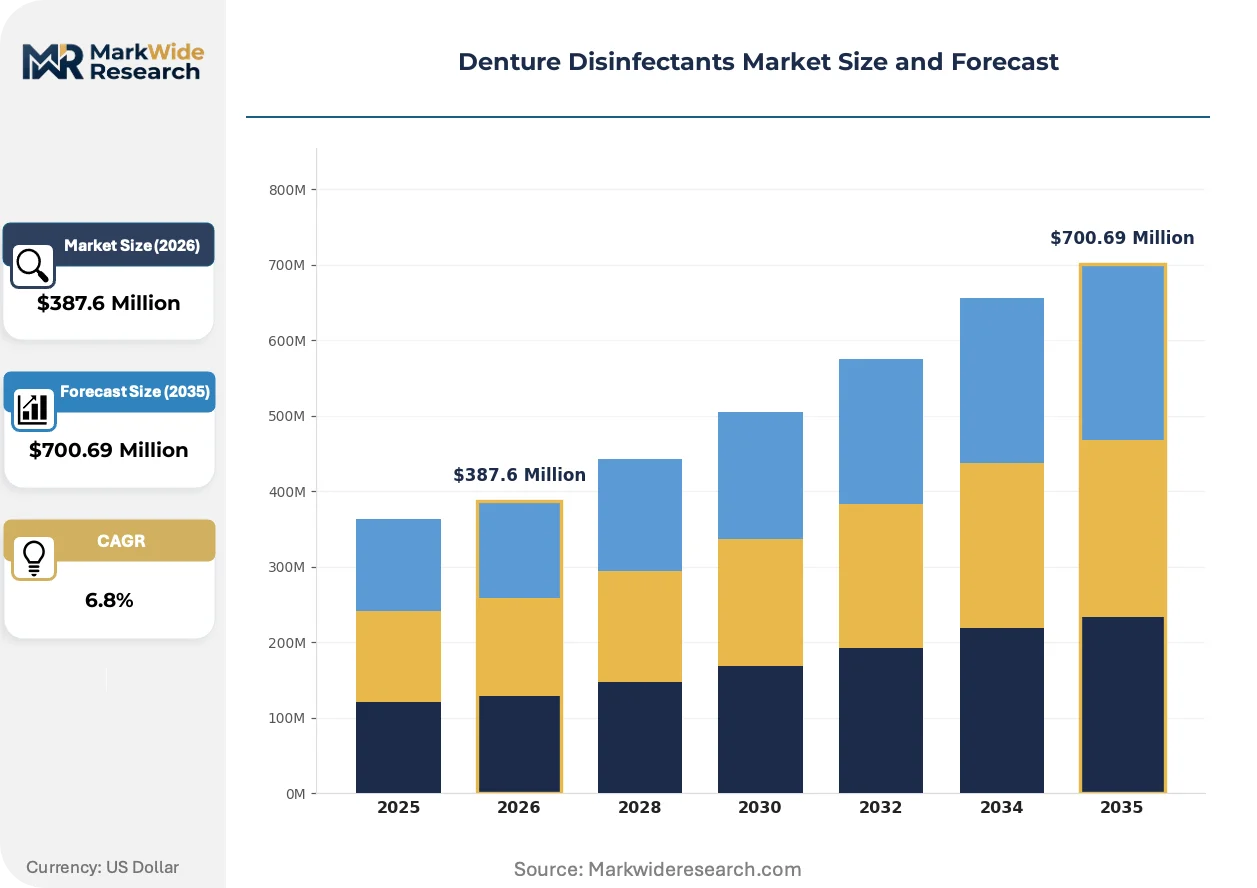
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Powders, Liquid Solutions, Foam Sprays Formulation: Alcohol-Based, Chlorhexidine-Based, Hydrogen Peroxide, Natural Enzymatic Packaging Type: Bottles, Sachets, Canisters, Jars End User: Dental Clinics, Hospitals, Home Care, Long-Term Care Facilities |
| Companies Covered | GlaxoSmithKline plc, Prestige Consumer Healthcare Inc., Colgate-Palmolive Company, Procter & Gamble, Johnson & Johnson, Dentsply Sirona Inc., Fittydent International GmbH, Renfert GmbH, ICPA Health Products Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denture Disinfectants Market Emerging Trajectories
Formulation chemistry is pivoting toward biofilm-targeting mechanisms that preserve prosthetic materials, while regulatory frameworks on both sides of the Atlantic tighten efficacy documentation requirements. Distribution models are fragmenting as institutional procurement consolidates and direct channels emerge.
Photocatalytic titanium dioxide coatings are expanding into professional-grade disinfectant adjuncts for ultraviolet-activated biofilm degradation. German dental clinics are piloting these systems for high-throughput prosthetic processing. The technology is expanding into premium service tiers that command per-procedure fees beyond commodity chemical margins.
REACH authorization timelines for residual chlorhexidine are compressing formulation windows for European manufacturers. Industrial consequence includes accelerated hydrogen peroxide R&D investment and supply chain rebalancing toward peroxide precursor suppliers. Tablet production in Germany and France is responding with dual-active formulations that reduce chlorhexidine dependency.
Institutional procurement in United States long-term care is consolidating through group purchasing organizations that unbundle after-sales technical support from product pricing. Dental supply distributors are losing volume to direct manufacturer contracts with multi-facility operators. This consolidation is most visible in Florida and Texas, where regional care chains command sufficient scale to negotiate formulation exclusivity.
Denture Disinfectants Market Segmentation
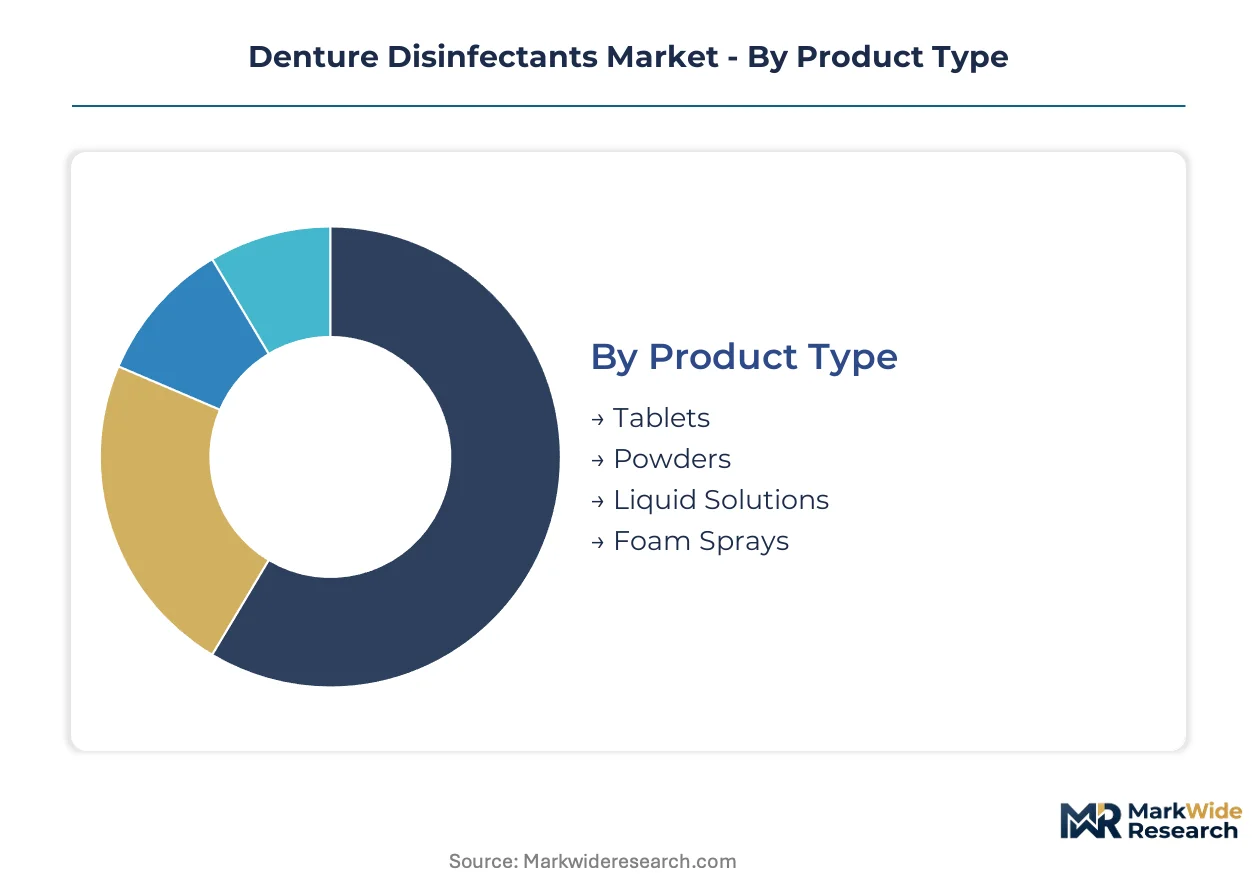
Denture disinfectant purchasing patterns diverge sharply between institutional procurement and retail pharmacy channels, with formulation chemistry and dosing convenience driving category selection. Understanding segment boundaries clarifies where margin compression versus premium pricing applies across the value chain.
Product Type:
Institutional buyers prioritize dosing precision and compliance documentation, while home users trade convenience against cost per use.
- Tablets:Effervescent formulations containing 0.12% to 3.6% active ingredients deliver pre-measured doses that satisfy FDA 21 CFR 872.6730 documentation requirements. Long-term care facilities in the United States standardize on tablet protocols for stomatitis prevention, compressing liquid solution volume in institutional procurement.
- Liquid Solutions:Higher-concentration formulations enable custom dilution for professional-grade biofilm elimination. Dental clinics in Germany favor these for chairside prosthetic processing where rapid turnaround trumps per-unit cost.
- Powders:Concentrated active ingredient carriers requiring reconstitution appeal to cost-sensitive home users seeking extended supply duration.
- Foam Sprays:Aerosolized delivery systems target spot-cleaning applications between full immersion cycles, gaining traction in Japanese home-care segments.
Tablets lead on scale; foam sprays lead on momentum.
Formulation:
Acrylic compatibility has displaced raw efficacy as the primary chemistry selection criterion, reshaping supplier R&D allocation.
- Hydrogen Peroxide:Oxygen-release mechanisms eliminate Candida albicans biofilm without degrading polymethyl methacrylate denture bases. German manufacturers are accelerating peroxide precursor supply chain rebalancing after chlorhexidine raw material constraints disrupted tablet production.
- Chlorhexidine-Based:Gluconate formulations at 0.12% to 2.0% concentrations deliver sustained antimicrobial activity against Staphylococcus aureus. EPA tolerance reassessments for environmental release profiles are threatening legacy active ingredient approvals.
- Alcohol-Based:Isopropanol and ethanol formulations face accelerating displacement as clinicians recognize acrylic surface degradation from repeated exposure.
- Natural Enzymatic:Protease and lipase blends target organic debris without synthetic chemistry, appealing to eco-conscious retail segments in European pharmacy channels.
Hydrogen peroxide formulations command the steepest expansion trajectory; alcohol-based products are losing share fastest.
Packaging Type:
Distribution channel economics and shelf-life requirements determine container selection, with institutional formats diverging from retail presentation.
- Canisters:Bulk tablet storage with desiccant integration supports high-throughput long-term care facilities managing multi-patient protocols. United States group purchasing organizations negotiate canister-scale contracts that unbundle technical support from unit pricing.
- Sachets:Single-unit foil packaging eliminates dosing error and extends portability for home users traveling with prosthetics. Japanese pharmacy chains favor sachet formats for aging demographic segments.
- Bottles:Standard liquid solution containers dominate dental clinic procurement through established supply distributors.
- Jars:Wide-mouth containers accommodate powder scoop access, concentrating in value-oriented retail segments.
Canisters dominate institutional volume; sachets are climbing fastest in direct-to-patient channels.
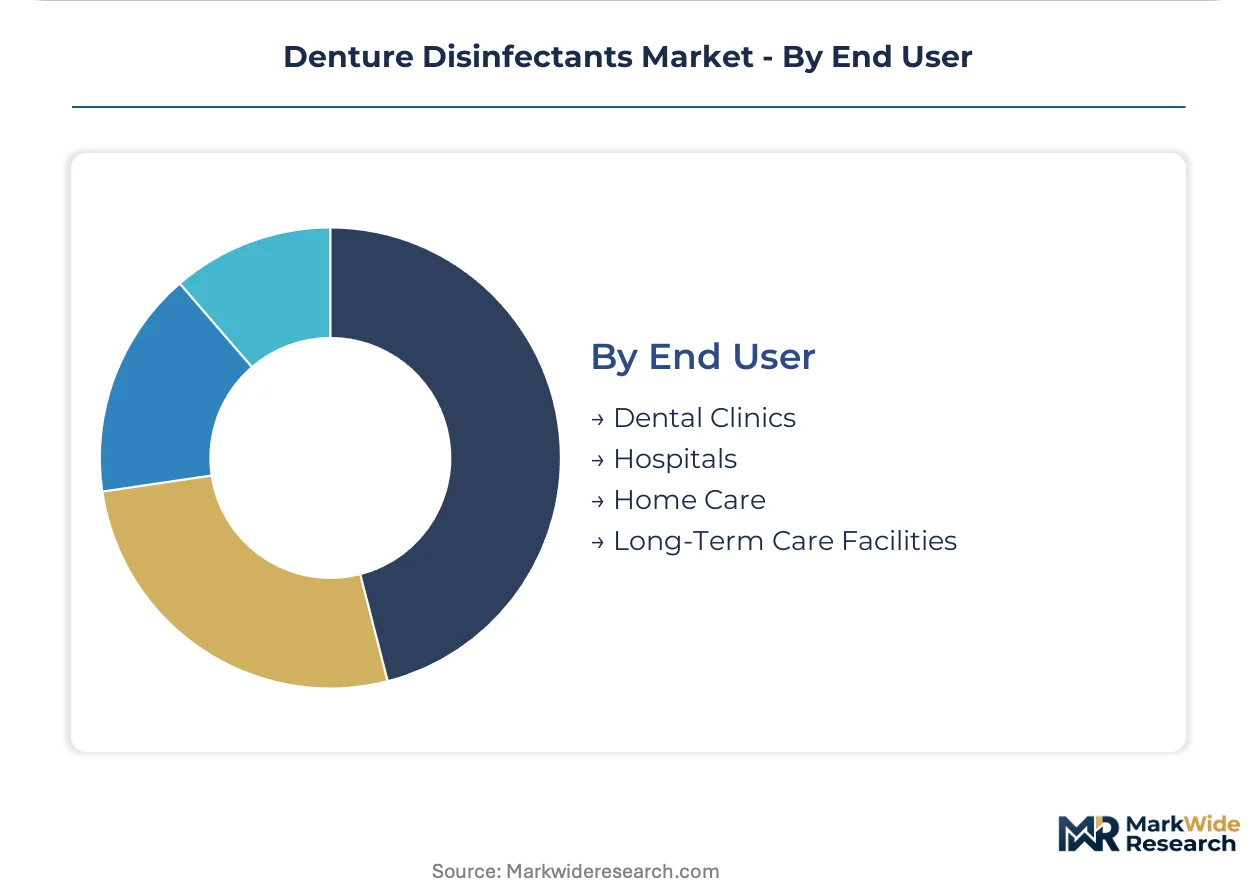
End User:
Regulatory oversight intensity and reimbursement structure create four distinct demand environments with diverging price elasticity.
- Long-Term Care Facilities:Medicare and Medicaid compliance documentation mandates standardized disinfectant protocols with audit trails. Florida and Texas regional care chains command sufficient scale to negotiate formulation exclusivity directly with manufacturers.
- Home Care:Unsupervised consumers employ sodium hypochlorite substitutes despite acrylic degradation risks, compressing branded disinfectant penetration. Japanese aging demographics exceed professional product adoption rates, creating white space for pharmacy-distributed tablet formats.
- Dental Clinics:Chairside prosthetic processing demands rapid biofilm elimination with material preservation, favoring hydrogen peroxide formulations.
- Hospitals:Infection control departments integrate denture disinfectants into broader antimicrobial device procurement frameworks.
Long-term care facilities anchor volume concentration; home care segments are expanding most quickly as pharmacy distribution deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as European REACH compliance costs push tablet production toward jurisdictions with streamlined chemical registration pathways. Producers are migrating active ingredient synthesis to regions where environmental release thresholds impose lighter documentation burdens.
United States
Medicare and Medicaid compliance documentation drives institutional procurement of tablet formats with audit trails. The FDA's 21 CFR 872.6730 antimicrobial device classification elevates clinical procurement standards. Florida and Texas regional care chains negotiate formulation exclusivity directly with manufacturers, bypassing traditional dental supply distributors.
Germany
EMA MDR biocompatibility alignment with ISO 23317 standards enables single-registration pathways across European Economic Area markets. REACH authorization timelines for residual chlorhexidine compress formulation windows. Dental clinics in Bavaria and North Rhine-Westphalia pilot photocatalytic titanium dioxide systems for ultraviolet-activated biofilm degradation.
Japan
Aging demographics and denture prevalence exceed professional product penetration rates. METI standards constrain antimicrobial device marketing claims. Pharmacy chains in Tokyo and Osaka favor sachet formats for aging demographic segments, creating white space for tablet formats with Japanese-language compliance labeling.
India
Cost-sensitive home users employ sodium hypochlorite substitutes despite acrylic degradation risks. CDSCO regulates antimicrobial devices under medical device rules. Manufacturing clusters in Maharashtra and Gujarat produce generic tablet formulations for export markets, competing on per-unit cost against branded European imports.
United Kingdom
Post-Brexit divergence from EU MDR creates parallel registration requirements for suppliers serving both markets. MHRA oversees antimicrobial device claims for denture disinfectants. London and Southeast England concentrate dental clinic procurement through group purchasing organizations consolidating volume from private practice networks.
Denture Disinfectants Market Vendor Landscape
United States producers anchor mass-market penetration through retail pharmacy networks; European specialists hold professional-grade positioning through dental supply channels. The vendor base stratifies across three tiers: pharmaceutical heritage manufacturers with FDA device registration expertise, consumer goods conglomerates with retail distribution scale, and dental equipment specialists with chairside product integration. Consolidation pressures concentrate among mid-scale tablet producers facing raw material constraints. Dominant competitive moves include backward integration into active ingredient synthesis and geographic licensing partnerships for regulatory pathway acceleration.
Within the pharmaceutical heritage tier, GlaxoSmithKline plc exemplifies premium positioning through clinical credibility. Among consumer goods conglomerates, Colgate-Palmolive Company and Procter & Gamble occupy positions defined by retail pharmacy network density. Dentsply Sirona Inc. represents the dental equipment specialist archetype, anchoring professional-grade distribution through supply channels serving chairside applications. These three company structures illustrate how regulatory registration depth, consumer marketing scale, and clinical channel integration constitute distinct competitive moats.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Prestige Consumer Healthcare Inc. |
| Colgate-Palmolive Company |
| Procter & Gamble |
| Johnson & Johnson |
| Dentsply Sirona Inc. |
| Fittydent International GmbH |
| Renfert GmbH |
| ICPA Health Products Ltd |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap chemical manufacturers in Germany and France anchor tablet production capacity, connecting conservative balance sheet management to disciplined pricing across hydrogen peroxide and chlorhexidine formulation tiers. Their ownership structure limits aggressive price competition, reinforcing margin stability even as raw material constraints force supply chain rebalancing toward peroxide precursor suppliers.
Pricing Analysis
Distributor margin layers compress as United States group purchasing organizations negotiate direct manufacturer contracts, bypassing traditional dental supply channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-registered clinical formulations from retail pharmacy tablets and unbranded home-use alternatives. Cost compression in the retail segment intensifies because sodium hypochlorite substitutes erode branded disinfectant penetration. Home-care consumers exhibit highest price sensitivity; long-term care facilities demonstrate lowest sensitivity due to Medicare compliance documentation requirements.
Supply Chain Analysis
Workforce availability constraints in Bavaria and North Rhine-Westphalia limit expansion of photocatalytic titanium dioxide coating production for ultraviolet-activated systems. Manufacturing concentrates in Germany, France, and India, with Maharashtra and Gujarat clusters producing generic tablet formulations for export markets. Active ingredient synthesis draws from European chemical manufacturers facing REACH authorization timelines for residual chlorhexidine. Single-source vulnerability in chlorhexidine gluconate precursors threatens formulation continuity. Distribution runs through dental supply distributors losing volume to direct manufacturer contracts with multi-facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denture disinfectants constitute a late-cycle quality story as clinicians migrate toward acrylic-preserving hydrogen peroxide formulations that command premium positioning over degrading alcohol-based alternatives.
For Market Incumbents: Anticipate EPA antimicrobial tolerance reassessments threatening chlorhexidine approvals by accelerating hydrogen peroxide R&D investment and securing captive supply of peroxide precursors through backward integration into active ingredient synthesis. Defend professional-grade positioning by deepening FDA 21 CFR 872.6730 registration expertise and expanding technical support bundling for institutional procurement consolidation. For New Entrants and Emerging Players: Photocatalytic coating technology offers entry into premium service tiers commanding per-procedure fees beyond commodity chemical margins. Target Japanese home-care white space where aging demographics exceed professional product penetration rates, deploying pharmacy-distributed sachet formats with Japanese-language compliance labeling. Pursue tele-dentistry channel integration in Germany for direct-to-patient distribution of prescription-strength disinfectants. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale tablet producers facing raw material constraints and regulatory friction. Long-term viability favors pharmaceutical heritage manufacturers with dual EPA-FDA jurisdiction navigation capabilities and ISO 23317 biocompatibility validation partnerships. Monitor EMA MDR alignment progress as inflection indicator for European market consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Captive supply of hydrogen peroxide precursors insulates margins from European chlorhexidine raw material constraints. |
| FDA 21 CFR 872.6730 Registration Expansion | Antimicrobial device classification substantiates professional-grade claims against Candida albicans in dental supply channels. |
| Photocatalytic Titanium Dioxide Coating Development | Ultraviolet-activated biofilm degradation systems command premium per-procedure fees in German dental clinics. |
| Japanese Pharmacy Distribution Partnership | Sachet and tablet formats with METI-compliant labeling capture underpenetrated aging demographic segments in Tokyo and Osaka. |
| Tele-Dentistry Channel Integration | Remote consultation platforms in Germany enable direct-to-patient fulfillment of prescription-strength disinfectants. |
Methodological Framework
Multiple input streams — structured interviews with dental supply distributors, regulatory affairs specialists at antimicrobial device manufacturers, and long-term care facility procurement directors — were reconciled against secondary validation from FDA 510(k) filings, EPA antimicrobial tolerance reassessment dockets, and ISO 23317 dental material standards documentation. Customs records tracking chlorhexidine gluconate and hydrogen peroxide precursor trade flows provided supply-side calibration. Bottom-up volume estimates from tablet and liquid solution production capacities were triangulated against top-down expenditure data from Medicare and Medicaid reimbursement databases.
Data-stream reconciliation across product type, formulation chemistry, packaging format, and end-user segment dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by regional regulatory cluster penetration rates. Forecast inputs incorporated FDA 21 CFR 872.6730 enforcement intensity indices, REACH authorization timeline scenarios for residual chlorhexidine, and tele-dentistry platform adoption curves in Germany and Japan.
The model holds under stable EPA-FDA jurisdiction alignment and REACH authorization continuity; deviation in antimicrobial tolerance reassessment outcomes or raw material supply disruptions would shift hydrogen peroxide versus chlorhexidine formulation mix assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Global High Level Disinfection Services Market
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Salivary Gland Infection Market
Infection Control
Sanitizers Market
Infection Control
Ear Infection Treatment Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Catheter-Related Bloodstream Infections (Crbsis) Market
Infection Control
Infection Prevention Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Sterilization Tunnel Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Ultraviolet Disinfection Equipment Market