
 Indwelling Catheter Market | 2026-2036
Indwelling Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Indwelling Catheter Market Analytics
China is reconfiguring regional supply dynamics through expanded silicone processing capacity and domestic medical device manufacturing investments. Becton Dickinson and Company leverages vertical integration across latex and silicone supply chains to sustain cost advantages in antimicrobial catheter production. Cardinal Health anchors North American distribution through direct hospital contracting networks, while B. Braun Melsungen AG competes on hydrogel coating technology leadership in European markets.
An indwelling catheter is a flexible tube inserted into the bladder through the urethra or suprapubic incision to enable continuous urine drainage, typically constructed from silicone, latex, or PVC with balloon retention mechanisms inflated by sterile water. The device serves patients with urinary retention, post-surgical recovery needs, or neurogenic bladder dysfunction requiring prolonged catheterization. Foley catheters occupy the largest revenue pool due to universal hospital adoption, though antimicrobial-coated variants command premium positioning as infection prevention protocols tighten. Home care settings represent the fastest-growing end-user channel as reimbursement shifts favor outpatient management and patient mobility improves.
The FDA enforces 510(k) premarket notification requirements for indwelling catheters, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance through EUDAMED, and ISO 13485 governs quality management systems for manufacturers seeking multi-jurisdiction access. These frameworks elevate compliance costs but simultaneously filter out low-quality competitors, concentrating procurement authority among accredited suppliers. Stakeholders must monitor evolving antimicrobial resistance data and reimbursement rate adjustments to align R&D portfolios with payer priorities.
Market Dynamics
Medicare reimbursement policy in the United States is accelerating the shift from acute care to ambulatory catheterization, forcing manufacturers to reconfigure product portfolios for home care durability and patient self-management.
Growth Catalysts
- Antimicrobial coating mandates:FDA's updated 510(k) pathways for infection-resistant devices are pulling hospitals toward premium catheter procurement as CAUTI prevention protocols tighten.
- Silicone processing expansion:China's domestic medical device manufacturing investments are reducing raw material dependence on imported elastomers for balloon retention mechanisms.
- Neurogenic bladder prevalence:Aging demographics in Japan and Germany are expanding the addressable patient pool for long-term suprapubic catheterization.
Market Restraints
- Latex supply concentration:Southeast Asian rubber plantations face climate volatility that disrupts cost structures for latex-based catheter production.
- CE marking friction:EU Medical Device Regulation clinical evidence requirements extend time-to-market for novel hydrogel coatings by 18-24 months.
- Intermittent catheter substitution:Clean intermittent self-catheterization protocols are displacing indwelling devices in spinal cord injury management.
Strategic Opportunities
- Home care channel innovation:Direct-to-patient subscription models for catheter supply resupply are bypassing traditional hospital purchasing committees.
- ISO 13485 certification arbitrage:Quality management accreditation is opening procurement access across Middle Eastern markets previously dominated by European suppliers.
- Telehealth integration:Remote monitoring of catheter dwell time and blockage alerts is creating service revenue attachments beyond device sales.
Industry Challenges
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity validation queues at accredited laboratories are compressing product launch windows.
- Legacy ERP integration:Hospital supply chain digitization requires EDI compatibility investments that strain mid-tier manufacturer IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indwelling Catheter Market |
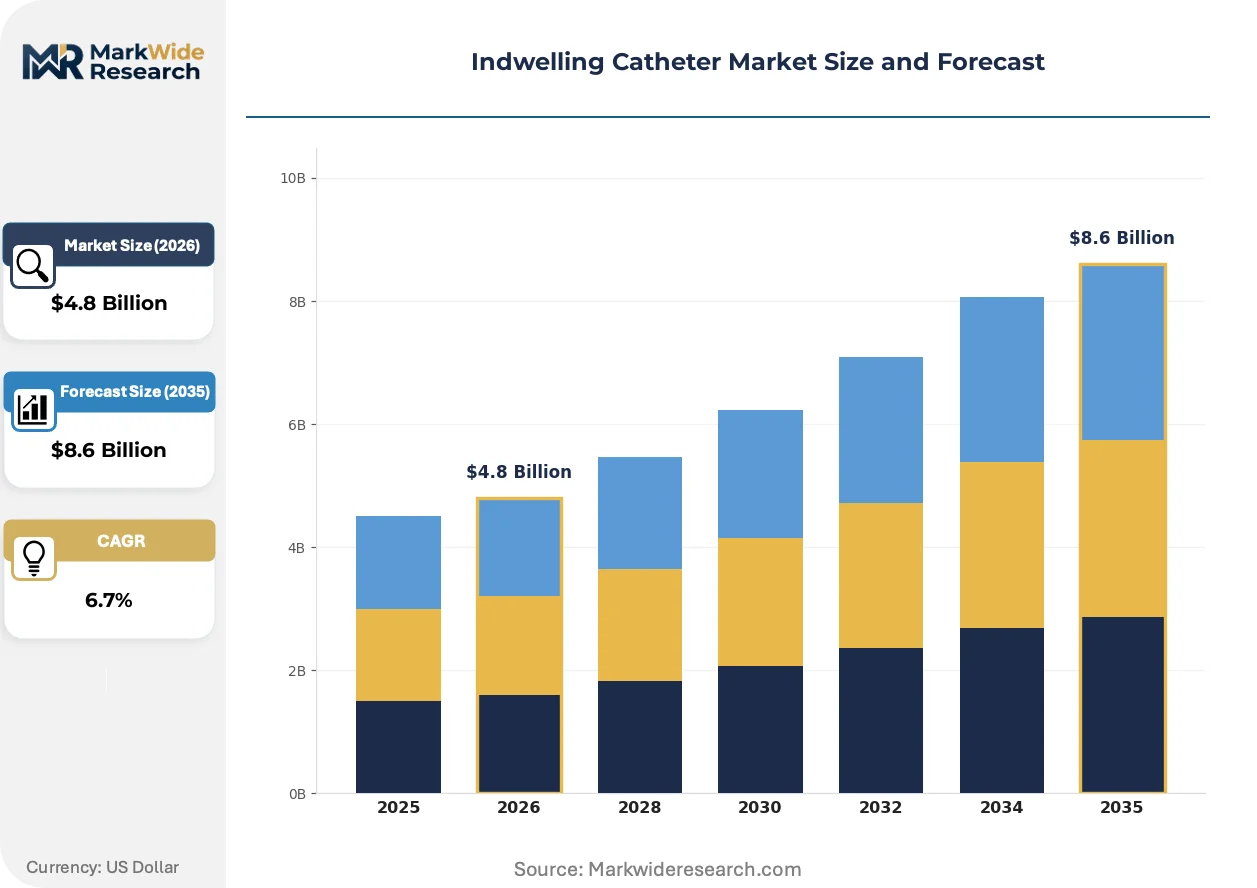
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foley Catheters, Suprapubic Catheters, Three-way Catheters, Antimicrobial Catheters Material: Silicone, Latex, PVC, Hydrogel End User: Hospitals, Long-term Care Facilities, Home Care Settings, Ambulatory Surgical Centers Application: Urinary Retention, Surgery, Palliative Care, Infection Management |
| Companies Covered | Becton Dickinson and Company, Cardinal Health, B. Braun Melsungen AG, Coloplast, Teleflex Incorporated, ConvaTec Group PLC, Cook Medical, Medline Industries, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indwelling Catheter Market Evolving Landscape
Digital health integration and material science advances are compressing the traditional catheter lifecycle, while regulatory evidence requirements are elevating R&D fixed costs across the competitive set.
Smart catheter systems embedding pressure sensors and wireless transmission modules are virtualizing the traditional nurse-led blockage detection workflow. Home care agencies in the Netherlands and Denmark are piloting these connected devices for nocturnal monitoring of spinal cord injury patients. This virtualization is compressing emergency intervention rates and shifting liability toward device manufacturers for real-time diagnostic accuracy.
EU Medical Device Regulation post-market surveillance mandates through EUDAMED are forcing manufacturers to maintain clinical follow-up registries for antimicrobial coating efficacy. German and French notified bodies are rejecting 510(k)-cleared US devices without supplemental European clinical data. Hydrogel-coated Foley segments are absorbing the heaviest compliance burden as infection rate benchmarking becomes a procurement gate.
Hospital purchasing consortia are consolidating catheter procurement into two-year sole-source agreements with performance guarantees on CAUTI reduction. Group purchasing organizations in the US Midwest are displacing fragmented spot-buying with standardized formularies tied to electronic health record integration. This concentration is most visible in integrated delivery networks where catheter choice is now dictated by system-wide infection control committees rather than individual urologists.
Indwelling Catheter Market Segmentation
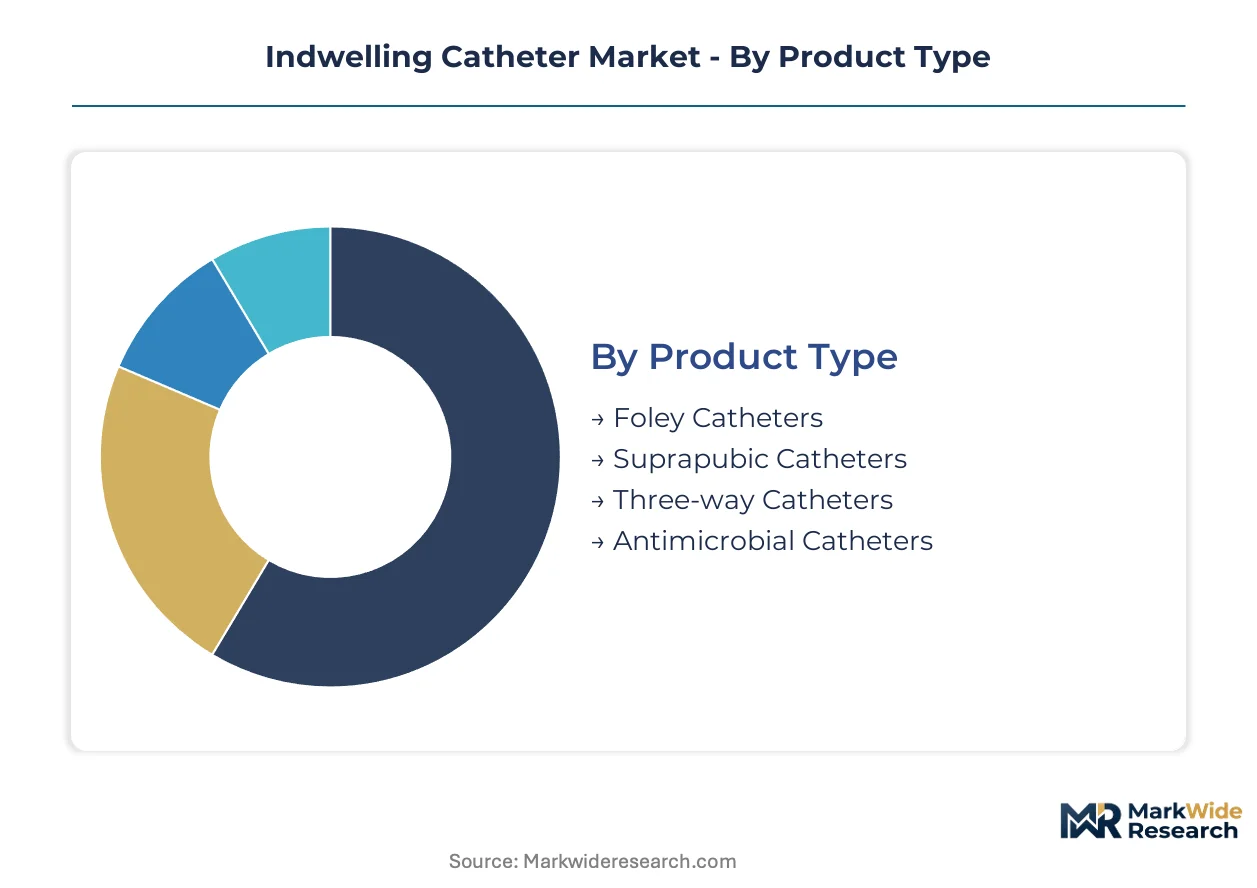
Segmentation in the indwelling catheter market determines service intensity requirements, with home care channels demanding patient education support while acute settings prioritize bulk logistics. Material choices and coating technologies further stratify procurement workflows across reimbursement tiers.
Product Type:
After-sales service intensity varies sharply by product type, with complex three-way systems requiring clinical training support and antimicrobial variants demanding infection outcome tracking.
- Foley Catheters:The balloon-retention design with sterile water inflation dominates hospital formularies due to universal insertion protocol familiarity. Demand concentrates in United States integrated delivery networks where Medicare reimbursement favors long-term indwelling use over intermittent alternatives.
- Antimicrobial Catheters:Silver-alloy or nitrofurazone-impregnated surfaces command premium positioning as FDA 510(k) pathways tighten infection prevention requirements. Procurement is accelerating in California and Texas hospital systems where CAUTI reduction metrics determine supplier selection.
- Suprapubic Catheters:Percutaneous placement tubes serve neurogenic bladder patients requiring months-long dwell times.
- Three-way Catheters:Irrigation-enabled designs for hematuria management require urology nursing support.
By volume, Foley catheters lead. By growth pace, antimicrobial-coated variants are expanding most quickly.
Material:
Cost tier stratification separates silicone's biocompatibility premium from latex's volume economics, with hydrogel coatings creating a mid-tier positioning.
- Silicone:Inert elastomer construction eliminates protein adhesion and enables extended dwell protocols up to 30 days. China's expanded domestic processing capacity is reducing raw material dependence for balloon retention mechanisms.
- Latex:Natural rubber construction offers cost efficiency for short-term post-surgical drainage. Southeast Asian plantation supply volatility is disrupting cost structures for budget-sensitive procurement.
- PVC:Rigid polymer construction suits intermittent drainage needs with lower material costs.
- Hydrogel:Hydrated polymer coatings reduce urethral friction during insertion and removal.
Silicone captures the premium tier by margin. Latex maintains volume leadership in emerging markets.
End User:
Customer type dictates channel architecture, with home care requiring direct-to-patient logistics and hospitals leveraging group purchasing organization consolidation.
- Home Care Settings:Patient-managed catheterization with monthly resupply subscriptions bypasses traditional hospital purchasing committees. Japan's aging demographics and Germany's outpatient reimbursement shifts are accelerating this channel's expansion.
- Hospitals:Inpatient surgical and ICU placement drives standardized formularies with infection control committee oversight. United States Midwest purchasing consortia are consolidating procurement into sole-source agreements with CAUTI performance guarantees.
- Long-term Care Facilities:Skilled nursing environments balance cost control with staff training limitations.
- Ambulatory Surgical Centers:Same-day discharge protocols favor short-dwell catheter protocols.
Home care settings gain share fastest. Hospitals retain the largest absolute volume position.
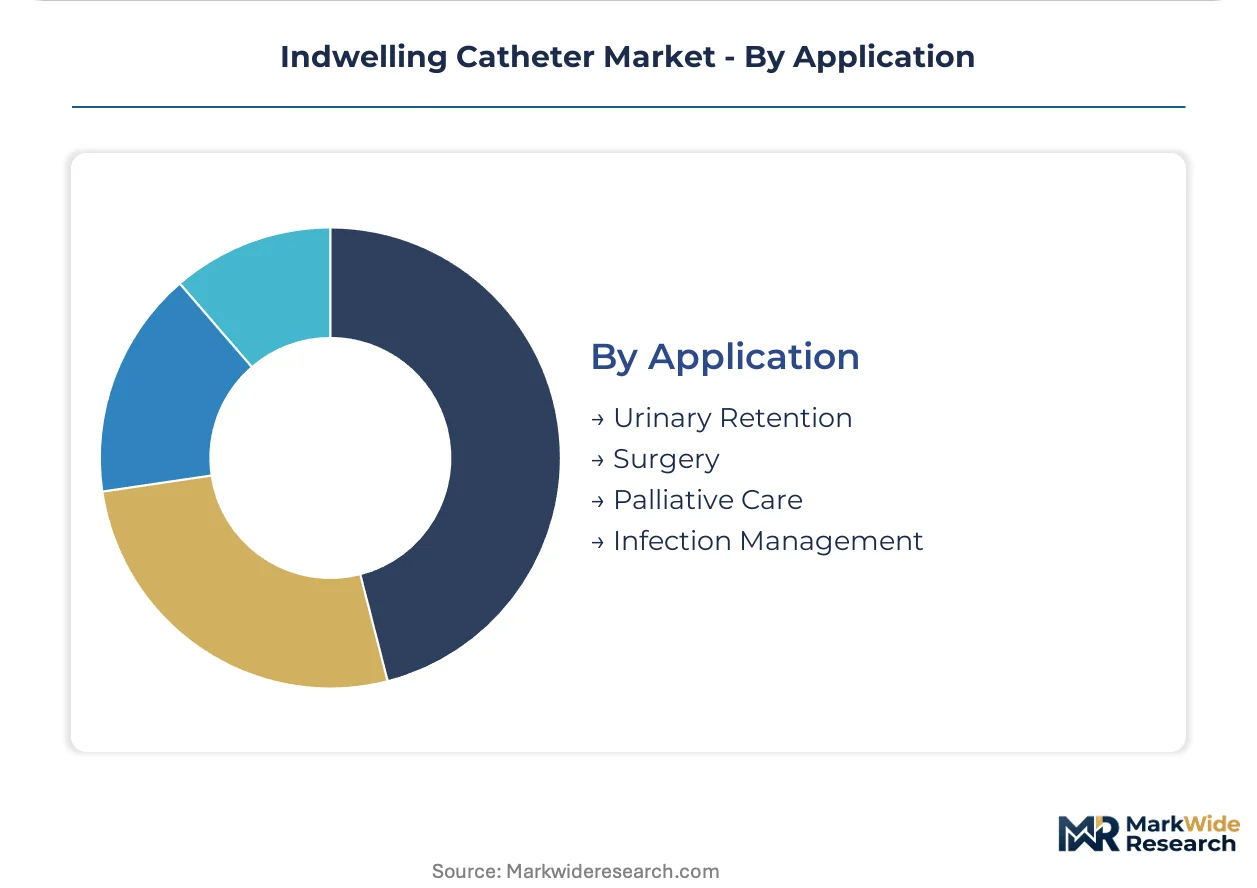
Application:
Clinical indication determines dwell time requirements and coating specifications, with palliative care prioritizing comfort over antimicrobial features.
- Urinary Retention:Benign prostatic hyperplasia and neurogenic bladder conditions require chronic catheterization with balloon retention. Demand concentrates in Japan and Germany where aging demographics expand the addressable patient pool for long-term suprapubic placement.
- Infection Management:Recurrent CAUTI prevention protocols drive antimicrobial-coated procurement with clinical outcome tracking. United States hospital systems facing CMS penalty exposure are mandating premium catheter tiers for high-risk patients.
- Surgery:Perioperative drainage supports post-procedural monitoring.
- Palliative Care:End-of-life comfort prioritizes soft silicone construction over infection resistance.
Infection management applications command the steepest price premiums. Urinary retention represents the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's medical device export capacity, while the Rhine-Main-Danube canal network anchors European distribution logistics for silicone-based catheter components.
United States
Medicare reimbursement shifts favor ambulatory catheterization over acute care stays, expanding home care channel volumes. The FDA's updated 510(k) pathways for antimicrobial-coated devices mandate enhanced clinical evidence for market entry. Minnesota and Illinois host integrated delivery networks consolidating procurement into sole-source agreements with CAUTI performance guarantees.
Germany
Aging demographics and outpatient reimbursement policies accelerate long-term suprapubic catheter adoption. The EU Medical Device Regulation through BfArM oversight requires post-market surveillance registries for hydrogel-coated variants. Baden-Württemberg's medical technology cluster concentrates coating innovation and notified body proximity for faster CE marking.
China
Domestic silicone processing capacity expansion reduces raw material import dependence for balloon retention mechanisms. NMPA streamlined registration pathways for Class II medical devices accelerate local manufacturing approvals. Suzhou and Shenzhen industrial parks attract catheter assembly investments from multinational suppliers seeking cost-advantaged production.
Japan
Neurogenic bladder prevalence among elderly populations drives chronic catheterization demand. PMDA's harmonization with IMDRF standards facilitates parallel submission with FDA pathways for antimicrobial devices. Osaka's medical device manufacturing corridor specializes in precision molding for extended-dwell silicone catheters.
United Kingdom
NHS procurement frameworks standardize infection prevention protocols across hospital trusts. MHRA post-Brexit regulatory autonomy maintains EU MDR equivalence while streamlining UKCA marking timelines. The East Midlands medtech cluster hosts contract manufacturers serving European distribution networks.
Indwelling Catheter Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying balloon mechanisms and coating chemistries. The vendor base stratifies across multinational conglomerates with hospital contracting networks, regional manufacturers with cost-optimized latex production, and niche innovators with hydrogel or antimicrobial specialization. Three archetypes dominate: vertically integrated elastomer processors, distribution-anchored procurement consolidators, and coating technology licensors. Capacity expansion in Chinese silicone processing and strategic partnerships for EHR-integrated supply tracking represent the dominant competitive vectors.
Among diversified medical technology conglomerates, Becton Dickinson and Company exemplifies the vertically integrated archetype spanning latex and silicone supply chains, while Cardinal Health occupies the distribution-anchored position through direct hospital contracting networks. B. Braun Melsungen AG represents the European coating technology specialist competing on hydrogel innovation leadership.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Cardinal Health |
| B. Braun Melsungen AG |
| Coloplast |
| Teleflex Incorporated |
| ConvaTec Group PLC |
| Cook Medical |
| Medline Industries |
| Boston Scientific Corporation |
| Others |
Value Network & Pricing Analysis
The Port of Shanghai's container throughput volatility feeds directly into landed cost spreads between antimicrobial-coated and standard latex catheters, compressing margin buffers for distributors serving Midwestern US hospital systems while amplifying price premiums on silicone-based extended-dwell devices.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silver-alloy antimicrobial Foley catheters from hydrogel-coated mid-tier variants and uncoated latex economy lines. Price differentiation hinges on FDA 510(k) clearance tier for infection-resistant coatings and volume scale of group purchasing organization contracts. Cost compression in the economy latex tier is intensifying because Southeast Asian rubber plantation supply disruptions are forcing raw material substitutions. Home care subscription buyers show highest price sensitivity, while integrated delivery networks with CAUTI penalty exposure absorb premium antimicrobial pricing without volume erosion.
Supply Chain Analysis
Contract manufacturing concentration among Suzhou and Shenzhen industrial park facilities anchors global balloon retention mechanism assembly, with Baden-Württemberg coating specialists and Minnesota precision molding operations feeding midstream component integration. Geographic supply concentration centers on China for silicone elastomer processing, Malaysia for latex compounding, and Germany for hydrogel polymer synthesis. Raw material dependencies draw from Thai plantation rubber, Chinese silicone monomers, and Indian nitrofurazone active pharmaceutical ingredients. Single-source vulnerability in Southeast Asian latex supply chains threatens cost stability for economy-tier production. Distribution runs through Cardinal Health and Medline Industries hospital contracting networks, with direct-to-patient subscription channels bypassing traditional procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized coating formulation expertise and ISO 13485 quality management accreditation constitute scarce capabilities that concentrate competitive advantage among a narrowing set of qualified suppliers, while mid-tier manufacturers face exclusion from integrated delivery network formularies.
For Market Incumbents: Insulate market position through backward integration into silicone elastomer processing and captive supply of balloon retention mechanisms, countering Chinese domestic manufacturers' raw material cost advantages. Prioritize CE marking investment for hydrogel-coated variants ahead of EU MDR clinical evidence deadlines to preempt European competitor displacement. Defend against clean intermittent catheter substitution by embedding smart monitoring sensors that create service revenue attachments beyond device commoditization. For New Entrants and Emerging Players: Pursue white-space opportunity in Middle Eastern markets where ISO 13485 certification arbitrage opens procurement access previously dominated by European suppliers. Target Japan's neurogenic bladder patient expansion with extended-dwell silicone suprapubic catheters, leveraging PMDA-FDA harmonization for parallel submission efficiency. Attack through telehealth-integrated subscription models that bypass hospital purchasing committee gatekeeping and capture home care channel growth. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core urology portfolios, particularly coating technology specialists with hydrogel IP and established notified body relationships. Long-term viability favors platform integrators with EHR compatibility and remote monitoring service stacks over pure-play device manufacturers. Watch FDA antimicrobial resistance surveillance data as inflection signal for premium coating tier demand acceleration or regulatory reversal.| Strategic Initiative | Industry Significance |
|---|---|
| 510(k) Antimicrobial Pathway Advancement | FDA infection-resistant device clearance accelerates hospital premium tier procurement as CAUTI protocols tighten. |
| Silicone Processing Backward Integration | Captive elastomer supply secures margin control against Chinese domestic manufacturer cost competition. |
| Home Care Subscription Channel Development | Direct-to-patient resupply models bypass GPO consolidation and capture Medicare reimbursement shift volumes. |
| EHR-Integrated Supply Tracking Partnership | Electronic health record compatibility satisfies Midwestern IDN sole-source contract technical requirements. |
| EU MDR Post-Market Surveillance Registry | EUDAMED clinical outcome tracking maintains CE marking access for hydrogel-coated Foley segments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital infection control committee members, GPO contracts managers, biomedical engineers, and home care agency procurement leads; and secondary validation against FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, hospital procurement contract repositories, and EU EUDAMED vigilance reports. Bottom-up demand modeling from patient population incidence rates and top-down supply verification from manufacturer capacity disclosures were triangulated to constrain estimate ranges.
Forecast inputs span product type segmentation by balloon retention and coating technology, material tier stratification across silicone-latex-PVC-hydrogel grades, end-user channel architecture distinguishing hospital from home care logistics, and application-specific dwell time protocols. CAGRs were derived from patient demographic projections cross-referenced with reimbursement policy trajectory and regulatory approval pipeline velocity. Antimicrobial coating efficacy data and Medicare ambulatory care shift rates served as industry-specific demand drivers across the projection horizon.
Sensitivities concentrate around FDA antimicrobial resistance surveillance revisions, Southeast Asian latex supply disruption severity, and EU MDR notified body capacity constraints extending CE marking timelines. Forecasts embed assumptions on sustained Medicare reimbursement favoring long-term indwelling use and stable ISO 10993 biocompatibility testing queue durations. Quarterly review of hospital CAUTI penalty exposure metrics and Chinese NMPA Class II registration pathway processing speeds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Mesh Market
Medical Devices
Pre-Owned Medical Devices Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Global Intravenous Infusion Pump Market
Medical Devices
Dialysis Catheters Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Medical Face Shield Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Digital Flexible Ureteroscopes Market
Medical Devices
Small Bone and Joint Devices Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market