
 United States Hand Sanitizer Market | 2026-2036
United States Hand Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hand Sanitizer Market Intelligence
Private-label contract manufacturing is rewriting profit distribution across the United States hand sanitizer value chain. GOJO Industries leverages its captive chemical supply and automated dispensing ecosystem to sustain premium positioning in institutional channels. Procter & Gamble competes through mass retail shelf dominance and cross-category brand leverage in household segments. Ecolab anchors its position in foodservice and hospitality through integrated hygiene programs that bundle sanitizer with audit services.
Hand sanitizer denotes a topical antiseptic preparation containing ethanol, isopropanol, or benzalkonium chloride formulated to reduce microbial load on intact skin without water rinsing, typically manufactured through compounding, homogenization, and sterile filling processes designed for rapid evaporation and residual efficacy. Gel formulations occupy the largest volume share due to consumer familiarity and controlled dispensing behavior, though foam formats are gaining traction in healthcare settings where spreadability and cost-per-use metrics matter. Alcohol-based formulations dominate the formulation landscape, while non-alcohol alternatives carve a niche in environments with flammability restrictions or religious compliance requirements.
FDA monograph compliance, EPA pesticide registration for residual claims, and OSHA bloodborne pathogen standards collectively shape product labeling, active ingredient concentration floors, and institutional procurement specifications across the United States. State-level health department mandates in California, New York, and Illinois further tighten placement requirements in schools and public facilities. Stakeholders must monitor evolving FDA enforcement discretion timelines and state bulk procurement consolidation to anticipate volume shifts and qualification barriers.
Market Dynamics
Bulk procurement consolidation across California and Texas school districts is compressing vendor margins while favoring manufacturers with captive ethanol supply and automated filling lines.
Growth Catalysts
- FDA Monograph Updates:Revised active ingredient thresholds for alcohol-based formulations are triggering hospital procurement department requalification cycles that favor established suppliers with validated sterile filling processes.
- California State Mandates:Placement requirements in public facilities and K-12 institutions under state health department directives are creating institutional volume anchors independent of consumer demand fluctuation.
- Ethanol Supply Integration:Domestic corn-derived alcohol producers with pharmaceutical-grade certification are securing multi-year supply agreements that lock in raw material cost stability for compounders.
Market Restraints
- Isopropanol Price Volatility:Gulf Coast petrochemical feedstock disruptions and refinery maintenance cycles create input cost swings that squeeze contract manufacturers without long-term supply hedges.
- Midwest Supply Concentration:Over 60% of US ethanol production clusters in Iowa and Illinois, exposing coastal formulators to freight cost inflation and rail logistics bottlenecks during harvest season.
- Flammability Restrictions:OSHA bloodborne pathogen standards and state fire codes limit alcohol-based product deployment in correctional facilities and certain industrial settings, capping addressable volume.
Strategic Opportunities
- Texas Healthcare Expansion:Houston and Dallas-Fort Worth hospital construction pipelines are generating multi-year hygiene supply contracts with integrated audit service bundling potential.
- Non-Alcohol Formulation Niche:Benzalkonium chloride alternatives are penetrating faith-based institutional channels and aviation maintenance facilities where flammability compliance blocks ethanol deployment.
- Automated Dispensing Convergence:IoT-enabled dispenser networks with usage analytics are creating recurring revenue streams and switching cost barriers in corporate campus and hospitality verticals.
Industry Challenges
- Sterile Filling Certification Backlogs:FDA facility inspection queues for OTC drug manufacturing sites are extending qualification timelines for new market entrants by 12-18 months.
- Formulation Chemist Scarcity:Specialized expertise in rapid-evaporation skin compatibility and residual efficacy testing is concentrating among legacy pharmaceutical compounders, constraining R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hand Sanitizer Market |
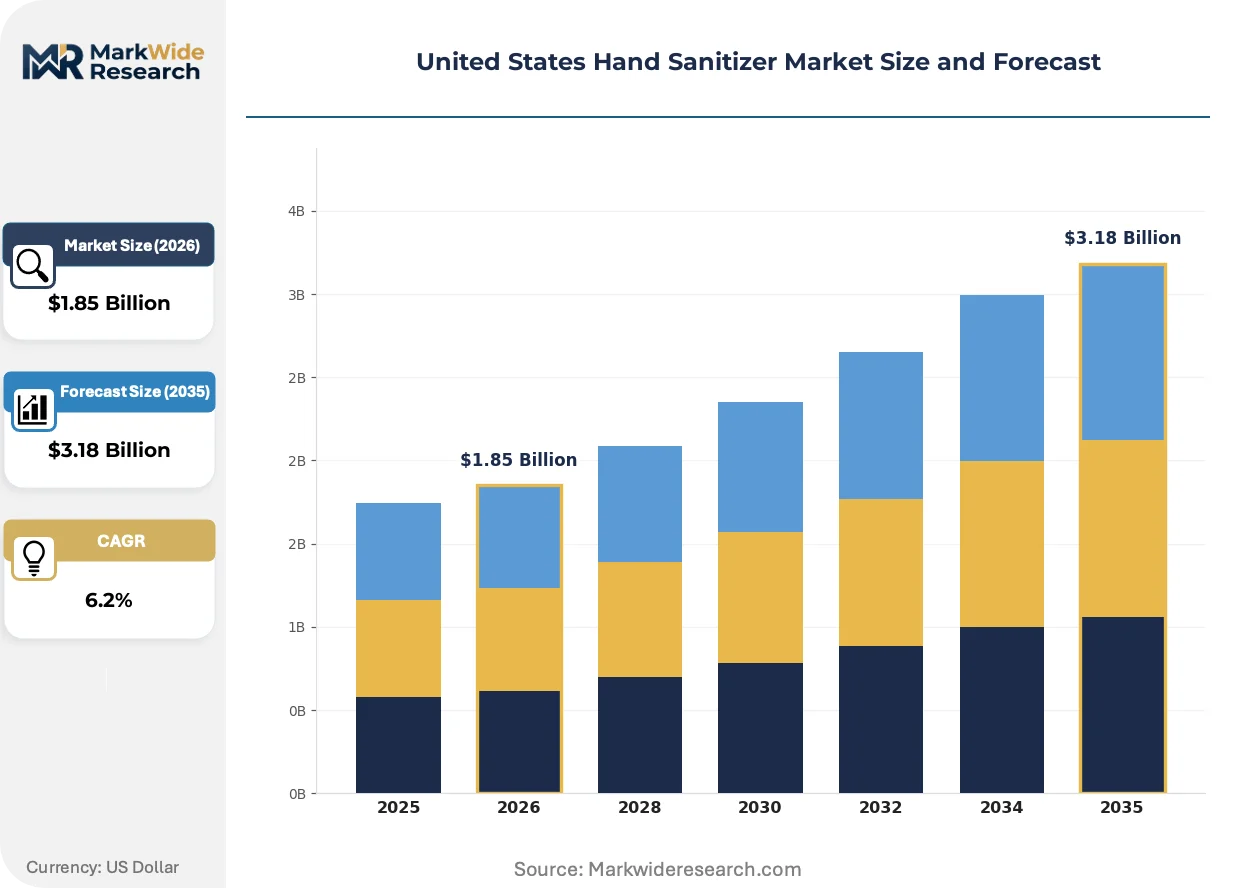
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Liquid, Spray Distribution Channel: Supermarkets, Online Retail, Pharmacies, Convenience Stores End User: Healthcare, Education, Hospitality, Household Formulation: Alcohol-based, Non-alcohol-based, Organic, Antibacterial |
| Companies Covered | GOJO Industries, Inc., Reckitt Benckiser Group plc, Procter & Gamble, 3M Company, Vi-Jon, Ecolab Inc., Edgewell Personal Care, The Clorox Company, Best Sanitizers, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hand Sanitizer Market Strategic Shifts & Innovations
Formulation chemistry and delivery mechanisms are diverging across institutional and consumer channels, with healthcare settings prioritizing cost-per-use metrics while retail segments emphasize sensorial experience and packaging differentiation.
Foam delivery systems are migrating from gel-dominant formats in acute care environments. Hospital infection control committees are adopting spreadable foam for surgical scrub replacements and patient room hygiene protocols. This migration from traditional gel is compressing per-dose volume requirements and enabling bulk refill contracts that reduce packaging waste disposal costs.
OSHA bloodborne pathogen standards and state-level school health mandates are tightening placement and concentration requirements simultaneously. Compliance documentation burdens are shifting procurement evaluation criteria toward suppliers with integrated regulatory affairs support. California and New York health departments are enforcing the most stringent labeling and accessibility specifications, forcing national distributors to maintain state-specific SKU portfolios.
Direct institutional contracting is displacing traditional distribution intermediaries in high-volume healthcare and education accounts. Third-party GPOs are losing share to manufacturer-direct sales teams that bundle formulation supply with dispenser hardware and compliance auditing. This channel restructuring is most visible in Texas and Florida, where consolidated school district purchasing cooperatives are negotiating multi-year sole-source agreements with integrated hygiene program providers.
United States Hand Sanitizer Market Segmentation
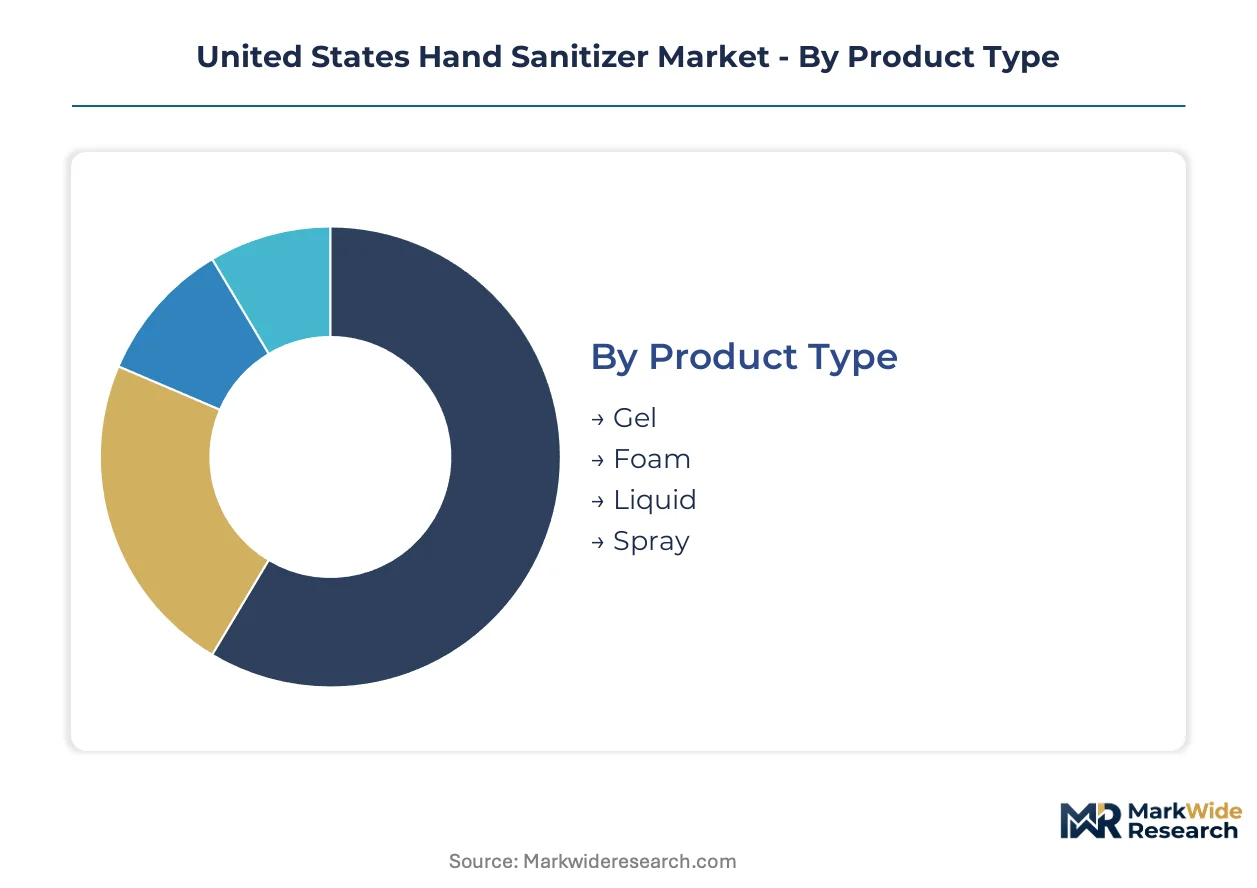
Hand sanitizer procurement cycles vary dramatically across product formats and institutional channels, with healthcare facilities rotating inventory quarterly while household segments exhibit seasonal surges tied to academic calendars. Understanding velocity differentials within each dimension reveals where manufacturers must maintain buffer stocks versus where just-in-time fulfillment suffices.
Product Type:
Gel formats turn inventory slowest due to entrenched consumer habits, while foam and spray variants cycle faster as institutional buyers experiment with dosing efficiency and application coverage.
- Gel:Viscous hydroxypropyl cellulose-thickened formulations deliver controlled dispensing and minimal drip loss. California and Texas school districts specify gel for K-12 placement under state health mandates, though per-dose volume requirements exceed foam alternatives by 40-60%.
- Foam:Air-entrapment systems create spreadable micro-bubbles that reduce per-use volume. Houston and Dallas-Fort Worth hospital construction pipelines are specifying foam for surgical scrub replacement protocols, driven by cost-per-use metrics and waste reduction targets.
- Liquid:Low-viscosity solutions suit automated dispenser systems and bulk refill operations in foodservice environments.
- Spray:Aerosol and pump-delivery formats penetrate aviation maintenance and faith-based institutional channels where rapid coverage of large surface areas matters.
Gel dominates installed base. Foam is where expansion concentrates.
Distribution Channel:
Channel economics separate high-frequency replenishment from planned procurement, with direct institutional contracts compressing distributor margins while retail intermediaries capture seasonal household spikes.
- Supermarkets:Mass retail shelf space allocation favors cross-category hygiene brands with household leverage. California and Texas volume anchors drive regional distribution center stocking priorities.
- Online Retail:E-commerce penetration concentrates in subscription-based household replenishment and bulk institutional procurement bypassing traditional GPOs.
- Pharmacies:White-label and pharmacy-brand formulations capture price-sensitive consumers seeking FDA monograph compliance at lower price points.
- Convenience Stores:Single-use and travel-size formats address immediate-need purchasing with minimal shelf space requirements.
Supermarkets and pharmacies hold established positions. Online retail is climbing the fastest as procurement digitization accelerates.
End User:
Application environments dictate formulation specifications, with healthcare requiring sterile filling certification while education and hospitality prioritize cost containment and dispenser integration.
- Healthcare:Acute care settings demand ethanol concentrations above 60% with validated sterile filling processes. FDA facility inspection backlogs are extending supplier qualification timelines.
- Education:California state mandates and Texas school district purchasing cooperatives are consolidating volume around multi-year sole-source agreements with integrated hygiene program providers.
- Hospitality:IoT-enabled dispenser networks with usage analytics are creating recurring revenue streams in corporate campus and hotel verticals.
- Household:Sensorial experience and packaging differentiation drive brand selection, with seasonal demand spikes aligned to influenza season and back-to-school periods.
Healthcare commands premium pricing. Education is gaining share fastest through mandate-driven procurement consolidation.
Formulation:
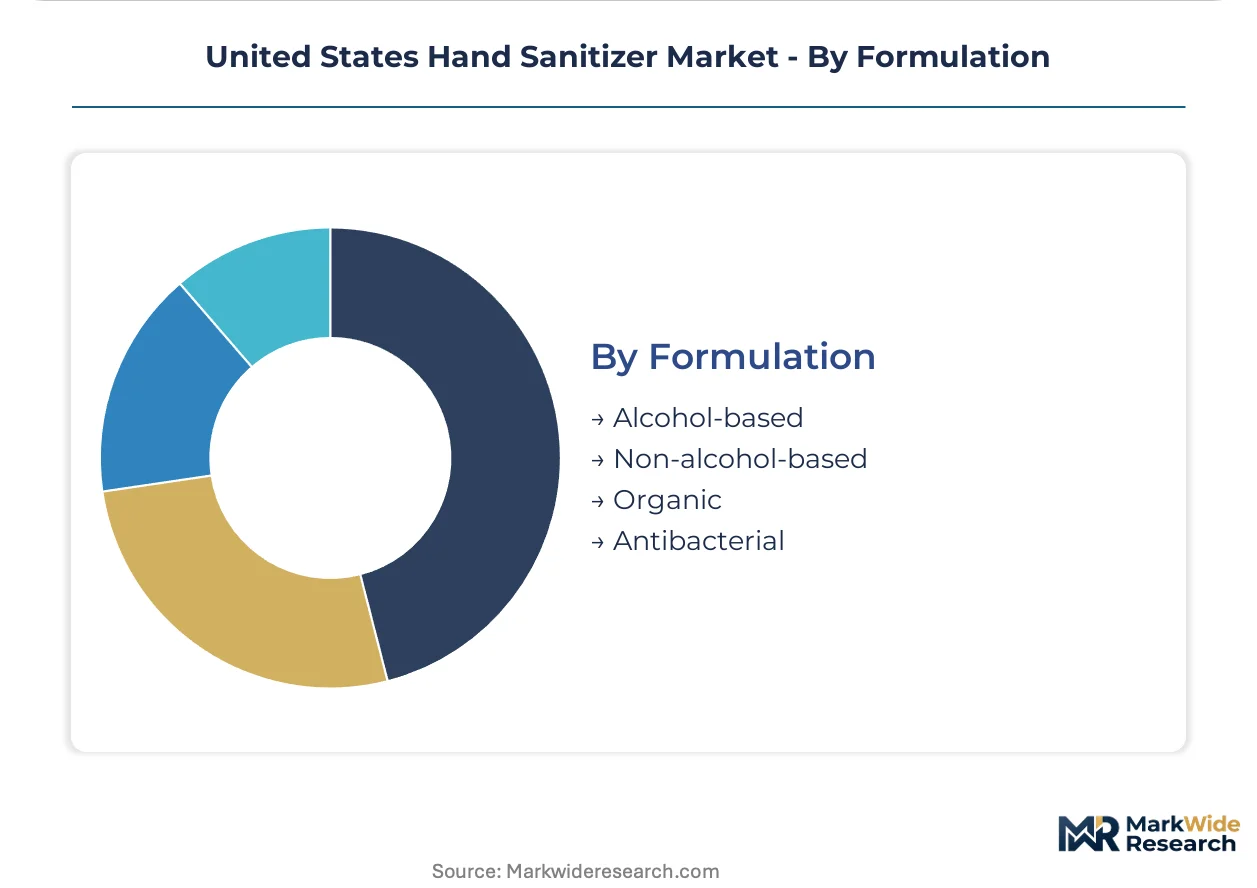
Active ingredient selection determines addressable environments, with alcohol-based formulations excluded from flammability-restricted settings while organic and benzalkonium chloride alternatives carve compliance-driven niches.
- Alcohol-based:Ethanol and isopropanol formulations above 60% concentration dominate hospital procurement following FDA monograph updates on active ingredient thresholds. Gulf Coast petrochemical feedstock disruptions create input cost volatility.
- Non-alcohol-based:Benzalkonium chloride alternatives penetrate correctional facilities and aviation maintenance environments where OSHA and state fire codes block ethanol deployment.
- Organic:Plant-derived ethanol and natural thickeners address sustainability preferences in corporate wellness programs and eco-certified hospitality properties.
- Antibacterial:Triclosan and triclocarban formulations have contracted sharply under FDA enforcement discretion, leaving residual claims to EPA-registered pesticide products.
Alcohol-based formulations anchor volume. Non-alcohol alternatives represent the steepest expansion trajectory as flammability compliance requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over sixty percent of US ethanol production clusters in Iowa and Illinois, exposing coastal formulators to freight cost inflation and rail logistics bottlenecks during harvest season. California and Texas anchor institutional demand through school district contracts and healthcare construction pipelines. State-level mandates create divergent compliance environments across the country.
California
K-12 placement requirements under state health department directives drive volume through multi-year sole-source agreements with integrated hygiene program providers. California mandates the most stringent labeling and accessibility specifications nationwide, forcing distributors to maintain state-specific SKU portfolios. Los Angeles and San Francisco Bay Area school districts consolidate purchasing through cooperative procurement vehicles.
Texas
Houston and Dallas-Fort Worth hospital construction pipelines generate multi-year hygiene supply contracts with bundled audit service potential. Texas school district purchasing cooperatives negotiate directly with manufacturers, bypassing traditional GPOs. State fire codes and OSHA standards limit alcohol-based deployment in correctional facilities, creating openings for non-alcohol alternatives.
New York
State health department enforcement of placement requirements in public facilities creates institutional volume anchors independent of consumer demand fluctuation. New York City municipal procurement consolidates sanitizer supply across agencies, transit authorities, and public housing. Upstate manufacturing presence remains limited, driving inbound logistics costs for regional distributors.
Illinois
Pharmaceutical-grade ethanol production concentration supports captive supply agreements for compounders with sterile filling certification. Chicago-area distribution hubs serve as consolidation points for Midwest institutional buyers. FDA facility inspection backlogs extend qualification timelines for new market entrants seeking to serve regional healthcare systems.
Florida
Hospitality verticals drive IoT-enabled dispenser network deployments with usage analytics creating recurring revenue streams. Miami and Orlando hotel chains specify integrated hygiene programs bundling formulation supply with compliance auditing. State procurement consolidation in education parallels Texas and California models, favoring manufacturers with automated filling lines.
United States Hand Sanitizer Market Key Industry Players
Integrated hygiene program providers and mass-market consumer brands split the market along institutional-versus-household lines. Three strategic archetypes dominate: captive chemical supply specialists with automated dispensing ecosystems, cross-category consumer goods conglomerates with retail shelf dominance, and contract manufacturers serving private-label pharmacy channels. Competitive moves concentrate on direct institutional contracting displacement of traditional distributors and ethanol supply integration through multi-year raw material agreements.
Within the integrated hygiene tier, GOJO Industries and Ecolab exemplify archetypes combining formulation supply with dispenser hardware and compliance services. GOJO anchors the captive supply model through in-house chemical production and automated dispensing ecosystems. Ecolab occupies a parallel position bundling sanitizer with audit services for foodservice and hospitality verticals. Procter & Gamble represents the mass-market vector, competing through cross-category brand leverage in household segments and retail shelf dominance. These three companies illustrate how strategic positioning diverges across institutional and consumer channels without requiring identical capability sets.
| Leading Market Players |
|---|
| GOJO Industries, Inc. |
| Reckitt Benckiser Group plc |
| Procter & Gamble |
| 3M Company |
| Vi-Jon |
| Ecolab Inc. |
| Edgewell Personal Care |
| The Clorox Company |
| Best Sanitizers, Inc. |
| Others |
Cost & Logistics Intelligence
Iowa and Illinois corn-belt ethanol clusters concentrate pharmaceutical-grade alcohol supply, granting captive producers pricing leverage over coastal compounders who absorb freight inflation and rail logistics bottlenecks during harvest cycles. This geographic asymmetry stratifies procurement economics between Midwest manufacturers with backward-integrated feedstock and coastal formulators exposed to input cost volatility.
Pricing Analysis
FDA monograph compliance dictates the pricing tier structure across institutional channels, separating sterile-certified suppliers from contract manufacturers lacking validated filling processes. Three-tier pricing structure across premium institutional, standard commercial, and economy private-label levels reflects certification grade and volume scale differentiation. Pricing pressure stems from bulk procurement consolidation in California and Texas school districts, compressing vendor margins. Education buyers exhibit highest price sensitivity, while healthcare procurement prioritizes compliance documentation over unit cost.
Supply Chain Analysis
Domestic corn-derived ethanol production anchors upstream feedstock supply, drawing from Iowa, Illinois, and Nebraska agricultural processing infrastructure. Isopropanol sourcing hinges on Gulf Coast petrochemical refinery output, creating dual-dependency for alcohol-based formulation. Single-source vulnerability concentrates in sterile filling certification capacity, where FDA inspection backlogs constrain new entrant qualification. Distribution runs through direct institutional contracts displacing traditional GPO intermediaries in high-volume healthcare and education accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States hand sanitizer market functions as a defensive-moat arena where regulatory entrenchment creates durable switching costs. FDA facility certification and state mandate compliance erect qualification barriers that protect incumbent positions.
For Market Incumbents: Entrench through captive ethanol supply integration and automated dispensing ecosystem lock-in. Secure multi-year sole-source agreements with Texas and California purchasing cooperatives before emerging contract manufacturers achieve sterile filling certification. Prioritize IoT-enabled dispenser deployments in hospitality verticals to create usage analytics recurring revenue streams that raise switching costs. For New Entrants and Emerging Players: Establish a beachhead in non-alcohol formulation niches serving correctional facilities and aviation maintenance environments where flammability restrictions block ethanol deployment. Target benzalkonium chloride alternatives for faith-based institutional channels seeking religious compliance. Pursue white-label pharmacy partnerships as a lower-barrier volume entry point bypassing sterile filling certification queues. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated hygiene program providers with bundled formulation-dispenser-service capabilities over standalone compounders. Five-to-ten year viability concentrates in manufacturers with captive chemical supply and automated filling infrastructure. Monitor FDA enforcement discretion timelines and state bulk procurement consolidation patterns as inflection signals for volume shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Ethanol Supply Integration | Backward integration into Iowa and Illinois corn-belt production locks in raw material cost stability against Gulf Coast petrochemical volatility. |
| Sterile Filling Certification Investment | FDA facility qualification enables hospital procurement department requalification cycles following updated monograph thresholds. |
| IoT-Enabled Dispenser Network Deployment | Usage analytics platforms create recurring revenue streams and switching cost barriers in corporate campus and hospitality verticals. |
| Non-Alcohol Formulation Development | Benzalkonium chloride alternatives penetrate correctional and aviation channels where OSHA and state fire codes restrict ethanol deployment. |
| Direct Institutional Contracting | Manufacturer-direct sales teams displace traditional GPOs in Texas and Florida school district purchasing cooperatives. |
Research Approach
The analysis maps gel, foam, liquid, and spray formulation sub-sectors, each validated through procurement directors at hospital systems, K-12 facility managers, and foodservice hygiene coordinators. Primary interviews with GPO contracts managers, ethanol supply specialists, and FDA regulatory consultants combined with secondary validation from FDA enforcement discretion documents, state health department mandate filings, and SEC 10-K disclosures from listed manufacturers. Bottom-up volume triangulation across end-user segments reconciled with top-down market sizing.
Assumptions held fixed include FDA monograph compliance requirements and state-level placement mandates, while ethanol feedstock pricing and sterile filling capacity expansion varied across scenarios. Segmentation dimensions modeled encompass product format, distribution channel, end-user environment, and active ingredient classification. CAGRs derived from volume trajectory analysis against pricing trend normalization. Forecast inputs incorporated hospital construction pipeline data and school district procurement consolidation patterns.
Sensitivities concentrate around FDA enforcement discretion timeline extensions and Gulf Coast petrochemical supply disruptions. Forecasts reflect documented assumptions regarding regulatory compliance stability and institutional procurement digitization rates. Cross-checking against state health department contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Virus Filtration Market
Infection Control
Botulism Market
Infection Control
Medical Activated Carbon Dressing Market
Infection Control
Global Biofilms Treatment Market
Infection Control
Surgical Site Infections Market
Infection Control
Antiseptic Bathing Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market
Infection Control
Ear Infection Treatment Market
Infection Control
Hospital Acquired Infections Therapeutic Market
Infection Control
North America Hand Sanitizer Market
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Staphylococcal Infection Treatment Market
Infection Control
Sterility Indicators Market
Infection Control
UV Sterilizer Pouch Market
Infection Control
Global Hospital Infection Therapeutics Market
Infection Control
Disinfection Equipment Market