
 Infection Prevention Market | 2026-2036
Infection Prevention Market Size, Share, and Industry Trends Forecast 2026-2036
Infection Prevention Market Outlook
Hospital supply chain restructuring is reshaping how infection prevention products reach end users. STERIS leverages its installed base of sterilization equipment to sustain long-term service contracts with major health systems. Ecolab competes through its integrated water and hygiene platform that anchors recurring revenue in acute care facilities. Getinge AB specializes in advanced sterilization modalities for complex surgical instruments, differentiating its portfolio from commodity disinfectant suppliers.
Infection prevention encompasses antiseptics, disinfectants, sterilization equipment, and personal protective equipment designed to eliminate or reduce pathogenic microorganisms in healthcare and commercial environments. Ethylene oxide and vaporized hydrogen peroxide sterilization systems operate at precise temperature and pressure parameters to achieve sterility assurance levels of 10^-6 for surgical instruments and implantable devices. Sterilization equipment commands the highest capital investment per unit and generates substantial aftermarket revenue through preventive maintenance and consumable cycles. Hand hygiene applications within the product type dimension represent the most frequently repeated intervention, creating volume-driven margin pools distinct from the equipment-intensive sterilization segment.
The FDA enforces stringent reprocessing validation requirements under its 510(k) clearance pathway for reusable devices, while the EPA regulates disinfectant efficacy claims through its Emerging Viral Pathogen guidance framework. OSHA's Bloodborne Pathogens Standard mandates employer-provided PPE and exposure control plans, directly institutionalizing demand for gloves, gowns, and face protection across healthcare employers. Stakeholders must monitor evolving EPA List Q designations and state-level surgical smoke evacuation mandates as these regulatory vectors will determine which product categories face accelerated replacement cycles versus incremental compliance burdens.
Market Dynamics
Health system consolidation is compressing vendor relationships and standardizing infection control protocols across integrated delivery networks, forcing suppliers to restructure around enterprise service agreements rather than transactional equipment sales.
Growth Catalysts
- Surgical volume rebound:Elective procedure normalization across North American hospitals is accelerating capital deployment for sterilization infrastructure. Health systems are prioritizing redundant sterilization capacity to address backlog clearance.
- FDA reprocessing guidance:Updated 510(k) validation requirements for reusable devices are compelling hospitals to upgrade legacy sterilization systems. This regulatory vector sustains replacement demand regardless of macroeconomic conditions.
- Vaporized hydrogen peroxide modality:Low-temperature sterilization technology is penetrating complex instrument categories including flexible endoscopes and robotic surgical platforms. Adoption concentrates in tertiary referral centers performing minimally invasive procedures.
Market Restraints
- Ethylene oxide regulatory pressure:EPA emissions scrutiny and community opposition in the United States are constraining EtO sterilization capacity. Medical device manufacturers face supply risk for heat-sensitive implants.
- Capital intensity barrier:Automated washer-disinfector and sterilizer installations require substantial facility infrastructure investment. Smaller ambulatory surgical centers defer upgrades due to balance sheet constraints.
- Consumable cost volatility:Hydrogen peroxide sterilant and chemical indicator pricing fluctuates with industrial chemical feedstock markets. Hospital supply chains struggle to pass through input cost swings under fixed-price contracts.
Strategic Opportunities
- Outpatient migration:Ambulatory surgery center expansion in the United States creates demand for compact, rapid-cycle sterilization systems. Vendors can displace manual high-level disinfection with automated alternatives.
- Service contract penetration:Preventive maintenance and remote monitoring subscriptions represent underdeveloped revenue pools. Equipment OEMs can capture lifetime value through predictive service models.
- State surgical smoke mandates:Evacuation system requirements in California, Colorado, and Illinois are institutionalizing demand for integrated operating room air handling. This regulatory tailwind extends to filtration and HVAC-adjacent infection control.
Industry Challenges
- Sterile processing technician shortage:Certification bottlenecks and wage competition from acute care nursing are constraining hospital staffing. Automated documentation systems face adoption friction where technical literacy gaps persist.
- Legacy equipment interoperability:New sterilization systems must integrate with hospital information systems and instrument tracking databases. Interface standardization delays extend implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infection Prevention Market |
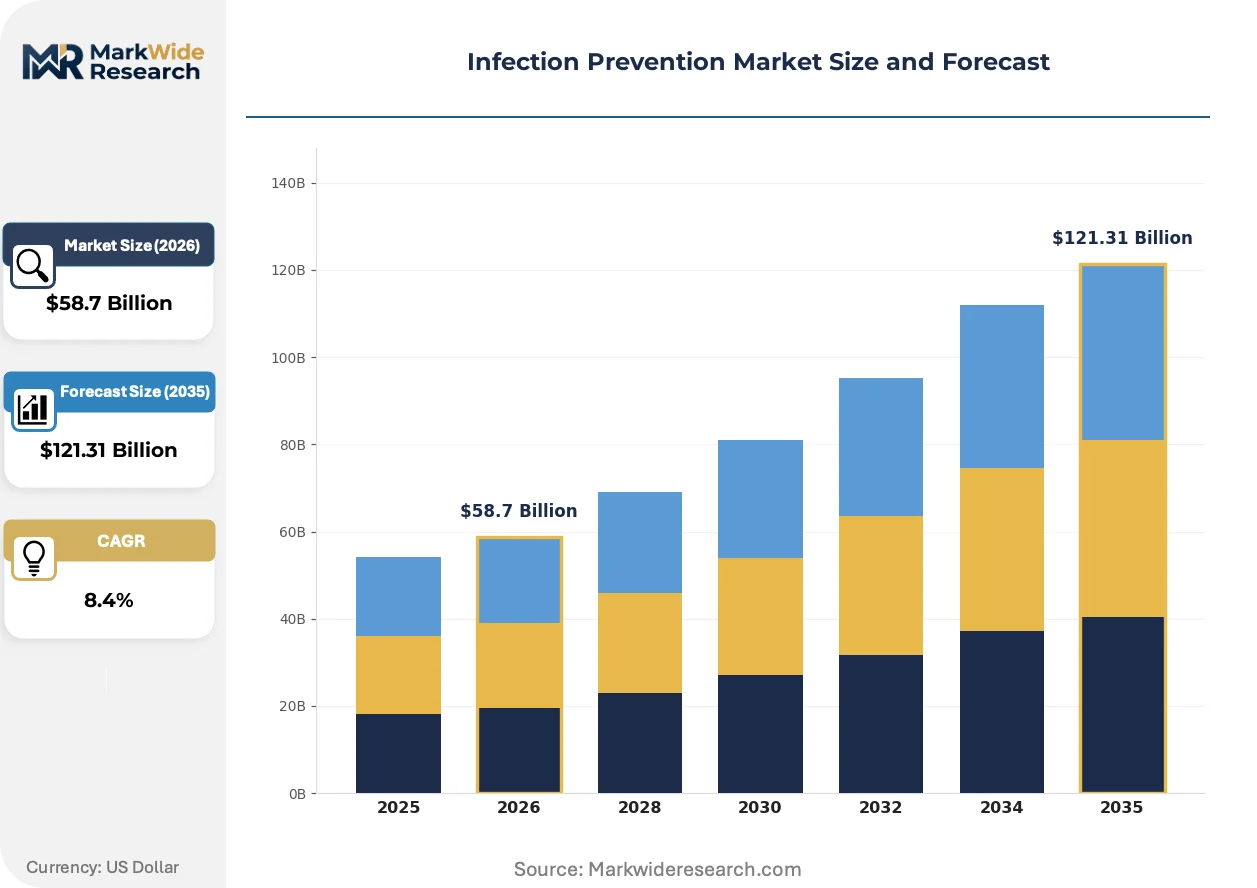
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiseptics, Disinfectants, Sterilization Equipment, Personal Protective Equipment End User: Hospitals, Clinics, Long-term Care Facilities, Homecare Settings Application: Surface Disinfection, Hand Hygiene, Instrument Sterilization, Environmental Cleaning Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | STERIS, 3M, Getinge AB, Ecolab, Fortive, Sotera Health, Belimed AG, Cantel Medical, MMM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infection Prevention Market Strategic Shifts
Automation and connectivity are converging to transform sterile processing from a manual, compliance-driven function into a data-integrated clinical service line with measurable throughput and quality metrics.
Radio-frequency identification is digitizing instrument tracking throughout reprocessing workflows. Academic medical centers and large health systems are deploying RFID-enabled cabinets and automated dispensing systems to eliminate manual count sheets and reduce retained foreign object risk. This technology is digitizing asset utilization data, enabling predictive maintenance scheduling and capital planning optimization.
The EPA Emerging Viral Pathogen guidance framework is accelerating disinfectant efficacy testing protocols. Manufacturers must now submit data against SARS-CoV-2, influenza, and norovirus surrogates to maintain List Q eligibility. Hospital environmental services departments are reformulating chemistries and application protocols, with acute care facilities in the United States leading compliance adoption.
Consolidated procurement through group purchasing organizations is compressing vendor margins and standardizing product formularies. Integrated delivery networks are unbundling equipment, consumables, and service contracts to optimize total cost of ownership. This concentration is most visible in the United States, where three GPOs control procurement for the majority of hospital beds and are extracting price concessions through exclusive sourcing agreements.
Infection Prevention Market Segmentation
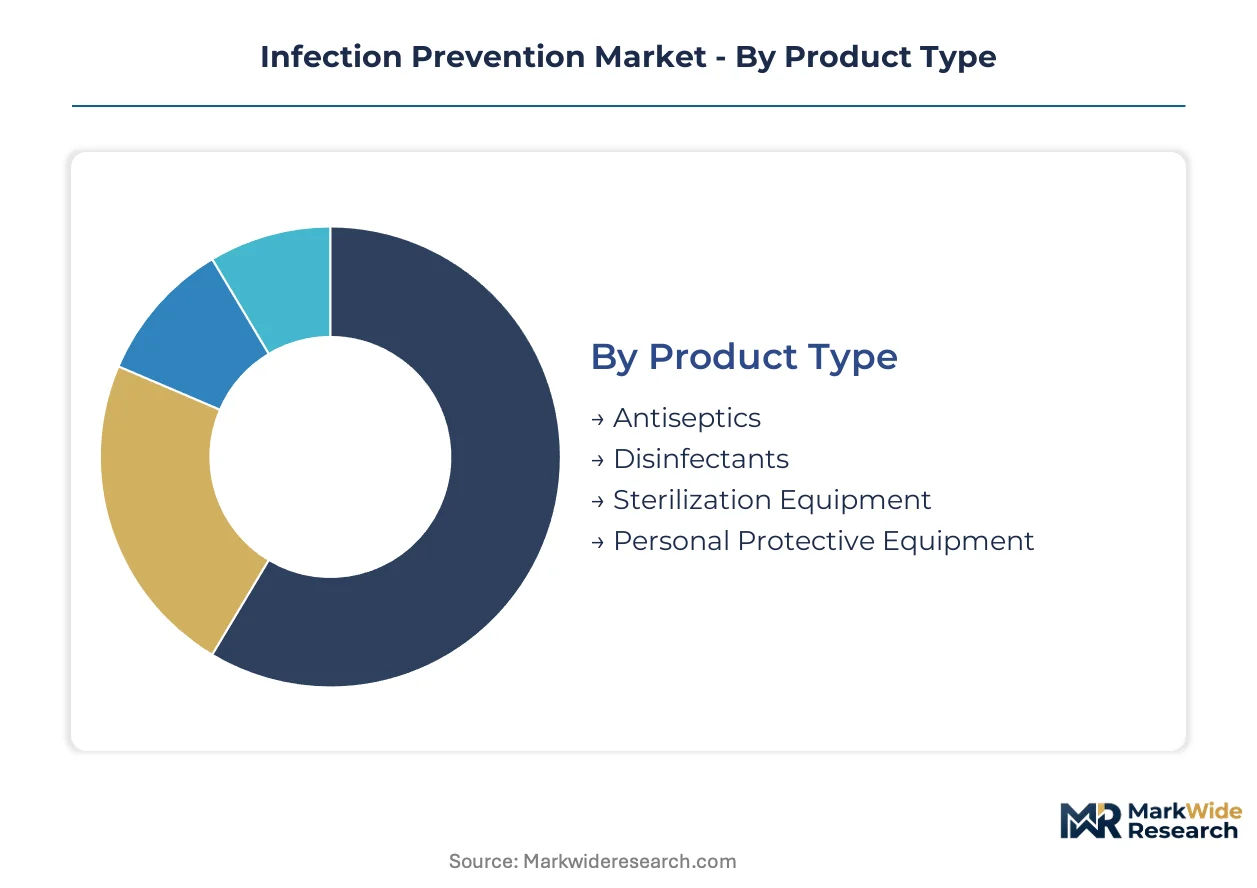
Infection prevention markets fragment across clinical workflows, procurement channels, and care settings. Each segmentation dimension reveals distinct margin structures, regulatory exposure, and vendor competitive dynamics that determine capital allocation and partnership strategies.
Product Type:
Use-case spectrum spans episodic surface treatment through capital-intensive sterilization infrastructure, with revenue recurrence and technical barriers varying dramatically across the four product classes.
- Sterilization Equipment:Capital systems including steam, ethylene oxide, and vaporized hydrogen peroxide modalities operate under FDA 510(k) validation requirements. Tertiary hospitals in the United States anchor procurement volume as surgical backlogs drive redundant capacity installation.
- Disinfectants:EPA-registered chemistries for surface and instrument reprocessing face accelerated efficacy testing under Emerging Viral Pathogen guidance. Acute care facilities concentrate demand for sporicidal and emerging pathogen claims.
- Antiseptics:Skin preparation and surgical site solutions with persistent antimicrobial activity.
- Personal Protective Equipment:Gloves, gowns, and face protection institutionalized through OSHA Bloodborne Pathogens Standard mandates.
The dominant share belongs to Disinfectants, while Sterilization Equipment is closing the gap fastest.
End User:
Customer archetypes distribute across facility scale, acuity mix, and procurement sophistication, with integrated delivery networks compressing vendor relationships at the top of the pyramid.
- Hospitals:Acute care systems command the highest per-bed infection prevention spend, driven by surgical volume, regulatory scrutiny, and liability exposure. Health system consolidation in the United States is standardizing protocols across IDNs and favoring enterprise service agreements over transactional purchasing.
- Clinics:Ambulatory surgery centers and specialty practices represent the steepest expansion trajectory as outpatient migration accelerates. Compact rapid-cycle sterilization systems displace manual high-level disinfection in these settings.
- Long-term Care Facilities:Skilled nursing and assisted living with heightened vulnerability to multidrug-resistant organism transmission.
- Homecare Settings:Dialysis, infusion therapy, and wound care performed in residential environments.
Hospitals retain the largest revenue footprint, though Clinics are gaining share fastest.
Application:
Intervention frequency and technical complexity diverge sharply across the four application modes, from continuous hand hygiene through episodic environmental terminal cleaning.
- Hand Hygiene:The most repeated intervention in healthcare delivery, creating volume-driven consumable demand distinct from capital-intensive segments. Alcohol-based rubs and surgical scrubs dominate hospital formulary compliance monitoring.
- Instrument Sterilization:Reprocessing workflows for surgical devices require validated sterilization assurance levels. FDA reprocessing guidance sustains replacement demand for legacy system upgrades regardless of macroeconomic conditions.
- Surface Disinfection:Environmental services application of EPA-registered chemistries across patient care areas.
- Environmental Cleaning:Terminal disinfection and HVAC-adjacent air handling interventions.
Hand Hygiene generates the highest transaction velocity, while Instrument Sterilization commands the steepest expansion trajectory.
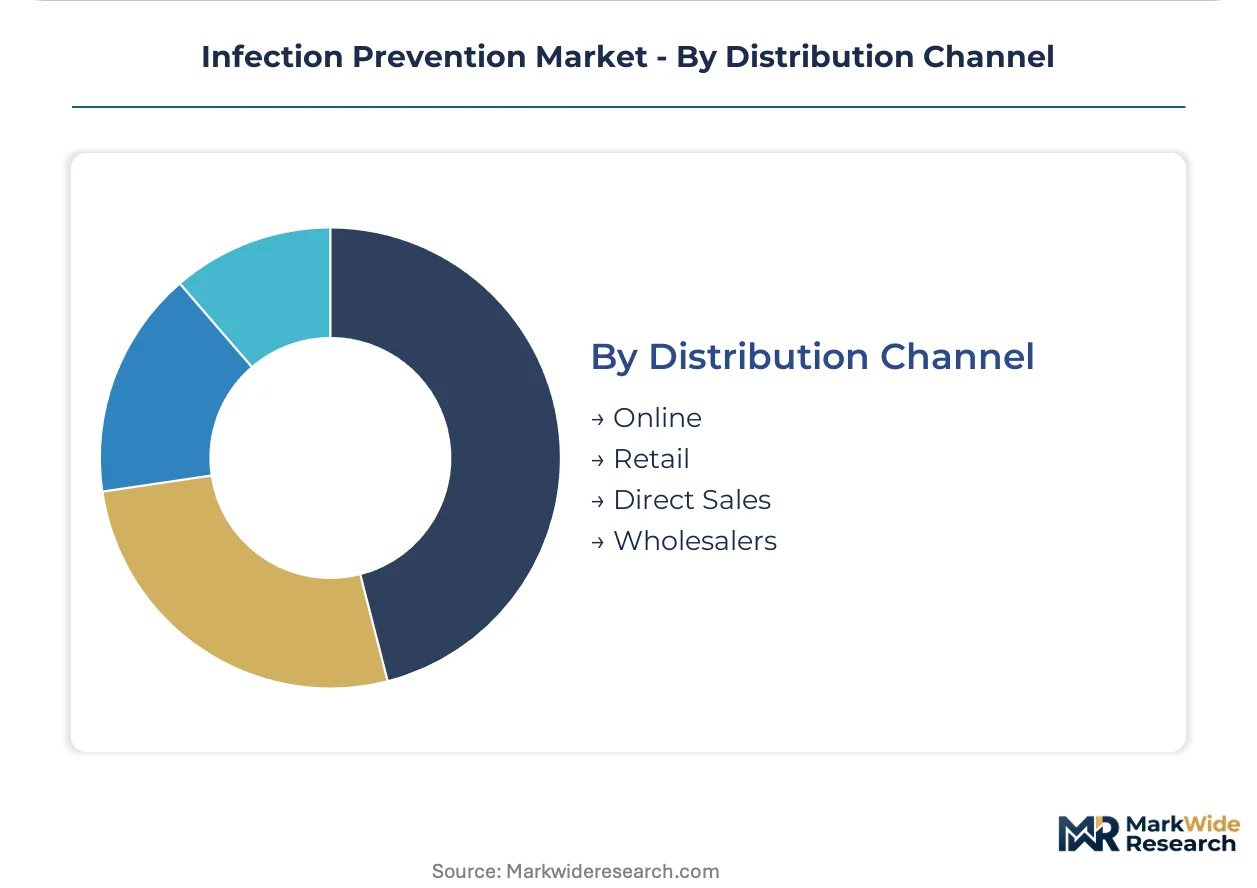
Distribution Channel:
Channel economics reflect contract structures, inventory carrying costs, and technical service requirements that vary by product complexity and customer scale.
- Direct Sales:Capital equipment and enterprise consumable contracts route through manufacturer field organizations. Sterilization system OEMs leverage installed base relationships for preventive maintenance subscriptions and remote monitoring services.
- Wholesalers:Distributor networks handle high-velocity consumables and PPE for fragmented clinic and long-term care accounts. Group purchasing organization aggregation concentrates procurement power in the United States.
- Online:E-commerce platforms serving smaller ambulatory and homecare purchasers with standardized products.
- Retail:Pharmacy and medical supply storefronts for consumer-directed infection prevention products.
Direct Sales captures the premium equipment and service value pool, though Wholesalers are expanding fastest as GPO consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany, where health system consolidation and surgical volume density enable premium equipment procurement, while cost-sensitive markets in India and Brazil compress margins on consumable-heavy portfolios.
United States
Integrated delivery networks standardize infection control protocols across multi-hospital systems, concentrating procurement through three dominant group purchasing organizations. FDA reprocessing guidance under its 510(k) pathway sustains replacement demand for legacy sterilization systems regardless of macroeconomic conditions. The Boston-Cambridge corridor anchors medical device innovation clusters where vaporized hydrogen peroxide sterilization technology penetrates robotic surgical platforms.
Germany
Precision manufacturing demand for validated sterilization assurance levels drives capital investment in advanced sterilization modalities. ECHA chemical safety assessments and MDR compliance requirements elevate technical barriers for disinfectant suppliers. The Baden-Württemberg region concentrates sterile processing equipment engineering, with Stuttgart-area firms specializing in automated washer-disinfector systems for complex surgical instruments.
China
Hospital infrastructure expansion in tier-two and tier-three cities accelerates deployment of steam sterilization capacity for surgical volume growth. NMPA medical device registration requirements and GB standards for sterilization equipment create compliance-driven replacement cycles. The Yangtze River Delta cluster around Shanghai hosts domestic sterilization equipment manufacturers scaling production for provincial hospital procurement tenders.
Japan
Aging surgical populations and minimally invasive procedure adoption sustain demand for low-temperature sterilization systems compatible with flexible endoscopes. PMDA quality management system inspections enforce stringent validation documentation for reusable device reprocessing. The Chubu region around Nagoya concentrates precision sterilization equipment component suppliers serving domestic and export markets.
India
Private hospital chain expansion and medical tourism infrastructure investment drive sterilization equipment procurement in metropolitan markets. CDSCO medical device rules and BIS certification requirements for sterilizers create regulatory compliance costs that favor established equipment suppliers. The Maharashtra-Gujarat industrial corridor hosts contract sterilization service providers scaling ethylene oxide and gamma irradiation capacity for export-oriented medical device manufacturers.
Infection Prevention Market Competitive Environment
Equipment-centric sterilization specialists and integrated hygiene platforms split the market along capital intensity and service recurrence vectors. Tier-one suppliers leverage installed base relationships for preventive maintenance subscriptions, while regional equipment fabricators compete on price for greenfield hospital installations. Strategic archetypes include sterilization modality specialists, integrated water-hygiene platforms, and contract sterilization service operators. Consolidation concentrates through health system enterprise agreements and GPO-exclusive sourcing arrangements, while technology licensing partnerships accelerate vaporized hydrogen peroxide system deployment.
Within the integrated platform tier, STERIS and Ecolab occupy positions that exemplify divergent recurring revenue models—equipment lifecycle services versus consumable-intensive hygiene programs. Getinge AB represents the sterilization modality specialist archetype, with its corporate structure reflecting Swedish industrial engineering heritage. These three entities anchor competitive dynamics across health system procurement channels, with each exemplifying distinct strategic postures toward service contract penetration and geographic market prioritization.
| Leading Market Players |
|---|
| STERIS |
| 3M |
| Getinge AB |
| Ecolab |
| Fortive |
| Sotera Health |
| Belimed AG |
| Cantel Medical |
| MMM Group |
| Others |
Value Chain & Pricing Dynamics
Ethylene oxide sterilization undercapacity in the United States is compressing contract sterilization pricing while elevating vaporized hydrogen peroxide system premiums. Utilization rates above 85% in legacy EtO facilities are forcing medical device manufacturers toward alternative modalities, reshaping both supplier capacity investments and hospital procurement negotiations.
Pricing Analysis
The customization-premium spread separates configured-to-order sterilization systems from standard steam sterilizer SKUs by 40-60% at list price. Pricing stratifies across FDA-validated premium tiers, CE-marked standard configurations, and economy steam sterilizers for emerging markets. Price differentiation hinges on sterility assurance documentation and remote monitoring integration. Cost compression in the economy tier is intensifying because Chinese manufacturers are scaling washer-disinfector exports. Ambulatory surgery centers exhibit the highest price sensitivity, while academic medical centers prioritize throughput metrics over capital cost.
Supply Chain Analysis
Contract manufacturing concentration sits with STERIS and Getinge AB for sterilization equipment final assembly, alongside Foxconn-affiliated EMS providers for control system electronics. Component sourcing draws from Germany for precision pressure vessels, China for stainless steel fabrication, and Japan for sensor modules. Raw material dependencies include surgical-grade stainless steel, hydrogen peroxide sterilant, and ethylene oxide gas. Single-source vulnerability concentrates in vaporized hydrogen peroxide generator subassemblies. Distribution runs through manufacturer direct sales for capital equipment and wholesaler networks for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States, where three group purchasing organizations now control procurement for the majority of acute care beds.
For Market Incumbents: Insulate installed base relationships through predictive maintenance subscriptions and remote sterilizer monitoring. Extend backward integration into hydrogen peroxide sterilant production to capture margin pools currently held by chemical suppliers. FDA reprocessing guidance updates threaten legacy system compatibility, making certification investment the critical defensive lever. For New Entrants and Emerging Players: Mid-market ambulatory surgery centers in the United States represent the most penetrable entry point, as these facilities lack capital for tier-one sterilization platforms and tolerate longer implementation timelines. Compact rapid-cycle sterilizers displacing manual high-level disinfection in outpatient settings offer the clearest white-space opportunity. A service-contract-first go-to-market angle bypasses capital purchase committees and establishes recurring revenue footholds. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across sterilization equipment as software and service revenue expands as a share of OEM economics. Viable acquisition targets include RFID-enabled instrument tracking specialists and contract sterilization service operators with EPA-compliant EtO capacity. The signal to watch is EPA emissions enforcement actions, which will accelerate capacity retirement and concentrate pricing power among compliant operators.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Enterprise service agreements with IDNs lock out competitors through multi-year sterilization equipment and consumable bundles. |
| FDA 510(k) Submission | Novel sterilization modalities require validation documentation for reusable device reprocessing clearance. |
| Software Companion Development | Sterilizer remote monitoring platforms enable predictive maintenance subscriptions and instrument tracking integration. |
| CE Marking Pathway | MDR compliance for sterilization equipment opens European hospital procurement channels. |
| Reimbursement Strategy | Surgical site infection reduction protocols tie sterilization quality metrics to value-based care contracts. |
Study Parameters
Desk research of FDA 510(k) filings, EPA disinfectant registration databases, and hospital procurement contract disclosures preceded structured interviews with sterile processing directors, biomedical engineers, GPO contracts managers, and sterilization equipment service technicians. Secondary validation drew from CMS Medicare cost reports, AAMI sterilization standards documentation, and SEC 10-K equipment revenue disclosures. Bottom-up demand modeling triangulated against top-down health system capital expenditure surveys.
Assumptions held surgical volume recovery trajectories and EPA emissions enforcement timelines fixed across scenarios, while vaporized hydrogen peroxide adoption rates and health system consolidation pace were varied. The analytical framework segmented by sterilization modality, end-user facility scale, and application workflow across the projection horizon. CAGRs were derived from installed base replacement cycles and outpatient migration patterns. Forecast inputs included FDA reprocessing guidance implementation timelines and state-level surgical smoke mandate adoption curves.
Practitioners should monitor EPA List Q disinfectant designation updates and ethylene oxide facility emission enforcement actions for early signals of supply disruption or compliance cost inflation. Quarterly review of GPO contract renewal volumes and sterilization equipment backlog data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Salivary Gland Infection Market
Infection Control
Middle East and Africa Hand Sanitizer Market
Infection Control
Global Viral Clearance Services Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Infection Control Surveillance Solutions Market
Infection Control
Healthcare Protective Masks Market
Infection Control
Yeast Infection Market
Infection Control
Preventable Vaccines Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Healthcare Associated Infections (HAI) Treatment Market
Infection Control
Ultraviolet Disinfection Equipment Market
Infection Control
Sterility Indicators Market
Infection Control
Botulism Market
Infection Control
Surgical Site Infections Market
Infection Control
Global Skin Antiseptic Products Market
Infection Control
Disinfection Equipment Market