
 Catheter Coatings Market | 2026-2036
Catheter Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Catheter Coatings Market Analysis
Polyvinylpyrrolidone is shifting from peripheral use to primary hydrophilic matrix status as manufacturers seek lower-friction alternatives to legacy silicone platforms. B. Braun Melsungen AG anchors its European catheter supply through captive coating operations in Melsungen and Penang. Royal DSM leverages its biomedical-grade polymer portfolio to supply coating resins across multiple catheter OEMs. Surmodics, Inc. specializes in surface modification chemistries for neurovascular and coronary applications where lubricity thresholds are most demanding.
Catheter coatings constitute thin functional layers applied to polymer or metal substrates to reduce friction, prevent thrombosis, inhibit microbial colonization, or enable localized drug release; typical formulations incorporate 2-5 micrometer thicknesses of hydrophilic polymers, silver-ion complexes, or paclitaxel matrices deposited via dip-coating or spray processes. Hydrophilic coatings dominate current procurement volumes due to their established efficacy in reducing insertion trauma across cardiology and urology procedures. Antimicrobial formulations are gaining specification share as hospital-acquired infection protocols tighten, though drug-eluting platforms command the highest unit margins in oncology and peripheral vascular segments. Application-area segmentation reveals cardiology as the most mature demand pool, while gastroenterology represents an emerging frontier for lubricious coating adoption.
The FDA enforces biocompatibility and sterility standards under 21 CFR Part 820 quality system regulations, while the EU Medical Device Regulation mandates clinical evidence for coated devices exceeding Class I risk classifications. ISO 10993 biological evaluation protocols shape premarket testing requirements across both jurisdictions, directly influencing coating formulation choices and validation timelines. Stakeholders must monitor evolving antimicrobial resistance surveillance data and corresponding regulatory restrictions on silver-based coatings to anticipate specification shifts before they disrupt existing supply agreements.
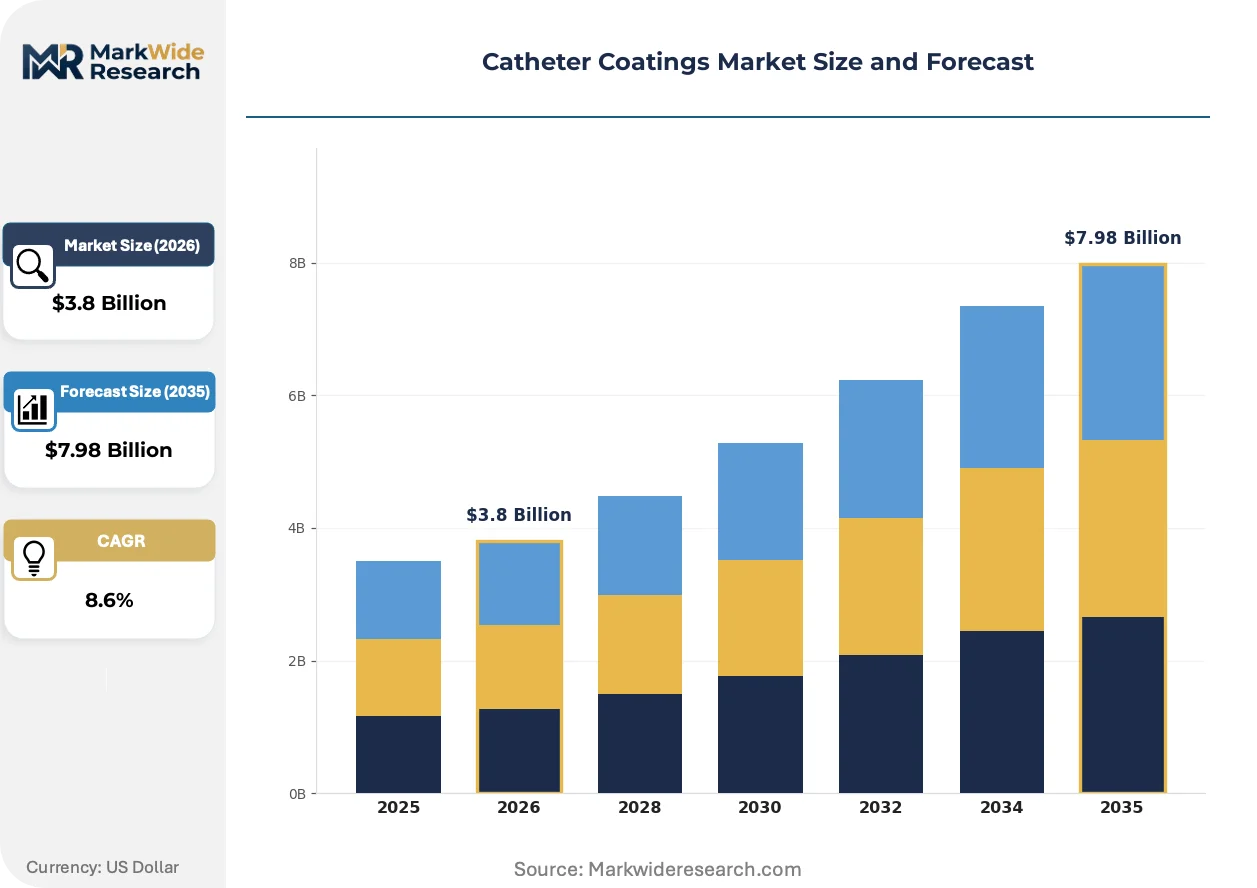
Market Dynamics
FDA's renewed scrutiny of antimicrobial coating biocompatibility profiles is compressing reformulation timelines and forcing catheter OEMs to accelerate validation cycles before commercial release. This regulatory pressure is reshaping R&D resource allocation across hydrophilic, antimicrobial, and drug-eluting coating platforms.
Growth Catalysts
- Complex percutaneous procedure expansion:Interventional cardiology departments in tertiary hospitals are multiplying device utilization rates as patient eligibility criteria broaden for minimally invasive interventions.
- 21 CFR Part 820 quality system enforcement:FDA's tightened sterility documentation requirements are elevating coating vendor qualification thresholds, favoring suppliers with validated manufacturing processes.
- Lake Constance OEM clustering:German catheter manufacturing concentration around this region is generating specification intensity that propagates advanced coating standards across European supply chains.
Market Restraints
- Silver-ion input cost volatility:Antimicrobial coating feedstock prices fluctuate with precious metal markets, compressing margins on standardized hospital procurement contracts.
- Biocompatibility testing bottlenecks:ISO 10993 protocol completion timelines extend premarket submission windows, delaying revenue recognition for reformulated products.
- Legacy silicone platform entrenchment:Established manufacturing lines and clinician familiarity create switching friction against polyvinylpyrrolidone alternatives despite superior lubricity metrics.
Strategic Opportunities
- Gastroenterology lubricious coating adoption:Endoscopic procedure volume expansion is opening specification pathways previously dominated by cardiology and urology segments.
- EU MDR clinical evidence pathways:Class IIa and IIb coated device classification requirements create consultative service opportunities for coating vendors with regulatory affairs capabilities.
- Drug-eluting oncology catheter convergence:Paclitaxel matrix deposition expertise from peripheral vascular applications is transferring to localized chemotherapy delivery platforms.
Industry Challenges
- Surface chemistry PhD talent scarcity:Coating formulation groups compete with pharmaceutical and biotechnology sectors for specialized polymer scientists, elongating hiring cycles.
- Dual jurisdiction validation costs:Simultaneous FDA 510(k) and EU MDR technical documentation preparation strains mid-tier coating operations without dedicated regulatory staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catheter Coatings Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Hydrophilic, Antimicrobial, Drug-Eluting, Silicone Application Area: Cardiology, Urology, Gastroenterology, Oncology End User: Hospitals, Clinics, Long-term Care Facilities, Home Healthcare Material: Polyurethane, Polyethylene, PVC, Nylon |
| Companies Covered | B. Braun Melsungen AG, Royal DSM, Surmodics, Inc., Biocoat Incorporated, Specialty Coating Systems Inc., Hydromer, Polyone Corporation, Covalon OEM Technologies, LipoCoat BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catheter Coatings Market Emerging Trajectories
Coating functionality is migrating beyond passive lubricity toward active therapeutic delivery and infection prevention, driven by procedural complexity and hospital-acquired infection protocol intensification.
Polyvinylpyrrolidone is integrating into primary hydrophilic matrices as manufacturers abandon legacy silicone platforms for lower-friction alternatives in neurovascular and coronary access devices. Tertiary hospital interventional suites are specifying these platforms for tortuous anatomy navigation where insertion trauma reduction proves critical. The technology is integrating antimicrobial and drug-eluting capabilities into unified deposition processes, collapsing separate manufacturing steps into single-line operations.
EU MDR clinical evidence requirements for Class IIa and above coated devices are mandating biocompatibility validation beyond previous CE marking self-certification thresholds. Coating vendors must now sponsor or collaborate on clinical investigations to support OEM technical documentation, shifting cost structures toward post-market surveillance commitments. Peripheral vascular and oncology catheter segments face the steepest compliance burden due to prolonged patient contact duration and drug substance integration.
Hospital procurement committees are consolidating supplier relationships around coating vendors with integrated regulatory affairs and clinical evidence generation capabilities. Single-source agreements are displacing fragmented multi-vendor purchasing for hydrophilic and antimicrobial platforms, concentrating volume among full-service suppliers. Germany's Lake Constance catheter manufacturing corridor exhibits this consolidation most visibly, as OEMs prioritize coating partners with validated EU MDR technical files over price-competitive alternatives.
Catheter Coatings Market Segmentation
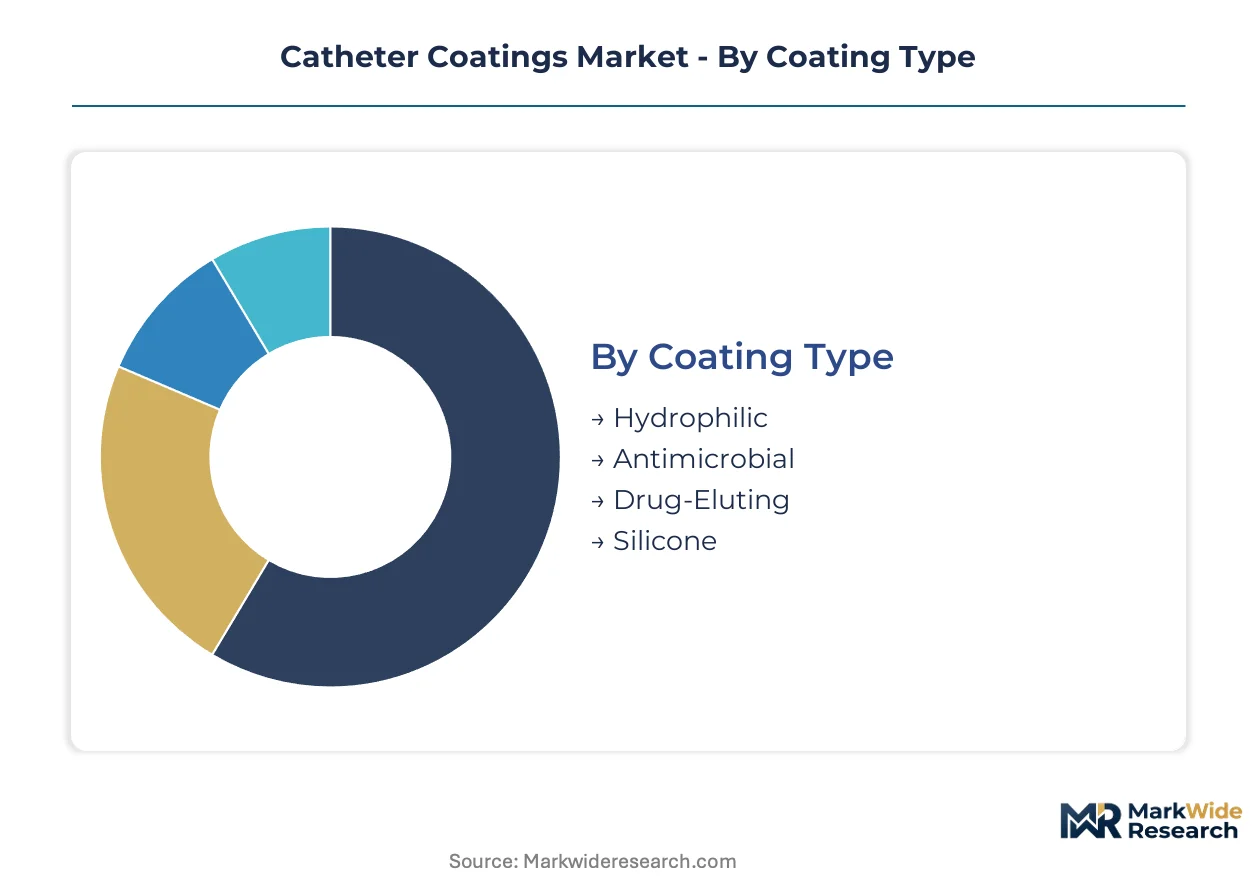
Catheter coating specifications diverge sharply by procedural environment and substrate compatibility, creating distinct procurement channels that reward specialized formulation capabilities over generic supply. Understanding these segment boundaries clarifies where coating vendors must build technical depth versus where commoditized supply suffices.
Coating Type:
Integration depth varies: hydrophilic and silicone coatings function as standalone lubricity layers, while antimicrobial and drug-eluting platforms embed active agents requiring sustained-release engineering.
- Hydrophilic:Polyvinylpyrrolidone matrices deposited at 2-5 micrometer thickness deliver friction coefficients below 0.05 for neurovascular navigation. Tertiary hospital interventional cardiology suites in Germany specify these platforms for tortuous anatomy access where insertion trauma reduction proves critical.
- Antimicrobial:Silver-ion complexes or quaternary ammonium compounds inhibit biofilm formation on indwelling devices. FDA's renewed biocompatibility scrutiny is compressing reformulation timelines for hospital-acquired infection protocols, particularly in US acute care settings.
- Drug-Eluting:Paclitaxel or sirolimus matrices enable localized therapeutic delivery in peripheral vascular oncology applications.
- Silicone:Legacy polydimethylsiloxane platforms persist in cost-sensitive urology segments despite higher friction coefficients.
Volume placements concentrate in Hydrophilic; the faster expansion belongs to Drug-Eluting.
Application Area:
Procedure complexity and reimbursement intensity shape coating specification tiers, with cardiology demanding the most sophisticated multi-functional platforms.
- Cardiology:Complex percutaneous coronary interventions require combined hydrophilic-antimicrobial coatings with hemocompatibility validation under ISO 10993-4. German Lake Constance OEM clusters drive the most advanced specification intensity for these platforms.
- Urology:Intermittent and indwelling catheters utilize standardized hydrophilic or silicone coatings with antimicrobial overlays for recurrent infection management.
- Gastroenterology:Endoscopic accessories represent an emerging frontier for lubricious coating adoption as procedure volumes expand.
- Oncology:Localized chemotherapy delivery via drug-eluting platforms commands premium unit margins in peripheral vascular segments.
Revenue concentration sits with Cardiology; Gastroenterology is gaining share fastest.
End User:
Procurement sophistication and sterilization infrastructure determine coating performance requirements across care settings.
- Hospitals:Tertiary academic medical centers specify multi-functional coatings with full ISO 10993 biocompatibility dossiers and EU MDR technical documentation. These institutions consolidate supplier relationships around vendors with integrated regulatory affairs capabilities.
- Clinics:Ambulatory surgical centers prioritize hydrophilic platforms for same-day discharge procedures with streamlined sterilization protocols.
- Long-term Care Facilities:Antimicrobial-coated indwelling catheters dominate procurement for infection prevention in extended-duration use.
- Home Healthcare:Self-catheterization products favor pre-lubricated hydrophilic platforms with intuitive handling characteristics.
Specification intensity peaks in Hospitals; Home Healthcare shows the steepest volume climb.
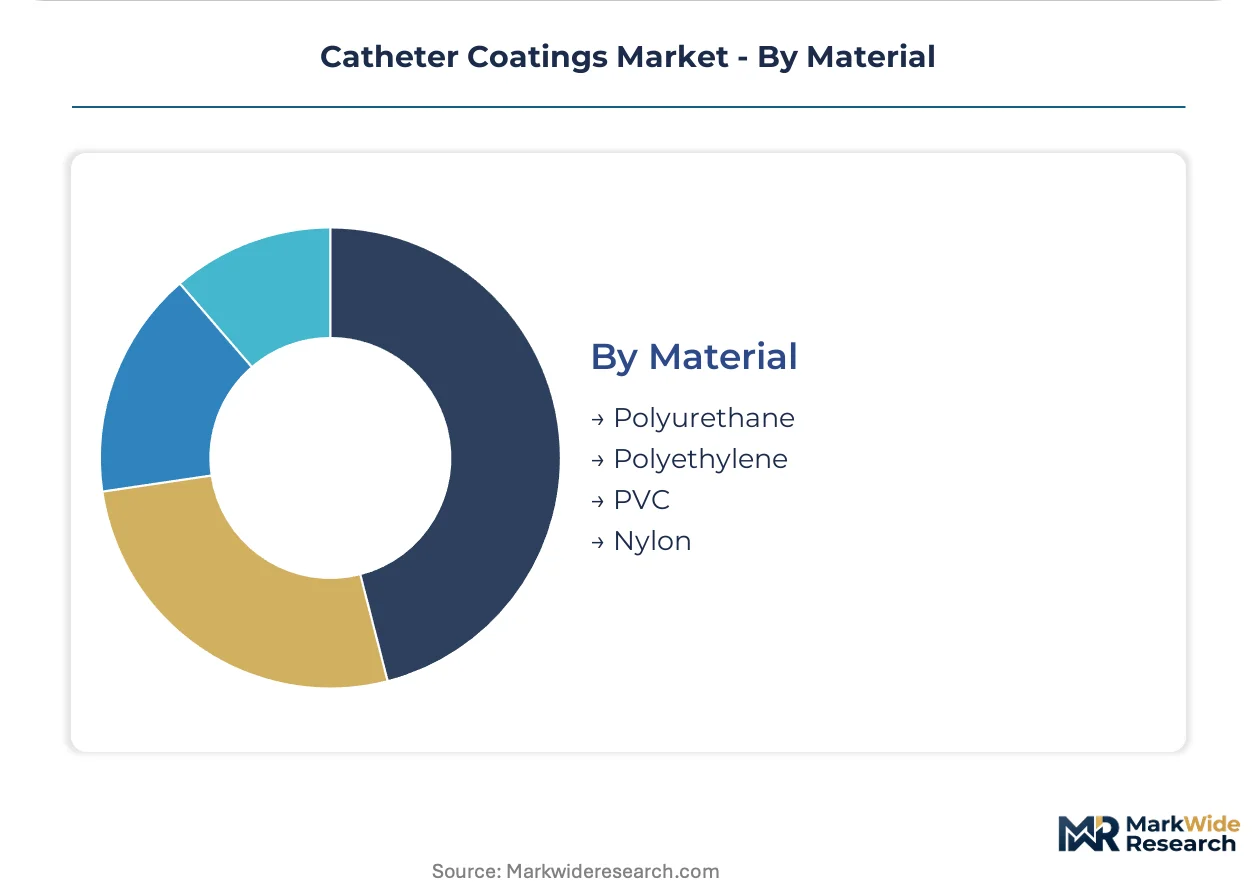
Material:
Substrate surface energy and mechanical compliance dictate coating adhesion chemistry and deposition process selection.
- Polyurethane:Segmented elastomers with tunable hardness profiles accommodate neurovascular and coronary devices requiring kink resistance alongside lubricity. B. Braun Melsungen AG anchors European supply through captive coating operations matching polyurethane substrates to hydrophilic matrices.
- Polyethylene:Low-density formulations serve cost-optimized urology segments with plasma-treated surfaces for coating anchorage.
- PVC:Plasticized substrates face regulatory pressure from phthalate restrictions in EU and select US jurisdictions.
- Nylon:Polyamide substrates deliver puncture resistance for high-pressure interventional applications.
Technology leadership resides in Polyurethane; polyethylene maintains the broadest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones around Lake Constance and Penang anchor catheter coating supply chains, with tax incentives concentrating formulation expertise and captive manufacturing operations in these corridors.
United States
FDA's renewed biocompatibility scrutiny under 21 CFR Part 820 is compressing reformulation timelines for antimicrobial coatings. Hospital-acquired infection protocols in acute care settings are tightening specification thresholds. Minneapolis hosts Surmodics, Inc., where surface modification chemistries for neurovascular applications command premium positioning.
Germany
EU MDR clinical evidence requirements for Class IIa and above devices are mandating biocompatibility validation beyond previous CE marking thresholds. Lake Constance OEM clusters around Melsungen drive the most advanced specification intensity for hydrophilic and drug-eluting platforms. B. Braun Melsungen AG anchors European supply through captive coating operations matching polyurethane substrates to hydrophilic matrices.
Netherlands
Heerlen-based Royal DSM leverages biomedical-grade polymer portfolios to supply coating resins across multiple catheter OEMs. REACH compliance for antimicrobial feedstocks is reshaping supplier qualification protocols. Eindhoven's high-tech corridor concentrates surface chemistry talent pools that coating vendors compete to access.
Malaysia
Penang's medical device free trade zone status attracts catheter OEMs seeking ASEAN market access with reduced tariff exposure. B. Braun Melsungen AG operates captive coating facilities here to serve Asia-Pacific demand pools. The country's national pharmaceutical regulator aligns with ISO 10993 protocols to streamline premarket testing for export-oriented manufacturers.
Switzerland
Swissmedic's stringent device classification requirements elevate coating vendor qualification thresholds for neurovascular applications. Basel's pharmaceutical heritage concentrates polymer science expertise that transfers to catheter coating formulation groups. Tertiary hospital procurement committees in Zurich and Geneva consolidate supplier relationships around vendors with integrated regulatory affairs capabilities.
Catheter Coatings Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service suppliers capturing volume concentration in tertiary hospital procurement while niche formulators defend margin positions in neurovascular and oncology applications. The vendor base organizes around three strategic archetypes: integrated polymer resin suppliers, captive coating operations of major catheter OEMs, and independent surface modification specialists. M&A activity targets regulatory affairs capabilities and ISO 10993 testing infrastructure. Geographic expansion into ASEAN free trade zones represents the second dominant competitive move as vendors seek tariff-advantaged manufacturing footprints.
Within the integrated polymer resin tier, Royal DSM and Specialty Coating Systems Inc. exemplify suppliers leveraging biomedical-grade material portfolios across multiple OEM relationships. Among independent surface modification specialists, Surmodics, Inc. occupies a position anchored in demanding neurovascular and coronary lubricity thresholds. B. Braun Melsungen AG represents the captive coating operation archetype, with Melsungen and Penang facilities supplying internal catheter manufacturing lines. These three patterns—external resin supply, independent specialist service, and vertical captive integration—structure competitive positioning across hydrophilic, antimicrobial, and drug-eluting platform categories.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Royal DSM |
| Surmodics, Inc. |
| Biocoat Incorporated |
| Specialty Coating Systems Inc. |
| Hydromer |
| Polyone Corporation |
| Covalon OEM Technologies |
| LipoCoat BV |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap coating specialists anchored around Germany's Lake Constance corridor maintain pricing discipline through captive resin compounding and long-term polyurethane supply agreements with B. Braun Melsungen AG. This ownership structure insulates pricing from quarterly earnings pressure while concentrating procurement leverage against silver-ion feedstock volatility.
Pricing Analysis
Short lead-time premiums command substantial markups as ISO 10993 biocompatibility testing bottlenecks extend validation windows for reformulated antimicrobial platforms. Three-tier pricing structure across premium, standard, and economy levels separates validated EU MDR technical dossiers from legacy CE-marked inventory and uncoated commodity substrates. Cost compression in standard-tier hydrophilic coatings is intensifying because polyvinylpyrrolidone feedstock contracts face precious metal-linked volatility. Ambulatory surgical centers exhibit the highest price sensitivity, while tertiary hospital procurement committees prioritize regulatory documentation over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Lake Constance catheter manufacturing clusters, with secondary distribution serving mid-tier Asian contract manufacturers. Geographic supply concentrates in Germany, Malaysia, and the Netherlands, where B. Braun Melsungen AG operates captive coating facilities in Melsungen and Penang while Royal DSM supplies biomedical-grade polymer resins from Heerlen. Raw material dependencies center on polyvinylpyrrolidone, silver-ion complexes, and segmented polyurethane elastomers. Single-source vulnerability around DSM's specialty resin portfolio poses structural risk if REACH compliance disruptions affect antimicrobial feedstock qualification. Distribution runs through catheter OEM direct procurement with limited spot market activity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into polymer resin compounding and downstream regulatory consulting services defines the current vertical-integration race, with coating vendors acquiring ISO 10993 testing infrastructure to compress premarket submission timelines.
For Market Incumbents: Extend formulation expertise into unified deposition processes that collapse hydrophilic-antimicrobial-drug-eluting manufacturing steps into single-line operations. Acquire surface chemistry PhD talent pools in Eindhoven and Basel before pharmaceutical and biotechnology sectors exhaust available candidates. Build captive EU MDR technical documentation capabilities to defend against hospital procurement committee consolidation around full-service suppliers.
For New Entrants and Emerging Players: Capture gastroenterology lubricious coating specifications as endoscopic procedure volumes expand beyond established cardiology and urology demand pools. Target ASEAN manufacturing corridors through Penang free trade zone facilities to bypass tariff exposure in Asia-Pacific catheter markets. Lead with integrated regulatory affairs consulting to differentiate against price-competitive commodity coating vendors lacking clinical evidence generation capabilities.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier coating operations with validated ISO 10993 testing infrastructure but strained dual-jurisdiction validation costs in the US Northeast and Midwest manufacturing belts. Long-term viability over the extended analysis window hinges on antimicrobial resistance surveillance data shifts that could restrict silver-based coating specifications. Watch FDA guidance documents on coating biocompatibility profiles as the critical inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Buildout | CE marking self-certification expiration elevates clinical evidence requirements for Class IIa coated devices. |
| Unified Deposition Process Development | Single-line manufacturing collapses separate hydrophilic, antimicrobial, and drug-eluting coating steps. |
| ISO 10993 Testing Infrastructure Acquisition | In-house biocompatibility validation compresses premarket submission windows against FDA scrutiny. |
| Penang Free Trade Zone Manufacturing Footprint | ASEAN tariff advantages attract catheter OEMs seeking Asia-Pacific demand access. |
| Surface Chemistry Talent Recruitment Programs | Eindhoven and Basel PhD pools face competition from pharmaceutical and biotechnology sectors. |
Methodological Framework
Multi-period observation of catheter OEM procurement patterns, regulatory submission timelines, and coating formulation patent filings anchored the trend analysis, supplemented by interviews with hospital purchasing committee members, biomedical engineers at tertiary interventional cardiology departments, GPO contracts managers, and regulatory affairs leads at coating vendors. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, ISO 10993 biological evaluation protocols, and REACH antimicrobial feedstock compliance records. Bottom-up coating unit demand estimates triangulated against top-down catheter market value projections.
Segment-weighting approaches applied coating-type, application-area, and end-user dimensions across the projection horizon, with material substrate compatibility layered as an additional modeling dimension. CAGRs derived from procedure volume expansion rates in interventional cardiology, urology, and gastroenterology segments, cross-referenced against hospital-acquired infection protocol intensification and EU MDR implementation timelines. Forecast inputs incorporated silver-ion price volatility indices and polyvinylpyrrolidone supply contract renewal patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA antimicrobial coating biocompatibility guidance revisions and EU MDR clinical evidence requirement enforcement variability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
IoT Medical Devices Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Oxygen Generator Market
Medical Devices
Implantable Port Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Genitourinary Prosthetics Market
Medical Devices
US Peripheral Vascular Devices and Accessories Market
Medical Devices
Facial Pumps Market
Medical Devices
North America Portable Medical and Healthcare Devices Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Nurse Call Systems Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Artificial Retina Market
Medical Devices
IOL Delivery Systems Market