
 Australia Hand Sanitizer Market | 2026-2036
Australia Hand Sanitizer Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Hand Sanitizer Market Intelligence
TGA registration requirements for therapeutic goods is shifting the cost-of-entry calculus for new entrants seeking therapeutic claims. Schulke Australia Pvt Limited leverages its hospital-grade certification to sustain contract positions with major health networks. Reckitt Benckiser Australia Pvt Ltd anchors retail shelf presence through pharmacy and supermarket channels. GOJO Australasia Pvt Limited specializes in touch-free dispensing systems for commercial facilities.
Hand sanitizer denotes an alcohol-based or alcohol-free antiseptic formulation designed for topical application to reduce microbial load on hands, typically containing ethanol or isopropanol at concentrations between 60% and 95% alongside emollients and humectants to prevent dermal irritation. The product serves infection control protocols across healthcare, food service, education, and workplace environments where handwashing infrastructure is unavailable or insufficient. Gel formulations dominate volume sales through pharmacy and supermarket channels due to consumer familiarity and portability. Above 60% alcohol content products capture the institutional segment where hospital accreditation standards mandate specific efficacy thresholds. Spray formats are gaining traction in workplace and hospitality settings where rapid application and minimal residue prove operationally advantageous.
TGA therapeutic goods standards, ACCC consumer product safety requirements, and Food Standards Australia New Zealand labeling rules collectively govern formulation claims, packaging disclosures, and channel eligibility across the Australian market. These frameworks compel manufacturers to maintain batch-level efficacy documentation and restrict marketing language that implies unsubstantiated pathogen kill rates. Stakeholders must monitor pending amendments to biosecurity procurement guidelines that could redirect institutional purchasing toward domestic manufacturing sources.
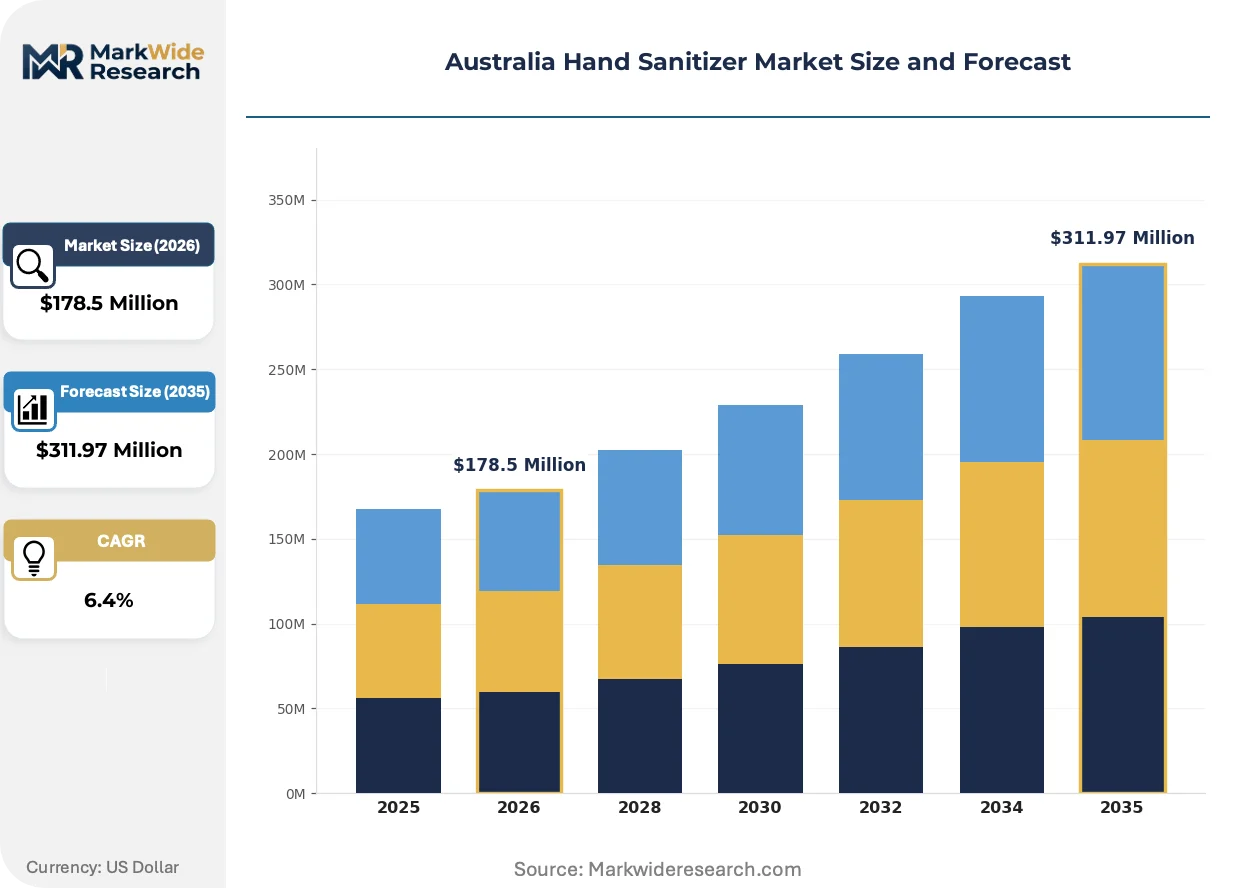
Market Dynamics
TGA therapeutic goods registration requirements are compressing the supplier base by elevating documentation and batch-testing burdens, forcing smaller formulators toward contract manufacturing or private-label arrangements rather than direct therapeutic claims.
Growth Catalysts
- Healthcare facility expansion:Hospital networks and aged care operators in New South Wales and Victoria are extending hygiene protocols into non-clinical zones, creating incremental dispenser placement opportunities.
- Food Standards Australia New Zealand labeling alignment:Harmonized disclosure rules reduce packaging complexity for cross-Tasman distribution, lowering compliance overhead for multi-market suppliers.
- Touch-free dispensing adoption:Commercial facilities are retrofitting washrooms and entry points with sensor-activated units to reduce cross-contamination vectors in high-traffic environments.
Market Restraints
- Ethanol feedstock volatility:Biofuel policy fluctuations in Queensland and Western Australia create input cost instability for domestic alcohol-based formulation.
- TGA audit backlog:Therapeutic goods registration timelines now extend 14-18 months, freezing new entrant pipeline and preserving incumbent positions.
- Isopropanol import dependency:Bulk chemical supply concentrates through Port Botany and Port of Melbourne, creating single-point vulnerability for non-ethanol formulations.
Strategic Opportunities
- Queensland regional health districts:Decentralized procurement in Cairns, Townsville, and Gold Coast remains underpenetrated by hospital-grade certified suppliers.
- Biosecurity procurement amendments:Pending federal guidelines may mandate domestic manufacturing preferences for institutional tenders, advantaging local production assets.
- Alcohol-free formulation convergence:Benzalkonium chloride and quaternary ammonium compounds are gaining traction in food processing and childcare settings where flammability restrictions apply.
Industry Challenges
- Microbiological validation capacity:Batch-level efficacy documentation requires third-party laboratory partnerships that face 6-8 week turnaround constraints.
- Dispenser hardware integration:Retrofitting legacy plumbing infrastructure in aged care facilities creates installation complexity and capital allocation disputes between operators and suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Hand Sanitizer Market |
| Market Size in 2026 | $178.5 Million |
| Market Size in 2035 | $311.97 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Foam, Spray, Wipe Alcohol Content: Above 60%, Below 60%, Alcohol-Free, Others Packaging Type: Bottle, Tube, Refill, Pump Distribution Channel: Online, Supermarket, Pharmacy, Convenience Store |
| Companies Covered | Colgate Palmolive Australia Pvt Limited, Sukin Australia Private Ltd, Schulke Australia Pvt Limited, Reckitt Benckiser Australia Pvt Ltd, PZ Cussons Australia Private Ltd, Care Line Australia Pvt Limited, ALDI Australia Pvt Limited, GOJO Australasia Pvt Limited, Ego Pharma Australia Pvt Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Hand Sanitizer Market Strategic Shifts & Innovations
Formulation chemistry and dispensing hardware are converging to address residual irritation complaints that limit compliance in high-frequency use environments. Three developments are restructuring competitive advantage.
Smart dispensing systems with usage-monitoring sensors are unifying compliance tracking and inventory replenishment into single-platform solutions. Aged care operators and hospital procurement departments are piloting these units in Victoria and New South Wales. The technology is compressing service contract structures by bundling hardware, consumables, and data analytics into per-bed or per-station pricing.
TGA guidance document updates on therapeutic claims substantiation are tightening evidentiary standards for pathogen-specific kill-rate marketing. Manufacturers must now submit standardized suspension test data rather than in-house methodology summaries. Hospital-grade certification applicants face the steepest compliance burden, with several pending registrations delayed pending additional Pseudomonas aeruginosa efficacy documentation.
Workplace safety officers are consolidating vendor relationships from multi-brand fragmentation toward single-source supply agreements with compliance audit support. Property management firms and hospitality chains are displacing opportunistic retail purchasing with scheduled bulk delivery contracts. This concentration is most visible in Sydney and Melbourne CBD commercial towers where facilities management teams negotiate enterprise-level hygiene service bundles.
Australia Hand Sanitizer Market Segmentation
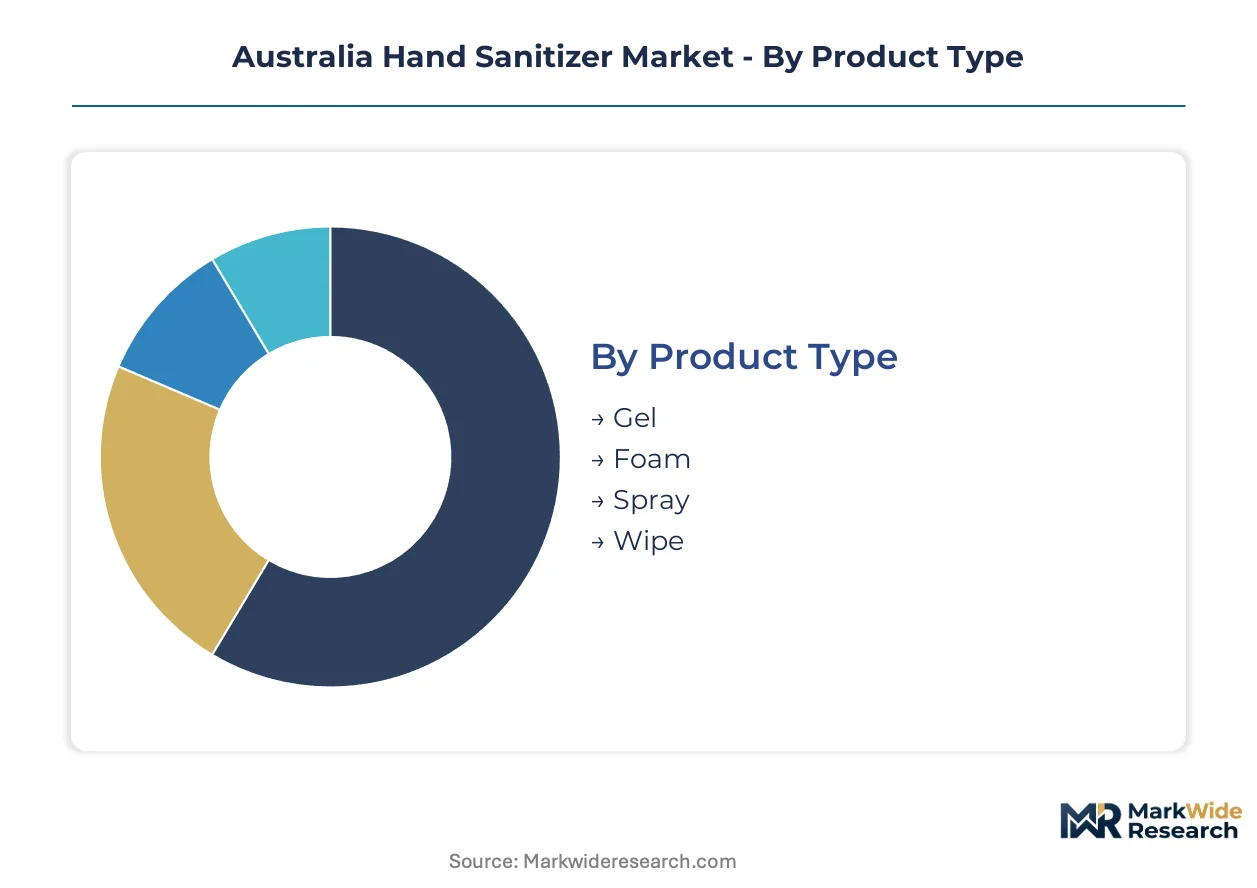
Hand sanitizer procurement in Australia fragments across four distinct category hierarchies. Each dimension carries specific TGA compliance implications that reshape supplier economics and channel eligibility. Understanding these fault lines exposes where capital deployment concentrates and where margin compression threatens.
Product Type:
Capital intensity peaks with foam and spray systems requiring specialized dispensing hardware and compressed gas propellant infrastructure. Gel formulations demand comparatively modest mixing and filling equipment.
- Gel:Viscous ethanol or isopropanol suspensions thickened with carbomer or cellulose derivatives dominate pharmacy and supermarket shelves. New South Wales and Victoria hospital networks specify gel for bedside dispensers due to drip control and user familiarity. TGA documentation requirements favor incumbent gel manufacturers with established batch-testing protocols.
- Foam:Air-entrained formulations reduce alcohol volume per dose while maintaining efficacy, requiring specialized aerating pump mechanisms. Aged care operators in Queensland are retrofitting foam dispensers to limit dermatitis complaints among high-frequency users. Hardware integration costs elevate total cost of ownership versus gel alternatives.
- Spray:Atomized delivery enables rapid surface coverage with minimal residue, penetrating workplace and hospitality procurement in Sydney and Melbourne CBD towers. Flammability labeling under ACCC rules constrains transport and storage configurations.
- Wipe:Pre-saturated towelettes packaged in flow-wrap or canister formats serve field-based healthcare and food processing where water access is limited. Single-use waste disposal regulations in Victoria are compressing institutional uptake.
Most installed capacity flows through Gel. Expansion is steepest in Foam.
Alcohol Content:
Regulatory tiering creates three distinct compliance cost structures. Above 60% formulations carry therapeutic goods registration burdens that exclude smaller compounders.
- Above 60%:Ethanol or isopropanol concentrations meeting WHO and TGA hospital-grade efficacy thresholds command premium positioning in clinical procurement. Batch-level Pseudomonas aeruginosa validation documentation is mandatory for network contract eligibility. Victorian and New South Wales health districts mandate this tier for accreditation compliance.
- Below 60%:Reduced alcohol formulations targeting consumer convenience trade absolute kill rates for skin conditioning claims. Retail channels in Queensland and Western Australia favor this tier for price-sensitive household segments. TGA exempts from therapeutic registration but requires ACCC-compliant efficacy disclosures.
- Alcohol-Free:Benzalkonium chloride and quaternary ammonium compound bases serve food processing and childcare settings where ignition risk is prohibited. Cairns and Townsville regional health districts are piloting these formulations in kitchen and laundry facilities.
- Others:Emerging botanical and hypochlorous acid variants occupy niche positioning with limited TGA guidance clarity, constraining institutional procurement uptake.
Hospital procurement concentrates in Above 60%. Alcohol-Free is climbing the fastest as flammability restrictions proliferate.
Packaging Type:
Volume scale and automation compatibility differentiate packaging economics. Refill and pump systems require capital-intensive blow-fill-seal lines versus commodity bottle sourcing.
- Bottle:Standard HDPE or PET containers with flip-top or screw closures dominate retail shelf presence. Pharmacy chains in Melbourne and Sydney specify bottle formats for home-use SKUs. Lightweighting initiatives are reducing resin content per unit.
- Tube:Collapsible aluminum or laminate tubes serve travel and personal care positioning with premium price realization. Limited penetration outside airport retail and hotel amenity channels.
- Refill:Bulk pouch and bag-in-box formats supply touch-free dispenser networks in commercial towers and aged care facilities. Gold Coast and Cairns property managers are consolidating toward refill contracts to reduce packaging waste compliance costs.
- Pump:Integrated dispenser-and-reservoir systems lock in consumable pull-through for facilities management vendors. Hardware-software bundling is restructuring service contract economics in Victoria.
Refill systems capture the steepest volume expansion. Bottle maintains the largest unit base.
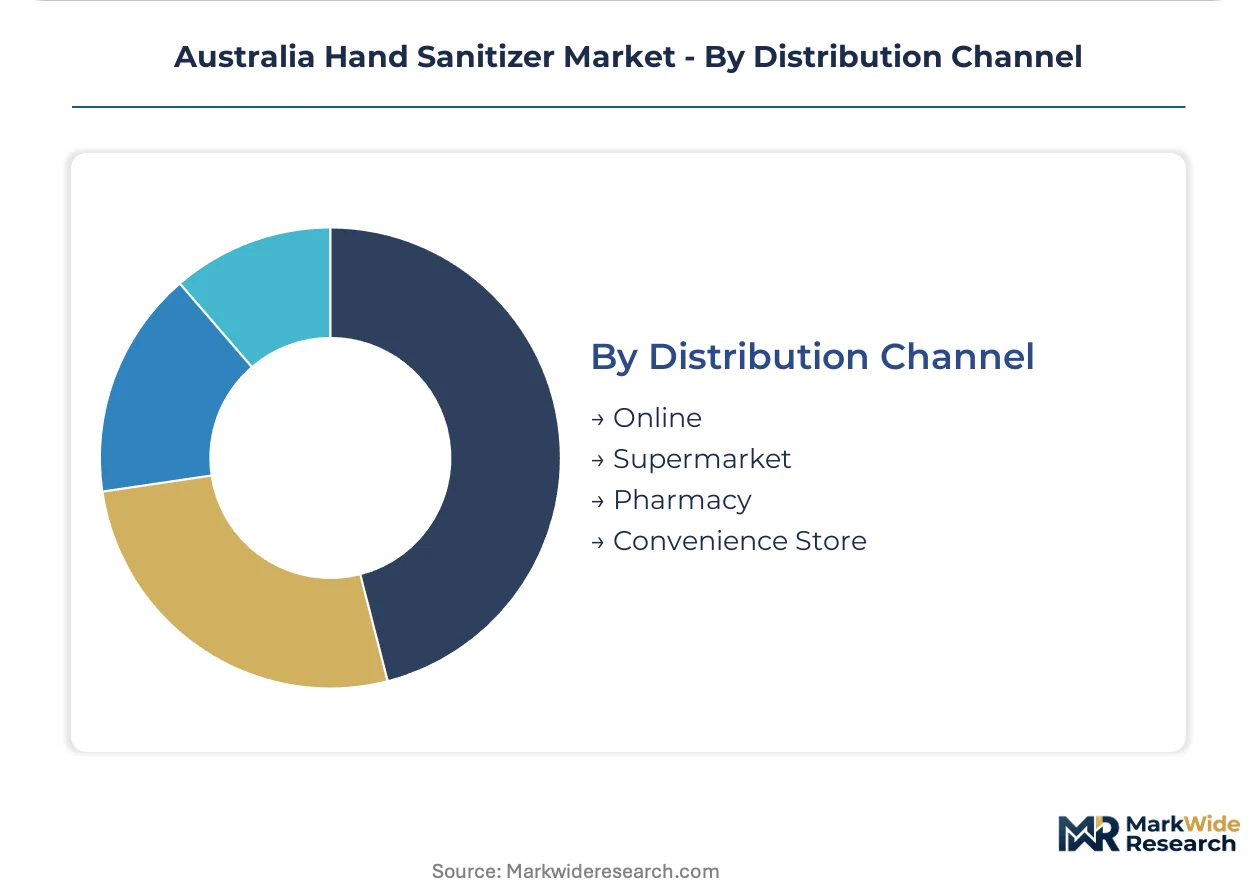
Distribution Channel:
Channel selection determines margin structure and TGA compliance exposure. Pharmacy and supermarket routes demand trade investment scale that favors national brand portfolios.
- Online:Direct-to-consumer and B2B platform sales enable private-label and specialty formulation reach without retail slotting fees. Melbourne and Sydney metro delivery windows are compressing toward same-day fulfillment. ACCC advertising claim monitoring is intensifying for pathogen-kill assertions.
- Supermarket:Coles and Woolworths shelf placement requires promotional fund commitments and standardized packaging formats. Volume concentration in New South Wales and Victoria metro stores drives national brand dominance.
- Pharmacy:Chemist Warehouse and independent pharmacy networks provide TGA-registered therapeutic goods credibility with pharmacist endorsement access. Professional recommendation influence sustains premium pricing for hospital-grade variants.
- Convenience Store:7-Eleven and petrol station forecourt placement captures impulse and travel occasion demand with compact SKUs. Limited refrigeration tolerance constrains formulation options.
Pharmacy channels anchor therapeutic claim legitimacy. Online is gaining share fastest in regional Queensland districts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare workforce concentration in New South Wales and Victoria anchors national procurement volume. Hospital networks and aged care operators in these states maintain centralized purchasing desks that dictate contract terms for suppliers seeking institutional placement. TGA registration requirements apply uniformly across all jurisdictions, though enforcement intensity varies by state health department audit protocols.
New South Wales
Sydney's hospital network expansion drives dispenser placement in non-clinical zones. NSW Health's infection control guidelines mandate above 60% alcohol formulations for acute care accreditation. The Northern Beaches and Western Sydney health districts pilot smart dispensing systems with usage monitoring.
Victoria
Melbourne's aged care density generates concentrated demand for dermatitis-mitigating foam formulations. Victorian Department of Health audits enforce batch-level efficacy documentation for therapeutic claims. The Monash Health and Alfred Health clusters negotiate enterprise hygiene service bundles.
Queensland
Regional health districts in Cairns and Townsville remain underpenetrated by hospital-grade certified suppliers. Queensland's biofuel policy fluctuations create ethanol feedstock cost instability for domestic formulators. The Gold Coast property management sector consolidates toward refill contracts to reduce packaging waste compliance costs.
Western Australia
Perth's mining camp and fly-in-fly-out operations sustain bulk institutional procurement for remote workforce hygiene. Western Australian Department of Health procurement guidelines align with TGA standards but permit longer lead times for regional delivery. The Pilbara and Kimberley regions test alcohol-free formulations in kitchen and laundry facilities.
South Australia
Adelaide's medical research precinct generates specialized demand for laboratory-grade hand hygiene protocols. South Australian Health's biosecurity procurement amendments may redirect institutional purchasing toward domestic manufacturing sources. The Barossa Valley food processing cluster drives benzalkonium chloride formulation trials.
Australia Hand Sanitizer Market Key Industry Players
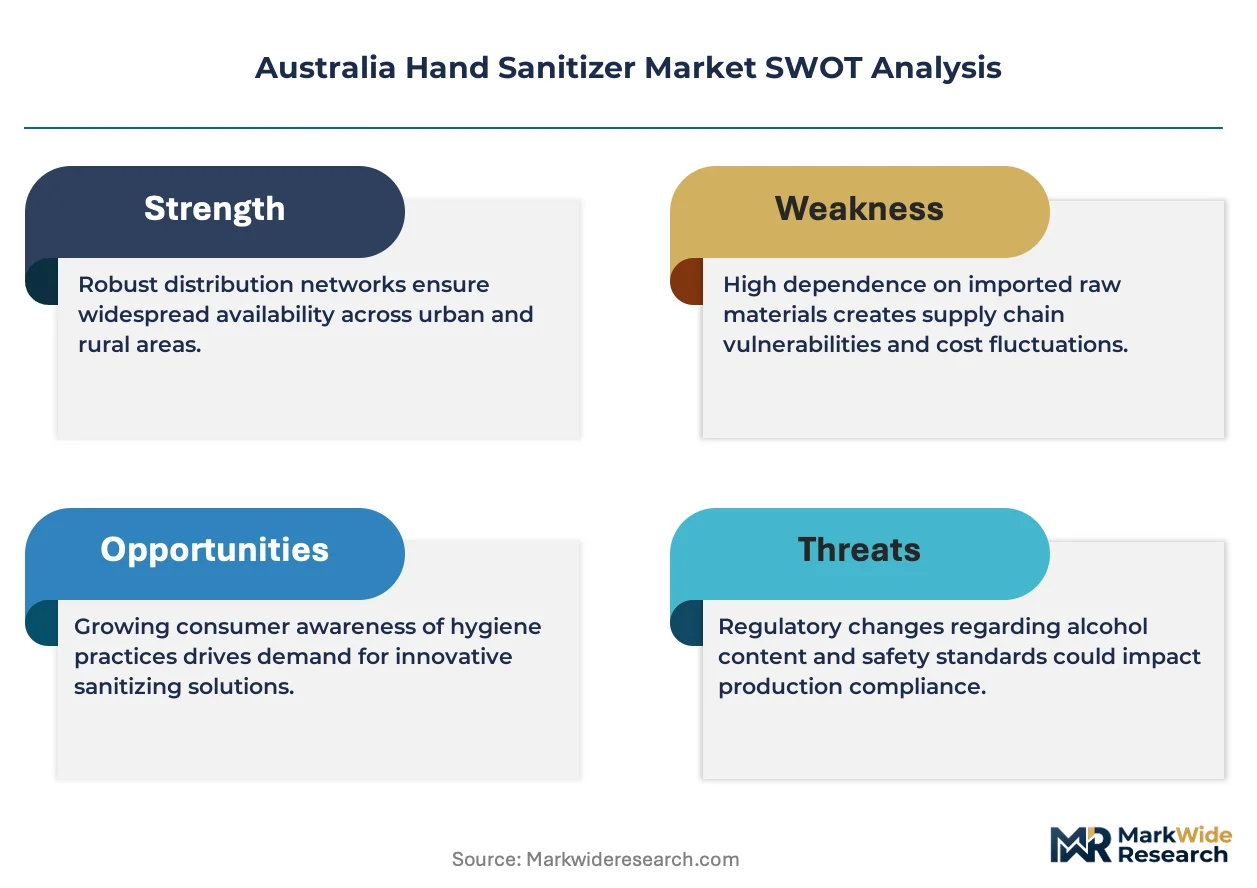
The competitive structure tilts toward incumbent certification holders. TGA therapeutic goods registration requirements compress the supplier base by elevating documentation burdens, forcing smaller formulators toward contract manufacturing arrangements. Three archetypes dominate: multinational consumer goods conglomerates with pharmacy network access, specialized hospital-grade certification holders with health system contracts, and private-label suppliers serving retail concentration. Consolidation occurs through strategic partnerships bundling hardware and consumables, and portfolio diversification into touch-free dispensing systems.
Within the hospital-grade certification tier, Schulke Australia Pvt Limited and GOJO Australasia Pvt Limited exemplify archetypes leveraging institutional compliance credentials. Schulke occupies a position anchored by hospital network contract maintenance, while GOJO represents the dispensing hardware-consumables bundling model. Among retail-channel conglomerates, Reckitt Benckiser Australia Pvt Ltd sits within the pharmacy and supermarket shelf-preservation archetype. These three companies collectively illustrate how TGA registration barriers partition competitive terrain between institutional and consumer segments.
| Leading Market Players |
|---|
| Colgate Palmolive Australia Pvt Limited |
| Sukin Australia Private Ltd |
| Schulke Australia Pvt Limited |
| Reckitt Benckiser Australia Pvt Ltd |
| PZ Cussons Australia Private Ltd |
| Care Line Australia Pvt Limited |
| ALDI Australia Pvt Limited |
| GOJO Australasia Pvt Limited |
| Ego Pharma Australia Pvt Limited |
| Others |
Cost & Logistics Intelligence
Family-owned chemical distributors with multi-decade ethanol supply relationships anchor bulk procurement in Queensland and New South Wales, translating feedstock security into pricing discipline that resists spot-market volatility. Their long-tenured contracts with domestic distillers insulate hospital-grade formulators from biofuel policy swings while compressing margin recovery timelines for smaller compounders lacking comparable volume commitments.
Pricing Analysis
Bundled hardware-consumables service contracts command premium positioning against unbundled transactional purchasing in aged care and commercial property sectors. Three-tier pricing structure across premium hospital-grade, standard commercial, and economy retail levels stratifies by TGA certification intensity and batch-documentation burden. Cost compression in the economy tier intensifies as private-label supermarket entrants absorb ethanol feedstock spikes without margin buffer. Pharmacy channels exhibit lowest price sensitivity due to clinician endorsement reliance, while convenience store placement faces acute pressure from impulse-trade-down behavior.
Supply Chain Analysis
Single-source vulnerability sits with isopropanol import flows through Port Botany and Port of Melbourne, concentrating non-ethanol formulation exposure in two maritime gateways. Domestic ethanol sourcing draws from Queensland and Western Australia biofuel refiners, with cellulose derivative thickeners and pump hardware components resting on Chinese and German manufacturing bases. Tariff exposure on specialty dispensing mechanisms creates margin risk for facilities management vendors bundling hardware-software solutions. Distribution runs through national pharmacy wholesalers, supermarket distribution centers, and direct B2B logistics contracts to institutional procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia hand sanitizer market functions as a stable compounder, with infection control protocol permanence in healthcare and aged care settings generating recurring consumable demand that outpaces discretionary consumer categories.
For Market Incumbents: Deploy TGA certification maintenance as the primary defensive lever. Deepen hospital network contract positions through batch-level documentation automation that compresses audit response times. Add alcohol-free formulation capacity to capture food processing and childcare procurement where flammability restrictions displace ethanol bases. Counter private-label supermarket pressure by emphasizing pharmacist-channel endorsement access that trade brands cannot replicate.
For New Entrants and Emerging Players: Smart dispensing system integration with usage-monitoring analytics offers a technology-first wedge against hardware-agnostic incumbents. Target Queensland regional health districts in Cairns and Townsville where hospital-grade certified supplier penetration remains thin. Pursue aged care facility retrofit contracts through per-bed pricing models that convert capital expenditure objections into operational budget line items.
For Investors and Strategic Acquirers: Valuations sit cheapest among private-label manufacturers lacking therapeutic goods registration but possessing Coles and Woolworths shelf placement. Five-to-ten year viability hinges on biosecurity procurement amendments favoring domestic manufacturing assets. Monitor TGA audit backlog duration as the critical inflection signal—registration timeline compression would erode incumbent protection and reopen competitive entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Touch-Free Dispenser Retrofit Programs | Sensor-activated hardware bundling locks in consumable pull-through with aged care operators in Victoria. |
| Alcohol-Free Formulation Development | Benzalkonium chloride bases capture food processing procurement where TGA flammability restrictions apply. |
| Regional Queensland Distribution Buildout | Cairns and Townsville health district penetration addresses under-served institutional demand outside metro centers. |
| Smart Dispensing System Integration | Usage-monitoring analytics compress service contracts into per-bed pricing for hospital network procurement. |
| Domestic Manufacturing Asset Acquisition | Pending biosecurity amendments may mandate local production preferences for federal institutional tenders. |
Research Approach
Multiple input streams — procurement manager interviews at New South Wales and Victorian health networks, regulatory affairs consultations with TGA registration specialists, and ethanol feedstock sourcing discussions with Queensland biofuel refiners — were reconciled against secondary validation. Hospital infection control officers, aged care facility managers, pharmacy category buyers, and commercial property facilities directors contributed primary perspective. TGA guidance documents, ACCC consumer safety rulings, Food Standards Australia New Zealand labeling directives, and customs import data provided secondary anchor points. Bottom-up dispenser placement counts and top-down healthcare expenditure aggregates were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against panel input from institutional procurement committees to establish baseline elasticity. Segmentation modeling spanned product type, alcohol content tier, packaging format, and distribution channel across the projection horizon. CAGRs were derived from compound growth path fitting rather than single-point extrapolation. Ethanol feedstock cost curves and TGA registration pipeline duration served as industry-specific forecast inputs alongside healthcare workforce expansion projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biosecurity procurement amendment timing and biofuel policy volatility. Forecasts reflect documented assumptions regarding TGA audit backlog resolution and hospital network capital expenditure continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Botulism Market
Infection Control
Antimicrobial Catheters Market
Infection Control
Sterilization Monitoring Market
Infection Control
Peptide-Based Infection Therapeutics Market
Infection Control
Disinfection Cupboard Market
Infection Control
Pertussis Infection Testing Market
Infection Control
Dental Infection Treatment Market
Infection Control
Ear Infection Treatment Market
Infection Control
Antimicrobial Suture Market
Infection Control
Salivary Gland Infection Market
Infection Control
Sterilization Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Global Pseudomonas Aeruginosa Infection Treatment Market
Infection Control
Antimicrobial Wipes Market
Infection Control
Virus Filtration Market
Infection Control
Global Disinfection Robots Market