
 Electroceuticals Bioelectric Medicine Market | 2026-2036
Electroceuticals Bioelectric Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Electroceuticals Bioelectric Medicine Market Analysis
The EU Medical Device Regulation is recalibrating the cost-of-entry calculus for electroceutical manufacturers seeking CE marking in Europe. Medtronic plc leverages its vertically integrated manufacturing footprint to sustain compliance economies across multiple device classes. Boston Scientific Corporation anchors its European position through specialized regulatory affairs teams focused on MDR technical documentation. Abbott Laboratories differentiates via its cardiac rhythm management heritage, which competes directly in the pacemaker and neuromodulation segments.
Electroceuticals bioelectric medicine encompasses implantable and non-implantable devices that deliver precisely controlled electrical impulses to modulate neural, cardiac, or cellular activity, typically operating at pulse frequencies between 1 Hz and 10 kHz with output currents below 100 mA to achieve therapeutic bioelectronic effects without tissue damage. The primary commercial purpose centers on substituting or augmenting pharmaceutical interventions for chronic conditions through targeted electrical neuromodulation. Neurostimulators occupy the highest-margin segment due to complex lead technology and long-term implantation protocols, while transcutaneous electrical nerve stimulation devices compete primarily on price in home care settings. Implantable devices lead absolute revenue contribution, though bioelectronic interfaces represent the fastest-growing technology category as closed-loop adaptive stimulation platforms advance.
The FDA breakthrough device program accelerates market access for novel electroceuticals addressing neurological disorders, while the EU MDR and ISO 14155 clinical investigation standards impose rigorous evidence requirements that filter smaller competitors from premium segments. Japan's PMDA SAKIGAKE designation creates a parallel fast-track pathway for companies prioritizing Asian market entry. Stakeholders must monitor evolving reimbursement codes for outpatient neuromodulation procedures, as payment policy shifts will determine whether home care settings capture meaningful volume from hospitals and ambulatory surgical centers.
Market Dynamics
Closed-loop adaptive stimulation platforms are compressing product development cycles and forcing legacy neuromodulation manufacturers to reengineer hardware architectures around real-time biosignal processing capabilities.
Growth Catalysts
- FDA Breakthrough Device Program:Accelerated review timelines for novel electroceuticals addressing treatment-resistant epilepsy and Parkinson's disease are shortening time-to-revenue for first movers.
- Japan's PMDA SAKIGAKE Pathway:Priority review status for bioelectric therapies targeting unmet neurological needs creates regulatory arbitrage opportunities for firms prioritizing Asian market sequencing.
- Closed-loop neural interfaces:Algorithm-driven feedback systems enabling personalized stimulation parameters are expanding addressable indications beyond static open-loop devices.
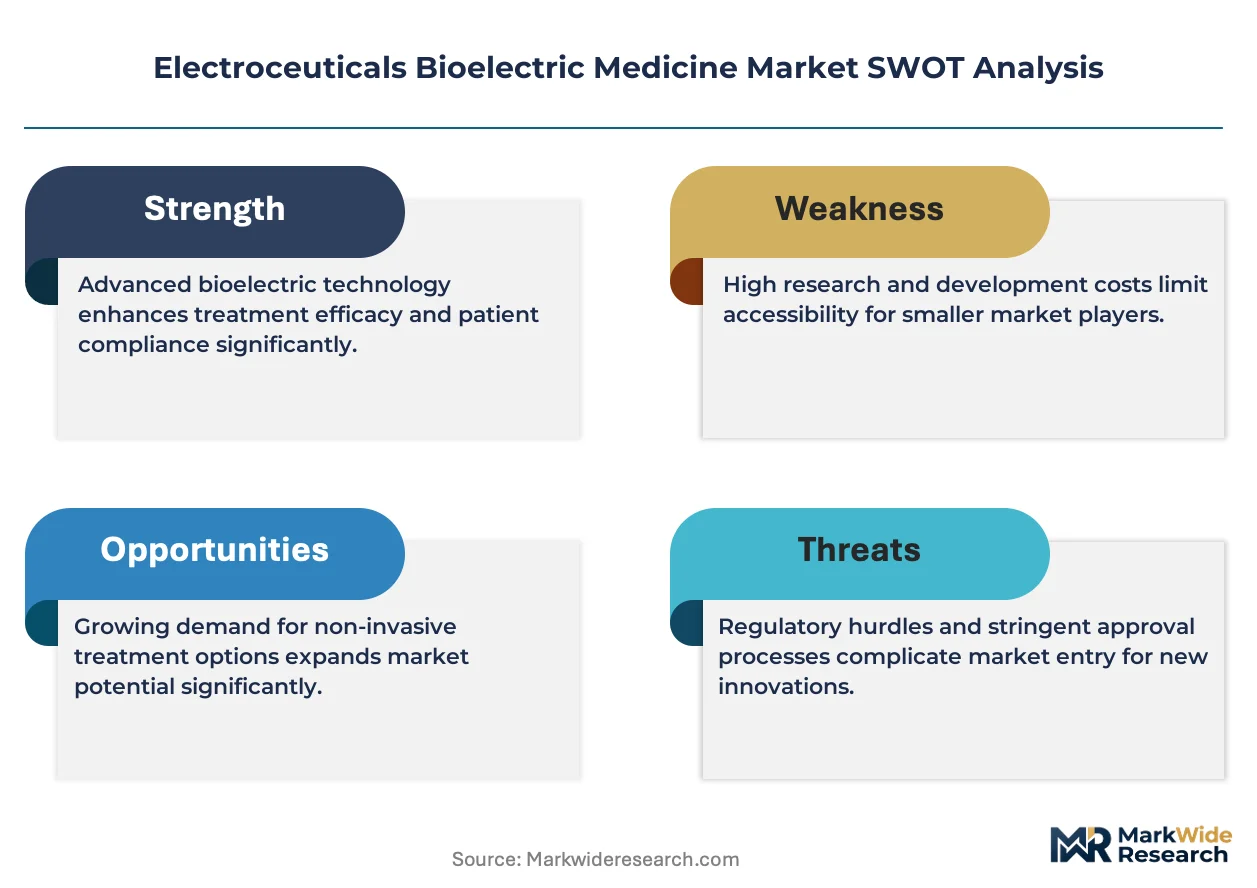
Market Restraints
- Platinum-iridium alloy supply concentration:Lead electrode manufacturing depends on South African and Russian feedstock, exposing neurostimulator producers to input cost volatility and sanctions risk.
- EU MDR technical documentation burden:Clinical evidence requirements for Class III implantable devices have extended CE marking timelines and filtered smaller competitors from premium segments.
- Pharmacological substitution in pain management:Next-generation non-opioid analgesics and gene therapies for neuropathic conditions threaten transcutaneous electrical nerve stimulation device volumes.
Strategic Opportunities
- German outpatient neuromodulation reimbursement expansion:Updated procedure codes for spinal cord stimulation in chronic pain are shifting procedure volume from inpatient to ambulatory settings.
- AI-enabled predictive maintenance:Machine learning algorithms analyzing device telemetry are enabling remote monitoring services that extend manufacturer recurring revenue streams.
- United States home care channel penetration:Medicare Advantage plan flexibility for remote patient management is creating direct-to-patient distribution pathways bypassing traditional hospital procurement.
Industry Challenges
- Neural engineering talent scarcity:Cross-disciplinary expertise combining electrophysiology, firmware development, and biocompatibility testing commands premium compensation and extends hiring timelines.
- ISO 14155 clinical investigation compliance:Multinational trials for adaptive stimulation algorithms require harmonized protocols across FDA, EMA, and PMDA jurisdictions, inflating study management overhead.
- Legacy device cybersecurity retrofitting:Bluetooth-enabled neuromodulators face patching complexity for implanted units with decade-long lifecycles, exposing manufacturers to post-market surveillance liabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electroceuticals Bioelectric Medicine Market |
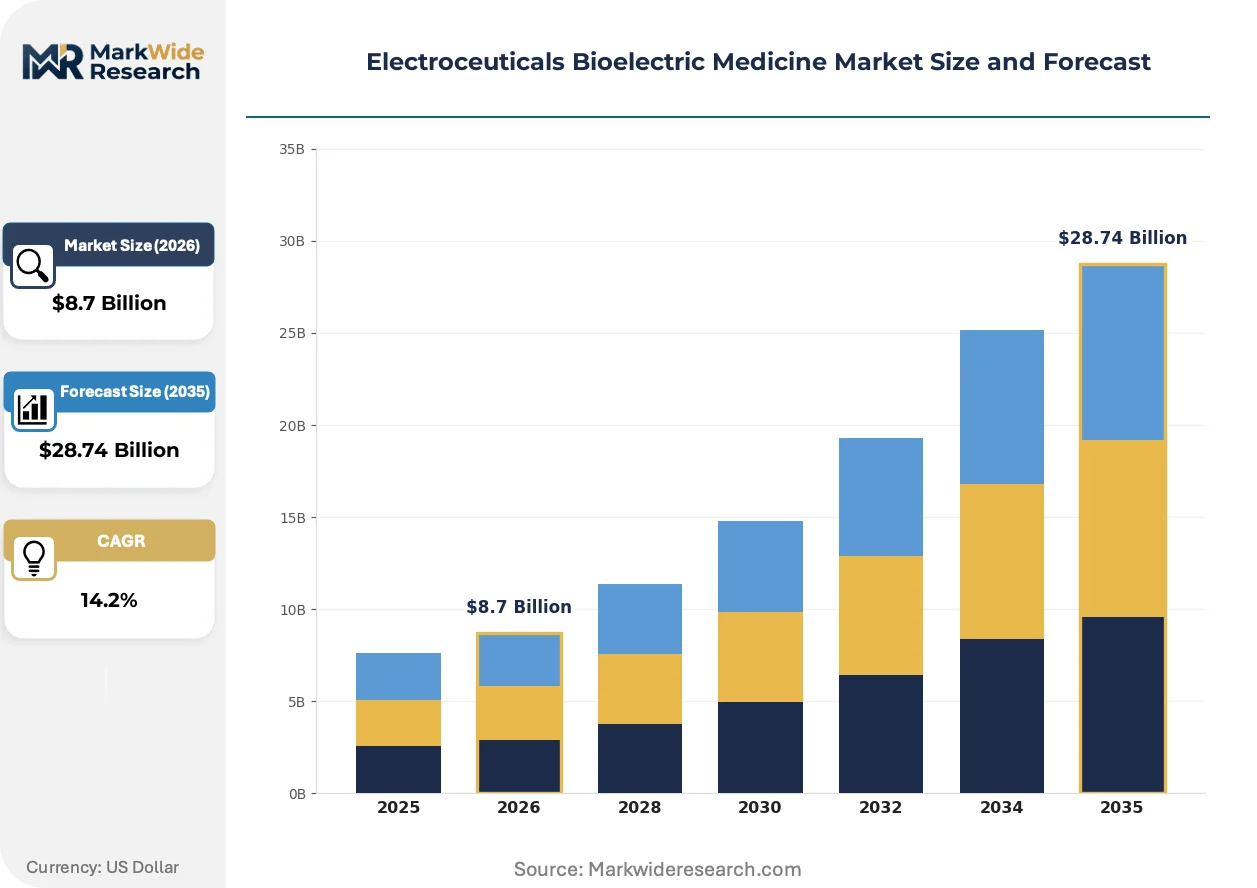
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Growth Stimulators, Neurostimulators, Cardiac Pacemakers, Spinal Cord Stimulators Application: Pain Management, Neurological Disorders, Cardiovascular Diseases, Inflammatory Conditions End User: Hospitals, Rehabilitation Centers, Home Care Settings, Ambulatory Surgical Centers Technology: Transcutaneous Electrical Nerve Stimulation, Implantable Devices, Bioelectronic Interfaces, Magneto Electrical Stimulation |
| Companies Covered | LivaNova PLC, Biotronik, Medtronic plc, Sonova, Nevro Corp., Boston Scientific Corporation, Cochlear Ltd., electroCore, Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electroceuticals Bioelectric Medicine Market Emerging Trajectories
Digital biomarker integration and miniaturized power electronics are converging to enable autonomous therapeutic adjustment without clinician intervention, fundamentally altering the service model for chronic condition management.
Thin-film electrode arrays with microfabricated polyimide substrates are modularizing the physical interface between implanted pulse generators and target neural tissue. Academic medical centers in the United States and Germany are piloting these conformable interfaces for peripheral nerve applications. The technology is modularizing how manufacturers segment product portfolios, allowing mixing of generator platforms with interchangeable lead systems rather than locked ecosystems.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic literature reviews and periodic safety update reports for all active implantable devices. Manufacturers must maintain dedicated vigilance teams and automated adverse event detection systems. Neurostimulator product lines face the steepest compliance cost escalation due to long implantation durations and complex lead-related failure modes.
Hospital procurement committees are consolidating vendor relationships for implantable devices around integrated service contracts bundling device, implantation support, and long-term remote monitoring. United States integrated delivery networks are replacing transaction-based purchasing with multi-year partnership agreements. This concentration is most visible in cardiac rhythm management and neuromodulation categories where device longevity and service responsiveness determine total cost of ownership calculations.
Electroceuticals Bioelectric Medicine Market Segmentation
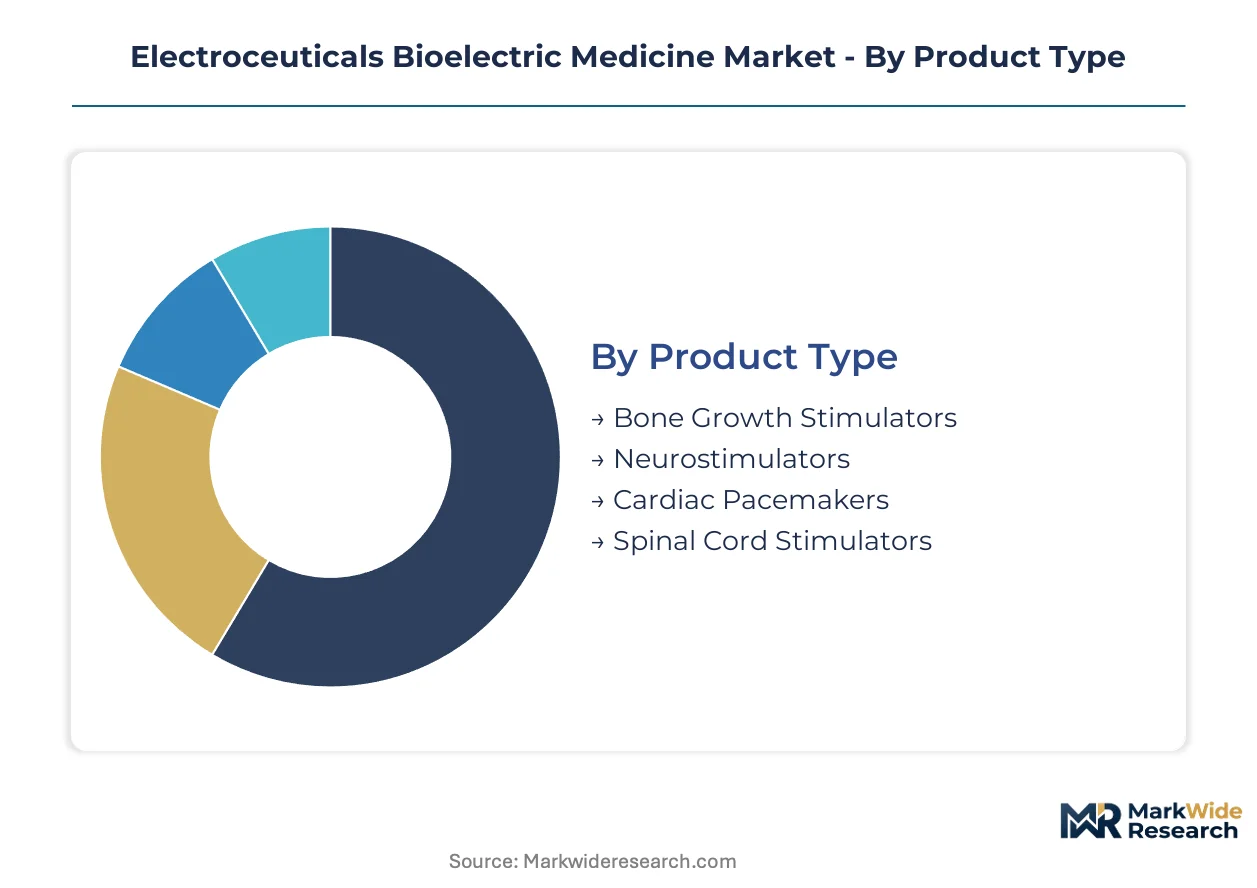
Electroceuticals bioelectric medicine segments diverge sharply by reimbursement pathway and implantation protocol. Device longevity, lead complexity, and outpatient procedure economics determine which categories command manufacturer investment priority.
Product Type:
Replacement cycles and upgrade incentives vary dramatically across implantable device classes, with rechargeable versus primary battery technologies creating divergent revenue recognition patterns.
- Neurostimulators:Deep brain and vagus nerve stimulators incorporate multi-channel lead arrays with platinum-iridium electrodes requiring surgical revision every 5-7 years. Demand clusters in movement disorder centers at Cleveland Clinic and Charité Berlin where interdisciplinary teams manage complex electrode programming.
- Spinal Cord Stimulators:These devices deliver epidural electrical pulses through cylindrical or paddle leads for chronic intractable pain. United States integrated delivery networks are consolidating procurement around single-vendor partnerships bundling device, implantation, and remote monitoring services.
- Cardiac Pacemakers:Subcutaneous pulse generators with transvenous or leadless configurations manage bradyarrhythmias through rate-responsive algorithms.
- Bone Growth Stimulators:External capacitive coupling and pulsed electromagnetic field devices accelerate fracture healing in non-union cases without surgical implantation.
Neurostimulators sit at the top of the volume ranking, with spinal cord stimulators climbing the fastest.
Application:
Clinical evidence thresholds and payer coverage policies segment addressable markets by condition severity and pharmaceutical failure history.
- Neurological Disorders:FDA breakthrough designations for treatment-resistant epilepsy and Parkinson's disease compress review timelines for adaptive stimulation platforms. Academic medical centers in Boston and Heidelberg pilot closed-loop systems that adjust parameters based on real-time neural biomarkers.
- Pain Management:Spinal cord and peripheral nerve stimulation compete directly with opioid tapering programs and emerging non-opioid pharmacotherapies. German outpatient reimbursement expansion under updated procedure codes is shifting volume from inpatient stays to ambulatory settings.
- Cardiovascular Diseases:Cardiac rhythm management addresses bradyarrhythmia, heart failure, and sudden cardiac death risk through pacemaker and implantable cardioverter-defibrillator platforms.
- Inflammatory Conditions:Vagus nerve stimulation for rheumatoid arthritis and Crohn's disease represents an emerging indication with bioelectronic medicine companies pursuing modular platform extensions.
Pain management captures the largest installed base, while inflammatory conditions are expanding most quickly as immunomodulatory applications mature.
End User:
Procurement authority and total cost-of-ownership calculations differ across care settings, with hospital committees prioritizing device longevity and home care channels emphasizing patient self-management capabilities.
- Hospitals:Tertiary centers with electrophysiology and functional neurosurgery departments manage complex implantations requiring intraoperative neurophysiological monitoring. United States academic medical centers anchor volume for deep brain stimulator placements given surgical expertise requirements.
- Ambulatory Surgical Centers:Spinal cord stimulator trials and permanent implants are migrating to outpatient settings where procedure efficiency and same-day discharge protocols reduce total episode cost. Medicare Advantage plan flexibility is accelerating this channel shift.
- Rehabilitation Centers:Post-implantation programming and parameter optimization for neuromodulation devices occur in specialized rehabilitation settings with physical medicine expertise.
- Home Care Settings:Transcutaneous electrical nerve stimulation devices and external bone growth stimulators bypass clinical procurement entirely through direct-to-patient distribution.
Hospitals retain the dominant volume position, though ambulatory surgical centers are gaining share fastest as reimbursement migrates toward site-neutral payment.
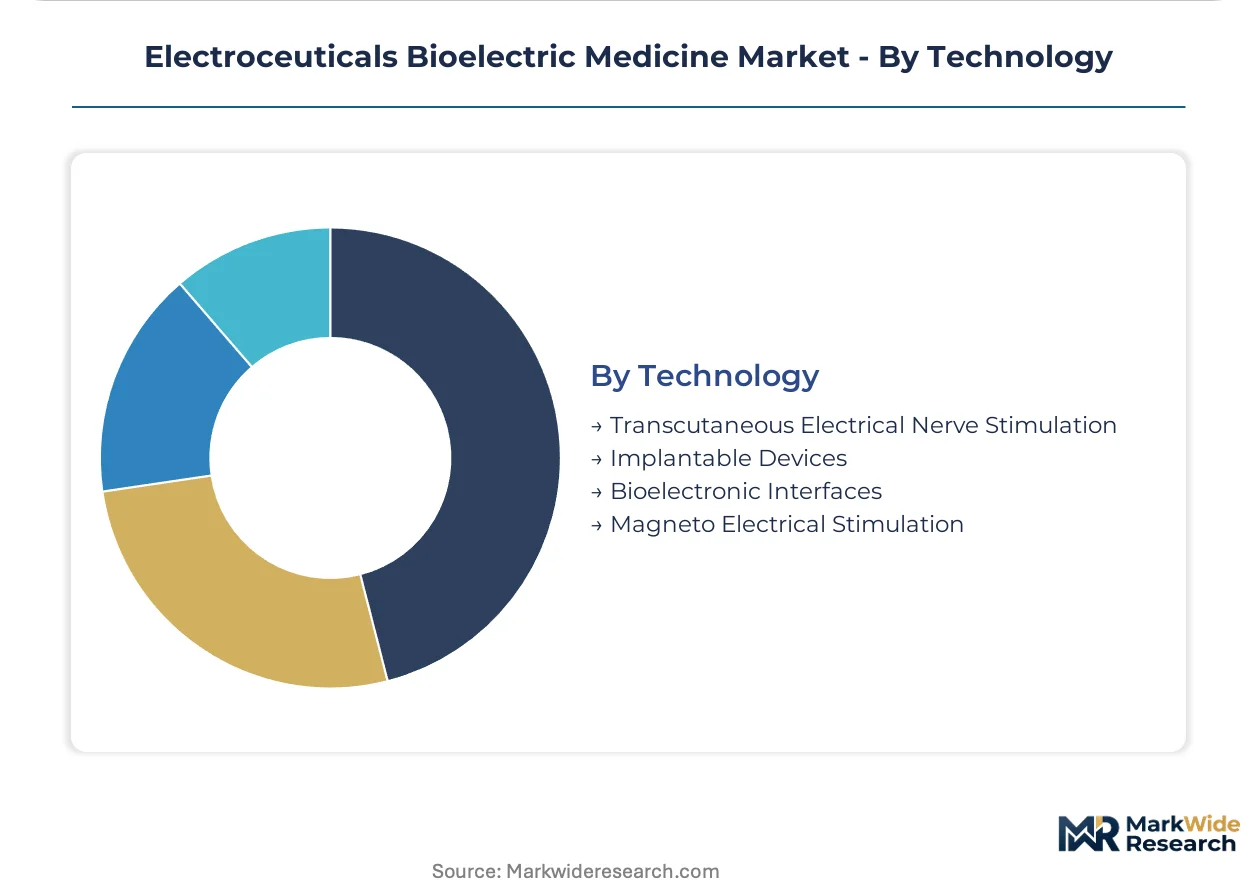
Technology:
Hardware architecture choices between open-loop and closed-loop control systems determine firmware complexity and regulatory evidence requirements.
- Implantable Devices:Pulse generators with hermetic titanium enclosures and feedthrough assemblies deliver chronic therapy through inductive charging or primary cell designs. ISO 14155 clinical investigation standards and EU MDR post-market surveillance obligations impose the steepest compliance burdens on this category.
- Bioelectronic Interfaces:Thin-film electrode arrays with microfabricated polyimide substrates enable conformal neural interfaces for peripheral nerve applications. Research partnerships between manufacturers and academic medical centers in Stanford and Munich are accelerating modular platform development.
- Transcutaneous Electrical Nerve Stimulation:Surface electrode systems compete primarily on price in retail and home care channels with limited clinical differentiation.
- Magneto Electrical Stimulation:Pulsed electromagnetic field devices target bone healing and soft tissue repair through non-invasive delivery.
Implantable devices dominate absolute revenue contribution, while bioelectronic interfaces follow the steepest expansion trajectory as closed-loop adaptive platforms advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neuroengineering talent clusters in Boston, Stanford, and Heidelberg anchor electroceutical innovation, with regulatory pathways in the United States, Germany, and Japan compressing approval timelines for adaptive stimulation platforms.
United States
Academic medical centers at Cleveland Clinic and Mayo Clinic drive deep brain stimulator volume through interdisciplinary movement disorder programs. The FDA breakthrough device program accelerates review timelines for closed-loop epilepsy systems. Boston anchors the highest concentration of neuromodulation clinical trials, with Massachusetts General Hospital piloting real-time biomarker-responsive stimulation.
Germany
Charité Berlin and Heidelberg University Hospital anchor European demand for complex neurostimulator implantations requiring intraoperative monitoring. The EU MDR technical documentation requirements filter smaller competitors from Class III device segments. The Baden-Württemberg industrial corridor concentrates precision electronics manufacturing for hermetic pulse generator enclosures.
Japan
Osaka University and Tokyo Women's Medical University lead Asian adoption of vagus nerve stimulation for inflammatory conditions. The PMDA SAKIGAKE designation creates priority review pathways for bioelectric therapies addressing unmet neurological needs. The Kansai region hosts specialized microfabrication facilities for thin-film electrode arrays.
Switzerland
ETH Zurich and the University Hospital of Geneva anchor precision neurotechnology research partnerships with industrial manufacturers. Swissmedic maintains streamlined approval pathways for innovative implantable devices through its fast-track procedure. The Lake Geneva region concentrates microelectronics expertise for biosignal processing chipsets.
United Kingdom
University College London and King's College Hospital drive demand for spinal cord stimulation in chronic pain management. The MHRA operates parallel recognition routes for FDA-approved electroceuticals, compressing market entry timelines. The Oxford-Cambridge arc concentrates algorithm development talent for adaptive stimulation platforms.
Electroceuticals Bioelectric Medicine Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the electroceuticals landscape, with hospital procurement consolidation favoring integrated service contracts over transactional device sales. The vendor base stratifies into three tiers: multinational healthcare conglomerates with vertically integrated manufacturing, mid-cap neuromodulation specialists with concentrated R&D pipelines, and emerging bioelectronic interface developers pursuing modular platform architectures. Dominant competitive moves include M&A activity targeting closed-loop algorithm capabilities and strategic partnerships with academic medical centers for clinical evidence generation.
Among diversified healthcare conglomerates, Medtronic plc and Abbott Laboratories occupy positions exemplifying scale-driven regulatory compliance economies across multiple device classes. Boston Scientific Corporation represents the mid-cap specialist archetype, with regulatory affairs capabilities concentrated on EU MDR technical documentation. Within the emerging bioelectronic interface tier, Nevro Corp. and electroCore, Inc. exemplify focused commercial strategies targeting specific neuromodulation indications.
| Leading Market Players |
|---|
| LivaNova PLC |
| Biotronik |
| Medtronic plc |
| Sonova |
| Nevro Corp. |
| Boston Scientific Corporation |
| Cochlear Ltd. |
| electroCore, Inc. |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Closed-loop adaptive stimulation platforms are compressing hardware design cycles and concentrating procurement power among United States integrated delivery networks capable of absorbing multi-year service contracts. This technological shift simultaneously elevates firmware development costs while filtering price-competitive vendors from premium neuromodulation segments.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across implantable device tiers. Three-tier pricing structure across premium, standard, and economy levels separates rechargeable neurostimulators with remote monitoring from primary-cell devices and transcutaneous alternatives. Certification level under EU MDR and FDA breakthrough pathways commands measurable premiums in hospital procurement. Pricing pressure stems from Medicare Advantage site-neutral payment expansion compressing spinal cord stimulator margins. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers prioritize device longevity and service responsiveness over unit cost.
Supply Chain Analysis
Workforce-availability constraints in precision microfabrication concentrate hermetic pulse generator production across Germany, Switzerland, and the United States. Platinum-iridium electrode feedstock draws from South African and Russian mining operations, exposing lead manufacturers to sanctions-linked supply interruption. Polyimide substrate fabrication for thin-film arrays hinges on specialized cleanroom capacity in the Kansai region and Baden-Württemberg. Single-source vulnerability in noble metal refining elevates input cost volatility. Distribution runs through hospital procurement committees consolidating vendor relationships around integrated service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electroceuticals bioelectric medicine market functions as a stable compounder anchored by chronic disease prevalence expansion and pharmaceutical substitution tailwinds. Reimbursement code evolution and regulatory pathway compression sustain predictable demand visibility.
For Market Incumbents: Acquire closed-loop algorithm capabilities and bioelectronic interface intellectual property to defend against modular platform disruptors. Backward integration into platinum-iridium electrode manufacturing mitigates feedstock concentration risk. Hospital procurement consolidation demands multi-year partnership structures bundling device, implantation support, and predictive maintenance services. For New Entrants and Emerging Players: AI-enabled predictive maintenance algorithms offer technology-first wedge positioning against legacy neuromodulation hardware vendors. Peripheral nerve applications for inflammatory conditions present the most penetrable white space given limited incumbent clinical evidence. Direct-to-patient distribution through Medicare Advantage remote patient management channels bypasses traditional hospital gatekeeping. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap neuromodulation specialists with concentrated R&D pipelines and EU MDR technical documentation capabilities. Five-to-ten-year viability rests on adaptive stimulation platform regulatory approvals and reimbursement expansion velocity. Watch FDA breakthrough device designations and German outpatient procedure code updates as inflection signals for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review timelines compress time-to-revenue for closed-loop epilepsy systems. |
| EU MDR Technical Documentation | CE marking compliance filters smaller competitors from Class III implantable segments. |
| Hospital System Partnership | Integrated service contracts bundle device procurement with long-term remote monitoring revenue. |
| Software Companion Development | Machine learning algorithms analyzing device telemetry enable predictive maintenance services. |
| Reimbursement Strategy | Medicare Advantage plan flexibility creates direct-to-patient distribution pathways. |
Methodological Framework
Coverage spans the United States, Germany, Japan, Switzerland, and the United Kingdom, with primary inputs from each market informing demand calibration. Interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare data. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored market sizing.
Granularity-level modeling disaggregated revenue across implantable versus non-implantable technologies, open-loop versus closed-loop control architectures, and rechargeable versus primary battery configurations. CAGRs derived from logistic diffusion curves fitted to historical neuromodulator adoption patterns and reimbursement expansion trajectories. Forecast inputs incorporated EU MDR compliance cost escalation curves and Japan PMDA SAKIGAKE review timeline compression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platinum-iridium supply disruption, pharmacological substitution advances, and cybersecurity retrofitting liabilities for Bluetooth-enabled legacy implants. Practitioners should monitor FDA breakthrough device designation velocity and German outpatient neuromodulation reimbursement code updates for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic and Therapeutic Devices
Dissolving Microneedles Market
Diagnostic and Therapeutic Devices
Global Acoustic Medicine and Ultrasound Therapy Market
Diagnostic and Therapeutic Devices
Smart Infusion System Market
Diagnostic and Therapeutic Devices
Localized Temperature Therapy Products Market
Diagnostic and Therapeutic Devices
Electrosurgical Analyzer Market
Diagnostic and Therapeutic Devices
Global Cold Plasma in Healthcare Market
Diagnostic and Therapeutic Devices
Cruciate Ligament Diagnosis Treatment Market
Diagnostic and Therapeutic Devices
Global Needle Free Injection Systems Market
Diagnostic and Therapeutic Devices
Positive Patient Identification Market
Diagnostic and Therapeutic Devices
Global Smart Inhaler Technology Market
Diagnostic and Therapeutic Devices
Anti Neurofilament L Antibody Market
Diagnostic and Therapeutic Devices
Global Exosome Diagnostic and Therapeutic Market
Diagnostic and Therapeutic Devices
Robotic Surgery System Haptic Feedback Test Platforms Market
Diagnostic and Therapeutic Devices
Nanobiosensors in Healthcare Market
Diagnostic and Therapeutic Devices
Magnetic Therapy Devices Market
Diagnostic and Therapeutic Devices
Heat Therapy Lamp Market