
 India Cookware Market | 2026-2036
India Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
India Cookware Market Outlook
Market Context with Strategic Players
Hard-anodized aluminum is consolidating share against traditional cast iron in Indian kitchens due to superior heat distribution and lighter weight. TTK Prestige leverages its southern manufacturing base to dominate pressure cooker sales across Tamil Nadu and Karnataka. Hawkins Cookers sustains brand loyalty through its safety valve technology and decades of replacement parts availability. Wonderchef Home Appliances competes via celebrity chef partnerships and premium non-stick lines aimed at metro consumers.
Technical Definition and Structural Segments
India cookware encompasses vessels designed for stovetop food preparation, typically fabricated from stainless steel with chromium-nickel compositions, aluminum substrates with polytetrafluoroethylene coatings, or cast iron with preseasoned surfaces, engineered to withstand temperatures exceeding 200°C while meeting food-grade migration limits. The primary commercial purpose spans residential meal preparation, commercial restaurant operations, and institutional catering where thermal efficiency and durability determine replacement cycles. Stainless steel cookware anchors volume sales in the budget and mid-range tiers, while non-stick aluminum captures premium household demand in Mumbai, Delhi, and Bangalore. Pressure cookers represent a mature but replacement-heavy category where BIS ISI mark compliance creates a quality floor that unorganized imports struggle to clear.
Regulatory Frame and Forward Outlook
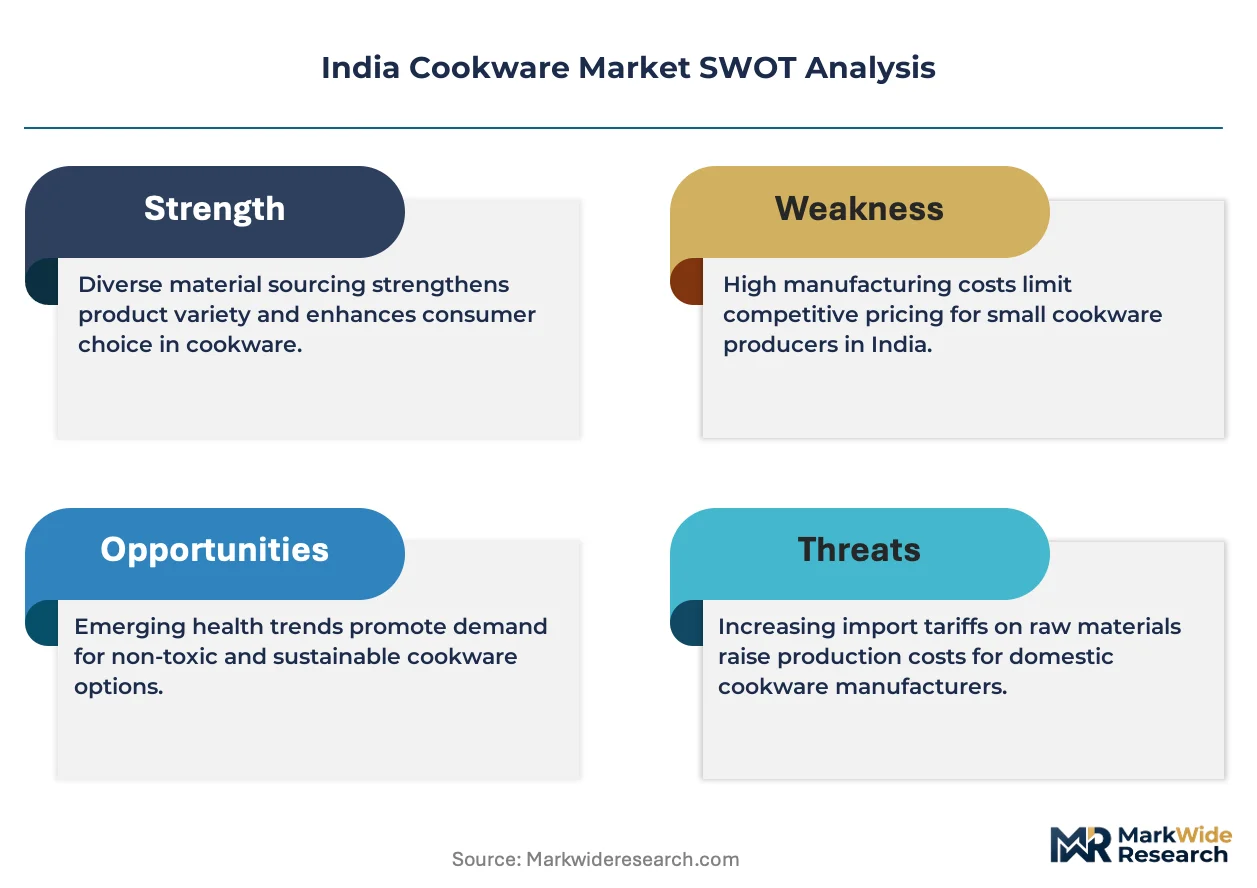
BIS mandates ISI certification for pressure cookers and aluminum vessels under compulsory registration, while FSSAI governs food-contact material safety and heavy metal migration thresholds. The PLI scheme for domestic manufacturing of consumer durables incentivizes local stainless steel fabrication capacity expansion. CDSCO oversight extends to ceramic coating imports used in premium non-stick lines. Stakeholders must monitor BIS draft standards for new ceramic and granite-derived coatings, as these will determine which material platforms gain formal approval and therefore channel access.
Market Dynamics
The PLI scheme for consumer durables is redirecting capital toward domestic stainless steel fabrication, compressing import dependency for raw substrates while raising quality floors through BIS ISI mark enforcement across pressure cooker and aluminum vessel categories.
Growth Catalysts
- Urban kitchen upgrades:Metro households in Mumbai, Delhi, and Bangalore are replacing legacy cast iron with lighter hard-anodized aluminum and tri-ply stainless steel configurations, shortening replacement cycles from decades to 5-7 years.
- BIS certification tightening:Compulsory ISI mark requirements for pressure cookers and food-contact aluminum vessels under BIS jurisdiction are filtering substandard imports and consolidating organized channel share.
- Hard-anodized substrate adoption:Superior heat distribution properties and reduced weight versus cast iron are accelerating uptake in southern and western Indian states where gas stove penetration is highest.
Market Restraints
- Nickel price volatility:Stainless steel cookware grades depend on nickel-chromium alloys, and input cost swings compress margin stability for mid-tier fabricators lacking long-term raw material contracts.
- Unorganized sector persistence:Uncertified aluminum vessels from small-scale units in Uttar Pradesh and Bihar continue to undercut ISI-compliant pricing in rural distribution channels.
- Ceramic coating import dependency:Premium non-stick lines rely on CDSCO-regulated ceramic coating imports, exposing brands to currency fluctuation and customs clearance delays at Mumbai and Chennai ports.
Strategic Opportunities
- Tier-2 and Tier-3 city penetration:Organized retail expansion into Indore, Lucknow, and Coimbatore creates first-mover advantage for brands establishing exclusive distributor networks before local competitors consolidate.
- PLI scheme capacity expansion:Domestic stainless steel fabrication incentives under the consumer durables PLI framework enable backward integration into substrate production, reducing import reliance for 304-grade coils.
- Induction-compatible product lines:Ferromagnetic stainless steel bases that function on induction cooktops address the 40% of urban kitchens transitioning from gas, opening replacement demand in apartment complexes.
Industry Challenges
- BIS testing backlog:ISI certification queues for new ceramic and granite-derived coating formulations extend product launch timelines by 8-12 months, delaying revenue recognition for R&D investments.
- Skilled die-casting technician scarcity:Pressure cooker manufacturing requires precision aluminum casting expertise concentrated in Kerala and Tamil Nadu, constraining capacity scaling for northern greenfield facilities.
- Legacy inventory markdown pressure:Pre-certified stock accumulated before BIS enforcement deadlines must clear through discount channels, eroding brand positioning in premium segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cookware Market |
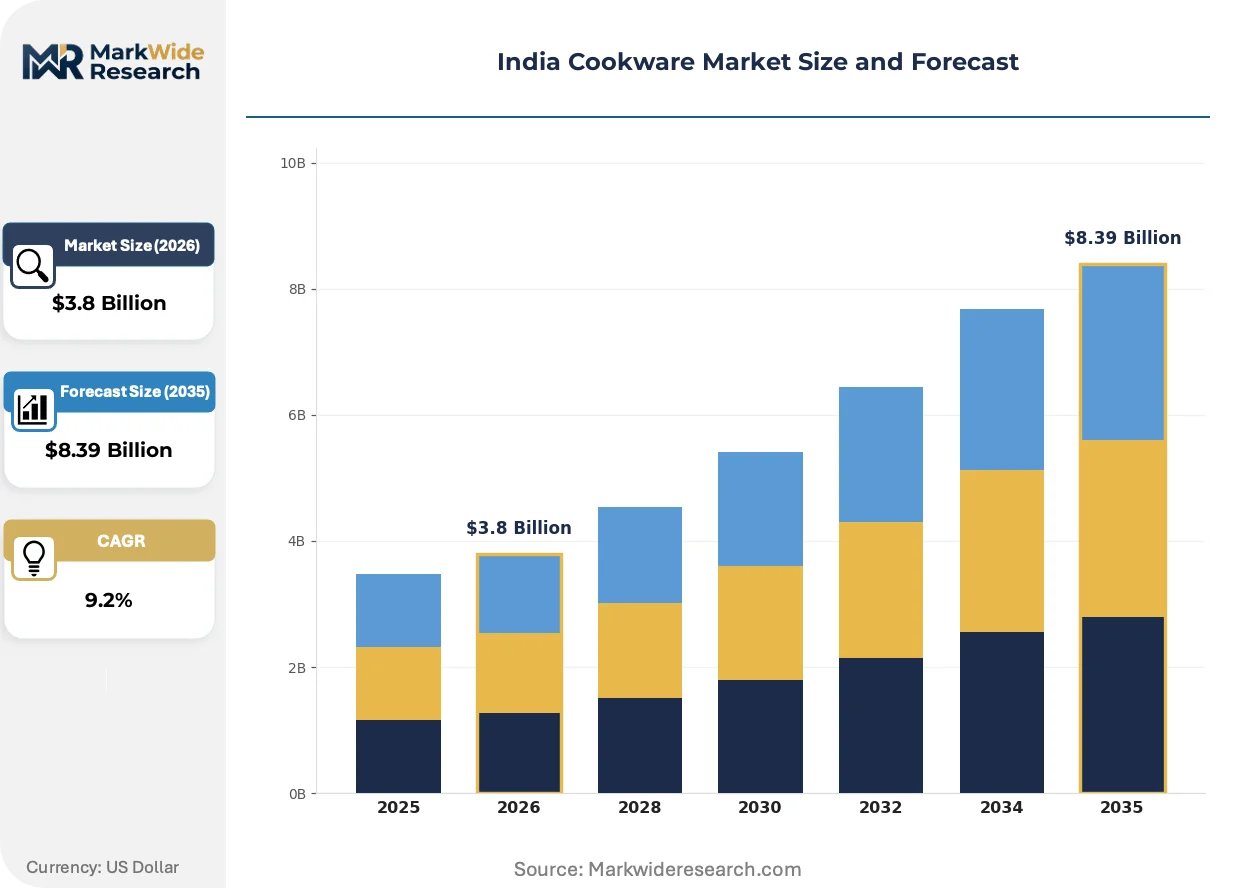
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookware Sets, Frying Pans, Pressure Cookers, Woks Material: Stainless Steel, Non-Stick, Cast Iron, Aluminum End User: Household, Restaurants, Cafés, Catering Services Price Segment: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Vinod Cookware, Wonderchef Home Appliances, TTK Prestige, Butterfly Gandhimathi Appliances, Bajaj Electricals, Hawkins Cookers, Cello World, Bergner Group, Stovekraft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cookware Market Strategic Shifts
Material convergence between traditional durability and modern thermal efficiency is redefining product architecture, while regulatory pressure on food-contact safety and shifting urban cooking infrastructure are compressing design-to-market cycles across the value chain.
Tri-ply construction technology is unifying the thermal conductivity of aluminum cores with the corrosion resistance of stainless steel exteriors, enabling single-vessel solutions that replace multiple legacy pots. Premium households in Bangalore and Hyderabad are adopting these configurations at twice the rate of single-material alternatives. This unification is compressing SKU proliferation while raising average selling prices in organized retail channels.
FSSAI migration limit enforcement for heavy metals in food-contact surfaces is forcing substrate reformulation across aluminum and ceramic-coated lines, with testing protocols now mandatory for all imported coating batches. Fabricators must maintain batch-level traceability documentation or face channel exclusion. Pressure cooker and infant food preparation segments are experiencing the steepest compliance cost escalation as they operate under dual BIS and FSSAI jurisdiction.
Direct-to-consumer online channels are displacing traditional distributor networks for premium cookware, with branded storefronts on major e-commerce platforms capturing urban buyers who previously relied on physical retail for tactile evaluation. Metro consumers now complete 35% of cookware purchases without in-person inspection, trusting certification marks and review aggregation instead. This behavioral shift is most pronounced in Mumbai and Delhi, where apartment living limits storage for large retail formats.
India Cookware Market Segmentation
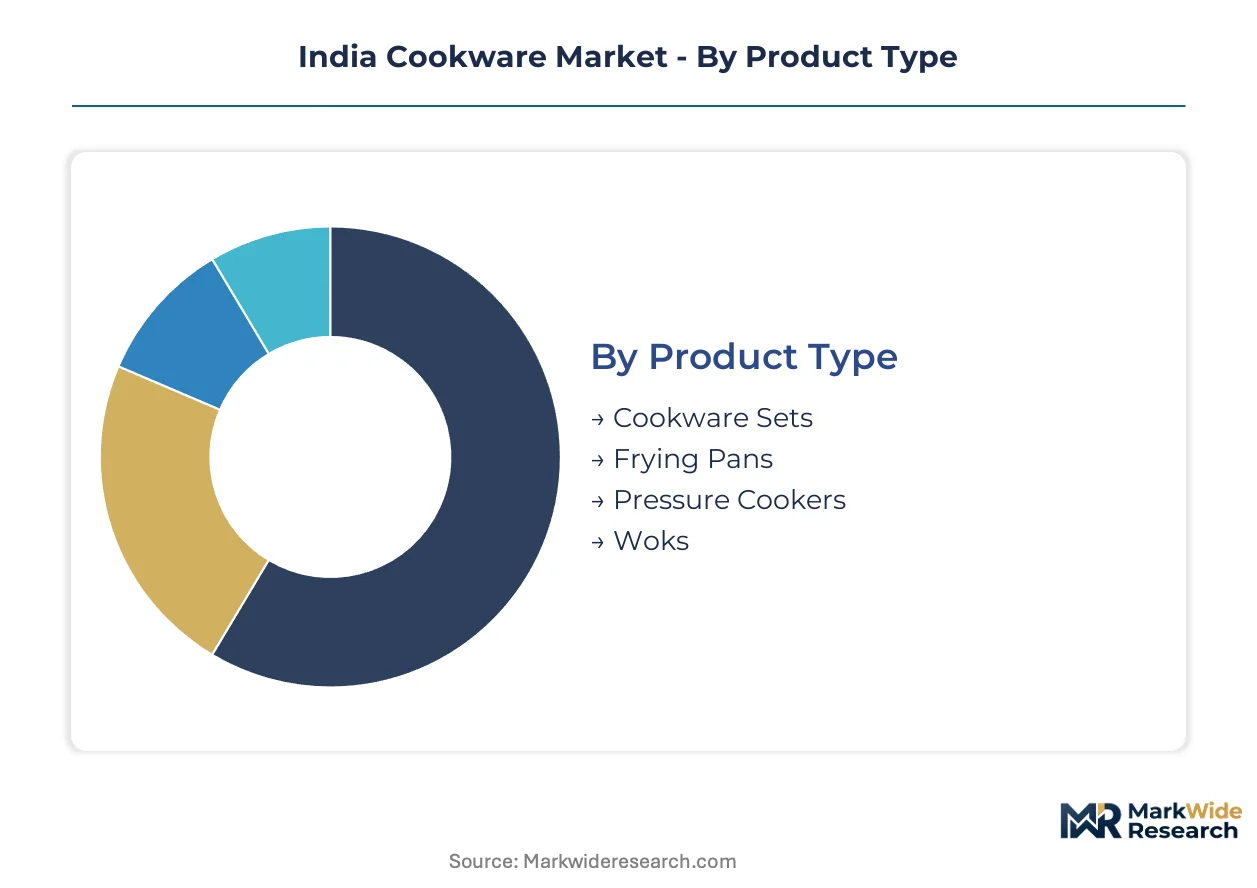
Segmentation in the India cookware market reveals how purchasing decisions split across cooking infrastructure, household income tiers, and regulatory exposure. Understanding these divides allows manufacturers to align product development with the specific thermal requirements and certification burdens each buyer type faces.
Product Type:
Urban kitchen configuration determines replacement frequency and vessel specialization needs.
- Cookware Sets:Tri-ply and hard-anodized aluminum configurations dominate organized retail in Mumbai and Delhi, where apartment storage constraints favor coordinated nesting designs over individual vessel accumulation.
- Frying Pans:Non-stick aluminum substrates with ceramic coatings capture premium household demand, though BIS testing backlogs for new coating formulations delay launches by 8-12 months.
- Pressure Cookers:ISI mark compliance creates a quality floor that filters substandard imports; replacement cycles compress as safety valve technology improves and urban households upgrade from legacy cast iron models.
- Woks:Traditional carbon steel and cast iron variants persist in southern Indian states where high-heat oil cooking remains prevalent; induction-compatible flat-bottom adaptations gain traction in Bangalore and Hyderabad apartment complexes.
Volume sits with pressure cookers; growth tilts toward cookware sets.
Material:
Substrate selection reflects the trade-off between thermal performance, weight, and food-contact safety compliance.
- Stainless Steel:304-grade chromium-nickel alloys anchor budget and mid-range sales volumes, with PLI scheme incentives now compressing import dependency for raw coils through domestic fabrication capacity expansion.
- Non-Stick:Polytetrafluoroethylene and ceramic-coated aluminum lines depend on CDSCO-regulated coating imports, exposing brands to currency fluctuation and customs clearance delays at Mumbai and Chennai ports.
- Cast Iron:Preseasoned surfaces retain share in rural distribution channels where durability expectations span decades; weight disadvantages accelerate share loss in urban gas-stove kitchens.
- Aluminum:Hard-anodized substrates with sealed oxide layers are displacing raw aluminum in western and southern states, driven by superior heat distribution and lighter handling characteristics.
Stainless steel dominates unit shipments; hard-anodized aluminum climbs fastest on urban replacement demand.
End User:
Operational intensity and regulatory scrutiny scale sharply across buyer categories.
- Household:Metro consumers in Delhi, Mumbai, and Bangalore complete 35% of purchases through direct-to-consumer online channels, trusting certification marks over tactile evaluation.
- Restaurants:Commercial kitchens in Maharashtra and Gujarat demand thermal efficiency and rapid heat recovery, favoring tri-ply stainless steel and heavy-gauge aluminum for high-throughput service.
- Cafés:Limited kitchen footprints in urban retail clusters drive demand for multi-function induction-compatible vessels that reduce equipment count.
- Catering Services:Institutional buyers face dual BIS and FSSAI jurisdiction with mandatory batch-level traceability documentation for food-contact surfaces.
Households generate the revenue base; catering services face the steepest compliance cost escalation.
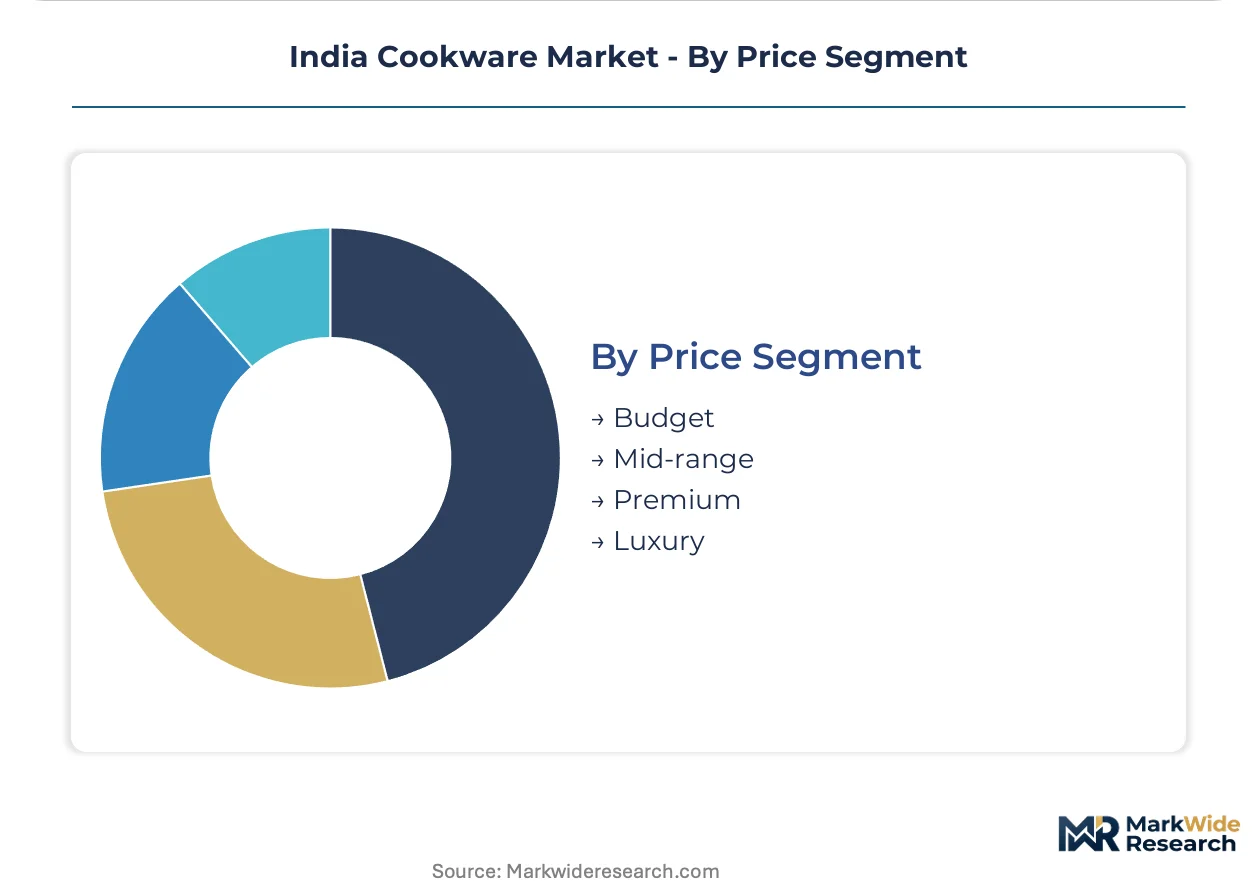
Price Segment:
Income distribution and certification awareness stratify the market into distinct procurement behaviors.
- Budget:Uncertified aluminum vessels from small-scale units in Uttar Pradesh and Bihar undercut ISI-compliant pricing in rural channels, though FSSAI enforcement is narrowing this gap.
- Mid-range:Organized retail penetration in Tier-2 cities like Indore and Lucknow concentrates demand here, with exclusive distributor networks determining first-mover advantage.
- Premium:Celebrity chef partnerships and non-stick ceramic lines target metro consumers with replacement cycles compressed to 5-7 years.
- Luxury:Copper-core and clad stainless steel configurations serve a narrow segment where thermal performance justifies price multiples over standard tri-ply alternatives.
Mid-range captures the volume expansion; premium segments show the steepest margin expansion as organized retail deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand clusters in Maharashtra, Gujarat, and Tamil Nadu where organized retail penetration is deepest. Urban kitchen upgrades in these states are shortening replacement cycles from decades to 5-7 years. BIS certification enforcement is filtering substandard imports and consolidating organized channel share in these concentrated markets.
Maharashtra
Mumbai households drive premium cookware adoption with tri-ply stainless steel and hard-anodized aluminum configurations replacing legacy cast iron. BIS ISI mark requirements for pressure cookers filter substandard imports entering through Nhava Sheva port. Organized retail expansion in Pune and Nagpur creates first-mover advantage for brands establishing exclusive distributor networks.
Gujarat
Surat and Ahmedabad commercial kitchens demand thermal efficiency and rapid heat recovery, favoring heavy-gauge aluminum for high-throughput restaurant service. FSSAI migration limit enforcement for heavy metals in food-contact surfaces forces substrate reformulation across aluminum lines. Domestic stainless steel fabrication capacity expands under PLI scheme incentives, compressing import dependency for raw coils.
Tamil Nadu
Chennai's apartment complexes accelerate induction-compatible product adoption as 40% of urban kitchens transition from gas. CDSCO oversight of ceramic coating imports creates customs clearance delays at Chennai port, exposing brands to currency fluctuation. Precision aluminum casting expertise concentrates in Kerala-bordering districts, constraining capacity scaling for greenfield facilities elsewhere.
Karnataka
Bangalore premium households adopt tri-ply construction technology at twice the rate of single-material alternatives, compressing SKU proliferation while raising average selling prices. BIS draft standards for new ceramic and granite-derived coatings determine which material platforms gain formal approval and channel access. Direct-to-consumer online channels capture 35% of cookware purchases without in-person inspection.
Delhi-NCR
Metro consumers complete over one-third of cookware purchases through branded storefronts on major e-commerce platforms, trusting certification marks over tactile evaluation. Uncertified aluminum vessels from small-scale units in neighboring Uttar Pradesh undercut ISI-compliant pricing in peripheral distribution channels. Skilled die-casting technician scarcity constrains pressure cooker manufacturing capacity scaling for northern facilities.
India Cookware Market Competitive Environment
Capacity expansion dominates the current landscape as PLI scheme incentives redirect capital toward domestic stainless steel fabrication. The vendor base splits between organized fabricators with BIS certification and unorganized small-scale units in northern states. Three archetypes anchor competitive positioning: southern manufacturing specialists with decades of safety valve expertise, celebrity-partnership premium brands targeting metro consumers, and diversified electrical goods conglomerates leveraging distribution scale. Dominant competitive moves include backward integration into substrate production and exclusive distributor network establishment in Tier-2 cities before local competitors consolidate.
Among southern manufacturing specialists, TTK Prestige and Hawkins Cookers exemplify the certification-compliant archetype with established replacement parts ecosystems. Wonderchef Home Appliances occupies the premium-tier position through chef partnerships and non-stick ceramic lines. These three anchors demonstrate how competitive positioning splits across manufacturing heritage versus brand marketing investment, with each representing a distinct path to organized channel dominance under tightening BIS enforcement.
| Leading Market Players |
|---|
| Vinod Cookware |
| Wonderchef Home Appliances |
| TTK Prestige |
| Butterfly Gandhimathi Appliances |
| Bajaj Electricals |
| Hawkins Cookers |
| Cello World |
| Bergner Group |
| Stovekraft |
| Others |
Value Chain & Pricing Dynamics
Precision die-casting technicians concentrated in Kerala and Tamil Nadu create labor-cost differentials that widen pricing-tier spreads between ISI-certified pressure cookers from organized fabricators and uncertified aluminum vessels from small-scale units in Uttar Pradesh and Bihar.
Pricing Analysis
Volume concentrates in budget stainless steel grades while margin expansion accrues to premium hard-anodized and tri-ply configurations. Pricing stratifies across premium, standard, and economy tiers driven by BIS certification level and brand heritage. Cost compression in economy segments is intensifying because nickel price volatility squeezes mid-tier fabricators lacking long-term raw material contracts. Rural household buyers exhibit highest price sensitivity, while metro apartment dwellers in Mumbai and Bangalore prioritize thermal performance over unit cost.
Supply Chain Analysis
Skilled aluminum casting workforce availability concentrates in southern India, constraining capacity scaling for northern greenfield facilities. Raw substrate supply draws from domestic 304-grade stainless steel coil production under PLI incentives, CDSCO-regulated ceramic coating imports, and nickel-chromium alloy shipments. Single-source vulnerability sits with ceramic coating batches cleared through Mumbai and Chennai ports. Distribution runs through exclusive distributor networks in Tier-2 cities and direct-to-consumer e-commerce platforms capturing metro demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over 304-grade stainless steel substrate production determines margin sustainability against nickel price swings and import dependency.
For Market Incumbents: Deploy exclusive distributor network establishment in Indore, Lucknow, and Coimbatore before local competitors consolidate channel access. Anchor ISI certification investment against unorganized sector undercutting from uncertified Uttar Pradesh and Bihar units. Capacity addition in Tamil Nadu leverages existing precision die-casting technician pools. For New Entrants and Emerging Players: The premium-to-economy price-point gap in induction-compatible product lines offers white-space capture in Bangalore and Hyderabad apartment complexes where gas-to-induction kitchen transitions accelerate. Tier-3 city organized retail penetration remains underdeveloped relative to Maharashtra and Gujarat saturation. Pursue celebrity chef partnership go-to-market angles mirroring Wonderchef's metro consumer acquisition model. For Investors and Strategic Acquirers: Re-rating potential sits with southern manufacturing specialists possessing BIS-compliant pressure cooker expertise and replacement parts ecosystems given PLI scheme acceleration of domestic fabrication capacity. Long-term viability hinges on substrate backward integration completion and ceramic coating formulation approval timelines. Monitor BIS draft standard finalization for new granite-derived coatings as inflection indicator for material platform channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive 304-grade stainless steel coil supply insulates margin from nickel price volatility and import delays. |
| Exclusive Distributor Network Expansion | First-mover positioning in Indore and Lucknow secures organized retail shelf space before local consolidation. |
| Induction-Compatible Product Line Launch | Ferromagnetic base configurations address 40% of urban kitchens transitioning from gas in apartment complexes. |
| BIS Certification Fast-Track Investment | Accelerated ISI mark acquisition filters substandard import competition and commands retail premium. |
| Ceramic Coating Formulation R&D | Proprietary BIS-compliant surface technologies reduce CDSCO import dependency and customs clearance exposure. |
Study Parameters
Document review covered BIS certification registries, FSSAI food-contact material safety filings, and PLI scheme disbursement records, complemented by interviews with pressure cooker manufacturing plant managers, organized retail category buyers, stainless steel procurement leads at downstream fabricators, and channel distribution partners. Secondary validation drew from customs import data for ceramic coatings, SEC filings of listed cookware manufacturers, and trade association production statistics. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segmented volume and value trajectories emerged from modeling across product type, material substrate, end-user category, and price tier dimensions throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycle compression, urban kitchen upgrade penetration curves, and regulatory enforcement intensity indicators. Nickel price volatility bands and BIS certification queue lengths fed scenario-weighted projections.
Underlying measurement precision varies by segment; organized retail channels in Maharashtra and Gujarat carry tighter precision than unorganized rural distribution in Bihar and Uttar Pradesh. Forecasts embed assumptions regarding PLI scheme continuation and BIS enforcement escalation. Material deviation in nickel alloy pricing spikes or ceramic coating import restriction triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
United Kingdom Air Purifier Market
Household Items
Thermos Drinkware Market
Household Items
Copper Water Bottle Market
Household Items
Multi Pocket Holders Market
Household Items
Ironing Boards Market
Household Items
Europe Digital Showers Market
Household Items
Sanitary Napkin Vending Machine Market
Household Items
Portable Humidifiers Market
Household Items
Sleeping Pods Market
Household Items
Deodorizer Bag Market
Household Items
Mosquito Repellent Candles Market
Household Items
Can Opener Market
Household Items
Sorting Hampers Market
Household Items
Cat Hair Remover Market
Household Items
South Africa Cookware Market
Household Items
Coffin and Cremation Urn Market