
 Brazil Cookware Market | 2026-2036
Brazil Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Cookware Market Insights
Aftermarket service revenue, including warranty extensions and replacement lid programs, is tilting margin pools away from one-time sales toward recurring consumer relationships. Tramontina leverages its integrated foundry-to-retail chain to control cost structures across stainless steel and cast iron lines. Brinox anchors its position through deep penetration of department store and supermarket channels in Brazil's urban centers. Newell Brands competes by extending its international design standards into locally adapted product ranges.
Brazil cookware comprises food preparation vessels and surface cooking equipment, typically fabricated from aluminum substrates with ceramic or polytetrafluoroethylene coatings, formed through deep drawing or gravity casting processes to achieve wall thicknesses of 2.5–4.0 mm for thermal uniformity. These products serve residential meal preparation and commercial foodservice operations requiring controlled heat distribution and durability under cyclic thermal loading. Stainless steel skillets command premium positioning among health-conscious households, while non-stick saucepans dominate volume sales through supermarket and online retail channels. Cast iron Dutch ovens sustain niche demand from culinary enthusiasts and high-end restaurants, though copper remains a marginal segment limited by cost and maintenance requirements.
ANVISA governs food-contact material safety approvals, while INMETRO administers mandatory conformity assessment programs for cookware sold in Brazil, and ABNT technical standards specify coating adhesion and thermal performance benchmarks. These frameworks elevate compliance costs for imported goods while creating protected terrain for domestic manufacturers with established certification pathways. Stakeholders must monitor evolving heavy metal migration limits and energy efficiency labeling requirements that could reshape material selection and pricing architecture.
Market Dynamics
ANVISA's tightening migration limits for heavy metals in food-contact coatings are forcing domestic foundries to retool substrate formulations and certification pathways. This regulatory compression is accelerating consolidation among smaller aluminum processors while elevating compliance costs for imported non-stick lines.
Growth Catalysts
- Urban household equipment upgrades:São Paulo and Rio de Janeiro households are replacing basic aluminum vessels with multi-layer stainless steel and ceramic-coated lines as disposable incomes expand. This replacement cycle is concentrating volume in premium supermarket and online channels.
- INMETRO conformity mandates:Mandatory certification programs for cookware thermal performance are filtering out uncertified imports. Domestic manufacturers with established testing relationships are capturing shelf space formerly held by gray-market Asian suppliers.
- Southeast commercial foodservice expansion:Restaurant and catering operations in Minas Gerais and Paraná are scaling kitchen capacity. This is pulling commercial-grade aluminum stockpots and induction-compatible skillets through foodservice distribution networks.
Market Restraints
- Aluminum ingot price volatility:Primary aluminum input costs swing with exchange rate fluctuations and energy pricing. This compresses margin predictability for gravity-casting foundries serving the mid-market segment.
- PTFE coating supply concentration:Fluoropolymer coating chemistries rely on imported resin systems. Brazilian manufacturers face extended lead times and currency exposure when sourcing from Asian and European chemical suppliers.
- Copper segment marginalization:High material costs and maintenance complexity limit copper cookware to niche culinary enthusiasts. This constrains portfolio diversification for brands seeking premium positioning above stainless steel tiers.
Strategic Opportunities
- Northeast urban market underpenetration:Recife, Salvador, and Fortaleza retail networks carry thinner cookware assortments than Southeast counterparts. Brands with regional distribution partnerships can establish first-mover positioning before national competitors expand.
- Energy efficiency labeling tailwinds:INMETRO's emerging thermal efficiency ratings for induction-compatible vessels will favor multi-ply construction. Early certification investments will secure preferred placement in appliance retailer bundled promotions.
- Direct-to-consumer channel innovation:Social commerce and subscription-based cookware curation are bypassing traditional department store markups. Digital-native entrants are capturing younger household formation cohorts before they lock into supermarket loyalty patterns.
Industry Challenges
- Coating formulation chemistry expertise gap:Ceramic and sol-gel non-stick alternatives require specialized application engineering. Foundries with legacy PTFE lines face retraining timelines and defect rate spikes during process transitions.
- ABNT thermal performance certification delays:Testing queue congestion at accredited laboratories extends product launch timelines. Manufacturers must book certification slots months ahead of seasonal demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Cookware Market |
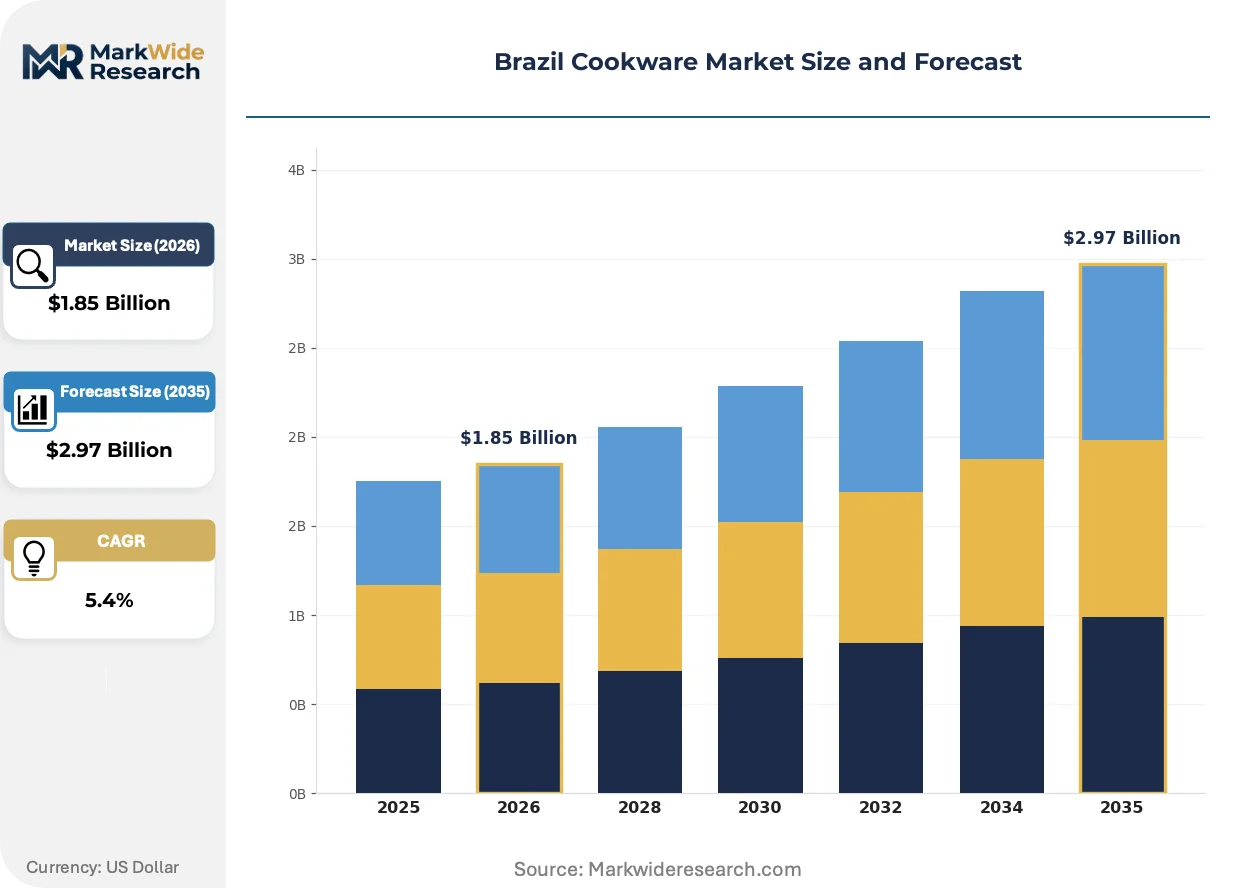
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skillets, Saucepans, Dutch Ovens, Cookware Sets Material: Stainless Steel, Cast Iron, Non-Stick, Copper Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets End User: Households, Restaurants, Catering Services, Hotels |
| Companies Covered | Newell Brands, Brinox, Tramontina, Panelux, MTA Panelas, Groupe SEB, The Vollrath Company, Rochedo, Meyer International Holdings Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Cookware Market Trends and Innovations
Smart manufacturing and regulatory transparency requirements are digitizing quality assurance and traceability across Brazilian cookware supply chains. These shifts are compressing defect detection cycles while elevating consumer-facing technical specifications.
Ceramic-reinforced sol-gel coating technology is digitizing non-stick surface engineering through automated spray deposition and real-time thickness monitoring. São Paulo-based foundries are adopting these systems to meet ANVISA's batch-level traceability mandates. The technology is compressing variation in coating adhesion metrics while enabling lot-specific digital certificates for retail packaging.
ANVISA's phased implementation of heavy metal migration testing protocols is tightening food-contact material documentation requirements. Manufacturers must now submit coating substrate interaction data across accelerated aging cycles. Stainless steel and cast iron lines face lighter compliance burdens than aluminum-ceramic hybrids, tilting portfolio investments toward uncoated metal categories.
Appliance retailer bundling is displacing standalone cookware purchasing among first-time household formers. Magazine Luiza and Casas Bahia are packaging induction cooktops with certified-compatible vessel sets at price points matching premium open-stock items. This channel shift is most visible in São Paulo's peripheral districts where housing stock electrification is accelerating.
Brazil Cookware Market Segmentation
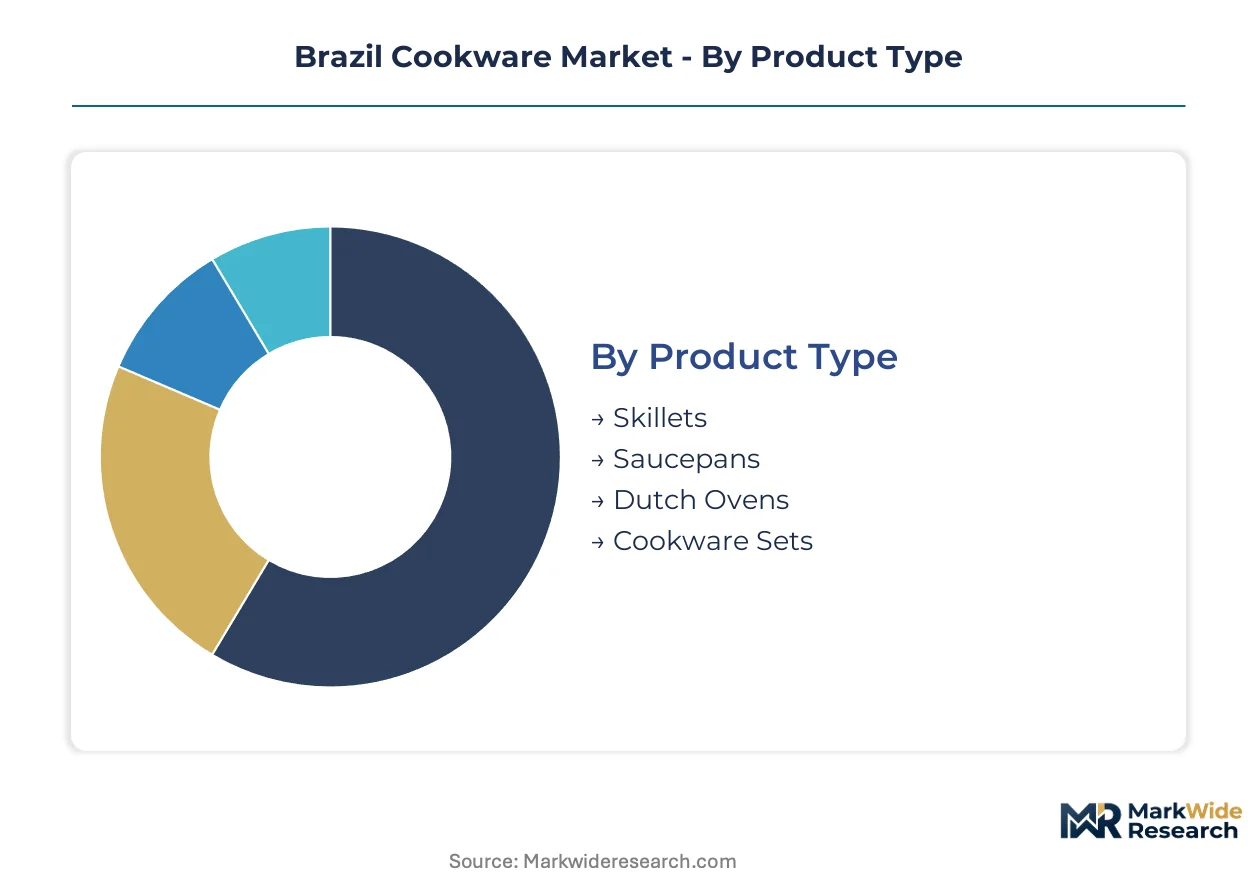
Cookware segmentation in Brazil reveals distinct replacement rhythms across product categories. Material composition and distribution channel access determine which households upgrade annually versus those on decade-long cycles.
Product Type:
Skillets turn over fastest at 3-5 year intervals as coating degradation forces replacement. Dutch ovens and complete sets move slowest, often lasting 15-20 years before discard.
- Skillets:Flat-bottomed vessels with 24-30 cm diameters, typically aluminum-ceramic or tri-ply stainless construction. São Paulo apartment kitchens drive replacement demand as induction cooktop adoption accelerates compatibility requirements.
- Saucepans:Medium-walled vessels with 1.5-3.0 liter capacities, dominated by PTFE-coated aluminum in supermarket channels. Rio de Janeiro households favor these for daily rice and bean preparation, concentrating volume in 18-20 cm base diameters.
- Dutch Ovens:Heavy-walled cast iron or enameled vessels with 4-7 liter capacities, serving slow-cooking traditions across Minas Gerais.
- Cookware Sets:Coordinated 5-12 piece assortments with matching aesthetics, purchased primarily for wedding registries in Southeast Brazil.
Saucepans dominate installed base. Skillets are where expansion concentrates.
Material:
Cost tiers separate health-conscious premium buyers from price-sensitive mass market segments. Stainless steel commands 3-4x aluminum price multiples while copper sits 10x above mid-market offerings.
- Stainless Steel:Austenitic 304-grade or tri-ply clad construction with 2.5-3.5 mm wall thickness. Health-conscious households in São Paulo's upper-middle districts favor these for acid-resistant cooking and dishwasher durability.
- Cast Iron:Gray iron or enameled vessels with 4-6 mm walls, seasoned or factory-coated. Traditional churrasco culture in Rio Grande do Sul sustains demand for uncoated grill pans and griddles.
- Non-Stick:Aluminum substrates with PTFE or ceramic sol-gel coatings, representing volume leadership through supermarket and online channels.
- Copper:2.0-2.5 mm hammered or spun vessels with tin or stainless linings, limited to professional kitchens and culinary enthusiasts in São Paulo.
Non-stick dominates installed base. Stainless steel is climbing the fastest.
Distribution Channel:
Channel concentration shapes pricing transparency and brand access. Online retail compresses margins fastest while department stores preserve premium positioning through service bundling.
- Online Retail:Marketplace platforms and direct-to-consumer sites with 15-30 day return windows. Younger household formers in Fortaleza and Salvador bypass traditional retail, pulling volume from established supermarket loyalty programs.
- Specialty Stores:Dedicated kitchenware retailers with in-store demonstration capacity. Curitiba and Belo Horizonte host concentrated specialty networks serving serious home cooks.
- Department Stores:Multi-category retailers with gift registry services and installment financing, anchoring premium brand presence in Rio de Janeiro.
- Supermarkets:High-frequency grocery channels with promotional stacking and private label penetration, dominating saucepans and basic skillets.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
End User:
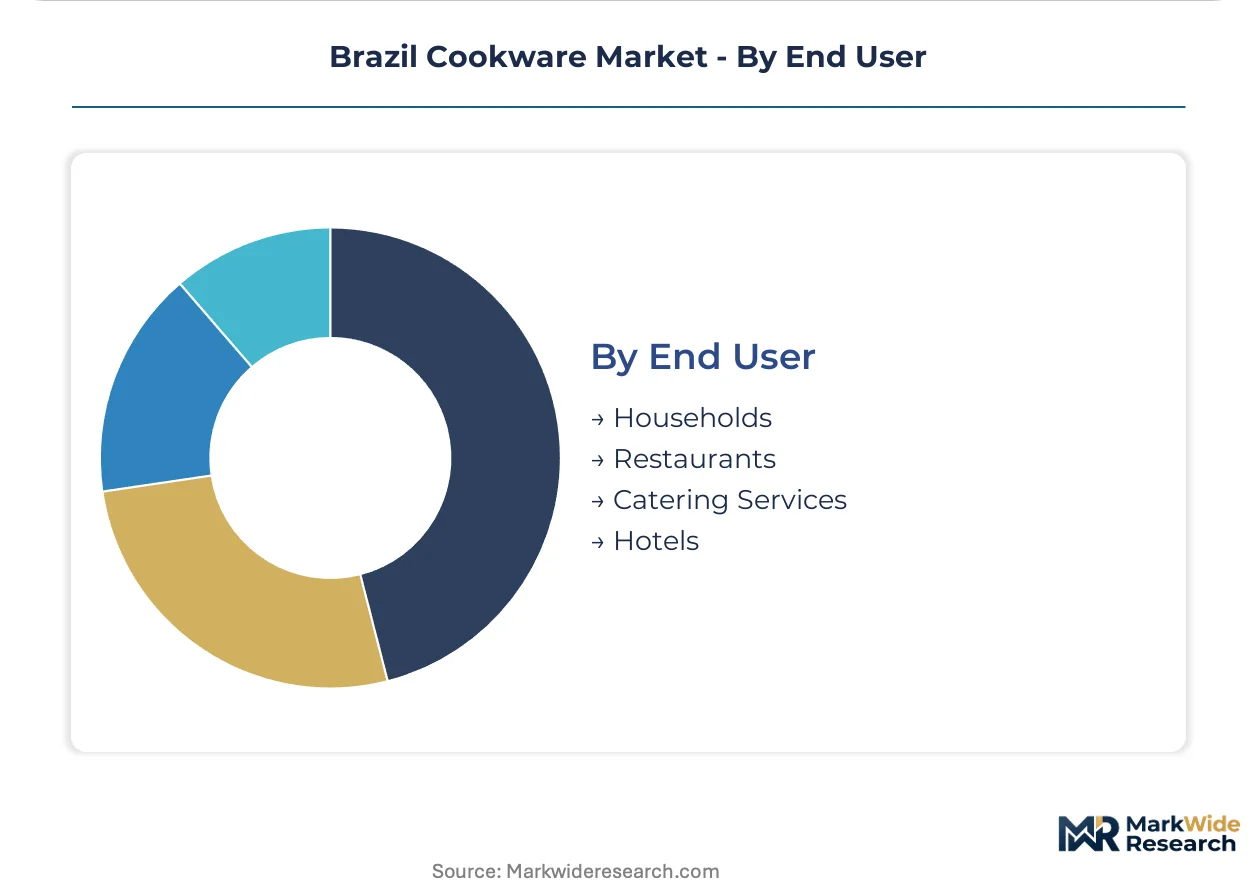
Volume scale separates residential replacement cycles from commercial equipment decisions. Restaurants replace worn stockpots quarterly while households stretch aluminum vessels across years.
- Households:Individual and family units purchasing 1-5 pieces annually, concentrated in Southeast Brazil's electrified housing stock with induction compatibility requirements.
- Restaurants:Full-service and fast-casual operations in São Paulo and Rio de Janeiro scaling kitchen capacity, pulling commercial-grade aluminum and clad stainless through foodservice distributors.
- Catering Services:Event and institutional food operations requiring volume-scale vessels with rapid thermal response for buffet service.
- Hotels:Hospitality operations with standardized kitchen specifications and procurement through group purchasing organizations.
Households dominate installed base. Restaurants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Brazilian sub-regions. Southeast households absorb premium stainless steel price multiples, while Northeast markets remain anchored to basic aluminum vessels despite rising disposable incomes.
São Paulo
Induction cooktop penetration drives replacement demand for ferromagnetic-compatible cookware. ANVISA's heavy metal migration protocols concentrate testing laboratory capacity in the metropolitan region. São Paulo's foundry clusters supply multi-ply stainless steel lines to national retail networks.
Rio de Janeiro
Apartment kitchen downsizing favors compact skillet and saucepan formats over bulky Dutch ovens. INMETRO conformity assessment programs filter uncertified imports through port-of-entry inspections. The city's specialty retail corridors serve health-conscious households seeking acid-resistant stainless construction.
Minas Gerais
Traditional slow-cooking culture sustains cast iron demand for bean and meat preparations. State-level industrial incentives support gravity-casting foundries serving commercial foodservice accounts. Belo Horizonte's restaurant density pulls commercial-grade aluminum stockpots through regional distribution hubs.
Rio Grande do Sul
Churrasco heritage maintains uncoated cast iron grill pan demand for outdoor cooking. The state's meat-processing economy links cookware procurement to protein industry expansion. Porto Alegre's retail networks carry deeper cast iron assortments than national averages.
Bahia
Underpenetrated retail infrastructure limits cookware assortment breadth versus Southeast benchmarks. Salvador's emerging middle-class households represent first-mover opportunity for brands establishing regional distribution partnerships. Social commerce channels bypass traditional supermarket markups among younger household formers.
Brazil Cookware Market Competitive Landscape
Capability concentration sits with integrated foundry-to-retail chains; scale advantage sits with diversified consumer goods conglomerates. The market structures around three tiers: domestic manufacturers with captive metallurgical capacity, international brands adapting global designs for local certification requirements, and regional specialists serving single-state markets. Strategic moves center on backward integration into aluminum processing and certification queue pre-booking at INMETRO-accredited laboratories.
Within the integrated manufacturing tier, Tramontina exemplifies foundry-to-retail control over cost structures. Among domestic specialists, Brinox anchors department store and supermarket penetration in urban centers. Newell Brands occupies a position bridging international design standards with locally adapted ranges. These three represent distinct archetypes: captive metallurgy, channel depth, and global-local portfolio balancing.
| Leading Market Players |
|---|
| Newell Brands |
| Brinox |
| Tramontina |
| Panelux |
| MTA Panelas |
| Groupe SEB |
| The Vollrath Company |
| Rochedo |
| Meyer International Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
Foundry undercapacity in São Paulo's metallurgical belt is compressing lead times for multi-ply stainless steel substrates while elevating pricing power among integrated manufacturers with captive smelting operations. This utilization squeeze forces mid-market processors to absorb aluminum ingot volatility or cede shelf space to backward-integrated competitors.
Pricing Analysis
Aftermarket service revenue from warranty extensions and replacement lid programs is shifting lifetime value calculations toward recurring consumer relationships rather than transactional vessel sales. Three-tier pricing structure across premium, standard, and economy levels separates induction-certified multi-ply lines from basic aluminum offerings, with certification grade and channel markup driving differentiation. Cost compression in the mid-market segment is intensifying because supermarket private labels are capturing volume through promotional stacking. Price-sensitive households in Northeast Brazil gravitate toward basic non-stick saucepans, while health-conscious buyers in São Paulo absorb stainless steel premiums.
Supply Chain Analysis
Supplier-financing facilities extended by Tramontina's captive foundry operations are locking regional distributors into exclusive procurement relationships. Geographic supply concentration rests on domestic aluminum smelting in Minas Gerais, ceramic sol-gel resin imports from Germany and Japan, and PTFE coating systems sourced from Chinese chemical suppliers. Raw material dependencies hinge on primary aluminum ingots, fluoropolymer resins, and austenitic stainless steel coils. Single-source vulnerability in fluoropolymer coating chemistry exposes Brazilian manufacturers to currency-driven cost spikes. Distribution runs through foodservice distributors for commercial accounts and supermarket networks for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized coating formulation expertise is scarce across Brazilian foundries, creating protected terrain for manufacturers with established ANVISA certification pathways and in-house application engineering capabilities.
For Market Incumbents: Entrench market position by pre-booking ABNT thermal performance certification slots at INMETRO-accredited laboratories ahead of seasonal demand windows, and deepen backward integration into aluminum gravity-casting capacity to offset ingot price volatility. Ceramic sol-gel coating substitution threatens legacy PTFE lines; vertical integration into substrate metallurgy preserves margin control against Asian import competition. For New Entrants and Emerging Players: Northeast urban corridors in Recife, Salvador, and Fortaleza carry thinner cookware assortments than Southeast benchmarks, offering first-mover positioning before national competitors expand distribution partnerships. Social commerce channels bypass traditional supermarket markups among younger household formers; direct-to-consumer subscription curation captures cohorts before loyalty patterns solidify. Appliance retailer bundling with induction cooktops represents the most penetrable entry vector. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with integrated foundry-to-retail chains and established aftermarket service programs. Long-term viability across the projection horizon favors targets with captive metallurgical capacity and ANVISA pre-certification assets. Monitor INMETRO queue congestion and heavy metal migration limit tightening as inflection indicators for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Captive supply from Minas Gerais foundries insulates margin structures from exchange rate volatility. |
| Ceramic Sol-Gel Coating Certification | ANVISA batch-level traceability mandates favor early adopters with automated spray deposition systems. |
| Northeast Distribution Partnership Expansion | Recife and Salvador retail networks offer undefended shelf space versus saturated Southeast channels. |
| Direct-to-Consumer Channel Launch | Social commerce bypasses Magazine Luiza and Casas Bahia markups among Fortaleza household formers. |
| Induction Compatibility Pre-Certification | INMETRO thermal efficiency ratings secure preferred placement in appliance retailer bundled promotions. |
Research Methodology
The analysis maps stainless steel, cast iron, aluminum-ceramic, and copper sub-sectors, each validated through primary interviews with foundry operations managers, supermarket category buyers, restaurant procurement heads, and INMETRO certification laboratory directors. Secondary sources include ANVISA food-contact material filings, ABNT technical standards documentation, customs import records for fluoropolymer resins, and Nielsen retail audit data from Southeast Brazil. Bottom-up vessel volume estimates triangulate against top-down household equipment replacement cycle modeling.
Assumptions held fixed across the analysis window include ANVISA regulatory phase-in timelines, INMETRO conformity assessment program scope, and aluminum ingot price banding. Segmentation dimensions modeled span material composition, product type, distribution channel, and end-user category with regional urbanization rates as an industry-specific overlay. CAGRs derive from replacement cycle compression in skillets versus extended durability in Dutch ovens, cross-referenced against disposable income elasticity in São Paulo and Rio de Janeiro metropolitan regions.
Practitioners should monitor INMETRO testing queue congestion, ANVISA heavy metal migration limit revisions, and induction cooktop penetration rates for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Paper Towels Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Folded Tissues Market
Household Items
Drinkware Market
Household Items
Aromatherapy Diffuser Market
Household Items
Nebulizing Diffuser Market
Household Items
Shoe Dryer Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Laundry Detergent Sheets Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Air Purifier Market
Household Items
Barbecue Grill Market
Household Items
Steam Cleaners Market
Household Items
Facial Tissue Paper Market