
 Smart Pool Skimmer Market | 2026-2036
Smart Pool Skimmer Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pool Skimmer Market Insights
Aftermarket service revenue from filter cartridge subscriptions and predictive maintenance alerts is tilting toward recurring monetization models in the smart pool skimmer space. Maytronics leverages its established dealer network to sustain aftermarket attach rates across North American markets. Pentair anchors its position through backward integration into pump and filtration ecosystems that lock in skimmer compatibility. Aiper competes aggressively on direct-to-consumer pricing, while Zodiac specializes in commercial-grade deployment contracts with hospitality chains.
A smart pool skimmer is an autonomous surface-cleaning device that uses buoyancy-regulated hull designs, mesh filtration baskets rated to 50-200 microns, and onboard pumps or passive water-flow channels to capture leaves, pollen, and petroleum films before sinkage. Its primary commercial purpose is reducing pump strain and chemical load while extending filtration system intervals. Robotic product types command the dominant margin pool due to integrated navigation algorithms and premium pricing, whereas solar-powered variants represent the fastest-growing category as off-grid pool installations multiply in sun-belt geographies. Wi-Fi-enabled technology segments attract the majority of R&D allocation because cloud connectivity enables usage-based service contracts and over-the-air firmware upgrades that manufacturers favor.
EPA recreational water-quality standards and state-level chemical-handling regulations in California and Florida shape product design by mandating debris-reduction performance that lowers sanitizer demand. FCC wireless certification requirements govern the RF modules embedded in Wi-Fi and Bluetooth skimmer variants, creating a compliance bottleneck for new entrants without existing radio-frequency expertise. Stakeholders must monitor how municipal water-conservation ordinances in drought-prone states redefine acceptable backwash frequency and filtration efficiency thresholds.

Market Dynamics
Connected-home ecosystems are consolidating control over outdoor maintenance automation, pulling smart pool skimmers into unified device management platforms and recalibrating hardware specifications toward API interoperability and voice-assistant compatibility.
Growth Catalysts
- EPA recreational water-quality standards:Federal debris-reduction mandates in the United States lower permissible sanitizer loads, forcing residential and commercial pool operators toward sensor-integrated skimmer deployment.
- Wi-Fi module integration:Cloud connectivity architectures enable usage-based service contracts and over-the-air firmware upgrades that manufacturers prioritize in R&D allocation.
- Sun-belt pool density:Florida, California, and Texas concentrate demand where smart-home penetration overlaps with year-round pool operation.
Market Restraints
- FCC wireless certification:RF module compliance creates a bottleneck for new entrants lacking existing radio-frequency engineering capabilities.
- Lithium-ion cell supply:Battery chemistry cost volatility constrains margin expansion for cordless robotic variants.
- Passive solar skimmer performance:Off-grid variants face capture-rate limitations in low-wind conditions that degrade user satisfaction metrics.
Strategic Opportunities
- Hospitality chain standardization:Hotel and resort operators seek fleet-wide deployment contracts with predictive maintenance integration.
- Subscription cartridge services:Recurring filter replacement revenue models attach to hardware sales and extend customer lifetime value.
- Municipal water-conservation ordinances:Drought-prone jurisdictions in California and Arizona are redefining backwash frequency limits that favor high-efficiency filtration skimmers.
Industry Challenges
- Mesh filtration engineering:50-200 micron rating consistency across production batches demands precision manufacturing that strains mid-tier suppliers.
- Pump ecosystem compatibility:Backward integration by incumbent filtration manufacturers locks skimmer interoperability to proprietary protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pool Skimmer Market |
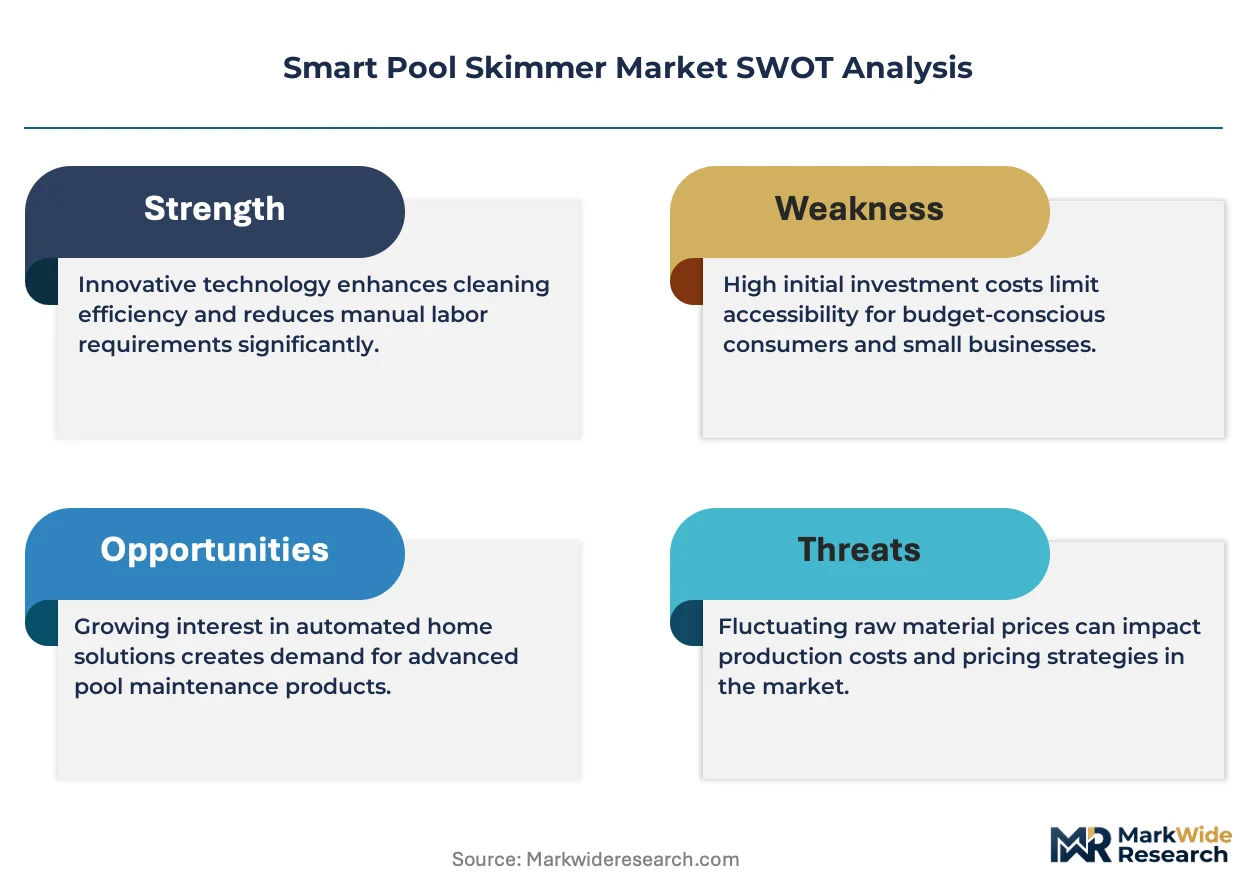
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,032.06 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Manual, Solar-Powered, Robotic Technology: Wi-Fi, Bluetooth, GPS, Sensors Deployment: Residential, Commercial, Industrial, Public Facilities End User: Homeowners, Pool Service Companies, Hotels, Recreational Centers |
| Companies Covered | Aiper, Maytronics, Pentair, Hayward Industries, iRobot Corporation, Zodiac, Betta, Solar-Breeze, PoolPure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pool Skimmer Market Trends and Innovations
Autonomous surface-cleaning architectures are converging with predictive analytics platforms, compressing the traditional reactive maintenance cycle into preemptive debris management systems.
Navigation algorithms are migrating from random-collision patterns to LiDAR-assisted mapping and computer-vision edge detection. Residential buyers in high-value pool markets adopt these premium robotic variants despite price premiums. The technology is migrating from luxury-tier positioning toward mid-market standardization as sensor costs decline and software licensing models proliferate.
California state-level chemical-handling regulations and Florida county health ordinances mandate debris-capture performance thresholds that reduce chlorine demand. Equipment manufacturers redesign filtration basket geometry and pump flow rates to satisfy these prescriptive standards. Commercial operators in these jurisdictions accelerate replacement cycles to maintain compliance.
Aftermarket service unbundling separates hardware ownership from consumable fulfillment and predictive alert subscriptions. Direct-to-consumer channels displace traditional pool-service dealer networks for initial purchase decisions. This pattern concentrates in metropolitan markets with established e-commerce logistics infrastructure and tech-forward homeowner demographics.
Smart Pool Skimmer Market Segmentation
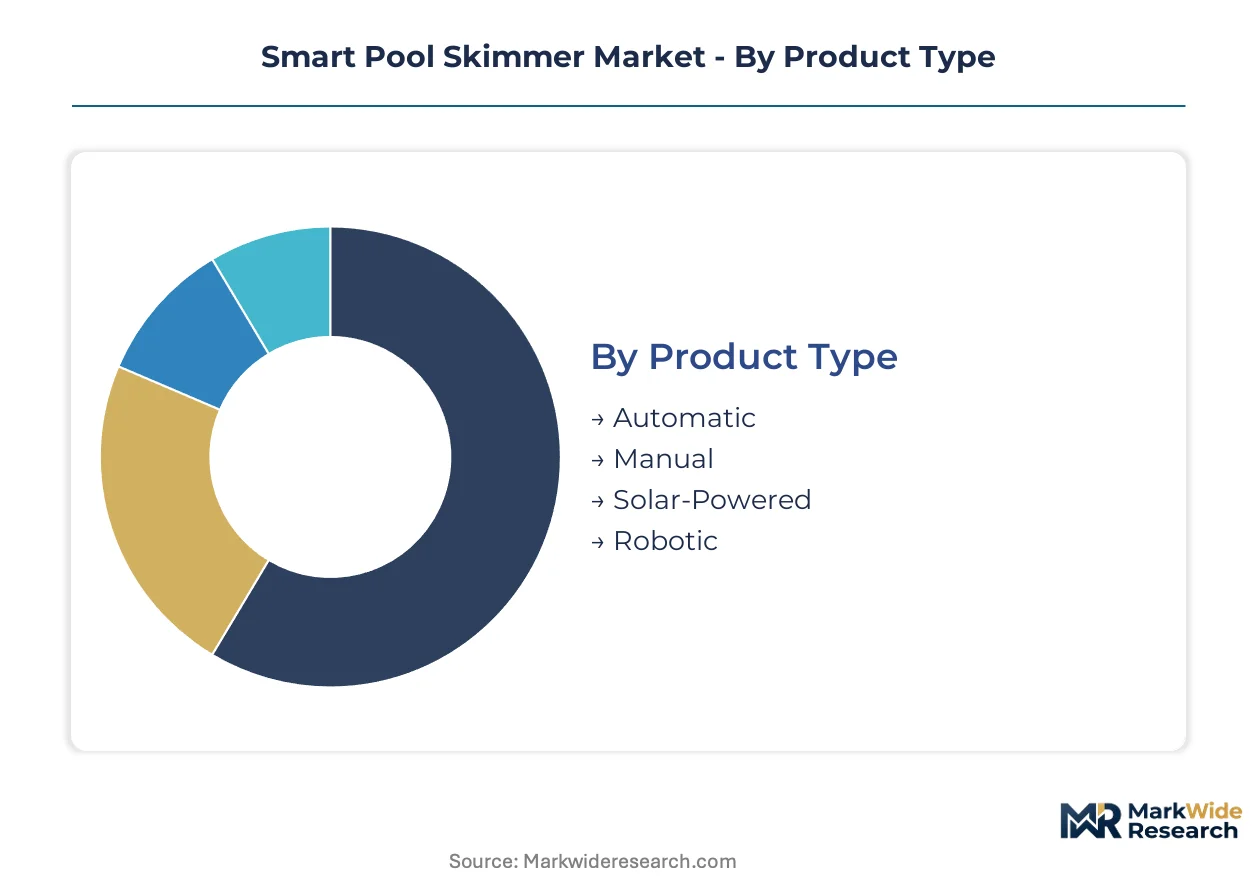
Segmentation in the smart pool skimmer market exposes divergent replacement cycles and margin profiles. Product type determines hardware refresh cadence, while technology and deployment choices shape recurring revenue attachment and regulatory compliance burdens.
Product Type:
Robotic skimmers turn over fastest at three-to-five year replacement cycles, while solar-powered variants stretch toward eight-to-ten years. Manual and automatic categories occupy intermediate positions where component fatigue and filtration efficiency degradation drive upgrade timing.
- Robotic:Integrated navigation algorithms and onboard pump systems enable autonomous debris mapping with minimal human intervention. Demand concentrates in Florida and California residential markets where EPA water-quality guidelines mandate debris-reduction performance that lowers sanitizer loads. Premium pricing sustains manufacturer margins despite lithium-ion battery cost volatility.
- Solar-Powered:Passive water-flow channels and photovoltaic cell arrays eliminate cord dependency for off-grid pool installations. Sun-belt geographies in Texas and Arizona favor this category where municipal water-conservation ordinances redefine acceptable backwash frequency thresholds. Capture-rate limitations in low-wind conditions constrain user satisfaction metrics and warranty claim exposure.
- Automatic:Buoyancy-regulated hull designs with mesh filtration baskets rated to 50-200 microns capture surface debris through continuous pump-driven suction. Pool service companies in high-density metropolitan markets favor automatic units for predictable maintenance scheduling.
- Manual:Hand-operated pole attachments with detachable mesh heads serve budget-conscious homeowners and backup redundancy applications. Hospitality chains deploy manual skimmers as secondary cleaning protocols alongside automated primary systems.
Robotic skimmers anchor the volume base while solar-powered variants gain share at the steepest rate.
Technology:
Cost tier stratification separates cloud-connected architectures from basic RF modules. Wi-Fi-enabled segments command R&D priority and service contract attachment, while Bluetooth and GPS occupy mid-tier positioning with narrower functionality scopes.
- Wi-Fi:Cloud connectivity architectures enable over-the-air firmware upgrades and usage-based service contracts that manufacturers prioritize in development roadmaps. FCC wireless certification requirements create compliance bottlenecks for new entrants lacking radio-frequency engineering capabilities. Residential buyers in tech-forward demographics accept subscription bundling for predictive maintenance alerts.
- Sensors:Multi-parameter water-quality probes measuring turbidity, temperature, and chemical balance integrate with skimmer housings for ecosystem-wide automation. Commercial operators in California and Florida accelerate sensor-integrated deployment to satisfy state-level chemical-reduction mandates.
- Bluetooth:Short-range RF modules support localized smartphone control without internet dependency. Budget residential segments favor Bluetooth for simplified pairing and lower hardware cost structures.
- GPS:Geofencing and location-tracking capabilities serve fleet management applications for multi-pool commercial operators. Large hospitality chains with distributed properties leverage GPS for asset tracking and maintenance routing optimization.
Wi-Fi-enabled technology commands the dominant R&D allocation while sensor integration climbs fastest among commercial deployment specifications.
Deployment:
Application context dictates performance requirements and procurement authority structures. Residential buyers emphasize direct-to-consumer channels and voice-assistant compatibility, while commercial and industrial segments demand fleet-scale manageability and predictive maintenance integration.
- Residential:Connected-home ecosystem integration pulls smart pool skimmers into unified device management platforms with API interoperability requirements. Florida, California, and Texas concentrate demand where smart-home penetration overlaps with year-round pool operation. EPA recreational water-quality standards accelerate sensor-integrated skimmer adoption among compliance-conscious homeowners.
- Commercial:Hotels and resort operators seek fleet-wide deployment contracts with standardized equipment specifications and consolidated billing structures. Predictive maintenance integration reduces downtime exposure in high-occupancy hospitality environments.
- Public Facilities:Municipal pools and community recreation centers face procurement complexity from multi-stakeholder approval chains and public-bidding requirements. County health ordinances in Florida mandate debris-capture performance thresholds that drive replacement cycle acceleration.
- Industrial:Processing plants and manufacturing facilities with cooling ponds or wastewater containment applications require heavy-duty filtration ratings and chemical-resistant materials. Specialized engineering demands limit supplier participation in this niche deployment category.
Residential deployment anchors the volume base while commercial segments gain share at the steepest rate.
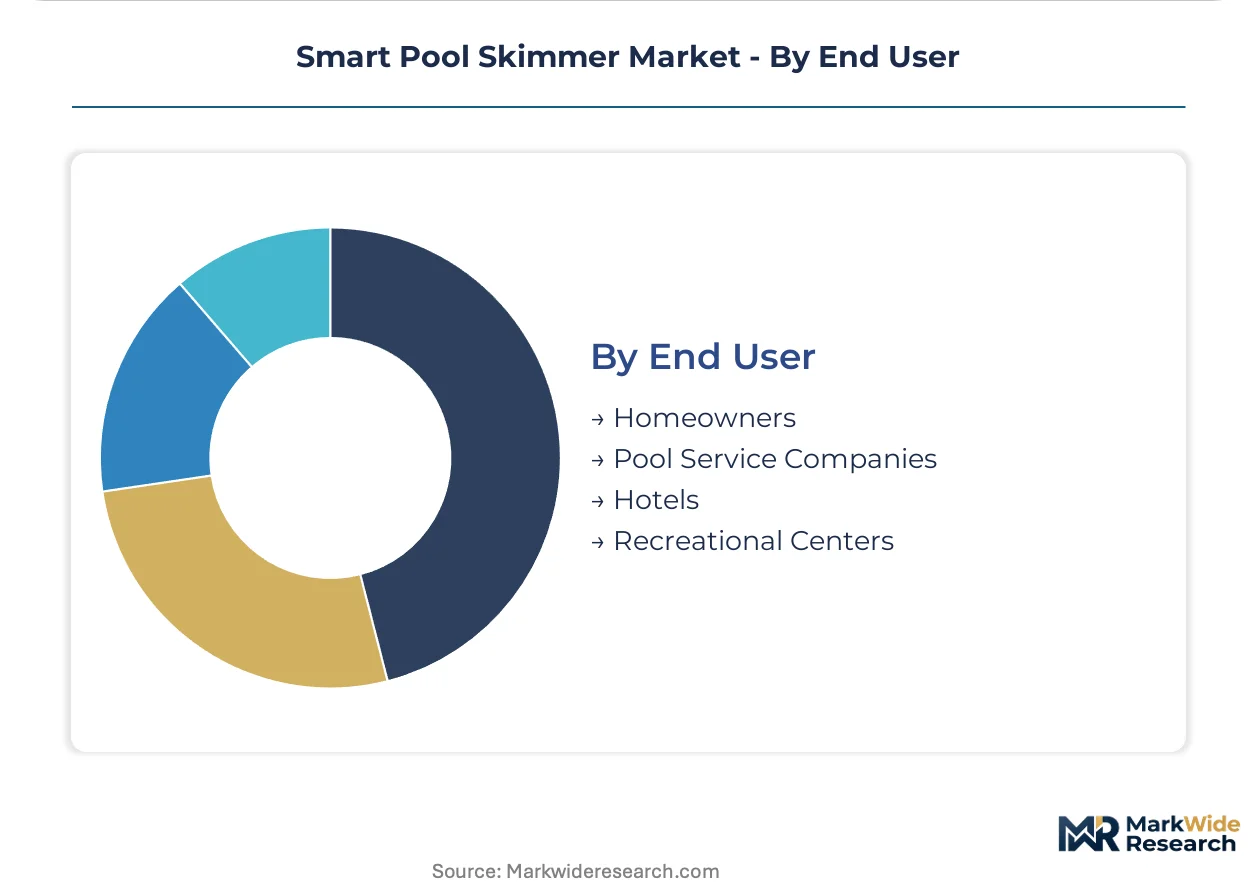
End User:
Customer type determines purchase authority, service expectations, and lifetime value potential. Homeowners exercise direct decision-making with price sensitivity, while institutional buyers prioritize standardization and vendor consolidation.
- Homeowners:Direct-to-consumer channel migration displaces traditional pool-service dealer networks for initial purchase decisions. E-commerce logistics infrastructure and tech-forward demographics in metropolitan markets accelerate this pattern. Aftermarket service unbundling separates hardware ownership from consumable fulfillment subscriptions.
- Hotels:Brand-standardization mandates across property portfolios create volume concentration for approved vendor relationships. Predictive maintenance integration and fleet-wide visibility tools command procurement priority over unit-level pricing.
- Pool Service Companies:Dealer network relationships with incumbent manufacturers like Maytronics sustain aftermarket attach rates across North American markets. Route-density optimization drives equipment standardization preferences for simplified parts inventory and technician training.
- Recreational Centers:Municipal ownership structures impose budget-cycle constraints and competitive-bidding requirements that elongate procurement timelines. State-level chemical-handling regulations in California reshape filtration basket geometry specifications for compliance maintenance.
Homeowners anchor the volume base while hotels gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between sun-belt geographies with year-round pool operation and temperate climates where seasonal deployment drives different technology preferences. The United States concentrates premium robotic adoption, while Australia and Southern Europe favor solar-powered variants for energy-conscious outdoor living. Middle Eastern markets prioritize commercial-grade fleet management for hospitality infrastructure.
United States
Florida, California, and Texas generate the densest demand overlap between smart-home penetration and residential pool density. EPA recreational water-quality standards and state-level chemical-reduction mandates in California and Florida accelerate sensor-integrated skimmer deployment. Miami-Dade and Orange County health ordinances enforce debris-capture performance thresholds that shorten commercial replacement cycles.
Australia
Solar-powered skimmers dominate residential adoption in Queensland and New South Wales where off-grid pool installations and municipal water-conservation ordinances intersect. The country's national environmental regulator enforces strict chemical-handling protocols for backyard pools that favor automated debris management. Sydney's metropolitan pool service market concentrates fleet-standardization demand among route-dense operators.
Germany
Technical buyers in Bavaria and North Rhine-Westphalia prioritize Wi-Fi-enabled architectures with API interoperability for connected-home integration. EU REACH chemical regulations and national sustainability frameworks reshape filtration efficiency requirements for imported equipment. Stuttgart's industrial automation cluster spurs precision-manufacturing partnerships for mesh filtration component sourcing.
United Arab Emirates
Hospitality chains in Dubai and Abu Dhabi drive commercial fleet deployment with predictive maintenance integration for high-occupancy resort environments. The country's national standards body mandates wireless certification protocols that filter new market entrants. Dubai's smart city infrastructure investments pull outdoor maintenance devices into unified building management platforms.
Spain
Andalusia and Catalonia concentrate residential demand where Mediterranean climate patterns extend pool operating seasons. Regional water-conservation directives in drought-prone provinces redefine acceptable backwash frequency thresholds that favor high-efficiency filtration skimmers. Barcelona's tech-forward homeowner demographics accelerate direct-to-consumer channel migration for initial purchase decisions.
Smart Pool Skimmer Market Competitive Landscape
Capability concentration sits with specialist robotics firms possessing navigation algorithm expertise; scale advantage sits with diversified filtration equipment manufacturers leveraging backward integration into pump ecosystems. The market structures around three archetypes: integrated pool equipment conglomerates, pure-play robotic specialists, and solar-powered niche innovators. Dominant competitive moves include dealer network consolidation for aftermarket attach rates and cloud-platform development for recurring service revenue.
Among diversified filtration equipment manufacturers, Pentair and Maytronics occupy positions anchored by captive distribution networks and ecosystem lock-in strategies. Aiper exemplifies the direct-to-consumer archetype competing aggressively on pricing accessibility. Zodiac sits within the commercial-grade deployment tier specializing in hospitality chain standardization contracts. These three named entities represent distinct strategic postures without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| Aiper |
| Maytronics |
| Pentair |
| Hayward Industries |
| iRobot Corporation |
| Zodiac |
| Betta |
| Solar-Breeze |
| PoolPure |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in precision mesh filtration manufacturing across Guangdong and Zhejiang provinces is compressing supplier margins and amplifying pricing power for robotic skimmer incumbents with captive component sourcing. This utilization squeeze feeds back into procurement decisions, pushing mid-tier assemblers toward longer-term offtake commitments to secure micron-rated basket supply.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-one manufacturers and lithium-ion cell suppliers, insulating incumbents from spot-market volatility that punishes smaller competitors. Pricing stratifies across premium, standard, and economy tiers based on navigation algorithm sophistication and Wi-Fi certification status. Cost compression in the solar-powered tier is intensifying because photovoltaic cell import duties have expanded, while pool service companies exhibit the highest price sensitivity due to route-density economics that prioritize equipment standardization over feature premiums.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for RF module and battery pack sourcing. Component manufacturing concentrates in China, South Korea, and Vietnam, with mesh filtration engineering anchored in German precision-tooling partnerships. Raw material dependencies span lithium carbonate, rare-earth magnets for pump motors, and marine-grade ABS polymers. Distribution runs through dealer networks in North America and direct-to-consumer platforms in metropolitan European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospitality chains consolidating fleet-standardization mandates, fragmenting procurement authority away from individual property managers toward centralized vendor selection committees.
For Market Incumbents: Insulate aftermarket revenue streams by deepening backward integration into filter cartridge production and predictive maintenance cloud platforms. Lock in dealer network exclusivity agreements before direct-to-consumer channels erode route-density economics for pool service companies. Prioritize FCC pre-certification investments to accelerate Wi-Fi-enabled product launches ahead of regulatory bottlenecks.
For New Entrants and Emerging Players: Build out white-space positioning in the solar-powered category for Arizona and Texas municipal markets where water-conservation ordinances favor off-grid installations. Target the commercial hospitality segment in Dubai and Abu Dhabi with fleet-management GPS integration. Pursue API interoperability certifications that enable connected-home ecosystem inclusion without ecosystem-owner development costs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among robotic specialists with established subscription cartridge services and over-the-air firmware upgrade capabilities. Long-term viability across the analysis window favors acquisition targets with navigation algorithm IP and existing FCC certification portfolios rather than hardware-only assemblers. Monitor lithium-ion cell supply contract renegotiation cycles as an inflection indicator for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Cartridge Services | Recurring revenue from filter replacements extends customer lifetime value beyond hardware margins. |
| API Interoperability Certification | Connected-home ecosystem inclusion in Alexa and Google Home platforms expands addressable residential demand. |
| FCC Pre-Certification Investment | Accelerated RF module approval timelines compress new product introduction cycles for Wi-Fi-enabled variants. |
| Fleet Management Platform Development | Multi-property hospitality operators in Dubai and Miami consolidate vendor relationships around predictive maintenance visibility. |
| Backward Integration into Pump Motors | Captive supply of brushless DC components insulates robotic skimmer margins from rare-earth magnet price volatility. |
Research Methodology
Operator-level perspectives from pool service company route managers, hospitality procurement directors, smart-home platform engineers, and filtration equipment R&D heads anchored the qualitative base. Primary interview insights were cross-validated against EPA regulatory filings, FCC equipment authorization databases, state-level chemical-handling statutes in California and Florida, and import customs records for lithium-ion cell and photovoltaic component trade flows. Bottom-up unit shipment estimates by product type and technology tier were triangulated against top-down market sizing derived from pump and filtration equipment manufacturer revenue disclosures.
Scenario-bracketing around lithium-ion cost trajectories and solar-cell efficiency curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, connectivity technology, deployment context, and regional regulatory cluster. CAGRs were derived from trend-line extrapolation of replacement cycle compression and smart-home penetration rates, with cross-checks against municipal water-conservation ordinance adoption timelines and hospitality chain capital expenditure patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer entrants or battery chemistry innovators would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Rimless Toilets Market
Household Items
Laundry Dryer Sheets and Bars Market
Household Items
US Digital Showers Market
Household Items
Electric Soap Dispenser Market
Household Items
Global Nap Pod Market
Household Items
Facial Tissue Market
Household Items
Electric Clothes Drying Hanger Market
Household Items
Pet Stain Remover and Odour Control Market
Household Items
Plastic Bathtub Market
Household Items
Replacement Sheets Market
Household Items
Fan Market
Household Items
Smart Toilet Market
Household Items
Toilet Rim Blocks Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
Powered Lawn Mowers Market
Household Items
Global Laptop Tables Market