
 Enameled Cookware Market | 2026-2036
Enameled Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Enameled Cookware Market Intelligence
Consumer and regulatory pressure against per- and polyfluoroalkyl substances (PFAS) in traditional non-stick coatings is hardening demand for inert alternatives like enamel. Le Creuset France SAS leverages its premium brand positioning and extensive color options to command a significant market presence in this environment. Lodge Manufacturing Company competes through its focus on durable, American-made cast iron products, appealing to a value-conscious consumer base. Staub, part of the ZWILLING group, differentiates with specific design features like self-basting lids that enhance cooking performance.
Enameled cookware consists of a metal base, most often cast iron or carbon steel, which is fused with a vitreous enamel glaze through a high-temperature firing process. This creates a non-porous, non-reactive surface valued for its even heat distribution, superior heat retention, and resistance to acidic foods. Cast Iron remains the dominant material choice due to these thermal properties, with Dutch Ovens representing a high-value product category. The Households end-user segment drives the majority of volume, seeking versatile pieces for baking, roasting, and frying applications.
Regulatory oversight from bodies like the U.S. Food and Drug Administration (FDA) and compliance with Europe's REACH regulation governs the composition of enamel glazes. These frameworks set strict limits on heavy metals like lead and cadmium, ensuring products are safe for food contact and building consumer trust. Future competitive advantage will depend on balancing the aesthetic appeal of vibrant, durable glazes with the rising costs of raw materials and energy-intensive manufacturing processes.
Market Dynamics
The market's trajectory is shaped by regulatory pressure on food-contact materials, particularly per- and polyfluoroalkyl substances. This scrutiny elevates demand for inert alternatives like vitreous enamel, especially within health-conscious household segments seeking non-toxic cooking surfaces.
Growth Catalysts
- PFAS Regulation:Tightening regulations on PFAS under frameworks like the EU's REACH steer consumers toward inert enamel, challenging traditional non-stick coatings.
- Home Cooking Culture:The expansion of home cooking in affluent households, particularly in the United States, drives demand for durable and aesthetically versatile cookware.
- Material Performance:Enameled cast iron's superior heat retention and distribution are critical for techniques like braising, reinforcing its position in the Households segment.
Market Restraints
- Raw Material Volatility:Manufacturing margins are exposed to price fluctuations in pig iron and the high energy costs required for furnace firing.
- Product Weight and Fragility:The substantial weight of cast iron is a usability barrier for some consumers, while the enamel surface remains vulnerable to chipping.
- Substitution from Alternatives:Lower-cost stainless steel and ceramic non-stick cookware present a substitution threat, particularly in price-sensitive consumer segments.
Strategic Opportunities
- Emerging Market Penetration:Targeting affluent urban consumers in Asia-Pacific, where Western culinary trends are gaining traction, offers a key growth avenue.
- Niche Product Development:Creating specialized items for applications like bread baking or ethnic cuisines can capture high-value segments beyond standard Dutch ovens.
- Direct-to-Consumer Channels:Building DTC e-commerce platforms allows brands to control the customer experience, improve margins, and gather valuable consumer data.
Industry Challenges
- Navigating Glaze Regulations:Maintaining compliance with evolving heavy metal limits in enamel glazes, set by bodies like the FDA and ECHA, requires continuous testing and reformulation.
- Energy-Intensive Production:Managing the high energy consumption of the casting and enameling processes poses a significant operational cost challenge amid rising global energy prices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enameled Cookware Market |
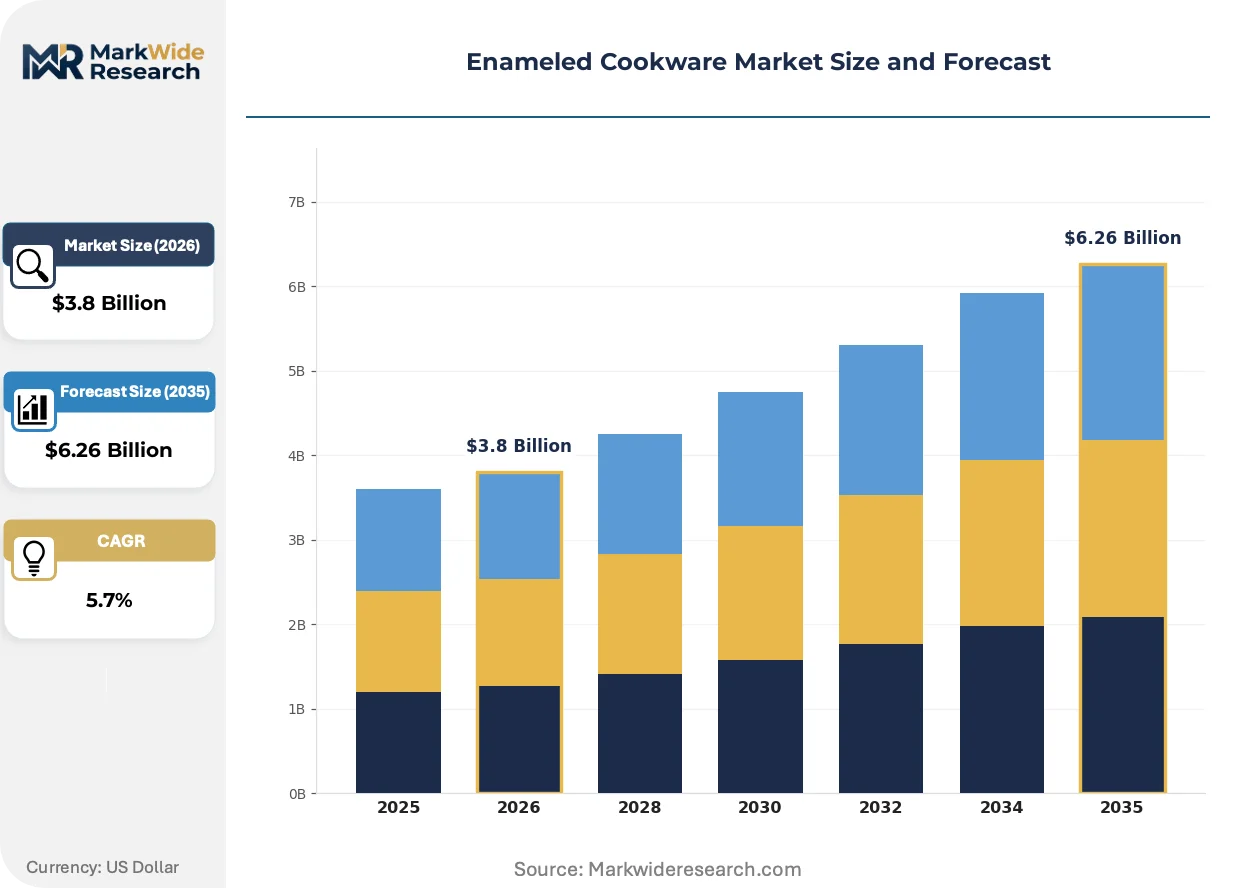
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skillets, Dutch Ovens, Stock Pots, Bakeware Material: Ceramic, Cast Iron, Aluminum, Steel End User: Households, Professional Chefs, Restaurants, Catering Services Application: Baking, Frying, Boiling, Roasting |
| Companies Covered | Le Creuset France SAS, Lodge Manufacturing Company, Staub, Tramontina, Cuisinart, ZWILLING, Emile Henry, Camp Chef, Williams-Sonoma, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enameled Cookware Market Strategic Shifts & Innovations
Material science advancements and a focus on visual customization are defining the next wave of product development in the enameled cookware sector. These shifts address both performance demands and the role of cookware as a kitchen decor element.
Advanced glazing techniques are enabling the creation of more durable, chip-resistant enamel surfaces with unique finishes like gradients and mattes. Premium household consumers are rapidly adopting these innovations, seeking both enhanced longevity and greater aesthetic choice for their kitchens. This focus on customizable aesthetics and performance tiers is modularizing the market, allowing brands to offer distinct product lines at varied price points.
The U.S. Food and Drug Administration (FDA) enforces strict regulations on food contact substances, specifically concerning lead and cadmium in glazes. This environment compels manufacturers to invest in rigorous quality control and transparent sourcing for their enamel frit and pigments. Premium brands leverage their compliance and safety certifications as a key marketing differentiator to build trust with health-conscious consumers.
Consumer purchasing decisions are increasingly shaped by social media influencers and online cooking communities that feature aspirational cookware. This dynamic shifts influence away from traditional retail toward digital content, making a brand's online presence and partnerships critical. The trend is most prominent among younger consumers in the United States and Western Europe, who treat cookware as a lifestyle statement.
Enameled Cookware Market Segmentation
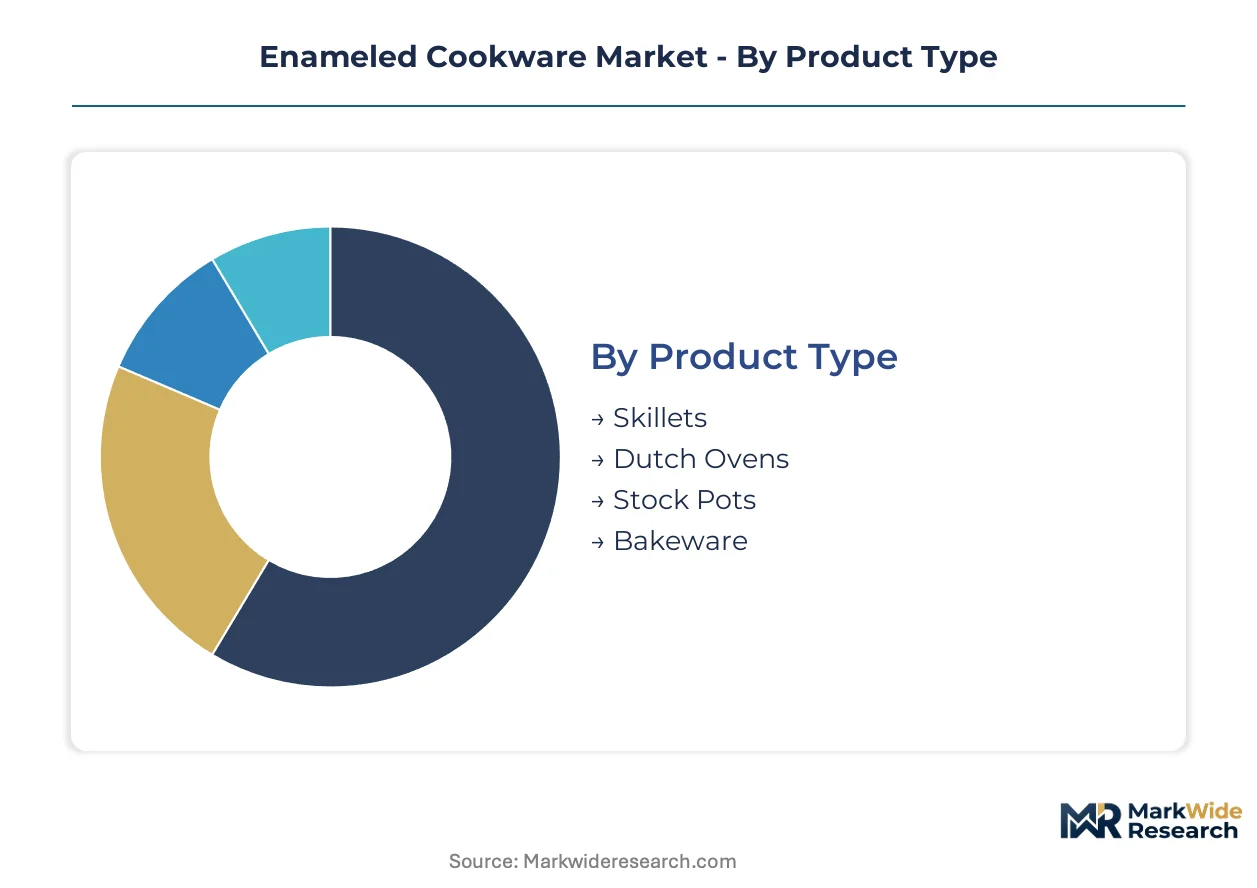
The enameled cookware market's segmentation reveals distinct consumer preferences and manufacturing specializations across product forms and materials. Understanding these segments is crucial for brands to align product development with demand patterns and optimize distribution strategies.
Product Type:
Supply concentration for enameled cookware heavily favors versatile pieces that serve multiple culinary functions.
- Dutch Ovens:These heavy, lidded pots are ideal for slow cooking, braising, and baking due to their superior heat retention and even heat distribution. Demand is strong in affluent households across the United States, where home cooking trends emphasize gourmet preparation.
- Skillets:Enameled skillets offer a non-reactive surface for frying, searing, and sautéing, preventing acidic foods from reacting with the metal base. Consumers in Western Europe prioritize these for everyday cooking versatility and durability.
- Stock Pots:Larger capacity pots designed for boiling, simmering stocks, and preparing soups. These are essential for households and professional kitchens alike.
- Bakeware:Includes enameled dishes and pans used for baking casseroles, gratins, and desserts. Their aesthetic appeal makes them popular for oven-to-table serving.
Dutch Ovens absorbs the bulk of installed capacity; Bakeware is expanding most quickly.
Material:
The volume of material processing for enameled cookware is dominated by traditional, high-performance substrates.
- Cast Iron:This material forms the base for the majority of premium enameled cookware, valued for exceptional heat retention and durability after the vitreous enamel application. Demand concentrates in markets like Germany, where consumers prioritize long-lasting kitchen investments.
- Steel:Enamel applied to carbon steel or stainless steel offers a lighter alternative to cast iron, providing good heat conductivity and resistance to chipping. These products often target budget-conscious consumers seeking functionality.
- Ceramic:While some ceramic cookware features an enamel-like glaze, true enameled ceramic involves a metal substrate. These are often chosen for their aesthetic appeal and perceived natural properties.
- Aluminum:Enameled aluminum cookware provides a lightweight option with good heat conduction, appealing to consumers seeking ease of handling.
The adoption of Cast Iron remains widespread, while Ceramic secures niche applications.
End User:
Customer type dictates product specifications and purchasing volume across the enameled cookware market.
- Households:This segment represents the largest volume driver, with consumers seeking durable, aesthetically pleasing, and versatile cookware for daily meal preparation. Consumers in the United States increasingly invest in premium enameled pieces for both utility and kitchen decor.
- Restaurants:Professional kitchens require heavy-duty, high-performance enameled cookware capable of withstanding rigorous use and frequent cleaning. Durability and heat efficiency are paramount for these commercial buyers.
- Professional Chefs:Individual chefs often invest in specialized enameled pieces that meet specific culinary requirements, valuing precision and performance. They influence broader consumer trends through their endorsements and usage.
- Catering Services:These operations utilize enameled cookware for large-batch preparation and transport, prioritizing robust construction and even heating.
Demand from Households dictates product innovation, with Professional Chefs showing consistent growth.
Application:
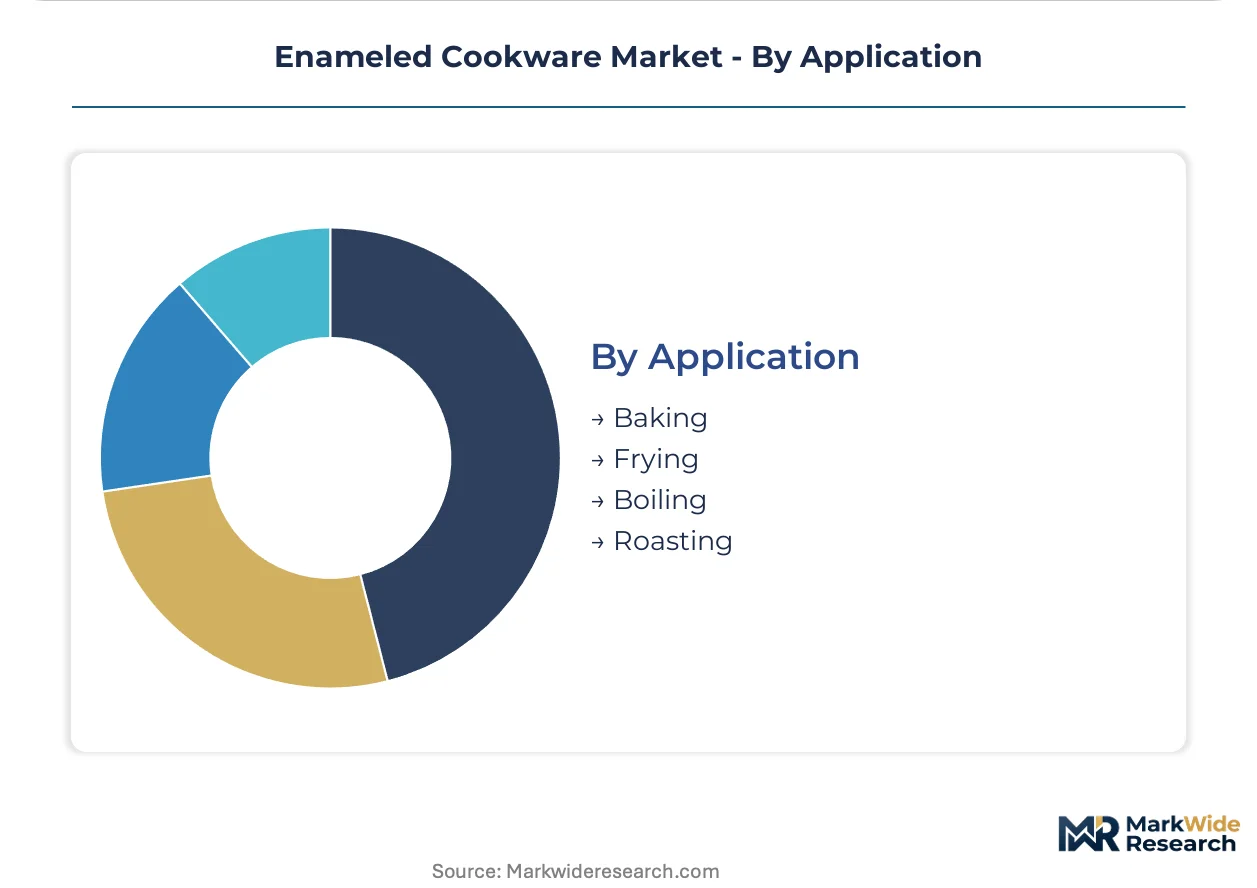
Specific cooking applications drive demand for particular forms and material properties within the enameled cookware sector.
- Roasting:Enameled cast iron Dutch ovens and roasting pans excel in this application, providing consistent, even heat for perfect browning and moisture retention. This segment is particularly strong in Western markets during holiday seasons.
- Baking:Enameled bakeware ensures uniform heat distribution and easy release, making it suitable for a variety of baked goods and casseroles. The rise of home baking culture supports this application globally.
- Frying:Enameled skillets offer a non-stick-like surface for frying eggs, meats, and vegetables, providing easy cleanup.
- Boiling:Stock pots and Dutch ovens are frequently used for boiling water, pasta, or blanching vegetables.
The versatility for Frying applications remains a primary purchase driver, while Roasting represents a specialized requirement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Los Angeles metropolitan area, a significant hub for culinary innovation, drives demand for enameled cookware, reflecting broader market trends. Consumers in affluent urban centers globally prioritize durable and aesthetically pleasing kitchenware for home cooking applications. Regulatory bodies increasingly influence material choices, ensuring product safety and consumer trust.
United States
Demand for enameled cookware in the United States stems from a robust home cooking culture and a desire for visually appealing kitchen aesthetics. The U.S. Food and Drug Administration (FDA) enforces strict regulations on food contact materials, including heavy metal limits in glazes. Major culinary centers like New York City continue to foster trends for premium and specialized enameled pieces.
Germany
German consumers prioritize long-lasting kitchen investments and superior heat retention, supporting the enameled cast iron segment. Europe's REACH framework governs chemical substances, influencing material sourcing and manufacturing processes for cookware. The Stuttgart region, known for precision engineering, focuses on high-quality, durable enameled product development.
France
French demand for enameled cookware is sustained by a preference for premium brand positioning and extensive color options. The European Food Safety Authority (EFSA) provides scientific advice on food safety, guiding manufacturers on safe material composition. The Burgundy region maintains a strong tradition in artisanal cookware production, emphasizing heritage and craftsmanship.
Japan
Japanese households seek high-quality kitchenware and culinary precision, fostering a market for well-crafted enameled products. The Ministry of Health, Labour and Welfare (MHLW) sets stringent food safety standards for imported and domestically produced goods. Osaka, a major commercial center, exhibits a strong focus on design-led kitchen tools and appliances.
China
China's market for enameled cookware expands with rising disposable incomes and a growing adoption of Western culinary practices. National GB standards dictate material safety and performance for food contact articles, ensuring product compliance. The Yangtze River Delta region represents a significant manufacturing base and a large consumer market for diverse cookware options.
Enameled Cookware Market Key Industry Players
Premium-margin players sit above commodity-margin players across brand reputation and material innovation within the enameled cookware market. The market exhibits a tiered structure, with established brands commanding higher price points through perceived quality and design. Strategic archetypes include heritage brands, value-oriented manufacturers, and design-focused specialists. Companies primarily engage in portfolio diversification and geographic expansion to solidify their market presence.
On the premium-tier vector, Le Creuset France SAS exemplifies a brand leveraging extensive color options and strong market positioning. Lodge Manufacturing Company anchors the value-conscious segment with its focus on durable, American-made cast iron products. Staub, part of the ZWILLING group, represents a design-centric approach, differentiating through specific performance-enhancing features like self-basting lids.
| Leading Market Players |
|---|
| Le Creuset France SAS |
| Lodge Manufacturing Company |
| Staub |
| Tramontina |
| Cuisinart |
| ZWILLING |
| Emile Henry |
| Camp Chef |
| Williams-Sonoma, Inc. |
| Others |
Cost & Logistics Intelligence
Premium brand positioning and commodity-level functionality divergence dictates pricing strategies and supply chain configurations within the enameled cookware market. This split reflects varying consumer willingness to pay for aesthetics and perceived durability versus basic utility.
Pricing Analysis
Product performance and brand heritage anchor pricing in the enameled cookware market, reflecting consumer value for long-term kitchen investments. Per-unit transactional pricing dominates, with premium brands like Le Creuset leveraging brand equity and aesthetic options for higher price points. Quality grade and extensive color options serve as key differentiation drivers. Pricing softness stems from lower-cost alternatives, particularly in the carbon steel segment, while health-conscious households show lower price sensitivity for inert surfaces compared to highly sensitive budget consumers.
Supply Chain Analysis
Pig iron and steel supply for enameled cookware production primarily draws from China, India, and Germany. Vitreous enamel glazes rely on specialized chemical producers concentrated in Europe and the United States. Energy costs for furnace firing represent a significant operational expense. Commodity price volatility for pig iron poses a structural supply chain risk. Distribution runs through a mix of specialty kitchenware retailers, department stores, and increasingly, direct-to-consumer e-commerce platforms globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enameled cookware market is a cost-of-compliance story, where adherence to stringent regulations like Europe's REACH framework creates a barrier-to-entry moat for established, compliant players. This regulatory environment favors manufacturers with robust quality control and transparent sourcing capabilities.
For Market Incumbents:Deepen vertical integration into raw material sourcing, particularly for pig iron and specialized enamel frit, to mitigate commodity price volatility. Invest in advanced glazing technologies to enhance chip resistance, addressing a key usability barrier and differentiating from lower-cost alternatives. Expand direct-to-consumer channels to control the customer experience and gather valuable purchasing data, countering traditional retail pressures.
For New Entrants and Emerging Players:Enter via niche product development, targeting specialized applications like bread baking or ethnic cuisines to capture high-value segments. Focus on affluent urban centers in Asia-Pacific, where Western culinary trends are gaining traction and aesthetic appeal holds sway. Leverage digital marketing and influencer partnerships to build brand awareness quickly, bypassing traditional retail gatekeepers.
For Investors and Strategic Acquirers:Exit pathways concentrate in established premium brands with strong intellectual property in glaze technology or a dominant direct-to-consumer presence. Long-term viability hinges on brands capable of balancing aesthetic innovation with continuous regulatory compliance over a five-to-ten-year window. A signal to watch is sustained investment in sustainable manufacturing processes and energy efficiency, indicating operational resilience.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Glaze R&D | Developing chip-resistant and aesthetically diverse enamel surfaces enhances product longevity and market appeal. |
| Direct-to-Consumer Channel Expansion | Building proprietary e-commerce platforms improves margin control and provides direct consumer insights for product innovation. |
| Sustainable Manufacturing Investment | Reducing energy consumption in firing processes addresses rising operational costs and appeals to environmentally conscious consumers. |
| Asia-Pacific Market Penetration | Targeting affluent urban consumers in rapidly growing economies expands the addressable market for premium enameled cookware. |
| Specialized Product Line Development | Creating niche items for specific cooking techniques captures high-value segments and diversifies product portfolios beyond Dutch ovens. |
Research Approach
Independent corroboration across manufacturer financial reports, regulatory body publications, and trade association data underwrites the qualitative findings. Primary interviews with product development executives, sourcing managers, retail buyers, and culinary trend analysts provided critical market insights. Secondary validation involved cross-referencing data from the U.S. FDA, Europe's ECHA, and Japan's MHLW. This approach enabled comprehensive bottom-up and top-down triangulation of market dynamics.
Historical market performance across a five-year comparable period anchored the forecast framework, projecting future trends over the projection horizon. Segmentation dimensions modeled included product type, material, end-user, application, and regional adoption patterns. Compound annual growth rates were derived through a statistical analysis of historical data and forward-looking economic indicators. Key forecast inputs included raw material price trends and consumer spending on home goods.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant shifts in global trade policy or energy prices. Forecasts reflect assumptions documented regarding regulatory stability and consumer preferences. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Command Hooks Market
Household Items
Barbecue Grill Market
Household Items
South Africa Cookware Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Heated Towel Rail Market
Household Items
Robotic Vacuum Cleaner Market
Household Items
Facial Tissue Market
Household Items
Disposable Cutlery Market
Household Items
Moving Supplies Market
Household Items
Portable Humidifiers Market
Household Items
Electric Shoe Dryer Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Smart Air Purifier Market
Household Items
Cast Iron Cookware Market
Household Items
Automatic Dishwashing Products Market
Household Items
Insulated Tumblers Market