
 Moving Supplies Market | 2026-2036
Moving Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Moving Supplies Market Foresight
Premium-grade corrugated specifications are redrawing competitive boundaries in moving supplies. U-Haul leverages its captive rental network to dominate self-service moving channels. WestRock sustains manufacturing scale through integrated paper mills and box plants across North America. Mondi Group specializes in performance-engineered packaging grades that navigate stringent EU circular-economy requirements.
Moving supplies encompass protective and containment materials engineered from kraft paper, polyethylene films, and expanded polystyrene with burst strengths typically exceeding 200 lb per square inch, designed to shield household and commercial goods from mechanical shock, moisture, and compression during transit. Boxes and packing tape constitute the mature volume core where margin compression is acute, while biodegradable packaging types capture premium pricing from environmentally constrained corporate relocations. Bubble wrap and custom-sized solutions concentrate margin pools in high-value electronics and fine-art logistics segments.
The EPA regulates recycled content thresholds under Comprehensive Procurement Guidelines, while OSHA mandates ergonomic handling standards for heavy-lift packaging that shape box weight specifications and material selection. California's SB 54 and New York's extended producer responsibility frameworks are forcing reformulation of plastic-based cushioning toward fiber alternatives. Stakeholders must monitor how state-level packaging EPR legislation proliferates and whether fiber-based substitutes achieve cost parity with conventional polyethylene cushioning before committing capital to line conversions.
Market Dynamics
State-level extended producer responsibility mandates are compressing plastic cushioning demand while e-commerce fulfillment centers accelerate fiber-based protective packaging procurement across Sun Belt metropolitan corridors.
Growth Catalysts
- California SB 54:The state's plastic pollution reduction law mandates 30% recycled content thresholds by 2028, redirecting corporate relocation budgets toward biodegradable corrugated alternatives and molded fiber cushioning systems.
- E-commerce fulfillment densification:Amazon, Wayfair, and Overstock distribution nodes in Phoenix, Dallas, and Atlanta are standardizing burst-strength specifications above 275 lb per square inch for double-wall corrugated, creating pull-through demand for premium-grade boxboard.
- Sun Belt residential migration:Net inflows exceeding 500,000 annually into Texas, Florida, and Arizona metropolitan areas are sustaining peak-season box demand that outstrips historical Northeast and Midwest seasonal patterns.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs swing 40% within fiscal quarters, compressing converter margins when boxboard contracts reset on six-month lags against spot pulp markets.
- Mid-Atlantic mill concentration:Integrated producers cluster within 300 miles of Richmond and Philadelphia, exposing regional supply to single-point hurricane and winter storm disruptions along I-95 logistics corridors.
- Expanded polystyrene substitution limits:Molded pulp achieves only 60-70% cushioning equivalence for electronics shock absorption below 50G impact thresholds, locking high-value semiconductor logistics into legacy foam despite EPR penalties.
Strategic Opportunities
- New York extended producer responsibility:The state's 2024 packaging EPR framework creates first-mover advantage for fiber-based cushioning suppliers who achieve cost parity with polyethylene bubble wrap before 2027 compliance deadlines.
- Fine-art logistics specialization:Museums and auction houses in Los Angeles, Chicago, and Miami are commissioning custom crating with climate-buffered interiors, opening margin pools 3-4x standard residential moving supplies.
- Rental network captive demand:U-Haul, Penske, and Budget Truck maintain 22,000+ dealer locations where exclusive box and tape contracts lock out independent distributors from self-service moving channels.
Industry Challenges
- Ergonomic compliance complexity:OSHA's 2023 updated lifting guidelines for packages above 50 pounds force repackaging of book and dish barrel specifications, requiring SKU proliferation that fragments production runs.
- Recycled content certification lag:FTC Green Guides enforcement and California Truth in Labeling audits create 90-120 day documentation delays for post-consumer fiber claims, freezing marketing timelines ahead of peak summer moving season.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Moving Supplies Market |
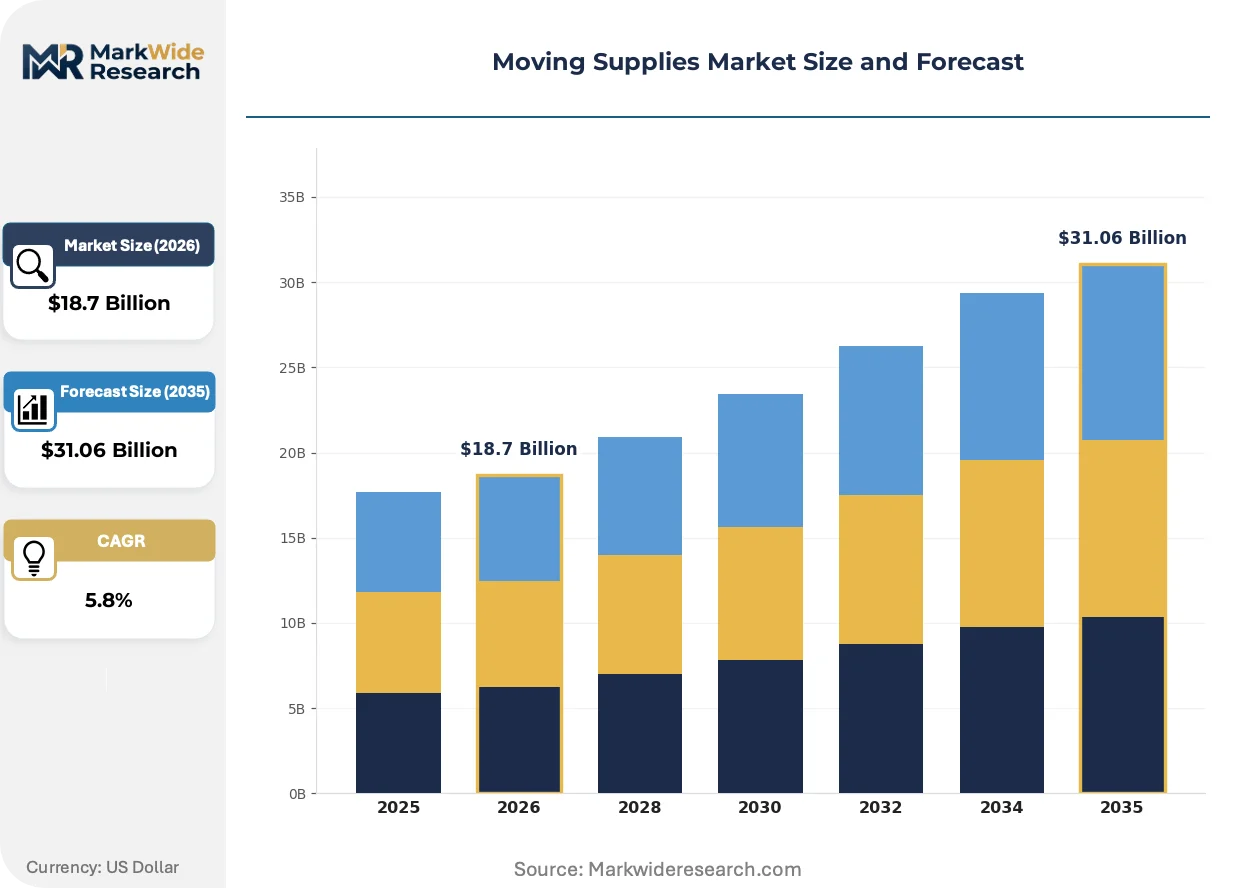
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Packing Tape, Bubble Wrap, Mattress Covers End User: Households, Businesses, Contractors, Logistics Providers Packaging Type: Single-Walled, Double-Walled, Biodegradable, Custom-Sized Distribution Channel: Retail Stores, Online Platforms, Wholesale, Direct Sales |
| Companies Covered | U-Haul, The Home Depot, Lowe’s, Uline, WestRock, International Paper, Smurfit Kappa, Mondi Group, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Moving Supplies Market Shifts & Advancements
Material science breakthroughs and regulatory compression are converging to displace conventional polyethylene cushioning with performance-engineered fiber alternatives across high-value logistics segments.
Corrugated micro-flute technology is miniaturizing protective profiles without sacrificing burst strength. E-commerce shippers of consumer electronics and glassware are adopting F- and N-flute constructions at accelerating rates. The structural consequence is compression of void-fill volume requirements by 15-20% per shipment, reducing dimensional weight charges and fiber input costs simultaneously.
EPA Comprehensive Procurement Guidelines are tightening recycled content verification protocols for federal procurement contracts. Manufacturers must now document chain-of-custody from municipal recovery facility through paper mill to finished box plant. Federal relocation services and military household goods programs represent the most affected buyer segments, with compliance costs driving consolidation toward integrated producers with captive OCC supply.
Corporate relocation procurement departments are unbundling moving supply contracts from van line services, creating direct purchasing relationships with specialized packaging distributors. This disintermediation is most visible in technology sector relocations centered on Austin, Seattle, and Raleigh-Durham, where HR and procurement teams negotiate box and cushioning specifications independent of transportation providers, compressing distributor margins while expanding SKU customization requirements.
Moving Supplies Market Segmentation
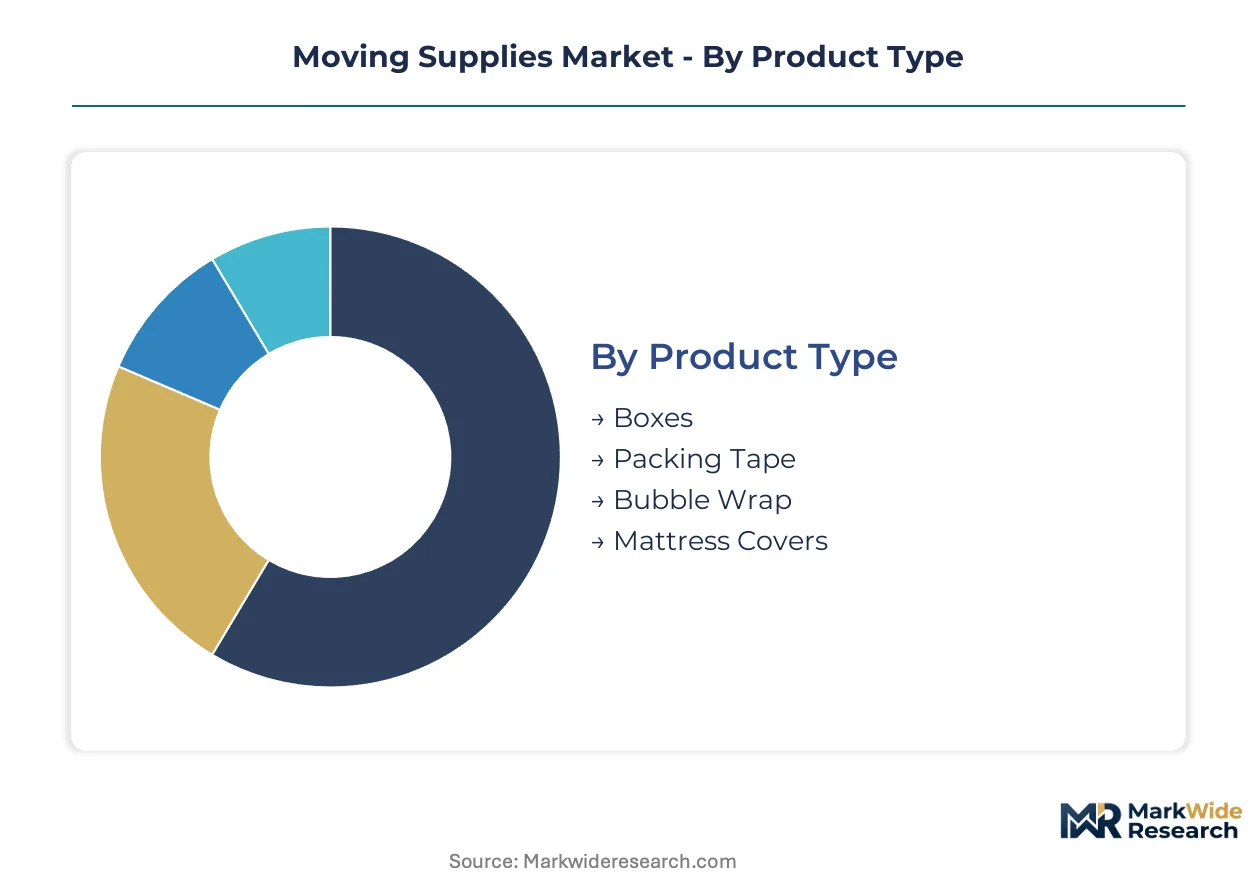
Moving supplies segmentation reveals how regulatory pressure and logistics specialization fragment procurement patterns across customer tiers. Product specifications diverge sharply between residential self-service channels and commercial relocation contracts governed by EPR mandates.
Product Type:
EPA recycled content thresholds and OSHA ergonomic standards differentiate material specifications across product categories, with fiber-based alternatives gaining procurement share in regulated corporate channels.
- Boxes:Corrugated containers engineered from kraft paper with burst strengths ranging 200-350 lb per square inch constitute the volume core. Demand concentrates in Sun Belt metropolitan corridors where annual residential inflows exceed 500,000 households, though margin compression is acute due to OCC price volatility and converter overcapacity.
- Packing Tape:Pressure-sensitive adhesives formulated from synthetic rubber or hot-melt resins secure box closures under transit stress. Procurement is shifting toward water-activated gummed tape in California and New York fulfillment centers to meet plastic-reduction mandates without sacrificing seal integrity.
- Bubble Wrap:Polyethylene film cushioning with encapsulated air pockets protects fragile goods from mechanical shock.
- Mattress Covers:Polyethylene or woven polypropylene sheaths shield bedding from moisture and soiling during transport.
Established volume favors Boxes; emerging adoption favors Packing Tape reformulations.
End User:
Customer procurement sophistication spans from price-sensitive residential self-service to specification-driven corporate relocation contracts with embedded compliance documentation.
- Households:Individual consumers purchasing through retail or rental network channels prioritize unit cost over performance specifications. Sun Belt migration patterns sustain demand for standard corrugated and cushioning bundles through U-Haul and home improvement retail locations.
- Businesses:Corporate relocation departments negotiate direct contracts with specialized packaging distributors, unbundling supply procurement from van line services in technology sector corridors including Austin and Raleigh-Durham.
- Contractors:Professional moving services purchase bulk quantities through wholesale channels with seasonal demand smoothing.
- Logistics Providers:Third-party fulfillment operators standardize burst-strength specifications above 275 lb per square inch for e-commerce distribution nodes.
Procurement sophistication climbs fastest among Businesses; volume concentration remains with Households.
Packaging Type:
Structural engineering and material composition determine performance thresholds for shock absorption, compression resistance, and regulatory compliance across logistics applications.
- Single-Walled:Standard C-flute corrugated construction provides baseline protection for lightweight household goods. Cost efficiency sustains dominance in residential moving channels where shipment weights remain below 50 pounds.
- Double-Walled:BC-flute combinations deliver burst strengths exceeding 275 lb per square inch for heavy or high-value cargo. Amazon and Wayfair distribution centers in Phoenix and Dallas mandate these specifications for electronics and glassware fulfillment.
- Biodegradable:Molded fiber and recycled-content corrugated alternatives navigate California SB 54 and New York EPR frameworks.
- Custom-Sized:Engineered-to-order crating with climate-buffered interiors serves fine-art logistics in Los Angeles, Chicago, and Miami.
Functional performance anchors Double-Walled procurement; regulatory compliance accelerates Biodegradable conversion.
Distribution Channel:
Channel selection determines pricing transparency, SKU breadth, and delivery velocity for distinct customer urgency profiles.
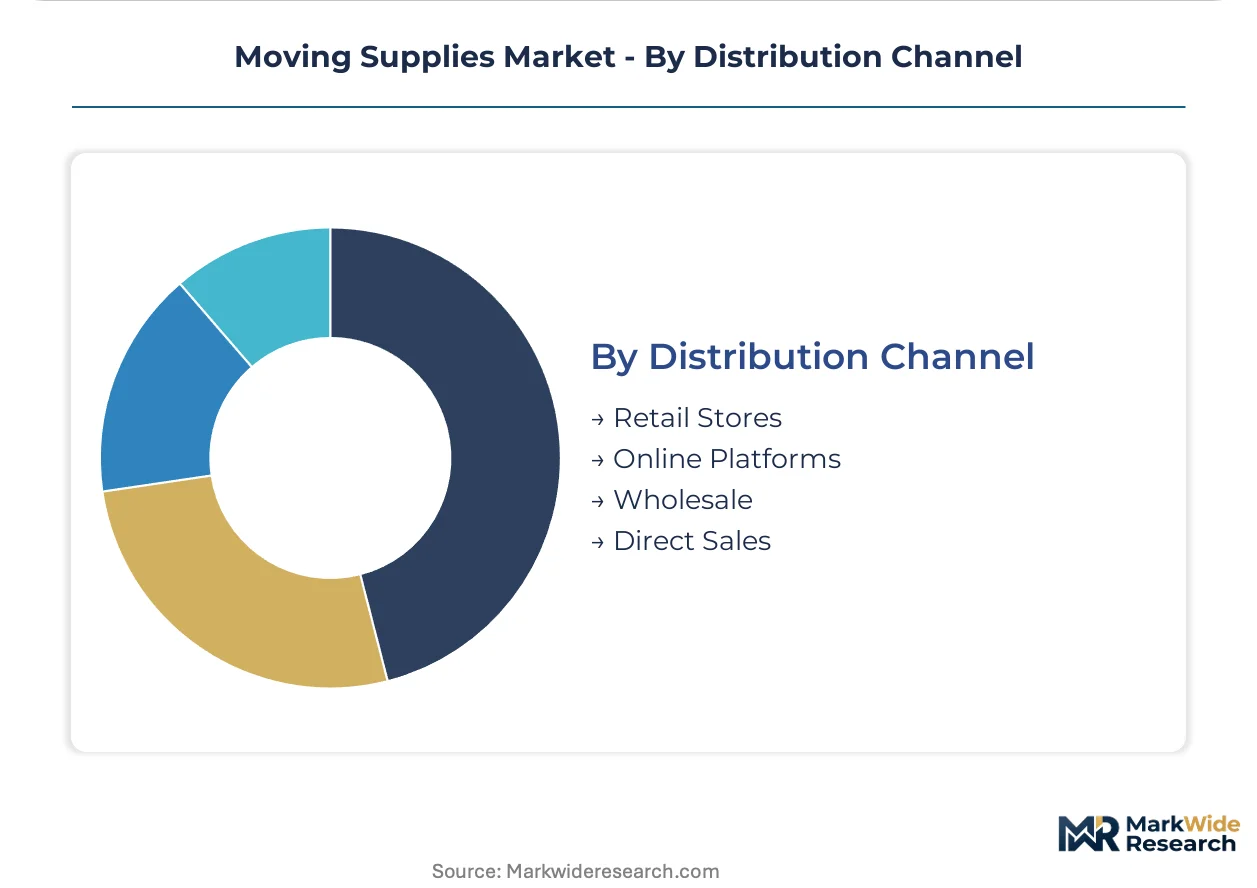
- Retail Stores:Big-box home improvement and dedicated moving supply outlets provide immediate availability for unplanned residential moves. Geographic concentration in Sun Belt growth metros captures migration-driven demand spikes.
- Online Platforms:E-commerce direct-to-consumer sales enable specification comparison and bulk pricing for planned relocations. Corporate procurement teams in technology sector corridors leverage platform transparency for contract benchmarking.
- Wholesale:Volume distributors serve contractor and logistics provider accounts with palletized fulfillment.
- Direct Sales:Manufacturer-direct relationships lock in exclusive supply contracts with rental network operators.
Transactional convenience sustains Retail Stores; procurement efficiency gains favor Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Households in Sun Belt corridors absorb price increases with minimal volume elasticity, while corporate procurement teams in Northeast technology hubs negotiate specification-for-specification substitutions when fiber premiums exceed polyethylene baselines.
United States
Sun Belt metropolitan areas including Phoenix, Dallas, and Atlanta sustain peak-season demand that outstrips historical Northeast seasonal patterns, with net inflows exceeding 500,000 households annually into Texas, Florida, and Arizona. EPA Comprehensive Procurement Guidelines tighten recycled content verification protocols for federal contracts. Amazon and Wayfair distribution nodes in Phoenix standardize double-wall corrugated specifications above 275 lb per square inch.
Canada
Cross-border e-commerce fulfillment from Vancouver and Toronto accelerates procurement of protective packaging aligned with US burst-strength specifications. Health Canada maintains packaging material safety standards that parallel FDA guidelines for food-contact corrugated applications. Greater Toronto Area distribution clusters serve as overflow capacity for Midwest US demand spikes.
Germany
Industrial machinery export corridors through Hamburg and Duisburg generate specialized crating demand for precision equipment logistics. ECHA REACH regulations restrict certain adhesive formulations in pressure-sensitive tapes, redirecting procurement toward water-activated gummed alternatives. Bavaria-based automotive suppliers commission custom-engineered cushioning for prototype vehicle component shipments.
China
Yangtze River Delta manufacturing clusters supply molded fiber cushioning components to North American distributors seeking California SB 54 compliance pathways. MEE enforcement of dual carbon goals pressures export-oriented packaging converters toward energy-intensive recycled fiber processing. Shenzhen electronics fulfillment centers prototype micro-flute corrugated constructions for consumer device protection.
India
Bangalore and Hyderabad technology sector relocations drive direct procurement relationships unbundled from van line services. BIS certification requirements for corrugated burst strength create compliance friction for imported packaging materials. Maharashtra-based paper mills expand kraft linerboard capacity to serve domestic e-commerce fulfillment growth.
Moving Supplies Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated paper mills commanding scale efficiencies while specialized converters capture specification premiums in regulated corporate channels. The vendor base organizes around three strategic archetypes: rental network operators with captive dealer locations, integrated producers with backward control over OCC supply chains, and performance-engineered specialists navigating EU circular-economy requirements. Dominant competitive moves include exclusive supply contracts locking independent distributors out of self-service channels, and SKU proliferation addressing OSHA ergonomic compliance for heavy-lift packaging.
Among North American integrated producers, WestRock and International Paper exemplify scale-driven archetypes with manufacturing footprints spanning paper mill and box plant operations. U-Haul occupies a distinct position as a rental network operator leveraging captive demand across 22,000+ dealer locations. Mondi Group represents the performance-engineered specialist tier, with technical capabilities aligned to stringent European regulatory frameworks.
| Leading Market Players |
|---|
| U-Haul |
| The Home Depot |
| Lowe's |
| Uline |
| WestRock |
| International Paper |
| Smurfit Kappa |
| Mondi Group |
| Packaging Corporation of America |
| Others |
Supply & Pricing Matrix
Six-month boxboard contracts with six-month lags against spot pulp markets lock in supply access for converters while exposing margins to OCC price swings. This structure concentrates pricing power with integrated producers controlling captive recycled fiber supply across the Mid-Atlantic corridor.
Pricing Analysis
California SB 54 dictates the pricing tier structure across the moving supplies market. Three-tier pricing separates biodegradable corrugated alternatives from standard double-wall specifications and economy single-walled construction. Price differentiation rests on burst-strength certification tiers and post-consumer fiber content verification. Cost compression in standard box grades is intensifying because converter overcapacity outpaces Sun Belt demand growth. Households purchasing through rental networks exhibit highest price sensitivity, while corporate relocation procurement teams negotiate specification premiums with minimal elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate e-commerce fulfillment channels, while strategic stockpiling persists among rental network operators ahead of peak summer moving season. Geographic supply concentrates in the United States, Canada, and China. Raw material dependencies draw from old corrugated container feedstock, kraft linerboard, and polyethylene resin. Single-point vulnerability runs through Mid-Atlantic mill clusters within 300 miles of Richmond and Philadelphia. Distribution runs through captive rental network locations, wholesale palletized fulfillment, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Moving supplies represent a service-attach opportunity where packaging specification consulting and compliance documentation services expand faster than commodity box sales. Recurring revenue from corporate procurement advisory contracts outpaces transactional hardware growth.
For Market Incumbents: Secure exclusive supply contracts with rental network operators before independent distributors penetrate self-service channels. Capture backward integration into OCC collection and municipal recovery facility partnerships to insulate margins from feedstock volatility. Invest in micro-flute R&D capabilities to defend specification premiums against fiber-based substitute entrants. For New Entrants and Emerging Players: Lead with biodegradable cushioning formulations targeting New York EPR compliance deadlines ahead of incumbent line conversions. White-space exists in fine-art logistics specialization serving Los Angeles and Miami museum corridors. Pursue direct sales relationships with technology sector HR procurement teams unbundled from van line services. For Investors and Strategic Acquirers: Performance-engineered packaging specialists with EU circular-economy certification capabilities anchor long-term viability across the analysis window. Monitor fiber-based substitute cost parity thresholds as the inflection indicator for polyethylene displacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Supply | Captive fiber access insulates margins from quarterly price swings at Richmond mills. |
| Micro-Flute R&D Investment | F- and N-flute constructions reduce dimensional weight charges for Amazon fulfillment nodes. |
| Biodegradable Line Conversion | California SB 54 compliance unlocks corporate relocation budgets previously allocated to plastic cushioning. |
| Rental Network Exclusive Contracting | U-Haul's 22,000 dealer locations lock out independent distributors from self-service moving channels. |
| Fine-Art Logistics Specialization | Climate-buffered custom crating commands margin pools 3-4x standard residential specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with industry stakeholders and secondary validation across regulatory and trade databases. Primary fieldwork engaged corrugated converter operations managers, corporate relocation procurement directors, rental network supply chain leads, and EPA compliance officers. Secondary sources encompassed EPA Comprehensive Procurement Guidelines filings, state-level EPR legislative tracking, OCC price index data, and SEC 10-K disclosures from integrated paper producers. Bottom-up volume modeling triangulated against top-down market sizing across product and end-use segments.
Across the analysis window, forecasts deployed a segmented growth framework modeling product type, packaging construction, end-user sophistication tier, and regional migration corridor dimensions. CAGRs derived from historical elasticity patterns applied to projected regulatory compliance deadlines and e-commerce fulfillment densification curves. Forecast inputs incorporated Sun Belt residential inflow projections and double-wall corrugated specification adoption rates at Amazon and Wayfair distribution nodes.
Forecasts assume regulatory continuity in California SB 54 and New York EPR frameworks; material policy shifts would require re-modeling recycled content thresholds and fiber substitute penetration curves. Revision becomes warranted when molded pulp cushioning achieves cost parity with polyethylene bubble wrap in high-value electronics logistics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Electric Blankets Market
Household Items
Smart Drying Racks Market
Household Items
Multi-Door Fridges Market
Household Items
Cast Iron Cookware Market
Household Items
Smart Faucets Market
Household Items
Germany Digital Showers Market
Household Items
Party Supplies Market
Household Items
Electric Soap Dispenser Market
Household Items
Shower Heads and Systems Market
Household Items
Robotic Pool Cleaner Market
Household Items
Non-Stick Cookware Market
Household Items
Cutlery Steel Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
China Cookware Market
Household Items
Insulated Water Bottles Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market