
 Collapsible Water Bottle Market | 2026-2036
Collapsible Water Bottle Market Size, Share, and Industry Trends Forecast 2026-2036
Collapsible Water Bottle Market Outlook
Direct-to-consumer channels is narrowing as specialty outdoor retailers and sporting goods shops consolidate shelf space for premium hydration brands. CamelBak leverages its trail-running and cycling heritage to dominate performance-oriented distribution. Hydro Flask sustains brand loyalty through color customization and insulated variants that compete at higher price points. Que specializes in ultralight silicone construction for backpackers who prioritize packability over thermal retention.
A collapsible water bottle compresses through accordion folds, roll-up sleeves, or twist-flat mechanisms, typically employing food-grade silicone, thermoplastic polyurethane, or polyethylene vinyl acetate with capacities ranging from twelve to thirty-two ounces and leak-proof valve closures. The product serves travelers, athletes, and commuters requiring portable hydration without rigid container bulk. Silicone and TPU formulations lead product type demand due to dishwasher safety and repeated collapse durability, while nylon and LDPE alternatives occupy budget-oriented segments with thinner wall construction. Corporate giveaways and travel accessories represent the fastest-growing application channels as employers and airlines seek branded, practical items with minimal storage footprint.
FDA food-contact regulations govern silicone and TPU material safety in the United States, while the EU's REACH framework and Single-Use Plastics Directive restrict certain additives and mandate recyclability disclosures for reusable alternatives. These standards elevate compliance costs for new entrants but protect established manufacturers with certified supply chains. Stakeholders must monitor evolving state-level extended producer responsibility laws and material-specific restrictions that could reshape acceptable polymer portfolios.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing demand toward reusable formats while silicone and TPU supply chains consolidate among certified processors, creating tiered access to compliant material streams.
Growth Catalysts
- REACH Framework Compliance:European chemical safety standards favor food-grade silicone and TPU over disposable plastics, accelerating certified material procurement by German cycling gear distributors and alpine outfitters.
- Corporate Travel Programs:Airlines and hospitality employers are sourcing branded collapsible bottles as employee and passenger amenities, prioritizing packable storage footprints over rigid alternatives.
- Outdoor Recreation Procurement:University outdoor programs and national park concessionaires in the United States are expanding bulk purchasing of packable hydration gear for student and visitor use.
Market Restraints
- Silicone Raw Material Volatility:Precipitated silica and methyl chloride feedstock costs fluctuate with energy pricing, compressing margins for TPU and silicone processors without long-term supply contracts.
- Concentrated Certification Bodies:FDA food-contact and EU REACH testing capacity clusters among three major laboratories, creating bottlenecks for new entrants seeking material safety validation.
- Performance Trade-offs:Ultralight nylon and LDPE alternatives sacrifice collapse-cycle durability, limiting replacement intervals and lifetime value against rigid insulated competitors.
Strategic Opportunities
- Extended Producer Responsibility Laws:State-level EPR legislation in California and Oregon mandates recyclability disclosures and material recovery programs, creating first-mover advantages for brands with closed-loop silicone collection infrastructure.
- Smart Hydration Convergence:Integration of hydration-tracking sensors and Bluetooth connectivity with collapsible formats targets marathon runners and trekking operators seeking consumption analytics without rigid electronics housing.
- Direct-to-Institution Channels:Bypassing specialty retail through corporate wellness platforms and university procurement portals reduces shelf-space dependency and captures recurring bulk orders.
Industry Challenges
- Food-Contact Chemist Shortage:Qualified toxicologists capable of navigating FDA indirect additive regulations and EU migration testing protocols command premium salaries, delaying product launch timelines.
- Multi-Jurisdiction Certification Overlap:Simultaneous compliance with FDA, REACH, and emerging state-level EPR requirements extends validation cycles and fragments testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collapsible Water Bottle Market |
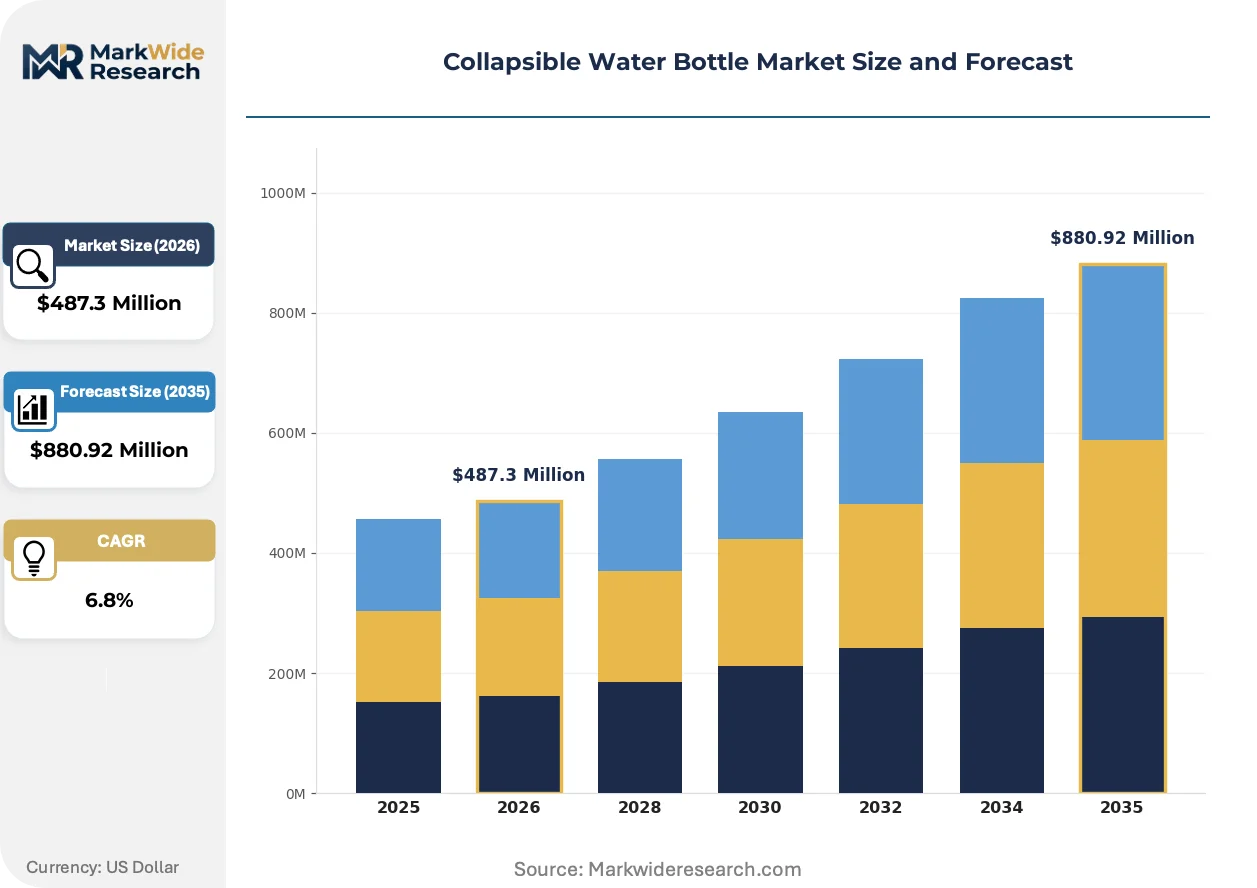
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, TPU, PEVA, Nylon, LDPE, Others Application: Outdoor Recreation, Fitness Centers, Corporate Giveaways, Travel Accessories, School Supplies End User: Adventure Enthusiasts, Gym Members, Corporate Clients, Frequent Flyers, Students Distribution Channel: Online Retailers, Specialty Stores, Sporting Goods Shops, Corporate Sales, Travel Retail |
| Companies Covered | CamelBak, YETI, Que, Owala, Stanley, Hydro Flask, Nalgene, Iron Flask, Klean Kanteen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collapsible Water Bottle Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape product architecture and channel strategy across collapsible hydration, with durability testing and connected features emerging as differentiation axes.
Platinum-cured liquid silicone rubber is migrating from medical device applications into consumer hydration, delivering higher purity and tear strength than peroxide-cured alternatives. Backpacking outfitters and trail-running specialists are adopting these formulations for 10,000+ collapse-cycle guarantees. The technology is migrating from premium medical supply chains into mid-market outdoor retail, compressing the historical price gap between hospital-grade and consumer silicone.
REACH Annex XVII restrictions on phthalates and heavy metal additives are tightening acceptable polymer portfolios for reusable food-contact items. Manufacturers must reformulate colorants and plasticizers or face market withdrawal from EU distribution channels. German and Dutch sporting goods importers are demanding full material disclosure documentation, shifting supplier qualification criteria upstream.
Buyers are consolidating vendor relationships around certified supply chains rather than sourcing on unit economics alone. Specialty outdoor retailers are reducing SKU counts and prioritizing brands with documented FDA and REACH compliance, displacing unverified direct-to-consumer imports. This concentration is most visible in Germany's cycling tourism corridor, where alpine sports retailers now require batch-level testing certificates for all silicone hydration products.
Collapsible Water Bottle Market Segmentation
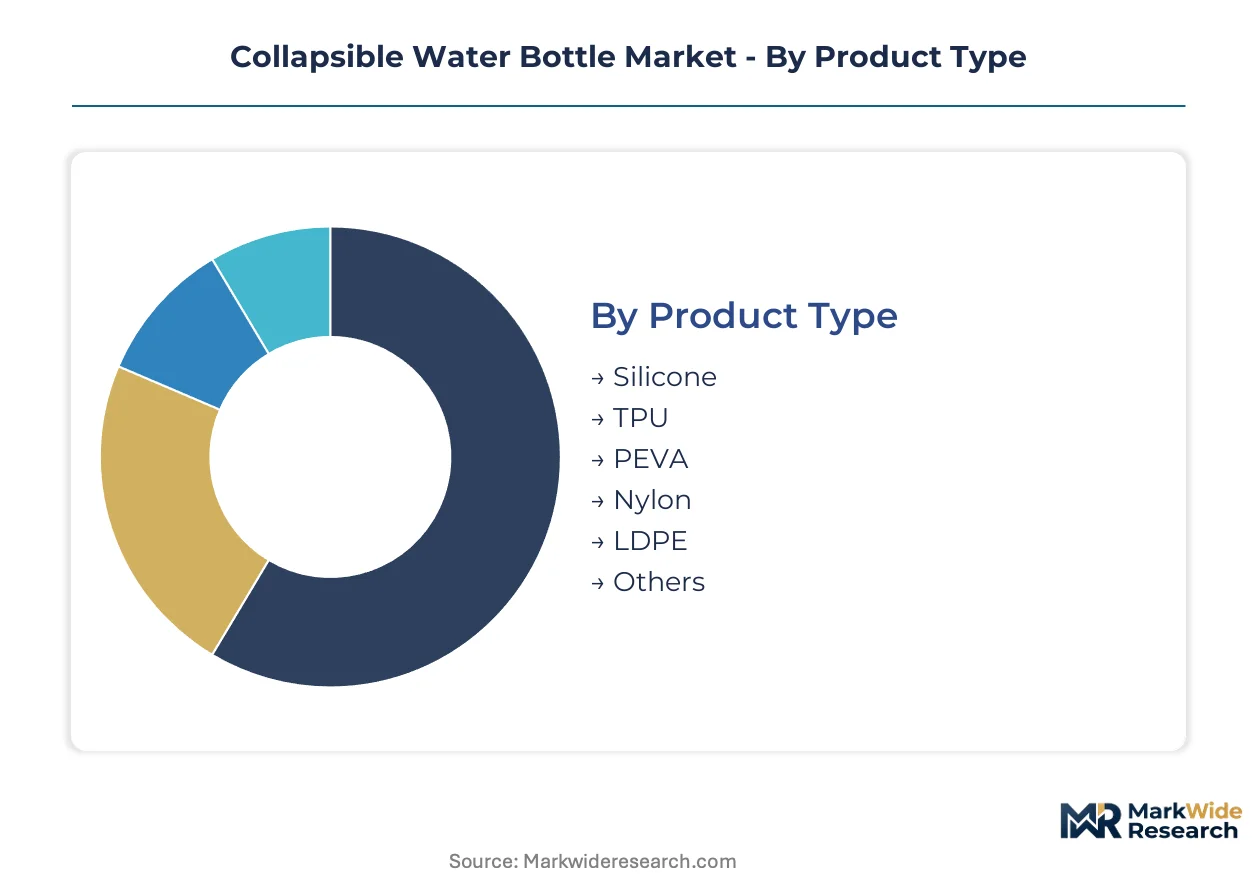
Collapsible water bottle manufacturers segment demand across material chemistry, use case intensity, buyer procurement behavior, and channel access requirements. Each dimension carries distinct margin profiles and replacement-cycle economics that shape portfolio prioritization.
Product Type:
Silicone and TPU formulations command the longest replacement cycles due to collapse durability, while nylon and LDPE alternatives turn over faster as thin-wall construction degrades under repeated stress.
- Silicone:Platinum-cured liquid silicone rubber delivers 10,000-plus collapse cycles with dishwasher-safe thermal stability. German cycling tourism retailers and alpine outfitters concentrate procurement here, driven by REACH Annex XVII compliance requirements that disqualify lower-grade alternatives.
- TPU:Thermoplastic polyurethane balances tear resistance with lighter pack weight than silicone, typically serving trail runners and ultralight backpackers who prioritize gram savings over thermal retention. FDA food-contact certification clusters among three major testing laboratories, creating supply bottlenecks for new entrants.
- PEVA:Polyethylene vinyl acetate occupies budget-oriented segments with moderate flexibility and lower material cost, common in corporate giveaway programs where unit economics dominate durability requirements.
- Nylon:Thin-wall construction sacrifices collapse-cycle longevity for minimal pack weight, limiting replacement intervals and lifetime value against rigid insulated competitors.
- LDPE:Low-density polyethylene serves single-season outdoor programs and disposable-adjacent applications where lowest unit cost outweighs multi-year durability expectations.
- Others:Emerging bio-based and recycled-content formulations from certified processors targeting state-level extended producer responsibility mandates in California and Oregon.
Silicone anchors the volume base while TPU gains share at the steepest rate as REACH compliance tightens acceptable polymer portfolios.
Application:
Cost tier stratification separates premium performance positioning from high-volume commoditized procurement across institutional and consumer channels.
- Outdoor Recreation:University outdoor programs and national park concessionaires in the United States expand bulk purchasing of packable hydration gear for student and visitor use. Replacement cycles align with academic calendar and seasonal staffing turnover.
- Corporate Giveaways:Employers and airlines source branded collapsible bottles as employee and passenger amenities, prioritizing packable storage footprints and logo visibility over thermal performance. This segment expands most quickly as corporate wellness platforms consolidate vendor relationships.
- Fitness Centers:Gym chains procure mid-grade silicone formats for member onboarding kits, balancing unit cost against minimum durability thresholds for daily use.
- Travel Accessories:Duty-free and airport retail channels favor TPU and PEVA constructions that compress to pocket size for security checkpoint convenience.
- School Supplies:K-12 procurement emphasizes BPA-free certifications and bright colorants, with replacement driven by academic year cycles and loss rates.
Outdoor Recreation generates the steadiest institutional volume while Corporate Giveaways climb fastest on airline and hospitality procurement expansion.
End User:
Customer type determines performance premium tolerance and channel access preferences, from technical specification readers to price-sensitive bulk buyers.
- Adventure Enthusiasts:Backpackers and trail runners demand ultralight silicone construction with documented batch-level testing certificates, common in Germany's alpine sports corridor.
- Frequent Flyers:Compression-to-flat formats that pass empty through security checkpoints drive preference for twist-flat mechanisms over accordion folds.
- Corporate Clients:Procurement officers prioritize documented FDA and REACH compliance with customizable branding surfaces and minimal storage footprint for conference swag.
- Gym Members:Price-conscious repeat purchasers favor standard-capacity silicone bottles with leak-proof valve closures for locker storage.
- Students:Loss-tolerant buyers drive demand for lowest-cost PEVA and LDPE alternatives with bright colorants for visual identification.
Adventure Enthusiasts anchor premium pricing power while Corporate Clients drive volume through recurring bulk orders.
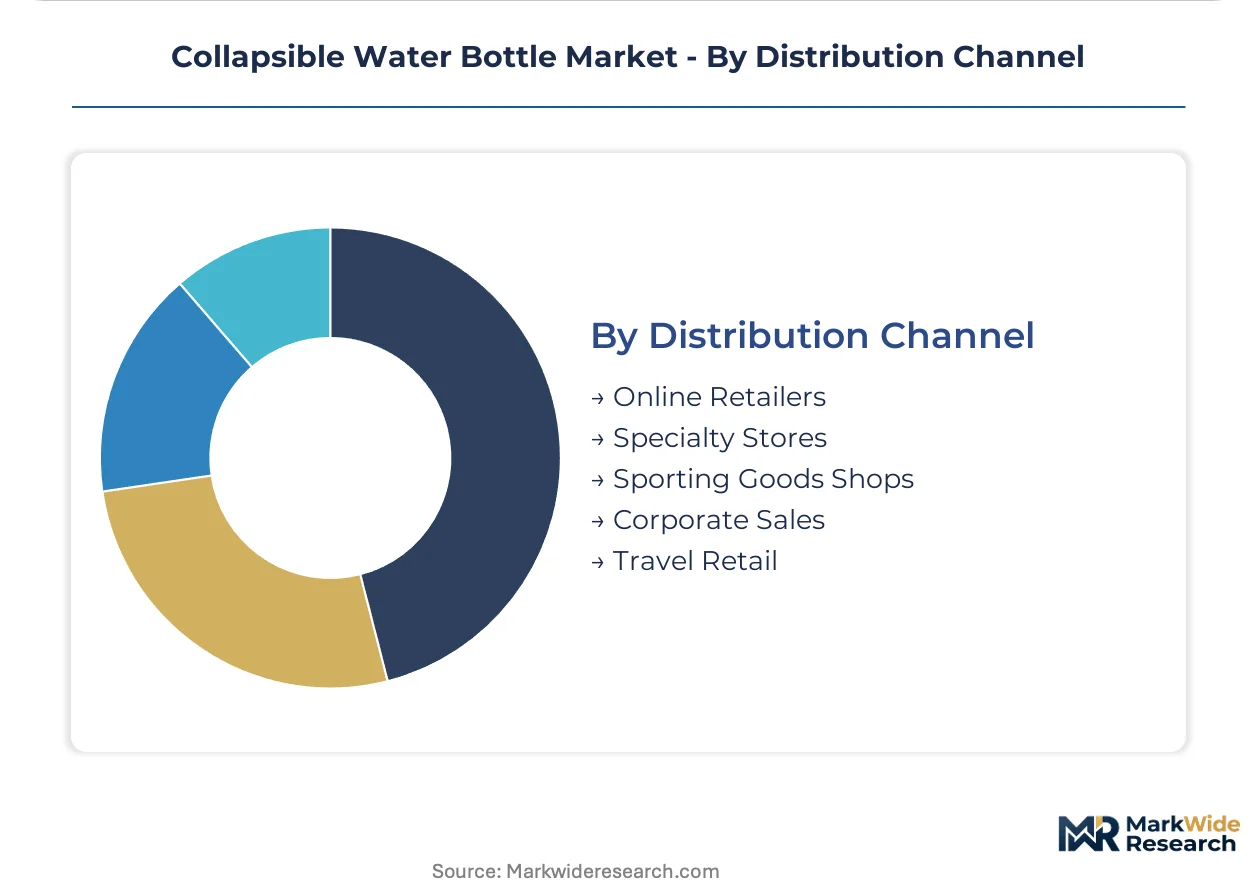
Distribution Channel:
Supply concentration among certified processors favors established brands with documented compliance, displacing unverified direct-to-consumer imports from specialty retail shelf space.
- Specialty Stores:Alpine sports and cycling retailers in Germany reduce SKU counts to prioritize brands with batch-level testing certificates, consolidating around verified silicone supply chains.
- Online Retailers:Direct-to-consumer channels narrow as marketplace algorithms favor established hydration brands with review velocity and return-rate metrics.
- Corporate Sales:Bypassing specialty retail through corporate wellness platforms and university procurement portals reduces shelf-space dependency and captures recurring bulk orders.
- Sporting Goods Shops:Performance-oriented distribution concentrates around trail-running and cycling heritage brands with color customization and insulated variant portfolios.
- Travel Retail:Airport and duty-free channels prioritize packability demonstrations and impulse price points under twenty dollars.
Specialty Stores defend the highest margin tier while Corporate Sales expands fastest through institutional procurement portal consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for silicone and TPU hydration components, channeling certified materials into Germany's cycling tourism corridor while FDA-registered shipments from the Port of Los Angeles supply university procurement networks across the western United States.
United States
National park concessionaires and university outdoor programs drive institutional procurement of packable hydration gear. FDA food-contact regulations govern silicone safety standards, elevating compliance costs for new entrants. The Pacific Northwest corridor concentrates specialty outdoor retail distribution, with Seattle and Portland retailers reducing SKU counts to prioritize verified supply chains.
Germany
Cycling tourism and alpine sports create concentrated adoption of collapsible formats among adventure enthusiasts. REACH Annex XVII restrictions on phthalates tighten acceptable polymer portfolios, favoring platinum-cured liquid silicone rubber. The Bavarian Alps corridor anchors premium specialty retail, with Munich and Innsbruck-area outfitters demanding batch-level testing certificates.
China
Manufacturing clusters in Guangdong and Zhejiang provinces supply food-grade silicone and TPU formulations to global hydration brands. GB standards for food-contact materials align with FDA and REACH frameworks for export-oriented production. The Pearl River Delta concentrates certified processing capacity, with Shenzhen and Dongguan facilities handling platinum-cured liquid silicone rubber migration.
Japan
Trail-running and ultralight backpacking communities prioritize gram savings and collapse-cycle durability in hydration gear. METI guidelines on chemical safety in consumer products reinforce stringent material disclosure requirements. The Kanto region around Tokyo anchors specialty outdoor retail distribution, with Shibuya and Shinjuku retailers curating premium hydration portfolios.
United Kingdom
Corporate wellness programs and airline procurement channels expand demand for branded collapsible bottles as employee amenities. The UK's post-Brexit chemicals regulatory framework maintains alignment with REACH substance restrictions for reusable food-contact items. London and the Southeast concentrate corporate sales channels, with procurement portals consolidating vendor relationships around documented compliance.
Collapsible Water Bottle Market Competitive Environment
On the supply side, the industry is consolidating around established hydration specialists with certified silicone supply chains and documented FDA and REACH compliance. Three strategic archetypes dominate: heritage outdoor brands leveraging trail-running and cycling distribution, premium insulated specialists competing on color customization and thermal retention, and ultralight specialists prioritizing packability for backpacking applications. Competitive moves concentrate on strategic partnerships with certified material processors and portfolio diversification into smart hydration formats with integrated tracking sensors.
Among heritage outdoor specialists, CamelBak and Hydro Flask occupy positions that exemplify divergent competitive vectors—CamelBak anchoring performance-oriented distribution through trail-running heritage, Hydro Flask sustaining brand loyalty through color customization and insulated variants. Que represents the ultralight specialization archetype, with its positioning in silicone construction for backpackers prioritizing packability. These three companies illustrate how material certification, channel access, and use-case targeting stratify competitive positioning.
| Leading Market Players |
|---|
| CamelBak |
| YETI |
| Que |
| Owala |
| Stanley |
| Hydro Flask |
| Nalgene |
| Iron Flask |
| Klean Kanteen |
| Others |
Value Chain & Pricing Dynamics
The Port of Hamburg's container handling costs for silicone and TPU feedstock shipments directly compress margin structures for European hydration brands while enabling price stratification between certified and uncertified supply tiers across German cycling retail channels.
Pricing Analysis
Volume-discount tiering separates institutional procurement from specialty retail markups across the collapsible hydration category. Three-tier pricing structure across premium, standard, and economy levels reflects FDA food-contact certification grade and platinum-cured silicone purity. Pricing pressure stems from precipitated silica feedstock volatility and concentrated testing laboratory bottlenecks. Corporate giveaway buyers exhibit highest price sensitivity, while adventure enthusiasts tolerate premium positioning for documented batch-level compliance.
Supply Chain Analysis
Export-control restrictions on advanced polymer processing equipment limit technology transfer to uncertified Chinese processors, concentrating high-purity silicone production among REACH-compliant facilities. Manufacturing clusters in Guangdong, Zhejiang, and Jiangsu provinces supply food-grade formulations to global hydration brands. Raw material dependencies center on precipitated silica, methyl chloride, and platinum catalyst feedstocks. Single-source vulnerability runs through the three major FDA testing laboratories. Distribution runs through Hamburg for European specialty retail and Los Angeles for US institutional procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collapsible water bottle category presents a service-attach opportunity as corporate wellness platform subscriptions and university procurement portal recurring orders expand faster than unit hardware sales.
For Market Incumbents: Insulate certified supply chain positions through backward integration into platinum-cured liquid silicone rubber processing or long-term offtake agreements with Pearl River Delta facilities. Direct-to-institution channel control and documented REACH Annex XVII compliance displace unverified imports from German alpine sports retail. FDA food-contact certification investment creates switching costs against emerging TPU specialists.
For New Entrants and Emerging Players: Establish a beachhead in corporate giveaway procurement through corporate wellness platform partnerships and airline amenity programs. The UK corporate wellness corridor and US university outdoor program networks offer lowest certification barrier entry points. Lead with PEVA and LDPE budget formats to bypass platinum-cured silicone supply bottlenecks.
For Investors and Strategic Acquirers: California's extended producer responsibility legislation reshapes the acquisition landscape toward brands with closed-loop silicone collection infrastructure and documented recyclability disclosure systems. Five-to-ten year viability favors vertically integrated processors with captive FDA and REACH testing relationships. The signal to watch is state-level EPR mandate expansion beyond California and Oregon into additional US jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Platinum-Cured Silicone Processing | CamelBak and Hydro Flask secure captive supply of 10,000-collapse-cycle material grades. |
| Direct-to-Institution Channel Expansion | Bypasses specialty retail SKU consolidation and captures recurring corporate wellness orders. |
| Smart Hydration Sensor Integration | Bluetooth-enabled consumption tracking targets marathon runners and trekking operators. |
| Closed-Loop Collection Infrastructure | California EPR compliance creates first-mover advantage in state-mandated material recovery. |
| REACH Annex XVII Certification Investment | German cycling tourism retailers require batch-level testing certificates for shelf placement. |
Study Parameters
Initial hypotheses were tested against primary input from brand managers at hydration specialists, procurement officers at university outdoor programs, category buyers at German cycling retailers, and supply chain directors at silicone processors and refined through secondary validation. Sources included FDA food-contact substance filings, ECHA REACH registration databases, US National Park Service concessionaire procurement records, and German cycling tourism economic impact reports. Bottom-up volume estimates triangulated against top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, application intensity, buyer procurement behavior, and channel access requirements. CAGRs derived from replacement cycle economics and institutional procurement expansion trajectories. Forecast inputs incorporated REACH Annex XVII regulatory stringency indices and state-level EPR adoption timelines.
Sensitivities concentrate around precipitated silica feedstock cost volatility and testing laboratory capacity constraints. Forecasts reflect assumptions on certification timeline standardization and corporate wellness platform vendor consolidation. Material shifts in FDA indirect additive regulations or EU polymer portfolio restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Portable Steamers Market
Household Items
UV Sanitizer Travel Wand Market
Household Items
United States Smart Shower Market
Household Items
Facial Tissue Paper Market
Household Items
Replacement Sheets Market
Household Items
Beach Towel Market
Household Items
Hand-Held Vacuum Cleaner Market
Household Items
Shower Heads Market
Household Items
Scouring Pads Market
Household Items
Paper Towel Dispenser Market
Household Items
Kitchen Towel Market
Household Items
Smart Toilet Market
Household Items
Latex Mattress Market
Household Items
Water Purifier Bottle Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Water Purifier Market