
 North America Robotic Pool Cleaner Market | 2026-2036
North America Robotic Pool Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
North America Robotic Pool Cleaner Market Insights
The capital-intensity gap between established manufacturers and emerging entrants is collapsing as modular component sourcing and contract manufacturing lower barriers to robotic assembly. Maytronics Ltd. leverages its dedicated research facilities in Israel to sustain proprietary scanning algorithms that anchor premium positioning across North American dealer networks. Pentair competes through backward integration into pump and filtration systems, allowing bundled equipment packages that control project specifications for new pool construction. Fluidra S.A. extends its European manufacturing scale to occupy price-sensitive segments through volume production of standardized drive mechanisms.
A robotic pool cleaner is an autonomous underwater vehicle engineered with sealed DC motors, polymer tracks or wheels, and debris filtration canisters typically rated between 2-5 microns, designed to traverse submerged surfaces without human guidance. These systems reduce chemical consumption by improving circulation and removing organic matter before algae colonization. In-ground cleaners dominate unit volume due to the structural complexity of sloped walls and deep ends that demand programmable navigation, while smart technology integration represents the fastest-expanding margin pool as WiFi-connected units enable scheduling through mobile applications. Above-ground cleaners remain a mature category with limited feature differentiation and compressed retail pricing.
The EPA's ENERGY STAR certification requirements shape motor efficiency standards, while FCC oversight governs wireless connectivity modules in smart-enabled units, and UL 1081 safety standards dictate electrical isolation for submerged operation. CSA Group certification creates parallel compliance obligations for Canadian market access, adding testing costs that favor larger manufacturers with dedicated regulatory affairs staff. Stakeholders must monitor how state-level water conservation mandates in California and Arizona reshape permissible flow rates and runtime algorithms.
Market Dynamics
The EPA's tightening ENERGY STAR motor efficiency standards are compressing product development cycles while forcing manufacturers to redesign sealed DC motor architectures for compliance, creating a structural bottleneck that favors incumbents with dedicated regulatory affairs capacity.
Growth Catalysts
- Suburban residential expansion:New housing developments across Texas, Florida, and Arizona are incorporating in-ground pools as standard amenities, creating installed-base growth that sustains replacement demand cycles.
- EPA ENERGY STAR certification:The federal efficiency program creates procurement preference among municipal and commercial buyers, locking in premium-tier specifications for public facility installations.
- Smart home integration:WiFi-enabled scheduling and mobile application control are shifting buyer expectations toward connected maintenance ecosystems, accelerating upgrade cycles among tech-adopting households.
Market Restraints
- Lithium-ion battery cost volatility:Sealed battery pack components face input price swings that compress margin predictability for cordless cleaner variants targeting premium segments.
- Canadian certification friction:CSA Group testing requirements add parallel compliance layers that extend time-to-market for new models, disproportionately burdening smaller manufacturers without dedicated certification staff.
- Manual cleaning substitution persistence:Suction-side and pressure-side hydraulic cleaners retain cost advantages in price-sensitive above-ground segments, limiting robotic unit penetration.
Strategic Opportunities
- California water conservation mandates:State-level restrictions on backwash discharge and runtime algorithms create demand for precision filtration that robotic units deliver through micron-rated canister systems.
- Arizona year-round usage intensity:Desert climate conditions sustain 12-month operational cycles that accelerate wear-based replacement compared to seasonal markets, concentrating demand velocity.
- Dealer network service bundling:Independent pool service contractors are expanding into equipment sales, creating alternative channel access beyond big-box retail that rewards technical training investments.
Industry Challenges
- Navigation algorithm talent scarcity:Proprietary scanning and mapping software development requires specialized robotics engineering expertise that concentrates in coastal technology clusters, creating recruitment friction for inland manufacturers.
- UL 1081 electrical isolation compliance:Submerged safety certification timelines extend product launch schedules, requiring advance planning that conflicts with seasonal demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Robotic Pool Cleaner Market |
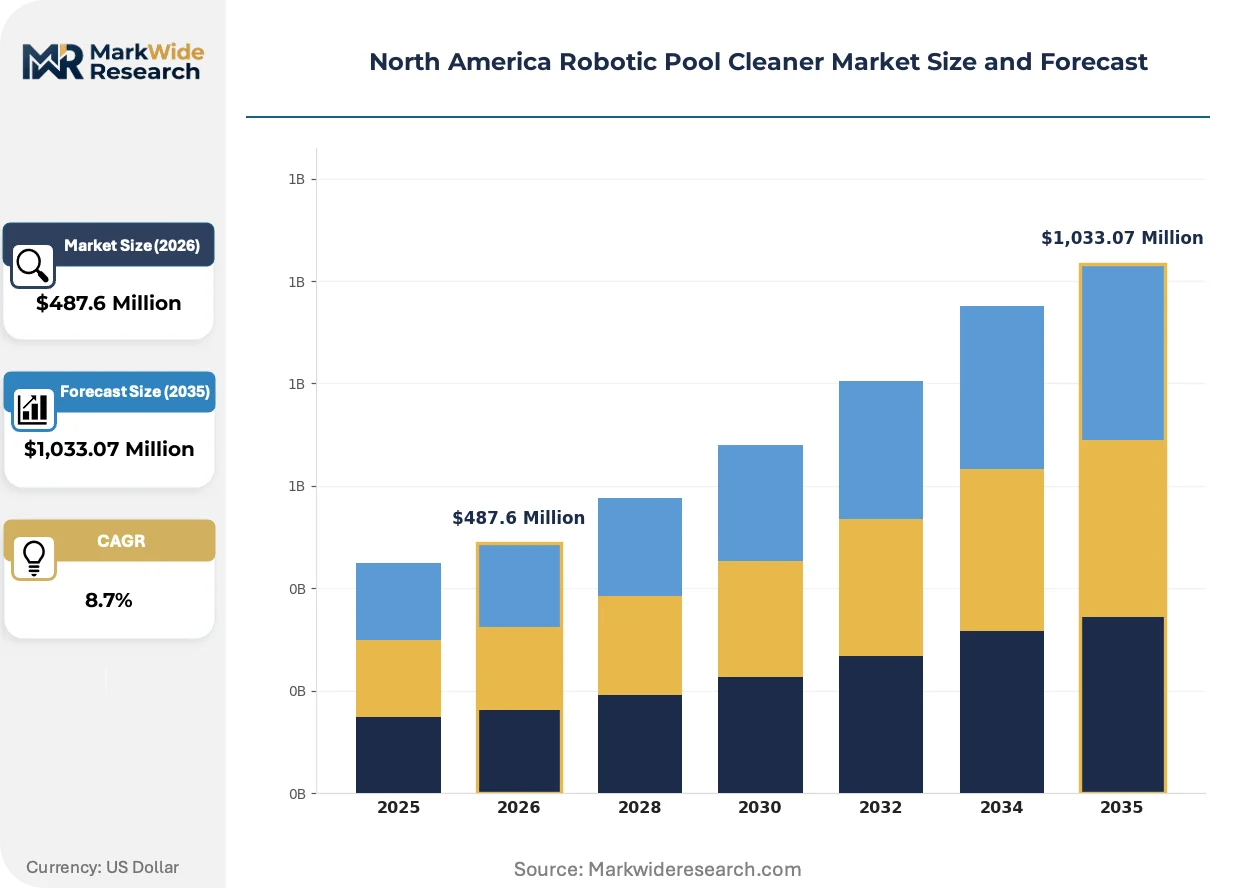
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ground Cleaners, Above-Ground Cleaners, Hybrid Cleaners, Suction Cleaners Technology: Automation, Remote Control, Sensor-Based, Smart Technology End User: Residential Users, Commercial Pools, Municipal Pools, Hotel Resorts Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Fluidra S.A., Water Tech, Pentair, iRobot Corporation, Polaris, Hayward Industries, Zodiac Pool Systems, BWT Holding Gmbh, Maytronics Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Robotic Pool Cleaner Market Trends and Innovations
Robotic pool cleaner architecture is splitting along capability lines as smart connectivity and autonomous navigation become baseline expectations rather than premium differentiators, compressing the feature-value equation across price tiers.
Machine vision and gyroscopic mapping is bifurcating the competitive landscape. Advanced units now deploy camera-based surface recognition and inertial measurement units to build real-time pool geometry models. High-end residential buyers in Florida and California are adopting these systems at accelerating rates. The technology is bifurcating premium positioning from mid-tier products, forcing standard-drive manufacturers toward price competition.
The EPA's evolving ENERGY STAR pool equipment specifications are tightening standby power draw and active runtime efficiency thresholds. Manufacturers must redesign motor controllers and pump algorithms to maintain certification eligibility. Cordless battery-powered variants face the steepest redesign burden, as EPA test protocols now capture full charge-cycle consumption profiles.
Service-oriented revenue models are displacing pure equipment sales in commercial segments. Municipal pool operators in Texas and Arizona are contracting for guaranteed uptime performance rather than capital purchasing, shifting vendor relationships toward maintenance subscriptions. This reconfiguration concentrates volume with manufacturers possessing regional technician networks, marginalizing direct-to-consumer brands lacking field service infrastructure.
North America Robotic Pool Cleaner Market Segmentation
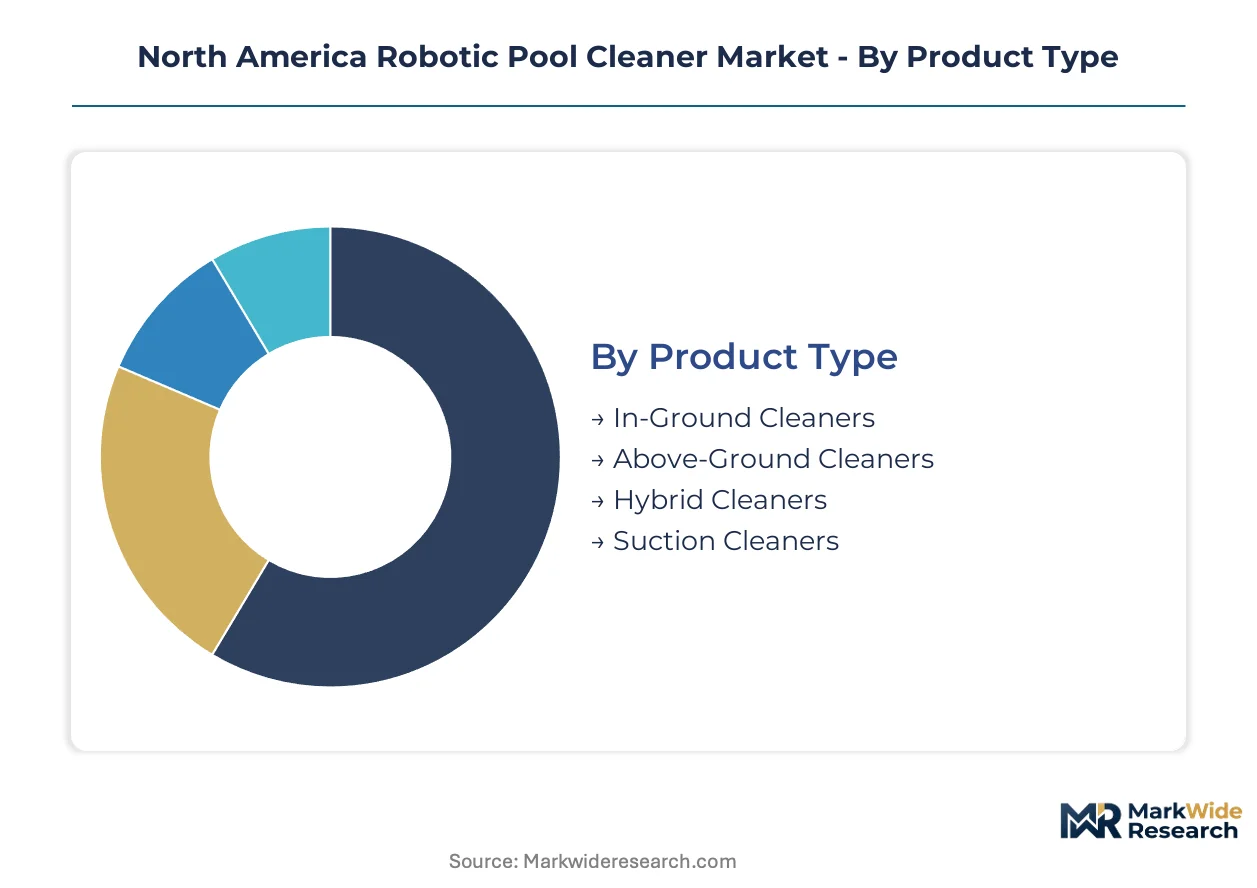
Segmentation in the North American robotic pool cleaner market reveals how substitution pressures from hydraulic cleaners and manual maintenance reshape competitive intensity across product tiers. Understanding these fault lines clarifies where automation delivers sufficient value to displace legacy cleaning methods.
Product Type:
Substitution pressure from suction-side and pressure-side hydraulic cleaners weighs most heavily on lower-tier robotic variants, forcing clear capability differentiation to justify price premiums.
- In-Ground Cleaners:These units incorporate sealed DC motors, polymer tracks, and programmable navigation algorithms engineered for sloped walls and deep-end traversal. Demand concentrates in suburban Texas and Florida communities where new housing developments specify in-ground pools as standard amenities, with EPA ENERGY STAR certification requirements tightening motor efficiency thresholds that favor established manufacturers with dedicated regulatory affairs capacity.
- Above-Ground Cleaners:Simplified drive mechanisms and flat-bottom navigation profiles define this mature category. Sales cluster in seasonal Midwest and Northeast markets where limited operational months compress replacement cycles and price sensitivity dominates purchasing decisions, leaving these units vulnerable to suction-cleaner substitution in cost-conscious segments.
- Hybrid Cleaners:Convertible architectures adapt between in-ground and above-ground configurations through modular track systems.
- Suction Cleaners:Hydraulic units that attach to existing pool pump infrastructure, representing the primary substitution threat to entry-level robotic models rather than a robotic segment per se.
In-Ground Cleaners retain volume leadership; Smart-enabled variants within this category hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium autonomous systems from mid-market remote-control units, with sensor density and connectivity modules driving manufacturing cost spreads.
- Automation:Self-contained navigation systems with gyroscopic mapping and programmable cleaning cycles eliminate human intervention. Arizona and California municipalities specify these units for public facilities to reduce labor costs, while FCC oversight of wireless connectivity modules adds compliance layers that extend development timelines for new entrants.
- Smart Technology:WiFi-enabled scheduling, mobile application control, and cloud-based performance monitoring integrate pool maintenance into connected home ecosystems. Adoption accelerates among tech-forward households in Florida's coastal communities where remote monitoring of vacation properties drives upgrade cycles.
- Remote Control:Tethered operation through handheld transmitters offers directional cleaning for spot maintenance at reduced cost.
- Sensor-Based:Obstacle detection and surface recognition through ultrasonic or infrared arrays enable adaptive navigation without full machine vision.
Automation commands the largest installed base; Smart Technology is climbing the fastest as connectivity becomes a baseline expectation rather than premium differentiator.
End User:
Application-specific durability requirements and procurement authority structures fragment demand across customer types with divergent purchasing rhythms.
- Residential Users:Individual homeowners purchasing through retail channels or pool service contractors, representing the volume foundation of the market. Sun-belt states including Arizona, Texas, and Florida sustain year-round usage intensity that accelerates wear-based replacement compared to seasonal markets.
- Commercial Pools:Fitness centers, aquatic facilities, and multi-unit residential complexes with high daily bather loads. These buyers in Texas and Arizona are shifting toward service-oriented revenue models with guaranteed uptime contracts rather than capital purchasing, concentrating volume with manufacturers possessing regional technician networks.
- Municipal Pools:Public facilities subject to municipal procurement rules and EPA ENERGY STAR preferences that lock in premium-tier specifications.
- Hotel Resorts:Hospitality properties where aesthetic standards and liability concerns drive specification of premium autonomous units with proven reliability records.
Residential Users anchor volume concentration; Commercial Pools are expanding most quickly as performance-based contracting reconfigures vendor relationships.
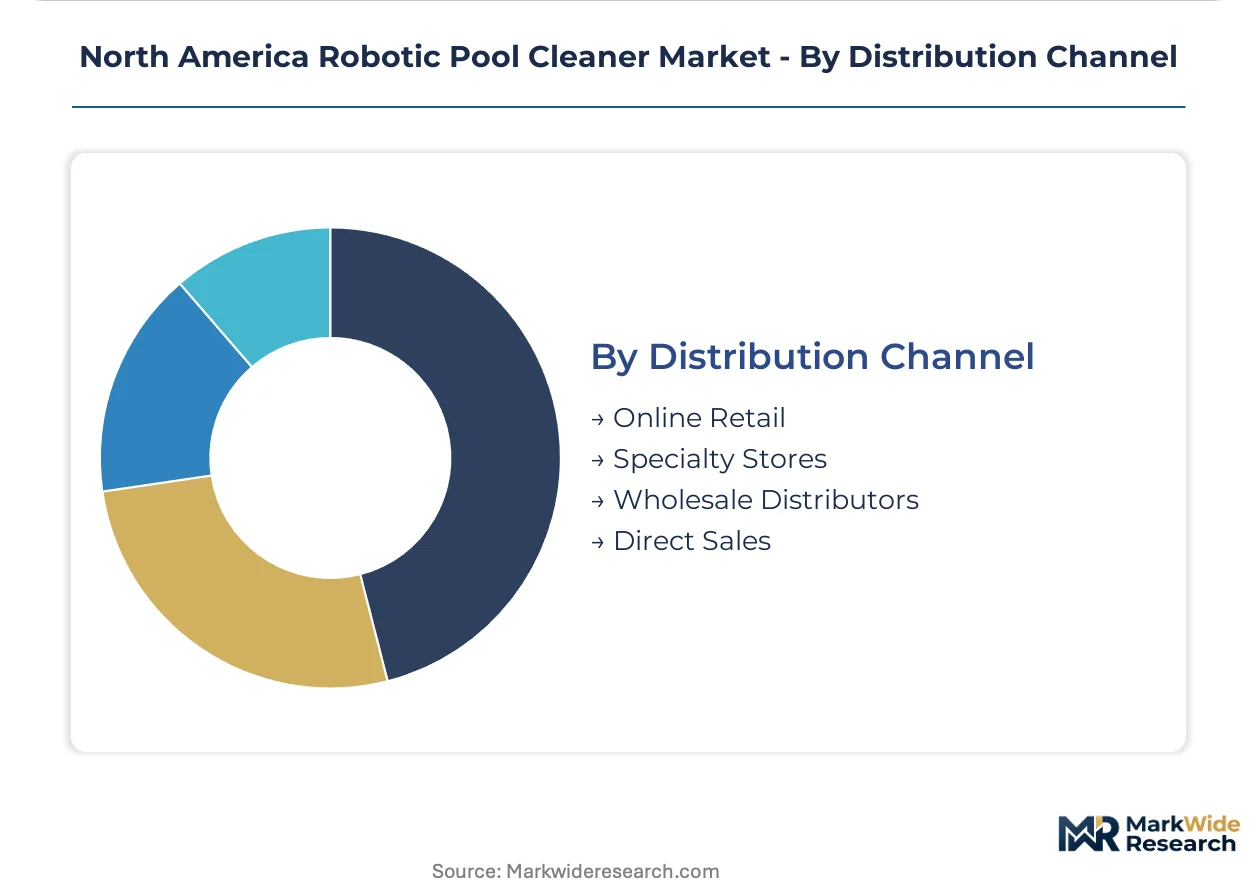
Distribution Channel:
Customer type and geography dictate channel selection, with technical complexity and service bundling requirements favoring specialized intermediaries over mass retail.
- Specialty Stores:Independent pool supply retailers with technical staff capable of demonstrating navigation features and maintenance procedures. These outlets dominate in Florida and Arizona where established dealer networks reward manufacturer investments in training and inventory support programs.
- Online Retail:E-commerce platforms capturing price-sensitive segments and replacement part sales, with growth concentrated among tech-adopting households comfortable with self-installation and remote troubleshooting.
- Wholesale Distributors:Regional inventory aggregators supplying contractor and builder channels with bulk pricing for new construction projects.
- Direct Sales:Manufacturer-owned channels targeting commercial and municipal accounts with customized service agreements.
Specialty Stores maintain the deepest market penetration; Online Retail is gaining share fastest as digital purchasing behaviors normalize across demographic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pool usage intensity varies sharply across North American geographies, with sun-belt states sustaining year-round operational cycles that accelerate equipment replacement while northern markets compress demand into seasonal windows.
United States
Suburban residential expansion across Texas and Florida anchors unit demand, with new housing developments specifying in-ground pools as standard amenities. The EPA's ENERGY STAR certification requirements tighten motor efficiency thresholds for equipment sold into municipal and commercial accounts. Dallas-Fort Worth and Houston metropolitan clusters concentrate dealer network activity, with independent pool service contractors expanding into equipment sales.
Canada
Seasonal operational constraints compress replacement cycles in Ontario and Quebec, where limited swimming months reduce wear-based demand compared to southern markets. CSA Group certification creates parallel compliance obligations that extend time-to-market for new models, favoring manufacturers with dedicated regulatory affairs staff. Toronto and Vancouver metropolitan areas sustain the deepest specialty retail penetration for premium-tier units.
California
State-level water conservation mandates on backwash discharge and runtime algorithms create procurement preference for precision filtration systems. The California Energy Commission supplements federal EPA standards with additional standby power draw requirements. Los Angeles and San Diego counties concentrate smart-home integration adoption, with WiFi-enabled scheduling shifting buyer expectations toward connected maintenance ecosystems.
Florida
Year-round pool usage intensity sustains the steepest replacement velocity in the national market, with 12-month operational cycles accelerating wear-based equipment turnover. Municipal procurement rules for public facilities lock in premium-tier autonomous specifications. Miami-Dade and Broward county clusters anchor dealer network density, with independent contractors capturing growing share through technical service bundling.
Arizona
Desert climate conditions drive continuous operational demand that concentrates replacement cycles compared to seasonal markets. State-level restrictions on water discharge reshape permissible flow rates and runtime algorithms for commercial installations. Phoenix and Tucson metropolitan areas represent the fastest-expanding residential buyer segments, with automated cleaning reducing manual maintenance labor across suburban communities.
North America Robotic Pool Cleaner Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the capital-intensity gap between established manufacturers and emerging entrants collapsing as modular component sourcing lowers barriers to robotic assembly. The competitive landscape splits into three strategic archetypes: vertically integrated pump and filtration system providers leveraging bundled equipment packages; dedicated robotics specialists commanding premium positioning through proprietary navigation algorithms; and volume-scale European manufacturers extending manufacturing scale to occupy price-sensitive segments. Dominant competitive moves include backward integration into core component supply and geographic expansion through regional technician network buildout.
Within the integrated systems tier, Pentair and Hayward Industries occupy positions anchored by captive pump and filtration supply chains that control project specifications for new pool construction. Maytronics Ltd. exemplifies the dedicated robotics specialist archetype, with Israeli research facilities sustaining proprietary scanning capabilities that anchor premium dealer network positioning. Fluidra S.A. represents the scale-driven European manufacturer, extending volume production of standardized drive mechanisms to capture price-sensitive segments across North American distribution channels.
| Leading Market Players |
|---|
| Fluidra S.A. |
| Water Tech |
| Pentair |
| iRobot Corporation |
| Polaris |
| Hayward Industries |
| Zodiac Pool Systems |
| BWT Holding Gmbh |
| Maytronics Ltd. |
| Others |
Pricing and Supply Chain Analysis
Polymer track systems replacing metal drive chains simultaneously redraws component sourcing maps toward Southeast Asian injection molders and compresses margin structures for legacy mechanical suppliers locked into higher-cost European production. This substitution dynamic concentrates pricing power with contract manufacturers capable of rapid tooling iteration while forcing incumbent brands to absorb certification costs or cede mid-market share.
Pricing Analysis
Project-based contracting dominates municipal and commercial procurement, with multi-year service agreements bundling equipment and maintenance displacing transactional sales. Price differentiation separates EPA ENERGY STAR-certified premium units from uncertified economy tiers, with brand premium and after-sales service coverage as secondary drivers. Pricing pressure stems from cordless battery variants facing lithium-ion cost volatility that squeezes margin predictability. Residential above-ground buyers exhibit highest price sensitivity, while municipal accounts with mandated efficiency specifications show lowest.
Supply Chain Analysis
China and Vietnam anchor polymer component fabrication and sealed motor assembly, with Israel sustaining proprietary navigation algorithm development. DC motor controllers, lithium-ion battery packs, and micron-rated filtration canisters constitute critical input dependencies. Single-source vulnerability concentrates in specialized gyroscopic sensor supply, where limited qualified vendors create chokepoint exposure. Distribution runs through independent specialty retailers in sun-belt states, supplemented by direct-to-consumer e-commerce for replacement parts and entry-tier units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among municipal procurement consortia and multi-site commercial operators, consolidating demand volume with manufacturers possessing regional service infrastructure and certified efficiency credentials.
For Market Incumbents: Compound dealer network loyalty through exclusive territory arrangements and technical certification programs that lock in contractor channel access. Defend against emerging Asian contract manufacturers by accelerating EPA ENERGY STAR pre-certification for next-generation motor architectures, creating compliance lead time that smaller rivals cannot match. For New Entrants and Emerging Players: Anchor in Arizona's suburban residential expansion, where year-round usage intensity accelerates replacement cycles and established service coverage remains patchy outside Phoenix-Tucson corridors. Target price-sensitive above-ground segments through online retail channels with simplified flat-bottom navigation units that undercut specialty store premiums. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated pump and filtration system providers with captive distribution. Long-term viability over the next decade rests on regulatory compliance capacity and technician network density rather than pure product innovation. Watch CSA Group certification backlog lengths as the inflection signal—extended timelines indicate regulatory friction favoring scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| EPA ENERGY STAR Pre-Certification Investment | Accelerates product launch timelines ahead of tightening federal motor efficiency mandates. |
| Regional Technician Network Expansion | Captures commercial service-contract revenue shifting from capital sales to uptime guarantees. |
| Modular Drive System Standardization | Reduces tooling costs and enables rapid configuration shifts between in-ground and above-ground variants. |
| Smart Home Platform Integration | Positions WiFi-enabled units within connected home ecosystems that tech-forward households prioritize. |
| Water Conservation Algorithm Development | Addresses California and Arizona state mandates on backwash discharge and runtime restrictions. |
Research Methodology
The analysis maps in-ground cleaners, above-ground cleaners, smart-enabled variants, and cordless battery architectures, each validated through primary interviews with pool service contractors, independent dealer owners, municipal procurement officers, and regulatory affairs directors at major manufacturers. Secondary validation draws from EPA ENERGY STAR certification databases, FCC equipment authorization filings, UL safety standard documentation, and customs import records. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, automation technology tier, end-user category, and geographic climate zone. CAGRs derive from fitted growth curves applied to replacement cycle analysis and new housing development correlations. Forecast inputs incorporate lithium-ion battery cost trajectory assumptions and state-level water conservation mandate adoption timelines.
Decision-makers should treat outputs as directional under assumptions of stable EPA regulatory timelines and continued sun-belt suburban expansion; material deviation in federal efficiency standards or regional housing construction would warrant model refresh. Recalibration cycles align with material shifts in battery chemistry costs and municipal procurement rule changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Ceramic Tableware Market
Household Items
Smart Memory Foam Market
Household Items
Portable Iron Market
Household Items
United States Barbeque Grill Market
Household Items
Europe Digital Showers Market
Household Items
Canada Digital Showers Market
Household Items
North America Water Purifier Market
Household Items
Soap Tablet Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Alarm Clocks Market
Household Items
Stainless Steel Water Bottles Market
Household Items
US Coin-Operated Commercial Laundry Market
Household Items
Smart Bathtub Market
Household Items
Pet Fur Remover Market
Household Items
Air Humidifier Market
Household Items
Barbecue Grill Market