
 US Hand Dryers Market | 2026-2036
US Hand Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
US Hand Dryers Market Insights
American manufacturing capacity for electric hand dryers is rebalancing toward high-velocity motor platforms and antimicrobial housing production. Excel Dryer leverages its Massachusetts-based operations to sustain domestic assembly lines for jet-air models. Dyson competes through R&D intensity in digital motor miniaturization, while World Dryer anchors the Midwest with broad distribution across institutional channels. Bradley Corporation differentiates through stainless-steel fabrication capabilities that serve correctional and healthcare specifications.
A hand dryer is an electrically powered device that removes moisture from hands through forced airflow, typically operating at air speeds between 180 and 400 mph with drying cycles of 10-15 seconds for high-speed units. The equipment serves commercial and institutional restrooms by eliminating paper waste and reducing maintenance labor. Jet and high-speed types command premium positioning due to energy efficiency gains and faster throughput in high-traffic venues. Wall-mounted installation dominates new construction, while portable variants capture renovation projects where electrical rough-in is constrained. Stainless steel and aluminum housings concentrate margin pools in sectors with stringent hygiene protocols.
OSHA guidelines on restroom sanitation, the EPA's Energy Star certification for commercial appliances, and DOE efficiency standards for electric motors collectively elevate baseline performance requirements for market entry. ADA compliance mandates on mounting heights and operational force thresholds filter product designs toward sensor-activation and universal-access formats. Stakeholders must monitor state-level building code adoptions and utility rebate programs that accelerate payback calculations for facility managers weighing capital upgrades against operating cost reductions.
Market Dynamics
Facility managers across US commercial real estate are compressing replacement cycles for restroom infrastructure, driven by EPA WaterSense water-efficiency mandates and state-level building code adoptions that penalize paper-based hygiene systems.
Growth Catalysts
- ADA Accessibility Standards:Federal mandates on mounting heights and operational force thresholds are filtering new construction specifications toward sensor-activated, universal-access hand dryer formats.
- Airports and Stadium Infrastructure:High-traffic venue operators are accelerating capital deployment toward jet-air platforms that reduce labor costs and waste removal burdens.
- Brushless DC Motor Platforms:Advances in high-velocity motor efficiency are extending equipment lifespans while cutting per-cycle energy consumption below legacy alternatives.
Market Restraints
- Copper and Aluminum Input Volatility:Housing fabrication depends on commodity metals exposed to tariff and supply chain disruptions, compressing margin predictability for domestic manufacturers.
- Midwest Supplier Concentration:Motor and control component sourcing clusters around Illinois and Ohio manufacturing corridors, creating geographic vulnerability to regional logistics constraints.
- Acoustic Performance Limitations:High-velocity airflow generates decibel levels that conflict with open-plan office and healthcare quiet-zone requirements, restricting addressable market segments.
Strategic Opportunities
- Texas and Florida Building Booms:Sun Belt commercial construction permits are outpacing national averages, creating concentrated demand for new-installation wall-mounted units.
- Antimicrobial Housing Convergence:Integration of copper-alloy surfaces with HEPA filtration systems opens specification pathways into correctional and clinical hygiene protocols.
- Utility Rebate Programs:State energy efficiency incentives in California and New York are shortening payback calculations for facility managers evaluating capital upgrades.
Industry Challenges
- Electrical Rough-In Coordination:Renovation projects in pre-1990 buildings face constrained conduit access, complicating installation timelines and requiring specialized contractor networks.
- Interoperability with Legacy BAS:Smart sensor integration demands protocol compatibility with existing building automation systems, extending commissioning cycles and technical support burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hand Dryers Market |
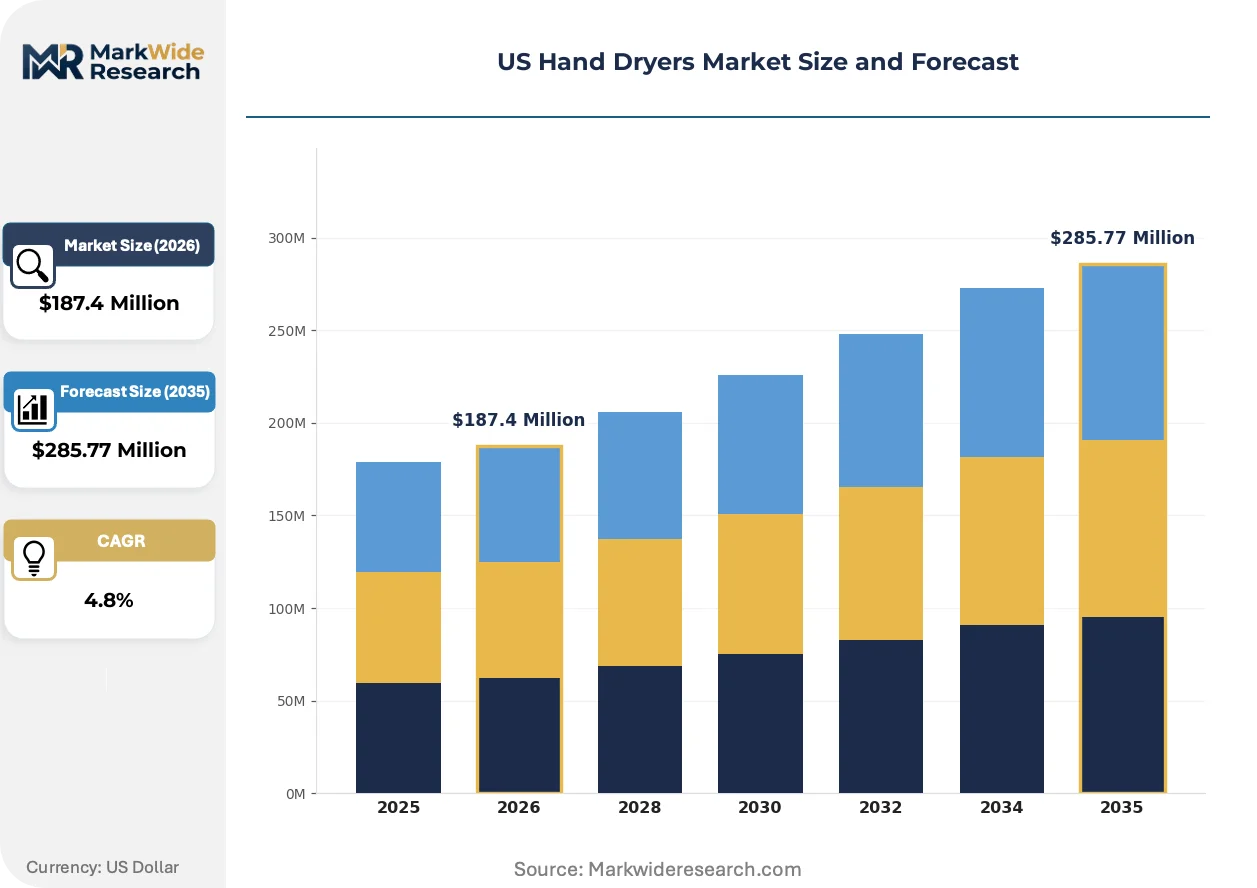
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Jet, Hot Air, Warm Air, High-Speed Installation Type: Wall-Mounted, Portable, Countertop, Integrated End User: Commercial, Residential, Industrial, Educational Material: Plastic, Stainless Steel, Aluminum, Metal |
| Companies Covered | Dyson, Excel Dryer, American Dryer, World Dryer, Bobrick Washroom Equipment, Bradley Corporation, Mitsubishi Electric, ASI Group, Palmer Fixture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hand Dryers Market Trends and Innovations
US restroom infrastructure is undergoing specification-driven transformation as energy efficiency mandates and hygiene protocols converge, compressing traditional equipment replacement timelines and elevating performance baselines for market entry.
HEPA filtration technology is integrating into high-velocity hand dryer housings to capture airborne pathogens during the drying cycle. Healthcare facility procurement teams in California and New York are specifying these units for patient-facing restrooms. This convergence of air purification with drying functionality is integrating infection control protocols directly into standard restroom equipment specifications.
EPA Energy Star certification requirements for commercial electric appliances are tightening motor efficiency thresholds and standby power limits. Manufacturers must redesign control electronics and fan assemblies to maintain program eligibility. The institutional channel, particularly K-12 school districts and municipal buildings, is responding by bundling Energy Star compliance into RFP evaluation criteria.
Facilities management departments are consolidating vendor relationships through national purchasing agreements with integrated hygiene service providers. Independent distributors and local electrical contractors are losing specification influence to centralized procurement platforms. This concentration is most visible in multi-site retail and hospitality chains operating across California, Texas, and Florida markets.
US Hand Dryers Market Segmentation
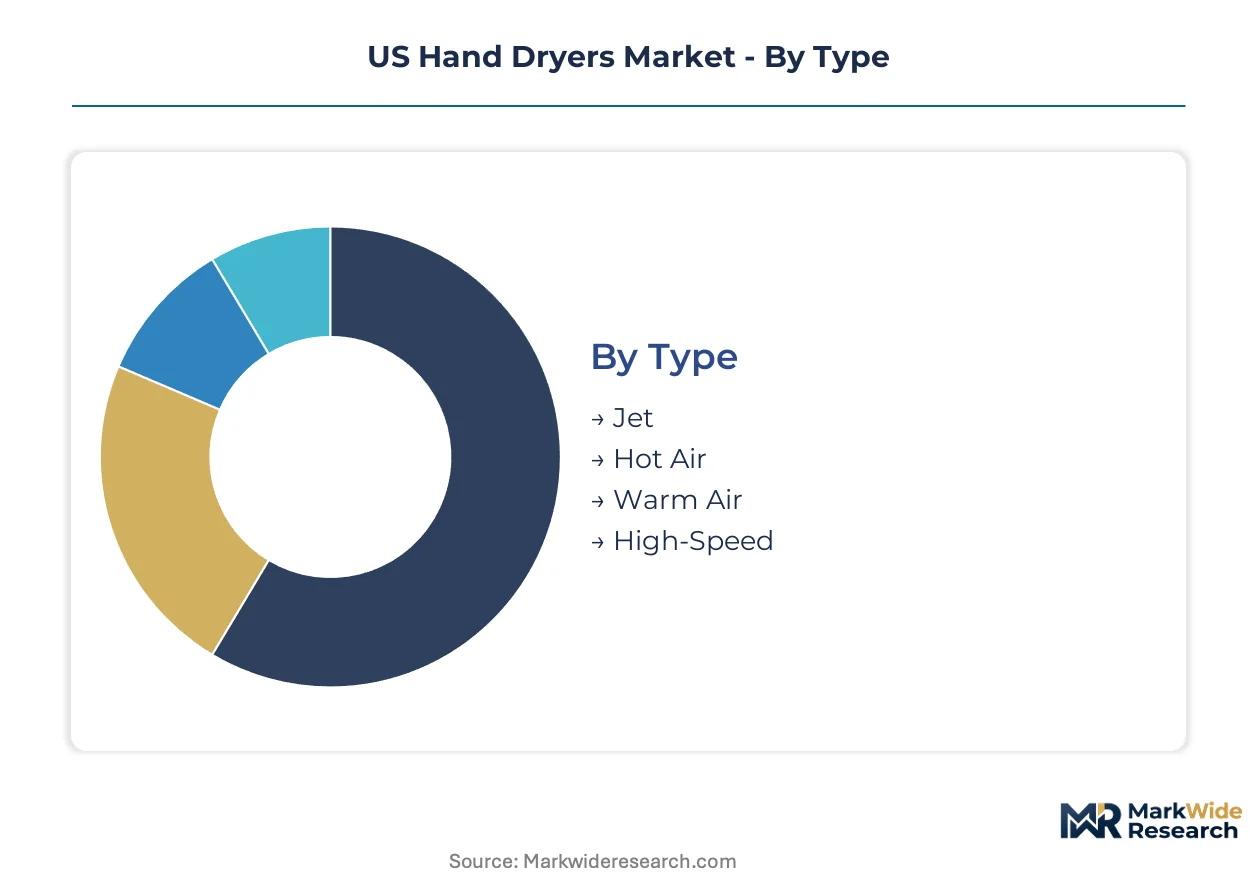
Facility managers evaluate hand dryers through divergent lenses: capital cost sensitivity in education, throughput demands in aviation, and infection control in healthcare. Segmentation clarity enables specification alignment with operational priorities and code compliance requirements.
Type:
Purchase decisions pivot on drying speed versus acoustic tolerance and energy recovery timelines.
- Jet:These units deploy focused high-velocity air streams at 300-400 mph to strip water from hands in 10-12 seconds. Demand concentrates in Texas and Florida airport terminals where passenger throughput metrics dominate capital planning and labor cost reduction justifies premium positioning.
- High-Speed:Operating at 180-250 mph with brushless DC motor platforms, these models balance performance with noise containment. California school districts specify these for K-12 renovations where ADA compliance and Energy Star qualification filter procurement shortlists.
- Hot Air:Conventional heating-element designs deliver 30-40 second cycles at lower capital cost. Budget-constrained municipal buildings in Midwest states specify these for replacement cycles.
- Warm Air:Moderate-velocity units with reduced heat output serve residential and light commercial installations where usage frequency remains intermittent.
Volume sits with Hot Air legacy replacements; growth tilts toward Jet platforms in high-traffic infrastructure.
Installation Type:
Construction phase determines specification—new builds favor permanent mounting while retrofits demand flexibility.
- Wall-Mounted:Hardwired electrical integration supports 15-20 year service lifespans in new commercial construction. Texas and Florida building booms are concentrating demand for these units in multi-tenant office and retail developments.
- Portable:Corded or battery-powered variants circumvent electrical rough-in constraints in pre-1990 buildings. Renovation contractors in New York and Chicago specify these for historic structure adaptations where conduit access remains restricted.
- Countertop:Surface-mounted designs serve temporary installations and event venues requiring rapid deployment.
- Integrated:Sink-adjacent or vanity-embedded configurations align with restroom design-build packages in hospitality and healthcare sectors.
Wall-Mounted dominates new construction value; Portable captures renovation flexibility premiums.
End User:
Operational intensity and hygiene protocols create divergent performance thresholds across sectors.
- Commercial:Airports, stadiums, and retail chains prioritize throughput and waste elimination. California and New York facility managers bundle these specifications into national purchasing agreements with integrated hygiene providers.
- Educational:K-12 and university procurement teams weight vandal resistance and acoustic performance. EPA Energy Star compliance filters RFP evaluation criteria for public district installations.
- Industrial:Manufacturing and warehouse environments specify heavy-duty housings for contamination control in food processing and pharmaceutical production zones.
- Residential:High-end multifamily and single-family installations represent a narrow premium segment driven by sustainability preferences.
Commercial commands installed base share; Educational exhibits steepest expansion trajectory as district modernization accelerates.
Material:
Housing selection balances procurement cost against durability requirements and hygiene audit standards.
- Stainless Steel:Grade 304 and 316 fabrications withstand corrosive cleaning protocols and physical impact. Correctional facilities and healthcare systems in California specify these for infection control compliance and longevity in high-abuse environments.
- Aluminum:Lightweight, corrosion-resistant housings serve mid-tier commercial installations where weight constraints and cost efficiency intersect.
- Plastic:ABS and polycarbonate variants dominate budget-sensitive educational and light commercial segments with shorter replacement cycles.
- Metal:Powder-coated steel alternatives occupy the value tier for industrial and municipal applications.
Plastic holds volume leadership in unit shipments; Stainless Steel gains specification share fastest in healthcare and corrections.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum and copper sourcing corridors in the Midwest anchor American hand dryer manufacturing, with motor component clusters concentrated around Illinois and Ohio production belts.
California
WaterSense mandates from the EPA and Title 24 building efficiency codes drive specification shifts toward high-velocity electric units in municipal and commercial restrooms. Los Angeles and San Francisco school districts bundle Energy Star compliance into procurement criteria. The Bay Area's tech campus construction pipeline sustains demand for sensor-activated, low-decibel installations.
Texas
Dallas-Fort Worth and Houston airport expansions prioritize jet-air platforms that compress passenger throughput times. State energy efficiency rebate programs shorten payback periods for facility managers replacing paper-based systems. The Austin-San Antonio corridor's corporate campus construction concentrates wall-mounted unit demand.
New York
ADA enforcement by the Department of Buildings filters renovation specifications toward universal-access formats with reduced operational force thresholds. Historic structure adaptations in Manhattan and Brooklyn rely on portable units where electrical rough-in remains constrained. The Port Authority's terminal modernization programs anchor high-traffic venue procurement.
Illinois
Chicago Public Schools' district-wide modernization drives specification volume for vandal-resistant, acoustic-controlled units. State procurement guidelines favor Energy Star-qualified equipment in public building renovations. The Rockford manufacturing corridor supplies brushless DC motor platforms to domestic assembly operations.
Florida
Orlando and Miami international airport terminals deploy jet-air systems to manage peak passenger volumes. Hurricane-resistant building codes elevate stainless-steel housing specifications for durability in high-humidity environments. The Tampa-St. Petersburg commercial construction permits outpace national averages for restroom infrastructure deployment.
US Hand Dryers Market Competitive Landscape
Global majors compete with regional champions across motor technology and distribution reach, producing a tiered structure where R&D intensity separates premium positioning from value-tier procurement. The vendor base clusters around three strategic archetypes: high-velocity motor specialists, institutional channel anchors, and stainless-steel fabrication experts. Capacity expansion and antimicrobial housing convergence represent the dominant competitive moves reshaping specification influence.
Among domestic manufacturers, Excel Dryer anchors the Massachusetts-based production cluster for jet-air platforms, while World Dryer occupies the Midwest institutional channel position. Bradley Corporation exemplifies the stainless-steel fabrication archetype serving correctional and healthcare specifications. These three represent distinct competitive vectors—geographic proximity to end-markets, distribution breadth, and material specialization—rather than overlapping strategic positioning.
| Leading Market Players |
|---|
| Dyson |
| Excel Dryer |
| American Dryer |
| World Dryer |
| Bobrick Washroom Equipment |
| Bradley Corporation |
| Mitsubishi Electric |
| ASI Group |
| Palmer Fixture |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor engineering talent clusters around the Rockford manufacturing corridor in Illinois, creating labor-cost differentials that widen pricing-tier spreads between premium jet-air platforms and conventional hot-air units.
Pricing Analysis
Warranty and service bundling separates procurement tiers in this market, with premium manufacturers packaging extended motor warranties and preventive maintenance while value-tier suppliers unbundle these services. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by motor efficiency certification and acoustic performance grade. Cost compression in the hot-air segment is intensifying because commodity metal input volatility compresses margin predictability. Municipal procurement teams in the Midwest exhibit the highest price sensitivity, while airport authorities in Texas and Florida prioritize throughput metrics over capital cost.
Supply Chain Analysis
Reverse-logistics flows for motor refurbishment and housing remanufacturing are underdeveloped, constraining circular economy participation and extending replacement cycle dependencies on virgin materials. Manufacturing capacity concentrates in the United States, China, and Mexico, with domestic assembly drawing from Illinois and Ohio motor component clusters. Raw material dependencies center on copper windings, aluminum extrusions, and ABS polymer resins. Single-source vulnerability in brushless DC controller chips creates procurement risk. Distribution runs through integrated hygiene service providers and electrical contractor networks serving commercial construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US hand dryer manufacturing operates under supply-constrained conditions, with domestic brushless DC motor fabrication capacity bottlenecks propping pricing power for manufacturers with captive component sourcing.
For Market Incumbents: Anchor manufacturing capacity in the Rockford corridor to secure motor engineering talent pools and reduce logistics exposure. Defend against emerging Asian entrants with antimicrobial housing convergence and HEPA filtration integration. Prioritize vertical integration into controller electronics to mitigate semiconductor supply vulnerability.
For New Entrants and Emerging Players: E-commerce specification platforms offer a direct channel to bypass entrenched distributor relationships in the educational segment. Target K-12 renovation projects in California and New York where Energy Star compliance filters create procurement entry points. Lead with portable unit configurations addressing electrical rough-in constraints in pre-1990 buildings.
For Investors and Strategic Acquirers: The window for entry favors stainless-steel fabrication specialists with healthcare and correctional certifications. Long-term viability hinges on antimicrobial housing technology convergence and smart sensor integration capabilities. Monitor EPA Energy Star threshold revisions as inflection indicators for specification lock-in opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Housing Convergence | Copper-alloy surface integration opens specification pathways into California healthcare procurement. |
| Brushless DC Motor Platform Expansion | Illinois-based capacity additions reduce geographic vulnerability to regional logistics constraints. |
| HEPA Filtration Integration | Air purification functionality aligns with New York hospital infection control protocols. |
| Smart Sensor Development | Building automation system compatibility addresses interoperability challenges in commercial retrofits. |
| Utility Rebate Program Alignment | California and New York incentive qualification shortens facility manager payback calculations. |
Research Methodology
SEC filings, EPA Energy Star certification databases, and state procurement records formed the secondary backbone, supplemented by customs trade data on copper and aluminum inputs. Primary interviews with facility managers, electrical contractors, and distribution channel partners validated installation trends and specification priorities. Bottom-up triangulation across product type, installation format, and end-use sector informed volume estimates, while top-down analysis anchored value projections.
Historical trendline analysis tracked replacement cycle compression and technology substitution patterns across the analysis window. Segmentation modeling incorporated type, installation format, end user, and material dimensions alongside regional building code adoption clusters. CAGRs were derived from installed base turnover rates and new construction permit trajectories, with motor efficiency standards and ADA compliance thresholds serving as structural forecast inputs.
The model holds under stable commodity metal pricing and continued EPA WaterSense program enforcement; deviation in tariff regimes or state-level rebate program suspensions would shift replacement cycle timelines. Practitioners should monitor Illinois and Ohio logistics corridor disruptions and brushless DC controller chip availability for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
India Non-Stick Cookware Market
Household Items
Enameled Cookware Market
Household Items
Smart Toilet Market
Household Items
Candle Air Fresheners Market
Household Items
Crash Mat Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Shower Caddies Market
Household Items
Shower Heads Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Car Air Freshener Market
Household Items
MENA POU Water Purifiers Market
Household Items
Flatware Market
Household Items
Electric Hedge Trimmer Market
Household Items
Electric Clothes Drying Hanger Market
Household Items
Collapsible Water Bottle Market