
 Oman Gas Hobs Market | 2026-2036
Oman Gas Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Gas Hobs Market Analytics
Omani appliance distributors is restructuring procurement networks to reduce lead times from European and Asian manufacturing hubs. Siemens anchors its position through technical partnerships with local kitchen integrators serving high-end residential compounds. Bosch competes on safety certification depth, leveraging its compliance portfolio to secure hospitality contracts in Muscat. Prestige differentiates through localized burner configurations optimized for LPG pressure standards common in Omani households.
A gas hob is a cooking appliance featuring one or more gas burners integrated into a countertop or standalone chassis, typically constructed from stainless steel or tempered glass with cast iron pan supports and thermal outputs ranging from one to five kilowatts per burner; its primary purpose is to provide controlled flame cooking for residential kitchens, commercial food preparation, and institutional catering. Built-in hobs dominate value capture in Oman's market, as villa-style housing and custom kitchen installations favor flush-mounted designs over freestanding alternatives. Touch control interfaces represent the fastest-growing segment, with digital ignition systems displacing traditional knob configurations in new Muscat residential developments.
The Omani Authority for Electricity Regulation enforces gas appliance safety standards that require type-testing and certification for all imported hobs, effectively limiting market access to manufacturers with established conformity assessment capabilities. MOHAP-aligned technical specifications for commercial kitchen equipment further shape product specifications in the hospitality end-user segment. Stakeholders must monitor evolving energy efficiency benchmarks and local content requirements that could reshape supplier qualification criteria.
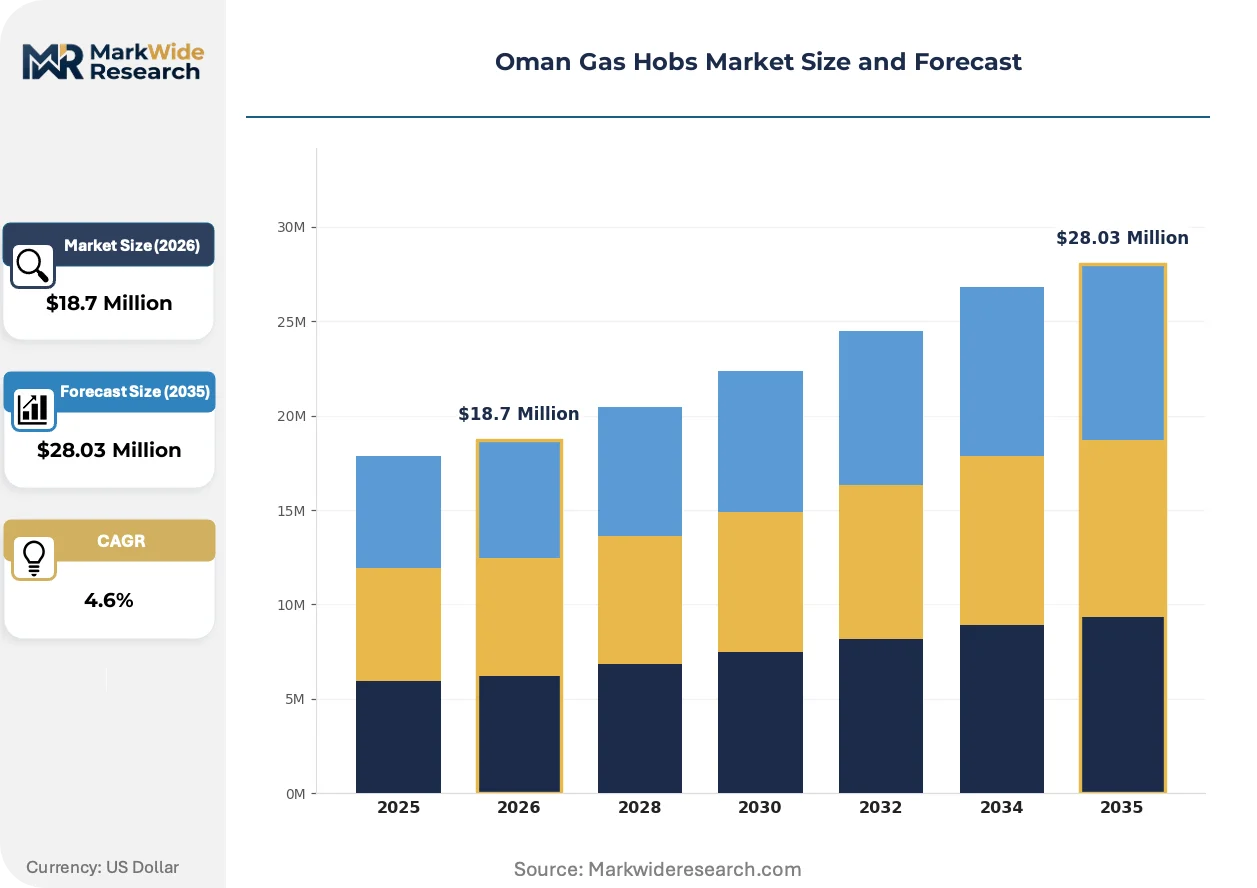
Market Dynamics
The Omani Authority for Electricity Regulation's mandatory gas appliance safety certifications are filtering import flows and restructuring competitive access, forcing distributors to rebuild supplier portfolios around conformity-assessment capabilities rather than pure cost optimization.
Growth Catalysts
- Residential Renovation Momentum:Kitchen refurbishment cycles in Muscat and Salalah are compressing replacement timelines for built-in hobs as villa owners prioritize modernized cooking infrastructure.
- Hospitality Procurement Anchors:New hotel and resort developments across the Sultanate are generating concentrated demand for certified commercial-grade gas hobs with extended burner configurations.
- LPG Infrastructure Maturity:Standardized household gas pressure specifications are enabling localized burner optimization that improves combustion efficiency for Omani cooking practices.
Market Restraints
- Import Certification Friction:Type-testing requirements enforced by the Omani Authority for Electricity Regulation extend lead times for uncertified manufacturers lacking established conformity assessment partnerships.
- European Supply Concentration:Premium hob sourcing remains concentrated in German and Italian manufacturing hubs, exposing distributors to currency volatility and extended shipping corridors.
- Induction Substitution Pressure:Electric cooking alternatives are capturing share in new apartment developments where gas infrastructure installation costs exceed electrical retrofit economics.
Strategic Opportunities
- Salalah Corridor Expansion:Dhofar Governorate's emerging residential compounds and tourism infrastructure present underpenetrated demand for mid-tier built-in hobs outside Muscat's saturated core.
- Touch Control Convergence:Digital ignition interfaces are converging with smart home integration protocols in high-end villa developments, creating upgrade pathways beyond basic knob configurations.
- Local Assembly Incentives:Potential domestic content requirements could reward distributors establishing kit-assembly operations within Omani free zones, reducing landed cost structures.
Industry Challenges
- Certification Timeline Compression:Safety testing backlogs at accredited laboratories are delaying product launches for new market entrants seeking Omani Authority for Electricity Regulation approval.
- Technical Service Fragmentation:After-sales support networks for digital control systems remain underdeveloped outside Muscat, constraining warranty fulfillment for touch-interface hobs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Gas Hobs Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $28.03 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in Hobs, Freestanding Hobs, Modular Hobs, Portable Hobs Material: Stainless Steel, Glass, Enamel, Cast Iron Control Type: Knob Control, Touch Control, Digital Control, Remote Control End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Simfer, Siemens, Electrolux, Bertazzoni, Gorenje, Bosch, Prestige, Carysil, Rinnai, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Gas Hobs Market Evolving Landscape
Digital control architectures are displacing mechanical ignition systems across Oman's premium residential segment, while regulatory compliance requirements are reshaping supplier qualification criteria and procurement patterns among major distributors.
Tempered glass surface technology is converging with flame-failure safety systems to create integrated cooking platforms that combine aesthetic minimalism with automatic gas cut-off protection. High-end villa developers in Muscat Governorate are specifying these configurations as standard fitments in new compound releases. The convergence is compressing demand for traditional stainless steel hob formats that lack integrated safety electronics.
The Omani Authority for Electricity Regulation's type-testing mandates are forcing distributors to maintain documented conformity assessment trails for every imported SKU, creating administrative overhead that favors established suppliers with dedicated certification staff. Commercial kitchen operators in hospitality are responding by consolidating procurement around vendors with pre-approved product portfolios rather than experimenting with unverified alternatives.
Buyer concentration among large-scale kitchen integrators is displacing fragmented retail purchasing as the dominant demand channel for built-in hobs in new construction. These integrators now specify burner configurations and control interfaces during early design phases, locking out last-minute substitution. The shift is most visible in Muscat's premium residential compounds where turnkey fit-out contracts bundle appliance selection with interior design services.
Oman Gas Hobs Market Segmentation
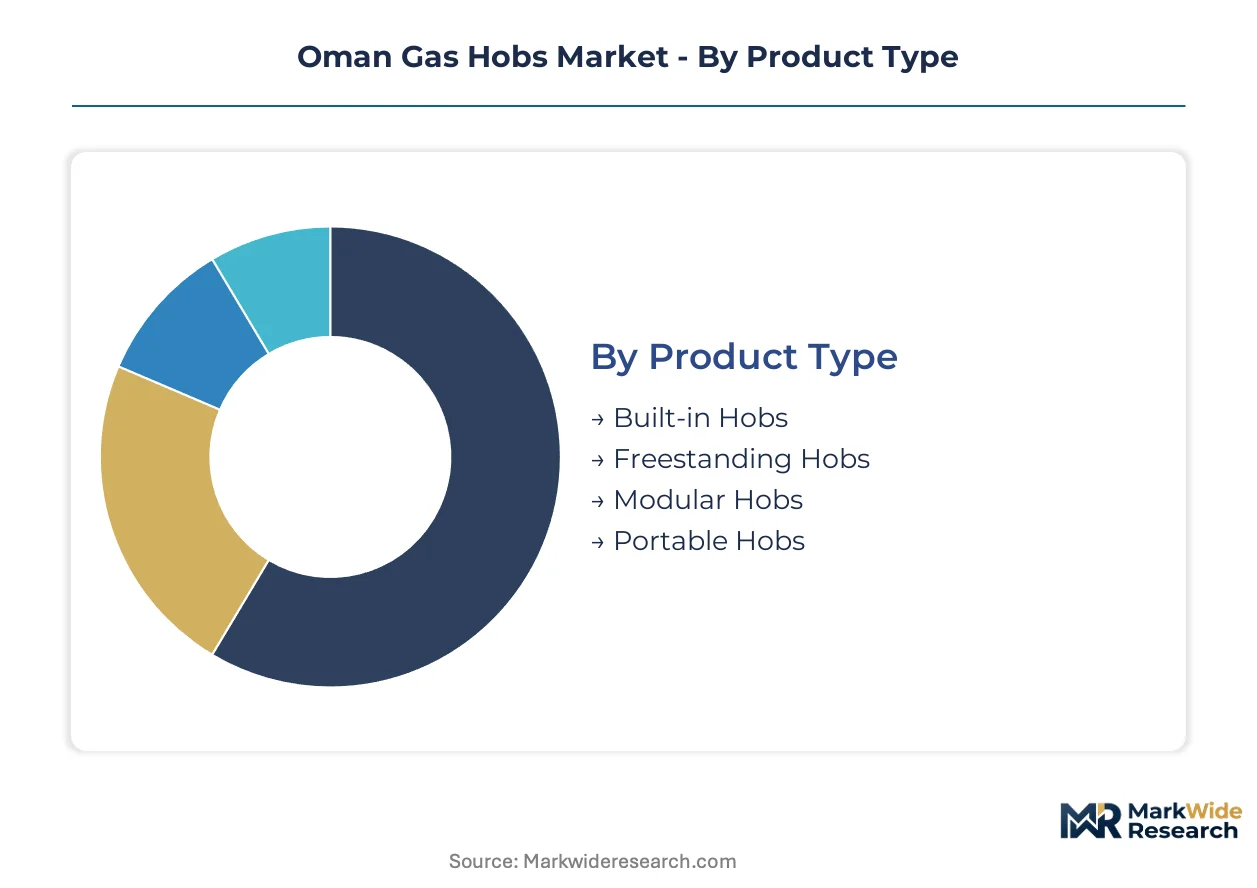
Segmentation in the Oman Gas Hobs Market reveals how procurement decisions split across installation constraints, surface durability requirements, interface preferences, and operational intensity. Each dimension carries distinct certification implications under Omani Authority for Electricity Regulation mandates.
Product Type:
Installation permanence and kitchen design integration drive buyer selection, with villa-style housing favoring flush-mounted solutions over movable alternatives.
- Built-in Hobs:These countertop-integrated units feature sealed burner assemblies and recessed chassis designed for permanent kitchen installation. Demand concentrates in Muscat Governorate's new villa compounds, where turnkey fit-out contracts specify flush-mounted configurations as standard. Custom kitchen integrators lock in burner specifications during early design phases, eliminating last-minute substitution.
- Freestanding Hobs:Self-contained units with integrated bases and side panels accommodate rental properties and temporary kitchen setups. Salalah's emerging residential compounds show rising procurement for mid-tier freestanding units where installation flexibility outweighs aesthetic integration. The Omani Authority for Electricity Regulation's certification requirements apply equally, extending lead times for uncertified imports.
- Modular Hobs:Configurable burner units allow spatial customization across non-standard countertop dimensions. Coastal tourism projects in Dhofar Governorate specify modular formats for open-plan kitchen layouts.
- Portable Hobs:Compact single-burner units with detachable gas connections serve outdoor catering and emergency backup cooking. Institutional procurement for remote site operations anchors volume.
Built-in hobs lead on scale; modular hobs lead on momentum.
Material:
Surface durability and thermal shock resistance determine replacement cycles, with coastal humidity and LPG combustion byproducts accelerating corrosion in lower-grade substrates.
- Stainless Steel:Brushed or polished steel surfaces with chromium-nickel alloy compositions resist oxidation and thermal deformation. Commercial kitchens in Muscat's hospitality sector specify heavy-gauge stainless formats for high-frequency cooking operations. The material's repairability extends service life beyond glass alternatives.
- Glass:Tempered ceramic glass panels with thermal printing deliver aesthetic minimalism and flat cleaning surfaces. Premium villa developers in Al Mouj and Al Hail compounds specify glass hobs as standard fitments. Flame-failure safety electronics integrate more cleanly beneath glass substrates than metal.
- Enamel:Powder-coated steel surfaces with vitreous enamel layers offer cost-effective corrosion protection. Mid-tier residential procurement in interior governorates favors enamel for budget-constrained renovations.
- Cast Iron:Solid iron grates and burner caps provide thermal mass for consistent heat distribution. Traditional cooking applications in rural households maintain demand despite weight and maintenance requirements.
Stainless steel dominates commercial procurement; glass surfaces are climbing the fastest in residential premium tiers.
Control Type:
Interface sophistication correlates with buyer age demographics and smart home integration requirements, with digital formats displacing mechanical ignition in new construction.
- Knob Control:Rotary mechanical valves with piezoelectric ignition deliver tactile feedback and field-repairable simplicity. Existing housing stock replacements and conservative buyer segments sustain demand despite aesthetic limitations.
- Touch Control:Capacitive sensor panels with digital ignition sequencing enable flat surface designs and programmable timer functions. Muscat's high-end residential compounds specify touch interfaces as standard in new releases. After-sales support networks for digital systems remain underdeveloped outside the capital.
- Digital Control:Microprocessor-managed flame modulation with temperature feedback loops supports precision cooking applications. Commercial kitchen operators in hospitality procurement value programmable consistency.
- Remote Control:Wireless-enabled interfaces with smartphone integration permit pre-heating and monitoring from adjacent spaces. Experimental deployment in luxury villa prototypes tests market readiness.
Knob control retains volume leadership; touch control shows the steepest expansion trajectory among new installations.
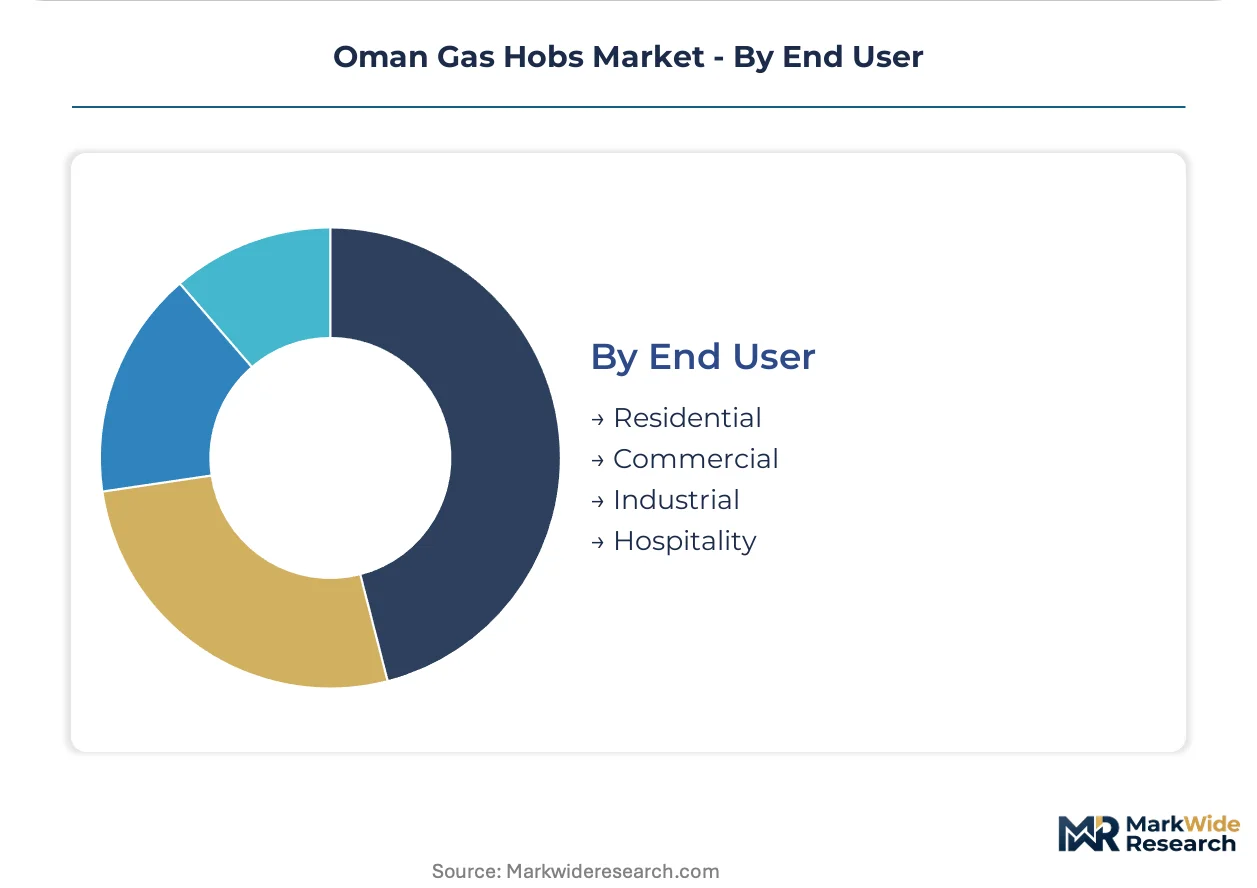
End User:
Operational intensity and duty cycle requirements separate procurement specifications, with certification depth varying across residential, commercial, and institutional applications.
- Residential:Household cooking installations with intermittent daily use and standardized burner configurations. Muscat and Salalah renovation cycles compress replacement timelines as villa owners modernize kitchen infrastructure.
- Commercial:High-throughput food service operations with extended daily runtimes and specialized burner formats. Restaurant clusters in Ruwi and Al Khuwair drive demand for heavy-duty cast iron grate systems.
- Industrial:Large-scale catering facilities and centralized kitchen operations with volume cooking requirements. Remote oil and gas site operations generate concentrated procurement for certified commercial-grade equipment.
- Hospitality:Hotel and resort kitchen installations with brand-standard fit-out specifications and extended warranty requirements. New tourism developments across the Sultanate anchor premium hob procurement with pre-approved vendor portfolios.
Residential captures absolute volume; hospitality commands the highest per-unit specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany anchors European gas hob manufacturing with precision engineering clusters; China dominates mass-market fabrication through integrated supply chains. The following countries concentrate production, certification expertise, and distribution networks for this appliance category.
Germany
Industrial engineering heritage supports high-precision burner manufacturing for premium export markets. The country's national product safety regulator enforces rigorous type-testing protocols for gas appliances entering distribution. Manufacturing concentrates in Baden-Württemberg and Bavaria, where specialized metalworking clusters supply cast iron components to hob assemblers.
China
Integrated steel and glass supply chains enable cost-competitive tempered glass hob production at scale. The State Administration for Market Regulation coordinates national standards alignment with import market requirements. Zhejiang and Guangdong provinces host dense concentrations of appliance OEMs serving Middle Eastern distributors through Ningbo and Shenzhen port corridors.
Italy
Design-forward kitchen appliance traditions sustain premium positioning in European and Gulf markets. National technical standards bodies collaborate with EU harmonized certification frameworks for gas-burning equipment. Manufacturing clusters in Lombardy and Emilia-Romagna export built-in hobs through Milan-based trading houses.
Japan
Advanced combustion control technologies differentiate precision flame modulation systems for commercial applications. The Ministry of Economy, Trade and Industry oversees energy efficiency benchmarking for residential cooking equipment. Industrial corridors around Nagoya and Osaka supply high-reliability ignition components to global hob manufacturers.
Turkey
Strategic geographic positioning bridges European supply chains with Middle Eastern distribution networks. The Turkish Standards Institution mandates conformity assessment for gas appliances transiting to Gulf Cooperation Council markets. Manufacturing in the Marmara region supplies mid-tier built-in hobs through Istanbul-based logistics hubs.
Oman Gas Hobs Market Competitive Landscape
German producers anchor one tier; Chinese fabricators hold volume manufacturing positions. The vendor base splits between consolidated European engineering groups with certification depth and fragmented Asian specialists competing on landed cost. Three archetypes dominate: heritage European appliance brands, integrated conglomerates with multi-category portfolios, and regional specialists optimizing for LPG pressure standards. Competitive moves concentrate on distributor partnership exclusivity and conformity assessment pre-certification to accelerate market entry.
Within the heritage European tier, Siemens and Bosch exemplify engineering-led positioning through technical compliance depth. Prestige occupies a distinct archetype as a regional specialist with localized burner configurations. These three anchors illustrate how certification capability and product adaptation separate sustainable market access from transactional import competition.
| Leading Market Players |
|---|
| Simfer |
| Siemens |
| Electrolux |
| Bertazzoni |
| Gorenje |
| Bosch |
| Prestige |
| Carysil |
| Rinnai |
| Others |
Value Network & Pricing Analysis
Touch control interface adoption across Muscat's premium villa compounds simultaneously compresses manufacturing cost curves at scale and concentrates procurement power among kitchen integrators with specification authority during early design phases. This technology shift feeds back into supplier selection, favoring established European and Asian manufacturers with dedicated certification staff over fragmented cost-optimizers lacking conformity assessment capabilities.
Pricing Analysis
Capacity additions in China's Zhejiang and Guangdong provinces are reshaping price floors for mid-tier tempered glass hobs entering Omani distribution. Three-tier pricing structure across premium, standard, and economy levels separates Siemens and Bosch's certification-heavy portfolios from Turkish mid-tier entrants and Chinese volume suppliers. Pricing pressure stems from induction cooking substitution in new apartment developments where electrical retrofit economics undercut gas infrastructure installation. Hospitality procurement shows lowest price sensitivity due to brand-standard fit-out specifications and extended warranty requirements.
Supply Chain Analysis
Freight cost volatility through Ningbo and Shenzhen port corridors directly impacts landed cost structures for Chinese-manufactured hobs destined for Muscat distributors. Supply concentrates in Germany, China, and Italy for finished assemblies, with cast iron burner components sourcing from Baden-Württemberg metalworking clusters and tempered glass substrates from Guangdong integrated steel-glass supply chains. Single-source vulnerability sits with European ignition component suppliers serving premium digital control architectures. Distribution runs through Istanbul-based logistics hubs and direct Muscat distributor relationships, bypassing traditional retail channels in favor of kitchen integrator consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
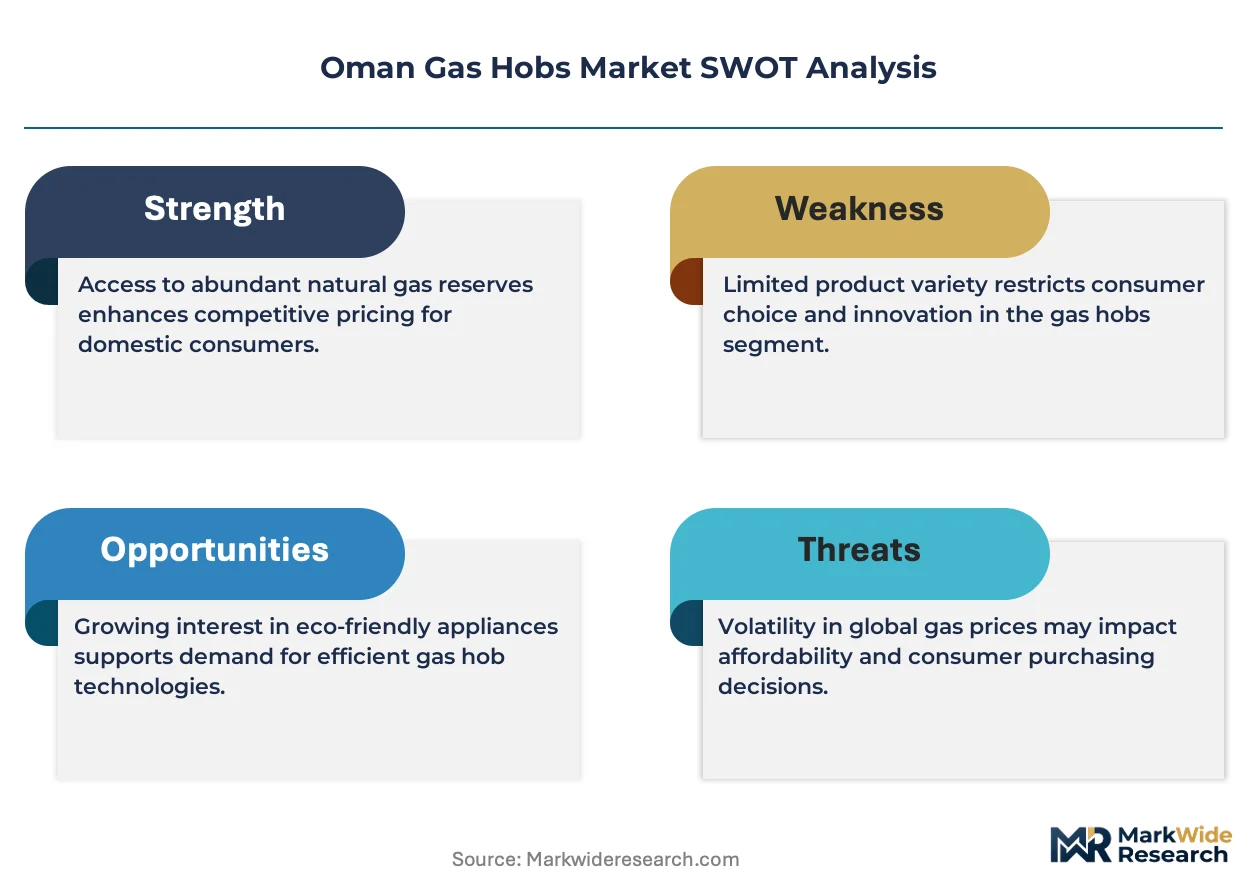
The Oman Gas Hobs Market functions as a stable compounder anchored by residential renovation momentum in Muscat and Salalah, where villa owners consistently prioritize modernized cooking infrastructure on compressed replacement timelines.
For Market Incumbents: Acquire certification expertise and laboratory partnerships to compress Omani Authority for Electricity Regulation approval timelines for new SKU introductions. Siemens and Bosch should deepen backward integration into digital ignition component supply to insulate against European single-source vulnerability, while reinforcing distributor exclusivity in Muscat's turnkey fit-out channel to lock out emerging Turkish entrants seeking hospitality procurement access. For New Entrants and Emerging Players: Launch via Salalah corridor distribution partnerships targeting Dhofar Governorate's underpenetrated residential compounds and tourism infrastructure. Mid-tier built-in hobs with localized LPG burner optimization present the most penetrable white space outside Muscat's saturated core, with procurement consolidation around kitchen integrators offering a direct go-to-market angle bypassing fragmented retail. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with pre-certified product portfolios and established Omani distributor relationships because certification backlogs at accredited laboratories create durable barriers against new market entrants. Target acquisition archetypes include Turkish mid-tier manufacturers with Marmara region production and existing GCC conformity assessment trails. The signal to watch is domestic content requirement announcements from Omani free zone authorities that would reward local kit-assembly operations.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Approval Investment | Accelerates Omani Authority for Electricity Regulation market entry against testing backlog constraints. |
| Touch Control Platform Integration | Aligns product specifications with Muscat villa developer smart home integration requirements. |
| Salalah Distribution Partnership | Captures Dhofar Governorate residential compound demand outside saturated Muscat core. |
| Local Assembly Free Zone Establishment | Positions for potential domestic content requirements reducing landed cost structures. |
| LPG Burner Localization Program | Optimizes combustion efficiency for standardized Omani household gas pressure specifications. |
Research Methodology
Bottom-up residential and hospitality procurement modeling reconciled against top-down manufacturing hub tracking forms the analytical core of this study. Primary interviews with kitchen integrators, appliance distributors, hotel procurement managers, and Omani Authority for Electricity Regulation compliance officers combined with secondary validation against customs records, SEC filings of listed appliance manufacturers, and hospitality project development databases. Triangulation across these sources ensures segmentation integrity across product type, material, control interface, and end-user dimensions.
Input-output matrices map burner configuration specifications, certification status, and regional demand intensity to generate volume and value outputs across the projection horizon. Segmentation dimensions modeled include installation type, surface material durability tier, control interface sophistication, and operational intensity by end-user category. CAGRs derive from replacement cycle compression analysis in Muscat and Salalah renovation markets, LPG infrastructure maturity trajectories, and hospitality project pipeline tracking across the Sultanate.
Several conditions sit outside the modeled scope, including specific Omani Authority for Electricity Regulation staffing levels at accredited laboratories, currency volatility magnitude in Euro-Rial and Yuan-Rial corridors, and induction technology cost reduction curves that could accelerate substitution beyond baseline assumptions. Forecasts reflect documented assumptions about renovation cycle continuity and hospitality project completion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Desktop Air Purifier Market
Household Items
Jet Hand Dryer Market
Household Items
US Flashlights Market
Household Items
Pocket Tissues Market
Household Items
Kitchen Towel Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Italy Digital Showers Market
Household Items
Remote Control Holder Market
Household Items
Electric Tealight Candles Market
Household Items
US Soap Dispenser Market
Household Items
Folded Tissues Market
Household Items
Non-Stick Cookware Market
Household Items
North America Water Purifier Market
Household Items
Electric Shoe Dryer Market
Household Items
Germany Induction Hobs Market
Household Items
MENA POU Water Purifiers Market