
 Neck Pillows Market | 2026-2036
Neck Pillows Market Size, Share, and Industry Trends Forecast 2026-2036
Neck Pillows Market Foresight
Asset-light licensing and private-label manufacturing partnerships is reconfiguring competitive entry in the neck pillows space, allowing digital-native brands to scale without captive production facilities. Cabeau leverages its specialty retail presence across major airports to sustain premium positioning in travel channels. Coop Sleep Goods anchors its growth through adjustable-fill memory foam designs that dominate the cervical therapy segment. Trtl differentiates via its patented wrap-around structural support system that occupies a distinct niche against traditional U-shaped competitors.
Neck pillows are ergonomic support devices engineered to maintain cervical spine alignment during rest, typically constructed from viscoelastic polyurethane foam, inflatable thermoplastic chambers, or gel-infused composites with densities ranging from 40D to 100D depending on therapeutic versus travel applications. Memory foam neck pillows command the dominant margin pool due to material cost premiums and clinical positioning for chronic pain management, while inflatable variants represent the fastest-growing travel subsegment driven by collapsible convenience and airline carry-on compliance. Distribution through online retail channels is accelerating as direct-to-consumer brands bypass wholesale markups and capture first-party data on sleep posture preferences.
The US Consumer Product Safety Commission enforces flammability standards under 16 CFR Part 1632 that govern foam-filled sleep accessories sold in domestic commerce, while the EU REACH regulation restricts hazardous substances in polyurethane formulations that enter European supply chains. The FDA classifies certain cervical pillows as Class I medical devices when marketed with specific therapeutic claims, creating a compliance threshold that shapes product labeling and channel access strategies. Stakeholders must monitor evolving chemical disclosure requirements across multiple jurisdictions and assess whether clinical certification investments justify premium positioning against commodity travel alternatives.
Market Dynamics
The EU REACH regulation on chemical safety in foam materials is forcing manufacturers toward certified memory foam formulations, while airlines expand amenity programs that embed ergonomic sleep accessories into premium cabin service tiers.
Growth Catalysts
- Aviation amenity expansion:Long-haul carriers are embedding neck pillows into premium cabin service tiers, creating institutional demand that bypasses individual consumer purchase cycles.
- REACH chemical compliance:The EU regulation restricts hazardous substances in polyurethane formulations, accelerating certified memory foam adoption across European supply chains.
- Chronic pain management positioning:Cervical therapy applications are driving clinical-grade memory foam demand from physical therapy channels and orthopedic recommendations.
Market Restraints
- Petrochemical input volatility:Viscoelastic polyurethane foam depends on crude oil derivatives, exposing margin structures to hydrocarbon price swings.
- Asian manufacturing concentration:Foam molding and compression facilities cluster in coastal Chinese provinces, creating single-source vulnerability for Western brands.
- Inflatable substitution threat:Collapsible thermoplastic alternatives satisfy airline carry-on compliance at lower price points, pressuring foam volume in travel segments.
Strategic Opportunities
- Direct-to-consumer channel expansion:Digital-native brands bypass wholesale markups through owned e-commerce platforms, capturing first-party data on sleep posture preferences.
- Airport retail network penetration:Duty-free and travel retail locations in Frankfurt, Dubai, and Singapore offer impulse purchase exposure to captive premium passengers.
- FDA Class I medical device certification:Therapeutic claim positioning unlocks reimbursement channels and clinical endorsement networks for cervical support products.
Industry Challenges
- Flammability testing timelines:US Consumer Product Safety Commission 16 CFR Part 1632 compliance requires extended laboratory certification cycles that delay product launches.
- Cross-border chemical disclosure fragmentation:Divergent substance reporting requirements between EU REACH, US EPA, and California Proposition 65 multiply compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neck Pillows Market |
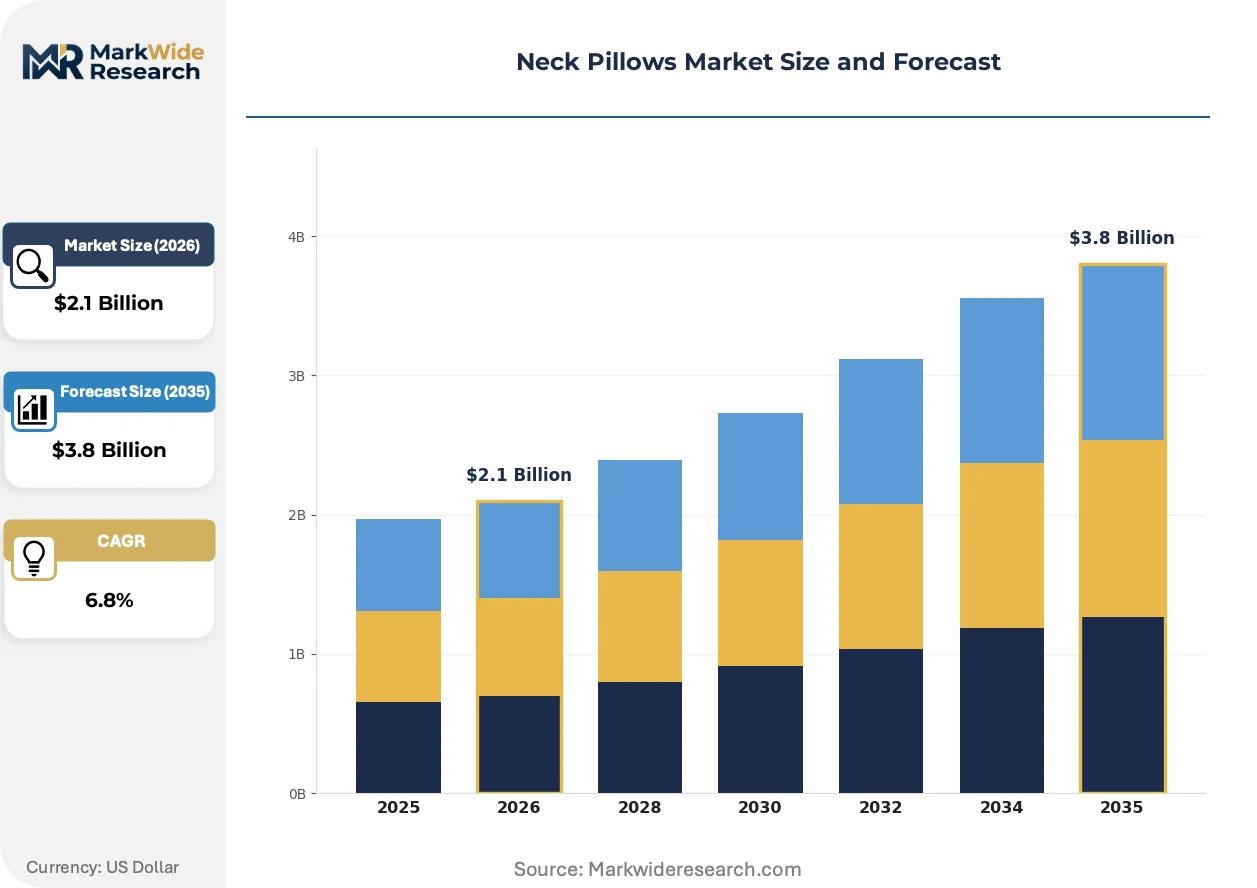
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Travel Neck Pillow, Cervical Neck Pillow, Inflatable Neck Pillow, Memory Foam Neck Pillow Material: Polyester, Cotton, Gel, Foam End User: Consumers, Office Workers, Travelers, Healthcare Providers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Warehouses |
| Companies Covered | Travelrest, J-Pillow, Cabeau, Huzi, Bcozzy, Coop Sleep Goods, Ostrichpillow, Cloudz, Trtl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neck Pillows Market Shifts & Advancements
Material science advances and regulatory chemistry standards are compressing traditional foam formulation cycles while digital distribution models disintermediate established wholesale networks.
Phase-change gel infusion is virtualizing thermal regulation in memory foam cores. Airlines operating ultra-long-haul routes from Doha to Auckland are specifying temperature-neutral cabin accessories for crew rest compartments. This material architecture is virtualizing the traditional trade-off between density comfort and breathability performance.
EU REACH Annex XVII restrictions on isocyanates in polyurethane production are forcing reformulation investments across foam suppliers serving European markets. Manufacturers must demonstrate substance safety through SCIP database registration, adding documentation overhead to each production batch. The clinical therapy segment faces the steepest compliance burden due to extended skin-contact duration claims.
Subscription-based pillow replacement programs are displacing one-time retail purchases in direct-to-consumer channels. Sleep wellness brands bundle cervical support products with posture-tracking apps, creating recurring revenue streams. This model concentrates in United States metropolitan markets where wellness expenditure per capita exceeds international benchmarks.
Neck Pillows Market Segmentation
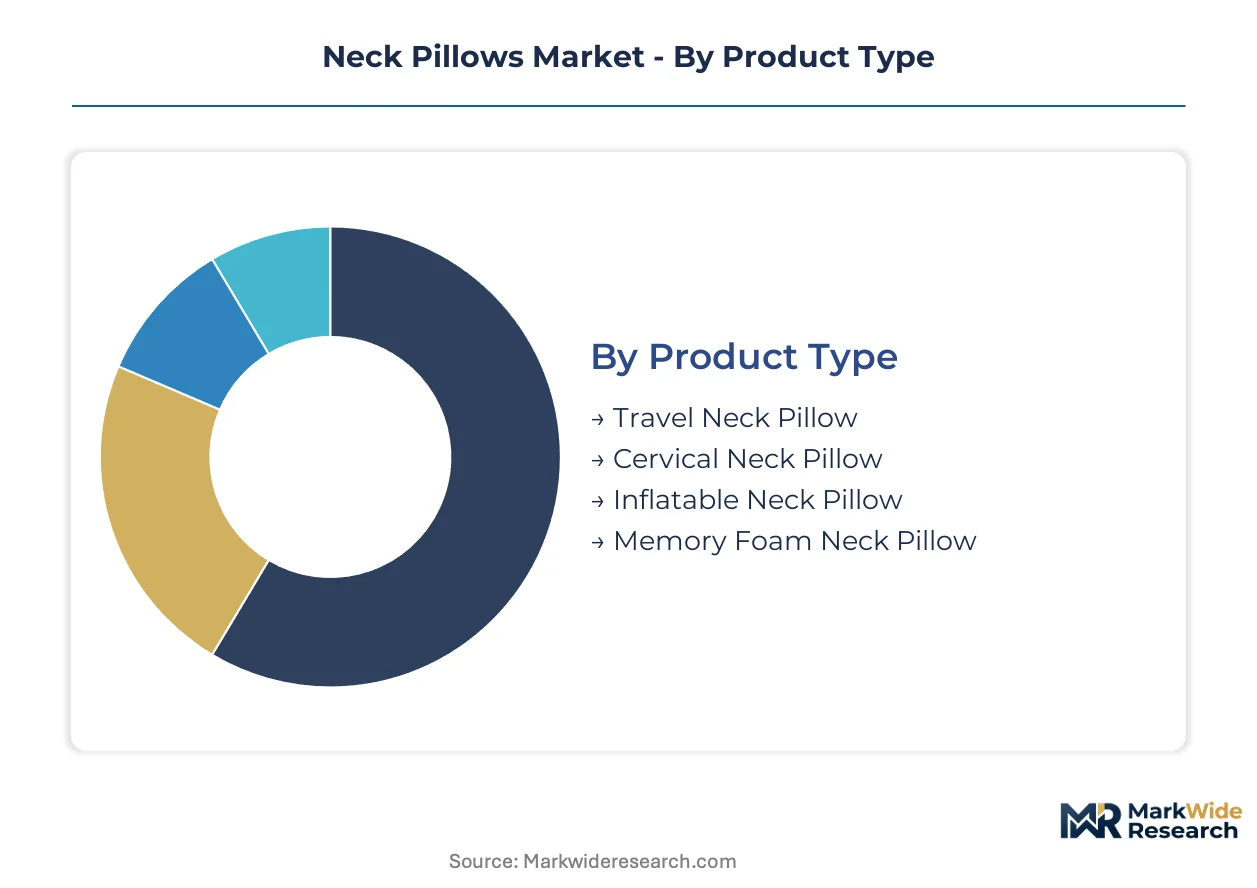
Segmentation in neck pillows reveals divergent replacement cycles and margin structures across use cases. Travel accessories turn over fastest through impulse purchases, while clinical-grade cervical products command extended lifecycles through therapeutic positioning.
Product Type:
Replacement velocity varies dramatically across categories, with travel-focused formats cycling through consumer hands within months while therapeutic designs persist for years.
- Travel Neck Pillow:U-shaped designs constructed from polyester fiberfill or microbead cores dominate airport retail and airline amenity programs. Demand concentrates among frequent flyers on trans-Pacific routes from Los Angeles and San Francisco, where carriers embed these accessories into premium cabin service tiers.
- Cervical Neck Pillow:Contoured foam architectures engineered for spinal alignment carry clinical positioning and extended replacement cycles. Physical therapy channels in Germany and the United States drive institutional procurement, with orthopedic recommendations sustaining premium pricing against commodity alternatives.
- Inflatable Neck Pillow:Thermoplastic chambers with adjustable firmness satisfy airline carry-on compliance at minimal packed volume.
- Memory Foam Neck Pillow:Viscoelastic polyurethane cores with densities from 40D to 100D deliver pressure-relieving support for chronic pain management.
Travel Neck Pillow anchors the volume base while Inflatable Neck Pillow gains share at the steepest rate through collapsible convenience.
Material:
Cost tier stratification separates commodity synthetics from premium formulations, with gel and high-density foam commanding manufacturing premiums that downstream pricing must recover.
- Polyester:Hollow-fiber synthetic fills dominate mass-market travel pillows through low unit economics and machine-washable durability. Asian contract manufacturers in Zhejiang province supply Western private-label brands, with cost concentration enabling aggressive retail pricing.
- Foam:Viscoelastic polyurethane formulations with open-cell structures dominate clinical and premium travel segments. EU REACH Annex XVII compliance on isocyanate content forces certified formulation investments across European supply chains, adding documentation overhead per production batch.
- Cotton:Natural fiber covers and fills appeal to sustainability-positioned brands seeking chemical-free positioning.
- Gel:Phase-change materials infused into memory foam cores deliver temperature-neutral sleep surfaces for ultra-long-haul aviation applications.
Foam anchors the volume base while Gel climbs the fastest through thermal regulation premiums in premium cabin specifications.
End User:
Customer type determines channel strategy and claim permissibility, with healthcare positioning unlocking reimbursement pathways unavailable to consumer marketers.
- Travelers:Individual purchasers and airline amenity programs drive impulse and institutional demand respectively. Dubai International and Singapore Changi airport retail networks capture premium passengers with limited purchase deliberation time.
- Healthcare Providers:Hospitals, physical therapy clinics, and chiropractic practices procure cervical support products with therapeutic claim requirements. FDA Class I medical device classification in the United States shapes labeling and channel access for this segment.
- Consumers:General household purchasers seek sleep comfort without clinical positioning.
- Office Workers:Ergonomic wellness programs at corporate campuses drive bulk procurement for workstation accessories.
Travelers anchors the volume base while Healthcare Providers expands most quickly through clinical endorsement networks and reimbursement channel development.
Distribution Channel:
Channel selection determines margin capture and data ownership, with direct models bypassing wholesale markups at the cost of customer acquisition investment.
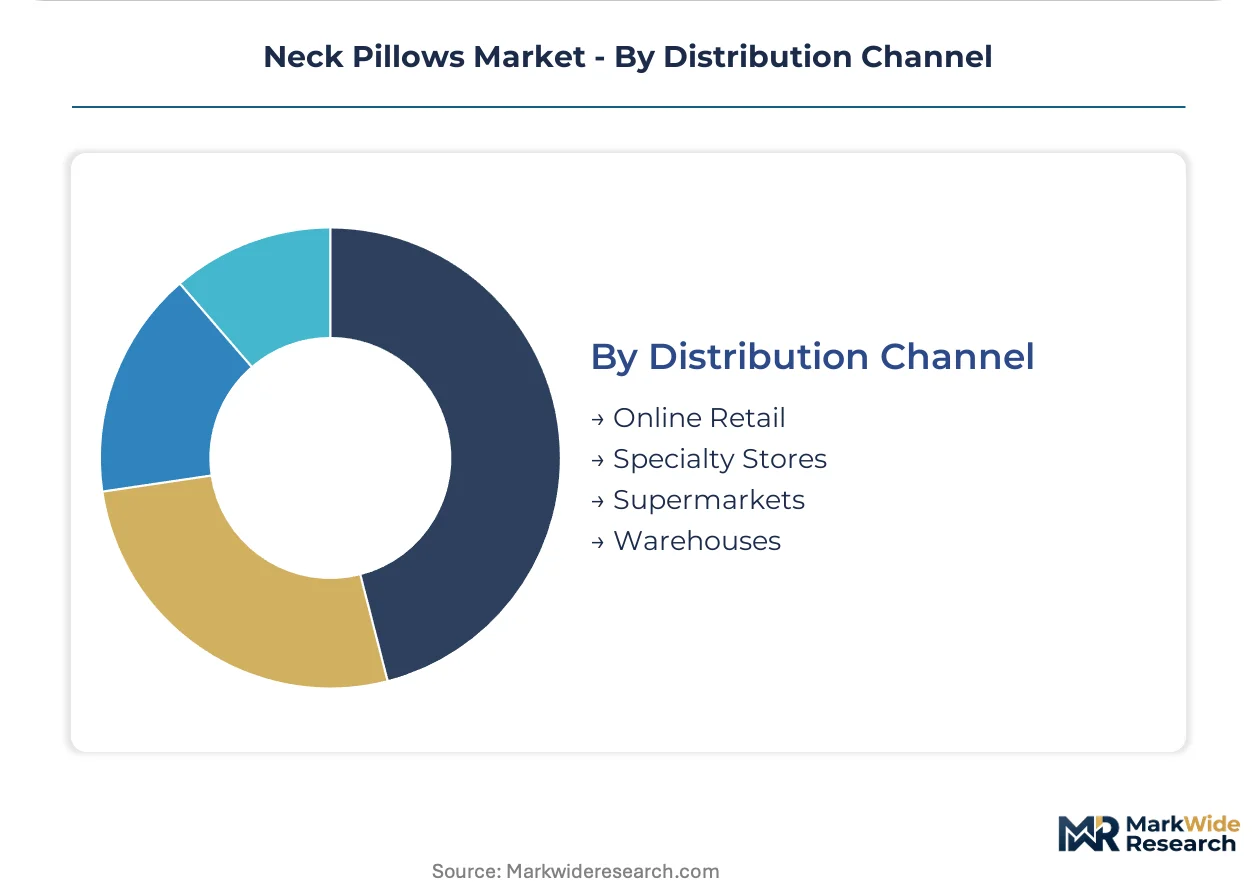
- Online Retail:Brand-owned e-commerce platforms and marketplace listings capture first-party data on sleep posture preferences. Direct-to-consumer brands in the United States metropolitan markets leverage subscription replacement programs to displace one-time purchases.
- Specialty Stores:Sleep wellness retailers and orthopedic supply outlets provide tactile evaluation and expert consultation. Airport travel retail locations in Frankfurt, Dubai, and Singapore offer impulse exposure to captive premium passengers with immediate departure timelines.
- Supermarkets:Mass-market retail chains move volume through low-price positioning and seasonal travel promotions.
- Warehouses:Club store formats drive bulk packaging and family multi-packs for cost-conscious household purchasers.
Online Retail anchors the volume base while Specialty Stores gains share fastest through airport network penetration and clinical channel partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for viscoelastic polyurethane foam concentrates Asian supply chains into coastal Chinese provinces, while Western markets exhibit trade deficits in finished cervical support products. Export-oriented manufacturers in Zhejiang and Guangdong supply North American and European distributors through private-label arrangements. Regional regulatory divergence on chemical disclosure is fragmenting procurement strategies across jurisdictions.
United States
Direct-to-consumer brands capture first-party data through subscription replacement programs in metropolitan wellness markets. The FDA Class I medical device classification governs therapeutic claim positioning for cervical support products entering clinical channels. Foam fabrication clusters concentrate in North Carolina and Ohio, where contract manufacturers serve private-label brands with REACH-compliant formulations.
Germany
Physical therapy clinics and orthopedic supply outlets drive institutional procurement of contoured cervical designs for spinal alignment applications. ECHA administers SCIP database registration requirements for isocyanate-containing polyurethane products under REACH Annex XVII restrictions. The Baden-Württemberg industrial corridor hosts specialty foam converters supplying medical-grade pillow cores to European healthcare networks.
China
Coastal manufacturing provinces dominate global foam molding capacity, with Zhejiang-based facilities producing compressed memory foam cores for Western travel brands. The Ministry of Ecology and Environment enforces dual carbon goals that constrain petrochemical-intensive polyurethane production. Guangdong province concentrates thermoplastic inflatable chamber fabrication for airline amenity programs serving trans-Pacific routes.
Japan
Corporate ergonomic wellness programs drive bulk procurement of workstation neck support accessories for office environments. METI oversees JIS standard compliance for sleep products marketed with posture-improvement claims. The Kansai region around Osaka maintains specialty textile processors supplying gel-infusion laminates for temperature-neutral pillow surfaces.
United Arab Emirates
Dubai International Airport retail networks capture impulse purchases from premium passengers with immediate departure timelines. MOHAP regulates product safety claims for sleep accessories distributed through Emirates airline amenity programs. The Jebel Ali free zone concentrates third-party logistics operations for Middle East and Africa distribution of travel neck pillows.
Neck Pillows Market Competitive Landscape
On the supply side, the industry is bifurcated between asset-light digital-native brands and vertically integrated foam fabricators with captive molding capacity. The vendor base separates into three strategic archetypes: airport retail specialists leveraging duty-free channel access, direct-to-consumer operators capturing subscription recurring revenue, and private-label manufacturers serving wholesale private-brand programs. Competitive moves concentrate on geographic licensing partnerships and certified formulation investments for REACH compliance.
Within the airport retail specialist tier, Cabeau and Cloudz exemplify channel-anchored positioning through major international hub penetration. Trtl occupies a distinct structural niche against traditional U-shaped competitors through patented wrap-around support architecture. Coop Sleep Goods represents the adjustable-fill memory foam archetype dominating cervical therapy positioning in physical therapy channels.
| Leading Market Players |
|---|
| Travelrest |
| J-Pillow |
| Cabeau |
| Huzi |
| Bcozzy |
| Coop Sleep Goods |
| Ostrichpillow |
| Cloudz |
| Trtl |
| Others |
Supply & Pricing Matrix
Trans-Pacific container freight corridors from Shanghai to Long Beach transmit petrochemical cost volatility directly into memory foam pricing tiers, compressing margins for uncertified producers while amplifying premium capture for REACH-compliant manufacturers serving European healthcare networks.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with FDA Class I certification and gel-infusion technology commanding 40-60% premiums over commodity polyester fills. Price differentiation rests on certification grade and volume scale, with airline amenity contracts leveraging 10,000-unit minimums to extract standard-tier pricing on clinically-positioned designs. Pricing pressure stems from inflatable thermoplastic substitution in travel segments, eroding foam volume at the economy tier. Leisure travelers exhibit highest price sensitivity through collapsible convenience preferences, while physical therapy clinics demonstrate lowest sensitivity due to reimbursement channel access.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now standard among Zhejiang foam converters signal working capital strain propagating upstream from Western private-label brands. Geographic supply concentration centers on China, Vietnam, and Germany, with viscoelastic polyurethane foam drawing from crude oil derivatives, isocyanate formulations, and phase-change gel laminates. Single-source vulnerability pervades coastal Chinese compression molding, where 70% of global memory foam core capacity resides within 200 kilometers of Ningbo port. Distribution runs through direct-to-consumer platforms, airport retail networks, and orthopedic supply channels in descending margin order.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation traffic recovery from trans-Pacific route suspension cyclicality positions the neck pillows market for sustained expansion, with premium cabin load factors serving as the lead indicator for institutional amenity demand.
For Market Incumbents: Entrench clinical channel relationships through FDA Class I certification maintenance and physical therapy network exclusivity arrangements. Counter inflatable substitution threat by embedding temperature-neutral gel technology into airline crew rest specifications. Deepen backward integration into REACH-compliant polyurethane formulation to defend margin position against petrochemical input volatility. For New Entrants and Emerging Players: Latin American airport retail networks present the most penetrable white-space target, with São Paulo-Guarulhos and Mexico City Benito Juárez offering underdeveloped duty-free sleep accessory categories. Target corporate ergonomic wellness programs in Japanese and South Korean office markets through posture-tracking app bundling. Pursue direct-to-consumer launch with subscription replacement models to bypass wholesale margin extraction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified consumer goods conglomerates with underperforming travel accessory divisions lacking digital-native capabilities. Five-to-ten year viability hinges on clinical certification asset durability and recurring revenue model adoption. Monitor EU SCIP database registration compliance rates as inflection indicator for formulation cost advantage consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Investment | ECHA SCIP registration unlocks European healthcare procurement channels against uncertified competitors. |
| Direct-to-Consumer Platform Launch | Owned e-commerce captures first-party sleep posture data for subscription replacement program optimization. |
| Airport Retail Network Expansion | Dubai International and Singapore Changi duty-free locations expose products to captive premium passengers. |
| FDA Class I Medical Device Certification | Therapeutic claim positioning enables reimbursement channel access and orthopedic endorsement networks. |
| Gel-Infusion Technology Integration | Phase-change materials satisfy ultra-long-haul airline crew rest specifications for temperature neutrality. |
Research Methodology
Desk research of customs trade databases, airline amenity procurement records, and orthopedic supply catalogs preceded structured interviews with foam manufacturing plant managers, airline procurement officers, physical therapy clinic directors, and airport retail category buyers. Primary fieldwork across Zhejiang province molding facilities and North Carolina foam fabrication clusters validated secondary estimates of capacity utilization and formulation cost structures. Bottom-up unit economics triangulated against top-down aviation passenger traffic projections.
Assumptions held fixed across the projection horizon include EU REACH Annex XVII enforcement intensity, FDA Class I classification criteria stability, and crude oil derivative pricing correlation with polyurethane foam input costs. The analytical framework modeled segmentation across product architecture, material formulation density, end-user type, and distribution channel complexity. CAGRs derived from replacement cycle velocity differentials between travel accessories and clinical-grade cervical designs, with aviation route expansion schedules and physical therapy referral pattern growth serving as volume scaling inputs.
Practitioners should monitor airline premium cabin retrofit announcements and EU ECHA substance restriction amendments for early signals of demand inflection or compliance cost escalation. Forecasts reflect documented assumptions regarding petrochemical input stability and trans-Pacific logistics capacity availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Cat Hair Remover Market
Household Items
Air Purifier Market
Household Items
Toilet Hygiene Products Market
Household Items
Automatic Dishwashing Products Market
Household Items
China Digital Showers Market
Household Items
Portable Iron Market
Household Items
Home Scales Market
Household Items
Coffin and Cremation Urn Market
Household Items
Mirror Holder Market
Household Items
Air Freshener Market
Household Items
Porcelain Tableware Market
Household Items
Smart Bathtub Market
Household Items
Washing Capsules Market
Household Items
Robotic Vacuum Cleaner Market
Household Items
Dishwashing Products Market
Household Items
Electric Clothes Drying Hanger Market