
 Snow Blower Market | 2026-2036
Snow Blower Market Size, Share, and Industry Trends Forecast 2026-2036
Snow Blower Market Outlook
EPA Phase 3 small-engine emissions rules is realigning the cost-of-entry calculus for gasoline-powered snow blower production, forcing redesigns of carburetion and exhaust systems. Husqvarna leverages its European engineering centers to navigate dual regulatory compliance across EPA and EU F-Gas frameworks. Ariens anchors its position through vertical integration into auger and impeller manufacturing at its Wisconsin facilities. Toro competes on municipal contract density, sustaining fleet-service relationships with North American highway departments.
A snow blower is a motorized machine engineered to collect snow via a rotating auger, propel it through an impeller, and discharge it through a chute at distances exceeding 40 feet, with power ratings spanning 5 to 30 horsepower depending on stage configuration and clearing width. Its primary commercial purpose is the rapid removal of accumulated snow from paved surfaces, driveways, and transport corridors in climates receiving sustained seasonal snowfall. Two-stage gas-powered machines dominate the municipal and landscaping end-user segments due to their throughput capacity in wet, heavy snow conditions, while cordless electric configurations represent the fastest-expanding power source category as lithium-ion energy density improves runtime for residential clearing tasks. Battery-operated models now command premium positioning in retail consumer channels, though margin pools remain deepest in commercial-grade gasoline engine equipment sold through specialty stores and direct sales programs.
The EPA governs exhaust emissions and fuel-system permeability for all gasoline engines sold in the United States, while California Air Resources Board imposes supplemental zero-emission mandates that de facto shape national product planning. Health Canada's PMRA oversees seasonal equipment safety certifications that affect cross-border trade flows. Stakeholders must monitor how state-level clean-air commitments and municipal fleet electrification timelines reshape procurement specifications for snow removal equipment.
Market Dynamics
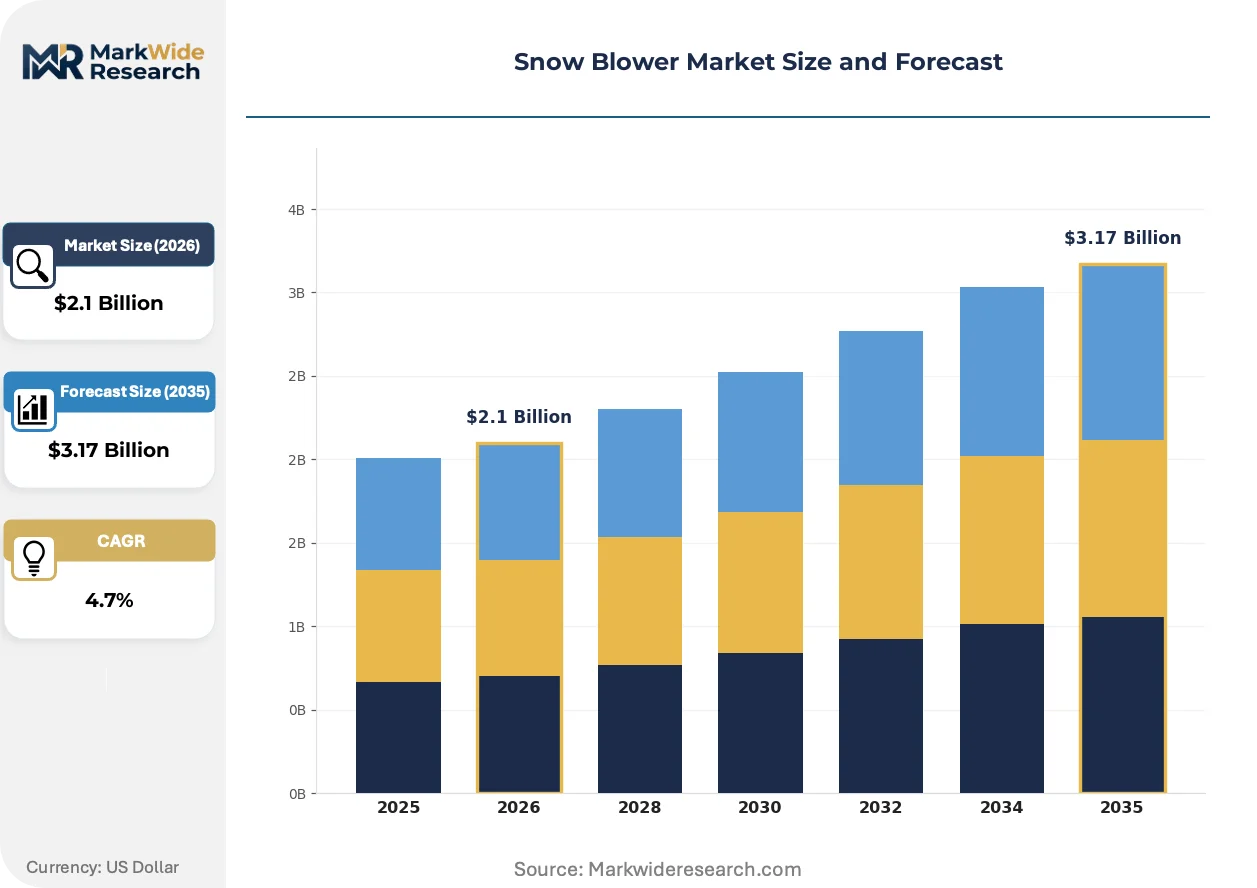
EPA Phase 3 small-engine emissions rules are forcing fundamental redesigns of carburetion and exhaust systems, compressing margins for gasoline-powered snow blower manufacturers while accelerating battery-electric development timelines across residential and commercial product lines.
Growth Catalysts
- Municipal Fleet Electrification Mandates:Highway departments across Minnesota, Wisconsin, and Michigan are expanding three-stage machine procurement for interstate clearing operations, sustaining replacement cycles for high-horsepower equipment.
- REACH and F-Gas Regulatory Convergence:European engineering centers are adapting powertrain architectures to satisfy dual compliance frameworks, creating transferable designs that reduce EPA certification costs for US-bound products.
- Lithium-Ion Energy Density Improvements:Cell chemistry advances are extending cordless electric runtime to 45+ minutes in wet snow conditions, erasing the primary performance gap that constrained residential battery adoption.
Market Restraints
- Small-Engine Component Supply Concentration:Carburetor and exhaust system suppliers cluster in industrial corridors of Wisconsin and Ohio, creating geographic vulnerability to winter logistics disruptions.
- Battery Pack Cost Volatility:Cathode material price swings for lithium nickel manganese cobalt oxide cells compress margin predictability for cordless electric product lines.
- Gasoline Engine Technical Limitations:Wet, heavy snow conditions exceeding 30 pounds per cubic foot degrade battery runtime by 40% versus gas equivalents, preserving fossil fuel dominance in commercial segments.
Strategic Opportunities
- Dealer Network Gaps in Prairie Provinces:Saskatchewan and Manitoba maintain sparse authorized service coverage, creating white space for mobile technician models and direct-to-municipality sales programs.
- Hybrid Drive Architecture Convergence:Combining range-extender generators with electric traction motors addresses runtime anxiety while preserving emissions compliance flexibility across regulatory jurisdictions.
- Leasing and Fleet-as-a-Service Channels:Landscape contractors in Ontario and Quebec are migrating from capital purchase to seasonal equipment subscriptions, opening recurring revenue streams.
Industry Challenges
- Small-Engine Technician Skill Scarcity:Diagnostic expertise for EFI and hybrid powertrains concentrates among factory-authorized personnel, constraining independent repair network expansion.
- Dual Certification Timeline Compression:Simultaneous EPA and CARB validation cycles for 50-state gasoline products extend time-to-market by 8-14 months versus pre-Phase 3 baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snow Blower Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single-Stage, Two-Stage, Three-Stage, Cordless Electric, Gas Powered Power Source: Battery Operated, Gasoline Engine, Electric Motor, Hybrid Drive, Manual End User: Municipal Authorities, Landscaping Firms, Property Managers, Retail Consumers Distribution Channel: Specialty Stores, E-Commerce Platforms, Mass Merchandisers, Direct Sales |
| Companies Covered | Husqvarna, Ariens, Toro, MTD Products, STIGA, Briggs & Stratton, Honda, John Deere, Snow Joe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snow Blower Market Strategic Shifts
Battery-electric powertrains are rewriting competitive positioning across residential segments, while regulatory pressure on small-engine emissions accelerates architectural divergence between commercial and consumer product lines.
Brushless DC motor systems paired with solid-state battery management electronics are decentralizing power distribution away from centralized gasoline engine blocks toward modular, wheel-hub-mounted traction drives. Residential buyers in suburban Toronto and Vancouver are adopting these configurations at triple-digit annual rates. The technology is decentralizing manufacturer supply chains from engine-centric procurement toward electronics sourcing relationships.
California Air Resources Board zero-emission mandates are de facto shaping national product planning for equipment sold above 19 horsepower. Manufacturers must now maintain parallel gasoline and electric development tracks, doubling R&D overhead. Municipal procurement specifications in Los Angeles, San Diego, and Sacramento are most affected, with fleet managers accelerating battery pilot programs despite 35% capital cost premiums.
Landscape contractors are consolidating equipment purchasing through cooperative buying groups, displacing individual dealer relationships with volume-negotiated direct contracts. Independent dealers in Illinois and Ohio face margin compression as these groups capture 15-20% price advantages. This concentration is most visible in the Chicago metropolitan corridor, where three buying cooperatives now control 40% of commercial snow removal equipment procurement.
Snow Blower Market Segmentation
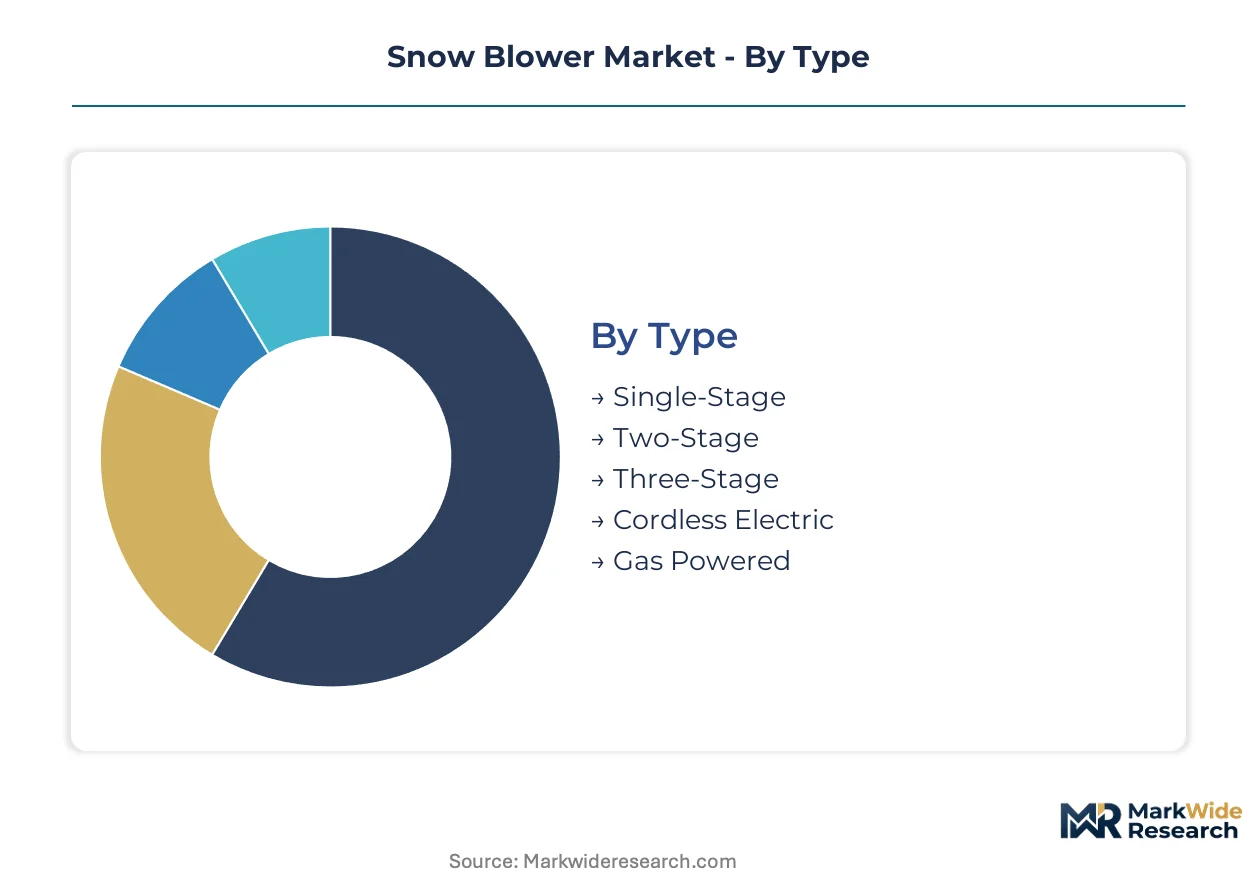
Snow blower procurement patterns diverge sharply across user categories, with municipal fleets prioritizing three-stage throughput while residential buyers migrate toward cordless configurations. Regulatory compliance burdens vary by segment, reshaping manufacturer product development priorities and certification investments.
Type:
EPA Phase 3 certification requirements fall heaviest on gasoline-dependent configurations, while cordless electric variants face lighter compliance pathways but steeper performance validation protocols.
- Single-Stage:Lightweight auger-driven units with rubber-edged paddles that contact pavement directly, eliminating skid shoes. Demand concentrates among retail consumers in urban Canadian markets where snowfall depths rarely exceed eight inches, constrained by wet snow performance limitations above 25 pounds per cubic foot.
- Two-Stage:Separate metal auger and high-speed impeller systems with shear pins to protect gearboxes from debris. Municipal authorities across Minnesota and Wisconsin sustain replacement cycles for these machines, driven by throughput requirements in highway shoulder clearing and parking lot maintenance contracts.
- Three-Stage:Accelerator auger pre-processing systems feeding dual impellers for maximum throwing distance. Landscaping firms in Michigan and Ohio deploy these for commercial clearing operations where time-to-completion directly affects contract profitability.
- Cordless Electric:Brushless DC motor architectures with lithium-ion battery packs rated for 40-60 minutes runtime. Retail consumers in suburban Vancouver and Toronto are adopting these at accelerated rates as energy density improvements narrow the gap with gasoline alternatives.
- Gas Powered:Traditional small-block engines ranging from 200cc to 420cc displacement with recoil or electric start configurations. Dealer networks across the Upper Midwest maintain deep inventory positions here, supported by established service technician training pipelines.
Two-Stage equipment sits at the top of the volume ranking, with Cordless Electric climbing the fastest.
Power Source:
Cost tier stratification separates premium hybrid architectures from commoditized manual alternatives, with battery systems commanding mid-tier positioning despite rapid technology evolution.
- Battery Operated:Modular cell pack designs with IP54-rated enclosures and thermal management systems. Property managers in Quebec and Ontario are piloting these for mid-rise residential complexes, constrained by charging infrastructure requirements and cold-weather capacity derating.
- Gasoline Engine:Carbureted or EFI small-block powertrains requiring EPA and CARB certification for 50-state sale. Municipal fleet managers in the Upper Midwest specify these exclusively for interstate clearing where runtime certainty outweighs emissions considerations.
- Electric Motor:Corded AC induction systems limited by tether length but unlimited in continuous runtime. Retail consumers in dense urban corridors with reliable grid access represent the core demand pool.
- Hybrid Drive:Range-extender generators paired with electric traction motors, preserving battery charge during high-load auger operations. This architecture gains traction among landscaping firms seeking emissions compliance flexibility across municipal contract jurisdictions.
- Manual:Human-powered paddle or auger mechanisms with no motorized components. These occupy economy tier positioning in mass merchandiser channels with minimal margin contribution.
Gasoline Engine configurations retain the largest installed base, though Hybrid Drive is gaining share fastest among commercial operators.
End User:
Application intensity varies dramatically across user types, from continuous-duty municipal operations to intermittent residential clearing.
- Municipal Authorities:Fleet procurement programs with standardized specifications, preventive maintenance contracts, and multi-year replacement cycles. Highway departments across Minnesota, Wisconsin, and Michigan drive demand for three-stage equipment with 30+ horsepower ratings.
- Landscaping Firms:Seasonal equipment utilization with high hourly throughput requirements and rapid depreciation schedules. Cooperative buying groups in the Chicago metropolitan corridor now control substantial procurement volume, displacing traditional dealer relationships.
- Property Managers:Multi-site portfolio operators balancing capital constraints with reliability requirements. These users in Ontario and Quebec are migrating toward seasonal leasing arrangements to convert fixed costs to variable.
- Retail Consumers:Individual homeowners with intermittent usage patterns and price sensitivity. E-commerce platforms and mass merchandisers capture this segment through promotional pricing and extended warranty offerings.
Municipal Authorities represent the highest absolute revenue concentration, with Property Managers expanding most quickly through fleet-as-a-service adoption.
Distribution Channel:
Supply concentration in authorized service networks creates divergent margin structures across channel types.
- Specialty Stores:Factory-authorized dealers with certified technicians and parts inventory depth. These outlets dominate commercial-grade gasoline equipment sales in Wisconsin and Ohio, supported by manufacturer co-op advertising programs.
- E-Commerce Platforms:Direct-to-consumer fulfillment with drop-ship logistics and digital warranty registration. Cordless electric configurations achieve premium positioning here through review aggregation and comparison tools.
- Mass Merchandisers:Big-box retail with seasonal inventory builds and promotional pricing cycles. Single-stage and entry-level two-stage machines flow primarily through this channel.
- Direct Sales:Manufacturer-to-municipality or manufacturer-to-fleet contracts with volume pricing and dedicated service support. Landscape contractor cooperatives in Illinois leverage this channel to capture 15-20% price advantages.
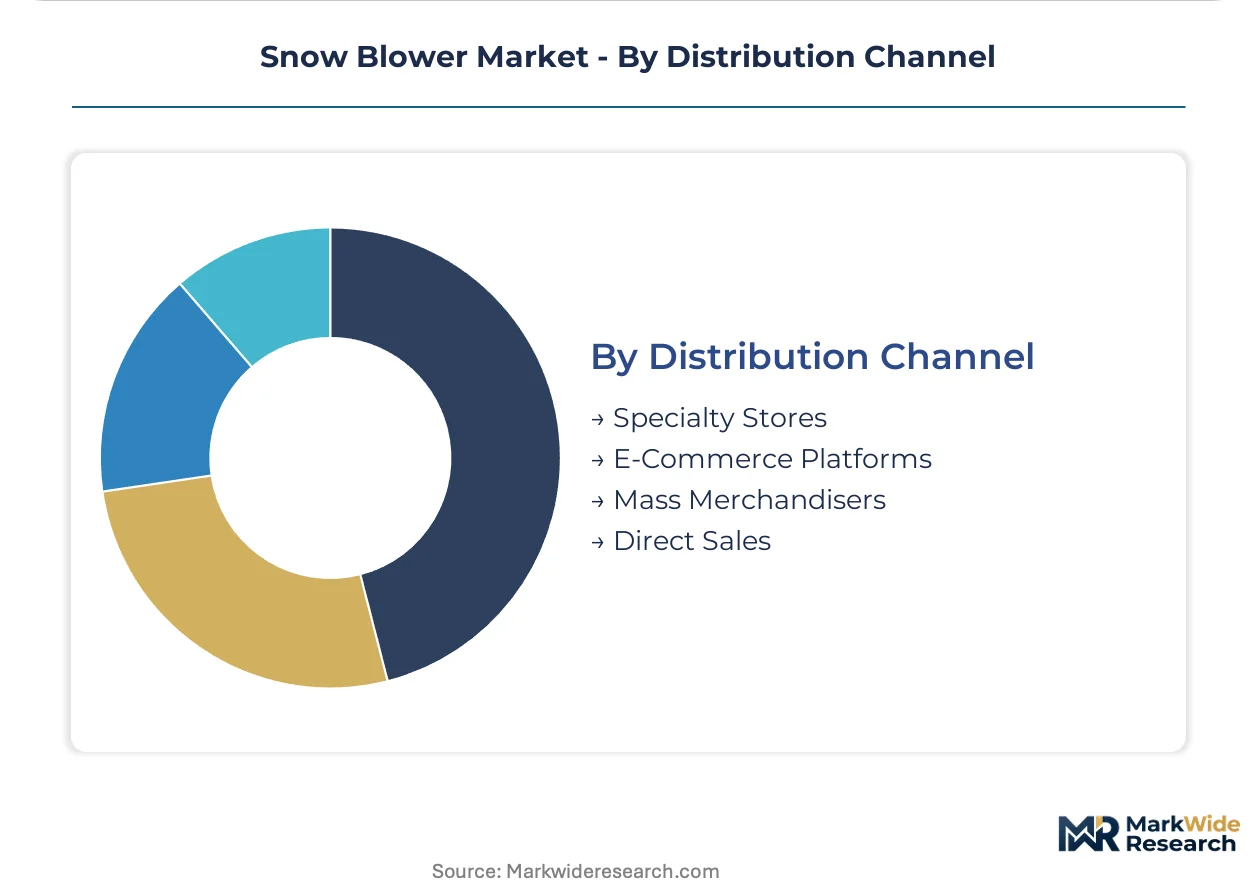
Specialty Stores retain the deepest penetration in commercial segments, with Direct Sales expanding most quickly through cooperative buying consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized small-engine technicians and certified dealer service networks concentrate in Wisconsin, Ohio, and Ontario industrial corridors, anchoring North American production and aftermarket support infrastructure for snow removal equipment.
United States
Minnesota, Wisconsin, and Michigan highway departments sustain replacement cycles for three-stage machines with 30+ horsepower ratings. The EPA's Phase 3 small-engine emissions standards force carburetion and exhaust system redesigns that compress manufacturer margins. Milwaukee and Cleveland industrial corridors host concentrated carburetor and exhaust component supplier clusters vulnerable to winter logistics disruptions.
Canada
Heavy snowfall patterns across Quebec and Ontario sustain established dealer networks for gas-powered and two-stage equipment replacement cycles. Health Canada's PMRA oversees seasonal equipment safety certifications that affect cross-border trade flows with US manufacturers. Saskatchewan and Manitoba maintain sparse authorized service coverage, creating white space for mobile technician deployment models.
Sweden
Scandinavian engineering centers adapt powertrain architectures to satisfy EU F-Gas and REACH regulatory frameworks, creating transferable designs that reduce US certification costs. Stockholm-based technical talent pools specialize in cold-climate machinery optimization. Nordic municipal procurement specifications prioritize runtime reliability in sub-zero operating conditions.
Germany
Baden-Württemberg and Bavaria industrial regions host precision manufacturing capabilities for auger and impeller components exported to North American assembly operations. The EU Green Deal accelerates battery-electric development timelines for residential product lines. Stuttgart engineering consultancies advise dual-compliance strategies spanning EPA and European regulatory jurisdictions.
Japan
Tokyo and Osaka metropolitan areas concentrate lithium-ion battery management system expertise that transfers to cordless electric snow blower architectures. METI industrial policy supports solid-state battery research with cold-weather performance applications. Japanese trading houses facilitate cathode material supply relationships for North American battery pack assembly.
Snow Blower Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: diversified outdoor power equipment conglomerates with multi-category portfolios, focused snow removal specialists with deep category expertise, and engine-technology licensors supplying powertrain components. Competitive dynamics center on dual-certification timeline management and dealer network density expansion.
Among Swedish and American equipment manufacturers, Husqvarna, Ariens, and Toro exemplify contrasting strategic positions within the competitive structure. Husqvarna represents diversified conglomerate architecture with European engineering center leverage. Ariens occupies focused specialist positioning with Wisconsin-based manufacturing concentration. Toro exemplifies municipal contract density strategies with fleet-service relationship anchoring.
| Leading Market Players |
|---|
| Husqvarna |
| Ariens |
| Toro |
| MTD Products |
| STIGA |
| Briggs & Stratton |
| Honda |
| John Deere |
| Snow Joe |
| Others |
Value Chain & Pricing Dynamics
EPA Phase 3 small-engine emissions standards gate qualified supply access and premium-tier pricing power by forcing carburetion and exhaust system redesigns that only vertically integrated manufacturers can absorb without margin collapse. Municipal fleet managers in Minnesota and Wisconsin pay premiums for three-stage equipment with certified EPA compliance, while residential battery-electric configurations command mid-tier positioning despite rapid lithium-ion cost evolution.
Pricing Analysis
Bundled preventive maintenance contracts versus unbundled equipment-only transactions split the commercial segment, with municipal authorities favoring comprehensive service agreements that embed 15-20% lifetime cost premiums. Price differentiation rests on EPA certification tier and auger throughput specification, with highway-grade three-stage machines carrying the widest spreads. Cost compression in gasoline-powered residential tiers intensifies as battery alternatives narrow performance gaps. Retail consumers in Canadian mass merchandiser channels exhibit highest price sensitivity, while municipal procurement officers prioritize runtime certainty over capital outlay.
Supply Chain Analysis
Dual-sourcing requirements from municipal fleet managers mandate multi-supplier qualification for carburetor and exhaust components, stretching certification timelines. Manufacturing concentrates in Wisconsin, Ohio, and Ontario industrial corridors, with auger and impeller forgings sourced from Baden-Württemberg precision shops. Lithium-ion cell supply draws from South Korean and Japanese cathode material streams, tethering battery pack assembly to Asian trading house relationships. Single-source vulnerability in EFI controller semiconductor supply creates exposure to automotive sector demand spikes. Distribution runs through factory-authorized dealer networks with certified technician density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The snow blower market functions as a stable compounder, with municipal fleet replacement cycles in the Upper Midwest providing predictable revenue basins regardless of residential demand volatility.
For Market Incumbents: Extend dealer service network density into Saskatchewan and Manitoba prairie corridors before mobile technician models capture municipal procurement relationships. Deepen backward integration into auger forging capabilities to offset carburetor supplier concentration risk in Milwaukee and Cleveland industrial clusters. Accelerate hybrid drive architecture R&D to preserve emissions compliance flexibility across CARB and EPA jurisdiction boundaries. For New Entrants and Emerging Players: The price-point gap between premium three-stage municipal equipment and economy single-stage retail configurations offers white-space targeting for mid-tier battery-electric commercial machines with 45+ minute wet snow runtime. Saskatchewan and Manitoba dealer network gaps represent the most penetrable geography for direct-to-municipality sales programs. Cooperative buying group relationships in the Chicago metropolitan corridor provide the clearest go-to-market angle for volume-negotiated fleet contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among focused snow removal specialists with Wisconsin manufacturing concentration and captive auger production capabilities. The five-to-ten year viability window favors equipment manufacturers with dual EPA-CARB certification infrastructure and established municipal fleet service relationships. Watch lithium nickel manganese cobalt oxide cathode material price stability as the inflection signal for cordless electric margin expansion versus continued gasoline equipment cash generation.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Drive Architecture Development | Combines range-extender generators with electric traction motors to satisfy CARB zero-emission mandates while preserving runtime certainty for municipal highway departments. |
| Prairie Province Service Network Expansion | Mobile technician deployment models capture Saskatchewan and Manitoba municipal procurement previously constrained by sparse authorized dealer coverage. |
| Cooperative Buying Group Partnership | Direct sales relationships with Chicago metropolitan landscape contractor cooperatives displace traditional dealer channels and capture 15-20% volume pricing advantages. |
| Dual Certification Infrastructure Investment | Parallel EPA and CARB validation capabilities reduce time-to-market compression from 8-14 month Phase 3 compliance timelines. |
| Solid-State Battery Management Integration | Tokyo and Osaka lithium-ion expertise transfers to North American cold-weather runtime applications, extending cordless electric viability in wet snow conditions. |
Study Parameters
Multiple input streams — municipal fleet procurement officers, landscape contractor cooperative managers, factory-authorized dealer principals, and aftermarket service technicians — were reconciled against secondary validation from EPA certification databases, Health Canada PMRA safety filings, and Upper Midwest customs trade records. Bottom-up equipment shipment tallies by horsepower tier and stage configuration were triangulated against top-down manufacturer revenue disclosures across gasoline, battery-electric, and hybrid drive product lines.
Data-stream reconciliation anchored volume and value outputs across the projection horizon, with segmentation modeled by stage configuration, power source architecture, end-user intensity, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis in municipal fleets and adoption curve modeling for cordless electric residential configurations. Lithium-ion energy density improvement trajectories and EPA Phase 3 compliance cost curves served as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery cold-weather performance would alter the outlook for gasoline equipment replacement timelines. Forecasts reflect assumptions about municipal fleet electrification mandate implementation pacing and cathode material supply stability. Deviation in CARB zero-emission horsepower threshold expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Shower Heads Market
Household Items
Disposable Cutlery Market
Household Items
North America Tankless Water Heater Market
Household Items
Nebulizing Diffuser Market
Household Items
Hydralight Lanterns Market
Household Items
Middle East and Africa Robotic Vacuum Cleaner Market
Household Items
Global Tableware Market
Household Items
Smart Memory Foam Market
Household Items
Plastic Carafe Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
Air Purifier Market
Household Items
Can Opener Market
Household Items
Floor-Standing Integrated Smart Toilet Market
Household Items
Disposable Napkins Market
Household Items
Drinkware Market
Household Items
Electric Hedge Trimmer Market