
 North America Diaper Market | 2026-2036
North America Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
North America Diaper Market Intelligence
Multi-source raw-material procurement is recalibrating how North American diaper manufacturers manage pulp and superabsorbent polymer costs. Procter & Gamble Co leverages its captive supply chains to insulate margin structures from volatile fluff pulp markets. Kimberly-Clark Corp anchors its competitive stance through R&D intensity in thinner-core technologies. First Quality competes aggressively on private-label manufacturing scale, supplying major retail banners across the United States and Canada.
A diaper is a multi-layer absorbent garment engineered with a topsheet of nonwoven polypropylene, an acquisition-distribution layer, a superabsorbent polymer core, and a breathable backsheet, manufactured through continuous web-forming and ultrasonic bonding processes to manage urinary and fecal incontinence across infant, juvenile, and adult populations. Disposable products dominate volume shipments and manufacturing asset utilization across the region, while biodegradable alternatives capture disproportionate attention from sustainability-focused investors despite higher unit economics. Adult end users represent the fastest-expanding demand pool as home-health and long-term care facilities expand absorbent-product budgets.
The U.S. Food and Drug Administration regulates medical-grade adult incontinence products as Class I devices, while the EPA oversees landfill-disposal pathways for post-consumer diaper waste; Health Canada imposes parallel absorbency-labeling standards that shape cross-border product harmonization. State-level extended producer responsibility frameworks in California and Maine are forcing reformulation timelines and recycling-infrastructure investments. Stakeholders must monitor how fragmented municipal composting capabilities constrain biodegradability claims and influence premium-tier pricing power.
Market Dynamics
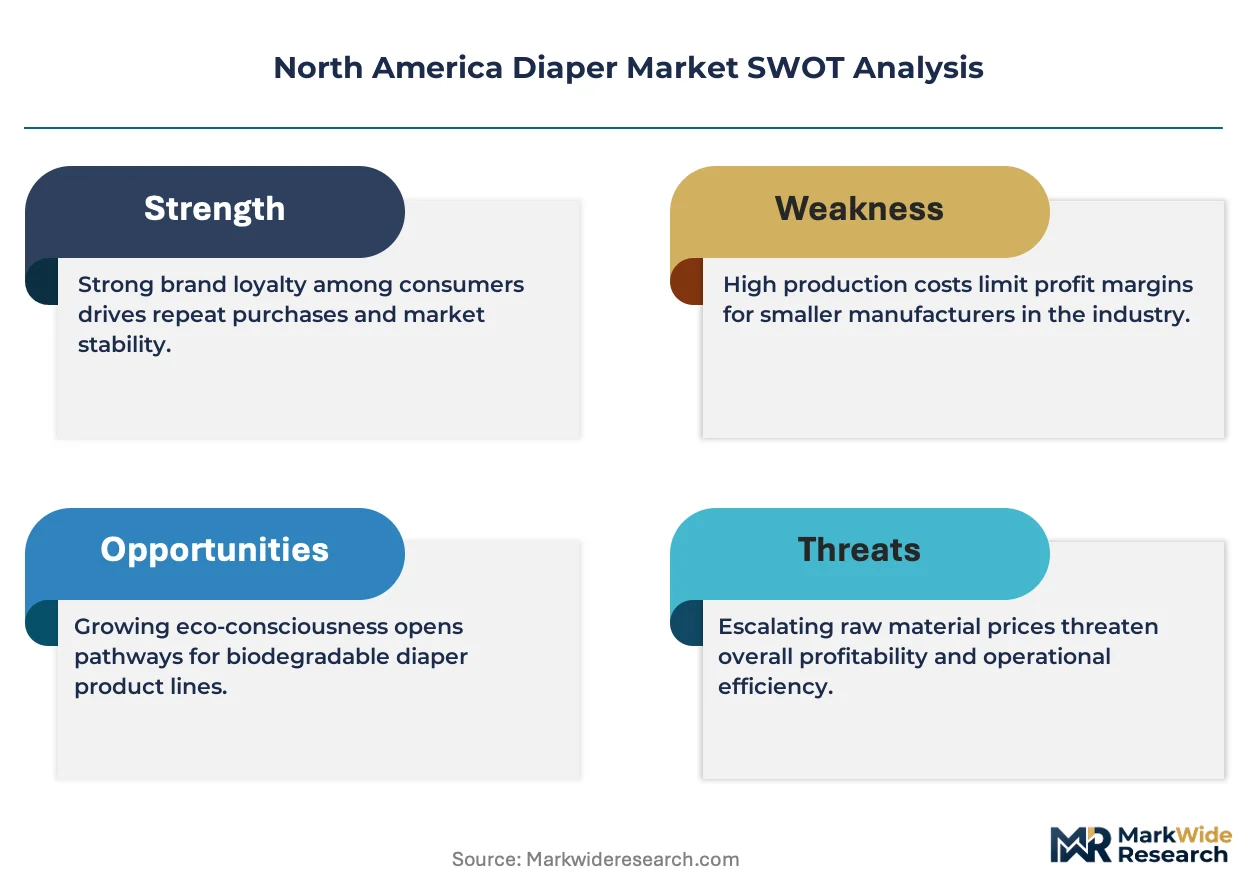
California's extended producer responsibility framework is forcing diaper manufacturers to internalize end-of-life costs, compressing margins for non-compliant suppliers while rewarding early movers in biodegradable core technologies. This regulatory pressure intersects with pulp supply volatility to reshape competitive positioning across the continent.
Growth Catalysts
- EPA landfill-diversion mandates:Federal solid-waste guidelines pressure manufacturers toward compostable backsheet materials, creating procurement pull from institutional healthcare buyers in the U.S. South.
- Home-health expansion:Skilled nursing facilities and Medicare-certified home agencies are absorbing adult brief volumes as hospital readmission penalties shift patient acuity downstream.
- Superabsorbent polymer innovation:Bio-based SAP derivatives from agricultural feedstocks reduce petrochemical dependency for manufacturers with captive R&D pipelines.
Market Restraints
- Fluff pulp concentration:Brazilian and Scandinavian pulp suppliers control critical input volumes, exposing margin structures to freight-rate spikes and currency swings.
- Biodegradability-performance tradeoff:Current compostable cores sacrifice overnight absorbency, limiting premium-tier pricing power against conventional polymer standards.
- Maine EPR compliance timelines:State-level producer-fee structures accelerate reformulation costs before municipal composting infrastructure reaches viable scale.
Strategic Opportunities
- Texas-Arizona corridor penetration:Sun Belt retirement migration outpaces national adult incontinence product availability, creating whitespace for regional distribution partnerships.
- Retail pharmacy channel integration:CVS and Walgreens clinic networks are embedding absorbent-product consultations into chronic-care workflows, opening direct-to-patient subscription models.
- Health Canada harmonization:Cross-border absorbency-labeling alignment reduces SKU complexity for manufacturers serving Ontario and Quebec markets from U.S. production assets.
Industry Challenges
- Composting-certification bottlenecks:ASTM D6400 and BPI verification timelines stretch 18-24 months, delaying market entry for reformulated products.
- Ultrasonic bonding technician scarcity:Continuous web-forming expertise concentrates among aging workforces in Wisconsin and Ohio manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Diaper Market |
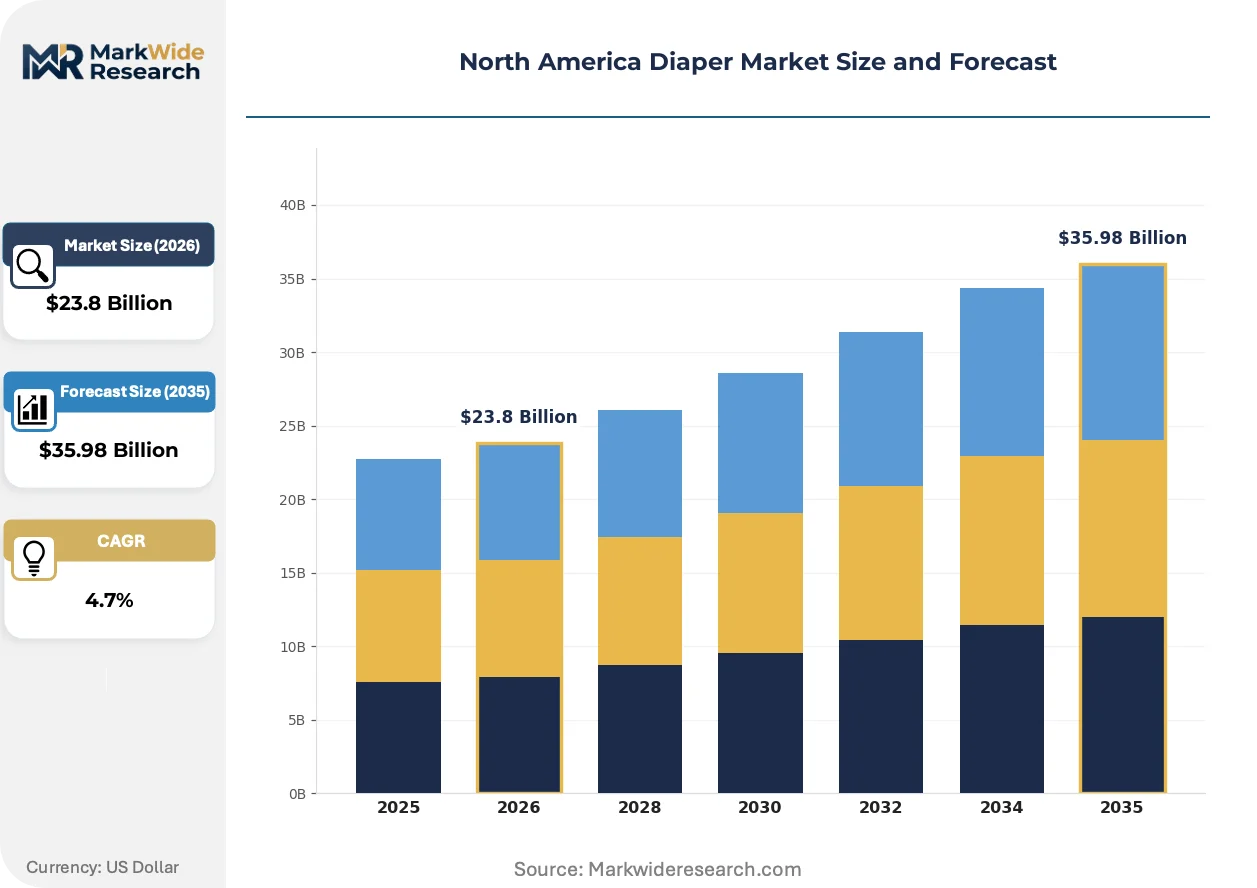
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $35.98 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cloth, Biodegradable, Training Pants End User: Infants, Toddlers, Adults, Care Facilities Distribution Channel: Online, Supermarkets, Convenience Stores, Pharmacies Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Procter & Gamble Co, Kimberly-Clark Corp, Johnson & Johnson, The Honest Co Inc, First Quality, Ontex Group NV, Essity AB, Domtar Corporation, Hengan International Group Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Diaper Market Strategic Shifts & Innovations
Absorbent-product engineering is pivoting from discrete performance metrics toward systems-level sustainability credentials, with material traceability and end-of-life verification becoming as consequential as leakage protection in buyer evaluation.
Plant-derived superabsorbent polymers derived from cornstarch and sugarcane bagasse are expanding into overnight adult brief segments previously reserved for petroleum-based acrylic acid derivatives. Long-term care procurement directors in Florida and Arizona are piloting these cores for resident populations with skin-sensitivity protocols. The technology is expanding into premium-tier SKUs as institutional buyers face Scope 3 emissions disclosure requirements.
California's SB 54 implementation rules are mandating 30% post-consumer recycled content in single-use packaging by 2030, with diaper backsheet films captured under the scope. Manufacturers with integrated film-extrusion capabilities are qualifying ocean-bound plastic feedstocks ahead of enforcement. The policy is reshaping supplier qualification criteria for private-label contracts with Kroger and Albertsons banners.
Subscription replenishment models through Amazon and Target Circle are displacing stock-up purchasing patterns among millennial parents in metropolitan Texas markets. Auto-replenishment algorithms tied to pediatrician visit schedules and diaper-bank eligibility portals are capturing loyalty through convenience lock-in. This channel migration is most visible in Dallas-Fort Worth and Houston, where same-day delivery density supports just-in-time inventory models.
North America Diaper Market Segmentation
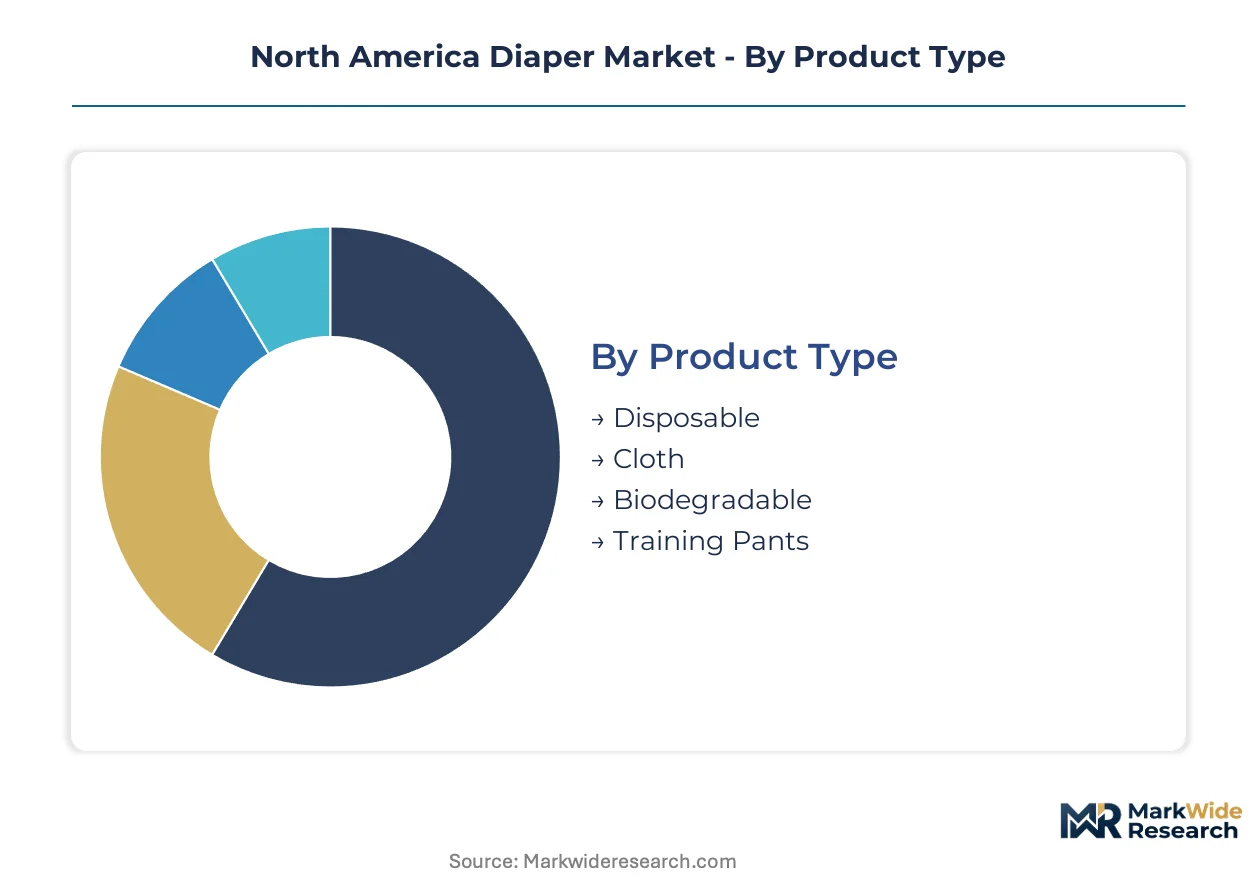
Diaper market segmentation reveals how absorbency engineering, procurement channels, and demographic targeting fragment manufacturing priorities across North America. Manufacturers must align core technologies with specific end-user physiology and institutional purchasing protocols.
Product Type:
Superabsorbent polymer chemistry and backsheet breathability define the technical axis separating volume leaders from emerging formats.
- Disposable:Multi-layer construction with polypropylene topsheets and SAP cores dominates hospital and home-health procurement. The U.S. South absorbs the highest institutional volumes as long-term care bed capacity expands across Florida and Texas.
- Cloth:Cotton terry and bamboo fiber inserts with polyurethane laminate covers serve sustainability-focused parents in Pacific Northwest urban markets. Seattle and Portland municipal composting infrastructure supports diaper-service subscription models unavailable in landfill-dependent regions.
- Biodegradable:PLA backsheet films and cornstarch-derived SAP from agricultural feedstocks.
- Training Pants:Elastic side panels and standing leg cuffs for toddler mobility.
Mature deployment sits with Disposable. Newer deployment is concentrated in Biodegradable.
End User:
Age-related continence requirements and care-setting acuity determine absorbency specifications and procurement cadence.
- Adults:Heavy-overnight briefs with odor-control additives and wetness indicators absorb the fastest volume expansion as Medicare-certified home agencies proliferate across Arizona retirement corridors. Phoenix and Tucson skilled-nursing discharges drive replenishment frequency exceeding infant segments.
- Infants:Newborn-size contoured cores with umbilical cord notches and umbilical cutouts dominate first-time parent purchasing in Dallas-Fort Worth and Houston metropolitan clusters. Hospital discharge gift packs anchor brand loyalty before retail conversion.
- Toddlers:Cruiser-stage elastic waistbands for crawling and walking mobility.
- Care Facilities:Bulk-packaged briefs with color-coded sizing for inventory management.
Volume concentration favors Infants. Steepest expansion trajectory belongs to Adults.
Distribution Channel:
Channel selection determines replenishment velocity, private-label exposure, and clinical consultation integration.
- Supermarkets:Kroger and Albertsons banners in California and Texas move economy and mid-range SKUs through high-velocity center-store placement. Slotting fee structures favor manufacturers with integrated film-extrusion capabilities qualifying for SB 54 recycled-content mandates.
- Online:Amazon Subscribe & Save and Target Circle algorithms tied to pediatrician schedules capture millennial parent loyalty in metropolitan Texas markets. Same-day delivery density in Dallas-Fort Worth enables just-in-time inventory models displacing stock-up purchasing.
- Pharmacies:CVS and Walgreens clinic networks embedding absorbent-product consultations into chronic-care workflows.
- Convenience Stores:Emergency replenishment of travel packs and single-count emergency SKUs.
Supermarkets anchor volume throughput. Online channels are gaining share fastest in suburban markets.
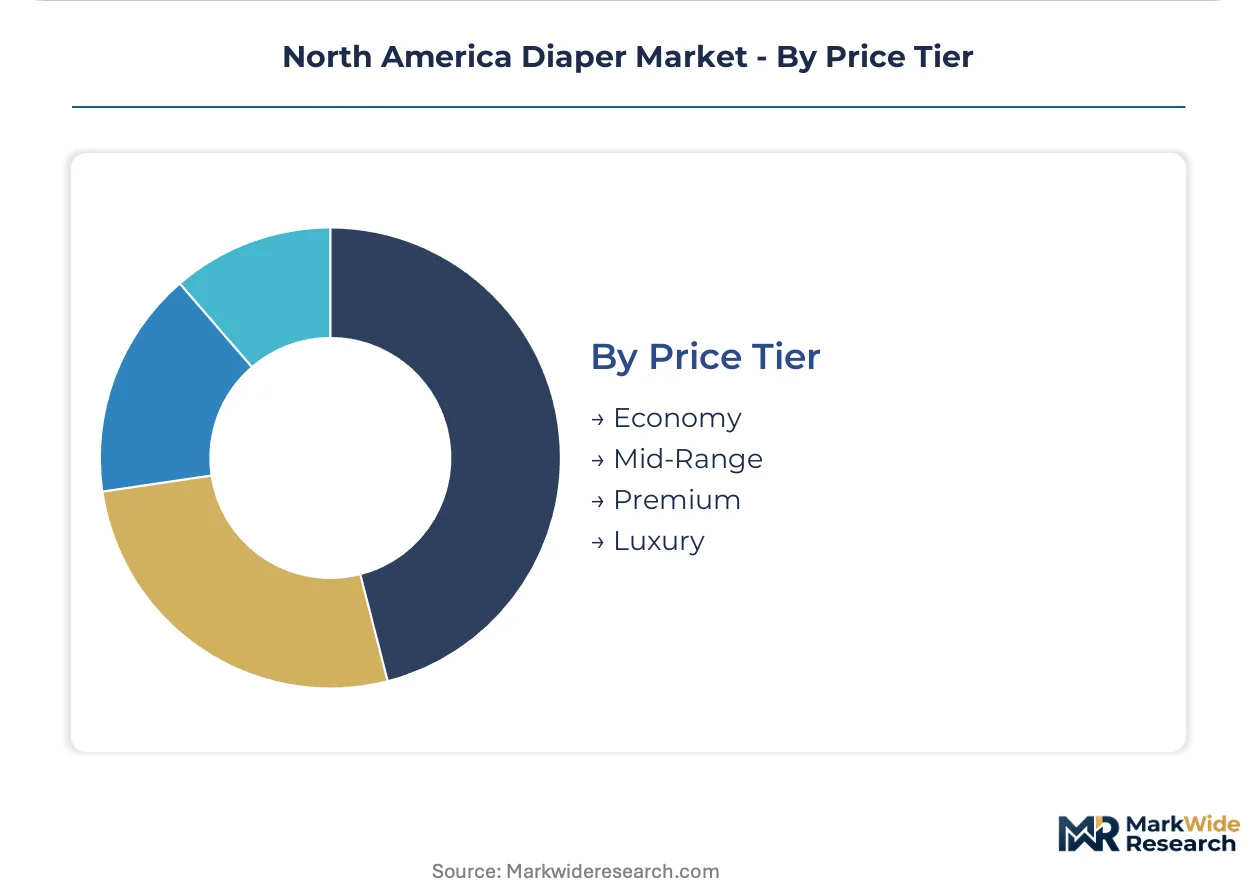
Price Tier:
Raw-material specification and certification overhead stratify margin structures across procurement segments.
- Premium:Bio-based SAP derivatives and breathable microporous backsheets with dermatological certification. Maine and California extended producer responsibility compliance costs push institutional buyers toward verifiable sustainability credentials despite unit price premiums.
- Economy:Petrochemical-based SAP and polyethylene backsheets with basic leakage protection. Price-sensitive procurement in budget-constrained care facilities across the U.S. Southwest absorbs volume despite thinner core construction.
- Mid-Range:Hybrid polymer cores with selective breathable zones.
- Luxury:Organic cotton linings and artisanal packaging for gift-market positioning.
Economy tiers dominate Medicaid-reimbursed procurement. Premium positioning is climbing fastest among private-pay home-health subscribers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian boreal forests and southeastern U.S. pine plantations anchor fluff pulp supply chains for North American diaper manufacturing. Regional demand concentrates where population aging intersects with young-family migration patterns.
United States
Florida and Texas absorb the fastest adult incontinence volume expansion as Medicare-certified home agencies proliferate across Sun Belt retirement corridors. EPA landfill-diversion mandates pressure manufacturers toward compostable backsheet materials. Wisconsin and Ohio manufacturing clusters face ultrasonic bonding technician scarcity as continuous web-forming expertise concentrates among aging workforces.
Canada
Ontario and Quebec markets drive cross-border absorbency-labeling harmonization with U.S. production assets. Health Canada standards shape product reformulation timelines for manufacturers serving Toronto and Montreal metropolitan areas. British Columbia municipal composting infrastructure supports diaper-service subscription models unavailable in landfill-dependent prairie provinces.
Mexico
Northern border states absorb maquiladora-scale production for U.S. private-label contracts. Mexican regulatory frameworks for absorbent products align with U.S. FDA Class I device classifications to facilitate cross-border trade. Mexico City metropolitan clusters concentrate distribution partnerships for economy-tier SKUs serving price-sensitive procurement.
North America Diaper Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers qualify bio-based superabsorbent polymer derivatives ahead of state-level extended producer responsibility deadlines. The vendor base stratifies across three tiers: multinational consumer goods conglomerates with captive R&D pipelines, private-label specialists supplying retail banners, and niche sustainability-focused entrants. Strategic archetypes include integrated pulp-to-product manufacturers, pure-play absorbent hygiene specialists, and agricultural-feedstock technology licensors. Competitive intensity centers on biodegradable core certification timelines and recycled-content packaging qualification.
Within the multinational tier, Procter & Gamble Co and Kimberly-Clark Corp exemplify scale-driven positioning through integrated supply chains and thinner-core R&D intensity. First Quality occupies a distinct archetype as a private-label manufacturing specialist supplying major retail banners. These three entities represent divergent strategic postures: captive raw-material procurement, technology-led product differentiation, and contract-manufacturing scale respectively.
| Leading Market Players |
|---|
| Procter & Gamble Co |
| Kimberly-Clark Corp |
| Johnson & Johnson |
| The Honest Co Inc |
| First Quality |
| Ontex Group NV |
| Essity AB |
| Domtar Corporation |
| Hengan International Group Co Ltd |
| Others |
Cost & Logistics Intelligence
Premium-economy bifurcation in North American diaper procurement separates institutional buyers demanding biodegradable certification from budget-constrained Medicaid programs tolerating petrochemical cores. This divergence manifests in parallel supply chain configurations: bio-based SAP manufacturers with captive agricultural feedstock contracts serve premium tiers, while commodity fluff pulp traders supply economy segments through spot-market purchasing.
Pricing Analysis
Service-bundling in the North America diaper market unbundles clinical consultation from product cost for pharmacy-channel subscribers while embedding auto-replenishment algorithms in online pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification overhead, with Maine and California EPR compliance fees compressing margins on non-compliant SKUs. Cost compression in economy tiers intensifies because Brazilian pulp suppliers control critical input volumes. Medicaid-reimbursed procurement exhibits highest price sensitivity; private-pay home-health subscribers demonstrate lowest sensitivity to unit premiums.
Supply Chain Analysis
Regional distribution centers in Wisconsin and Ohio manufacturing clusters anchor hub-and-spoke patterns serving Sun Belt demand corridors. Supply concentration rests on Brazilian and Scandinavian fluff pulp suppliers, with superabsorbent polymer feedstock dependency on petrochemical and emerging agricultural-starch alternatives. Single-source vulnerability concentrates in ultrasonic bonding technician expertise among aging workforces. Distribution runs through retail pharmacy networks and Amazon-Target subscription platforms for replenishment velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America diaper market sits in a technology-transition phase as cornstarch-derived superabsorbent polymers displace petroleum-based acrylic acid derivatives in overnight adult brief segments.
For Market Incumbents: Acquire captive bio-based SAP production capacity to insulate margin structures from pulp volatility. Secure ASTM D6400 and BPI certification pipelines ahead of California SB 54 enforcement timelines. Defend against private-label specialists by embedding thinner-core R&D into institutional procurement contracts with Florida and Arizona long-term care networks. For New Entrants and Emerging Players: California's SB 54 implementation rules in the United States open a window for compostable backsheet specialists to penetrate Kroger and Albertsons private-label contracts. Target the Texas-Arizona retirement corridor where Medicare-certified home agency expansion outpaces product availability. Pursue direct-to-patient subscription models through CVS and Walgreens clinic network integration. For Investors and Strategic Acquirers: Re-rating potential sits with integrated pulp-to-product manufacturers given EPA landfill-diversion mandate acceleration. Long-term viability favors entities with backward control over agricultural-feedstock supply chains and cross-border Health Canada harmonization capabilities. Monitor composting-certification bottleneck resolution as inflection indicator for biodegradable core market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based SAP Capacity Expansion | Cornstarch-derived polymer production reduces petrochemical dependency for overnight brief segments. |
| Composting Certification Investment | ASTM D6400 and BPI verification unlocks premium-tier pricing in California institutional procurement. |
| Pharmacy Channel Integration | CVS and Walgreens clinic networks embed absorbent-product consultations into chronic-care workflows. |
| Cross-Border Label Harmonization | Health Canada alignment reduces SKU complexity for Ontario and Quebec market service. |
| Subscription Platform Development | Amazon Subscribe & Save algorithms capture millennial parent loyalty in metropolitan Texas markets. |
Research Approach
SEC 10-K filings, Health Canada regulatory databases, and EPA solid-waste guideline documents formed the secondary backbone of this study. Primary interviews with long-term care procurement directors, retail pharmacy category managers, pulp supply chain planners, and biodegradable materials R&D heads combined with secondary validation. Bottom-up and top-down triangulation cross-referenced institutional purchasing volumes with manufacturing capacity disclosures.
Historical trendline analysis of adult incontinence product shipments and infant diaper replenishment patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, end-user age cohort, distribution channel, and price tier. CAGRs derived from volume trajectory analysis calibrated against fluff pulp cost pass-through elasticity and bio-based SAP adoption curves.
The model assumes a particular technology adoption path; alternative pathways for cornstarch-derived superabsorbent polymers would alter the outlook. Forecasts reflect assumptions about municipal composting infrastructure buildout and EPR compliance timeline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
United States Diaper Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Baby Diapers Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
Cat Diapers Market
Baby Diapers
Pet Diapers Market
Baby Diapers
Australia Pant Type Adult Diaper Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Malaysia Diapers Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
GCC Diaper Market
Baby Diapers
Diaper Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market