
 Asia Pacific Pet Diet Market | 2026-2036
Asia Pacific Pet Diet Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Pet Diet Market Insights
Urban millennial pet ownership is decoupling from traditional mass-market kibble purchasing across Asia Pacific metropolitan corridors. Mars Incorporated leverages its veterinary channel infrastructure to sustain premium positioning in Thailand and Indonesia. Nestle Purina PetCare anchors its regional supply chain through manufacturing scale in Australia and Japan. Unicharm Corp. dominates the cat diet segment in Northeast Asian convenience retail formats.
Asia Pacific Pet Diet comprises nutritionally formulated feed products for companion animals, typically manufactured through extrusion, retort processing, or cold-pressing methods to achieve specified protein, fat, and moisture parameters for species-specific metabolic requirements. Dry Food occupies the largest volume share due to shelf stability and cost efficiency in price-sensitive Southeast Asian markets. Functional ingredient formulations within the Ingredient Type dimension command disproportionate margin pools as pet owners in Japan and South Korea prioritize digestive health and senior animal therapeutics. Wet Food and Treats categories accelerate fastest among single-pet households in Chinese megacities where portion control and bonding rituals reshape consumption patterns.
Australia's Department of Agriculture enforces biosecurity-linked import standards that restrict certain protein sources, while Japan's MAFF feed safety regulations mandate contaminant testing protocols shaping formulation choices. China's National Feed Standard GB/T and India's FSSAI pet food guidelines create divergent compliance pathways that fragment cross-border product registration strategies. Stakeholders must monitor regulatory convergence pressures between ASEAN harmonization initiatives and national sovereignty over animal health protocols.
Market Dynamics
Japan's MAFF feed safety regulations are compressing formulation timelines across the Asia Pacific Pet Diet Market, forcing manufacturers to rebuild supply chains around certified ingredient sourcing while premium urban demand accelerates parallel to compliance costs.
Growth Catalysts
- Urban Millennial Pet Humanization:Single-pet households in Chinese megacities now prioritize functional nutrition formats, expanding the treat and supplement category faster than traditional kibble volumes.
- Veterinary Channel Infrastructure:Professional endorsement networks in Thailand and Indonesia sustain premium positioning by linking clinical nutrition credibility to retail conversion.
- MAFF Regulatory Harmonization:Japan's tightened contaminant testing protocols create competitive moats for compliant manufacturers while disqualifying informal import channels.
Market Restraints
- Protein Source Biosecurity Barriers:Australia's Department of Agriculture restricts certain animal protein imports, fragmenting regional sourcing strategies and elevating domestic ingredient costs.
- Divergent National Feed Standards:China's GB/T standards and India's FSSAI guidelines create non-overlapping compliance pathways that multiply product registration expenses.
- Price Sensitivity in Southeast Asia:Mass-market consumers in Indonesia and Vietnam resist premium pricing, capping margin expansion in the largest volume segment.
Strategic Opportunities
- Senior Animal Therapeutics:Aging pet populations in Japan and South Korea generate demand for digestive health and joint support formulations with veterinary-grade positioning.
- Convenience Retail Formats:Single-serve wet food and portion-controlled packaging penetrate Northeast Asian convenience store networks previously dominated by human snacks.
- ASEAN Harmonization Initiatives:Emerging regulatory convergence across Southeast Asia promises streamlined cross-border registration for first-mover manufacturers.
Industry Challenges
- Reformulation Expertise Scarcity:Contaminant testing protocols under Japan's MAFF framework require specialized analytical chemistry capabilities that outpace regional talent pipelines.
- Legacy Cold-Pressing Capacity:Existing extrusion-dominant facilities face retrofit costs to produce functional ingredient formats demanded by premium segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Pet Diet Market |
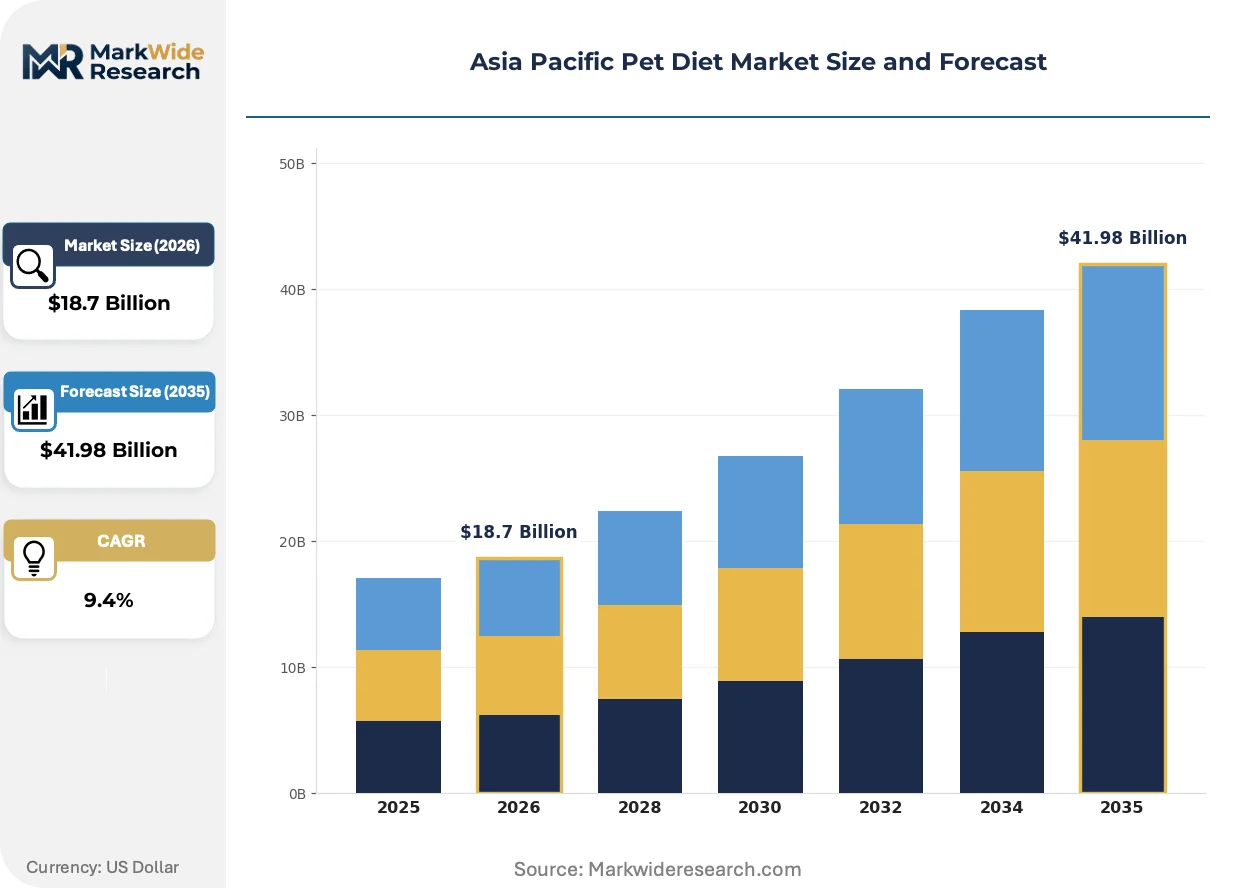
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Customer Type: Pet Owners, Veterinarians, Retailers, Distributors Ingredient Type: Meat-based, Grain-free, Organic, Functional Packaging Type: Bags, Cans, Pouches, Bulk Packaging |
| Companies Covered | Mars Incorporated, Nestle Purina PetCare, Colgate-Palmolive Company, General Mills Inc., Affinity Petcare SA, PLB International, Archer Daniels Midland, Unicharm Corp., Perfect Companion Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Pet Diet Market Trends and Innovations
Functional ingredient science and retail format innovation are redrawing competitive boundaries across the Asia Pacific Pet Diet Market, with regulatory compliance emerging as a technology differentiator rather than a cost center.
Cold-pressed manufacturing is integrating probiotic and prebiotic delivery systems that survive processing temperatures below 45°C. South Korean premium manufacturers are adopting these lines fastest, converting veterinary clinic endorsements into direct-to-consumer subscription models. This capability is integrating therapeutic nutrition claims into mass-market price points previously reserved for prescription diets.
Japan's MAFF feed regulation amendments now mandate batch-level contaminant documentation for all imported protein meals. Manufacturers serving the Japanese market must maintain dual supply chains: one for domestic-certified ingredients and another for export-destined production. Wet food and treat categories face the steepest compliance ramps due to higher moisture vulnerability to mycotoxin proliferation.
Single-pet household formation is compressing package size preferences toward 50-85 gram portions that mirror human snack rituals. Chinese tier-one city consumers now purchase pet treats through convenience store channels at frequencies matching coffee or confectionery. This rotation is most visible in Shanghai and Beijing, where premium treat penetration in 24-hour retail formats exceeds traditional pet specialty store growth rates.
Asia Pacific Pet Diet Market Segmentation
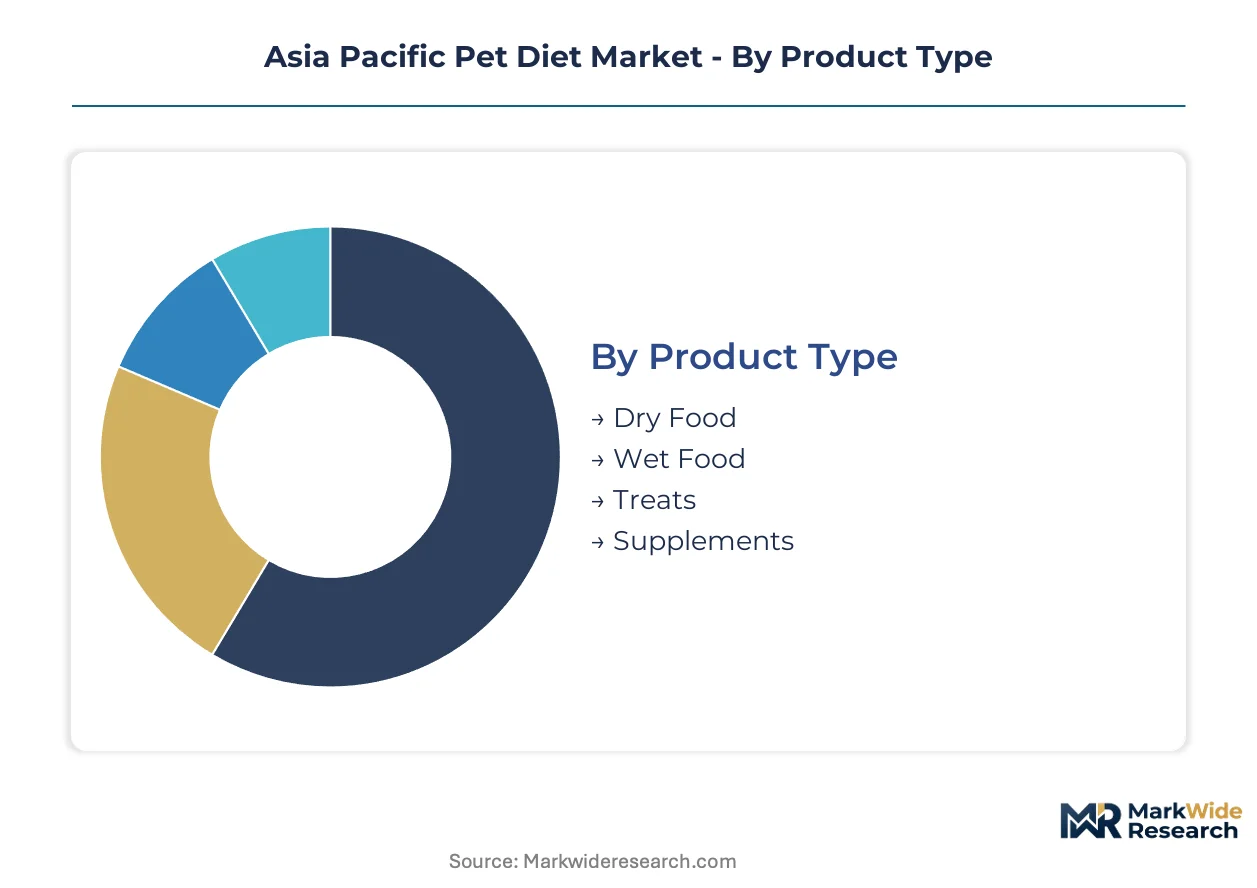
Segmentation in the Asia Pacific Pet Diet Market reveals divergent growth vectors between mass-market volume plays and premium margin extraction. Manufacturers must align production assets against distinct demand profiles across product formats, professional channels, and ingredient positioning tiers.
Product Type:
Dry Food operates as the standalone volume anchor across price-sensitive Southeast Asian markets, while Wet Food and Treats embed within premium household consumption rituals in Northeast Asian megacities.
- Dry Food:Extruded kibble formulations achieve shelf stability exceeding 18 months through moisture content below 10 percent. Demand concentrates in Indonesian and Vietnamese mass-market retail where cost-per-calorie dominates purchasing decisions.
- Wet Food:Retort-processed cans and pouches deliver moisture content above 75 percent for palatability-sensitive pets. Japanese and South Korean single-pet households drive category expansion through portion-controlled feeding rituals tied to humanization trends.
- Treats:Functional reward formats with dental or training claims penetrate Chinese tier-one city convenience channels at frequencies matching human snack purchases.
- Supplements:Joint support and digestive health formulations require veterinary endorsement in Japan's MAFF-regulated environment.
Volume placements concentrate in Dry Food; the faster expansion belongs to Treats.
Customer Type:
Channel selection determines margin capture, with professional gatekeepers extracting premium pricing power unavailable to mass retail intermediaries.
- Pet Owners:Direct purchasing through e-commerce platforms and convenience retail accelerates in Chinese megacities, bypassing traditional specialty store intermediaries.
- Veterinarians:Clinical endorsement networks in Thailand and Indonesia sustain premium positioning by linking therapeutic nutrition credibility to retail conversion.
- Retailers:Northeast Asian convenience store chains now allocate shelf space to single-serve pet formats previously reserved for human confectionery.
- Distributors:Cross-border logistics specialists navigate Australia's biosecurity-linked import standards and divergent national feed certification requirements.
Margin capture concentrates through Veterinarians; volume scale flows through Retailers.
Ingredient Type:
Cost tier stratification separates commodity protein formulations from certified functional inputs commanding disproportionate pricing power in aging pet demographics.
- Meat-based:Conventional poultry and fish meal formulations face sourcing constraints under Japan's MAFF contaminant testing mandates and Australia's restricted protein import protocols.
- Grain-free:Alternative carbohydrate sources from sweet potato and tapioca penetrate premium positioning in South Korean urban markets.
- Organic:Certified ingredient sourcing remains limited by regional agricultural certification infrastructure gaps.
- Functional:Probiotic, prebiotic, and joint support formulations command veterinary-grade pricing in Japan and South Korea's senior animal therapeutics segment.
Supply security challenges concentrate in Meat-based; the steepest margin expansion trajectory belongs to Functional.
Packaging Type:
Format selection aligns with distribution channel requirements and portion control preferences reshaping Northeast Asian consumption patterns.
- Bags:Multi-kilogram dry food packaging dominates warehouse club and e-commerce bulk purchasing in price-sensitive markets.
- Cans:Traditional wet food metal packaging retains veterinary channel preference for therapeutic diet credibility.
- Pouches:Flexible single-serve formats penetrate Chinese convenience retail with 50-85 gram portions matching human snack rituals.
- Bulk Packaging:Institutional and multi-pet household formats face limited penetration outside Australian and New Zealand commercial kennel operations.
Operational scale concentrates in Bags; the most rapid format innovation occurs in Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Australia's extrusion-dominant manufacturing base and Thailand's export-oriented processing zones, while consumption tilts toward Northeast Asian megacities where single-pet household formation outpaces supply chain localization.
China
Tier-one city consumers in Shanghai and Beijing drive treat and supplement category expansion through convenience store channels. The National Feed Standard GB/T mandates divergent compliance pathways for imported versus domestically manufactured products. Yangtze River Delta manufacturing clusters supply functional ingredient formulations to veterinary channels across East Asia.
Japan
Aging pet populations in Tokyo and Osaka generate demand for digestive health and joint support therapeutics. MAFF feed safety regulations mandate batch-level contaminant documentation for all imported protein meals. Kanto region manufacturers maintain dual supply chains separating domestic-certified from export-destined production.
South Korea
Urban millennial pet owners in Seoul prioritize functional nutrition formats with veterinary endorsement. The Ministry of Agriculture, Food and Rural Affairs enforces feed safety standards aligned with MAFF protocols. Seoul Capital Area cold-pressing facilities integrate probiotic delivery systems for subscription-based direct-to-consumer models.
Australia
Domestic ingredient costs elevate above regional benchmarks due to biosecurity-linked import restrictions on certain animal proteins. The Department of Agriculture enforces protein source barriers that fragment cross-border sourcing strategies. New South Wales and Victoria host extrusion-dominant manufacturing serving Southeast Asian export markets.
Thailand
Veterinary channel infrastructure in Bangkok sustains premium positioning through clinical nutrition credibility. The country's national feed regulator maintains alignment with emerging ASEAN harmonization initiatives. Central Plains manufacturing zones supply wet food and treat categories to Indonesian and Vietnamese markets.
Asia Pacific Pet Diet Market Competitive Landscape
Top-tier vendors anchor premium therapeutic nutrition, while mid-scale regional specialists occupy functional treat and convenience format tiers. Market structure tilts toward consolidation among multinational consumer goods conglomerates with veterinary channel infrastructure, alongside fragmentation among domestic cold-pressing specialists. Three archetypes dominate: multinational scale players with clinical endorsement networks, regional manufacturing specialists with biosecurity-compliant sourcing, and direct-to-consumer subscription operators with probiotic formulation capabilities. Competitive moves concentrate on portfolio diversification into senior animal therapeutics and strategic partnerships with convenience retail chains.
Among multinational scale players, Mars Incorporated and Nestle Purina PetCare exemplify the veterinary-channel archetype through clinical endorsement infrastructure. Unicharm Corp. occupies a position within the regional specialist tier, representing convenience retail format penetration in Northeast Asian markets.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestle Purina PetCare |
| Colgate-Palmolive Company |
| General Mills Inc. |
| Affinity Petcare SA |
| PLB International |
| Archer Daniels Midland |
| Unicharm Corp. |
| Perfect Companion Group |
| Others |
Pricing and Supply Chain Analysis
Urban millennial procurement of functional nutrition formats in Seoul and Shanghai is compressing lead times for cold-pressed probiotic formulations, forcing manufacturers to absorb expedited sourcing premiums or sacrifice shelf space to competitors with localized production.
Pricing Analysis
Short lead-time premiums dominate pricing architecture across Northeast Asian veterinary channels, where Japanese and South Korean clinics pay 15-25% markups for batch-certified MAFF-compliant inventory versus standard delivery windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and veterinary endorsement intensity. Cost compression in Southeast Asian mass-market dry food is intensifying because Indonesian and Vietnamese consumers resist per-kilogram price escalation above regional staple food benchmarks. Retailers extract the steepest price concessions, while veterinarians sustain premium capture through clinical credibility.
Supply Chain Analysis
Japan's MAFF domestic-content mandates for batch-level contaminant documentation are reshaping sourcing toward Australian and Thai certified protein suppliers, displacing informal import channels. Geographic supply concentration centers on Australia's extrusion-dominant manufacturing base, Thailand's export-oriented wet food processing zones, and South Korea's cold-pressing facilities. Raw material dependencies draw from certified poultry meals, sustainable fish proteins, and functional probiotic cultures. Single-source vulnerability concentrates in Japan's reliance on Australian biosecurity-compliant ingredient streams. Distribution runs through veterinary clinic networks in Bangkok and Jakarta, convenience retail chains in Chinese tier-one cities, and e-commerce platforms penetrating secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into certified ingredient sourcing and cold-pressing manufacturing capacity represents the decisive competitive race, with first movers securing MAFF-compliant supply security and veterinary channel lock-in across Northeast Asia.
For Market Incumbents: Cement premium positioning by acquiring cold-pressing manufacturing assets in the Seoul Capital Area, securing captive supply of probiotic cultures for functional formulations. Defend against direct-to-consumer subscription entrants by tightening veterinary clinic exclusivity arrangements in Thailand and Indonesia. MAFF regulatory escalation threatens margin structures for extrusion-dependent legacy facilities. For New Entrants and Emerging Players: Subscription-based direct-to-consumer platforms offer the lowest channel friction for penetrating South Korean urban millennial households with personalized senior animal therapeutics. Target white-space in Chinese tier-two city convenience retail, where pet treat penetration lags Shanghai and Beijing by 40-60 points. Bypass veterinary gatekeepers through influencer-driven functional nutrition education campaigns on Xiaohongshu and similar platforms. For Investors and Strategic Acquirers: The window for entry favors regional cold-pressing specialists with MAFF-aligned certification infrastructure and established probiotic formulation partnerships. Long-term viability hinges on 5-10 year regulatory convergence across ASEAN harmonization initiatives compressing compliance fragmentation. Watch for Japan's MAFF expanding contaminant testing mandates to wet food imports as the signal triggering accelerated consolidation among Thai and Indonesian manufacturers lacking analytical chemistry capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Protein Sourcing | Captures MAFF-compliant supply security for Japanese market access and veterinary channel credibility. |
| Cold-Pressing Manufacturing Scale-Up | Enables probiotic survival below 45°C processing temperatures demanded by South Korean premium segments. |
| Veterinary Channel Partnership Expansion | Links clinical nutrition endorsement to retail conversion in Thailand and Indonesia's fragmented retail landscape. |
| Convenience Retail Format Penetration | Secures 50-85 gram single-serve shelf space in Chinese 24-hour retail formats matching human snack rituals. |
| Direct-to-Consumer Subscription Launch | Converts Seoul millennial pet owners through personalized senior animal therapeutic nutrition delivery. |
Research Methodology
Document review covered customs and trade databases, national feed regulator filings from Japan's MAFF and Australia's Department of Agriculture, and industry association reports from ASEAN feed harmonization working groups, complemented by interviews with veterinary clinic procurement managers, pet food manufacturing plant directors, convenience retail category buyers, cold-pressing equipment specialists, and cross-border logistics operators. Secondary validation drew from GB/T standard documentation, FSSAI pet food guidelines, and extrusion processing technical literature. Bottom-up demand modeling triangulated against top-down production capacity assessments across Australian and Thai manufacturing clusters.
Segmentation outputs across product type, customer channel, ingredient positioning tier, and packaging format dimensions were projected across the analysis window using elasticity-adjusted volume trajectories and price-premium capture curves. CAGRs were derived from fitted growth curves incorporating urbanization rates, single-pet household formation indices, and regulatory compliance cost escalations. Industry-specific forecast inputs included MAFF amendment implementation timelines and ASEAN harmonization initiative progression milestones.
Inputs from veterinary channel stakeholders and manufacturing plant operators were available through the study window; gaps in real-time ASEAN regulatory convergence negotiations introduce uncertainty bands around cross-border registration streamline assumptions. Forecasts reflect documented assumptions regarding MAFF enforcement intensity and urban millennial pet humanization trajectory persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
South Korea Dog Food Market
Pet Care Products
US Dog Food Market
Pet Care Products
China Pet Clothing Market
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Dog Raincoats Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
North America Pet Food Market
Pet Care Products
GCC Dog Food Market
Pet Care Products
Spain Pet Food Market
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
Pet Clothing Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Global Kennel Software Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Saudi Arabia Pet Boarding Market