
 Gas Hobs Market | 2026-2036
Gas Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Hobs Market Foresight
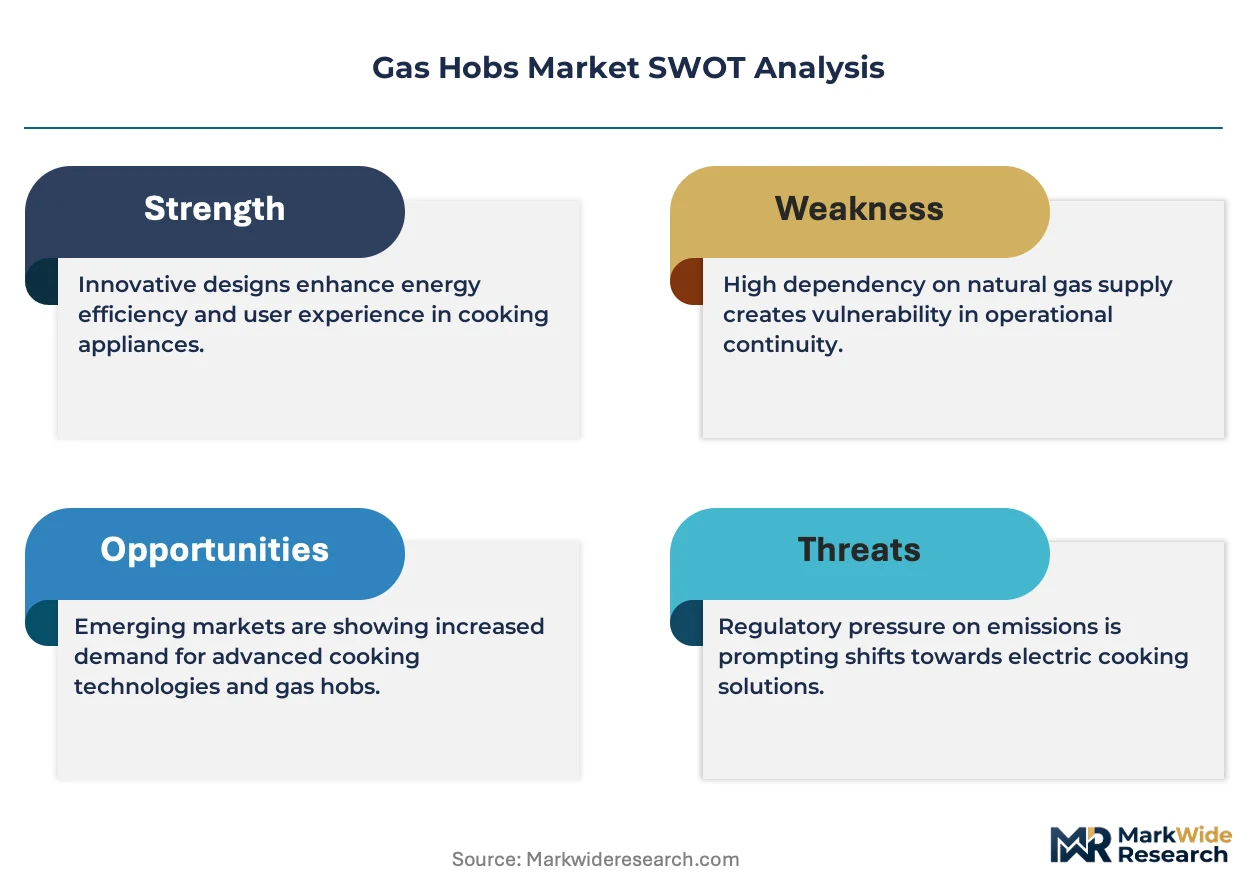
A capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is reorganizing competitive tiers in the gas hobs industry. Bosch leverages captive foundry capacity for cast-iron burner components to sustain margin stability across European supply chains. Whirlpool competes through modular platform architectures that anchor its North American aftermarket parts revenue. Miele specializes in precision-machined brass valve systems that differentiate its premium built-in portfolio.
Gas hobs are cooking appliances that mount on kitchen countertops or integrate into cabinetry, typically featuring sealed brass or aluminum burners with thermal outputs ranging from one to five kilowatts for domestic food preparation. Fabrication involves die-cast burner bodies, tempered glass or stainless-steel surface panels, and solenoid-actuated gas safety valves tested for flame-out cutoff within seconds. Built-in gas hobs dominate value capture in residential kitchens where renovation spending supports premium positioning, while modular gas hobs are gaining traction among food service operators seeking flexible kitchen layouts. Flame failure safety technology leads regulatory compliance investment as jurisdictions tighten automatic shutoff requirements.
The European Union's Gas Appliances Regulation and CE marking framework mandate flame supervision devices and combustion efficiency thresholds that shape product development budgets for export-oriented manufacturers. The U.S. Consumer Product Safety Commission and ANSI Z21.1 standards govern gas leakage and stability testing, creating divergent certification paths for cross-border suppliers. India's BIS certification and Petroleum and Natural Gas Regulatory Board pipeline codes are accelerating conversion from liquefied petroleum gas to piped natural gas compatibility in new product lines. Stakeholders must monitor municipal gas infrastructure rollout schedules and evolving safety standards to align regional product portfolios with enforcement timelines.
Market Dynamics
Flame failure safety mandates under the European Union's Gas Appliances Regulation are compressing product development cycles and forcing capital reallocation toward solenoid-actuated valve engineering and certification testing infrastructure.
Growth Catalysts
- CE marking flame supervision requirements:The EU Gas Appliances Regulation mandates automatic shutoff devices within seconds of flame-out, compelling manufacturers to redesign burner control systems and creating replacement demand for non-compliant legacy installations.
- Piped natural gas expansion in India:The Petroleum and Natural Gas Regulatory Board's pipeline codes are accelerating conversion from liquefied petroleum gas cylinders to piped natural gas compatibility in tier-two urban housing corridors.
- Southeast Asian kitchen renovation cycles:Residential remodeling in Vietnam, Thailand, and Indonesia is shortening replacement intervals for built-in gas hobs as middle-class households upgrade from freestanding cookers.
Market Restraints
- Brass valve component supply concentration:Precision-machined brass valve systems rely on foundry capacity concentrated in European and Chinese manufacturing clusters, exposing assemblers to input cost volatility and lead time extension.
- Induction cooktop substitution:Electric induction surfaces are capturing share in new European residential construction where building codes prioritize all-electric readiness and grid decarbonization incentives.
- Divergent certification path complexity:Separate ANSI Z21.1 testing for the U.S. market and BIS certification for India force dual-track product development, fragmenting engineering resources and extending time-to-revenue.
Strategic Opportunities
- Modular gas hobs for food service:Commercial kitchen operators in Singapore and Hong Kong are adopting flexible burner configurations that permit rapid layout reconfiguration without fixed cabinetry installation.
- India's tier-two city penetration:Municipal gas infrastructure rollout schedules in Surat, Kochi, and Coimbatore are creating first-mover advantages for manufacturers with localized piped natural gas-compatible product lines.
- Smart valve integration:Convergence of solenoid safety systems with IoT-enabled leak detection and remote shutoff is opening premium positioning in connected home ecosystems.
Industry Challenges
- Solenoid valve engineering talent scarcity:Specialized expertise in gas safety actuator design is concentrated among European and Japanese component suppliers, constraining in-house development timelines for assembly-dependent competitors.
- Flame failure device certification backlog:Third-party testing laboratory capacity for CE marking validation is creating queue delays that compress product launch windows and inventory planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Hobs Market |
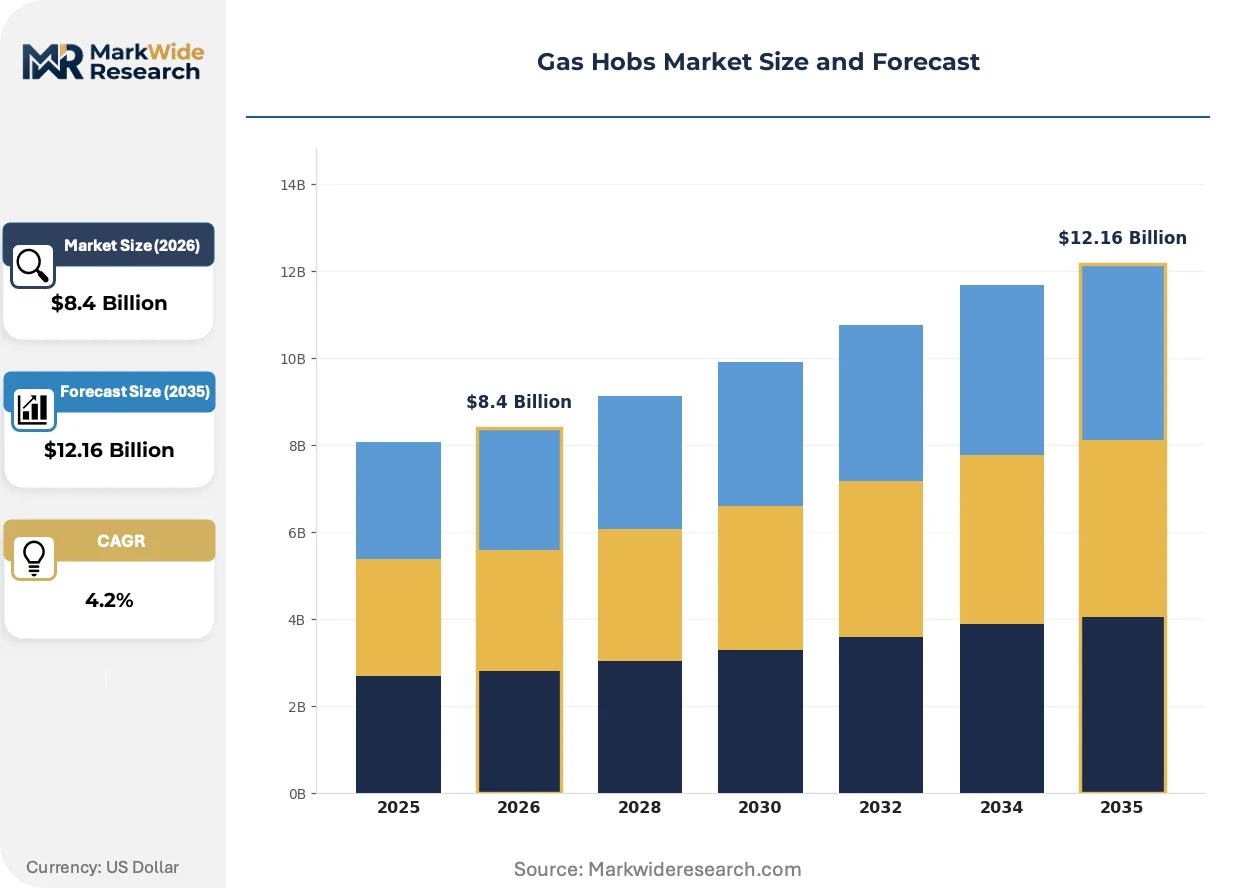
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-In Gas Hob, Freestanding Gas Hob, Modular Gas Hob, Portable Gas Burner Technology: Auto Ignition, Manual Ignition, Electric Ignition, Flame Failure Safety Application: Residential Kitchens, Commercial Catering, Institutional Cooking, Outdoor Cooking Customer Type: Households, Food Service Operators, Hospitality Establishments, Educational Institutions |
| Companies Covered | Bosch, Whirlpool, Electrolux, Samsung, LG Electronics, GE Appliances, Frigidaire, Miele, Faber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Hobs Market Shifts & Advancements
Tempered glass surface panels with integrated touch controls are displacing traditional knob-actuated interfaces as manufacturers respond to kitchen aesthetic standardization and simplified cleaning requirements.
Sealed brass burner assemblies with precision-machined flame ports are displacing die-cast aluminum alternatives in premium product tiers. High-end residential buyers in Germany and Switzerland are specifying these components for thermal consistency and extended service intervals. This material shift is compressing margin structures for manufacturers without captive foundry capacity or brass machining expertise.
The EU F-Gas Regulation's phase-down of fluorinated greenhouse gases is reshaping thermal insulation specifications for gas hob cavity components. Manufacturers must reformulate foam backing materials and retest thermal barrier performance, redirecting R&D expenditure toward compliant substrate alternatives. Built-in hob categories with integrated ovens face the steepest compliance cost escalation.
Direct-to-contractor distribution is eroding traditional kitchen retail channel dominance in India's metropolitan markets. Builders and interior designers in Mumbai and Bangalore are consolidating specification authority, displacing showroom-based consumer decision-making. This channel compression is forcing manufacturers to reconfigure sales force deployment and technical support resources toward project-based accounts.
Gas Hobs Market Segmentation
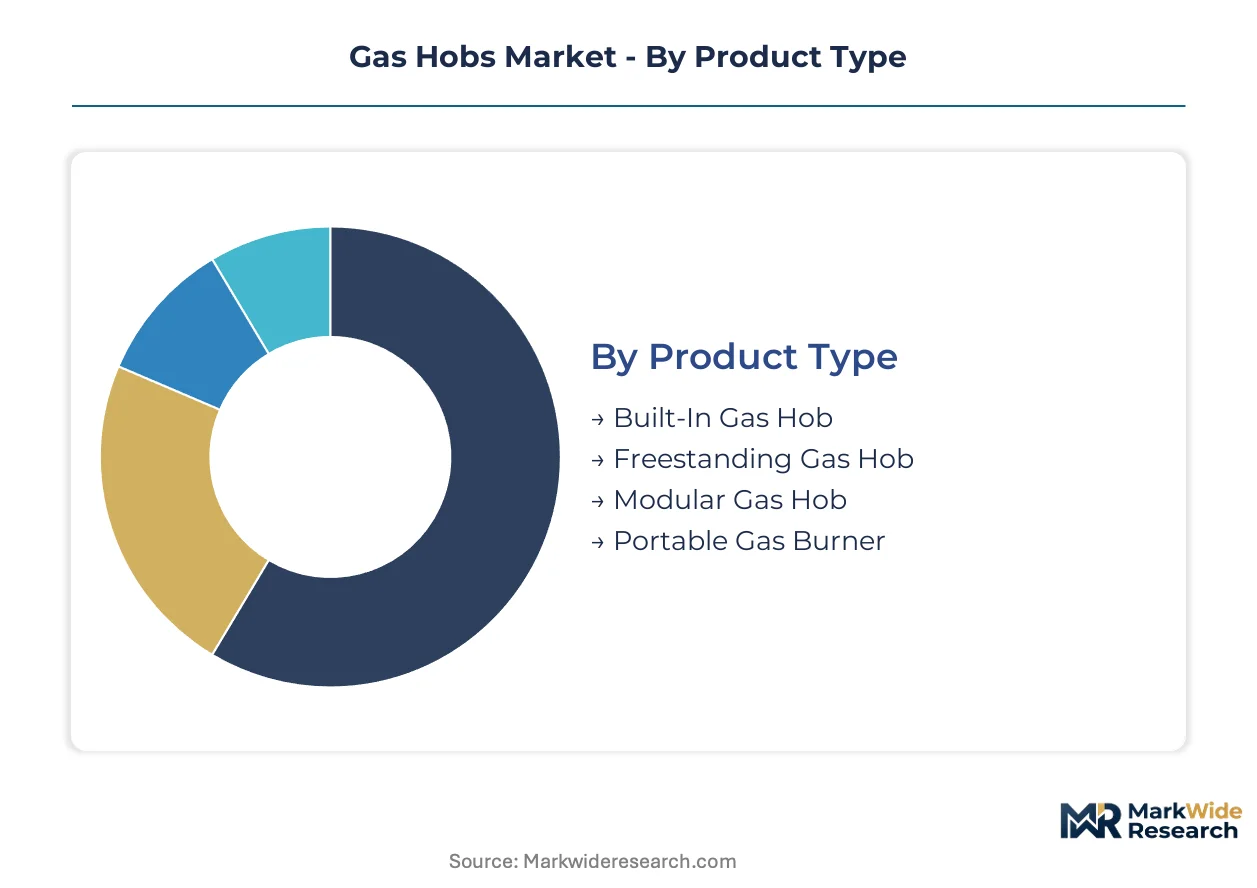
Gas hobs manufacturers configure product portfolios across four intersecting dimensions that determine pricing power, certification burden, and channel access. Each segmentation axis carries distinct margin profiles and competitive dynamics that shape resource allocation decisions.
Product Type:
Margin concentration pools in built-in configurations where kitchen renovation spending supports premium positioning and replacement cycle acceleration.
- Built-In Gas Hob:These units integrate into kitchen cabinetry with sealed burner assemblies and tempered glass or stainless-steel surfaces. Residential kitchen renovations across Vietnam, Thailand, and Indonesia are shortening replacement intervals as middle-class households upgrade from freestanding alternatives.
- Freestanding Gas Hob:Self-contained units with integrated oven compartments dominate entry-level residential penetration. India's tier-two urban housing corridors favor these configurations where piped natural gas infrastructure remains under deployment.
- Modular Gas Hob:Flexible burner configurations permit rapid kitchen layout reconfiguration without fixed cabinetry installation. Food service operators in Singapore and Hong Kong are adopting these systems for commercial flexibility.
- Portable Gas Burner:Compact single-burner units for outdoor or emergency use carry lower certification requirements and minimal safety feature integration.
The dominant share belongs to Built-In Gas Hob, while Modular Gas Hob is closing the gap fastest.
Technology:
Engineering investment intensity clusters around safety-actuated systems where regulatory mandates are compressing development timelines.
- Flame Failure Safety:Solenoid-actuated valves achieve automatic gas shutoff within seconds of flame-out detection. The European Union's Gas Appliances Regulation mandates these devices, compelling manufacturers to redesign burner control systems and creating replacement demand for non-compliant legacy installations.
- Auto Ignition:Piezoelectric or battery-powered spark generation eliminates manual lighting. Residential kitchens in Germany and Switzerland specify these systems for convenience and safety integration.
- Electric Ignition:Mains-powered spark modules require electrical connection infrastructure. This technology concentrates in new European residential construction where building codes prioritize all-electric readiness.
- Manual Ignition:Basic match or lighter-dependent systems persist in price-sensitive segments and emerging markets with limited electrical infrastructure.
Flame Failure Safety commands the technology investment budget, with Auto Ignition expanding most quickly through premium residential specifications.
Application:
Volume concentration sits in residential installations, though commercial catering carries higher per-unit margins and shorter replacement cycles.
- Residential Kitchens:Domestic food preparation environments with thermal outputs ranging from one to five kilowatts. India's urban housing corridors are driving demand as piped natural gas networks expand into Surat, Kochi, and Coimbatore.
- Commercial Catering:High-throughput food service operations requiring durable sealed brass burner assemblies. Singapore and Hong Kong operators prioritize flexible configurations for rapid layout reconfiguration.
- Institutional Cooking:Schools, hospitals, and military facilities with standardized equipment procurement and extended service interval requirements.
- Outdoor Cooking:Camping, catering events, and temporary food service with portable or weather-resistant specifications.
Residential Kitchens holds the volume base, while Commercial Catering is climbing the fastest on food service flexibility demand.
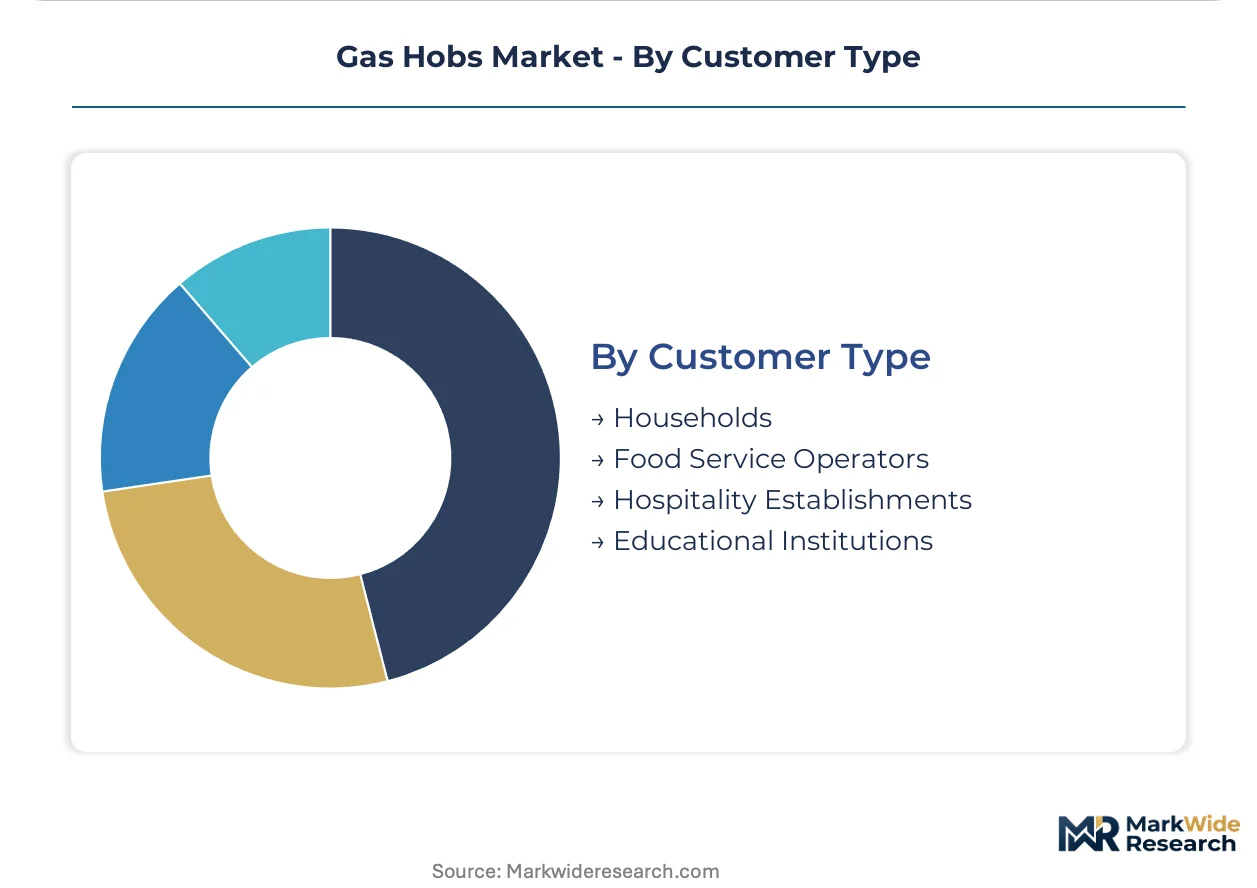
Customer Type:
Procurement authority is shifting from retail showrooms toward project-based accounts with consolidated specification power.
- Households:Individual consumers purchasing through retail or e-commerce channels. Direct-to-contractor distribution is eroding traditional kitchen retail dominance in India's metropolitan markets where builders and interior designers in Mumbai and Bangalore consolidate authority.
- Food Service Operators:Restaurants, cafeterias, and catering businesses with flexible burner configuration requirements. These customers prioritize modular systems for rapid kitchen layout adaptation.
- Hospitality Establishments:Hotels and resorts with standardized procurement protocols and premium aesthetic specifications.
- Educational Institutions:Schools and universities with budget-constrained, high-durability equipment requirements and centralized purchasing processes.
Households retain the largest customer base, though Food Service Operators are gaining share fastest on commercial kitchen reconfiguration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Southeast Asian buyers prioritize cost-efficient freestanding units, while German and Swiss consumers absorb premium pricing for precision-engineered built-in systems with advanced safety features.
Germany
Precision-machined brass valve systems command premium positioning in residential renovations across Bavaria and Baden-Württemberg. The EU Gas Appliances Regulation's flame failure mandates drive CE marking compliance investment. Stuttgart's industrial cluster anchors captive foundry capacity for cast-iron burner component production.
India
Piped natural gas conversion accelerates replacement demand in Surat, Kochi, and Coimbatore as municipal infrastructure expands. BIS certification and Petroleum and Natural Gas Regulatory Board pipeline codes reshape product compatibility requirements. Mumbai's direct-to-contractor distribution channels consolidate specification authority among builders and interior designers.
Vietnam
Middle-class kitchen renovations shorten replacement cycles for built-in gas hobs in Ho Chi Minh City and Hanoi. National technical regulations on gas appliance safety tighten import certification requirements. The Red River Delta manufacturing corridor attracts assembly operations serving domestic and export markets.
United States
Modular platform architectures sustain aftermarket parts revenue streams across North American supply chains. ANSI Z21.1 standards govern gas leakage and stability testing, creating divergent certification paths from European suppliers. The Southeast's residential construction recovery concentrates demand in Florida and Georgia housing markets.
Singapore
Food service operators adopt flexible burner configurations for rapid kitchen layout reconfiguration in commercial catering hubs. The national gas safety regulator enforces stringent flame supervision device compliance for all commercial installations. The Jurong industrial district hosts distribution centers serving regional hospitality procurement networks.
Gas Hobs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the gas hobs industry. Integrated manufacturers with captive foundry capacity command margin stability, while assembly-dependent competitors face input cost volatility and extended lead times. Three archetypes dominate: precision-engineering specialists, scale-driven platform players, and modular solution providers. Competitive moves center on backward integration into brass valve machining and strategic partnerships for certification testing infrastructure.
Among European precision-engineering specialists, Miele GmbH exemplifies the premium-tier positioning built on specialized component expertise. Whirlpool Corporation occupies a position within the scale-driven archetype, leveraging modular architectures across North American markets. Bosch anchors the integrated manufacturing tier, representing captive supply chain control from foundry operations through finished product assembly.
| Leading Market Players |
|---|
| Bosch |
| Whirlpool |
| Electrolux |
| Samsung |
| LG Electronics |
| GE Appliances |
| Frigidaire |
| Miele |
| Faber |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between European foundries and integrated manufacturers lock in brass valve component access while anchoring price visibility across multi-year procurement horizons. These contracts insulate captive producers from spot market volatility in precision-machined inputs while exposing assembly-dependent competitors to margin compression when foundry capacity tightens.
Pricing Analysis
Aftermarket parts revenue from modular platform architectures sustains lifetime value for scale-driven manufacturers serving North American replacement demand. Three-tier pricing structure across premium, standard, and economy levels separates Miele's precision-engineered brass valve systems from mid-market stainless-steel alternatives and entry-level die-cast aluminum configurations. Pricing pressure stems from induction cooktop substitution in European new construction where building codes prioritize all-electric readiness. Food service operators in Singapore exhibit lowest price sensitivity due to rapid kitchen reconfiguration requirements, while India's tier-two residential buyers absorb highest price elasticity as piped natural gas conversion accelerates.
Supply Chain Analysis
Port congestion along the Hamburg-Rotterdam- Antwerp corridor elevates inbound logistics costs for European precision-machined valve components destined to Asian assembly operations. Foundry capacity concentrates in Germany, China, and Italy for cast-iron burner bodies and brass valve systems. Raw material dependencies rest on copper-zinc alloy feedstock, tempered glass substrates from Chinese float-glass producers, and solenoid actuator coils from Japanese component specialists. Single-source vulnerability concentrates in European flame failure device certification testing where laboratory queue delays extend lead times. Distribution runs through direct-to-contractor channels in India's metropolitan markets and kitchen retail networks across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against induction cooktop capture in European residential construction, requiring strategic repositioning around gas infrastructure legacy and commercial flexibility advantages.
For Market Incumbents: Consolidate backward integration into brass valve machining to offset foundry cost volatility and compress certification timelines for CE marking compliance. Anchor capacity reservation contracts with European testing laboratories to secure flame failure device validation slots before queue delays extend product launch windows. Defend against induction substitution by emphasizing commercial kitchen reconfiguration flexibility where electric surfaces lack burner modularity. For New Entrants and Emerging Players: Differentiate on smart valve integration combining solenoid safety systems with IoT-enabled leak detection for connected home ecosystems in premium residential specifications. Target India's tier-two city penetration where Surat, Kochi, and Coimbatore municipal gas rollouts outpace established supply chain coverage. Pursue direct-to-contractor distribution partnerships with Mumbai and Bangalore builders consolidating kitchen specification authority. For Investors and Strategic Acquirers: The market sits at a regulatory-intensification phase that favors integrated manufacturers with captive foundry capacity and established certification infrastructure. Long-term viability hinges on backward integration depth and geographic diversification beyond European supply concentration. Acquisition target archetype: mid-scale European precision-engineering specialists with brass machining expertise and underutilized CE marking relationships. Signal to watch: flame failure device certification backlog duration as inflection indicator for competitive launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Valve Machining | Captive precision-machining capacity insulates margins from European foundry price volatility. |
| Smart Valve IoT Integration | Convergence with connected home ecosystems opens premium positioning beyond safety compliance. |
| Direct-to-Contractor Channel Expansion | Mumbai and Bangalore builder relationships displace traditional kitchen retail dominance. |
| Modular Platform Architecture Investment | Flexible burner configurations capture Singapore and Hong Kong commercial kitchen reconfiguration demand. |
| CE Marking Certification Infrastructure Partnership | Reserved laboratory capacity compresses flame failure device validation timelines. |
Research Methodology
A standing panel of gas appliance engineering directors, foundry operations managers, kitchen retail category buyers, and commercial food service procurement leads provided ongoing calibration across primary fieldwork. Secondary validation drew from EU Gas Appliances Regulation compliance filings, BIS certification databases, Petroleum and Natural Gas Regulatory Board infrastructure rollout schedules, and ANSI Z21.1 testing records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks validated volume and value outputs against customs trade data for brass valve component flows and tempered glass substrate shipments. Segmentation dimensions modeled include product type, safety technology tier, application environment, and customer procurement authority. CAGRs derived from regression analysis of replacement cycle acceleration, infrastructure penetration curves, and regulatory compliance investment trajectories. Industry-specific inputs incorporated municipal gas network deployment timelines and third-party testing laboratory capacity utilization rates.
The analysis sits within stated boundaries; outcomes outside sustained piped natural gas infrastructure investment, stable foundry capacity expansion, or unaltered flame failure safety mandates would require recalibration. Forecasts reflect documented assumptions regarding certification timeline normalization and substitution threat velocity from induction technologies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Wax Removal Aids Market
Household Items
Flushable Wipes Market
Household Items
Toilet Brush Market
Household Items
Tiki Torch Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Coin-Operated Laundries Market
Household Items
Smart Bathroom Market
Household Items
Wipes Market
Household Items
Permanent Marker Market
Household Items
Commercial Locker Market
Household Items
Global Rimless Toilets Market
Household Items
US Digital Showers Market
Household Items
Microwave Safe Utensils Market
Household Items
Saudi Arabia Cookware Market
Household Items
US Air Fresheners Market
Household Items
Brazil Cookware Market