
 Europe Handheld Vacuum Cleaners Market | 2026-2036
Europe Handheld Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Handheld Vacuum Cleaners Market Insights
Lithium-ion phosphate chemistry is repositioning cordless handheld units toward longer cycle life and reduced thermal runaway risk. Bosch leverages its power-tool battery ecosystem to cross-sell interchangeable packs across home and professional cleaning lines. Dyson sustains premium positioning through proprietary digital motor architectures that spin above 100,000 RPM. Karcher dominates commercial wet-and-dry applications where construction trades and hospitality operators demand IP-rated housings.
Handheld vacuum cleaners are portable suction devices typically weighing under three kilograms, designed for intermittent spot cleaning using centrifugal or axial fan impellers driven by brushed or brushless electric motors. Their primary purpose spans residential debris removal, automotive interior maintenance, and light commercial duty where maneuverability outweighs canister capacity. Cordless configurations now lead unit shipments across European retail channels as lithium-ion energy density improves runtime-to-weight ratios. The residential end-user segment anchors volume demand, while automotive detailing applications represent the fastest-growing niche driven by ride-share fleet maintenance contracts. HEPA filtration features command margin premiums in Germany and the Nordic markets where allergen sensitivity drives specification upgrades.
REACH compliance governs chemical substance restrictions in plastics and motor coatings, while the EU Ecodesign Directive mandates minimum energy efficiency indices for vacuum motor systems sold in member states. CE marking requirements under the Low Voltage Directive and EMC Directive shape product safety testing protocols and market access timelines. Stakeholders must monitor forthcoming revisions to the F-Gas Regulation and the EU Battery Passport framework, as these will impose new disclosure obligations on battery chemistry and end-of-life handling that could alter supplier qualification criteria and cost structures.
Market Dynamics
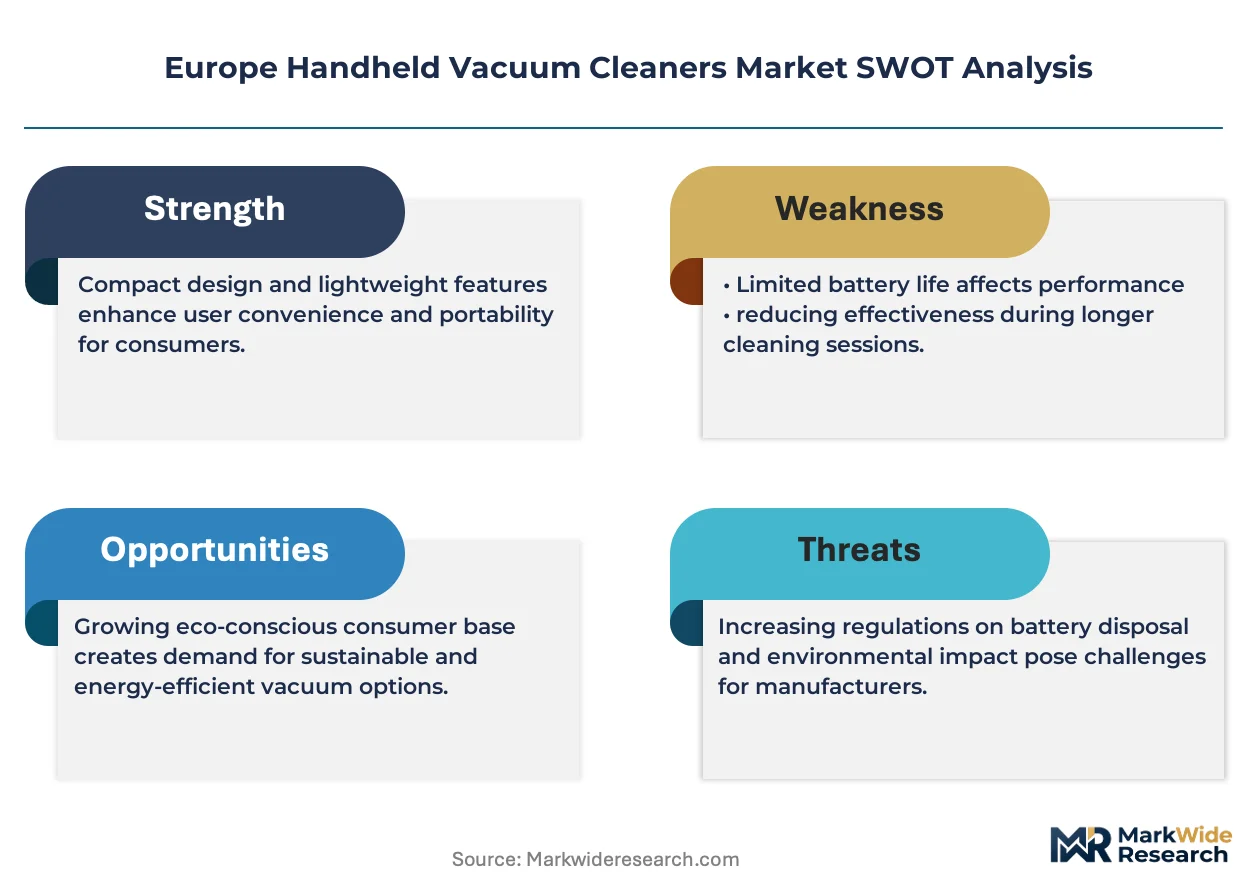
Brushless DC motor platforms are compressing energy consumption benchmarks while extending runtime-to-weight ratios, forcing incumbents to retool production lines or surrender shelf space to compliant rivals. The EU Ecodesign Directive's tightening efficiency indices have become the decisive filter for market access.
Growth Catalysts
- REACH compliance mandates:Chemical substance restrictions in plastics and motor coatings are accelerating substitution toward bio-based polymers and waterborne coatings that reduce hazardous substance liability.
- Automotive detailing contracts:Ride-share fleet operators in Germany and France are specifying handheld units for interior turnover protocols, creating recurring equipment refresh cycles.
- Lithium-ion phosphate chemistry:Battery energy density improvements are repositioning cordless configurations as runtime-competitive with corded alternatives for intermittent residential use.
Market Restraints
- Raw material concentration:Rare earth magnet supply for brushless motors concentrates in Chinese processing facilities, exposing European assemblers to export quota volatility and tariff uncertainty.
- Technical runtime ceilings:Thermal management constraints in sub-three-kilogram housings limit sustained suction duration below fifteen minutes for high-power modes.
- REACH registration burdens:Novel battery electrolyte formulations face eighteen-to-twenty-four-month substance evaluation timelines that delay product launches.
Strategic Opportunities
- Polish and Romanian retail penetration:Underdeveloped premium appliance distribution in Eastern European markets offers first-mover positioning before organized retail consolidation.
- EU Battery Passport framework:Early compliance with disclosure obligations on chemistry and end-of-life handling will qualify suppliers for public procurement tenders.
- HEPA-plus-UV convergence:Integration of ultraviolet-C emitters with filtration stacks targets hospitality sterilization protocols in Nordic markets.
Industry Challenges
- EMC certification bottlenecks:CE marking under the Electromagnetic Compatibility Directive requires third-party testing that extends time-to-market by eight to twelve weeks for new motor controller designs.
- Skill scarcity in motor control firmware:Brushless DC commutation algorithms demand embedded systems expertise that competes with automotive and industrial automation sectors for talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Handheld Vacuum Cleaners Market |
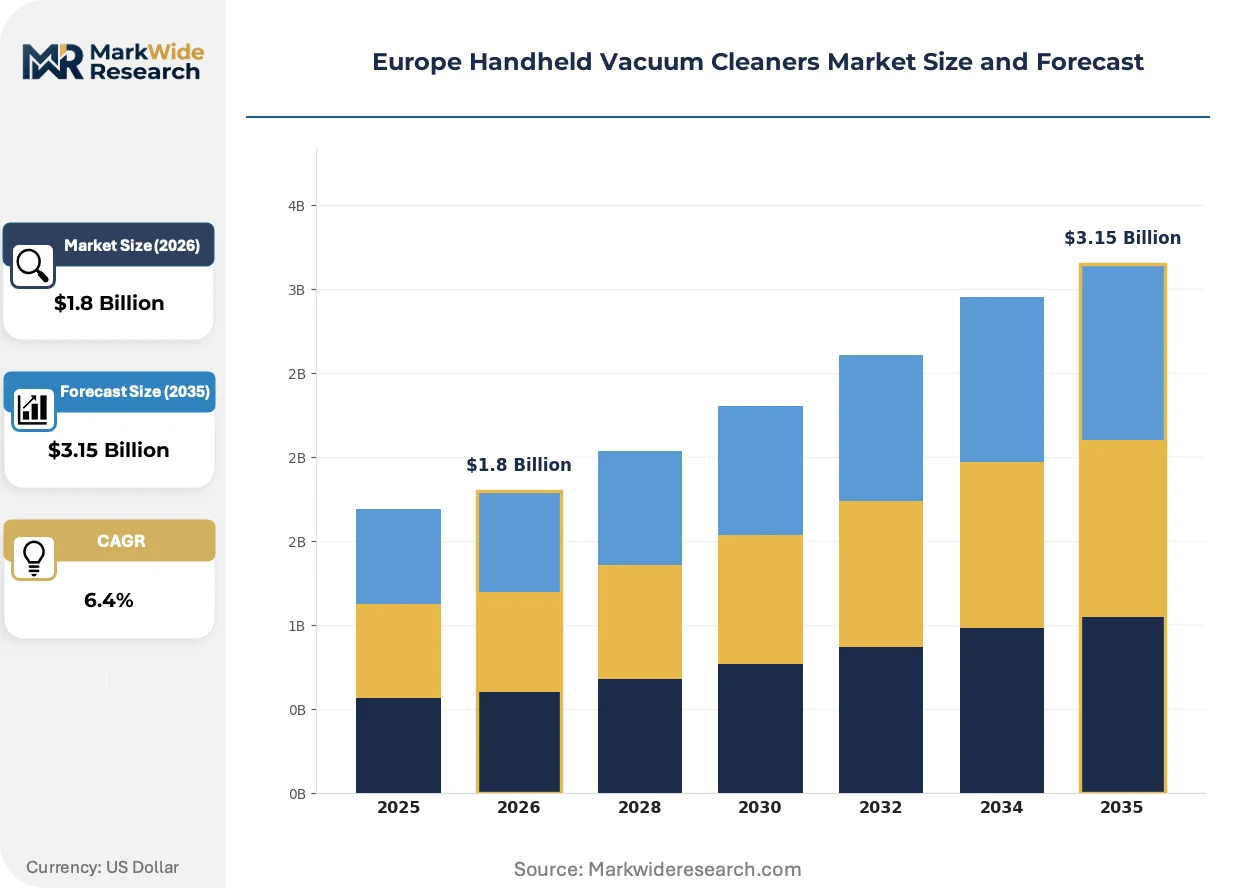
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Wet & Dry, Robotic End User: Residential, Commercial, Industrial, Automotive Power Source: Battery, Electric, Rechargeable, Disposable Feature: HEPA Filter, Lightweight, Multi-Surface, Noise Reduction |
| Companies Covered | Dyson, Bosch, Karcher, Dreame, iRobot, Roborock, Bissell, Electrolux, Miele, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Handheld Vacuum Cleaners Market Trends and Innovations
Motor architecture, chemical regulation, and distribution logic are simultaneously rewriting competitive rules. Incumbents must synchronize technical roadmaps with compliance calendars while rebuilding channel economics.
Digital motor controllers are converging with predictive battery management systems to optimize discharge curves against suction load profiles. German appliance engineers are deploying these stacks in premium cordless lines first. The convergence is compressing warranty claim rates and enabling subscription-based battery replacement programs.
The EU F-Gas Regulation's forthcoming revisions will restrict fluorinated greenhouse gases in thermal interface materials used in motor housings. Manufacturers must qualify phase-change materials or graphite-based alternatives by 2027. Commercial wet-and-dry segments face the steepest reformulation costs due to IP-rated sealing requirements.
Urban consumers in Paris and Amsterdam are compressing replacement cycles through direct-to-manufacturer subscription models that bundle filter replenishment with hardware upgrades. Traditional electronics retailers are responding with consignment inventory arrangements that transfer working capital risk to suppliers. The shift is most visible among allergy-sensitive households specifying HEPA-grade units.
Europe Handheld Vacuum Cleaners Market Segmentation
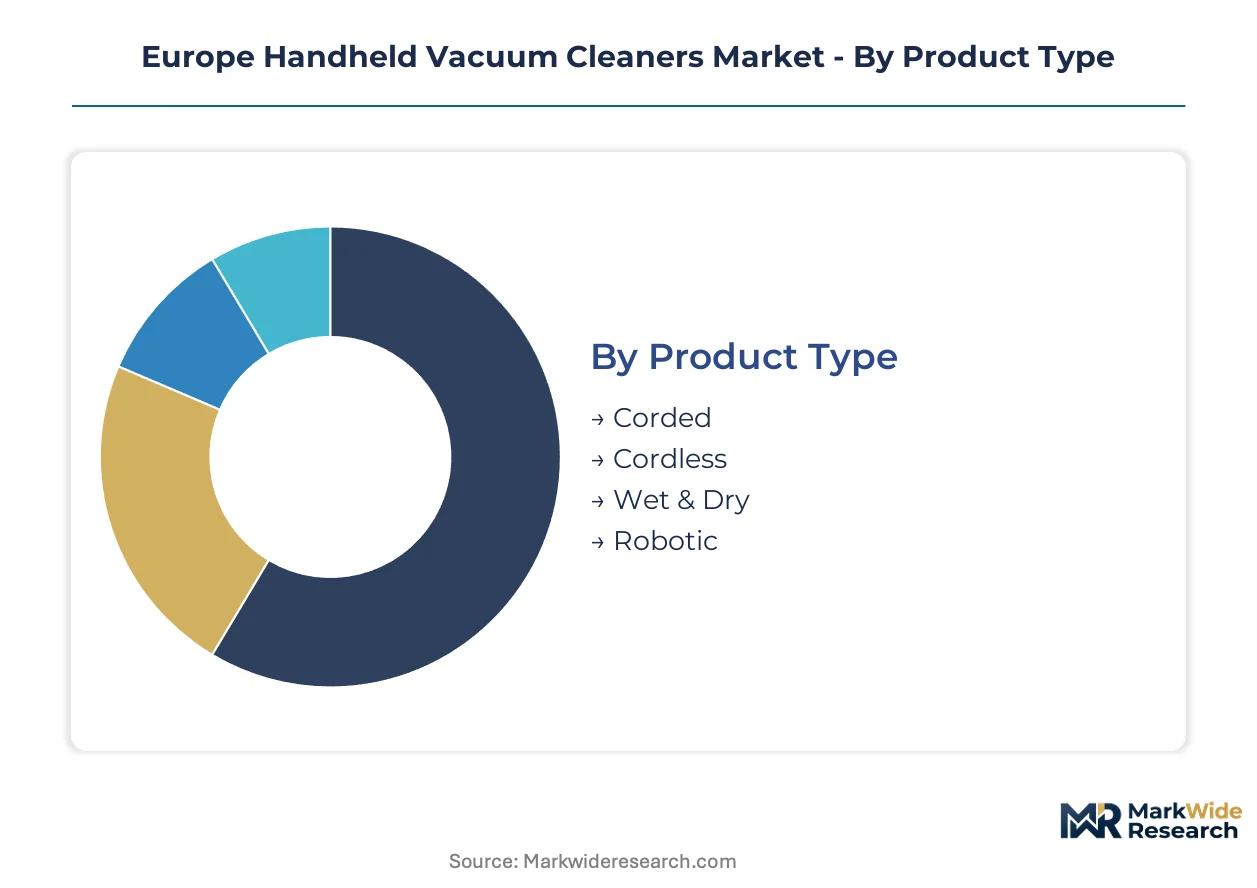
Segmentation reveals how technical specifications and use-case requirements fragment demand across European retail and professional channels. Motor efficiency mandates under EU Ecodesign Directive and battery chemistry disclosures are reshaping which configurations qualify for shelf space.
Product Type:
Supply concentration in brushless DC motor manufacturing favors platforms that amortize controller development across multiple form factors.
- Cordless:Lithium-ion phosphate cells now deliver runtime-to-weight ratios competitive with corded alternatives for intermittent residential cleaning. German and French urban households with sub-60-square-meter apartments drive replacement cycles as runtime benchmarks exceed 20 minutes per charge.
- Wet & Dry:IP-rated housings protect motor assemblies from liquid ingress during hospitality and construction site cleanup. Karcher and commercial specialists dominate this segment where trade professionals in the United Kingdom and Spain demand sealed electronics for safety compliance.
- Corded:Sustained suction duration without thermal throttling suits automotive detailing bays with fixed power infrastructure. Remaining demand concentrates in Eastern European markets where battery replacement costs deter cordless conversion.
- Robotic:Autonomous navigation stacks add cost premiums that limit penetration to premium residential segments in Nordic markets.
Cordless configurations absorb the bulk of installed capacity; wet & dry units are expanding most quickly through commercial channel penetration.
End User:
Application intensity determines motor duty cycles and warranty exposure, with commercial operators demanding mean-time-between-failure guarantees that residential buyers ignore.
- Residential:Intermittent spot-cleaning of hard floors and upholstery drives volume across German, French, and British mass retail. HEPA filtration specifications command margin premiums in allergen-sensitive households.
- Automotive:Ride-share fleet turnover protocols in Berlin, Paris, and London create recurring equipment refresh contracts. Detailing operators prioritize lightweight units with crevice tools for seat-track debris extraction.
- Commercial:Hospitality housekeeping departments in Spanish and Italian resorts specify quick-charge docks for multiple-shift coverage.
- Industrial:Light manufacturing maintenance crews in Polish automotive plants use handheld units for CNC chip cleanup where maneuverability outweighs canister capacity.
Residential buyers absorb the bulk of installed capacity; automotive detailing is climbing the fastest on fleet electrification and interior cleanliness standards.
Power Source:
Battery chemistry disclosure requirements under the forthcoming EU Battery Passport framework are disqualifying non-rechargeable configurations from public procurement tenders.
- Rechargeable:Interchangeable lithium-ion packs across Bosch home and professional tool ecosystems reduce total cost of ownership for multi-device households. The platform strategy locks in accessory and replacement battery revenue streams.
- Battery:Proprietary cell formats in Dyson digital motor lines optimize discharge curves against 100,000-plus RPM impeller loads. Thermal management firmware prevents cell degradation under sustained high-power extraction.
- Electric:Mains-powered units persist in price-sensitive Eastern European retail where cordless price premiums deter conversion.
- Disposable:Single-use alkaline configurations face regulatory pressure under REACH substance restrictions and battery waste directives.
Rechargeable systems absorb the bulk of installed capacity; battery-integrated proprietary platforms are gaining share fastest through ecosystem lock-in.
Feature:
Certification grade and weight specification determine pricing tiers, with multi-surface adaptability becoming table stakes rather than differentiation.
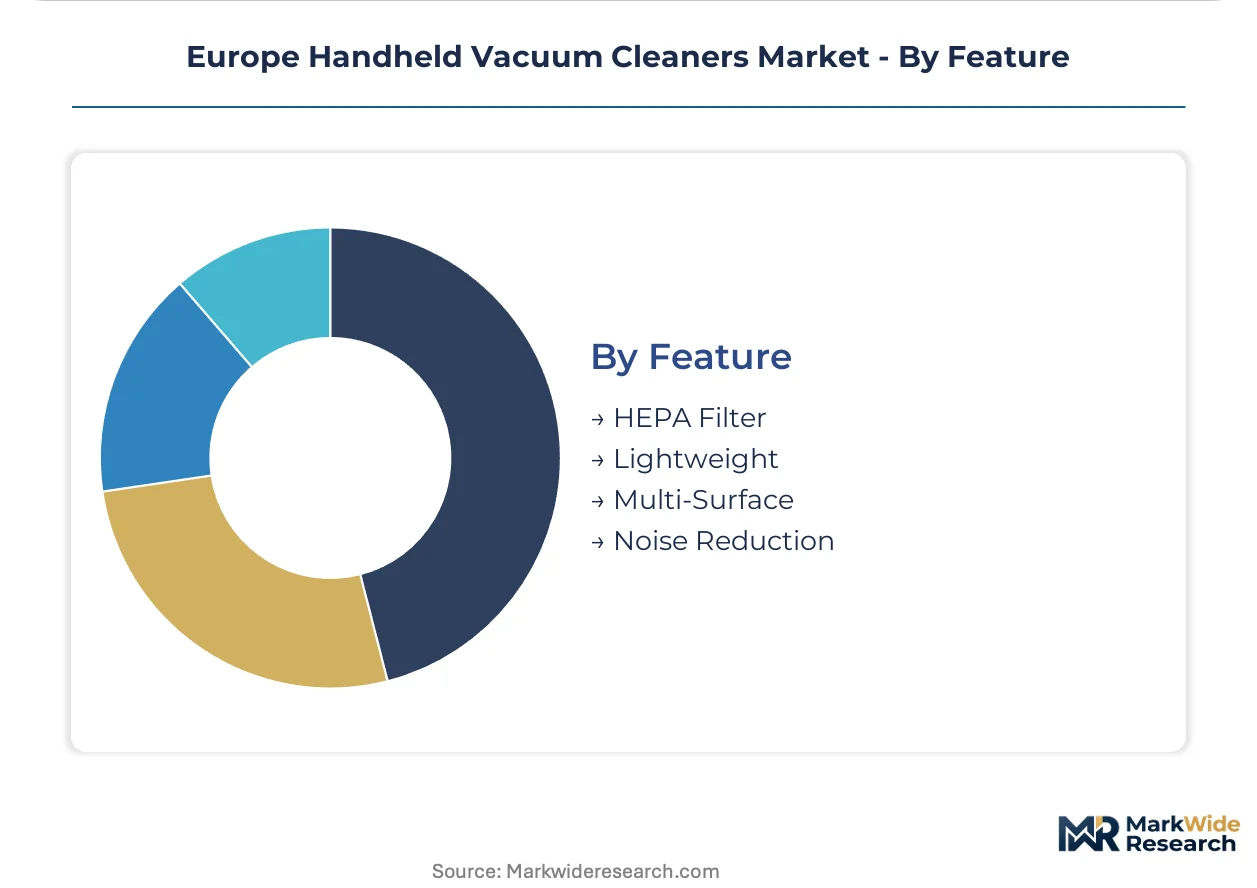
- HEPA Filter:Medical-grade filtration captures 99.97 percent of 0.3-micron particles, mandatory specification in German and Nordic markets where indoor air quality regulations are strictest. Filter replacement subscriptions generate recurring revenue for direct-to-manufacturer channels.
- Lightweight:Sub-1.5-kilogram housings target elderly users and repetitive-use commercial operators. Carbon fiber and glass-reinforced polymer chassis add material cost that compresses margin at economy price points.
- Multi-Surface:Motorized brush heads and suction adjustment switches transition between hard floors and carpet pile without tool changes.
- Noise Reduction:Acoustic dampening in motor housings and impeller blade redesigns target apartment dwellers in dense Paris and Amsterdam housing stock.
HEPA filtration absorbs the bulk of installed capacity; lightweight specifications are expanding most quickly through aging demographic targeting and ergonomic compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux special economic zones for circular manufacturing concentrate battery assembly and motor controller production for European distribution. These facilities leverage REACH pre-registration clusters to accelerate substance compliance timelines. Rotterdam and Antwerp logistics corridors feed finished goods into German and French retail channels.
Germany
Apartment density in Berlin, Munich, and Hamburg sustains replacement cycles for compact cleaning tools. The EU Ecodesign Directive's motor efficiency indices are enforced through the Federal Environment Agency's market surveillance protocols. Stuttgart's industrial corridor hosts brushless DC motor specialists supplying controllers to premium appliance brands.
France
Parisian ride-share fleet operators specify handheld units for interior turnover protocols under strict cleanliness mandates. ANSM allergen sensitivity guidelines elevate HEPA filtration requirements in retail channels. Lyon and Grenoble engineering clusters develop acoustic dampening materials for noise-reduced motor housings targeting dense urban housing.
United Kingdom
London's premium retail channels and high apartment concentration drive specification upgrades toward lightweight cordless configurations. The Office for Product Safety and Standards enforces CE marking under post-Brexit retained EU law frameworks. Manchester distribution hubs consolidate inventory for rapid replenishment of direct-to-consumer subscription models.
Spain
Hospitality housekeeping departments in Barcelona and Madrid resorts demand quick-charge docking stations for multi-shift coverage. The Spanish Ministry for the Ecological Transition monitors REACH compliance through delegated environmental authorities. Valencia's plastics processing cluster supplies bio-based polymer housings meeting tightening chemical substance restrictions.
Poland
Underdeveloped premium appliance distribution offers first-mover positioning before organized retail consolidation accelerates. The Polish Office of Competition and Consumer Protection aligns product safety enforcement with EU harmonized standards. Warsaw and Krakow logistics hubs are expanding cold-chain and electronics warehousing capacity for Central European distribution.
Europe Handheld Vacuum Cleaners Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium cordless lines concentrating around proprietary motor architectures and commercial wet-and-dry applications favoring industrial equipment heritage. The vendor base arranges into three tiers: ecosystem platform owners with interchangeable battery systems, digital motor specialists commanding margin premiums through RPM benchmarks, and commercial-grade fabricators with IP-rated sealing competencies. Consolidation pressure operates through M&A activity targeting brushless DC controller expertise and strategic partnerships securing rare earth magnet supply corridors.
Within the ecosystem platform tier, Bosch leverages its power-tool battery interchangeability across home and professional cleaning lines. Dyson occupies a position exemplifying digital motor specialization with proprietary architectures spinning above 100,000 RPM. Karcher anchors the commercial wet-and-dry segment where IP-rated housings protect motor assemblies from liquid ingress in hospitality and construction applications.
| Leading Market Players |
|---|
| Dyson |
| Bosch |
| Karcher |
| Dreame |
| iRobot |
| Roborock |
| Bissell |
| Electrolux |
| Miele |
| Others |
Pricing and Supply Chain Analysis
EU Ecodesign Directive motor efficiency mandates are forcing assemblers to source brushless DC motor platforms exclusively from REACH-compliant suppliers, compressing vendor pools and elevating procurement premiums for certified controller firmware. Battery chemistry disclosure requirements under the EU Battery Passport framework are layering qualification costs onto cell suppliers, with these compliance investments translating into tiered hardware pricing across retail channels.
Pricing Analysis
Short-lead-time premiums dominate procurement negotiations as ride-share fleet operators in Berlin and Paris demand rapid equipment refresh cycles for interior turnover protocols. Three-tier pricing structure across premium, standard, and economy levels stratifies around HEPA certification grade and runtime-to-weight benchmarks, with German and Nordic allergen-sensitive households absorbing the least price sensitivity. Cost compression in economy cordless tiers is intensifying because Eastern European price-sensitive buyers resist battery replacement economics. Subscription-based filter replenishment models in direct-to-manufacturer channels command recurring revenue premiums that offset transactional hardware margins.
Supply Chain Analysis
Rotterdam-Antwerp logistics corridors absorb inbound freight cost volatility for battery assembly and motor controller production feeding German and French retail. Rare earth magnet processing concentrates in Chinese facilities, while lithium-ion phosphate cell manufacturing draws from South Korean and Japanese suppliers. Single-source vulnerability in neodymium magnet supply exposes European assemblers to export quota disruptions. Distribution runs through Benelux special economic zone consolidation hubs before last-mile deployment via Manchester and Warsaw logistics centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless DC motor platforms are displacing brushed motor legacy architectures across European retail channels, compressing time-to-market windows for incumbents while opening specification gaps for agile entrants.
For Market Incumbents: Deploy controller firmware standardization across home and professional product lines to amortize R&D across higher unit volumes. Bosch's battery ecosystem interchangeability exemplifies this lever, locking multi-device households into captive replacement revenue streams. Incumbents must accelerate REACH pre-registration for bio-based polymer housings before the EU Ecodesign Directive's next enforcement wave disqualifies non-compliant suppliers from shelf space. For New Entrants and Emerging Players: Capture underdeveloped premium appliance distribution in Polish and Romanian retail before organized consolidation accelerates. Eastern European markets present the most penetrable geography, with Warsaw and Krakow logistics hubs expanding cold-chain and electronics warehousing capacity for Central European distribution. A direct-to-manufacturer subscription model bundling filter replenishment with hardware upgrades offers the strongest go-to-market angle against entrenched retail channel incumbents. For Investors and Strategic Acquirers: The window for entry favors brushless DC controller specialists with embedded systems expertise that competes with automotive and industrial automation sectors for talent. Long-term viability hinges on five-to-ten year positioning around EU Battery Passport compliance capabilities that qualify suppliers for public procurement tenders. The signal to watch is consolidation activity targeting motor control firmware engineering teams, as skill scarcity intensifies bidding wars for acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Supply | Captive neodymium sourcing insulates European assemblers from Chinese export quota volatility. |
| EU Battery Passport Early Compliance | Chemistry disclosure qualification unlocks public procurement tender access in Germany and France. |
| HEPA-Plus-UV Product Line Extension | Ultraviolet-C emitter integration targets Nordic hospitality sterilization protocols at margin premiums. |
| Direct-to-Consumer Subscription Launch | Filter replenishment bundling transfers working capital risk from retailers to manufacturers. |
| Polish Distribution Channel Expansion | First-mover positioning in underdeveloped premium appliance retail before consolidation accelerates. |
Research Methodology
Independent corroboration across appliance engineering directors, retail category buyers, and motor controller procurement leads underwrites the qualitative findings presented in this study. Secondary validation draws from EU Ecodesign Directive enforcement records, REACH substance registration databases, and Benelux customs aggregation data. Bottom-up shipment estimates from German, French, and British retail channels triangulate against top-down motor controller production volumes reported by Stuttgart industrial corridor suppliers.
Comparable-period anchoring to historical Ecodesign Directive implementation phases calibrates the projection horizon for efficiency mandate adoption curves. Segmentation modeling spans product type, end-user intensity, power source architecture, and certification grade dimensions throughout the forecast period. CAGRs derive from runtime-to-weight improvement trajectories in lithium-ion phosphate chemistry and brushless DC motor efficiency benchmarks tracked across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth magnet supply disruptions and REACH substance evaluation timeline extensions for novel battery electrolyte formulations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Aromatherapy Diffuser Market
Household Items
Global Humidifier Market
Household Items
Command Hooks Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Saudi Arabia Cookware Market
Household Items
Lunch Box Market
Household Items
Toilet Deodorant Market
Household Items
Residential Water Purifier Market
Household Items
Paper Towel Dispenser Market
Household Items
Asia Pacific Residential Vacuum Cleaners Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Steam Cleaners Market
Household Items
Mosquito Lamps Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Facial Tissue Paper Market
Household Items
Plastic Carafe Market