
 Household Vacuum Cleaners Market | 2026-2036
Household Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Household Vacuum Cleaners Market Intelligence
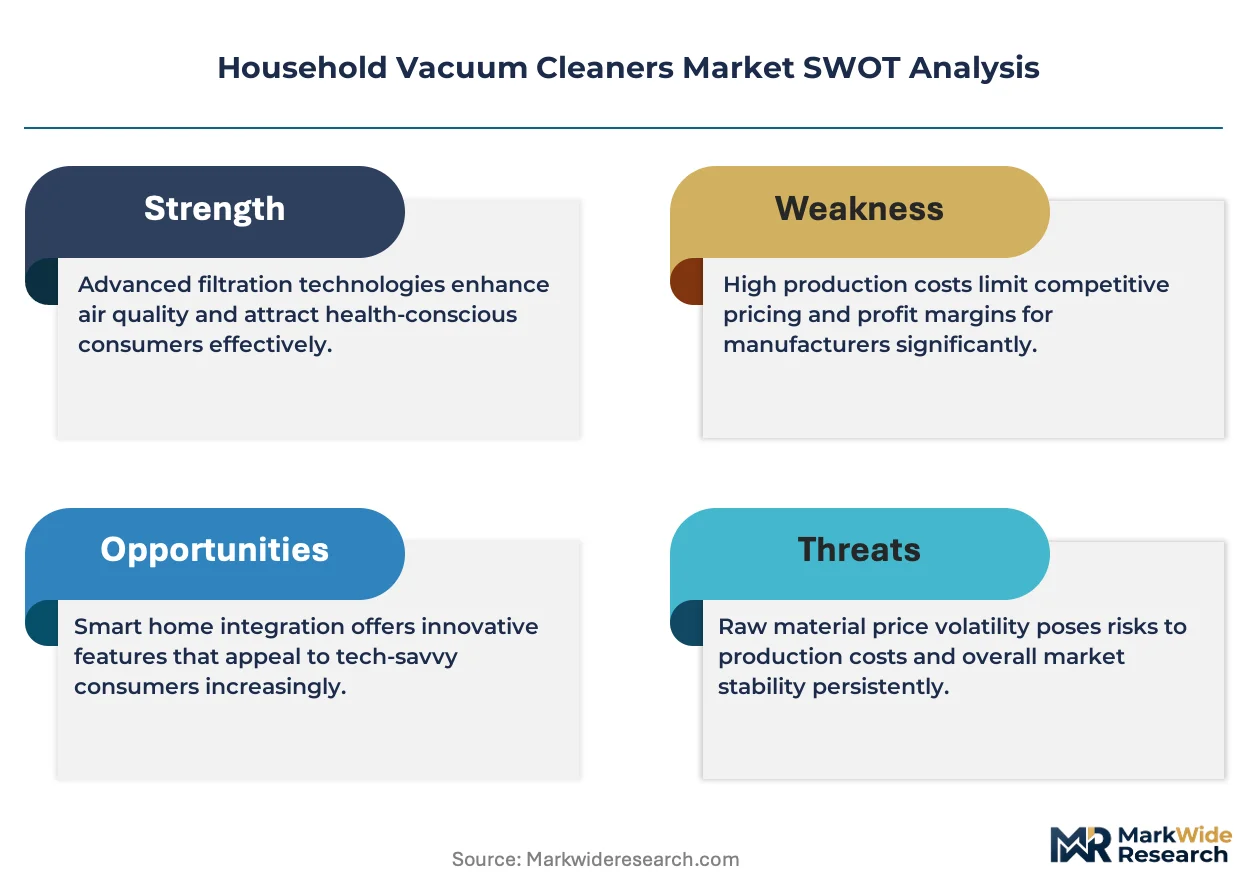
Robotics engineering talent scarcity is bifurcating the competitive landscape between established automation leaders and traditional appliance manufacturers racing to close capability gaps. iRobot leverages its two-decade autonomous navigation archive to sustain algorithmic differentiation in mapping and obstacle avoidance. Dyson anchors premium positioning through in-house motor and battery R&D, while SharkNinja competes aggressively on price-performance ratios in the cordless stick category.
Household vacuum cleaners are electromechanical suction devices engineered to remove particulate matter from residential surfaces, typically operating at airflow rates between 15 and 40 liters per second and incorporating filtration systems rated from HEPA H10 to H13 for allergen retention. Robot vacuum units now integrate LiDAR, vSLAM, and AI-driven object recognition to execute autonomous cleaning cycles with minimal human intervention. Cordless stick variants are capturing the fastest growth trajectory as lithium-ion energy density improvements extend runtime beyond sixty minutes, while canister formats retain margin concentration in European markets where consumers prioritize acoustic dampening and multi-surface versatility.
The US EPA Energy Star program and California Air Resources Board set baseline efficiency and emissions thresholds for corded equipment, while the EU Ecodesign Directive mandates standby power limits and motor efficiency grades that OEMs must satisfy for CE marking and market access. China's GB standards for electromagnetic compatibility and noise emissions add compliance layers for brands targeting domestic retail channels. Stakeholders must weigh whether to absorb certification costs for multi-jurisdiction compliance or narrow geographic focus to protect margin structures as regulatory divergence intensifies.
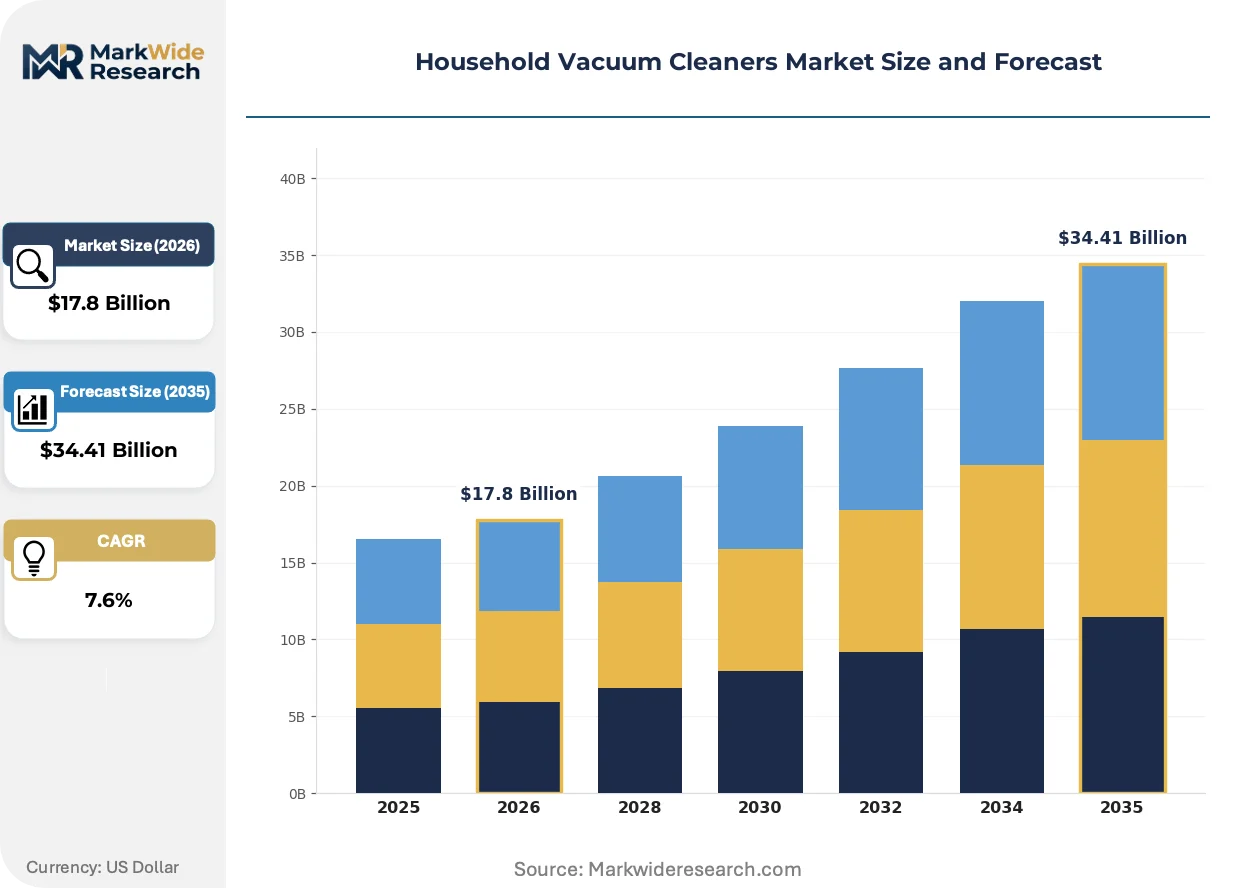
Market Dynamics
Lithium-ion energy density gains and autonomous navigation maturation are compressing replacement cycles while the EU Ecodesign Directive forces motor efficiency upgrades across European supply chains.
Growth Catalysts
- Urban apartment expansion:Compact cordless stick formats align with space-constrained dwelling configurations in dense metropolitan clusters, driving format preference shifts among younger household formations.
- EU Ecodesign Directive:Mandatory motor efficiency grades and standby power limits for CE marking access accelerate premium tier equipment turnover as legacy models face market withdrawal.
- Autonomous navigation archives:Two decades of accumulated SLAM algorithm development enable obstacle avoidance performance that reduces human intervention requirements and expands addressable buyer segments.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium dependency on Chinese processing infrastructure exposes motor manufacturers to input cost volatility and geopolitical supply disruption risk.
- Technical limitation in edge cleaning:Robot vacuum circular form factors and sensor blind spots persistently underperform along baseboards and furniture perimeters, preserving manual tool relevance.
- Substitution threat from hard surface flooring:Luxury vinyl tile and polished concrete adoption in new residential construction reduces carpet square footage and corresponding suction power requirements.
Strategic Opportunities
- India middle-class automation:Disproportionate robot vacuum shipment absorption in Indian metropolitan households creates white space for localized navigation algorithms addressing dust composition and floor type variation.
- Channel innovation via direct-to-consumer:Bypassing traditional appliance retail networks enables margin capture and subscription accessory replenishment models for consumable filtration components.
- Technology convergence of LiDAR and AI object recognition:Integration of spatial mapping with pet waste and cable identification expands autonomous operation confidence in cluttered residential environments.
Industry Challenges
- Robotics engineering talent scarcity:Algorithm development and sensor fusion expertise concentrates among automation specialists, forcing traditional appliance manufacturers into expensive capability acquisition or partnership dependency.
- Multi-jurisdiction certification timelines:Sequential compliance with US EPA Energy Star, California Air Resources Board thresholds, EU CE marking, and China GB standards extends product launch windows and strains R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Vacuum Cleaners Market |
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $34.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright Vacuum, Canister Vacuum, Handheld Vacuum, Robot Vacuum, Stick Vacuum Technology: Corded, Cordless, Bagged, Bagless, Cyclonic, Wet & Dry Application: Hardwood Floor Cleaning, Carpet Cleaning, Pet Hair Removal, Dust Mite Elimination, Allergy Reduction End User: Homeowners, Renters, Cleaning Services, Property Managers, Caretakers |
| Companies Covered | iRobot, LG Electronics, Dyson, Electrolux, Miele, SharkNinja, Samsung Electronics, Hoover, Bissell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Vacuum Cleaners Market Strategic Shifts & Innovations
Solid-state battery chemistry and AI-driven maintenance prediction are compressing form factor constraints while regulatory efficiency mandates accelerate hardware replacement cadences across major economies.
Solid-state lithium-metal cells are miniaturizing energy storage footprints without sacrificing runtime duration. Urban apartment dwellers in Tokyo, Seoul, and Singapore are adopting these configurations fastest as storage density enables sub-2.5kg stick designs. The technology is miniaturizing motor housing requirements and enabling handle-integrated battery architectures that previously demanded separate canister units.
The EU Ecodesign Directive's 2019/1782 standby power regulations and 2023 motor efficiency amendments are forcing redesigns of universal motor architectures that dominated corded equipment for decades. Manufacturers serving German, French, and Benelux markets must now achieve IE3 efficiency grades or forfeit CE marking eligibility. Premium canister producers are responding with switched reluctance and brushless DC platforms that trade higher BOM costs for compliance retention and acoustic performance gains.
Subscription-based filter and brush replenishment is displacing traditional retail accessory purchasing. Direct-to-consumer channels in US coastal metropolitan markets capture recurring revenue streams while reducing price transparency for consumable components. The shift is most visible among robot vacuum owners in California and New York, where app-integrated reordering algorithms exploit replacement interval predictability to lock in multi-year customer lifetime value.
Household Vacuum Cleaners Market Segmentation
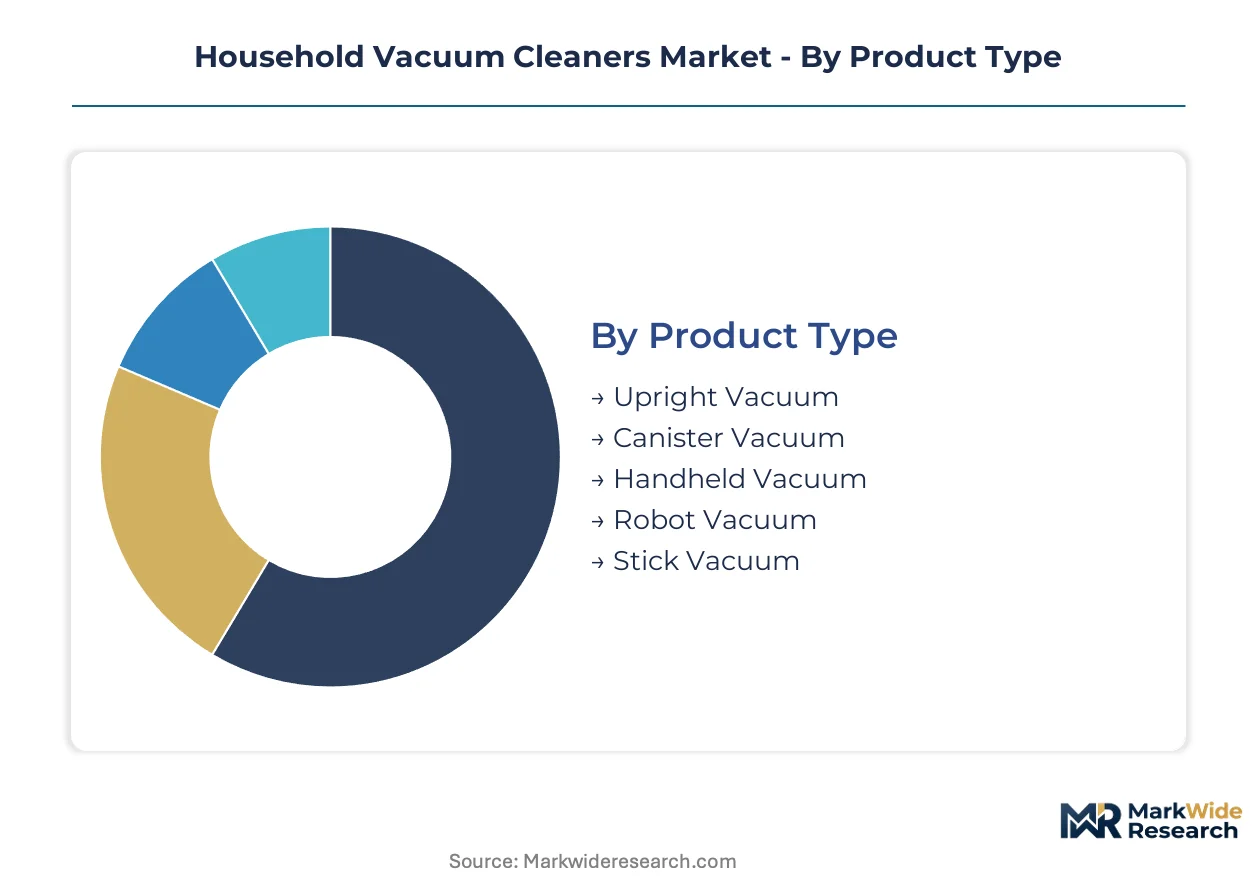
Segmentation in household vacuum cleaners reveals how divergent living arrangements and surface materials dictate equipment selection. Manufacturers configure motor architecture, filtration grade, and form factor to match distinct residential cleaning protocols rather than pursuing universal designs.
Product Type:
EU Ecodesign Directive efficiency grades and CE marking requirements force motor redesigns that segment equipment into compliance-tiered categories with diverging BOM structures.
- Upright Vacuum:Motor-fan assemblies mounted above cleaning heads deliver high suction across broad carpet surfaces. US suburban homeowners with wall-to-wall carpeting sustain demand despite cordless substitution pressure.
- Canister Vacuum:Separate motor housings connected to flexible hoses enable acoustic dampening and multi-surface versatility. German and French consumers prioritize these configurations where CE marking compliance and noise regulations intersect with premium positioning.
- Handheld Vacuum:Compact lithium-ion units target automotive and quick-clean applications. Limited runtime constrains addressable use cases.
- Robot Vacuum:Autonomous LiDAR and vSLAM navigation execute programmed cleaning cycles. Chinese and Indian metropolitan absorption drives volume concentration.
- Stick Vacuum:Lithium-ion density gains extend runtime beyond sixty minutes in sub-2.5kg formats. Tokyo, Seoul, and Singapore apartment dwellers adopt these fastest as space constraints align with cordless convenience.
Stick vacuum configurations are gaining share fastest; canister formats handle the majority of European throughput.
Technology:
Cost tier differentiation separates premium battery chemistry and filtration architectures from baseline universal motor platforms.
- Corded:Universal and brushless DC motors operating from mains power deliver sustained suction without runtime constraints. EU IE3 efficiency mandates accelerate replacement of legacy universal motor architectures in German supply chains.
- Cordless:Lithium-ion and emerging solid-state cells enable untethered operation with improving energy density. Younger household formations in dense metropolitan clusters drive preference shifts toward these formats.
- Bagged:Sealed paper or synthetic filtration media capture debris in disposable containers. Allergy-sensitive consumers in Japan and South Korea sustain demand for hygienic disposal.
- Bagless:Cyclonic separation chambers eliminate consumable costs but increase particulate exposure during emptying. Price-conscious segments prioritize total cost of ownership reduction.
- Cyclonic:Centrifugal force separates dust from airflow without filter loading. Dyson pioneered this architecture; competitors now engineer around patent expirations.
- Wet & Dry:Sealed motor housings and corrosion-resistant components handle liquid spills alongside solid debris. Workshop and utility applications concentrate demand.
Cordless technology is climbing the fastest; corded equipment retains volume concentration in established markets.
Application:
Surface material prevalence in new residential construction determines suction power and brush roll specifications across geographic markets.
- Hardwood Floor Cleaning:Soft bristle attachments and suction modulation prevent surface scratching. Scandinavian and Benelux markets with high wood flooring penetration sustain specialized tool demand.
- Carpet Cleaning:Motorized brush rolls agitate pile to release embedded particulate. US and UK residential stock with elevated carpet coverage sustains upright and canister demand.
- Pet Hair Removal:Tangle-resistant brush rolls and enhanced filtration address dander and fur accumulation. California and Australian households with elevated pet ownership drive accessory attachment sales.
- Dust Mite Elimination:UV-C emitters and high-temperature exhaust target allergen neutralization. Japanese and South Korean consumers prioritize these features in bedding and upholstery applications.
- Allergy Reduction:HEPA H13 filtration and sealed airflow paths retain sub-micron particles. EPA Indoor air quality awareness and EU ventilation standards expand specification requirements.
Hardwood floor cleaning applications are expanding most quickly; carpet cleaning handles the majority of current throughput.
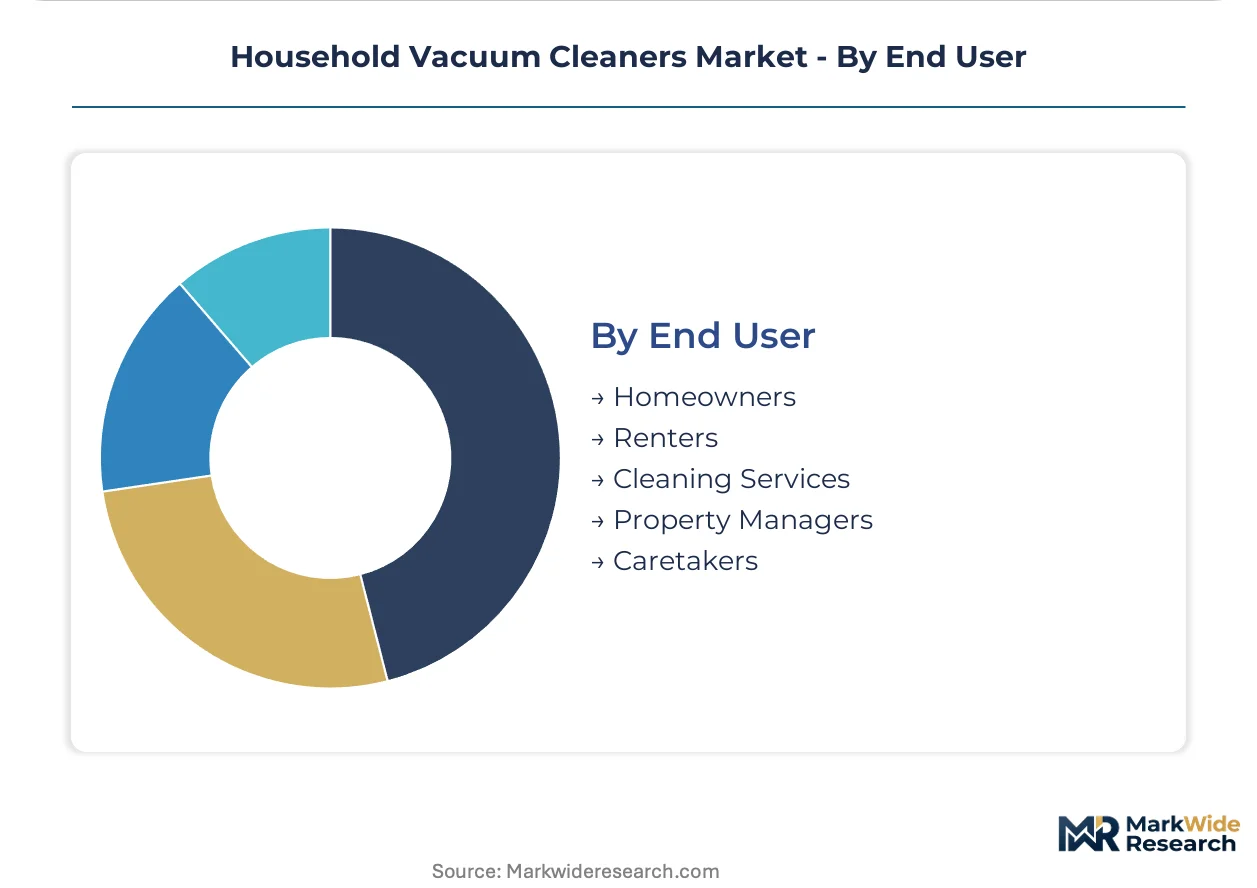
End User:
Customer type dictates purchase frequency, price sensitivity, and channel preference with diverging service expectations.
- Homeowners:Long-term residence stability justifies premium equipment investment with extended warranty preferences. US and Australian owner-occupied housing stock sustains replacement cycle compression.
- Renters:Mobility constraints and deposit recovery priorities favor compact, affordable formats. Urban apartment formations in London, Berlin, and New York concentrate cordless stick adoption.
- Cleaning Services:Commercial duty cycles demand durability and rapid serviceability. Fleet procurement concentrates in professional supply channels with volume pricing.
- Property Managers:Turnover preparation requirements drive standardized equipment selection across rental portfolios. Multi-unit operators in US Sun Belt markets prioritize cost minimization.
- Caretakers:Elderly and disability assistance applications require lightweight, maneuverable designs. Japan's aging demographic sustains ergonomic specification demand.
Homeowners handle the majority of equipment throughput; renters represent the steepest expansion trajectory in cordless categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Energy Star efficiency thresholds anchor US regulatory architecture while the EU Ecodesign Directive drives motor redesigns across German and French supply chains. Chinese GB standards and Indian BIS certifications add compliance layers for brands targeting Asia-Pacific expansion.
United States
California Air Resources Board emissions thresholds and EPA Energy Star labeling sustain demand for high-efficiency corded equipment in suburban markets. The US Department of Energy periodically revises appliance efficiency standards that OEMs must satisfy for federal procurement eligibility. Metropolitan clusters in Texas and Florida concentrate property manager fleet purchasing for multi-unit rental turnover preparation.
Germany
IE3 motor efficiency mandates under EU Ecodesign Directive amendments force universal motor replacements in premium canister segments. CE marking requirements intersect with national noise ordinances that acoustic engineering investments must satisfy. Industrial concentration in Baden-Württemberg and Bavaria hosts switched reluctance motor development for compliance-tiered product lines.
China
GB standards for electromagnetic compatibility and noise emissions filter market access for domestic retail channel penetration. MIIT industrial policy supports lithium-ion energy density research that solid-state battery developers leverage. Shenzhen and Dongguan manufacturing clusters dominate robot vacuum assembly capacity for export and domestic middle-class consumption.
India
BIS certification requirements and DGFT import regulations structure competitive entry for automated cleaning equipment. PLI scheme incentives for electronics manufacturing attract component localization investments from multinational OEMs. Mumbai and Bengaluru metropolitan households absorb disproportionate robot vacuum volumes as residential automation accelerates.
Japan
METI energy conservation standards and JIS noise specifications maintain premium tier equipment thresholds that domestic manufacturers engineer toward. Aging demographic profiles sustain ergonomic specification demand for lightweight caretaker-assist designs. Osaka and Nagoya industrial corridors concentrate motor and filtration component supply for regional appliance assembly.
Household Vacuum Cleaners Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in household vacuum cleaner manufacturing. The upper tier combines captive motor development with autonomous navigation software archives that algorithmic differentiation sustains. Specialist fabricators concentrate on price-performance optimization in cordless stick formats or regional compliance adaptation. Strategic moves center on robotics engineering talent acquisition and direct-to-consumer channel infrastructure buildout.
Within the integrated technology tier, iRobot and Dyson exemplify divergent capability anchoring. iRobot occupies a position defined by two decades of SLAM algorithm accumulation that obstacle avoidance performance leverages. Dyson represents premium positioning through in-house motor and battery R&D control. SharkNinja sits within the aggressive price-performance specialist category that cordless stick volume expansion targets.
| Leading Market Players |
|---|
| iRobot |
| LG Electronics |
| Dyson |
| Electrolux |
| Miele |
| SharkNinja |
| Samsung Electronics |
| Hoover |
| Bissell |
| Others |
Cost & Logistics Intelligence
Ninety-day motor component lead times from Asian manufacturing clusters concentrate procurement risk among OEMs serving European CE marking deadlines, compressing margin buffers and amplifying pricing power for vertically integrated suppliers with captive motor production. This inventory pressure cascades into tiered equipment pricing that separates IE3-compliant canister platforms from legacy universal motor architectures facing market withdrawal.
Pricing Analysis
Price spreads between German canister units and Southeast Asian stick vacuum imports exceed threefold at retail, reflecting divergent certification burdens and acoustic engineering investments. Pricing stratifies across premium, standard, and economy tiers where HEPA H13 filtration and lithium-ion energy density command measurable premiums. Cost compression in cordless categories is intensifying because solid-state battery developers are racing to displace cylindrical cell architectures. Property managers in US Sun Belt markets exhibit highest price sensitivity, while Japanese aging-demographic caretakers prioritize ergonomic specifications over unit economics.
Supply Chain Analysis
Inventory buffers for neodymium magnet feedstock have compressed to six weeks across motor manufacturers, exposing production schedules to Chinese rare earth processing volatility. Shenzhen and Dongguan concentrate robot vacuum final assembly, while South Korean chemical suppliers and Japanese precision motor houses anchor upstream component flows. Single-source vulnerability in dysprosium separation creates tariff-agnostic supply risk that no alternative geography currently mitigates. Distribution runs through appliance retail networks in established markets and direct-to-consumer platforms in metropolitan automation clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in localized navigation algorithms and regional compliance adaptation, as divergent floor compositions and certification timelines prevent global standardization. Urban apartment formations and middle-class automation in emerging economies create addressable niches beneath integrated leader radar.
For Market Incumbents: Shield algorithmic differentiation through selective robotics engineering talent acquisition in Tel Aviv and Boston autonomy clusters, while consolidating motor supply through backward integration into rare earth magnet recycling. The substitution threat from hard surface flooring demands acoustic performance investment to preserve canister relevance in European markets.
For New Entrants and Emerging Players: Differentiate on dust-composition adaptation for Indian metropolitan households, where localized SLAM training data remains scarce among established competitors. Target direct-to-consumer replenishment models for HEPA filtration consumables in California and New York, exploiting replacement interval predictability that incumbent retail channels underserve.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because robotics capability scarcity will force traditional appliance manufacturers into expensive acquisition cycles or partnership dependency. Acquisition targets should combine autonomous navigation software archives with regional compliance certification infrastructure. The signal to watch is BIS certification timeline compression for robot vacuum entrants into Indian retail channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Buildout | Subscription filter replenishment captures recurring revenue in California metropolitan markets. |
| LiDAR-AI Convergence Investment | Pet waste identification expands autonomous operation confidence in cluttered residential environments. |
| Solid-State Battery Integration | Sub-2.5kg stick designs penetrate Tokyo and Seoul space-constrained apartment segments. |
| Regional Compliance Certification | IE3 motor efficiency and CE marking retention secures German and French premium canister access. |
| Robotics Talent Acquisition | SLAM algorithm expertise concentrates defensive capability among automation-specialist employers. |
Research Approach
A standing panel of robotics engineering directors, appliance retail category managers, motor procurement leads, and regulatory compliance officers provided ongoing calibration against secondary validation from EPA Energy Star filings, EU Ecodesign Directive amendments, China GB standard releases, and India BIS certification databases. Bottom-up equipment shipment tracking across product formats combined with top-down household penetration modeling to triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, technology architecture, surface application, and end-user archetype dimensions. CAGRs derived from replacement cycle compression analysis and autonomous navigation adoption curves, with lithium-ion energy density improvement trajectories and regulatory efficiency mandate timelines as core forecast inputs.
Material uncertainties — rare earth supply disruption, solid-state battery commercialization delays, and regulatory divergence acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about middle-class automation penetration and motor efficiency compliance adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Household Beauty Appliances Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
Automatic Dishwasher Market
Appliances
Dishwasher Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Electric Dryers Market
Appliances
Under Counter Dishwasher Market
Appliances
Mini Washing Machine Market
Appliances
Wall Oven Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
Cooker Hoods Market
Appliances
Electric Kettle Market
Appliances
Digital Showers Market
Appliances
Clothing Iron Market
Appliances
Oman Dishwashers Market
Appliances
Oman Microwave Ovens Market