
 Stick Vacuum Cleaner Market | 2026-2036
Stick Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
Stick Vacuum Cleaner Market Insights
The capital-intensity divergence between in-house motor manufacturing and outsourced assembly is redrawing competitive tiers in the stick vacuum cleaner landscape. Dyson Limited leverages proprietary digital motor technology to sustain premium positioning across direct-to-consumer channels. Techtronic Industries Co. Ltd. anchors its cost structure through captive battery cell production in Southeast Asian facilities. SharkNinja Operating LLC competes aggressively via rapid product cycle turnover and dominant retail shelf presence in North American big-box stores.
A stick vacuum cleaner is a lightweight, elongated cleaning device typically weighing under three kilograms, employing cyclonic separation or bagged filtration to remove particulate matter from floors and elevated surfaces, with cordless variants relying on lithium-ion battery packs delivering 20–60 minutes of runtime per charge. The device serves residential and light commercial users who prioritize maneuverability over the raw suction capacity of canister or upright units. Cordless configurations now lead volume growth as battery energy density improvements reduce the performance gap with corded predecessors, while filtration technology represents the primary margin pool where HEPA certification commands price premiums. The residential end-user segment remains structurally mature in Western Europe but exhibits expansion potential in Asia-Pacific urban markets where apartment density favors compact formats.
The US Consumer Product Safety Commission enforces stringent lithium-ion battery safety standards that shape cordless product design and recall liability exposure, while the EU Ecodesign Directive mandates minimum energy efficiency thresholds that filter lower-tier imports from European shelves. China's State Administration for Market Regulation coordinates national standards for wireless appliance electromagnetic compatibility, creating a fragmented compliance landscape for brands operating across multiple jurisdictions. Stakeholders must monitor battery chemistry substitution timelines and evolving extended-producer-responsibility frameworks as these forces determine which product architectures achieve cross-border scale.
Market Dynamics
Battery energy density improvements above 250 Wh/kg are collapsing the performance premium that corded stick vacuums once commanded, forcing incumbent manufacturers to accelerate cordless platform transitions while managing lithium supply contract volatility.
Growth Catalysts
- EU Ecodesign Directive efficiency mandates:Minimum energy performance thresholds filter out lower-tier imports from European retail channels, creating shelf space for certified premium models.
- Urban apartment density in China's tier-one cities:Compact housing configurations favor lightweight formats over canister alternatives, concentrating replacement demand in Shanghai, Beijing, and Shenzhen.
- Lithium-ion cell cost curves:Cathode material innovations and scaled cell manufacturing in Southeast Asian facilities compress battery pack costs for cordless configurations.
Market Restraints
- Cobalt and lithium price volatility:Cathode material input costs swing with DRC mining output and Chilean brine extraction quotas, squeezing margin predictability for battery-dependent SKUs.
- HEPA certification concentration:Third-party testing capacity bottlenecks in Germany and the United States delay product launches by 4-8 months for brands seeking allergy-certification premiums.
- Corded residual demand in rental housing:Landlord-supplied cleaning equipment in multi-unit buildings sustains lower-price corded alternatives that delay cordless adoption cycles.
Strategic Opportunities
- India's urban middle-class expansion:Metro apartment construction in Mumbai, Delhi, and Bangalore creates first-time appliance purchasers favoring compact formats over full-size alternatives.
- Extended producer responsibility frameworks:French and German battery recycling mandates create service-revenue streams for brands establishing take-back infrastructure.
- AI-enabled dirt detection:Sensor fusion between particle counters and motor controllers enables automatic suction modulation, differentiating premium tiers through software rather than hardware.
Industry Challenges
- Battery safety engineering talent scarcity:Thermal runaway mitigation and cell balancing expertise concentrates among automotive and consumer electronics veterans, forcing appliance brands to compete for limited specialists.
- Cross-jurisdiction certification timelines:Simultaneous FCC electromagnetic compliance, CE marking, and China GB standard testing creates parallel validation costs that compress launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stick Vacuum Cleaner Market |
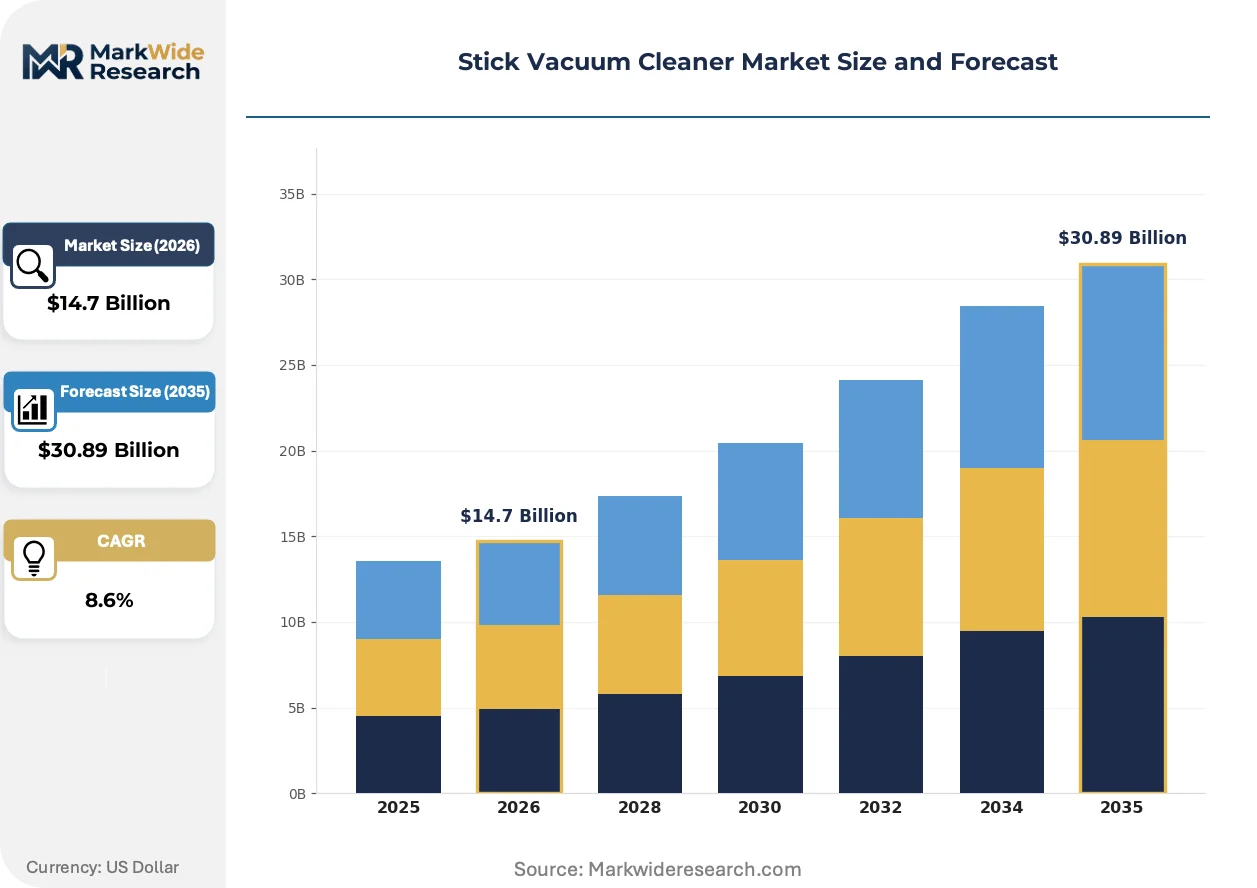
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Robotic, Handheld End User: Residential, Commercial, Industrial, Automotive Technology: Batteries, Suction, Filtration, Sensors Distribution Channel: Online, Retail, Wholesale, Direct |
| Companies Covered | Dyson Limited, Techtronic Industries Co. Ltd., SharkNinja Operating LLC., Electrolux AB, Samsung Electronics Co. Ltd., LG Electronics Inc., BISSELL Inc., Miele & Cie. KG, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stick Vacuum Cleaner Market Trends and Innovations
Solid-state battery prototyping and software-defined motor control are converging to redefine performance benchmarks and ownership economics across cordless cleaning platforms.
Silicon-anode lithium-ion cells are decomposing the runtime-versus-weight tradeoff that has constrained cordless suction power. Urban apartment dwellers in compact housing are adopting these configurations faster than suburban homeowners with storage space for multiple appliances. This chemistry transition is decomposing the historical three-tier product architecture into a simpler premium-mass bifurcation.
REACH substance restrictions on persistent organic pollutants are tightening requirements for plastic housing materials and motor coatings in European markets. Manufacturers serving Germany, France, and the Netherlands face reformulation costs or supplier switches to maintain market access. Cordless SKUs with sealed battery enclosures encounter additional compliance scrutiny under evolving end-of-life handling protocols.
Direct-to-consumer subscription filter replacement programs are capturing aftermarket revenue previously lost to third-party consumable suppliers. Premium brands bypass retail margin stacking while locking in recurring customer relationships through automated replenishment. This channel shift concentrates most visibly in North American markets where Amazon's Subscribe & Save infrastructure enables frictionless execution.
Stick Vacuum Cleaner Market Segmentation
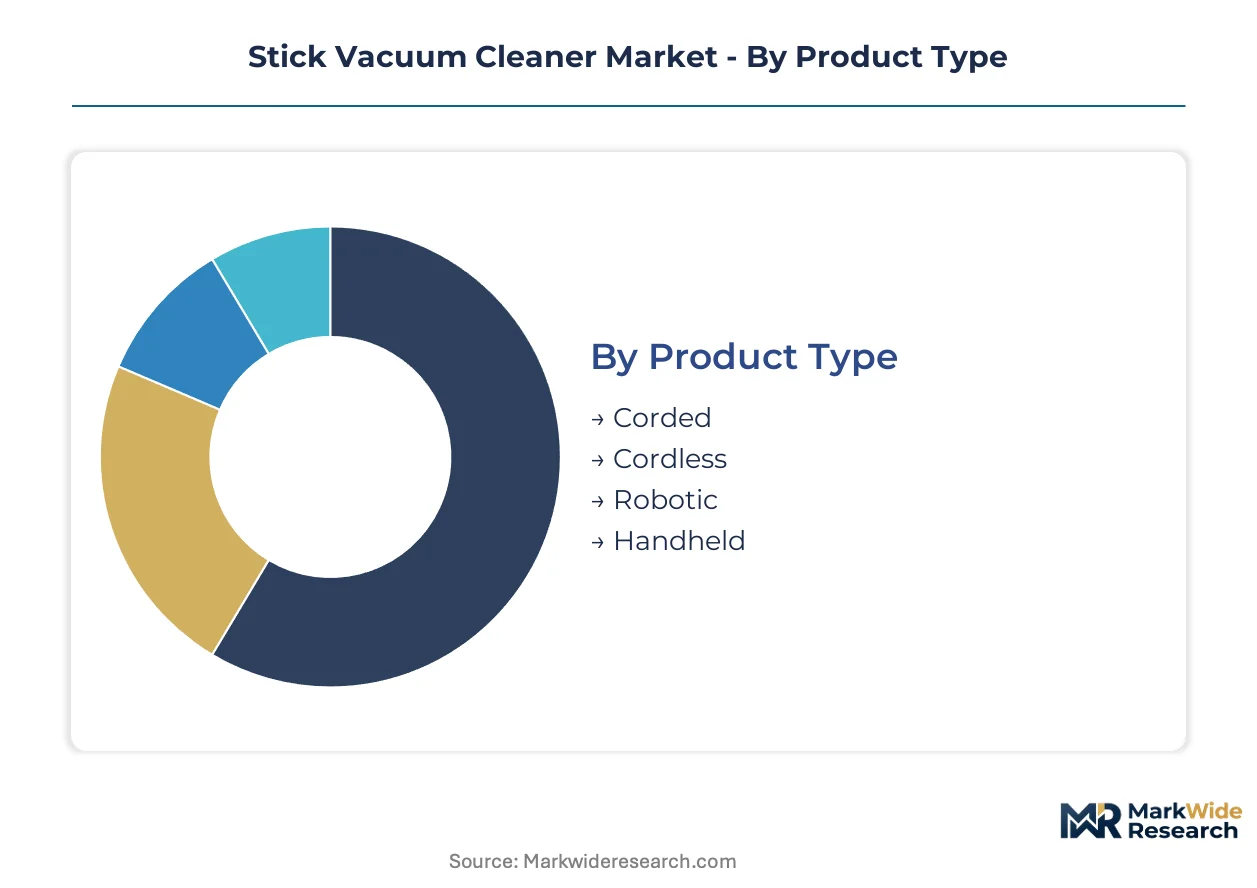
Segmentation in the stick vacuum cleaner market exposes how regulatory pressure and battery chemistry transitions reshape competitive positioning across product tiers. Manufacturers must align platform architectures with jurisdiction-specific compliance timelines rather than pursuing universal designs.
Product Type:
EU Ecodesign Directive efficiency thresholds and US CPSC battery safety mandates create divergent compliance burdens across power configurations, filtering which formats achieve cross-border scale.
- Corded:Mains-powered units deliver sustained suction without runtime constraints, relying on universal motors and bagged filtration systems. Rental housing in Germany and France sustains residual demand where landlords supply shared cleaning equipment, delaying replacement cycles.
- Cordless:Lithium-ion configurations dominate volume expansion as silicon-anode cells above 250 Wh/kg collapse the performance gap with corded predecessors. Urban apartment dwellers in Shanghai, Beijing, and Shenzhen favor these lightweight formats where storage constraints and outlet scarcity limit traditional alternatives.
- Robotic:Autonomous navigation platforms integrate LiDAR and camera-based mapping for scheduled cleaning cycles.
- Handheld:Compact battery-powered units target spot cleaning and vehicle interiors with reduced motor displacement.
Corded handles the majority of throughput; cordless is the fastest mover on share.
End User:
Application-specific duty cycles and contamination profiles determine motor specification, filtration grade, and warranty structure across customer categories.
- Residential:Household purchasers prioritize maneuverability and storage footprint over raw suction capacity, with HEPA certification commanding price premiums for allergy-sensitive consumers. China's tier-one cities concentrate replacement demand where apartment density favors stick formats over canister alternatives.
- Commercial:Light-duty professional users in hospitality and co-working spaces require rapid deployment and minimal training, driving procurement toward standardized cordless fleets with swappable battery systems.
- Industrial:Manufacturing and warehouse environments demand extended runtime and particulate containment for regulated dust classes.
- Automotive:Detailing specialists and fleet operators need crevice tools and upholstery attachments for interior finishing work.
Residential absorbs the dominant share of unit volume; commercial is climbing the fastest as facility management outsources cleaning operations.
Technology:
Component-level differentiation determines margin capture, with filtration certification and battery chemistry representing the primary value pools.
- Batteries:Cell chemistry selection between NMC, LFP, and emerging solid-state prototypes dictates runtime, weight, and thermal safety profiles. Southeast Asian cell manufacturing scales compress pack costs for brands with captive supply arrangements.
- Suction:Digital motor controllers enable variable speed mapping to surface types, with proprietary designs sustaining premium positioning.
- Filtration:Multi-stage HEPA and ULPA systems capture sub-micron particles for allergy certification.
- Sensors:Particle counters and floor-type detectors enable automatic suction modulation.
Filtration delivers the highest margin per unit; battery technology is gaining share fastest as energy density improvements unlock cordless substitution.
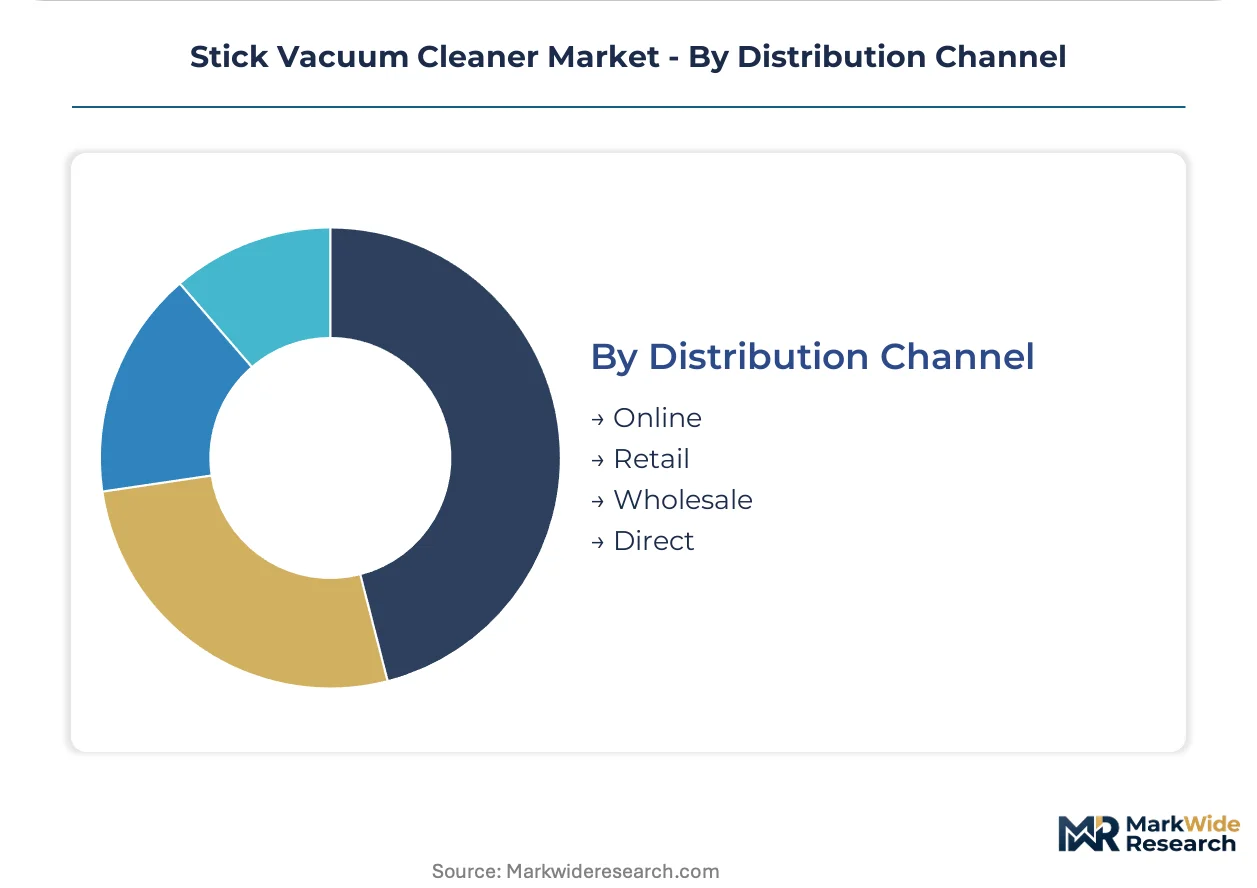
Distribution Channel:
Channel economics determine working capital intensity and aftermarket revenue capture, with direct-to-consumer models bypassing retail margin stacking.
- Online:E-commerce platforms enable subscription filter replenishment and automated accessory recommendations, concentrating in North American markets where Amazon's infrastructure supports frictionless execution.
- Retail:Big-box shelf presence in the United States drives impulse purchases and brand visibility through endcap placement and seasonal promotions.
- Wholesale:B2B procurement for commercial fleets and property management companies.
- Direct:Manufacturer-owned channels capture full margin and customer relationship data.
Online transacts the majority of premium units; direct channels are expanding most quickly as brands invest in subscription retention infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German and Japanese markets where HEPA certification commands substantial premiums, while cost-competitive manufacturing gravitates toward Vietnamese and Chinese coastal zones where cell assembly scales compress pack economics.
United States
The US Consumer Product Safety Commission enforces stringent lithium-ion battery safety standards that elevate compliance costs for cordless entrants. Big-box retail channels in suburban markets sustain impulse purchasing through seasonal promotional cycles. California's housing density and outlet-scarce apartment configurations accelerate cordless adoption in Los Angeles and San Francisco metro clusters.
Germany
German consumers prioritize filtration certification and energy efficiency, creating sustained demand for premium-tier products. The EU Ecodesign Directive and REACH substance restrictions filter lower-tier imports from retail shelves. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate component manufacturing and third-party testing capacity for HEPA validation.
China
China's State Administration for Market Regulation coordinates national standards for wireless appliance electromagnetic compatibility. Tier-one cities—Shanghai, Beijing, Shenzhen—concentrate replacement demand where compact apartment configurations favor stick formats. The Yangtze River Delta and Pearl River Delta host captive cell manufacturing facilities that compress battery pack costs for domestic brands.
Japan
Japanese households exhibit strong preference for lightweight, storage-efficient appliances in space-constrained urban dwellings. METI efficiency guidelines and JIS standards shape product specification requirements for domestic market entry. The Kanto region around Tokyo anchors premium retail distribution and after-sales service infrastructure.
India
Metro apartment construction in Mumbai, Delhi, and Bangalore creates first-time appliance purchasers favoring compact formats. The Bureau of Indian Standards implements mandatory certification for electronic appliances entering domestic commerce. Western and Southern industrial corridors host assembly operations serving price-sensitive mass-market segments.
Stick Vacuum Cleaner Market Competitive Landscape
Concentration sits with diversified appliance conglomerates and specialized cleaning equipment manufacturers. The vendor base spans three distinct tiers: premium technology specialists commanding direct-to-consumer margins, mid-market brands scaling through retail partnerships, and value-oriented assemblers competing on price. Strategic moves center on captive battery supply arrangements and rapid product cycle turnover to defend shelf positioning.
Among the named specialists, Dyson Limited exemplifies premium-tier positioning through proprietary motor technology and direct channel control. Techtronic Industries Co. Ltd. and SharkNinja Operating LLC occupy complementary positions—one leveraging Southeast Asian manufacturing scale, the other dominating North American retail presence through accelerated product refresh rates. These three anchors represent divergent paths to margin capture in a market bifurcating between technology-driven premium and scale-driven mass segments.
| Leading Market Players |
|---|
| Dyson Limited |
| Techtronic Industries Co. Ltd. |
| SharkNinja Operating LLC. |
| Electrolux AB |
| Samsung Electronics Co. Ltd. |
| LG Electronics Inc. |
| BISSELL Inc. |
| Miele & Cie. KG |
| Robert Bosch GmbH |
| Others |
Pricing and Supply Chain Analysis
EU Ecodesign Directive efficiency thresholds simultaneously gate supplier qualification and stratify price tiers, compressing margins for uncertified imports while amplifying premiums for compliant HEPA-certified configurations across German and French retail channels.
Pricing Analysis
The configured-to-order premium spread reaches widest in North American direct-to-consumer channels where subscription bundling commands sustained margin capture against transactional retail SKUs. Three-tier pricing structure across premium, standard, and economy levels stratifies by HEPA certification grade and motor displacement, with allergy-sensitive households showing lowest price sensitivity. Cost compression in mass-market cordless tiers intensifies as silicon-anode cell scaling feeds downstream pack economics, eroding differentiation for brands without captive battery supply.
Supply Chain Analysis
Lithium carbonate processing chokepoints in Chilean brine extraction and DRC cobalt mining underwrite cathode material cost volatility that propagates through Southeast Asian cell assembly hubs. Battery pack production concentrates in China, Vietnam, and South Korea, drawing from refined lithium, nickel sulfate, and cobalt hydroxide feedstocks. Single-source vulnerability in cathode precursor supply elevates margin risk for brands without diversified offtake agreements. Distribution runs through big-box retail in suburban United States and direct-to-consumer platforms in premium European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against autonomous robotic cleaning platforms, where incumbents must accelerate cordless performance convergence before navigation-enabled alternatives capture apartment-dweller segments.
For Market Incumbents: Consolidate captive lithium-ion cell supply through Southeast Asian manufacturing partnerships, insulating margin structures from cathode material volatility. Deepen backward integration into digital motor controller design to sustain proprietary differentiation against SharkNinja's rapid-cycle retail pressure. Prioritize HEPA certification pre-positioning ahead of REACH substance restriction tightening in German markets.
For New Entrants and Emerging Players: Aftermarket filter replenishment services represent the most penetrable white-space where Dyson's direct channel leaves price-sensitive households underserved. Target India's metro apartment construction corridors with compact-format SKUs positioned below premium import tiers. Deploy subscription-first go-to-market architecture leveraging Amazon Subscribe & Save infrastructure for recurring revenue lock-in.
For Investors and Strategic Acquirers: Solid-state battery commercialization timelines reshape the acquisition landscape toward brands with thermal runaway engineering depth and automotive-sector talent pipelines. Long-term viability centers on software-defined motor control capabilities that transcend hardware commoditization cycles. Battery recycling mandate enforcement across France and Germany signals inflection timing for take-back infrastructure valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Battery Cell Manufacturing | Southeast Asian production scale compresses pack costs for cordless platform transitions. |
| HEPA Certification Pre-Positioning | German third-party testing bottlenecks reward early regulatory alignment with shelf access timing. |
| Direct-to-Consumer Channel Expansion | Subscription filter replenishment captures aftermarket revenue previously lost to third-party suppliers. |
| Solid-State Battery Prototyping | Silicon-anode chemistry transitions unlock runtime-weight performance thresholds that redefine premium tiers. |
| Extended Producer Responsibility Infrastructure | French and German recycling mandates create service-revenue streams through take-back program deployment. |
Research Methodology
The analysis maps corded, cordless, robotic, and handheld configurations, each validated through appliance category managers, lithium-ion cell procurement leads, HEPA testing laboratory directors, and retail buyer committees. Primary interview intelligence triangulates against customs trade records, EU Ecodesign Directive compliance databases, SEC 10-K appliance segment disclosures, and Nielsen retail audit data. Bottom-up unit shipment modeling cross-references top-down value aggregation across power source, end-user, technology, and distribution channel dimensions.
Consistency checks validated volume and value outputs against IEA battery cost curve projections and China SAMR electromagnetic compatibility registration filings. Segmentation modeling spans product type, end-user application, battery chemistry tier, filtration certification grade, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to base-year market sizing, incorporating silicon-anode energy density improvement timelines and urban apartment construction forecasts as industry-specific demand drivers.
Forecasts assume regulatory continuity in EU Ecodesign efficiency mandates and US CPSC lithium-ion safety standards; material policy shifts would require re-modeling across the analysis window. Cobalt supply disruption, REACH substance restriction acceleration, or robotic navigation cost breakthroughs represent specific revision triggers. Practitioners should keep alternative scenarios live as solid-state battery commercialization timelines and extended producer responsibility enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Stainless Steel Water Bottles Market
Household Items
Dry and Wet Wipes Market
Household Items
Brush Cover Market
Household Items
Wax Removal Aids Market
Household Items
Canada Digital Showers Market
Household Items
Europe Cookware Market
Household Items
North America Robotic Pool Cleaner Market
Household Items
Coin-Operated Laundries Market
Household Items
Home Use Air Purifiers Market
Household Items
Europe Heated Mattress Pads Market
Household Items
Portable Steam Cleaners Market
Household Items
Disposable Napkins Market
Household Items
Powered Lawn Mowers Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Drinkware Accessories Market